
 Electric Vehicle Cables Market | 2026-2036
Electric Vehicle Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Cables Market Insights
Aftermarket service revenue is fragmenting as EV cable architectures diverge between 400V and 800V platforms, complicating inventory and technician training models. TE Connectivity Ltd. leverages its sensor-integrated connector portfolio to capture value from predictive maintenance contracts. Leoni AG anchors European supply through dedicated high-voltage harness production lines serving German OEM programs. Sumitomo Electric Industries, Ltd. dominates Asian material science development with proprietary silicone-insulated cable formulations rated for extreme thermal cycling.
Electric vehicle cables are engineered conductors—typically copper or aluminum cores sheathed in thermoplastic or cross-linked elastomer compounds—designed to transmit power between battery packs, inverters, motors, and charging interfaces at voltages ranging from 48V to 1000V DC, with primary purpose of minimizing resistive losses while managing electromagnetic interference and thermal runaway risks. Charging cables command the largest current revenue pool due to infrastructure buildout urgency, though battery cables within pack architectures represent the fastest-growing margin segment as cell-to-pack designs multiply connection density. OEMs as an end-user category absorb the majority of volume, while infrastructure providers are emerging as a structurally distinct procurement channel with longer contract horizons and stricter certification requirements.
The EU Green Deal and F-Gas Regulation constrain insulation material choices and mandate recyclability disclosures, pushing manufacturers toward halogen-free thermoplastic compounds. China's GB standards and MIIT technical guidelines enforce domestic testing protocols that foreign suppliers must navigate for market access. NHTSA and EPA rules in the United States are converging on thermal propagation resistance as a safety threshold for high-voltage cabling. Stakeholders must monitor how 800V platform proliferation and solid-state battery commercialization will redefine ampacity requirements and connector form factors before committing to multi-year capacity investments.
Market Dynamics
Voltage platform bifurcation between 400V and 800V architectures is fragmenting procurement specifications and forcing cable suppliers to maintain dual production capabilities without guaranteed volume commitments from OEMs.
Growth Catalysts
- EU Green Deal emission mandates:The EU Green Deal and F-Gas Regulation compel fleet operators across Germany, France, and the Netherlands to electrify logistics vehicles, generating sustained demand for high-voltage charging infrastructure and compatible cable systems.
- Cell-to-pack battery architectures:Cell-to-pack designs multiply internal connection density within battery enclosures, expanding the addressable cable surface area per vehicle and lifting specification requirements for thermal cycling resistance.
- China's eastern manufacturing corridor:Domestic OEMs and charging infrastructure builders in Shanghai, Jiangsu, and Zhejiang provinces are consolidating procurement volumes for 800V-capable charging and battery connection systems.
Market Restraints
- Copper price volatility:Raw material cost swings in copper cathode markets compress margin predictability for cable assemblers who lack backward integration into conductor drawing operations.
- Silicone compound supply concentration:Proprietary silicone insulation formulations remain concentrated among Japanese and German specialty chemical suppliers, creating single-source risk for extreme thermal cycling applications.
- Cross-platform inventory complexity:Divergent 400V and 800V connector form factors and ampacity ratings force distributors and service networks to carry duplicative SKUs without volume certainty.
Strategic Opportunities
- India's nascent EV manufacturing base:The country's PLI scheme for automotive and advanced chemistry cell manufacturing is attracting cable suppliers who can localize high-voltage harness production ahead of domestic OEM scaling.
- Predictive maintenance service contracts:Sensor-integrated cable and connector systems enable remote impedance monitoring and thermal anomaly detection, opening recurring revenue streams beyond hardware sales.
- Solid-state battery thermal profiles:Next-generation cell architectures with reduced thermal runaway risk will permit thinner insulation layers and revised connector specifications, rewarding early material science investment.
Industry Challenges
- High-voltage technician certification gaps:The shortage of technicians qualified to 1000V DC safety protocols slows aftermarket service network expansion and extends vehicle downtime for cable-related repairs.
- Multi-standard homologation timelines:Simultaneous compliance with China's GB standards, EU CE marking requirements, and US NHTSA thermal propagation rules extends product development cycles and testing expenditures.
- Legacy fleet retrofit complexity:Existing 400V charging infrastructure cannot accommodate 800V vehicle architectures without cable and cooling system upgrades, complicating mixed-fleet operator procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Cables Market |
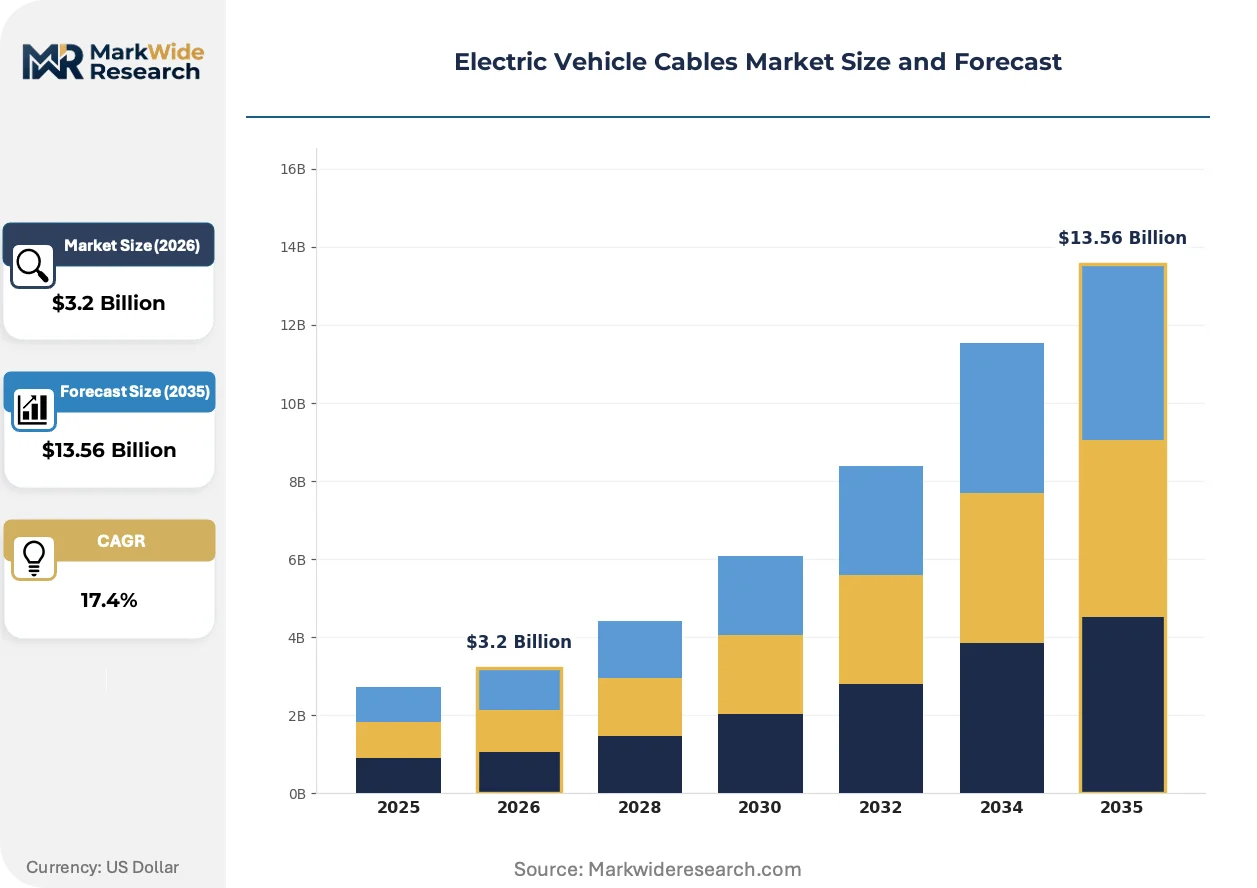
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $13.56 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Charging Cables, Battery Cables, Connector Cables, Harness Cables End User: OEMs, Aftermarket Providers, Fleet Operators, Infrastructure Providers Installation Type: Residential, Commercial, Public Charging Stations, Industrial Material: Copper, Aluminium, Thermoplastic, Composite |
| Companies Covered | TE Connectivity Ltd., Leoni AG, Aptiv PLC, HUBER+SUHNER AG, Nexans S.A., Sumitomo Electric Industries, Ltd., Phoenix Contact, BESEN International Group Co., Ltd., Sinbon Electronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Cables Market Trends and Innovations
Intelligent cable systems with embedded sensing capabilities are displacing passive conductors as the baseline specification for premium EV platforms, compressing the viable product lifecycle of conventional harness designs.
Silicone-insulated cable formulations rated for extreme thermal cycling are digitizing thermal management strategies within battery pack architectures. German and Chinese OEMs are specifying these materials for cell-to-pack designs where connection density limits air-cooling effectiveness. The technology is digitizing how battery management systems predict and preempt thermal runaway events through real-time impedance tracking.
The EU F-Gas Regulation and associated REACH amendments are constraining halogenated flame retardants in cable insulation compounds. Compound suppliers are reformulating toward halogen-free thermoplastic elastomers that maintain dielectric strength across temperature extremes. European harness manufacturers are absorbing reformulation costs and extending certification timelines to maintain CE marking compliance.
Fleet operators are consolidating procurement authority from regional managers to centralized sustainability offices, compressing supplier negotiation cycles and prioritizing total cost of ownership over unit pricing. Direct sourcing agreements between logistics fleets and cable assemblers are displacing tiered distribution channels in Germany and California. This concentration is most visible among last-mile delivery operators with published carbon-neutral deadlines.
Electric Vehicle Cables Market Segmentation
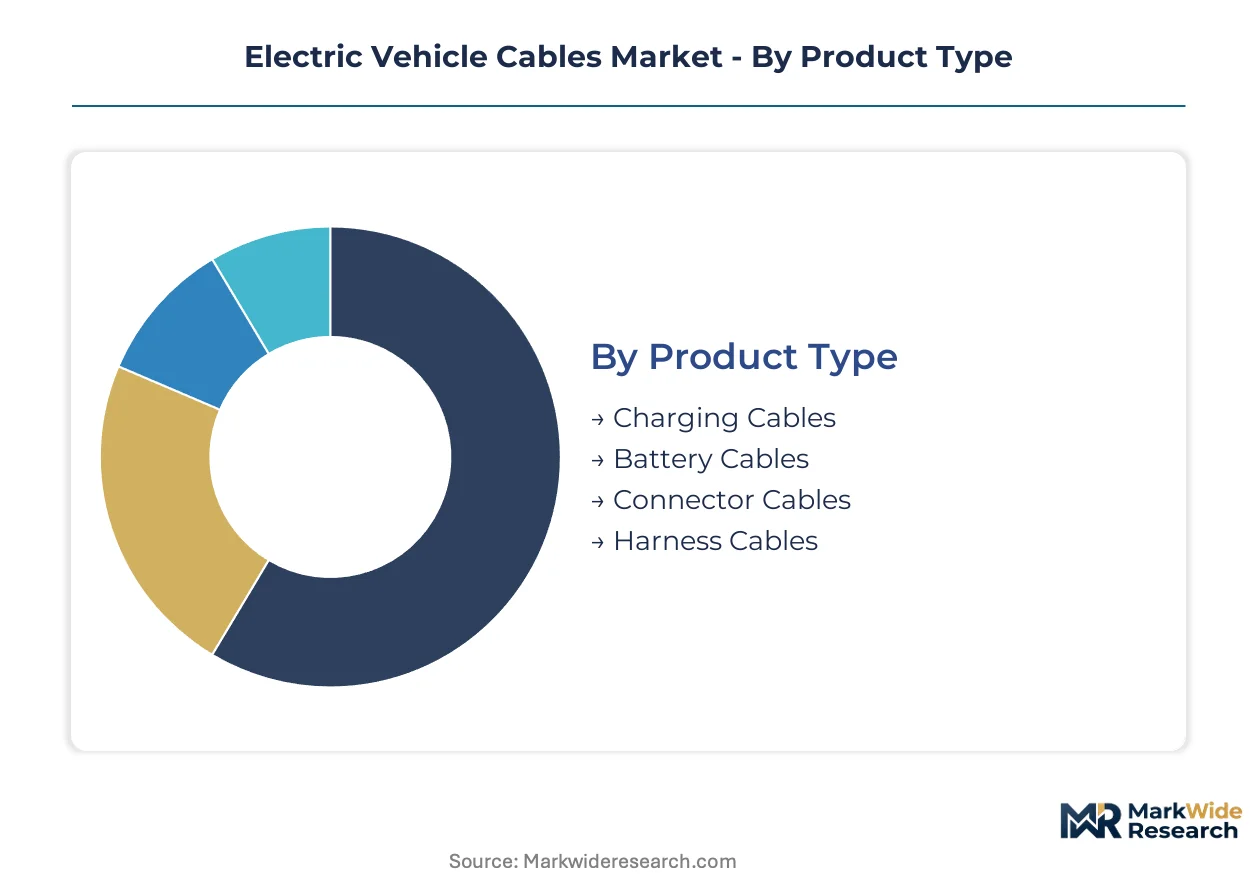
Segmentation in the electric vehicle cables market reveals how voltage platform divergence and installation environment complexity fragment procurement patterns. Suppliers must calibrate insulation specifications, connector form factors, and thermal cycling ratings across distinct use-cases rather than deploying universal product architectures.
Product Type:
The use-case spectrum spans stationary infrastructure to dynamic vehicle environments, each imposing distinct mechanical stress, thermal cycling, and electromagnetic shielding requirements.
- Charging Cables:Heavy-gauge conductors sheathed in thermoplastic elastomer compounds handle repetitive flexing and outdoor exposure at charging points. Demand concentrates among infrastructure builders across Germany, France, and the Netherlands where EU Green Deal mandates accelerate public charging deployment and strain supplier capacity for 800V-compatible assemblies.
- Battery Cables:Multi-strand copper cores with cross-linked silicone insulation route power between cells, modules, and pack-level busbars. Cell-to-pack architectures in China's eastern manufacturing corridor multiply connection density per vehicle, expanding addressable cable surface area and lifting thermal cycling specifications.
- Connector Cables:Short-run assemblies with integrated locking mechanisms bridge inverter-motor interfaces.
- Harness Cables:Bundled conductor groupings with braided shielding manage electromagnetic interference across vehicle platforms.
Established volume favors Charging Cables; emerging adoption favors Battery Cables.
End User:
Customer type determines contract structure, certification burden, and technical support intensity across the value chain.
- OEMs:Vehicle manufacturers specify cables during platform development, locking in multi-year supply agreements with stringent homologation requirements. German and Chinese OEMs dominate procurement for 800V architectures, forcing suppliers to maintain dual production capabilities without guaranteed volume commitments.
- Infrastructure Providers:Charging network operators source cables under longer contract horizons with stricter certification requirements than vehicle manufacturers. Operators across California and the Netherlands centralize procurement through sustainability offices, compressing negotiation cycles and prioritizing total cost of ownership metrics.
- Aftermarket Providers:Service networks face inventory fragmentation as 400V and 800V platforms diverge, complicating technician training and spare parts forecasting.
- Fleet Operators:Logistics electrification programs in North America and Europe generate concentrated demand for high-voltage charging infrastructure and compatible cable systems.
Contract scale favors OEMs; margin expansion favors Infrastructure Providers.
Installation Type:
Deployment environment shapes mechanical durability, environmental sealing, and thermal management specifications.
- Public Charging Stations:Outdoor-rated assemblies with reinforced jackets withstand vandalism, UV exposure, and temperature extremes. China's GB standards and MIIT technical guidelines enforce domestic testing protocols that foreign suppliers must navigate for market access to Shanghai and Jiangsu infrastructure tenders.
- Residential:Lower-amperage installations with simplified connector interfaces serve single-vehicle households.
- Commercial:Workplace and retail installations balance durability with aesthetic integration.
- Industrial:Heavy-duty configurations serve depot charging for logistics fleets with published carbon-neutral deadlines.
Deployment velocity favors Public Charging Stations; margin stability favors Industrial.
Material:
Material selection trades conductivity, weight, cost, and regulatory compliance against thermal and electrical performance requirements.
- Copper:Oxygen-free high-conductivity copper dominates conductor cores for its electrical efficiency and reliability under thermal cycling. Raw material cost swings in copper cathode markets compress margin predictability for cable assemblers lacking backward integration into conductor drawing operations.
- Thermoplastic:Halogen-free thermoplastic elastomers are displacing halogenated flame retardants under EU F-Gas Regulation and REACH amendments. European harness manufacturers absorb reformulation costs and extend certification timelines to maintain CE marking compliance.
- Aluminium:Lightweight alternative gaining traction in mass-sensitive applications.
- Composite:Hybrid constructions combining conductive cores with advanced insulation layers.
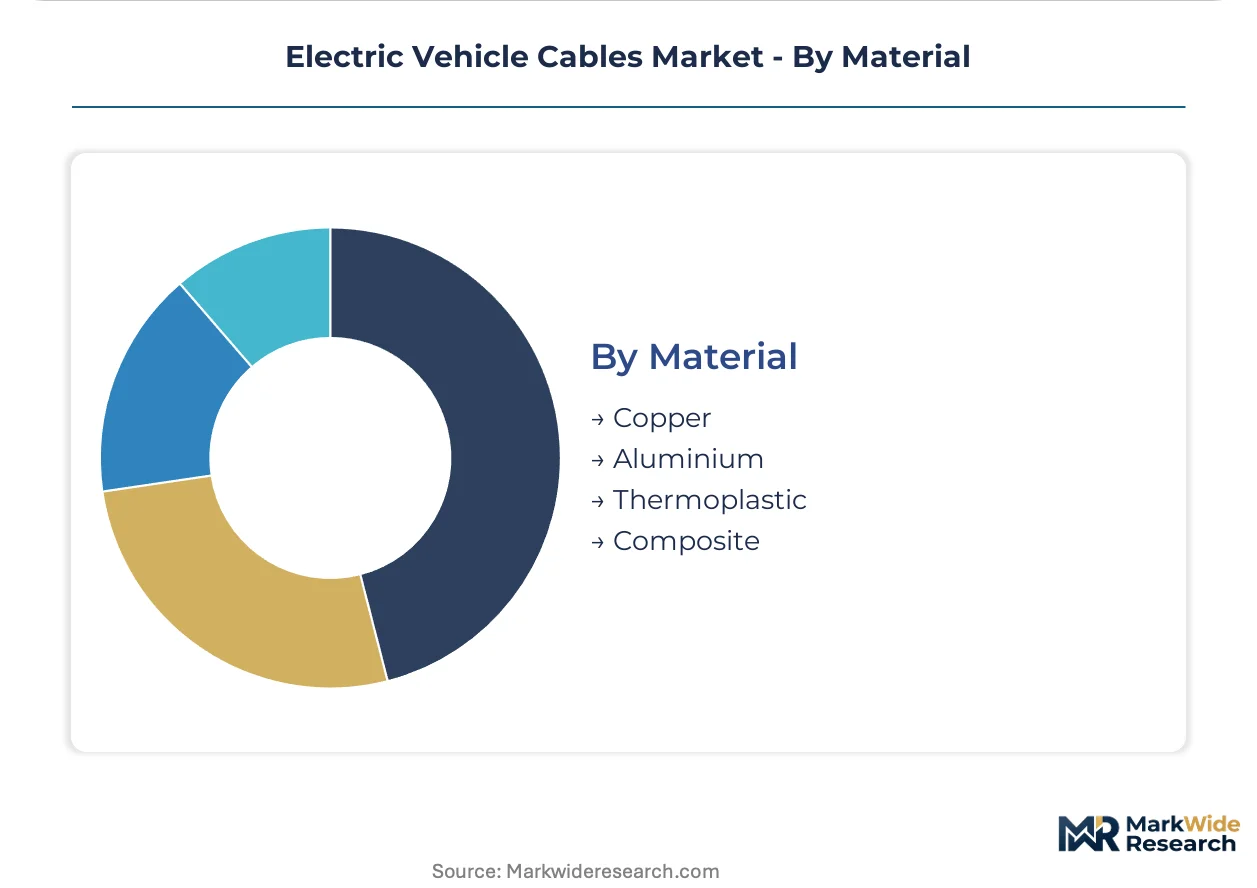
Conductivity performance favors Copper; regulatory alignment favors Thermoplastic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty cable fabrication concentrates in Germany, China, Japan, and the United States, with each jurisdiction enforcing distinct homologation protocols that fragment supplier certification burdens. Raw material procurement networks for copper cathode and silicone compounds span Chilean mining operations and Japanese chemical synthesis facilities.
China
Domestic OEMs in Shanghai, Jiangsu, and Zhejiang provinces are consolidating procurement volumes for 800V-capable charging and battery connection systems. MIIT technical guidelines and GB standards enforce domestic testing protocols that foreign suppliers must navigate for market access. The Yangtze River Delta manufacturing corridor anchors high-voltage harness production serving both domestic brands and joint ventures.
Germany
German OEM programs drive specification upgrades for high-voltage harness production lines serving premium vehicle platforms. The EU Green Deal and F-Gas Regulation compel fleet operators to electrify logistics vehicles, generating sustained demand for compatible cable systems. Bavaria and Baden-Württemberg host concentrated supplier engineering centers co-located with automaker technical campuses.
United States
California's Advanced Clean Trucks rule tightens emission thresholds and accelerates cable specification upgrades for electrified logistics fleets. NHTSA thermal propagation resistance rules converge with EPA guidance on high-voltage cabling safety thresholds. The Detroit automotive cluster and California's Bay Area technology corridor split procurement authority between legacy OEM programs and charging infrastructure buildout.
Japan
Specialty chemical suppliers concentrate proprietary silicone insulation formulations rated for extreme thermal cycling applications. METI industrial policy supports material science development for next-generation battery connection systems. The Kanto and Kansai industrial belts house integrated conductor-insulation manufacturing operations serving domestic and export markets.
Netherlands
Fleet operators across the Randstad region centralize procurement through sustainability offices, compressing supplier negotiation cycles. EU Green Deal mandates accelerate public charging deployment and strain supplier capacity for 800V-compatible assemblies. The Eindhoven-Utrecht corridor hosts testing and certification facilities serving cross-border OEM supply agreements.
Electric Vehicle Cables Market Competitive Landscape
Integrated component suppliers and specialty cable fabricators split the market based on backward integration depth and certification portfolio breadth. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with sensor-integrated connector portfolios, dedicated harness specialists with regional production footprints, and material science developers with proprietary insulation formulations. Dominant competitive moves include capacity expansion in high-voltage assembly lines and strategic partnerships with OEMs for platform-specific co-development.
Among diversified industrial suppliers, TE Connectivity Ltd. and Aptiv PLC exemplify the integrated-component archetype through their positioning across connector and sensing technologies. Leoni AG occupies a position within the European specialty harness tier, while Sumitomo Electric Industries, Ltd. anchors the material-science developer segment with its geographic origin signaling integrated conductor and compound capabilities.
| Leading Market Players |
|---|
| TE Connectivity Ltd. |
| Leoni AG |
| Aptiv PLC |
| HUBER+SUHNER AG |
| Nexans S.A. |
| Sumitomo Electric Industries, Ltd. |
| Phoenix Contact |
| BESEN International Group Co., Ltd. |
| Sinbon Electronics Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta freight corridor's container cost dynamics compress margin predictability for cable assemblers lacking captive conductor drawing operations while amplifying price differentiation between halogen-free certified and legacy insulation grades across OEM and infrastructure procurement channels.
Pricing Analysis
Aftermarket service revenue drives lifetime value capture as sensor-integrated cable systems enable predictive maintenance contracts beyond hardware sales. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier—UL 62 and CE marking compliance command 15-20% premiums over uncertified alternatives. Pricing pressure stems from copper cathode volatility and dual-platform inventory carrying costs for 400V and 800V architectures. Fleet operators exhibit highest price sensitivity through total cost of ownership metrics, while German OEMs prioritize thermal cycling performance over unit economics.
Supply Chain Analysis
Extended payment terms from Chinese infrastructure builders strain working capital for European harness manufacturers competing for Yangtze River Delta tenders. Raw material procurement draws from Chilean copper mining operations, Japanese silicone compound synthesis facilities, and German specialty chemical suppliers. Single-source vulnerability concentrates in proprietary silicone insulation formulations for extreme thermal cycling applications. Distribution runs through tiered channels of direct OEM supply agreements, infrastructure operator central procurement offices, and fragmented aftermarket service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to EV platform refresh cycles and 800V architecture proliferation, with procurement volumes accelerating as German and Chinese OEMs consolidate supplier bases ahead of next-generation vehicle launches.
For Market Incumbents: Entrench position through backward integration into oxygen-free copper conductor drawing and halogen-free compound formulation capabilities. Expand high-voltage assembly capacity in Bavaria and Jiangsu to defend against emerging Asian harness specialists. Prioritize GB standard certification investment to secure access to Shanghai infrastructure tenders before foreign supplier windows narrow.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI-supported automotive manufacturing corridor ahead of domestic OEM scaling. Target aftermarket service networks facing technician certification gaps and inventory fragmentation between voltage platforms. Pursue direct sourcing agreements with last-mile delivery fleets in California and the Netherlands through sustainability office procurement channels.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core cable and connector divisions amid portfolio rationalization. Long-term viability hinges on material science differentiation and platform-specific co-development relationships with 800V-focused OEMs. Monitor solid-state battery thermal profile specifications as the inflection signal for insulation layer thickness and connector form factor revisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces dual 400V/800V inventory burden for cable assemblers serving German OEM programs. |
| Battery Supply Agreement | Locks in cell-to-pack connection density specifications with Chinese OEMs in the Yangtze corridor. |
| Geographic Manufacturing Footprint | Localizes high-voltage harness production in India ahead of PLI scheme volume commitments. |
| Charging Infrastructure Partnership | Secures 800V-compatible assembly capacity allocation with Netherlands fleet operators. |
| Software-Defined Vehicle Investment | Integrates impedance monitoring sensors into cable systems for predictive maintenance revenue. |
Research Methodology
A standing panel of OEM platform engineers, Tier 1 supplier procurement leads, charging infrastructure operators, and aftermarket service technicians provided ongoing calibration against secondary validation from SEC 10-K filings, MIIT technical guideline releases, EU F-Gas Regulation amendments, and vehicle production databases. Primary fieldwork combined structured interviews with unstructured observation of certification testing protocols. Bottom-up segment sizing triangulated against top-down macroeconomic anchors.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning voltage platform architecture, installation environment, material composition, and end-user procurement channel. CAGRs derived from regression analysis against EV penetration curves and infrastructure deployment schedules. Forecast inputs incorporated copper price trajectory assumptions and regulatory compliance timeline variations across GB standards, CE marking, and NHTSA thermal propagation rules.
Sensitivities concentrate around 800V platform adoption velocity, solid-state battery commercialization timelines, and copper cathode supply disruptions. Forecasts reflect documented assumptions on OEM platform consolidation patterns and infrastructure buildout acceleration under EU Green Deal mandates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Ethernet Converters Market
Cables
Audio and Video Cables Market
Cables
EDM Wires Market
Cables
Cable Drum Market
Cables
Network Cable Tester Market
Cables
Mexico Wires and Cables Market
Cables
Copper Stranded Wire Market
Cables
Electric Vehicle Unshielded HV Cables Market
Cables
High Voltage Cable Termination Market
Cables
Mineral Insulated (MI) Cable Market
Cables
Anti-Static Space Wires Market
Cables
Solar Cable Market
Cables
Insulated Wire and Cable Market
Cables
LED Cable Market
Cables
Fiber Optical Cable and Cable Assembly Products Market
Cables
Cable Assembly Market