
 China Data Converter Market | 2026-2036
China Data Converter Market Size, Share, and Industry Trends Forecast 2026-2036
China Data Converter Market Outlook
Telecommunications OEMs is redrawing procurement priorities away from consumer electronics buyers as 5G base station rollouts consume higher converter volumes. Analog Devices leverages its precision converter portfolio to anchor relationships with domestic telecom equipment manufacturers. Texas Instruments sustains R&D intensity in SAR architectures for industrial automation customers requiring low-latency signal chains. NXP Semiconnavigates China's automotive qualification requirements by specializing in AEC-Q100 compliant delta-sigma devices for battery management systems.
China data converters translate continuous analog signals into discrete digital codes and vice versa, with resolution, sampling rate, and linearity defining performance boundaries for downstream signal processing. These components enable sensor interfacing, audio processing, and RF communication in systems where microcontroller-native ADC precision proves insufficient. High-speed converters dominate telecommunications applications where gigasample-per-second throughput supports massive MIMO antenna arrays, while precision converters capture margin pools in industrial automation through sub-LSB accuracy requirements. Pipeline architectures lead in high-frequency segments, whereas delta-sigma topologies occupy medical and test equipment niches demanding extended dynamic range.
MIIT enforces GB standards for electromagnetic compatibility and radio transmission equipment, directly shaping converter specifications for 5G infrastructure certification. SAMR oversees quality supervision and antitrust compliance, influencing how foreign suppliers like Infineon Technologies and STMicroelectronics structure local partnerships and distribution channels. China's dual carbon goals from MEE pressure industrial automation adopters to specify lower-power converter variants in motor control and energy monitoring systems. Stakeholders must monitor evolving GB standard revisions and provincial semiconductor subsidy programs to calibrate product roadmaps and localization strategies.
Market Dynamics
MIIT's tightening GB standards for 5G base station certification are forcing signal integrity component upgrades across China's telecommunications supply chain, compressing converter qualification timelines while expanding precision requirements for massive MIMO deployments.
Growth Catalysts
- Dual carbon goals:MEE mandates for industrial energy efficiency are accelerating low-power converter procurement in motor control and energy monitoring systems across Guangdong manufacturing clusters.
- 5G infrastructure deployment:Telecommunications OEMs in Shenzhen-Dongguan are scaling high-speed converter volumes for base station antenna arrays requiring gigasample-per-second throughput.
- Automotive electrification:Battery management system integrators are specifying AEC-Q100 compliant delta-sigma architectures for electric vehicle production lines in Shanghai and Chongqing.
Market Restraints
- Wafer supply concentration:Advanced node capacity constraints at Taiwan-based foundries are extending lead times for high-performance pipeline converter dice bound for mainland packaging facilities.
- GB certification friction:SAMR electromagnetic compatibility testing protocols are adding 4-6 month validation cycles for imported converter modules before domestic telecom integration.
- Precision analog talent scarcity:Mixed-signal design expertise pools concentrate in Beijing and Hangzhou, creating recruitment bottlenecks for SAR architecture development teams.
Strategic Opportunities
- Western China expansion:Chengdu-Xi'an semiconductor corridors are attracting converter module packaging investments through Sichuan and Shaanxi provincial subsidy programs.
- Medical imaging convergence:Delta-sigma topologies are penetrating CT and MRI equipment as domestic healthcare OEMs localize precision signal chain production.
- Industrial IoT channel innovation:Direct converter sales through Alibaba Cloud's hardware marketplace are shortening procurement cycles for mid-tier automation integrators in Jiangsu province.
Industry Challenges
- Multi-standard integration complexity:Test equipment manufacturers must reconcile MIIT radio transmission specifications with IEC measurement protocols for export-bound product lines.
- Legacy system compatibility:Semiconductor packaging facilities in Dongguan face retrofit costs when integrating new converter generations with existing wire-bonding infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Data Converter Market |
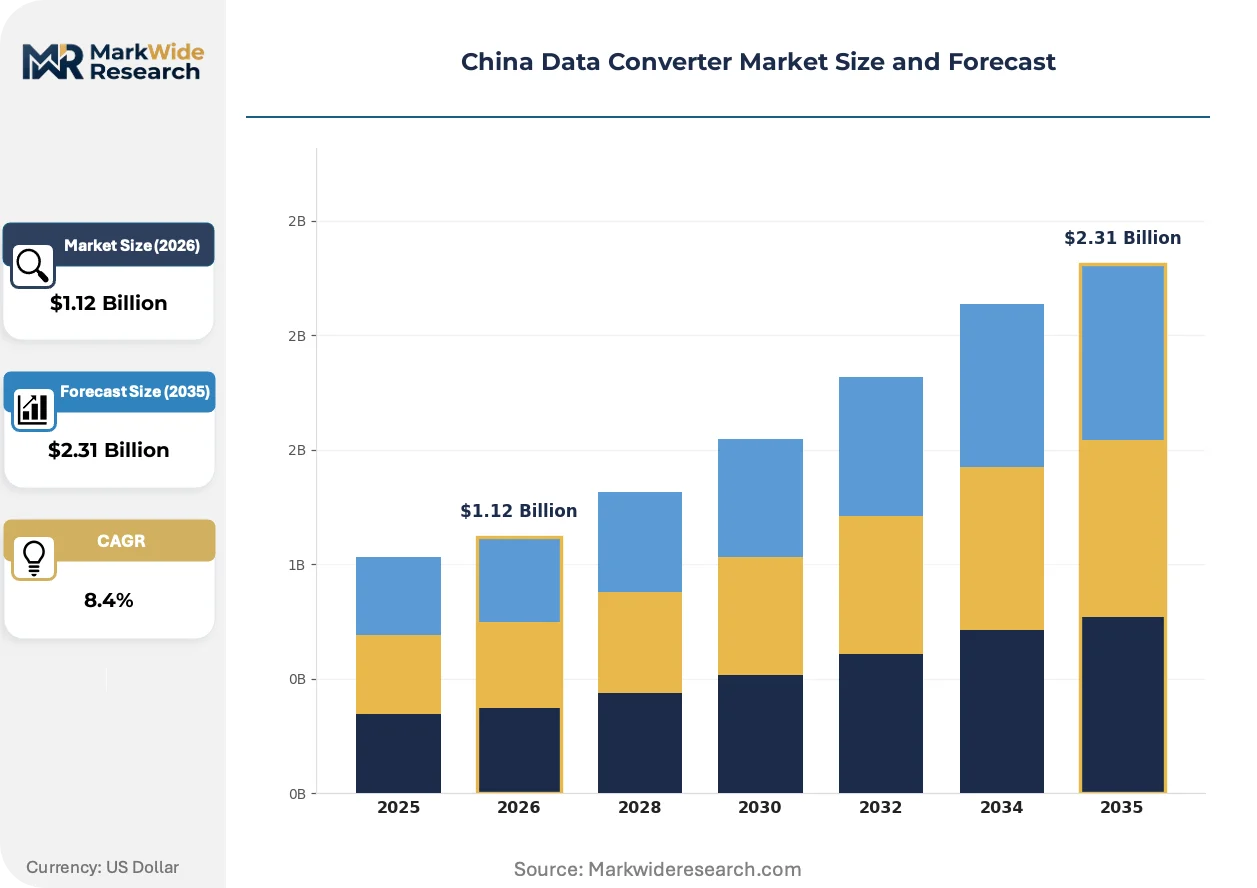
| Market Size in 2026 | $1.12 Billion |
| Market Size in 2035 | $2.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog-to-Digital Converters, Digital-to-Analog Converters, High-Speed Converters, Precision Converters Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Telecommunications, Consumer Electronics, Automotive, Industrial Automation Technology: Switched Capacitor, Delta-Sigma, Pipeline, SAR |
| Companies Covered | Analog Devices, Texas Instruments, Microchip Technology, Renesas Electronics Corporation, Infineon Technologies, NXP Semiconductors, ROHM, Asahi Kasei Microdevices Corporation, STMicroelectronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Data Converter Market Strategic Shifts
Chiplets are fragmenting monolithic converter architectures, enabling heterogeneous integration that separates analog front-ends from digital processing cores. This decomposition is redrawing competitive boundaries between specialized foundries and system-level integrators.
Time-interleaved ADC architectures are decomposing single-channel speed limitations by distributing sampling across multiple lower-rate cores. Telecommunications infrastructure builders in Guangdong are adopting these designs for 400G optical transceivers. The approach is compressing power consumption per gigasample while expanding dynamic range for massive MIMO baseband processing.
MIIT's revised GB/T radio transmission equipment standards are mandating enhanced spurious emission controls for 5G millimeter-wave bands. Converter suppliers must demonstrate -80 dBc harmonic distortion performance to secure network access licenses. Domestic telecom equipment manufacturers are pre-qualifying precision pipeline architectures before base station deployment tenders.
Specification-driven procurement is consolidating buyer power among state-owned telecommunications operators. Tier-one infrastructure vendors in Shenzhen are bypassing distribution intermediaries to negotiate direct converter supply agreements with analog semiconductor specialists. This channel compression is most visible in Guangdong province, where ZTE and Huawei procurement teams are consolidating approved vendor lists to sub-ten qualified suppliers per converter category.
China Data Converter Market Segmentation
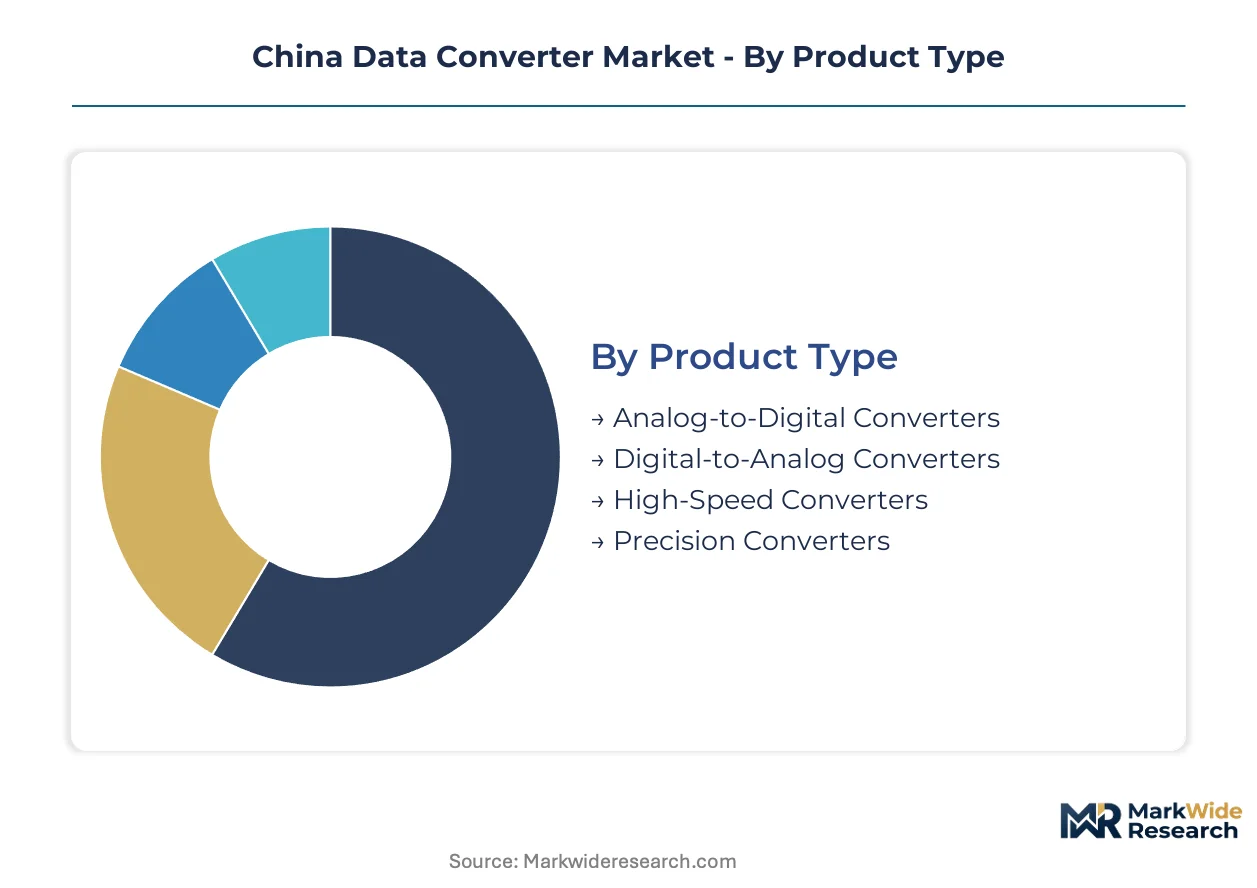
Data converter procurement patterns in China diverge sharply across application layers, with telecommunications infrastructure demanding gigasample-per-second throughput while industrial automation prioritizes sub-LSB accuracy. Channel configuration varies by segment—direct OEM relationships dominate high-volume base station deployments, whereas distribution intermediaries serve fragmented industrial integrators. Understanding these segment-channel pairings reveals where pricing power concentrates and where localization investments yield fastest returns.
Product Type:
High-speed converters flow through direct supply agreements with Shenzhen-Dongguan telecommunications OEMs, while precision variants reach industrial customers via regional distributors in Jiangsu and Zhejiang provinces.
- Analog-to-Digital Converters:Pipeline and SAR architectures handle sensor interfacing across industrial automation systems in Guangdong manufacturing clusters. MIIT certification requirements for 5G equipment are tightening resolution specifications for base station deployments.
- Digital-to-Analog Converters:String and current-steering topologies drive RF signal synthesis in massive MIMO antenna arrays. Demand concentrates among ZTE and Huawei procurement teams consolidating approved vendor lists to sub-ten qualified suppliers per converter category.
- High-Speed Converters:Gigasample-per-second pipeline ADCs enable 400G optical transceivers for telecommunications infrastructure builders accelerating base station rollouts.
- Precision Converters:Delta-sigma architectures with extended dynamic range serve medical imaging and test equipment niches requiring sub-LSB accuracy.
High-speed converters dominate installed base. Precision converters are where expansion concentrates.
Deployment:
Cost tier stratification separates edge computing modules—where silicon integration drives unit economics—from cloud-based configurations where software-defined signal processing commands premium pricing.
- On-Premises:Dedicated converter hardware in factory automation systems requires deterministic latency for motor control loops. Guangdong province's electronics corridor clusters packaging facilities around these embedded deployments.
- Cloud-Based:Remote signal processing infrastructure leverages high-speed converters at network aggregation points. MIIT's GB standards for electromagnetic compatibility shape hardware specifications for data center installations.
- Hybrid:Split architectures distribute analog front-ends locally while centralizing digital processing. Industrial IoT adopters in Jiangsu province favor this model for energy monitoring systems.
- Edge Computing:Converter-integrated modules at sensor nodes reduce bandwidth requirements for real-time automation. Sichuan and Shaanxi provincial subsidy programs are attracting packaging investments for these compact form factors.
On-premises deployments anchor current revenue. Edge computing modules are climbing the fastest.
End User:
Application urgency varies by sector—telecommunications procurement cycles compress around 5G tender deadlines while automotive qualification timelines stretch across AEC-Q100 validation protocols.
- Telecommunications:Massive MIMO base station arrays consume the highest converter volumes. Shenzhen-Dongguan infrastructure builders are scaling procurement directly with analog semiconductor specialists, bypassing distribution intermediaries.
- Consumer Electronics:Audio processing and display interface applications demand cost-optimized converter integration. This segment faces displacement as telecommunications OEMs redraw procurement priorities.
- Automotive:Battery management systems specify AEC-Q100 compliant delta-sigma devices for electric vehicle production lines in Shanghai and Chongqing.
- Industrial Automation:Motor control and energy monitoring systems require low-latency signal chains. MEE dual carbon mandates are accelerating low-power converter specification across Guangdong manufacturing clusters.
Telecommunications dominates volume share. Automotive electrification represents the steepest expansion trajectory.
Technology:
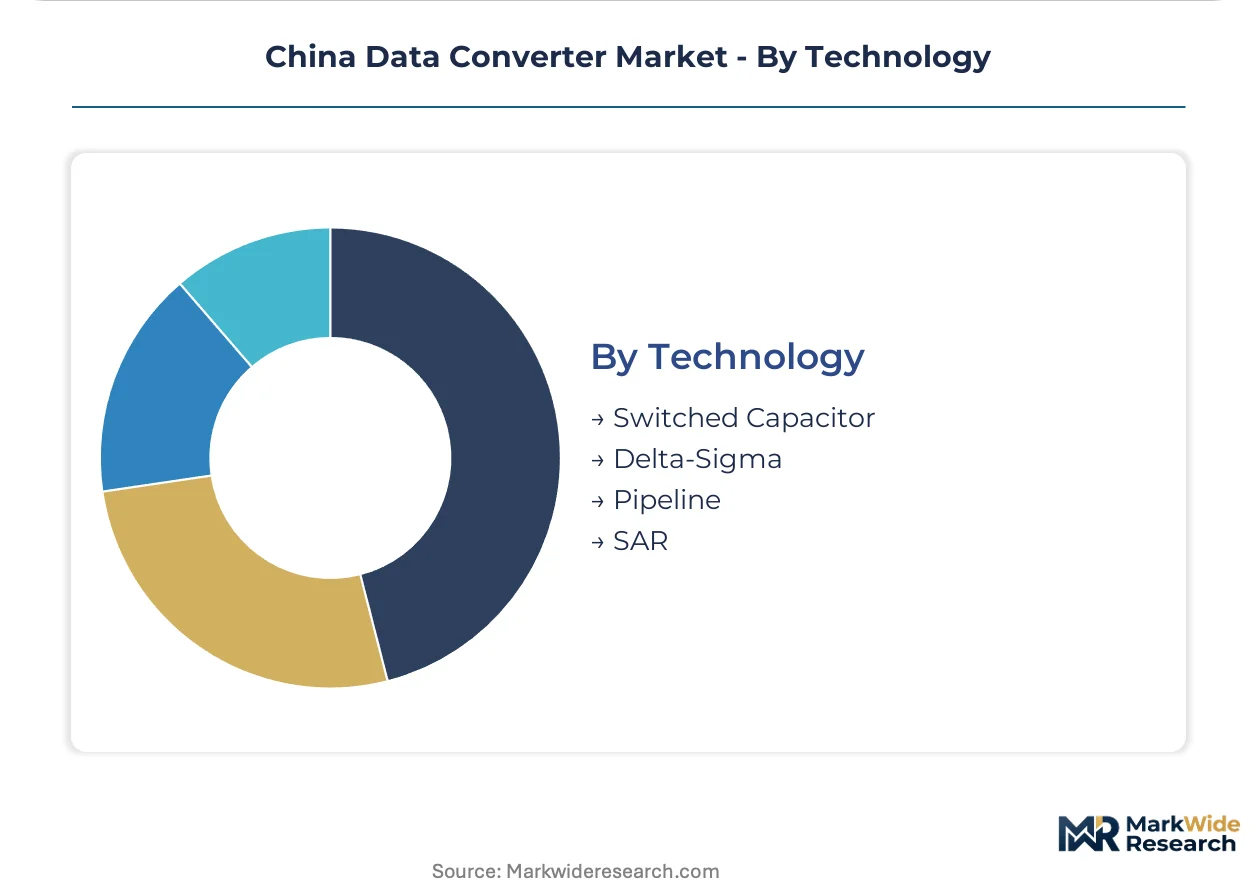
Architecture selection tracks performance requirements—speed versus resolution tradeoffs determine whether pipeline, SAR, or delta-sigma topologies capture design wins.
- Switched Capacitor:Sampling front-end circuits enable high input impedance with minimal power overhead. Medical imaging equipment in domestic healthcare OEM supply chains favors these structures for CT signal acquisition.
- Delta-Sigma:Oversampling converters achieve extended dynamic range through noise-shaping techniques. Automotive battery management integrators in Shanghai specify these architectures for AEC-Q100 compliant production.
- Pipeline:Multi-stage architectures deliver gigasample-per-second throughput for 5G millimeter-wave baseband processing. MIIT's revised GB/T standards mandate -80 dBc harmonic distortion performance for network access licenses.
- SAR:Successive approximation registers balance speed and resolution for industrial sensor interfacing. Mixed-signal design expertise pools concentrate in Beijing and Hangzhou, creating recruitment bottlenecks for development teams.
Pipeline architectures dominate high-frequency applications. Delta-sigma topologies are gaining share fastest in automotive and medical niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's data converter exports flow primarily to Southeast Asian telecommunications equipment manufacturers assembling 5G infrastructure for regional deployment. Domestic consumption dominates volume, with provincial industrial policies reshaping sub-regional production footprints.
Guangdong Province
Shenzhen-Dongguan electronics corridors cluster converter-integrated module production around semiconductor packaging facilities. MIIT's GB certification requirements for 5G equipment tighten performance thresholds for signal integrity components. ZTE and Huawei procurement teams consolidate approved vendor lists to sub-ten qualified suppliers per converter category.
Jiangsu Province
Industrial IoT adopters favor hybrid architectures distributing analog front-ends locally while centralizing digital processing. MEE dual carbon mandates accelerate low-power converter specification across manufacturing clusters. Direct converter sales through Alibaba Cloud's hardware marketplace shorten procurement cycles for mid-tier automation integrators.
Shanghai Municipality
Battery management system integrators specify AEC-Q100 compliant delta-sigma architectures for electric vehicle production lines. SAMR electromagnetic compatibility testing protocols add validation cycles for imported converter modules. Automotive electrification represents the steepest expansion trajectory within the municipal industrial plan.
Sichuan and Shaanxi Provinces
Chengdu-Xi'an semiconductor corridors attract converter module packaging investments through provincial subsidy programs. Edge computing modules at sensor nodes reduce bandwidth requirements for real-time automation. Western China expansion channels government support toward compact form factor production.
Beijing and Hangzhou
Mixed-signal design expertise pools concentrate in these hubs, creating recruitment bottlenecks for SAR architecture development teams. Precision analog talent scarcity limits domestic R&D scaling for industrial automation customers requiring low-latency signal chains. Pipeline converter development teams face competitive compensation pressure from telecommunications OEMs.
China Data Converter Market Competitive Environment
Listed leaders compete with private specialists across certification depth and geographic coverage. The vendor base stratifies between precision analog incumbents with MIIT-qualified portfolios and emerging domestic challengers leveraging provincial subsidy access. Three archetypes dominate: telecommunications-focused precision suppliers, automotive-qualified delta-sigma specialists, and industrial automation SAR architecture providers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with direct OEM relationships displacing distribution intermediaries in high-volume segments.
Within the telecommunications-focused tier, Analog Devices and Texas Instruments exemplify precision converter portfolio anchoring with domestic equipment manufacturers. NXP Semiconductors occupies a position bridging automotive qualification requirements with industrial automation signal chain integration. These three names represent the concentration of direct supply agreements with Shenzhen-Dongguan infrastructure builders bypassing traditional distribution channels.
| Leading Market Players |
|---|
| Analog Devices |
| Texas Instruments |
| Microchip Technology |
| Renesas Electronics Corporation |
| Infineon Technologies |
| NXP Semiconductors |
| ROHM |
| Asahi Kasei Microdevices Corporation |
| STMicroelectronics |
| Others |
Value Chain & Pricing Dynamics
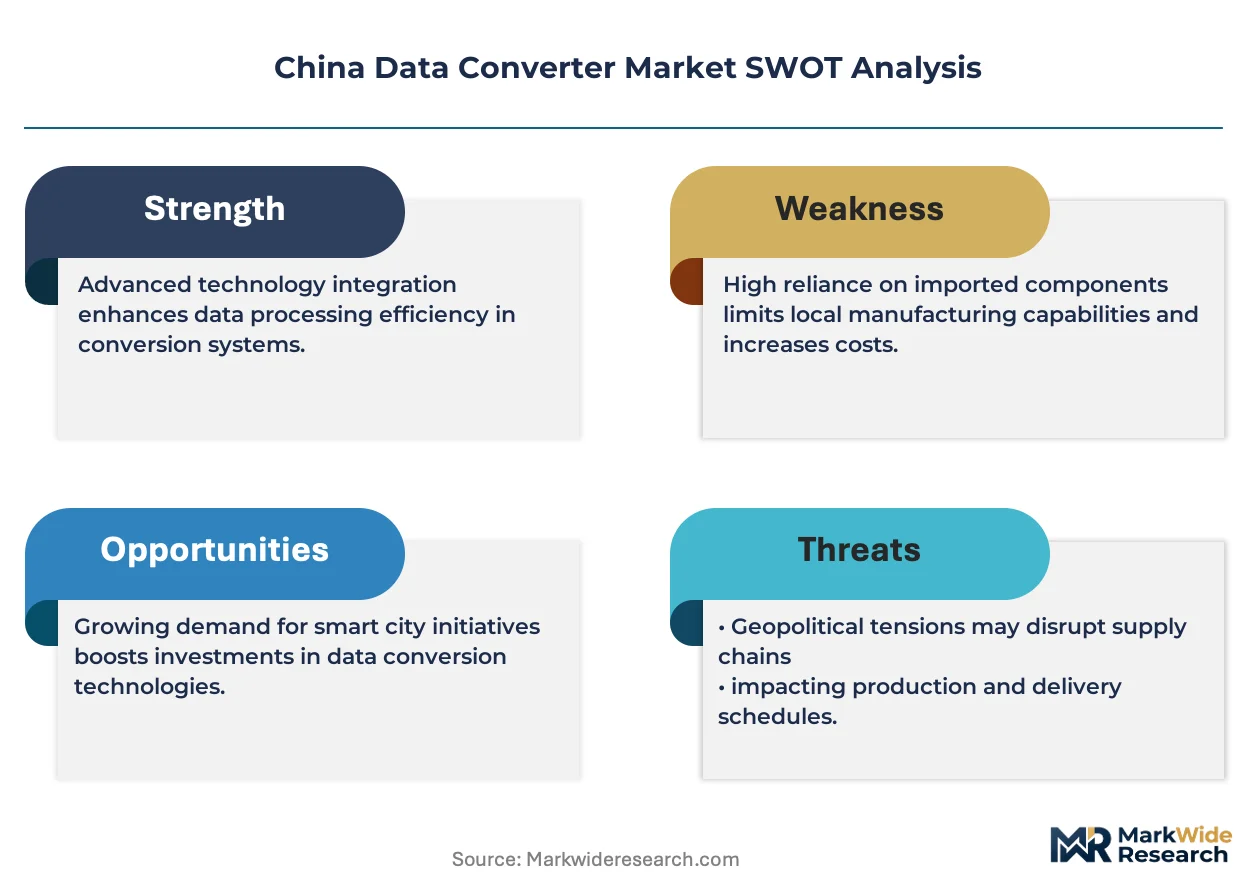
Ninety-day wafer start-to-die delivery timelines at Taiwan-based foundries are compressing margin flexibility for pipeline converter suppliers while amplifying pricing leverage for domestic packaging houses in Guangdong. This lead-time band concentrates procurement power among telecommunications OEMs consolidating direct supply agreements, forcing tier-two industrial integrators toward longer-horizon contract structures.
Pricing Analysis
Current-generation pipeline ADCs command substantial premiums over prior-generation SAR architectures, while next-generation time-interleaved designs are pricing at standard-tier levels to accelerate design-win capture. Three-tier pricing structure across premium MIIT-certified, standard industrial-grade, and economy consumer-grade levels dominates procurement. Price differentiation rests on GB certification status and volume scale commitments from Shenzhen-Dongguan infrastructure builders. Cost compression in economy tiers is intensifying because consumer electronics buyers face displacement from 5G procurement priorities. Industrial automation integrators in Jiangsu province exhibit highest price sensitivity due to fragmented demand, whereas telecommunications OEMs prioritize performance over unit cost.
Supply Chain Analysis
Inventory buffers at Dongguan packaging facilities have compressed to three weeks of die supply, exposing the channel to Taiwan foundry scheduling volatility. Geographic supply concentration centers on Taiwan for advanced node wafer fabrication, South Korea for specialty analog processes, and China for backend module integration. Raw material dependencies include silicon wafers, gold bonding wire, and ceramic package substrates. Single-source vulnerability at Taiwan-based foundries constitutes the dominant structural risk. Distribution runs through direct OEM relationships in telecommunications and regional distributor networks serving industrial automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's data converter market is approaching a platform-economics inflection where MIIT certification ecosystems and Alibaba Cloud hardware marketplaces are redefining interoperability standards and channel access. This shift favors suppliers embedding firmware-level integration with domestic cloud infrastructure.
For Market Incumbents: Consolidate approved vendor list positions with ZTE and Huawei procurement teams through dedicated MIIT pre-qualification pipelines. Deepen backward integration into Chengdu-Xi'an packaging corridors to offset Taiwan foundry concentration. Channel control through direct technical support teams in Shenzhen-Dongguan anchors pricing power against emerging domestic challengers leveraging provincial subsidies.
For New Entrants and Emerging Players: AEC-Q100 fast-track certification for delta-sigma architectures opens automotive battery management procurement in Shanghai and Chongqing. Medical imaging equipment localization in domestic healthcare OEM supply chains represents the most penetrable white-space target. Go-to-market execution through Alibaba Cloud hardware marketplace partnerships shortens qualification cycles for Jiangsu industrial IoT integrators.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational semiconductor parents seeking to monetize non-core precision analog divisions with established MIIT-qualified portfolios. Long-term viability across the analysis window hinges on certification depth rather than scale economics. Monitor SAMR electromagnetic compatibility testing queue lengths as an inflection indicator for import substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| MIIT GB Standard Pre-Qualification | Secures network access licenses for 5G millimeter-wave baseband processing tenders. |
| Chengdu-Xi'an Packaging Investment | Captures Sichuan and Shaanxi provincial subsidies while reducing Taiwan foundry dependency. |
| Alibaba Cloud Marketplace Integration | Shortens procurement cycles for Jiangsu mid-tier automation integrators through direct digital channels. |
| AEC-Q100 Delta-Sigma Development | Penetrates Shanghai and Chongqing electric vehicle battery management system specifications. |
| Time-Interleaved ADC Architecture Launch | Enables 400G optical transceiver adoption by Guangdong telecommunications infrastructure builders. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with telecommunications procurement directors, industrial automation system integrators, semiconductor packaging facility managers, and MIIT certification specialists. Secondary validation drew from MIIT equipment certification databases, SAMR electromagnetic compatibility filings, provincial semiconductor subsidy program disclosures, and customs trade records for converter module imports. Bottom-up demand modeling across end-use segments triangulated against top-down supply-side capacity assessments.
Across the analysis window, volume and value outputs reflect segmented modeling by converter architecture, deployment configuration, end-use sector, and regional production cluster. CAGRs were derived from time-series interpolation of procurement volume indicators and technology substitution curves. Industry-specific forecast inputs include 5G base station deployment schedules from state-owned operators and electric vehicle production line expansion timelines from Shanghai automotive OEMs.
Underlying assumptions cover sustained Taiwan foundry capacity allocation for analog processes and stable MIIT certification timeline protocols, with deviation risk concentrated in wafer supply disruptions and GB standard revision cycles. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Touchless Tubes Market
Electronic Components
Battery Holders Market
Electronic Components
Braking Resistors Market
Electronic Components
IF Digital Attenuator Market
Electronic Components
High Temperature Capacitor Market
Electronic Components
United States Radiation-Hardened Electronics Market
Electronic Components
Audio CODEC Market
Electronic Components
Fuel Pump Driver Module Market
Electronic Components
Electric Fuse Market
Electronic Components
PTC Resettable Device Market
Electronic Components
Coin Battery Holder Market
Electronic Components
Laser Direct Structuring (LDS) Antenna Market
Electronic Components
Screw Washer Market
Electronic Components
Gas Discharge Tube Market
Electronic Components
Radiation Hardened Electronics Market
Electronic Components
Global Capacitive Stylus Market