
 Type TC and Type TC-ER Cable (600 V) Market | 2026-2036
Type TC and Type TC-ER Cable (600 V) Market Size, Share, and Industry Trends Forecast 2026-2036
Type TC and Type TC-ER Cable (600 V) Market Insights
A widening capability gap between integrated manufacturers and regional distributors is rotating competitive dynamics across the Type TC and Type TC-ER cable landscape. Belden leverages its R&D intensity to dominate high-performance industrial instrumentation segments. General Cable sustains manufacturing scale across multiple North American production facilities. OmniCable competes through specialized distribution networks serving electrical contractors and OEM procurement channels.
Type TC and Type TC-ER cable (600 V) denotes power and control tray cable rated for 600 volts, constructed with stranded copper or aluminum conductors, thermoset or thermoplastic insulation, and a protective jacket designed for installation in cable trays, raceways, or exposed runs without additional conduit. The primary purpose centers on distributing electrical power and control signals in industrial facilities, commercial buildings, and infrastructure projects where flexible tray-rated wiring reduces installation labor and material costs. Copper conductor configurations command the dominant share of value given conductivity performance requirements, while aluminum alternatives occupy cost-sensitive commercial and infrastructure segments. Cable tray installation methods represent the mature core application, though direct burial and surface mount configurations are gaining traction in utility-scale solar and outdoor industrial environments.
NFPA 70 (National Electrical Code) governs tray cable and exposed run classifications through Article 336 and related provisions, with UL 1277 and UL 1685 standards defining flame propagation and vertical tray fire test requirements for product listing. OSHA electrical safety regulations intersect with cable selection in industrial environments, particularly regarding wet-location ratings and grounding conductor sizing. The EPA's emerging focus on per- and polyfluoroalkyl substance restrictions in cable jacketing materials may force compound reformulation across multiple supplier portfolios. Stakeholders must monitor evolving NEC adoption cycles across state and local jurisdictions, as amendment timelines directly influence product certification roadmaps and inventory positioning strategies.
Market Dynamics
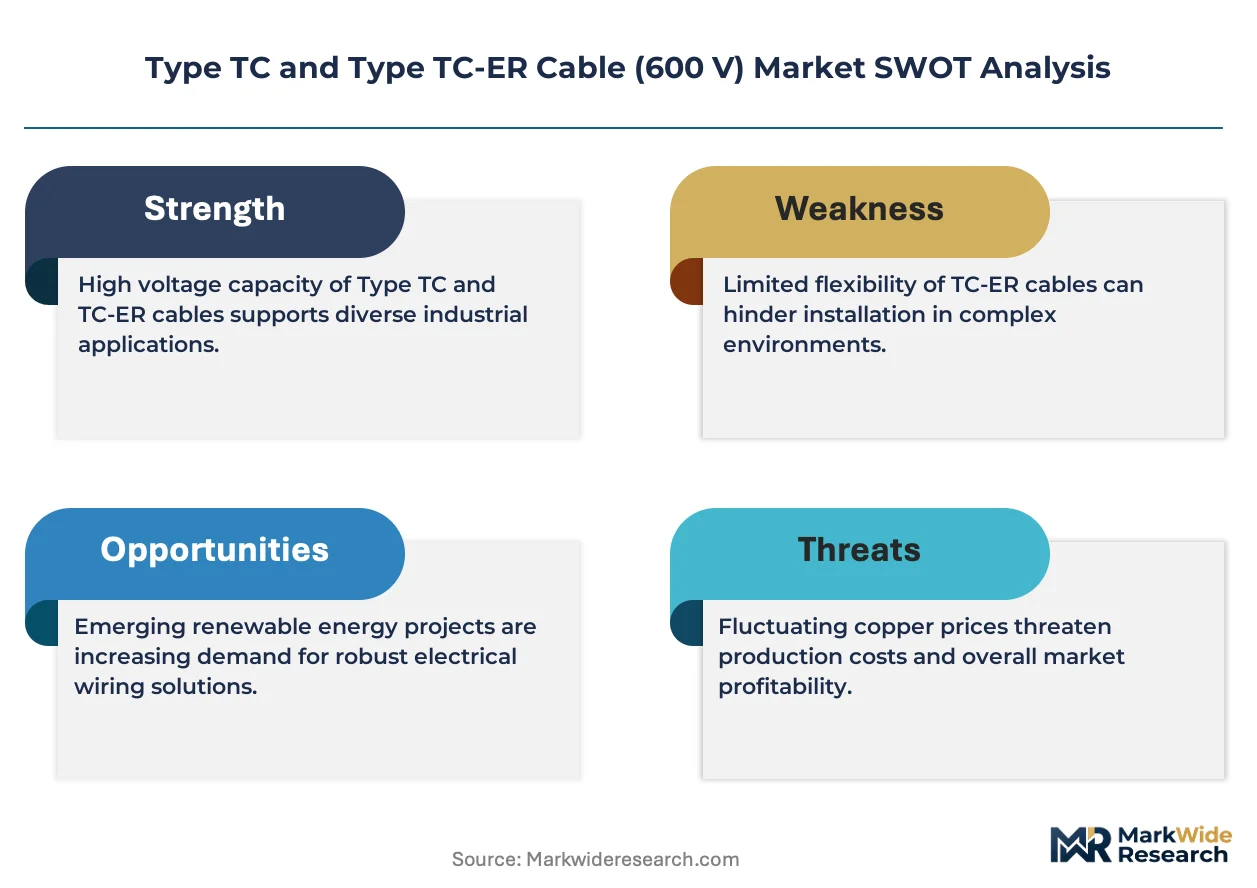
The NEC's 2023 tray cable amendments are compressing certification timelines and forcing compound reformulation across supplier portfolios, while data center buildouts in Texas and Arizona rotate procurement volumes toward high-conductor-count configurations.
Growth Catalysts
- Data Center Power Density:Hyperscale facilities in Dallas-Fort Worth and Phoenix are specifying 600 V tray cable bundles with 50+ conductors for busway distribution, pulling premium copper configurations into procurement pipelines.
- OSHA Electrical Safety Directives:Wet-location grounding requirements in industrial environments are mandating enhanced jacket ratings, expanding addressable product lines for tray-rated cable with integrated equipment grounding conductors.
- Utility-Scale Solar Expansion:Direct burial and surface mount TC-ER installations are displacing traditional conduit runs in Arizona and Ohio solar farms, reducing labor hours per megawatt of capacity.
Market Restraints
- Copper Price Volatility:LME copper fluctuations above historical baselines are compressing margin structures for distributors holding inventory, particularly affecting medium-gauge conductor stock positions.
- PFAS Compound Restrictions:EPA scrutiny of fluorinated jacketing materials is forcing premature compound transitions, with reformulation timelines running ahead of existing UL listing expiration cycles.
- Regional Supply Concentration:Thermoplastic and thermoset compound production clusters in the Gulf Coast create geographic vulnerability to hurricane disruption, with limited secondary sourcing for specialized tray cable jackets.
Strategic Opportunities
- Texas Manufacturing Corridor:Semiconductor fabrication and battery cell plants in Austin and Sherman are generating greenfield electrical infrastructure demand with 18-24 month procurement windows.
- Integrated Digital Specification Tools:Building information modeling plugins that auto-select tray cable based on ampacity and tray fill calculations are penetrating MEP contractor workflows, creating specification lock-in.
- UL 1277 Enhanced Flame Testing:Vertical tray fire performance certifications are becoming a de facto requirement for federal and institutional projects, opening premium pricing tiers for listed products.
Industry Challenges
- Skilled Electrician Shortage:Journeyman availability constraints in Arizona and Ohio are extending installation timelines, compressing project cash flows and increasing callback risk for improper tray fill ratios.
- State-by-State NEC Adoption Lag:Jurisdictional variation in Article 336 amendment implementation creates inventory fragmentation, with distributors holding multiple certification variants for adjacent markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Type TC and Type TC-ER Cable (600 V) Market |
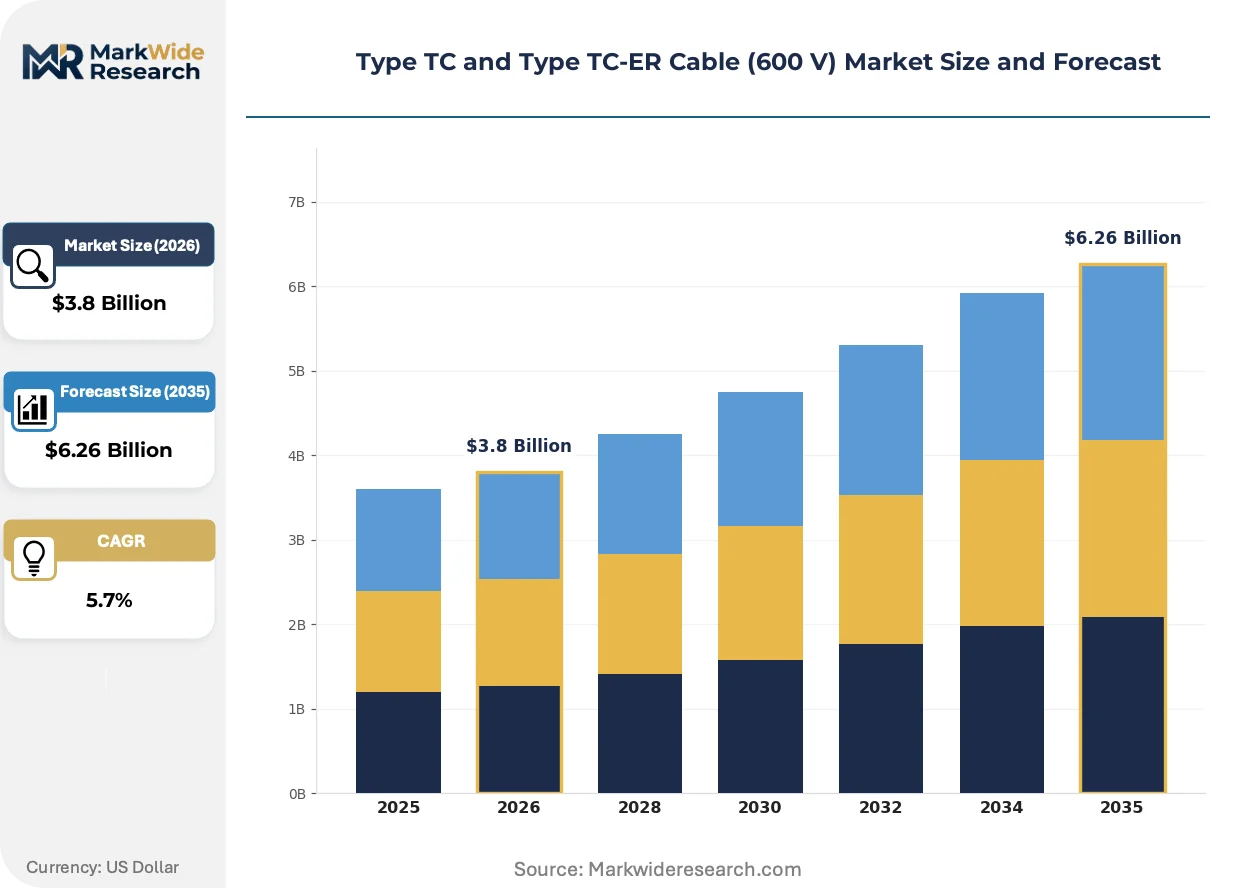
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
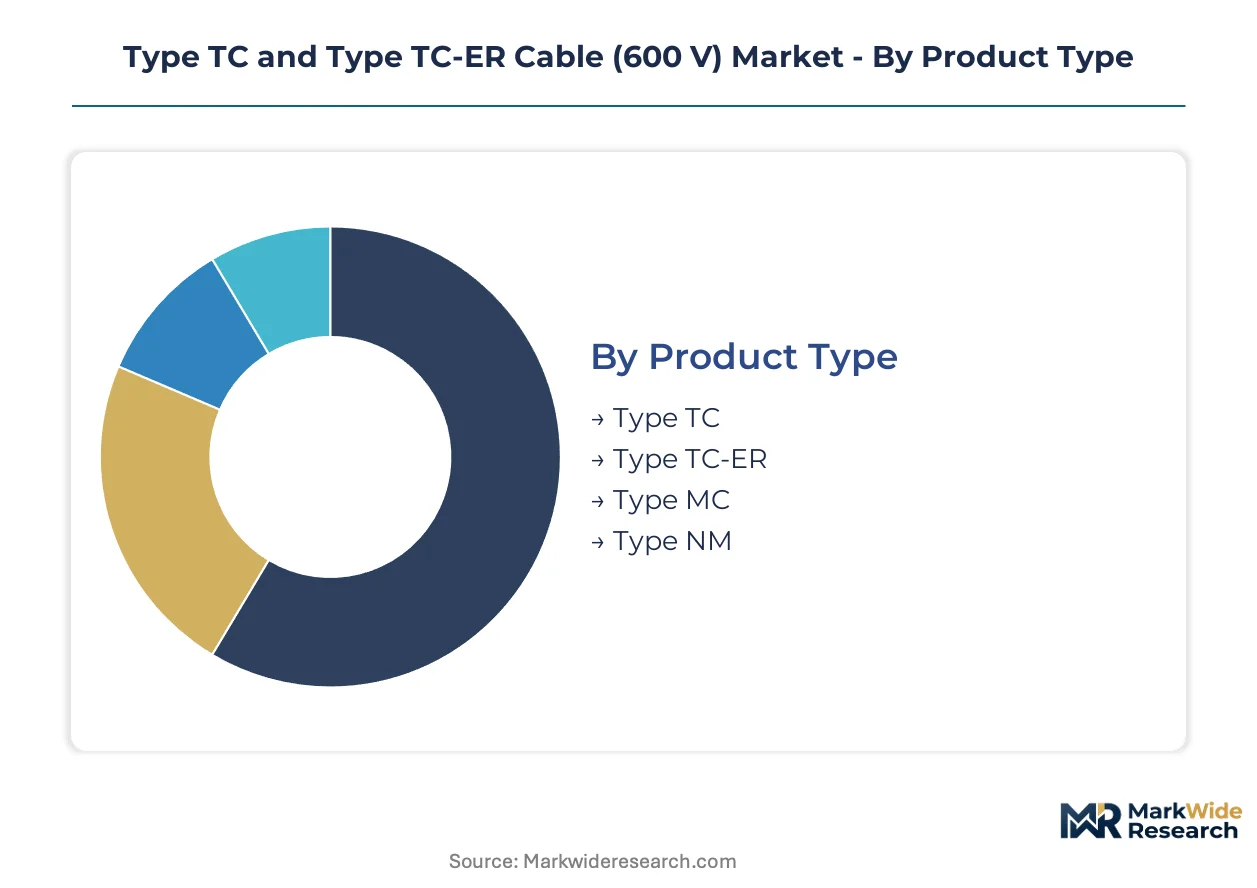
| Segmentation | Product Type: Type TC, Type TC-ER, Type MC, Type NM Application: Industrial, Commercial, Residential, Infrastructure Material: Copper, Aluminum, Steel, Polyethylene Installation Method: Surface Mount, Conduit, Direct Burial, Cable Tray |
| Companies Covered | OmniCable, Allied Wire and Cable, Belden, Shawflex, Galaxy Wire & Cable, General Cable, Multi/Cable, SAB, Service Wire, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Type TC and Type TC-ER Cable (600 V) Market Trends and Innovations
Active material science development and specification tool digitization are compressing traditional procurement cycles while fragmenting the supplier base across performance tiers.
Low-smoke zero-halogen jacket compounds are bifurcating the product architecture between standard PVC-sheathed tray cable and enhanced safety configurations for occupied building applications. Data center operators in Texas and Arizona are specifying LSZH for white space environments, compressing price premiums for traditional thermoplastic alternatives in mission-critical segments.
OSHA's updated electrical safety enforcement protocols are tightening wet-location verification requirements for exposed run installations. Industrial facilities in Ohio manufacturing corridors are responding with third-party witnessed testing documentation, expanding the compliance service layer between manufacturers and end-users.
Electrical contractor procurement patterns are fragmenting across direct manufacturer relationships and specialized distributor networks. Large MEP firms in Dallas-Fort Worth are consolidating spend through OmniCable and similar specialized channels, compressing traditional electrical supply house margins while capturing volume-tier pricing and dedicated inventory allocation.
Type TC and Type TC-ER Cable (600 V) Market Segmentation
Tray cable procurement patterns fragment sharply across voltage ratings, conductor materials, and installation environments. Specification engineers weight ampacity demands against labor cost tradeoffs, while NEC compliance requirements constrain substitution flexibility across project types.
Product Type:
Domestic manufacturing concentrates Type TC and Type TC-ER production in Texas and South Carolina facilities, while Type MC and Type NM sourcing draws more heavily on Mexican and Canadian supply bases for cost-competitive commercial segments.
- Type TC:Stranded copper or aluminum conductors with thermoset insulation and protective jacket, rated for 600 V tray installation without conduit. Demand concentrates in Ohio automotive manufacturing corridors where busway distribution systems require high-conductor-count configurations for power and control circuits.
- Type TC-ER:Exposed run-rated variant permitting direct installation outside cable tray per NEC Article 336, with enhanced crush and impact resistance. Procurement volumes are climbing fastest in Arizona utility-scale solar farms where surface mount and direct burial methods displace rigid conduit runs.
- Type MC:Metal-clad cable with interlocking aluminum armor, suited for industrial environments requiring mechanical protection beyond standard tray ratings.
- Type NM:Non-metallic sheathed cable for residential and light commercial branch circuits, operating at price points below industrial tray cable specifications.
Type TC holds the largest share; momentum sits with Type TC-ER.
Application:
Cost tier differentiation separates premium-specified industrial infrastructure from price-sensitive residential deployment, with commercial and infrastructure segments occupying intermediate positions on total installed cost curves.
- Industrial:Heavy manufacturing, petrochemical processing, and semiconductor fabrication facilities specifying 600 V tray cable for motor control centers and distributed power systems. Texas battery cell plants and Ohio automotive assembly lines are driving procurement volumes with 18-24 month specification windows.
- Infrastructure:Transportation, water treatment, and telecommunications facilities requiring wet-location ratings and enhanced grounding conductor configurations. Federal project specifications are tightening UL 1277 vertical tray fire test requirements, compressing supplier qualification pools.
- Commercial:Office buildings, retail centers, and hospitality properties balancing first-cost constraints against long-term maintenance access considerations.
- Residential:Single-family and multifamily construction where Type NM dominates branch circuit distribution, with limited 600 V tray cable penetration in high-rise service equipment.
Industrial applications command premium pricing tiers; infrastructure is expanding most quickly on federal and utility capital deployment.
Material:
Volume concentration tracks conductor conductivity requirements, with high-ampacity industrial specifications favoring copper despite raw material cost premiums over aluminum alternatives.
- Copper:Stranded annealed copper conductors delivering superior conductivity and flexibility for industrial instrumentation and power distribution. Dallas-Fort Worth data center operators specify copper exclusively for busway distribution bundles, accepting price premiums for thermal performance and voltage drop margins.
- Aluminum:Lightweight conductor alternative for cost-sensitive commercial and infrastructure segments where ampacity requirements permit larger gauge sizing. Arizona solar farm developers are specifying aluminum TC-ER for DC collection circuits to reduce structural loading and material costs.
- Steel:Armor and grounding conductor applications in metal-clad cable configurations.
- Polyethylene:Jacket and insulation compounds for direct burial and wet-location installations requiring moisture resistance.
Copper maintains dominant value share; aluminum is climbing fastest on solar and commercial cost optimization.
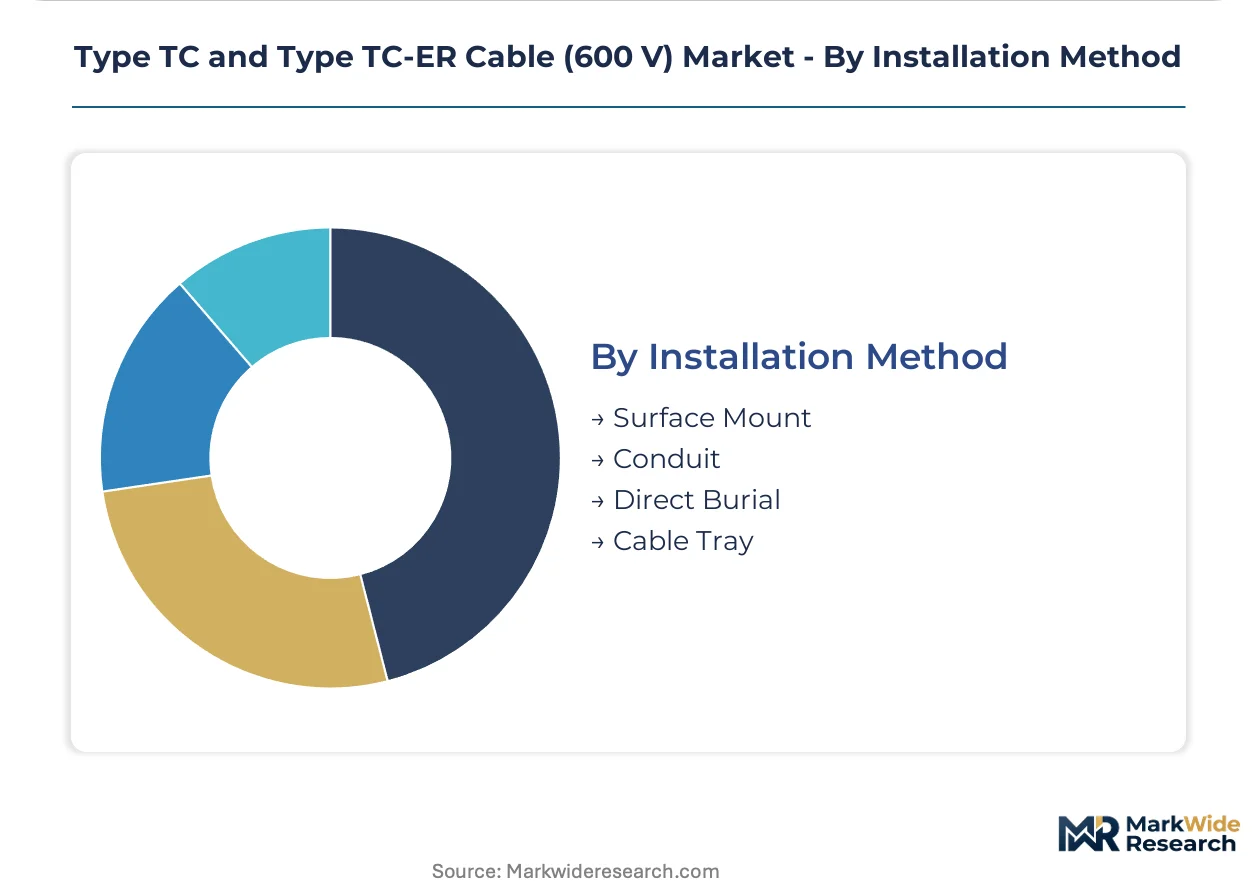
Installation Method:
Customer type fragmentation separates specification-driven MEP engineering firms from price-sensitive electrical contractors, with procurement channel preferences diverging across project scale and complexity tiers.
- Cable Tray:Traditional installation in ladder or ventilated trough systems, representing the mature core application for Type TC with established labor productivity rates and fill ratio calculations. Ohio manufacturing corridors sustain consistent demand for tray-rated configurations in facility expansion and retrofit projects.
- Direct Burial:TC-ER installations in utility-scale solar and outdoor industrial environments, eliminating trenching and conduit material costs. Sherman, Texas semiconductor plants are specifying direct burial TC-ER for substation interconnects to compress construction schedules.
- Surface Mount:Exposed run installations on walls, ceilings, or structural supports where TC-ER ratings permit conduit-free mounting.
- Conduit:Traditional raceway installation method, increasingly displaced by tray-rated and exposed run alternatives where code provisions permit.
Cable Tray retains the largest installed base; Direct Burial is gaining share fastest on utility-scale renewable deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement contexts. Industrial buyers in established manufacturing corridors accept copper premiums for performance reliability. Solar developers and commercial contractors in emerging markets prioritize aluminum configurations to compress installed costs.
United States
Hyperscale data center construction in Dallas-Fort Worth and Phoenix drives procurement of high-conductor-count copper bundles. OSHA electrical safety directives mandate enhanced wet-location ratings for exposed run installations. Texas semiconductor fabrication plants in Austin and Sherman specify TC-ER for substation interconnects to accelerate construction schedules.
Canada
Infrastructure renewal programs and mining electrification projects sustain steady demand for tray-rated cable. The Canadian Electrical Code adoption cycles track NEC amendments with provincial variation. Ontario manufacturing corridors around Toronto and Hamilton specify industrial-grade configurations for facility automation upgrades.
Germany
Industrial automation and automotive manufacturing anchor premium cable consumption. EU REACH regulations and emerging PFAS restrictions compound reformulation pressures for jacket materials. Bavarian industrial clusters around Munich specify enhanced flame-test certifications for federal and institutional project compliance.
China
Domestic data center buildouts and renewable energy infrastructure expand addressable volume. GB standards and MIIT industrial policy shape certification requirements for cable tray installations. Yangtze River Delta manufacturing zones concentrate procurement for semiconductor fabrication and battery cell plants.
India
Commercial construction and utility-scale solar deployment drive cost-optimized aluminum specifications. BIS certification requirements and state-level electrical inspectorates create fragmented compliance landscapes. Gujarat and Maharashtra industrial corridors specify tray cable for pharmaceutical manufacturing and port infrastructure electrification.
Type TC and Type TC-ER Cable (600 V) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with mid-scale regional fabricators occupying price-sensitive segments. The structure rewards manufacturing scale in copper conductor processing and compound formulation capabilities. Strategic archetypes include full-line manufacturers with captive compounding operations, specialized distributors with specification relationships, and regional fabricators serving contractor procurement channels. Competitive moves concentrate on capacity positioning near demand clusters and portfolio diversification into adjacent cable constructions.
Among integrated manufacturers, Belden and General Cable anchor the premium-performance tier with established industrial specification relationships. OmniCable occupies a distinct position as a specialized distributor channel, consolidating electrical contractor spend through dedicated inventory allocation and volume-tier pricing structures. Shawflex and Service Wire exemplify regional fabricators competing on lead-time compression and customized conductor configurations for project-specific procurement.
| Leading Market Players |
|---|
| OmniCable |
| Allied Wire and Cable |
| Belden |
| Shawflex |
| Galaxy Wire & Cable |
| General Cable |
| Multi/Cable |
| SAB |
| Service Wire |
| Others |
Pricing and Supply Chain Analysis
Copper conductor processing scale in Texas and South Carolina facilities anchors manufacturing cost structures, compressing price floors for integrated producers while fragmenting margin structures across distributor tiers. This concentration pattern concentrates procurement leverage with high-volume MEP contractors and hyperscale data center operators who command volume-tier pricing through consolidated spend programs.
Pricing Analysis
After-sales service bundling and specification support contracts drive lifetime value differentiation between integrated manufacturers and distributor channels. Three-tier pricing structure across premium UL 1277-listed, standard tray-rated, and economy aluminum configurations separates procurement tiers by certification grade and conductor material. Pricing pressure stems from LME copper volatility and PFAS compound reformulation costs compressing margin structures for distributors holding medium-gauge inventory. Electrical contractors exhibit highest price sensitivity, while data center operators accept copper premiums for thermal performance reliability.
Supply Chain Analysis
Inventory lead times for specialized thermoset compounds stretch procurement cycles, particularly for TC-ER configurations requiring enhanced crush resistance validation. Thermoplastic and thermoset compound production clusters in the United States Gulf Coast and South Carolina draw from copper rod mills in Arizona and Ohio, with jacketing materials resting on petrochemical feedstock networks. Single-source vulnerability concentrates in Gulf Coast compound production exposed to hurricane disruption. Distribution runs through specialized electrical distributor networks and direct manufacturer relationships serving large MEP firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Type TC and Type TC-ER cable demand sits in early-cycle expansion as data center power density requirements and utility-scale solar deployment accelerate specification penetration beyond traditional industrial applications.
For Market Incumbents: Consolidate specification relationships with Dallas-Fort Worth and Phoenix data center developers through dedicated inventory allocation and UL 1277 enhanced flame-test certification investment. Defend against regional distributor consolidation by capturing direct procurement relationships with large MEP contractors seeking volume-tier pricing and project-specific conductor configurations. For New Entrants and Emerging Players: UL 1277 fast-track certification programs open qualification pathways for federal and institutional project participation where incumbent supplier pools remain narrow. White-space opportunity concentrates in aluminum TC-ER direct burial configurations for Arizona utility-scale solar farms, with go-to-market positioning through EPC contractor channel partnerships bypassing established electrical supply house networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compound formulation capabilities and captive copper conductor processing over pure distribution plays. Long-term viability rests on backward integration into specialized jacket materials and wet-location rating certifications. The signal to watch is state-by-state NEC Article 336 adoption velocity as inflection indicator for certification demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| UL 1277 Enhanced Flame-Test Certification | Vertical tray fire performance listings unlock federal and institutional project qualification pools. |
| Backward Integration into Compound Formulation | Captive thermoset production insulates margin structures from Gulf Coast supply disruption. |
| Direct MEP Contractor Channel Development | Bypassing traditional electrical supply houses captures volume-tier pricing and specification lock-in. |
| Aluminum TC-ER Product Line Expansion | Cost-optimized configurations penetrate Arizona solar farm and commercial infrastructure segments. |
| Digital Specification Tool Integration | BIM plugin penetration creates procurement workflow embedding and reduces competitive bid exposure. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with electrical contractors, MEP engineering firms, data center facility managers, and distributor procurement leads; and secondary validation against NEC amendment documentation, UL listing databases, OSHA electrical safety directives, copper commodity trade data, and EPC project development filings. Bottom-up installation volume estimates triangulated against top-down cable procurement spend patterns across identified demand clusters.
Across the projection horizon, the analytical framework modeled segmentation by product type, conductor material, installation method, and application vertical with regional production hub differentiation. CAGRs derived from installation volume trajectories weighted against copper price normalization assumptions and NEC adoption cycle timing. Forecast inputs incorporated data center power density specifications and utility-scale solar interconnection standards.
Decision-makers should treat outputs as directional under stable copper commodity pricing and NEC amendment adoption timelines; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Electric Submersible Cables (ESP) Market
Cables
Cable Carrier Market
Cables
Military Fiber Optic Cables Market
Cables
Cable Management System Market
Cables
Radio Frequency Cables Market
Cables
Wire and Cable Label Market
Cables
EPR Cable Market
Cables
Cable Assembly Market
Cables
FFC/FPC Jumper Cables Market
Cables
Multi-Core Land High Voltage Underground Cable Market
Cables
Europe Cable Accessories Market
Cables
Global Cable Blowing Equipment Market
Cables
Premise Cable Market
Cables
Japan Cables Market
Cables
Cable Fault Locator Market
Cables
North America Patch Cable Market