
 US Medium Voltage Cable Accessories Market | 2026-2036
US Medium Voltage Cable Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
US Medium Voltage Cable Accessories Market Insights
Utility procurement is pivoting toward fewer, larger transmission buildouts that bundle medium voltage accessories into multi-year supply agreements. Southwire Company leverages its southeastern manufacturing footprint to anchor utility relationships across the Southeast. TE Connectivity sustains technology leadership in heat-shrink termination systems for underground installations. Prysmian competes through specialized submarine and land cable integration capabilities that reduce interface risk for developers.
Medium voltage cable accessories encompass connectors, joints, terminations, insulators, and lugs engineered for electrical systems operating between 1 kV and 69 kV, typically manufactured from cross-linked polyethylene, ethylene propylene rubber, or silicone compounds with conductive and stress-control layers. These components manage electrical field distribution, environmental sealing, and mechanical connection integrity in power distribution networks. Terminations and joints command the largest product share due to recurring replacement cycles in aging underground infrastructure, while renewable energy facilities represent the fastest-growing application segment driven by interconnection queue backlogs. Data centers emerge as a concentrated margin pool where uptime requirements justify premium accessory specifications.
NHTSA corridor electrification guidelines and FERC Order 2023 interconnection reforms shape utility capital allocation toward standardized, rapidly deployable medium voltage systems. IEEE 404 and IEEE 622 test standards govern accessory performance validation, creating compliance barriers for unqualified suppliers. Stakeholders must monitor state public utility commission procurement rulemakings that increasingly mandate domestic content verification for federally subsidized grid projects.
Market Dynamics
Utility procurement consolidation around renewable interconnection projects is compressing supplier qualification timelines while elevating performance specifications for medium voltage accessories. FERC Order 2023 reforms and EPA emissions standards are synchronizing capital deployment across Texas, California, and offshore wind corridors.
Growth Catalysts
- FERC Order 2023 Interconnection Reforms:Standardized study processes accelerate queue clearance for utility-scale solar and storage projects, pulling forward medium voltage infrastructure procurement cycles.
- Texas and California Transmission Buildouts:ERCOT interconnection backlogs and CAISO offshore wind integration mandates concentrate demand for 15-35 kV termination and joint systems.
- Cross-linked Polyethylene (XLPE) Material Advances:Enhanced treeing resistance and thermal cycling performance extend accessory service life in direct-buried renewable applications.
Market Restraints
- Copper and Aluminum Price Volatility:Conductor material cost swings compress margin predictability for lugs and connector manufacturers serving price-capped utility contracts.
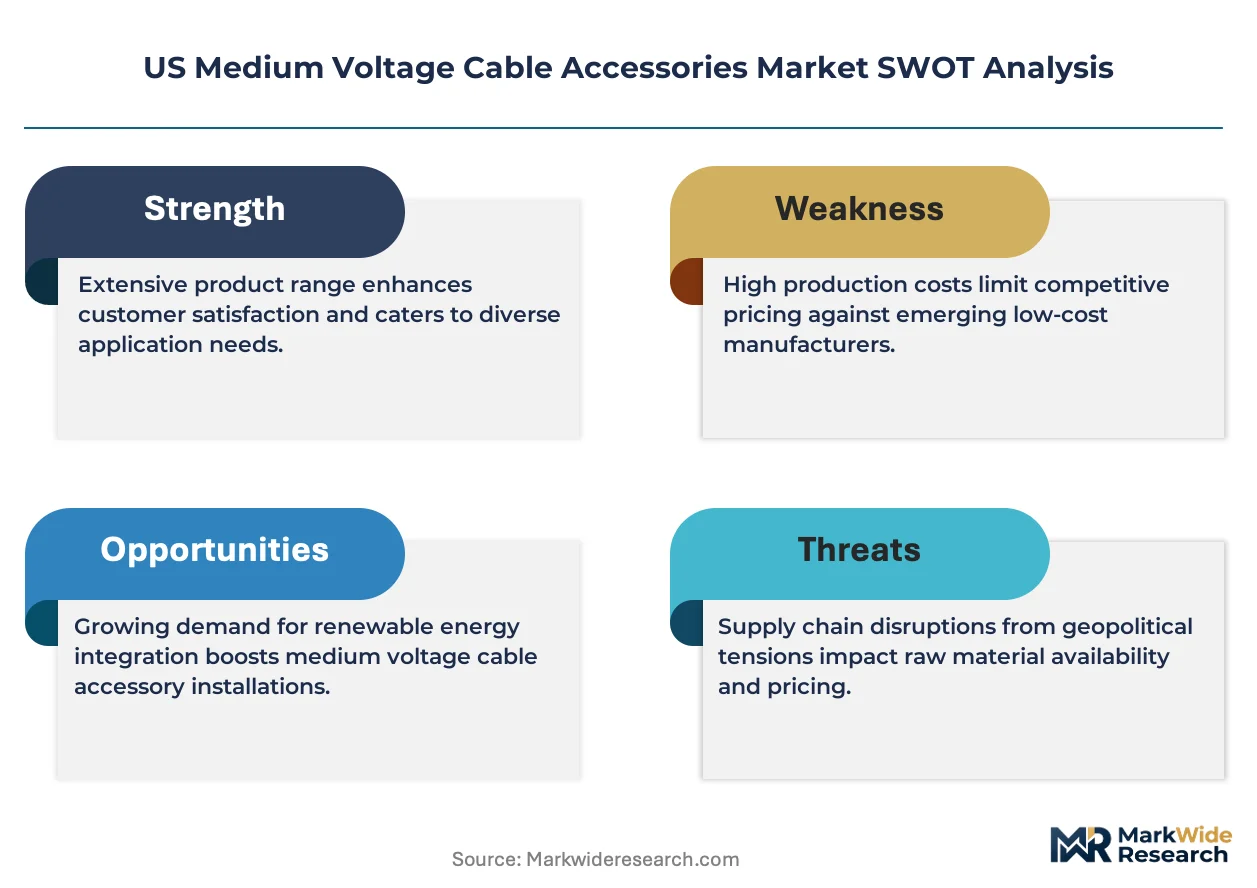
- Domestic Manufacturing Concentration:Limited qualified US-based production of silicone rubber stress-control components creates single-source vulnerability for heat-shrink termination suppliers.
- IEEE 404 Testing Burden:Extended qualification timelines for new accessory designs delay product commercialization against faster-moving import competitors.
Strategic Opportunities
- Data Center Power Distribution:Hyperscale facility construction in Northern Virginia and Phoenix creates concentrated demand for fault-tolerant medium voltage terminations with 99.999% uptime specifications.
- Inflation Reduction Act Domestic Content Bonuses:Ten percentage point tax credit adders for US-manufactured components incentivize reshoring of EPDM rubber molding and metal casting operations.
- Digital Twin Integration:Convergence of asset monitoring sensors with medium voltage accessories enables predictive maintenance contracts and recurring revenue streams for utilities.
Industry Challenges
- Medium Voltage Cable Splicer Certification Pipeline:Joint Apprenticeship and Training Committee programs produce fewer qualified technicians than replacement demand from retiring utility workforces.
- Legacy Paper-Insulated Lead-Covered (PILC) System Integration:Transition interfaces between aging underground networks and modern XLPE accessories require custom-engineered solutions that fragment production scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Medium Voltage Cable Accessories Market |
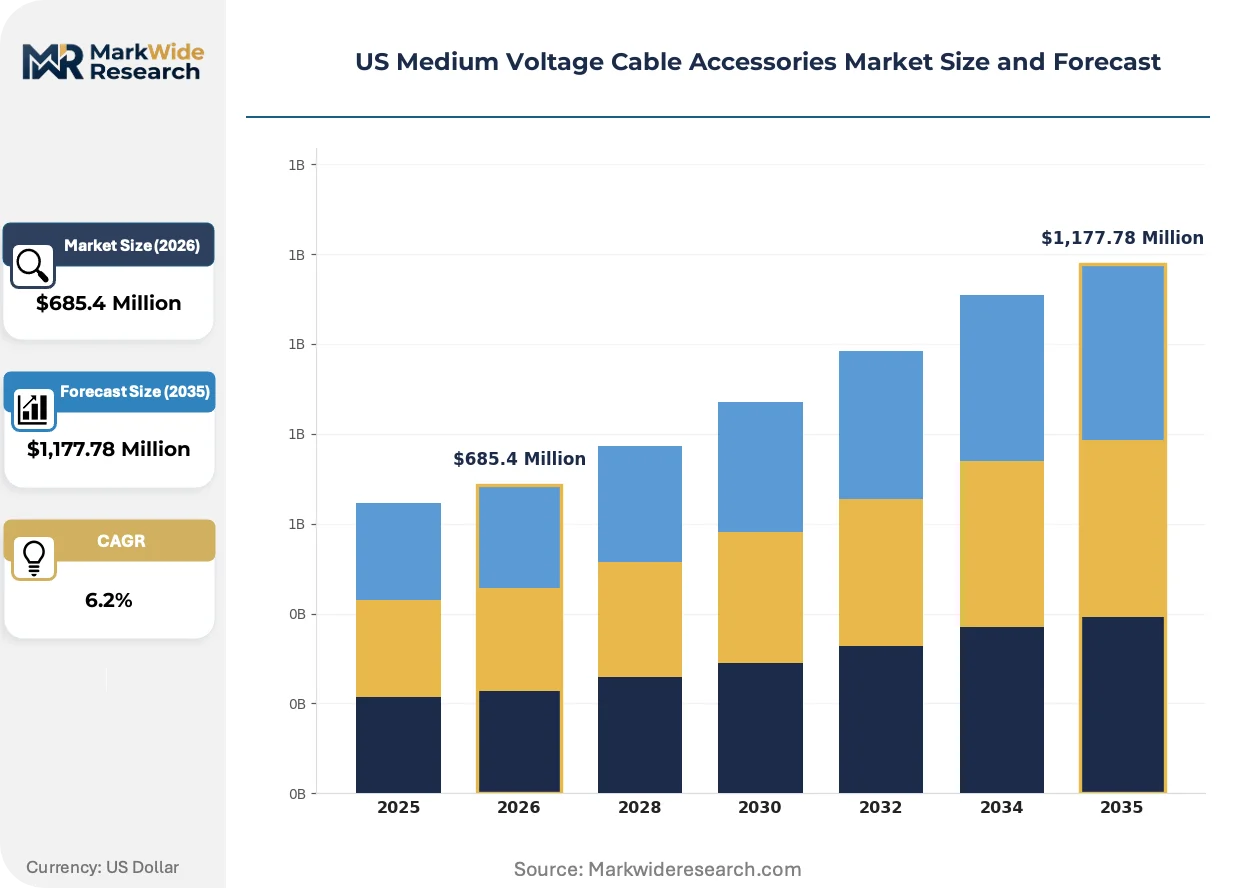
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Connectors, Joints, Terminations, Insulators, Lugs Application: Electric Utilities, Renewable Energy Facilities, Commercial Complexes, Data Centers, Transportation Networks End User: Power Generation Companies, Electrical Contractors, Industrial Facilities, Infrastructure Developers Installation: Underground, Overhead, Substation, Industrial Plants |
| Companies Covered | 3M, TE Connectivity, ABB, Prysmian, Nexans, Southwire Company, Sumitomo Electric U.S.A., General Cable, NKT, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Medium Voltage Cable Accessories Market Trends and Innovations
Material science advances and digital instrumentation are redefining accessory performance benchmarks while procurement centralization reshapes supplier relationships. Three developments dominate the technology and commercial landscape.
Cold-shrink silicone rubber termination technology is integrating factory-applied stress-control layers with integrated partial discharge sensors. Major Texas utilities deploying utility-scale solar farms specify these systems for their field-installation speed and reduced skilled-labor dependency. The technology is compressing project commissioning schedules from weeks to days in high-volume renewable interconnection corridors.
EPA power plant emissions standards finalized in 2024 mandate coal retirement timelines that accelerate distribution grid reinforcement investments. State public utility commissions in the Midwest and Southeast are approving accelerated depreciation schedules for medium voltage infrastructure replacements. Investor-owned utilities in Ohio and Indiana are front-loading accessory procurement to capture IRA domestic content incentives before phase-down triggers.
Multi-year supply agreements now displace transactional spot purchasing for termination and joint systems. Utility procurement teams in California and Texas bundle five-year accessory requirements into single-source contracts with volume commitments and price collars. This concentration is visible most acutely in ERCOT zones where interconnection queue velocity depends on predictable material availability.
US Medium Voltage Cable Accessories Market Segmentation
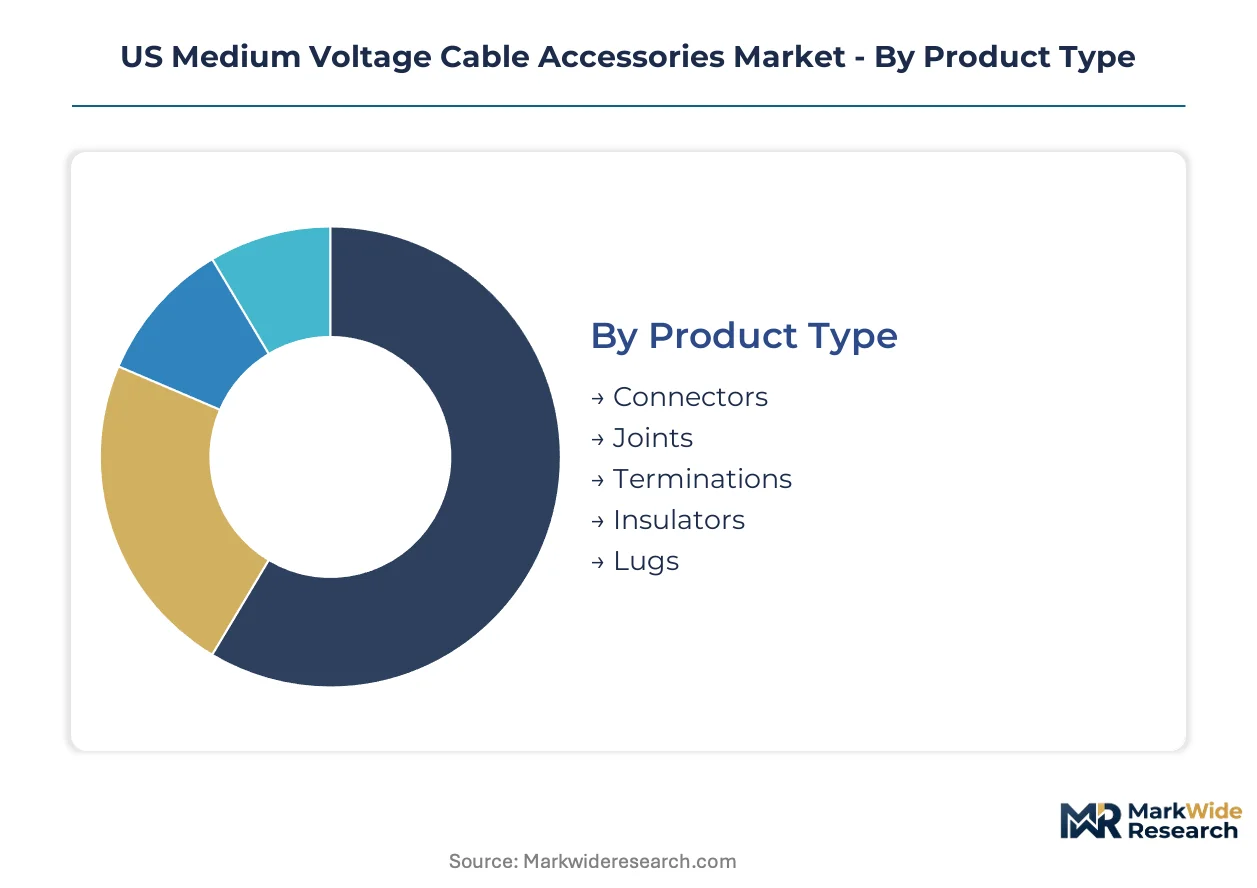
Medium voltage cable accessories demand fragments across technical specifications, installation environments, and procurement channels. Understanding these divisions reveals where IEEE 404 compliance burdens concentrate and which customer segments prioritize premium performance over cost minimization.
Product Type:
IEEE 404 qualification timelines vary sharply across product categories, with termination systems requiring the most extensive electrical field validation and lugs facing streamlined mechanical testing protocols.
- Terminations:Heat-shrink and cold-shrink silicone rubber assemblies manage electrical stress distribution in 15-35 kV underground circuits. ERCOT solar interconnection projects in West Texas specify factory-tested cold-shrink systems to compress commissioning schedules amid splicer shortages.
- Joints:XLPE-insulated splice kits bridge cable sections with conductive and stress-control layers engineered for direct-buried renewable applications. California offshore wind transmission buildouts drive demand for submarine-rated joint systems with integrated sealing technology.
- Connectors:Mechanical and compression fittings terminate conductor ends with torque-controlled reliability standards.
- Insulators:Polymeric housings provide environmental protection and tracking resistance for exposed terminations.
- Lugs:Copper and aluminum terminal fittings attach conductors to equipment bushings and switchgear.
Leading the category by volume: Joints. Growing fastest: Terminations.
Application:
End-use concentration determines margin structure, with uptime-critical facilities accepting premium pricing while price-capped utility contracts compress supplier returns.
- Renewable Energy Facilities:Utility-scale solar and offshore wind interconnection projects require 15-35 kV termination and joint systems engineered for thermal cycling and moisture resistance. FERC Order 2023 queue reforms accelerate procurement cycles across Texas and California ISO zones.
- Data Centers:Hyperscale facilities in Northern Virginia and Phoenix specify fault-tolerant medium voltage accessories with 99.999% uptime requirements and integrated partial discharge monitoring.
- Electric Utilities:Investor-owned and municipal distribution networks replace aging underground infrastructure on accelerated depreciation schedules.
- Commercial Complexes:Mixed-use developments specify standard-grade termination systems for secondary distribution vaults.
- Transportation Networks:NHTSA corridor electrification guidelines drive medium voltage infrastructure for EV charging hubs and rail electrification.
Revenue concentrates in: Electric Utilities. Expanding most quickly: Renewable Energy Facilities.
End User:
Procurement authority and technical specification control shift dramatically across buyer types, fragmenting supplier go-to-market requirements.
- Power Generation Companies:Utility-scale developers bundle multi-year accessory procurement into engineering-procurement-construction contracts with volume commitments and domestic content verification.
- Electrical Contractors:Installation firms specify field-proven termination systems that minimize skilled-labor dependency and commissioning risk.
- Industrial Facilities:Manufacturing plants prioritize maintenance-interval predictability over initial acquisition cost for critical power distribution circuits.
- Infrastructure Developers:Public-private partnership sponsors negotiate lifecycle cost guarantees that favor premium accessory specifications with extended warranty terms.
Contract volume dominates: Power Generation Companies. Procurement velocity climbing fastest: Infrastructure Developers.
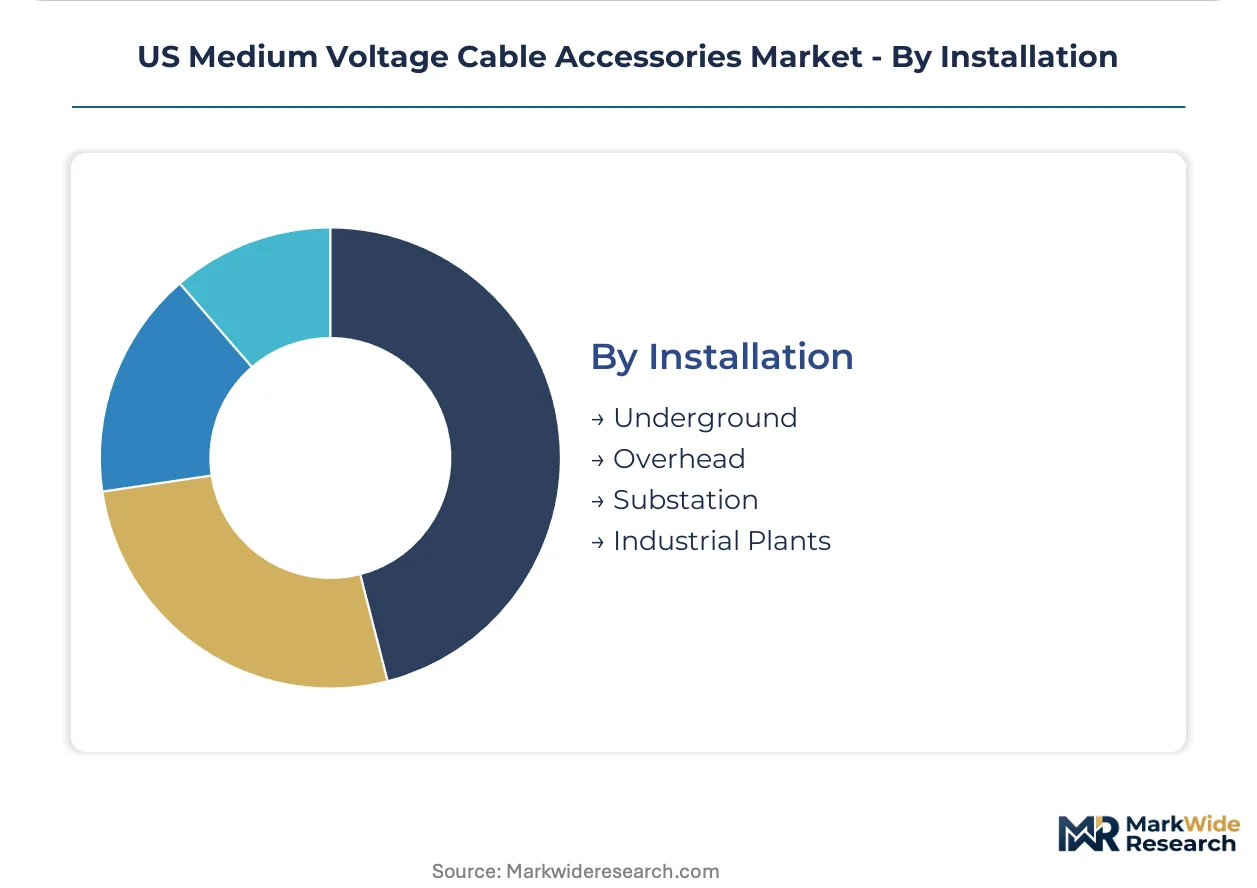
Installation:
Environmental exposure conditions dictate material selection and sealing technology, with buried applications commanding premium specifications.
- Underground:Direct-buried and duct-bank installations require moisture-impermeable terminations and joints with enhanced treeing resistance. Texas utility-scale solar farms deploy cold-shrink systems for field-speed advantages.
- Substation:Switchgear and transformer terminations demand compact, phase-separated designs with high-current carrying capacity.
- Overhead:Aerial line accessories integrate bird-guard and contamination-resistant housing for exposed environments.
- Industrial Plants:Process facility installations specify chemical-resistant EPDM rubber compounds and flame-retardant specifications.
Installation base by unit volume: Underground. Steepest expansion trajectory: Substation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for medium voltage cable accessories concentrates in Texas and California, where interconnection queues for utility-scale solar and offshore wind transmission buildouts drive procurement volumes. ERCOT backlogs and CAISO integration mandates synchronize capital deployment timelines across these states. Regional variation reflects divergent regulatory frameworks, renewable resource endowments, and utility ownership structures.
Texas
Utility-scale solar farms in West Texas deploy cold-shrink termination systems to compress commissioning schedules amid acute splicer shortages. ERCOT interconnection backlogs exceeding 180 gigawatts pull forward medium voltage infrastructure procurement cycles. Major developers in the Permian Basin and Rio Grande Valley specify factory-tested joint systems for direct-buried renewable applications.
California
Offshore wind transmission integration mandates from the California Public Utilities Commission accelerate demand for submarine-rated joint systems with integrated sealing technology. CAISO queue reforms align with state renewable portfolio standards requiring 100% clean electricity by 2045. Port of Long Beach and Humboldt Bay offshore wind staging areas concentrate procurement for 35 kV termination assemblies.
Midwest
Ohio and Indiana investor-owned utilities front-load accessory procurement to capture Inflation Reduction Act domestic content incentives before phase-down triggers. State public utility commissions approve accelerated depreciation schedules for aging underground infrastructure replacement. Indianapolis and Columbus distribution reinforcement projects specify XLPE-insulated splice kits for thermal cycling performance.
Southeast
Southwire Company anchors utility relationships across Georgia, North Carolina, and Florida through southeastern manufacturing proximity. Duke Energy and Southern Company procurement teams bundle five-year accessory requirements into multi-year supply agreements with volume commitments. Atlanta and Charlotte data center construction creates secondary demand for fault-tolerant medium voltage terminations.
Northeast
Offshore wind lease areas off Massachusetts and New York drive procurement for specialized submarine and land cable integration capabilities. State renewable portfolio standards in Connecticut and New Jersey mandate accelerated grid modernization timelines. Boston and New York City underground network reinforcement projects require custom-engineered transition interfaces between legacy PILC systems and modern XLPE accessories.
US Medium Voltage Cable Accessories Market Competitive Landscape
US-based producers anchor the domestic content tier; European and Japanese specialists hold technology leadership positions in heat-shrink and cold-shrink systems. The vendor base separates into three distinct tiers: integrated cable manufacturers with captive accessory production, pure-play accessory specialists with IEEE 404 qualification depth, and regional fabricators serving price-sensitive municipal contracts. Strategic moves concentrate on multi-year supply agreement anchoring and domestic manufacturing reshoring to capture IRA tax credit adders.
Within the integrated manufacturer tier, 3M and TE Connectivity exemplify technology leadership archetypes through their positions in termination system innovation. Southwire Company occupies a geographic anchoring role across the Southeast utility corridor. Prysmian and Nexans represent European-based specialists competing through submarine and land cable integration capabilities that reduce interface risk for developers.
| Leading Market Players |
|---|
| 3M |
| TE Connectivity |
| ABB |
| Prysmian |
| Nexans |
| Southwire Company |
| Sumitomo Electric U.S.A. |
| General Cable |
| NKT |
| Others |
Pricing and Supply Chain Analysis
Cold-shrink silicone rubber termination technology is compressing field installation times from weeks to days, simultaneously reducing labor cost exposure for developers and concentrating procurement power among suppliers with qualified manufacturing footprints. This production-method transition elevates performance premiums for factory-tested systems while squeezing margins on legacy heat-shrink alternatives.
Pricing Analysis
Volume concentrates in utility-scale renewable interconnection projects while margins pool in data center specifications with 99.999% uptime requirements. Three-tier pricing structure across premium, standard, and economy levels separates IEEE 404-qualified cold-shrink systems from field-assembled heat-shrink alternatives and import-sourced commodity fittings. Price differentiation hinges on certification grade and domestic content verification for IRA tax credit eligibility. Cost compression in standard-grade lugs and connectors is intensifying because copper and aluminum price volatility erodes predictability under price-capped utility contracts. Investor-owned utilities exhibit lowest price sensitivity due to accelerated depreciation schedules, while municipal distributors face hardest procurement constraints.
Supply Chain Analysis
Reverse-logistics flows for terminated cable sections and refurbished joint assemblies remain underdeveloped, creating stranded asset risk for utilities managing aging underground networks. Manufacturing concentrates in the United States, Germany, and Japan for silicone rubber stress-control components and XLPE-insulated splice systems. Raw material dependencies center on conductive-grade copper, aluminum alloy feedstock, and specialized EPDM rubber compounds. Single-source vulnerability for heat-shrink termination suppliers stems from limited qualified US-based production of critical stress-control layers. Distribution runs through direct OEM supply to investor-owned utilities and electrical contractors, with secondary channels serving municipal distributors and industrial facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive control over silicone rubber molding and EPDM compound production to secure IRA domestic content bonuses and insulate margin structures from commodity volatility.
For Market Incumbents: Lock in multi-year supply agreements with ERCOT and CAISO zone utilities before FERC Order 2023 queue reforms accelerate procurement cycles. Anchor southeastern manufacturing relationships against Southwire Company's geographic positioning through capacity expansion in Texas renewable corridors. Deepen backward integration into EPDM rubber molding to capture ten percentage point tax credit adders and defend against import competitors with faster IEEE 404 qualification timelines.
For New Entrants and Emerging Players: Municipal utilities in the Midwest face acute supplier concentration risk and limited qualified domestic sources for cold-shrink termination systems. Data center developers in Northern Virginia and Phoenix specify fault-tolerant accessories with integrated partial discharge monitoring where incumbent coverage remains thin. Enter through digital twin integration partnerships that bundle asset monitoring sensors with medium voltage accessories, creating recurring revenue streams that differentiate from transactional component sales.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated cable manufacturers seeking IEEE 404 qualification depth and utility relationship anchoring. Long-term viability favors pure-play accessory specialists with demonstrated submarine and land cable integration capabilities that reduce interface risk for offshore wind developers. Monitor state public utility commission procurement rulemakings that mandate domestic content verification as the inflection indicator for reshoring investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Reshoring | Captures IRA tax credit adders for US-manufactured silicone rubber and EPDM components. |
| Multi-Year Supply Agreement Anchoring | Bundles five-year accessory requirements into single-source contracts with ERCOT and CAISO utilities. |
| Digital Twin Integration Development | Converges asset monitoring sensors with terminations to enable predictive maintenance contracts. |
| Submarine Cable Integration Capability | Reduces interface risk for California and Northeast offshore wind transmission buildouts. |
| Cold-Shrink Technology Scale-Up | Compresses commissioning schedules for Texas utility-scale solar farms amid splicer shortages. |
Research Methodology
Independent corroboration across utility procurement officers, electrical contractor project managers, and EPC developer engineering directors underwrites the qualitative findings in this study. Primary interviews with IEEE 404 test laboratory technicians, silicone rubber compound specialists, and state public utility commission staff combined with secondary validation from FERC interconnection queue databases, EIA transmission investment disclosures, and SEC utility 10-K filings. Bottom-up project pipeline aggregation and top-down utility capital expenditure triangulation anchored market size estimates.
Rate-of-change decomposition across renewable interconnection velocity, data center construction permits, and utility depreciation schedule approvals structured the analytical framework. Segmentation modeling incorporated product type, installation environment, end-user procurement authority, and regional regulatory framework dimensions. CAGRs derived from weighted average of utility capital deployment timelines and project commissioning schedules. Forecast inputs included FERC Order 2023 implementation pace and IRA domestic content bonus phase-down triggers.
Revisions become necessary when FERC interconnection reform implementation stalls, copper price volatility exceeds historical bands, or state public utility commissions delay domestic content rulemakings. Practitioners should monitor ERCOT queue clearance rates and CAISO offshore wind integration mandates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Low-Temperature Cable Market
Cables
Latin America Wire and Cable Market
Cables
Type TC and Type TC-ER Cable (600 V) Market
Cables
Europe Cable Accessories Market
Cables
Copper Stranded Wire Market
Cables
Japan Cables Market
Cables
Radio Frequency Cables Market
Cables
Middle East Cable Market
Cables
Downhole Cables Market
Cables
EPR Cable Market
Cables
Fiber Optic Cables for Military & Aerospace Market
Cables
Submarine Cables Market
Cables
Fire Resistance Cable Market
Cables
UK Cables Market
Cables
Underground Cable Market
Cables
Europe Cable Management Market