
 Latin America Wire and Cable Market | 2026-2036
Latin America Wire and Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Wire and Cable Market Insights
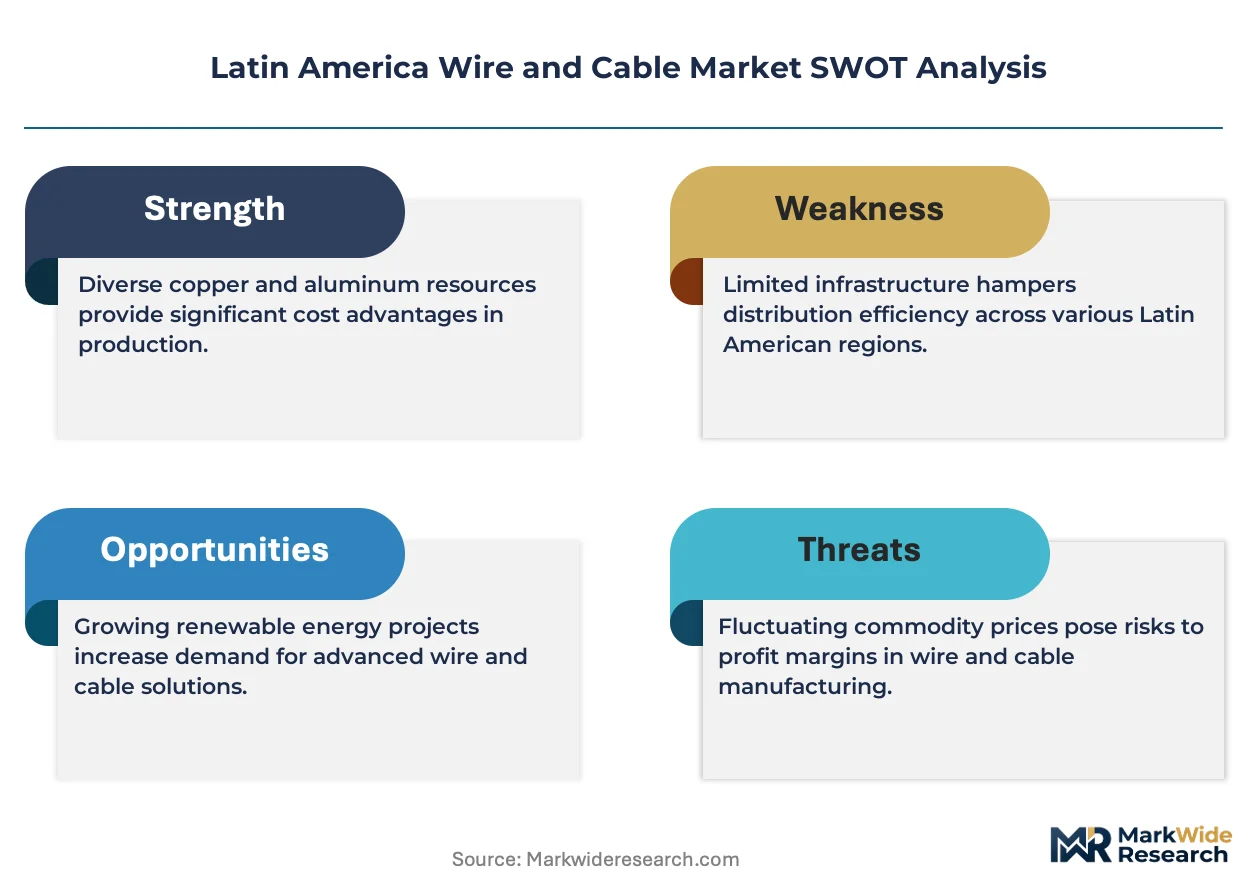
Renewable energy developers is rotating share from traditional construction buyers across Latin America wire and cable procurement. Prysmian Group leverages its regional manufacturing footprint to anchor utility-scale project deliveries from Brazil to Chile. Southwire Company LLC competes through specialized aluminum conductor offerings tailored to transmission line specifications. Nexans differentiates via deep technical expertise in submarine cable systems for offshore wind interconnectors.
Latin America wire and cable encompasses insulated electrical conductors engineered to transmit power, data, or control signals across rated voltage classes from low-tension building wire to extra-high-voltage transmission lines, with copper and aluminum metallurgy determining ampacity, thermal performance, and tensile loading parameters. Power cable occupies the largest value pool across the region given grid expansion and renewable interconnection mandates, while fiber optic cable represents the fastest-expanding segment as telecom operators deploy 5G backhaul and rural broadband infrastructure. Copper material specifications command premium positioning in industrial and energy applications where conductivity standards resist substitution, though aluminum gains ground in long-span transmission economics.
Brazil's ANATEL, Mexico's NOM framework under the national standards body, and Chile's SEC electrical safety certification collectively shape product compliance requirements for cross-border cable shipments. These regulators enforce fire-resistance ratings, halogen-free insulation standards, and electromagnetic compatibility protocols that filter import eligibility and drive domestic testing investments. Stakeholders must monitor evolving local-content thresholds and reciprocal certification agreements that could redraw competitive access across Andean, Mercosur, and Pacific Alliance trade configurations.
Market Dynamics
Utility-scale renewable interconnection mandates are compressing procurement cycles across Latin America, forcing cable manufacturers to reconfigure production schedules around project-financing timelines rather than traditional inventory cycles.
Growth Catalysts
- Grid Modernization Mandates:Brazil's ANEEL transmission auctions and Chile's SEC grid reliability standards are accelerating medium-voltage cable deployments for renewable integration.
- 5G Backhaul Infrastructure:Mexican telecom operators under NOM-121 certification requirements are expanding fiber optic cable procurement for urban densification and rural broadband expansion.
- Aluminum Conductor Economics:Long-span transmission developers across the Andean region are specifying aluminum alloy conductors to reduce tower loading and right-of-way costs.
Market Restraints
- Copper Price Volatility:London Metal Exchange copper futures fluctuations are compressing margin visibility for manufacturers locked into fixed-price utility tenders.
- Import Certification Friction:ANATEL electromagnetic compatibility testing protocols in Brazil are extending lead times for Asian communication cable suppliers.
- Technical Substitution Limits:High-temperature superconducting cables remain commercially unviable for Latin American transmission projects due to cryogenic cooling infrastructure gaps.
Strategic Opportunities
- Submarine Cable Systems:Offshore wind developers in southern Brazil are creating demand for subsea interconnection expertise currently concentrated in European suppliers.
- Halogen-Free Insulation Mandates:Chilean building code updates are opening specification windows for low-smoke zero-halogen cable grades in commercial construction.
- Direct Utility Contracting:State-owned transmission operators in Colombia and Peru are bypassing traditional distribution channels for high-voltage project procurement.
Industry Challenges
- Certification Timeline Compression:ANATEL and SEC parallel testing requirements are straining regional laboratory capacity for new product introductions.
- Specialized Installation Workforce:Extra-high-voltage cable jointing and termination skills are concentrated among aging technician pools in Argentina and Brazil.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Wire and Cable Market |
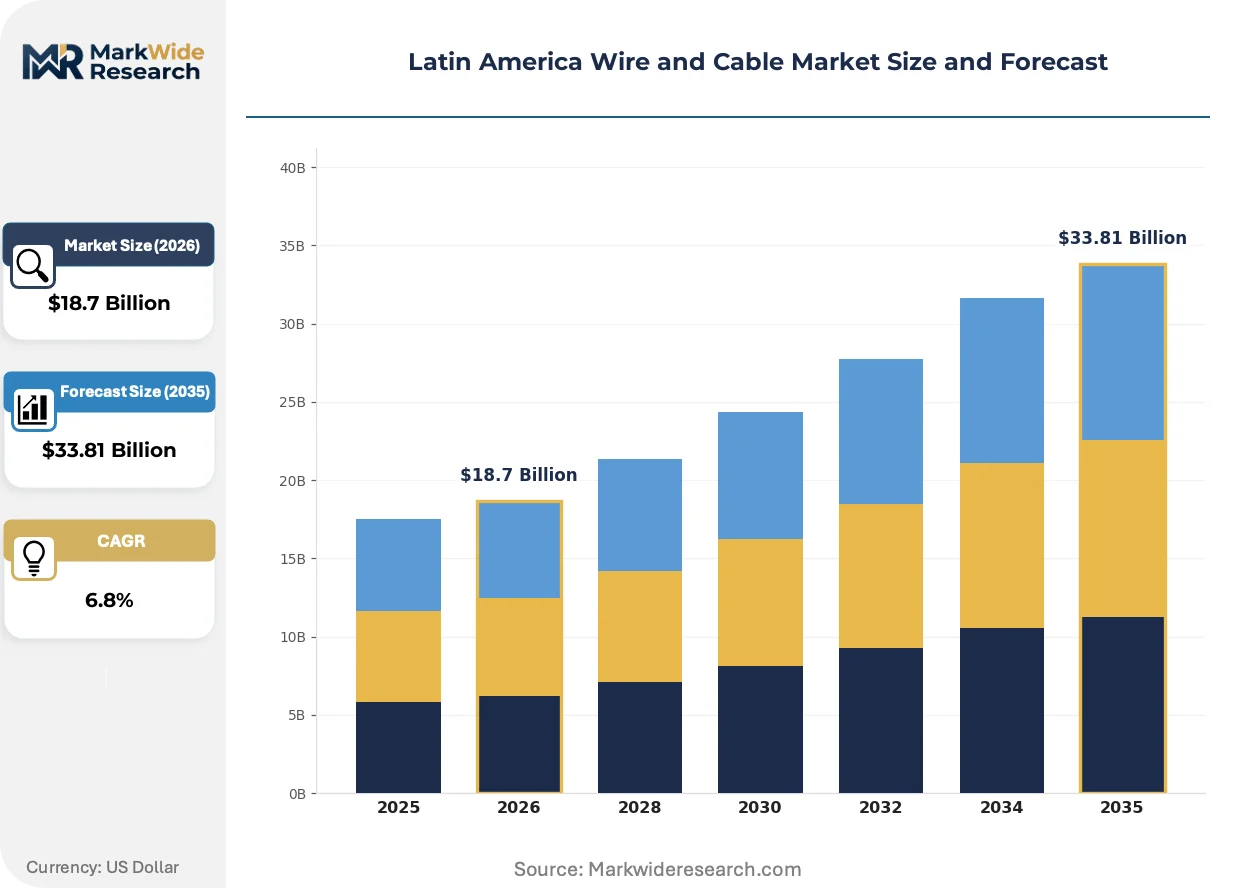
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Cable, Communication Cable, Control Cable, Fiber Optic Cable Material: Copper, Aluminum, Steel, PVC End User: Telecom, Energy, Construction, Industrial Deployment: Onshore, Offshore, Urban, Rural |
| Companies Covered | Prysmian Group, TFKable, TE Connectivity, Southwire Company LLC, Nexans, Encore Wire, Fujikura Ltd, Belden Incorporated, American Wire Group, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Wire and Cable Market Trends and Innovations
Cross-linked polyethylene insulation formulations and digital monitoring integration are reshaping cable specification priorities across Latin American transmission and distribution procurement.
Cross-linked polyethylene medium-voltage insulation is fragmenting procurement specifications between utilities demanding 40-year service life guarantees and industrial buyers prioritizing capital cost minimization. Brazilian distribution concessionaires are adopting tree-retardant XLPE formulations for humid climate performance. This fragmentation is compressing standardization efforts across Mercosur technical harmonization committees.
Mexico's NOM-001-SEDE electrical safety standards are tightening fire-resistance testing protocols for building wire imports. Manufacturers must now demonstrate circuit integrity under direct flame exposure for extended durations. Low-voltage construction cable suppliers are restructuring product portfolios to meet these specifications ahead of enforcement deadlines.
Integrated fiber optic sensing is displacing conventional thermal monitoring in high-ampacity transmission corridors. Colombian grid operators are specifying distributed temperature sensing cables for real-time conductor rating optimization. Chilean mining electrification projects are driving adoption of power-signal hybrid cables for remote equipment monitoring.
Latin America Wire and Cable Market Segmentation
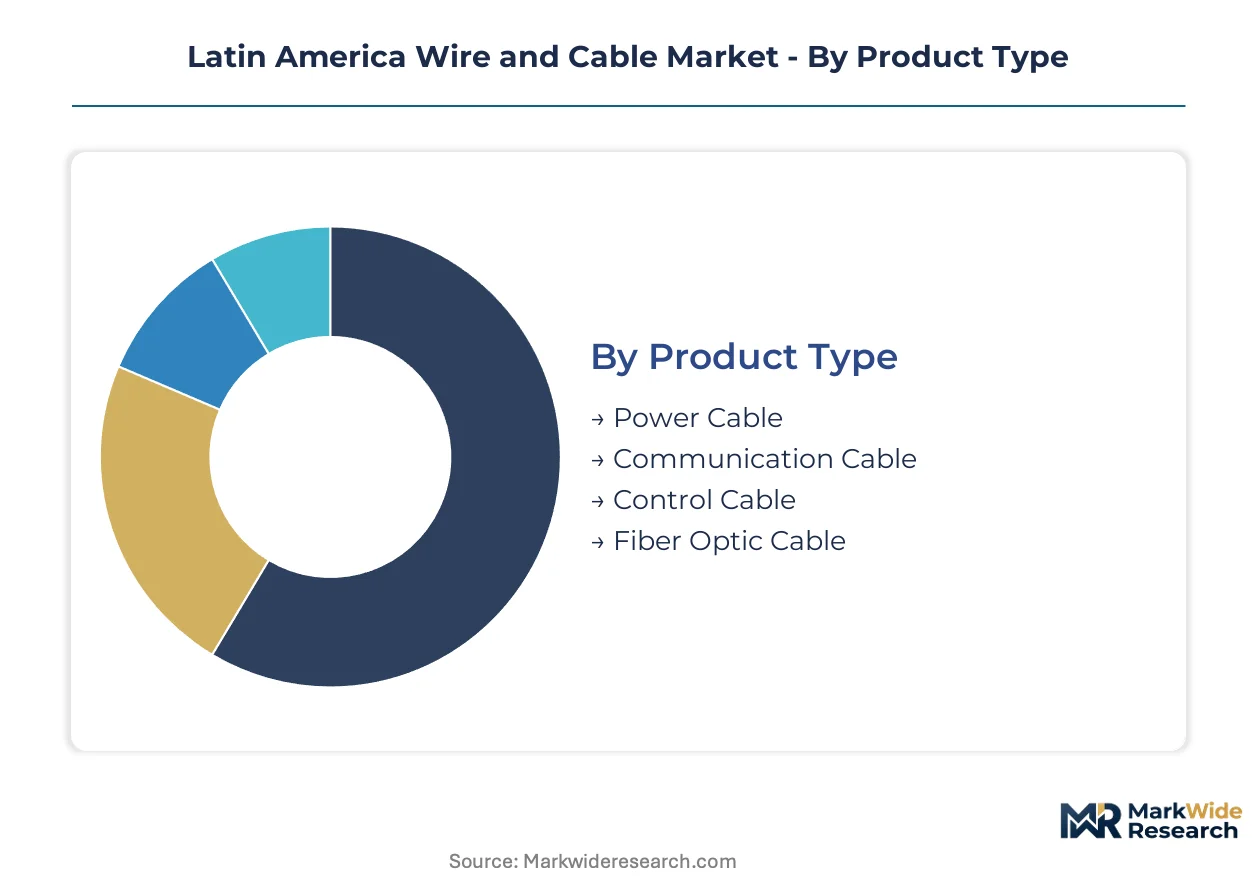
Segmentation reveals where copper conductor specifications retain pricing power against aluminum substitution pressure, and which cable categories face compression from wireless backhaul alternatives. Procurement patterns diverge sharply across voltage classes and metallurgical specifications.
Product Type:
Substitution pressure concentrates in communication cable segments where fiber-to-wireless migration threatens legacy copper data lines, while power cable maintains metallurgical lock-in due to ampacity requirements.
- Power Cable:Insulated conductors rated from low-tension building wire through extra-high-voltage transmission lines, with cross-linked polyethylene and ethylene propylene rubber jacketing systems. Brazilian ANEEL transmission auctions and Chilean SEC grid reliability standards are concentrating medium-voltage procurement around renewable interconnection timelines.
- Communication Cable:Twisted-pair and coaxial constructions for data transmission, facing displacement pressure from 5G millimeter-wave deployments and satellite backhaul alternatives. Mexican NOM-121 certification requirements sustain fiber optic substitution within this category.
- Control Cable:Multi-conductor flexible assemblies for industrial automation and instrumentation circuits.
- Fiber Optic Cable:Glass and plastic optical fiber constructions for telecom backhaul and broadband access networks.
Power cable anchors the volume base while fiber optic cable gains share at the steepest rate.
Material:
Cost tier stratification separates premium conductivity specifications from weight-optimized transmission economics, with regulatory fire-resistance mandates reshaping insulation compound priorities.
- Copper:Electrolytic tough pitch and oxygen-free high-conductivity grades dominating industrial and energy applications where resistivity standards resist substitution. Chilean mining electrification projects and Brazilian utility tenders specify copper for high-ampacity terminations.
- Aluminum:Aluminum alloy and aluminum conductor steel-reinforced constructions specified for long-span transmission to reduce tower loading and right-of-way costs across Andean corridor projects.
- Steel:Galvanized and stainless grades for armoring and messenger wire applications.
- PVC:Polyvinyl chloride insulation and jacketing compounds facing halogen-free substitution pressure in Chilean commercial construction codes.
Copper commands premium positioning in specification-driven procurement while aluminum expands most quickly in transmission volume.
End User:
Customer type concentration varies by project financing structure, with state-owned transmission operators bypassing traditional distribution channels for high-voltage procurement.
- Telecom:Fiber optic and copper data cable procurement driven by Mexican 5G densification and Brazilian rural broadband mandates under ANATEL frameworks.
- Energy:Generation, transmission, and distribution cable specifications spanning utility-scale renewable developers and grid operators. Brazilian offshore wind pre-development is creating subsea cable demand.
- Construction:Low-voltage building wire and fire-resistant power distribution cables.
- Industrial:Mining electrification, petrochemical, and manufacturing process cable requirements.
Energy sector procurement anchors the volume base while telecom infrastructure climbs the fastest.
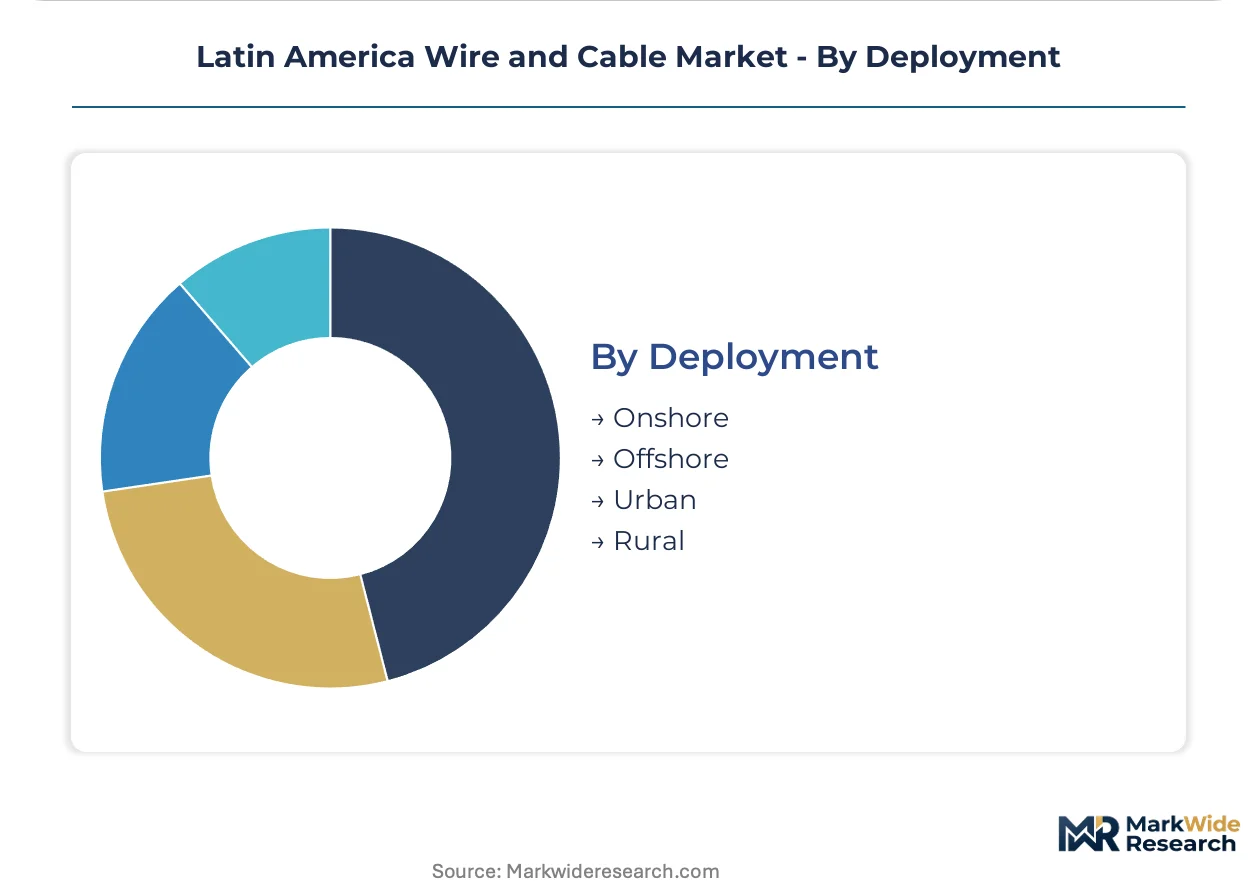
Deployment:
Geography-driven specification differences separate densely regulated urban corridors from cost-optimized rural installations, with offshore emerging as a specialized competency gap.
- Onshore:Terrestrial transmission and distribution installations spanning substation interconnects and overhead line conversions.
- Offshore:Submarine cable systems for offshore wind and island interconnections, where European suppliers currently concentrate technical expertise.
- Urban:Underground duct bank and direct-buried installations facing right-of-way constraints and fire-resistance mandates.
- Rural:Aerial bundled cable and overhead line economics prioritized for electrification access programs.
Onshore deployment anchors the volume base while offshore applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian cable manufacturers export medium-voltage interconnection assemblies to Chilean renewable developers under Pacific Alliance tariff preferences. Mexican producers supply building wire to Central American construction markets through established distribution corridors.
Brazil
Utility-scale solar and offshore wind pre-development is accelerating procurement of submarine and medium-voltage cables. ANATEL certification protocols and ANEEL transmission auction schedules compress supplier qualification timelines. São Paulo state hosts the densest concentration of cable manufacturing and testing laboratories serving the Mercosur trade bloc.
Mexico
5G network densification and rural broadband mandates under REDCOMPARTIDA are expanding fiber optic cable deployments. NOM-001-SEDE electrical safety standards and NOM-121 telecom certification requirements filter import eligibility for communication cables. Mexico City metropolitan area anchors procurement coordination for northern border manufacturing clusters and southern export corridors.
Chile
SEC grid reliability standards and renewable integration mandates are concentrating medium-voltage cable demand around solar and wind interconnection projects. Low-smoke zero-halogen building code updates are reshaping commercial construction specifications. Santiago metropolitan region coordinates procurement for northern mining electrification and southern transmission expansion.
Colombia
State-owned transmission operator ISA is bypassing distribution channels for direct high-voltage project procurement. Distributed temperature sensing cable adoption is climbing for real-time conductor rating optimization in Andean corridor transmission lines. Bogotá anchors technical specification development while Medellín concentrates installation contractor networks.
Argentina
Aging extra-high-voltage cable jointing technician pools are creating specialized installation workforce constraints for transmission upgrades. Import substitution policies favor domestic assembly of aluminum conductor steel-reinforced constructions for long-span lines. Buenos Aires province hosts the primary concentration of cable manufacturing capacity serving domestic and Uruguayan markets.
Latin America Wire and Cable Market Competitive Landscape
Player mix skews toward integrated European multinationals with regional manufacturing footprints and specialized North American producers competing on technical specifications. Market structure concentrates procurement influence among three to four vertically integrated cable groups with established ANATEL and SEC certification histories. Strategic archetypes include utility-scale project anchors, aluminum transmission specialists, and submarine cable technical leaders. Dominant competitive moves center on certification timeline acceleration and direct utility contracting relationships bypassing traditional distribution channels.
Among Italy-based integrated manufacturers, Prysmian Group represents the project-anchor archetype with established Brazilian production capacity. Nexans occupies a position exemplifying submarine cable technical specialization for emerging offshore wind applications. Southwire Company LLC anchors the North American specialist tier with aluminum conductor offerings calibrated to Andean transmission economics. These three entities sit within distinct competitive vectors shaped by metallurgical focus, voltage class expertise, and certification depth across ANATEL, NOM, and SEC frameworks.
| Leading Market Players |
|---|
| Prysmian Group |
| TFKable |
| TE Connectivity |
| Southwire Company LLC |
| Nexans |
| Encore Wire |
| Fujikura Ltd |
| Belden Incorporated |
| American Wire Group |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty-day certification lead times for ANATEL and SEC testing compress supplier margin visibility and concentrate pricing power among incumbent manufacturers with established laboratory relationships. Inventory cycles for copper cathode feedstock now track London Metal Exchange futures rather than traditional quarterly procurement schedules, forcing cable producers to absorb volatility or pass through costs via indexed contracts.
Pricing Analysis
Cross-linked polyethylene insulation generations separate pricing tiers between tree-retardant formulations commanding premium positioning and standard XLPE grades facing commoditization pressure. Project-based long-term offtake contracts dominate utility-scale procurement, with price differentiation driven by certification depth and volume scale. Pricing pressure stems from aluminum conductor substitution in Andean transmission projects where tower loading economics override conductivity premiums. Industrial mining electrification buyers exhibit lowest price sensitivity due to ampacity non-negotiability, while commercial construction segments prioritize capital cost minimization.
Supply Chain Analysis
Chile and Peru anchor copper cathode supply feeding regional conductor manufacturing, while China and South Korea dominate optical fiber preform imports for telecom cable assembly. Raw material dependencies center on electrolytic tough pitch copper, aluminum alloy billet, and cross-linkable polyethylene compound. Supply chain risk concentrates in single-source vulnerability for submarine cable armoring steel and specialized EPR insulation polymers. Distribution runs through direct utility contracting for high-voltage projects and established electrical wholesale networks for building wire.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installation service contracts and thermal monitoring subscriptions are expanding faster than commodity cable hardware, creating recurring revenue pools that offset copper price volatility. Technical support retainers for extra-high-voltage jointing represent the fastest-attaching service layer as aging technician pools concentrate specialized skills.
For Market Incumbents: Fortify ANATEL and SEC certification depth to compress competitor qualification timelines. Expand captive copper rod production in São Paulo state to hedge London Metal Exchange volatility. Anchor direct contracting relationships with ISA and ANEEL auction winners to lock out distribution-dependent challengers. For New Entrants and Emerging Players: Lead with halogen-free insulation formulations for Chilean commercial construction code compliance. Target Colombian distributed temperature sensing cable specifications where European suppliers lack local installation partnerships. Pursue joint-venture assembly with Brazilian laboratories to bypass certification timeline barriers. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-utility compounding play because grid modernization mandates and renewable interconnection timelines sustain demand visibility. Acquisition targets should concentrate on mid-cap specialists with ANATEL certification histories and submarine cable jointing capabilities. Monitor Brazilian offshore wind lease auction schedules as inflection signal for subsea cable demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Timeline Acceleration | ANATEL and SEC parallel testing investments compress competitor market access windows. |
| Backward Integration into Copper Rod | São Paulo state captive smelting hedges London Metal Exchange price volatility exposure. |
| Direct Utility Contracting | ISA and ANEEL auction relationships bypass traditional distribution margin layers. |
| Submarine Cable Capability Buildout | Brazilian offshore wind pre-development creates technical competency gaps for European suppliers. |
| Halogen-Free Product Line Expansion | Chilean building code updates open specification windows for low-smoke zero-halogen grades. |
Research Methodology
Initial hypotheses were tested against primary input from utility procurement directors, cable manufacturing plant managers, ANATEL certification laboratory technicians, and transmission EPC contractors and refined through secondary validation. Sources included ANEEL auction documentation, SEC electrical safety filings, Chilean customs trade data, and copper industry association production statistics. Bottom-up volume estimates from project-level procurement tracking were triangulated against top-down market sizing from national grid investment disclosures.
Variance decomposition across voltage class, metallurgical specification, end-use sector, and deployment geography structured the analytical framework. CAGRs were derived from regression analysis of historical procurement volumes against renewable interconnection mandates and 5G backhaul deployment schedules. Industry-specific forecast inputs incorporated ANEEL transmission auction calendars and Mexican REDCOMPARTIDA rural broadband milestone commitments.
The analysis sits within stated boundaries; outcomes outside sustained copper price stability and certification protocol continuity would require recalibration. Forecasts reflect assumptions regarding Pacific Alliance tariff preference durability and ANATEL electromagnetic compatibility testing capacity expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Solar Cable Market
Cables
Cable Testing and Certification Market
Cables
Cable Flange Market
Cables
Flat Flexible Cables Market
Cables
Magnetic Charging Cable Market
Cables
HVDC Cables Market
Cables
EV Charging Cable and Connector Durability and Safety Test Equipment Market
Cables
Cable Organisers Market
Cables
Direct Attach Cable Market
Cables
Aluminum Cable Market
Cables
Underground Power Cable Partial Discharge and Fault Location Test Equipment Market
Cables
XLPE Cables Market
Cables
Fiber Optical Cable and Cable Assembly Products Market
Cables
Global Low Voltage Cable Market
Cables
Global Cable Gland Market
Cables
Data Center Wire and Cable Market