
 High-Voltage Interlock Loop Wiring Components Market | 2026-2036
High-Voltage Interlock Loop Wiring Components Market Size, Share, and Industry Trends Forecast 2026-2036
High-Voltage Interlock Loop Wiring Components Market Insights
Software-defined interlock monitoring is broadening what suppliers actually deliver beyond physical harnesses. TE Connectivity leverages its sensor fusion architecture to bundle predictive diagnostics with connector hardware. Yazaki Corporation anchors its position through backward integration into specialized cable extrusion for 800V architectures. Amphenol Corporation differentiates via hermetic sealing IP that sustains qualification across aerospace and automotive programs simultaneously.
High-voltage interlock loop wiring components constitute shielded conductor assemblies with continuity-sensing circuits that break electrical paths when connectors disengage or insulation breaches occur, typically rated for 60V to 1500V DC isolation per ISO 6469-3. These systems prevent arc formation and electrocution risk during battery pack service or collision events by forcing controlled shutdown sequences before human contact with energized conductors. Connectors command the dominant share of component value due to precision contact geometries and sealing complexity, while fiber optic interlock channels represent the fastest-expanding technology segment as optical isolation eliminates electromagnetic interference in multi-kilowatt inverter environments. OEM procurement of complete interlock subsystems has shifted margin pools toward Tier-1 suppliers capable of integrating sensors, relays, and harness routing in single-source contracts.
FDA oversight of automotive-grade components remains indirect, yet NHTSA Federal Motor Vehicle Safety Standard 305 governs electrolyte spillage and electrical isolation thresholds that dictate interloop architecture in US-built electric vehicles. ECHA REACH restrictions on halogenated flame retardants are forcing reformulation of cable jacket compounds across European supply chains, while China's GB/T standards for electric vehicle safety mandate specific interlock response times that shape product validation protocols. Stakeholders must weigh certification investment against platform-specific requirements as regional technical divergence outpaces harmonization efforts.
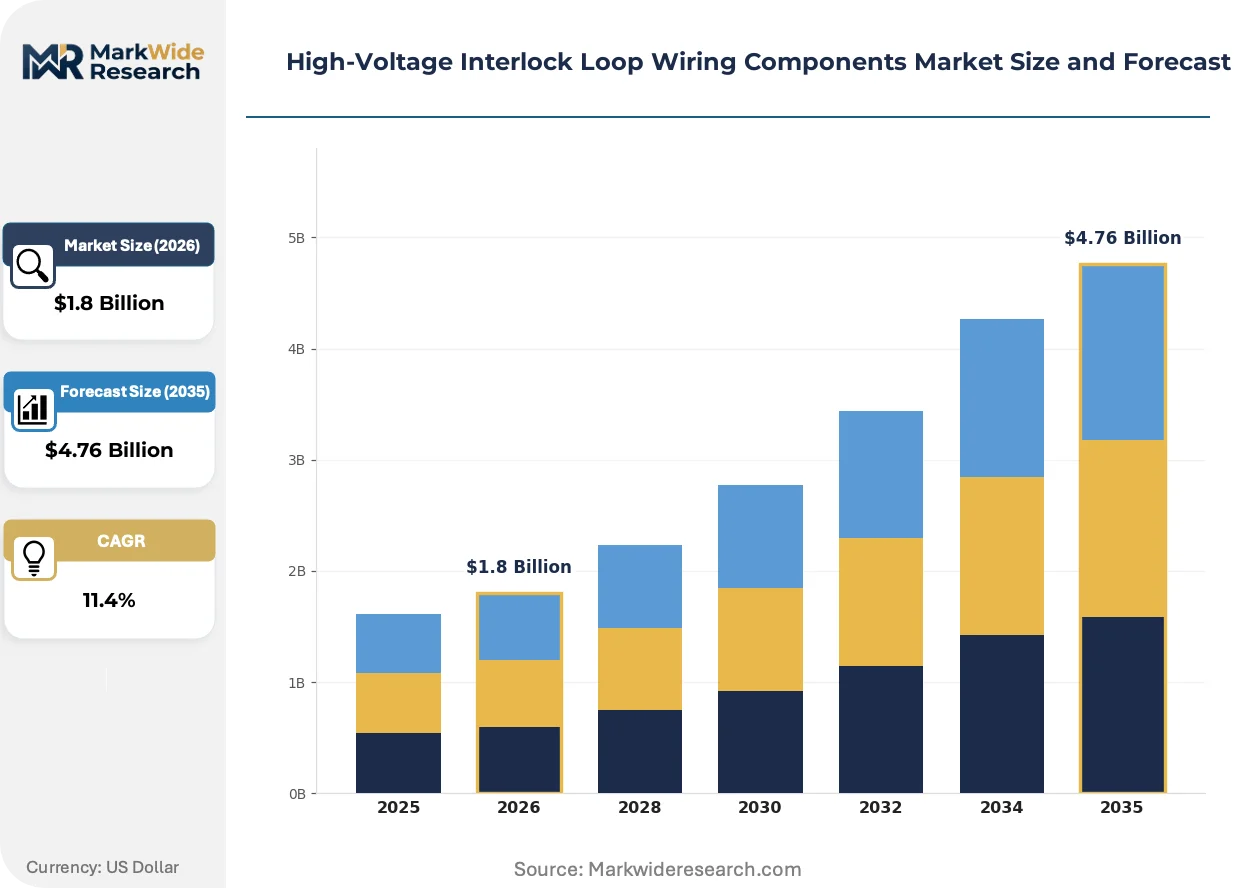
Market Dynamics
Platform voltage escalation from 400V to 800V architectures is compressing component qualification cycles and forcing simultaneous redesigns of shielding, sealing, and sensing subsystems across the supply base.
Growth Catalysts
- ISO 6469-3 electrical safety mandates:Battery-electric commercial vehicle OEMs in Germany now require interlock systems that force controlled shutdown sequences before human contact with energized conductors.
- Optical isolation technology:Fiber optic interlock channels eliminate electromagnetic interference in multi-kilowatt inverter environments, opening new design envelopes for shielded cabling.
- Chinese OEM platform expansion:GB/T standards for electric vehicle safety mandate specific interlock response times that validate next-generation product architectures.
Market Restraints
- Specialized polymer supply concentration:ECHA REACH restrictions on halogenated flame retardants force reformulation of cable jacket compounds across European supply chains with limited qualified compounders.
- Hermetic sealing IP concentration:Precision contact geometries and sealing complexity for connectors remain captive to aerospace-qualified suppliers with decade-long qualification timelines.
- Regional technical divergence:Platform-specific certification requirements in the United States, China, and Germany outpace harmonization efforts, fragmenting validation investment.
Strategic Opportunities
- Sensor fusion bundling:TE Connectivity's architecture demonstrates margin capture through predictive diagnostics packaged with connector hardware rather than discrete component sales.
- Backward integration into cable extrusion:Captive supply of specialized conductors for 800V architectures insulates against polymer formulation bottlenecks.
- Single-source subsystem contracts:OEM procurement of complete interlock systems including sensors, relays, and harness routing shifts margin pools toward integrated Tier-1 suppliers.
Industry Challenges
- Cross-industry qualification timelines:Suppliers sustaining simultaneous aerospace and automotive program qualifications face compressed development windows as platform voltages escalate.
- Continuity monitoring integration:Software-defined interlock monitoring requires firmware competency absent from traditional harness manufacturers, forcing capability acquisition or partnership.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Voltage Interlock Loop Wiring Components Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Connectors, Sensors, Relays, Fuses, Insulators Technology: Shielded Cabling, Fiber Optics, Coaxial Cabling, Optical Sensors, Piezoelectric Sensors Application: Electric Vehicles, Industrial Automation, Aerospace Systems, Renewable Energy, Consumer Electronics End User: OEMs, Tier-1 Suppliers, Aftermarket Service Providers, System Integrators, Vehicle Assemblers |
| Companies Covered | TE Connectivity, Amphenol Corporation, Yazaki Corporation, Sumitomo Electric Industries, Aptiv, Molex, Leoni, Hirose Electric, Rosenberger Hochfrequenztechnik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Voltage Interlock Loop Wiring Components Market Trends and Innovations
Shielded cabling with integrated continuity monitoring is actively displacing basic twisted-pair designs, while fiber optic channels and predictive diagnostics software are redrawing what suppliers actually deliver beyond physical harnesses.
Integrated fiber optic interlock channels are electrifying the electromagnetic compatibility landscape for high-power inverter environments. Commercial vehicle manufacturers adopting 800V battery architectures now specify optical isolation for control circuits in multi-kilowatt systems. This convergence of optical communication with safety-critical wiring is electrifying traditional copper-dominated interlock designs and compressing the addressable market for conventional shielded twisted-pair assemblies.
NHTSA Federal Motor Vehicle Safety Standard 305 governs electrolyte spillage and electrical isolation thresholds that dictate interlock architecture in US-built electric vehicles. The regulation's specific voltage isolation requirements force redesigns of connector sealing and conductor spacing in battery pack service applications. Domestic OEMs respond by qualifying interlock subsystems that exceed baseline thresholds, anticipating future amendments as platform voltages climb toward 1500V DC.
Complete interlock subsystem procurement now dominates OEM sourcing patterns for new platform launches. Discrete component purchasing of connectors, harnesses, and sensors separately is yielding to single-source contracts with Tier-1 suppliers capable of integrating routing, sensing, and relay logic. This bundling behavior is most visible in German and Chinese commercial vehicle programs, where platform complexity and safety liability concentrate sourcing authority with subsystem integrators rather than commodity harness vendors.
High-Voltage Interlock Loop Wiring Components Market Segmentation
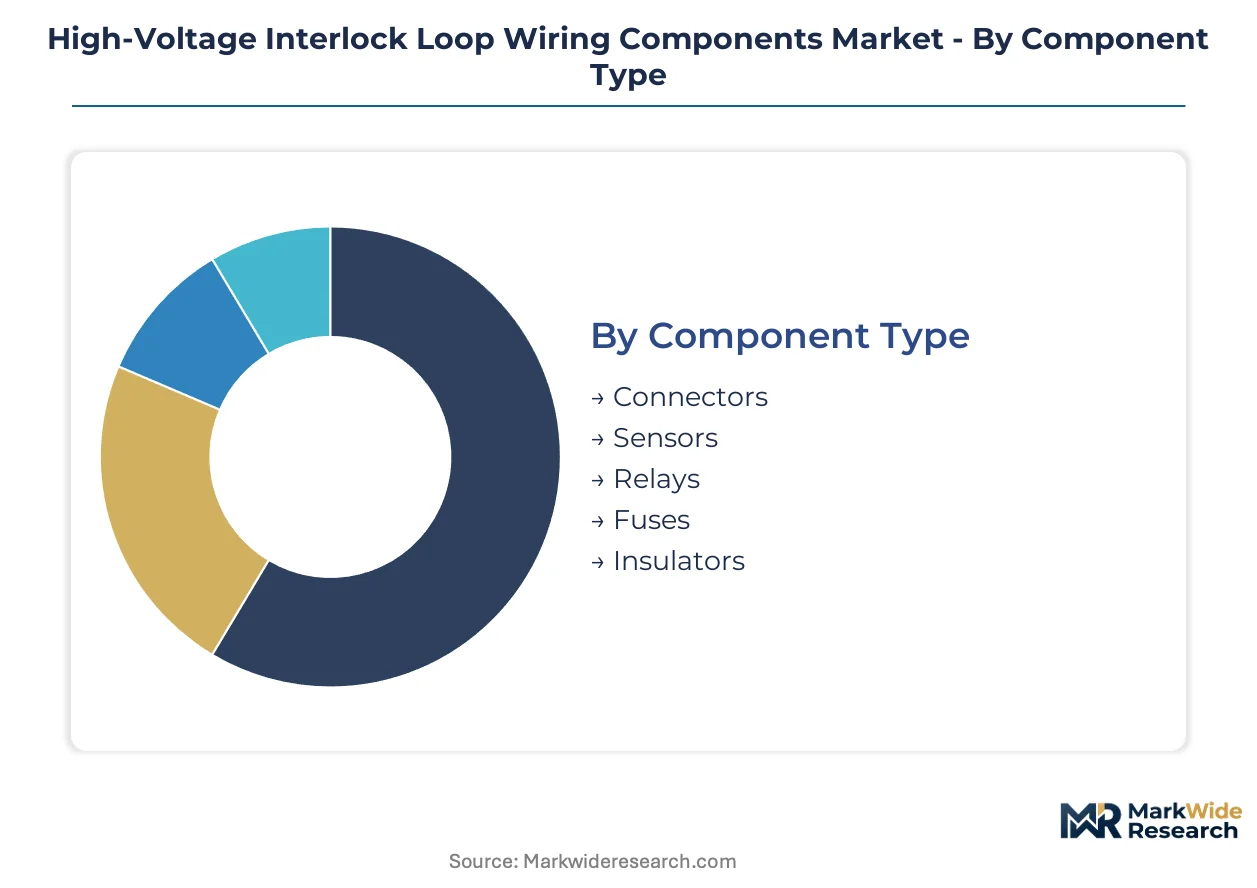
High-voltage interlock loop wiring components segment across multiple dimensions that determine certification burdens, supply chain positioning, and margin capture. Component type and technology selection dictate ISO 6469-3 compliance pathways, while application and end-user categories shape procurement authority and contract structures.
Component Type:
Connectors and sensors carry the heaviest certification loads under ISO 6469-3 and NHTSA FMVSS 305, requiring hermetic validation and continuity testing protocols that extend qualification timelines.
- Connectors:Precision contact geometries with integrated sealing systems dominate component value pools. German and Chinese battery-electric commercial vehicle OEMs now mandate connector subsystems that force controlled shutdown sequences before human contact with energized conductors, compressing supplier qualification windows as platform voltages escalate from 400V to 800V architectures.
- Sensors:Continuity-sensing circuits with predictive diagnostic capabilities are displacing passive detection mechanisms. TE Connectivity bundles sensor fusion architectures with hardware to capture margins through software-defined monitoring rather than discrete component sales.
- Relays:Electromechanical switching elements rated for 60V to 1500V DC isolation paths.
- Fuses:Overcurrent protection devices integrated into interlock circuit architectures.
- Insulators:Dielectric barriers maintaining conductor spacing under thermal and mechanical stress.
Leading the category by volume: Connectors. Growing fastest: Sensors with predictive diagnostic integration.
Technology:
Cost tiers separate legacy copper-dominated assemblies from next-generation optical and piezoelectric platforms commanding premium positioning in 800V and multi-kilowatt inverter environments.
- Shielded Cabling:Twisted-pair designs with integrated continuity monitoring now displace basic unshielded architectures. Yazaki Corporation anchors market position through captive cable extrusion capabilities for high-voltage platforms, insulating against polymer formulation bottlenecks triggered by ECHA REACH restrictions on halogenated flame retardants.
- Fiber Optics:Optical isolation channels eliminate electromagnetic interference in inverter environments. Chinese OEMs adopting 800V battery architectures specify fiber optic interlock for control circuits, compressing addressable demand for conventional copper assemblies while opening new design envelopes for electromagnetic compatibility.
- Coaxial Cabling:Concentric conductor arrangements with shielded outer braids for noise-sensitive signal paths.
- Optical Sensors:Photonic detection elements converting physical disengagement events into digital signals.
- Piezoelectric Sensors:Crystalline elements generating voltage signals from mechanical strain in connector interfaces.
Shielded cabling holds the largest installed base. Fiber optics is climbing the fastest as 800V architectures proliferate.
Application:
End-use concentration determines validation investment recovery timelines, with electric vehicles and aerospace systems demanding the most extensive cross-industry qualification portfolios.
- Electric Vehicles:Battery pack service and collision protection systems dominate procurement volume. NHTSA FMVSS 305 governs electrical isolation thresholds that force connector sealing and conductor spacing redesigns, with domestic OEMs qualifying subsystems exceeding baseline requirements in anticipation of amendments as platform voltages approach 1500V DC.
- Industrial Automation:Factory-floor high-voltage equipment protection with standardized response protocols.
- Aerospace Systems:Hermetic sealing requirements sustained across automotive and aerospace programs simultaneously. Amphenol Corporation leverages IP that maintains qualification across both sectors, though suppliers face compressed development windows as platform voltages escalate and dual-program timelines collide.
- Renewable Energy:Solar inverter and energy storage system integration with grid-tied safety requirements.
- Consumer Electronics:Low-voltage adaptation of interlock principles for premium device charging systems.
Electric vehicles command the dominant demand share. Aerospace systems carry the steepest certification premiums.
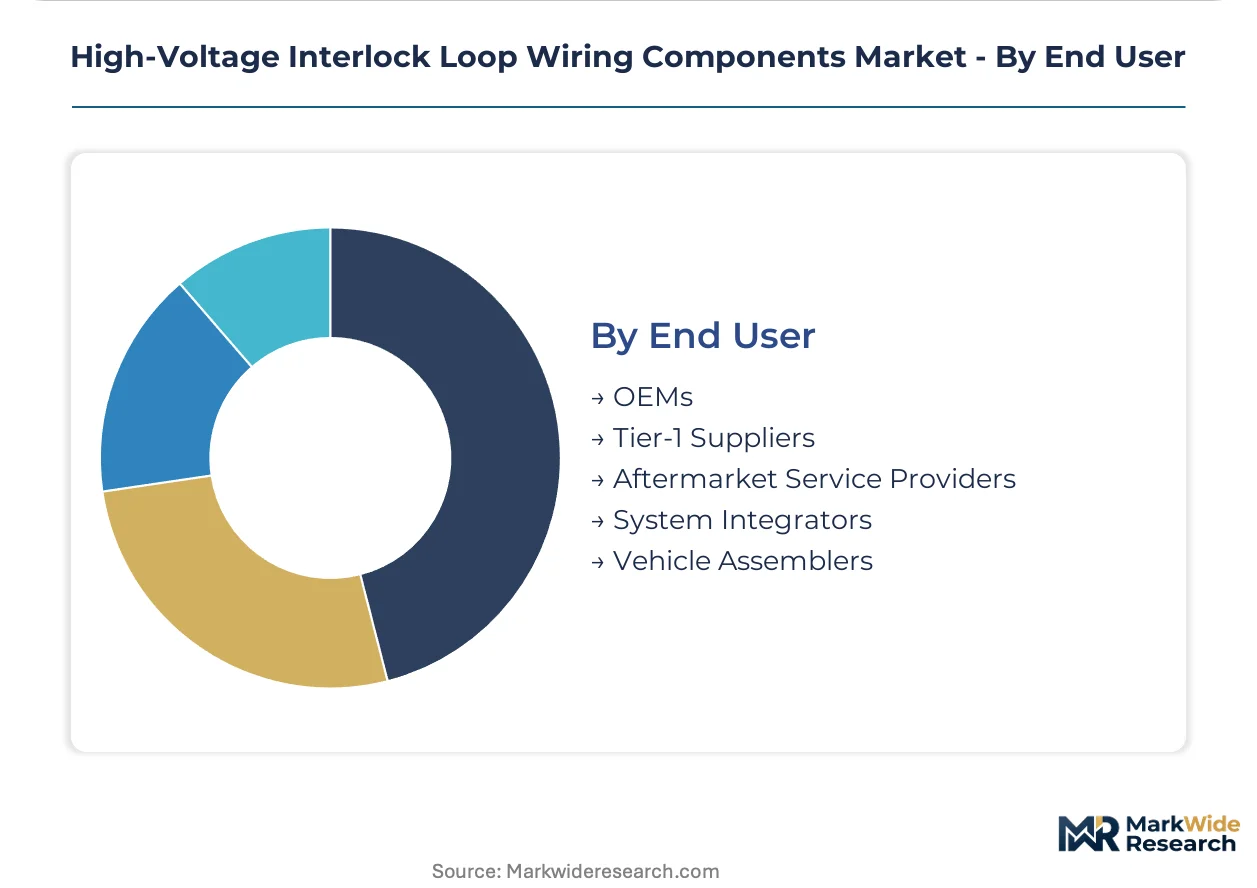
End User:
Customer type determines contract structure complexity, with integrated subsystem procurement concentrating margin pools toward single-source Tier-1 relationships.
- OEMs:Complete interlock subsystem sourcing now dominates new platform launches. German and Chinese commercial vehicle programs concentrate procurement authority with subsystem integrators capable of bundling routing, sensing, and relay logic, displacing discrete component purchasing of connectors, harnesses, and sensors separately.
- Tier-1 Suppliers:Intermediate integrators capturing margin pools through sensor fusion bundling and backward integration into specialized cable extrusion.
- Aftermarket Service Providers:Replacement and retrofit channels for vehicle maintenance and repair.
- System Integrators:Industrial and renewable energy project-specific assembly providers.
- Vehicle Assemblers:Final assembly operations with limited in-house interlock design authority.
OEMs direct the largest contract values. Tier-1 suppliers are gaining share fastest through single-source subsystem positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors the densest concentration of high-voltage interlock engineering activity, with OEM validation centers and Tier-1 subsystem integrators clustered across the Baden-Württemberg automotive corridor.
United States
Domestic battery-electric commercial vehicle programs in Michigan and California are compressing supplier qualification windows. NHTSA Federal Motor Vehicle Safety Standard 305 governs electrical isolation thresholds that force connector sealing redesigns. Detroit-based OEMs qualify interlock subsystems exceeding baseline requirements in anticipation of amendments as platform voltages approach 1500V DC.
Germany
Commercial vehicle manufacturers in Bavaria and Lower Saxony now mandate interlock systems forcing controlled shutdown sequences before human contact. ECHA REACH restrictions on halogenated flame retardants are reformulating cable jacket compounds. The Stuttgart automotive corridor concentrates subsystem integrators capable of bundling routing, sensing, and relay logic.
China
GB/T standards for electric vehicle safety mandate specific interlock response times that validate next-generation architectures. Yangtze River Delta OEMs adopting 800V battery architectures specify fiber optic interlock for control circuits. Shanghai-based battery pack service operations are driving shielded cabling procurement with integrated continuity monitoring.
Japan
Precision connector manufacturers in Aichi Prefecture face compressed development windows as platform voltages escalate. METI industrial standards shape electromagnetic compatibility requirements for multi-kilowatt inverter environments. Nagoya-area suppliers sustain simultaneous aerospace and automotive program qualifications with hermetic sealing IP.
South Korea
Seoul Capital Area battery-electric vehicle platforms are displacing basic twisted-pair designs with shielded cabling architectures. Domestic OEMs source complete interlock subsystems through single-source Tier-1 contracts. Busan-Ulsan industrial zones concentrate specialized cable extrusion capabilities for high-voltage platforms.
High-Voltage Interlock Loop Wiring Components Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the high-voltage interlock landscape. The supplier base concentrates around three strategic archetypes: integrated subsystem integrators bundling sensors and harness routing, specialized connector houses with hermetic sealing IP, and captive cable extrusion operators controlling polymer formulation. Dominant competitive moves include backward integration into specialized conductor production and sensor fusion bundling that captures margins through predictive diagnostics software rather than discrete hardware sales.
Within the integrated subsystem tier, TE Connectivity and Aptiv exemplify the architecture-forward positioning that shifts procurement authority toward single-source relationships. Yazaki Corporation anchors the captive cable extrusion archetype, insulating against polymer supply bottlenecks through in-house production capabilities. Amphenol Corporation occupies a position spanning aerospace and automotive qualification portfolios simultaneously, representing the cross-industry IP leverage archetype.
| Leading Market Players |
|---|
| TE Connectivity |
| Amphenol Corporation |
| Yazaki Corporation |
| Sumitomo Electric Industries |
| Aptiv |
| Molex |
| Leoni |
| Hirose Electric |
| Rosenberger Hochfrequenztechnik |
| Others |
Pricing and Supply Chain Analysis
Copper LME pricing volatility cascades through high-voltage interlock component manufacturing, compressing margins for harness assemblers while amplifying pricing power for integrated subsystem suppliers with captive conductor production.
Pricing Analysis
Cost-down pressure on standard-grade shielded cabling accelerates because ECHA REACH reformulation mandates are forcing compound substitution at qualified European extruders. Three-tier pricing structure across aerospace-qualified, automotive-certified, and industrial-grade levels separates hermetic sealing IP holders from commodity harness vendors. OEM procurement teams in Germany and China exhibit highest price sensitivity on discrete connectors, while integrated subsystem contracts command premium positioning through predictive diagnostics bundling.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale battery-electric commercial vehicle demand, with Tier-1 subsystem integrators consolidating routing, sensing, and relay logic under single-source agreements. Manufacturing concentrates in Germany, China, and Japan, where specialized polymer compounders and precision connector houses anchor regional supply clusters. The supply chain draws from halogen-free flame retardant formulations, high-purity copper conductors, and hermetic sealing polymers, with single-source vulnerability around aerospace-qualified sealing IP presenting structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with subsystem bundling and captive cable extrusion representing the decisive upstream levers separating margin leaders from commodity assemblers.
For Market Incumbents: Anticipate fiber optic interlock displacement of copper-dominated architectures by securing optical component sourcing partnerships or in-house photonics capability ahead of 800V platform proliferation. Defend positioning through accelerated qualification timelines for hermetic sealing IP that sustains simultaneous aerospace and automotive program access, as compressed development windows favor suppliers with existing dual-industry portfolios. For New Entrants and Emerging Players: GB/T standards in China open a window for fiber optic interlock channel specialists to penetrate Yangtze River Delta OEM supply chains before incumbent subsystem integrators complete optical capability integration. Target aftermarket service providers for battery pack maintenance operations with replacement harness architectures featuring plug-compatible continuity monitoring, leveraging lower certification burdens than new platform qualification pathways. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized cable extrusion operators in South Korea and Japan with existing 800V conductor formulations and polymer compounding relationships. Monitor NHTSA FMVSS 305 amendment proposals as the inflection signal for accelerated US platform voltage escalation toward 1500V DC isolation thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cable Extrusion | Captive conductor production insulates against ECHA REACH polymer bottlenecks and copper price volatility. |
| Sensor Fusion Architecture Development | Software-defined interlock monitoring captures margin pools through predictive diagnostics bundling with hardware. |
| Hermetic Sealing IP Expansion | Cross-industry aerospace-automotive qualification sustains premium positioning across dual program portfolios. |
| Fiber Optic Interlock Channel Qualification | Optical isolation capability opens 800V architecture procurement opportunities with Chinese and German OEMs. |
| Single-Source Subsystem Contracting | Integrated routing-sensing-relay bundling concentrates procurement authority with Tier-1 integrators. |
Research Methodology
Multi-period observation of platform voltage escalation timelines, OEM subsystem sourcing patterns, and polymer formulation regulatory shifts anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, specialized cable extrusion operators, and aftermarket service channel managers. Secondary validation drew from NHTSA FMVSS 305 regulatory filings, ECHA REACH substance restriction updates, GB/T standard revision notices, and vehicle production registration databases. Bottom-up component demand modeling and top-down OEM platform content analysis were triangulated against supplier revenue disclosures.
Segment-weighting across component type, technology platform, application end-use, and customer category informed the analytical framework throughout the projection horizon. CAGRs were derived from installed base turnover rates, platform voltage transition timelines, and regional regulatory compliance phase-in schedules. Forecast inputs included battery-electric commercial vehicle production volumes, 800V architecture adoption curves, and fiber optic interlock penetration assumptions in multi-kilowatt inverter environments.
Caveats apply where NHTSA regulatory amendments, ECHA polymer restriction expansions, or Chinese GB/T response time revisions could materially shift the outlook for component qualification timelines and subsystem bundling economics. Periodic stress-testing of base assumptions against OEM platform launch delays and raw material supply disruptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
United States MLCC Market
Electronic Components
Capacitor Kits Market
Electronic Components
SAW Filters Market
Electronic Components
North America Safety Relay and Timers Market
Electronic Components
Gigabit Interface Converter Market
Electronic Components
Lead Zirconate Titanate (PZT) Market
Electronic Components
Global Multilayer Varistors Market
Electronic Components
Amplifier Market
Electronic Components
Electric Vehicle (EV) Electronic Components Market
Electronic Components
Audio and Visual Public Address System Market
Electronic Components
Astable Multivibrator Market
Electronic Components
North America USB Retimer Market
Electronic Components
Audio Amplifier Market
Electronic Components
Electric Capacitor Market
Electronic Components
Metal Composite Power Inductor Market
Electronic Components
Electromechanical Timers Market