
 Europe Cable Joints Market | 2026-2036
Europe Cable Joints Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cable Joints Market Insights
Maintenance subscription bundles for thermal monitoring and predictive diagnostics is repositioning how cable joint vendors capture lifetime value from utility customers. Prysmian Group leverages its integrated cable-to-accessory platform to anchor long-term service contracts across Mediterranean utilities. Nexans S.A. sustains competitive positioning through specialized high-voltage joint engineering for subsea interconnectors. TE Connectivity Ltd. dominates the cold-shrink retrofit segment where grid operators prioritize minimized outage windows.
Cable joints are engineered electrical connectors that restore insulation, shielding continuity, and mechanical protection at cable section interfaces, typically rated from 1 kV through 500 kV depending on polymer or rubber compound formulation and resin-curing methodology. Their primary commercial purpose is to ensure reliable power transmission across segmented cable runs while containing electrical stress within defined geometric field-control structures. Heat shrink and cold shrink product types command the majority of installed volume in distribution networks, though pre-molded designs carry superior margin pools in EHV applications where factory-controlled geometry reduces field failure risk. Polymer and rubber material formulations face rising specification pressure as REACH compliance tightens phthalate and halogen content thresholds across European supply chains.
CE marking under the EU Construction Products Regulation and harmonized EN 50393 testing standards govern market access for medium-voltage joints sold throughout EU member states, while national regulators such as Germany's KBA and France's ANSM enforce sector-specific procurement qualifications in rail and nuclear-adjacent installations. The F-Gas Regulation progressively restricts greenhouse gas-intensive installation practices, redirecting R&D investment toward vacuum-interruption and mechanical-expansion sealing technologies. Stakeholders must monitor how the EU AI Act's predictive-maintenance software classifications reshape warranty and liability structures for smart-joint offerings.
Market Dynamics
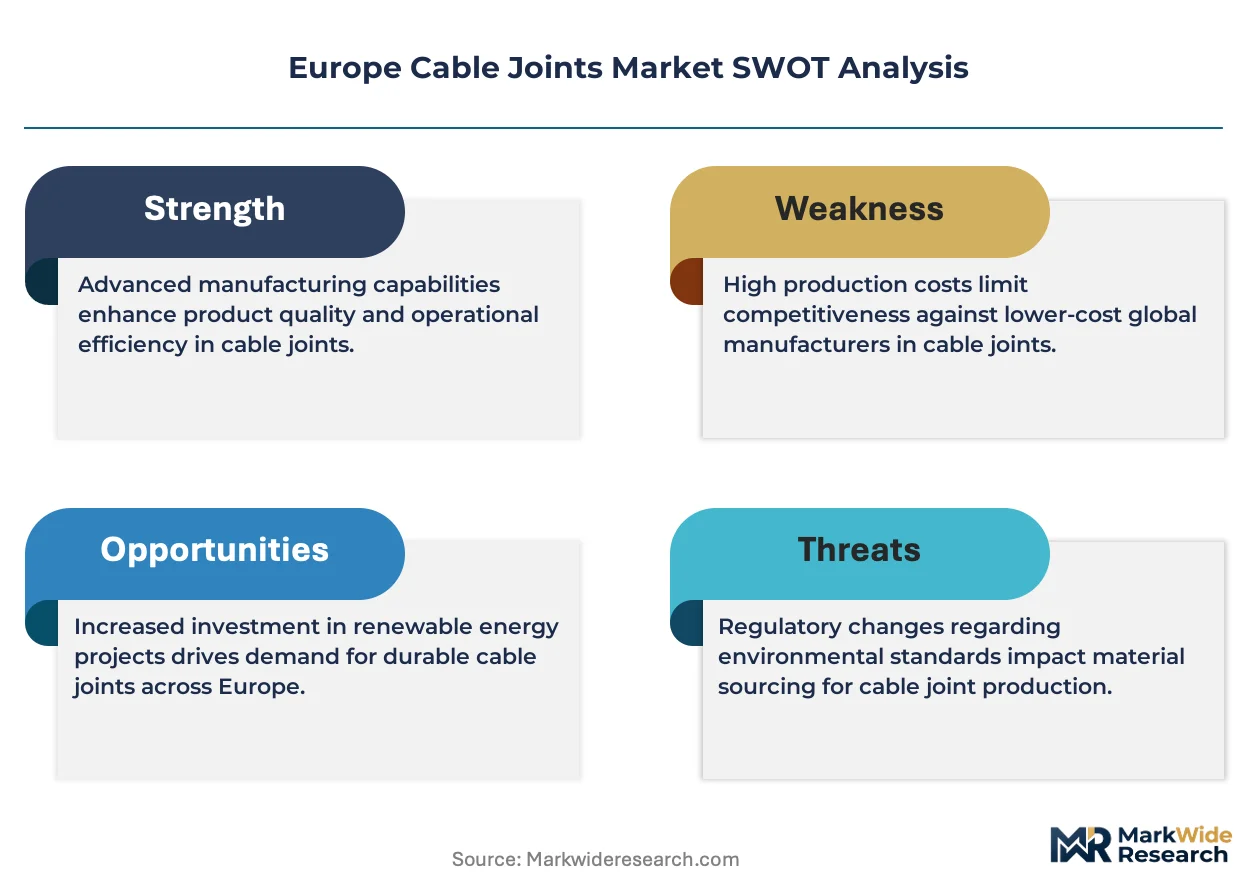
The EU F-Gas Regulation is compressing installation-method timelines across Europe, forcing joint manufacturers to abandon greenhouse gas-dependent sealing technologies before phase-down deadlines mature.
Growth Catalysts
- Offshore wind procurement:North Sea developers are accelerating procurement of 220 kV+ subsea joints as interconnector projects multiply across German, Dutch, and Danish territorial waters.
- Grid modernization mandates:National recovery funds in France, Italy, and Spain are channeling capital toward distribution network refurbishment, directly lifting medium-voltage joint volumes.
- REACH compliance premiums:Phthalate-free compound formulations are capturing specification preference among Scandinavian utilities with aggressive sustainability procurement criteria.
Market Restraints
- Silicone rubber price volatility:Feedstock cost swings for liquid silicone rubber are compressing margin pools for cold-shrink joint specialists dependent on polymer-intensive designs.
- EHV pre-molded supply concentration:Factory-controlled geometry for 400 kV+ applications relies on a concentrated German and Italian supplier base, creating single-source vulnerability.
- SF6 substitution friction:The F-Gas Regulation's installation restrictions leave limited technically validated alternatives for high-voltage gas-insulated joint sealing, delaying project commissioning.
Strategic Opportunities
- Polish distribution expansion:Underpenetrated rural electrification programs and EU cohesion fund access position Poland for accelerated medium-voltage joint deployment through 2030.
- Predictive maintenance convergence:Fiber-optic thermal sensing embedded within joint housings is converging with cloud analytics platforms, opening recurring revenue streams for hardware vendors.
- EU Green Deal certification premiums:Products validated under harmonized carbon-footprint protocols are capturing tender preference among French and Benelux transmission operators.
Industry Challenges
- Field technician certification gaps:EN 50393-qualified installers for 110 kV+ resin-cured joints remain scarce across Iberian and Eastern European markets, constraining deployment velocity.
- Legacy GIS integration complexity:Retrofitting cold-shrink solutions into existing gas-insulated substation architectures demands custom engineering that extends project timelines and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cable Joints Market |
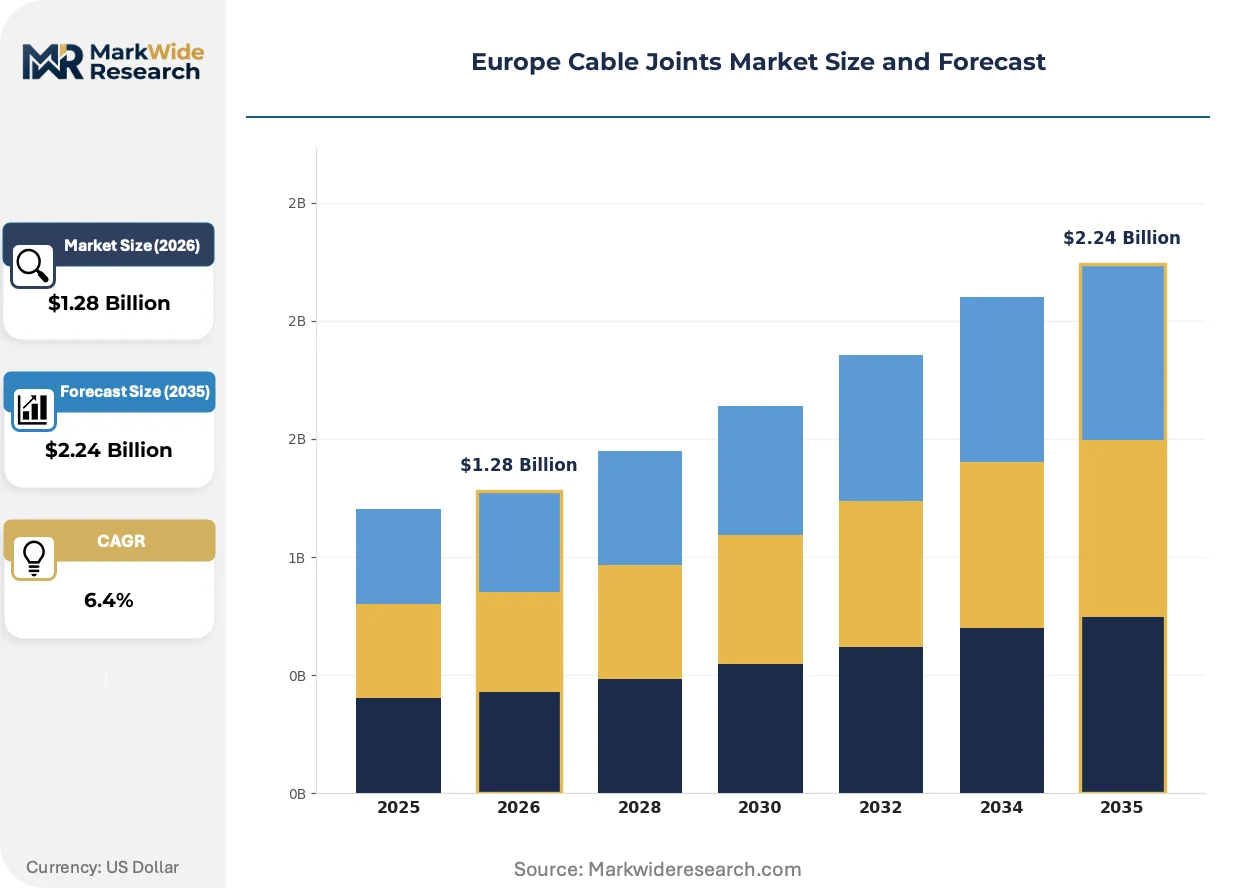
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Shrink, Cold Shrink, Pre-molded, Resin Material: Polymer, Rubber, Metal, Composite Application: Power Transmission, Distribution, Renewable Energy, Communication End User: Utilities, Telecom, Construction, Manufacturing |
| Companies Covered | ABB Ltd, 3M International, Prysmian Group, Cable Jointer Solutions, Fujikura, Nexans S.A., TE Connectivity Ltd., Connect Cable Accessories Co., Ltd., NKT A/S, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cable Joints Market Trends and Innovations
Sealing technology and embedded sensing are reshaping how cable joints are specified, installed, and monetized across European transmission and distribution networks.
Mechanical-expansion sealing technology is modularizing field installation workflows for medium-voltage distribution joints. German and Austrian utilities are adopting these systems at accelerating pace to eliminate heat-gun dependency and reduce outage windows. The shift is compressing contractor training cycles while expanding addressable market for retrofit-focused product lines.
REACH enforcement through ECHA is tightening phthalate and halogen content thresholds across polymer supply chains. Compound formulators are reformulating EPDM and silicone bases to maintain dielectric performance under stricter substance restrictions. Medium-voltage heat-shrink segments in France and Italy face the steepest compliance recertification burdens.
Utility procurement departments are unbundling hardware purchase from installation and long-term thermal monitoring services. TSOs in the United Kingdom and Netherlands are separating these elements across distinct contract vehicles, displacing traditional bundled EPC arrangements. This behavioral shift is most visible in offshore wind interconnector projects where joint vendors now compete for service-only scopes.
Europe Cable Joints Market Segmentation
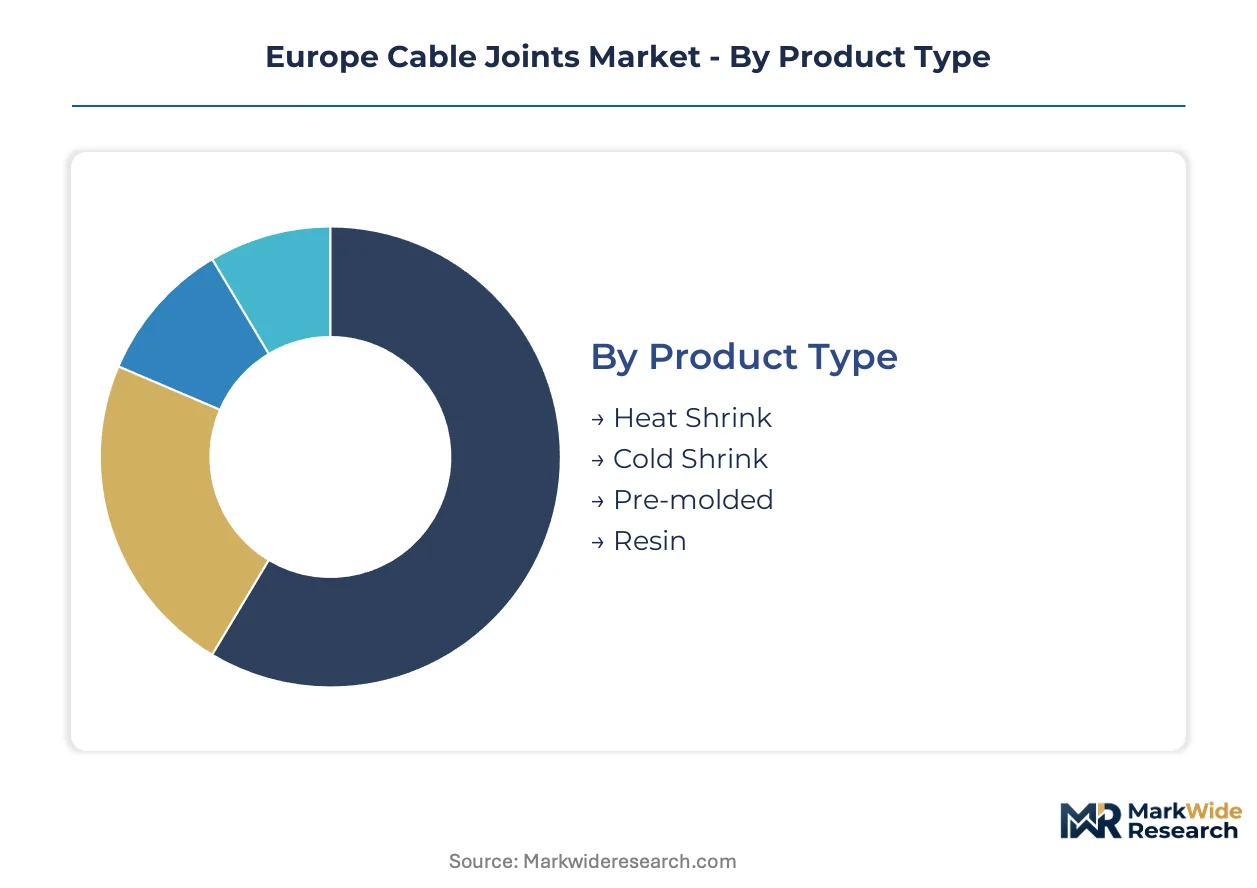
Cable joint procurement patterns diverge sharply across installation voltage tiers and end-use reliability requirements. Understanding these segment boundaries clarifies where specification premiums concentrate and which product lines face commoditization pressure from regulatory compliance costs.
Product Type:
Upgrade cycles for aging distribution infrastructure are lengthening for legacy heat-shrink installations while accelerating for cold-shrink alternatives that minimize outage windows during retrofit.
- Heat Shrink:Polyolefin-based sleeves with cross-linked polymer formulation require propane or electric heat-gun application to achieve radial shrink and environmental sealing. German and French distribution utilities continue specifying these for 1-36 kV underground cable refurbishment where installed base familiarity reduces contractor training costs.
- Cold Shrink:Factory-expanded silicone rubber tubes mounted on removable cores eliminate heat-source dependency and cut installation time by 60% versus heat-shrink equivalents. United Kingdom DNOs prioritize these for live-line working protocols in urban distribution networks where outage minimization drives procurement scoring.
- Pre-molded:Factory-cured EPDM or silicone geometries with integrated stress-cone structures for 72.5-500 kV applications.
- Resin:Cast polyurethane or epoxy compounds for direct-buried joints requiring flood resistance.
Volume placements concentrate in Heat Shrink; the faster expansion belongs to Cold Shrink.
Material:
REACH substance restrictions are fragmenting compound supply chains and forcing reformulation investments that favor integrated polymer producers over specialty distributors.
- Polymer:Cross-linked polyethylene and polyolefin compounds dominate medium-voltage heat-shrink manufacturing. Scandinavian utilities now mandate phthalate-free certification under ECHA enforcement timelines, redirecting specification preference toward compounders with in-house REACH compliance laboratories in Denmark and Sweden.
- Rubber:Liquid silicone rubber and EPDM formulations provide elastic recovery and dielectric stability across temperature cycling. Italian and German pre-molded joint specialists source these through backward integration into polymer production to buffer feedstock price volatility affecting cold-shrink margin pools.
- Metal:Aluminum and copper stress-control inserts for field-control geometry in high-voltage joints.
- Composite:Glass-reinforced polymer housings for mechanical protection in subsea installations.
Polymer maintains the largest installed base; Rubber is climbing the fastest on cold-shrink substitution trends.
Application:
Grid modernization fund disbursement schedules are sequencing procurement waves that favor distribution refurbishment before transmission greenfield investments.
- Power Transmission:220-500 kV joints for overhead line transitions and substation cable terminations. French and Spanish TSOs are accelerating 400 kV pre-molded procurement for cross-border interconnector reinforcement, though factory capacity constraints at German and Italian suppliers extend lead times.
- Distribution:1-36 kV joints for underground residential and industrial feeder networks. Italian and Polish utilities channel national recovery allocations toward medium-voltage refurbishment, lifting resin and heat-shrink volumes for direct-buried and duct-bank installations.
- Renewable Energy:Subsea and land-based joints for offshore wind export cables and solar farm collection systems.
- Communication:Fiber-optic cable joints for telecom infrastructure with minimal power-handling requirements.
Distribution absorbs the highest unit volumes; Renewable Energy shows the steepest expansion trajectory on North Sea offshore wind commissioning schedules.
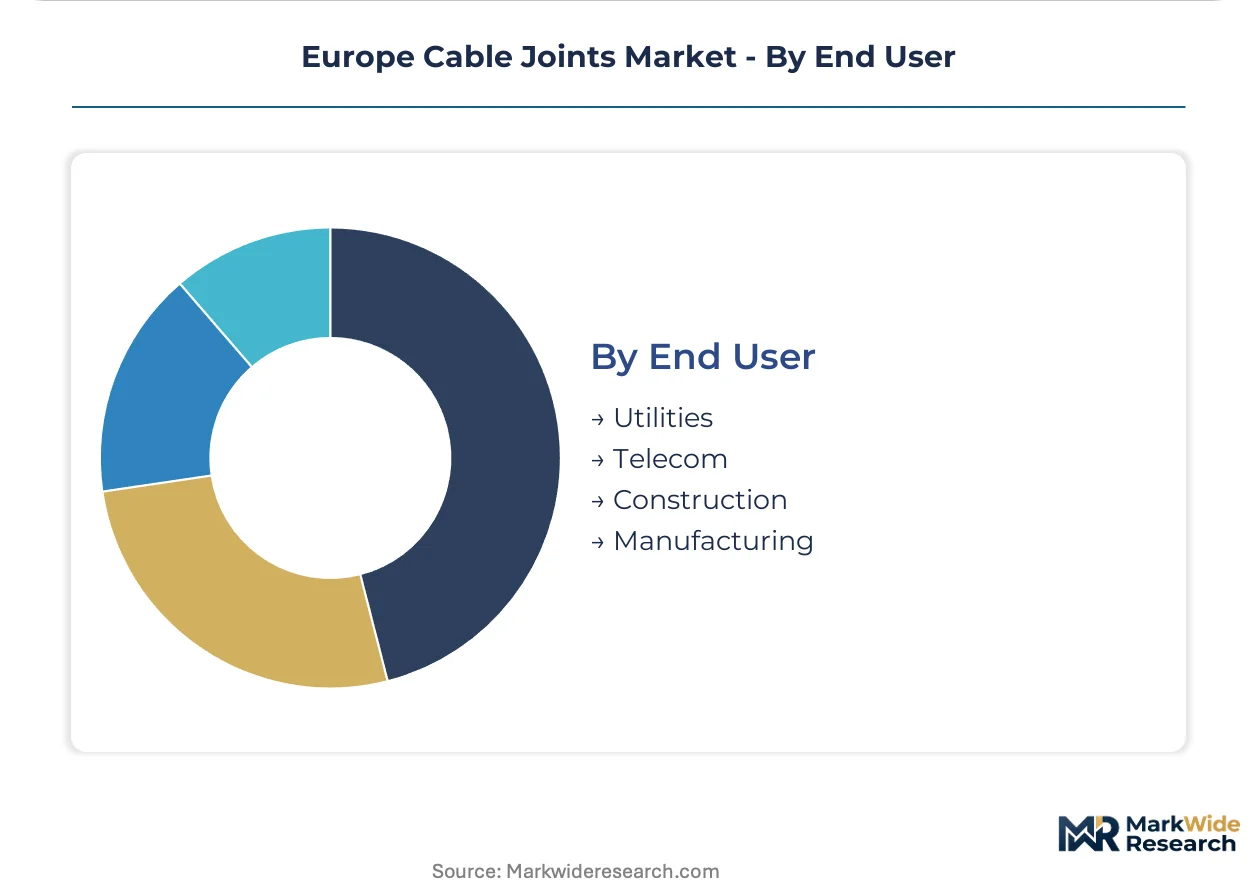
End User:
Procurement centralization patterns vary sharply across utility ownership structures and regulatory incentive frameworks governing network investment recovery.
- Utilities:Transmission and distribution system operators with standardized technical specifications and multi-year framework agreements. United Kingdom and Netherlands TSOs are unbundling hardware purchase from installation and monitoring services, displacing traditional bundled EPC contracting for interconnector projects.
- Telecom:Fiber network operators with joint requirements limited to mechanical protection and environmental sealing. Benelux and German fiber rollout programs generate recurring demand for low-voltage cold-shrink solutions in roadside cabinet and duct applications.
- Construction:Commercial and residential developers procuring joints through electrical contractor intermediaries.
- Manufacturing:Industrial facility owners with captive medium-voltage distribution networks.
Utilities dominate absolute procurement value; Construction offers the most fragmented pricing environment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Port of Rotterdam anchors North Sea offshore wind logistics, channeling subsea cable joint procurement toward Dutch installation contractors serving German and Danish interconnector projects.
Germany
Grid operators in North Rhine-Westphalia accelerate 400 kV pre-molded joint procurement for cross-border transmission reinforcement. The KBA enforces sector-specific qualifications for rail-adjacent cable installations. Munich-based engineering clusters concentrate EHV joint design expertise serving Austrian and Swiss export markets.
United Kingdom
Distribution network operators in London and the Southeast prioritize cold-shrink retrofit solutions to minimize urban outage windows. Ofgem's RIIO-ED2 price control mechanism channels capital toward underground cable refurbishment. Aberdeen's subsea technology corridor hosts joint testing facilities for North Sea wind farm export cables.
France
Transmission system operators in Île-de-France advance 400 kV interconnector projects requiring specialized high-voltage joint engineering. ANSM enforces procurement qualifications for nuclear-adjacent installations. Lyon-based polymer compounders reformulate EPDM bases to meet REACH phthalate restrictions.
Netherlands
TenneT's offshore wind connection program drives 220 kV+ subsea joint volumes through Rotterdam port logistics. The EU Green Deal shapes tender scoring for carbon-footprint-validated accessories. Eindhoven's high-voltage testing laboratories certify joint designs for Benelux distribution networks.
Poland
Rural electrification programs in Mazovia and Silesia lift medium-voltage resin joint demand for direct-buried installations. EU cohesion fund access accelerates distribution network refurbishment timelines. Warsaw-based contractors expand EN 50393-qualified installer training to address certification gaps.
Europe Cable Joints Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the European cable joints market. Factory-controlled pre-molded manufacturing demands specialized curing equipment and clean-room environments, while cold-shrink specialists outsource silicone rubber compounding to polymer partners. Three archetypes dominate: integrated cable-to-accessory platforms, specialized high-voltage engineering houses, and retrofit-focused cold-shrink distributors. Capacity expansion and predictive maintenance service bundling represent the primary competitive vectors reshaping vendor positioning.
Within the integrated platform tier, Prysmian Group and Nexans S.A. occupy positions anchoring long-term utility service contracts through captive cable production synergies. TE Connectivity Ltd. exemplifies the retrofit-specialist archetype, with cold-shrink expertise aligned to distribution network operator priorities. ABB Ltd and NKT A/S represent scale-driven engineering conglomerates where cable joints sit within broader electrification portfolios.
| Leading Market Players |
|---|
| ABB Ltd |
| 3M International |
| Prysmian Group |
| Cable Jointer Solutions |
| Fujikura |
| Nexans S.A. |
| TE Connectivity Ltd. |
| Connect Cable Accessories Co., Ltd. |
| NKT A/S |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal's carbon-footprint certification requirements gate qualified supply for premium-tier cable joint procurement across French and Benelux transmission operators. REACH phthalate restrictions compound material qualification costs, concentrating pricing power among compounders with in-house compliance laboratories in Denmark and Sweden while squeezing margin pools for distributors dependent on external formulation sources.
Pricing Analysis
Uptime-guarantee contracting anchors value-based pricing for predictive maintenance bundles in United Kingdom and Netherlands interconnector projects. Three-tier pricing structure across premium, standard, and economy levels separates factory-cured pre-molded joints from cold-shrink retrofit lines and heat-shrink commodity offerings. Cost compression in cold-shrink segments is intensifying because liquid silicone rubber feedstock volatility erodes polymer-intensive design margins. Distribution utilities in Poland and Iberia exhibit highest price sensitivity, while German and French TSOs prioritize installation-speed premiums over unit cost.
Supply Chain Analysis
Joint refurbishment and core-return programs for cold-shrink installations are emerging as reverse-logistics differentiators among Dutch and German distributors. Manufacturing concentrates in Germany, Italy, and Denmark, with EHV pre-molded curing capacity anchored in Munich and Milan engineering clusters. Raw material flows draw from liquid silicone rubber producers in Germany, EPDM compounders in Lyon, and cross-linked polyolefin specialists in Scandinavia. Single-source vulnerability persists for 400 kV+ factory-controlled geometry where German and Italian suppliers dominate qualified capacity. Distribution runs through utility framework agreements and EPC contractor intermediaries, with direct procurement expanding among unbundled service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Factory-cured pre-molded capacity constraints at German and Italian suppliers prop pricing premiums across European EHV procurement, creating supply-constrained dynamics favoring incumbent compounders with backward-integrated polymer production.
For Market Incumbents: Acquire EN 50393-qualified installer training networks in Iberia and Eastern Europe to capture deployment velocity constrained by certification scarcity. Prysmian Group and Nexans S.A. should expand captive silicone rubber compounding to buffer feedstock volatility threatening cold-shrink margin pools. Defensive positioning requires anchoring long-term thermal monitoring service contracts before predictive maintenance platforms commoditize hardware attachment. For New Entrants and Emerging Players: The mid-tier price gap between premium pre-molded and economy heat-shrink offerings creates entry space for mechanical-expansion sealing systems in Polish and Romanian distribution refurbishment. Target rural electrification programs in Mazovia and Silesia where EU cohesion fund access accelerates medium-voltage joint deployment. Channel partnerships with Warsaw-based contractors expanding qualified installer training offer the most penetrable go-to-market path. For Investors and Strategic Acquirers: TenneT's offshore wind connection program tender awards are the leading indicator that subsea joint service bundling will consolidate around integrated cable-to-accessory platforms. Long-term viability over the next decade hinges on predictive maintenance software classification clarity under the EU AI Act. Acquisition targets should display backward integration into REACH-compliant polymer formulation and installed base density in North Sea logistics corridors. Monitor F-Gas Regulation phase-down enforcement velocity for signals on vacuum-interruption technology substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive silicone rubber production buffers feedstock volatility affecting cold-shrink margin pools at TE Connectivity Ltd. |
| Predictive Maintenance Service Bundling | Fiber-optic thermal sensing convergence with cloud analytics opens recurring revenue streams for Prysmian Group's utility contracts. |
| EN 50393 Installer Certification Expansion | Training network acquisition in Iberia addresses field technician scarcity constraining 110 kV+ resin-cured joint deployment velocity. |
| Mechanical-Expansion Sealing Technology Adoption | German and Austrian utilities adopt modularized workflows eliminating heat-gun dependency and reducing outage windows. |
| EU Green Deal Carbon-Footprint Certification | Harmonized protocol validation captures tender preference among French and Benelux transmission operators procuring accessories. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with utility procurement officers, EPC contractors, polymer compounders, and grid operators across Germany, France, and the United Kingdom. ECHA substance restriction databases, KBA rail qualification registries, and ANSM nuclear-adjacent procurement records provided compliance tracking foundations. Bottom-up joint volume estimates from national recovery fund disbursement schedules were triangulated against top-down cable production correlations.
Data-stream reconciliation across installation-method splits, voltage-tier procurement patterns, and material formulation specifications shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, material composition, application voltage tier, and end-user procurement centralization patterns. CAGRs were derived from utility capital expenditure trajectories and offshore wind commissioning schedules. Forecast inputs incorporated REACH enforcement timelines and F-Gas Regulation phase-down milestones affecting installation technology substitution.
Inputs from utility framework agreement disclosures and polymer compounder production records were available through the study window; gaps in real-time installer certification tracking across Eastern European markets introduce uncertainty bands around deployment velocity assumptions. Practitioners should monitor TenneT tender award patterns and ECHA phthalate restriction enforcement velocity for early signals on premium-tier pricing power and supply qualification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Wire and Cable Materials Market
Cables
Downhole Cables Market
Cables
Fiber Optic Cable Materials Market
Cables
Cable Testing and Certification Market
Cables
Mineral Insulated (MI) Cable Market
Cables
High Voltage Cable Termination Market
Cables
High-Speed Interconnects Market
Cables
Asia Pacific MV and HV Underground Cables and Accessories Market
Cables
Global Low Voltage Cable Market
Cables
Europe Cable Accessories Market
Cables
Aluminium Battery Cable Market
Cables
Cable Racks Market
Cables
USB Cable Market
Cables
Submarine Optical Fiber Cables Market
Cables
Power and Control Cable Market
Cables
Coaxial Cable Market