
 Global Multi Coaxial Connectors Market | 2026-2036
Global Multi Coaxial Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Multi Coaxial Connectors Market Outlook
Distributor consolidation across North America and Western Europe is reconfiguring how multi coaxial connectors reach mid-tier OEMs. Amphenol Corporation leverages captive manufacturing across Mexico and China to sustain price competitiveness in RF connector lines. HUBER+SUHNER anchors its position through fiber-coaxial hybrid portfolios that dominate Swiss and German railway signaling installations. TE Connectivity competes on medical-grade cable assembly certifications that lock in healthcare manufacturer loyalty across FDA-regulated supply chains.
Multi coaxial connectors are electromechanical interfaces engineered to transmit radio-frequency signals through concentric conductor arrangements, typically achieving impedance tolerances of 50 or 75 ohms with shielding effectiveness exceeding 100 dB at microwave frequencies; they serve as critical junction points in systems where signal integrity, electromagnetic compatibility, and mechanical durability converge. Standard coaxial variants retain the largest installed base in legacy broadcast infrastructure, though mini coaxial formats are displacing them in portable medical imaging equipment where PCB real estate constraints tighten. RF connectors command premium positioning in aerospace applications, while compression connectors dominate telecom field installations where technician skill levels vary.
FCC equipment authorization rules in the United States shape connector performance thresholds for 5G millimeter-wave deployments, while EU CE marking and RoHS substance restrictions filter non-compliant Asian suppliers from European medical and automotive channels. Japan's METI promotes domestic JIS-standard interconnects through procurement preferences in public infrastructure, reinforcing insularity in its base station supply chain. Stakeholders must track evolving spectrum allocations and material compliance deadlines as primary determinants of product roadmap viability and market access eligibility.
Market Dynamics
Defense procurement cycles in the United States and Europe are compressing qualification timelines for ruggedized interconnect systems, forcing suppliers to parallel-track environmental testing with design validation rather than sequential gating.
Growth Catalysts
- 5G Millimeter-Wave Spectrum Allocation:FCC equipment authorization rules in the United States mandate stricter performance thresholds for base station deployments, pulling demand for precision RF connectors into South Korean and German manufacturing hubs.
- RoHS and REACH Compliance Mandates:ECHA substance restrictions in the European Union accelerate substitution of cadmium-plated shells with nickel-PTFE finishes, creating refresh demand across medical and automotive channels.
- Electronic Warfare Platform Modernization:Pentagon procurement offices and NATO defense agencies expand sourcing of shielded multi-coaxial assemblies for next-generation signal intelligence systems.
Market Restraints
- Raw Material Concentration Risk:Beryllium copper and high-purity PTFE supply chains concentrate among specialty chemical processors in Japan and Germany, exposing connector manufacturers to input volatility.
- Qualification Cost Barriers:MIL-STD-810 environmental testing and DO-160 airborne equipment certification impose six-figure validation costs that exclude mid-tier entrants from aerospace and defense contracts.
- Fiber-Optic Substitution Pressure:Single-mode fiber assemblies displace coaxial trunk lines in terrestrial telecom backhaul above 10 GHz, compressing addressable market for traditional RF connectors.
Strategic Opportunities
- India Industrial Automation Corridor:PLI scheme incentives for electronics manufacturing draw connector assembly investment toward Pune and Chennai industrial zones, creating captive supply opportunities for automation OEMs.
- Fiber-Coaxial Hybrid Architectures:Railway signaling networks in Switzerland and Germany integrate hybrid interconnect portfolios that combine optical and RF pathways within single ruggedized housings.
- Medical-Grade Certification Pathways:FDA 21 CFR Part 820 quality system requirements and EU MDR technical documentation standards lock in cable assembly partnerships with imaging equipment manufacturers.
Industry Challenges
- RF Simulation Talent Scarcity:Electromagnetic field modeling for millimeter-wave connector geometries requires specialized ANSYS HFSS or CST Studio expertise that outpaces vocational training pipelines.
- Legacy System Integration Friction:Backward compatibility demands for 50-ohm interfaces in broadcast infrastructure delay adoption of miniaturized PCB-mount variants despite space constraints.
- Cross-Border Certification Timelines:Dual-track approvals for CE marking and FCC equipment authorization extend product launch windows by eight to fourteen months for multi-region suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Multi Coaxial Connectors Market |
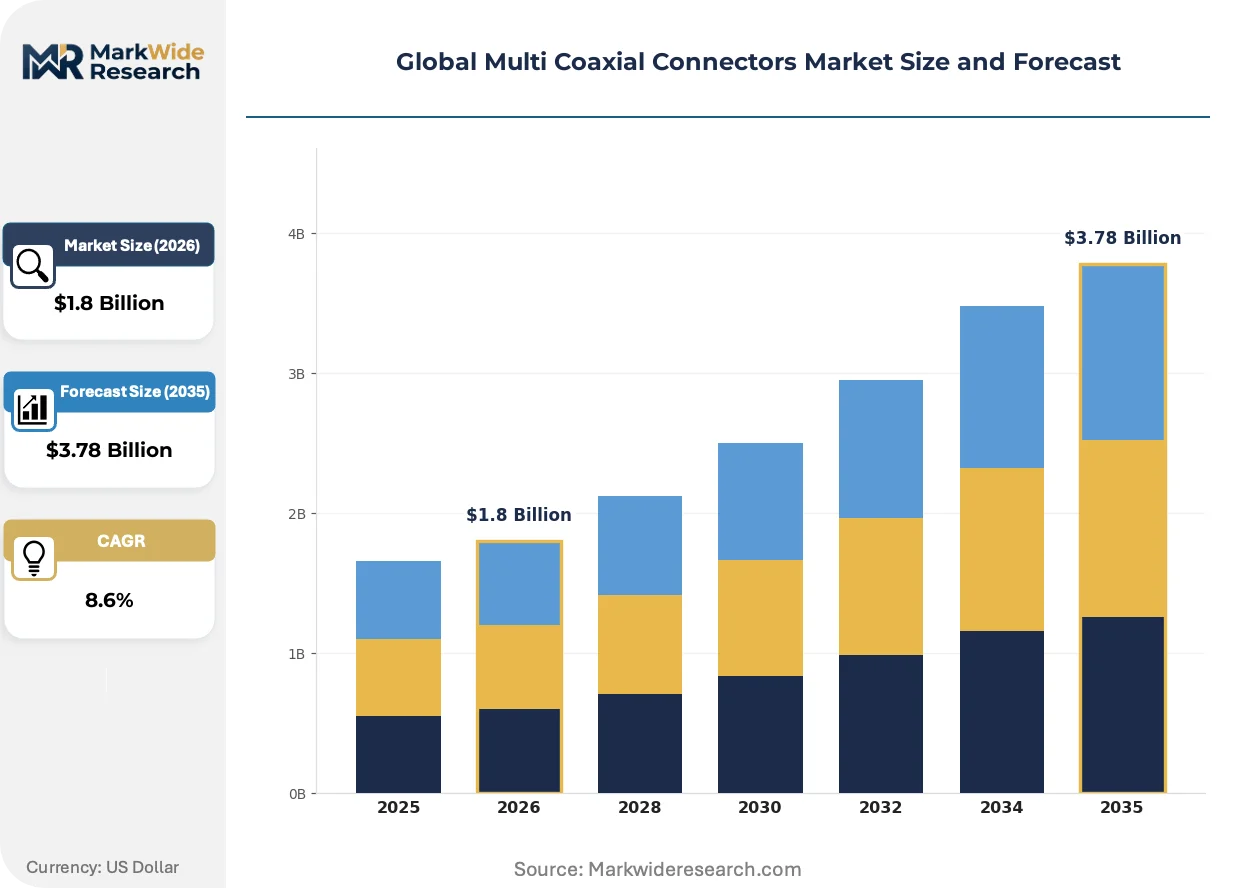
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Coaxial, Mini Coaxial, Compression Connectors, RF Connectors Application: Telecommunications, Aerospace, Medical Devices, Military Equipment Installation Type: Cable Assemblies, PCB Mounting, Panel Mount, Inline End User: Telecom Providers, Defense Contractors, Healthcare Manufacturers, Aerospace Companies |
| Companies Covered | Amphenol Corporation, HUBER+SUHNER, Molex, Laird Connectivity, HARTING, Murata Manufacturing, Southwest Microwave, Japan Aviation Electronics, TE Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Multi Coaxial Connectors Market Strategic Shifts
Signal integrity engineering and material science advances are converging to redefine connector architectures, with hybrid electromagnetic-optical systems and environmentally compliant surface finishes commanding development priority.
Miniaturized coaxial formats with sub-miniature push-on interfaces are hybridizing traditional screw-type coupling mechanisms with snap-lock retention systems. Portable medical imaging OEMs in Germany and South Korea adopt these variants to reclaim PCB real estate in handheld ultrasound and endoscopic systems. The technology is hybridizing procurement specifications across diagnostic equipment categories, collapsing legacy distinctions between laboratory and point-of-care connector grades.
REACH Annex XVII restrictions on cadmium and hexavalent chromium are forcing surface finish conversions across European medical and automotive supply chains. ECHA enforcement actions against non-compliant Asian shell suppliers filter market access, concentrating qualified vendor pools among nickel-PTFE and electroless nickel immersion gold finish specialists. German automotive Tier-1s respond by consolidating connector sourcing to pre-qualified European plating houses with documented substance compliance.
Defense procurement offices now mandate vendor-owned environmental testing rather than third-party laboratory certification for mission-critical interconnects. This pattern compresses supplier qualification cycles in United States and United Kingdom electronic warfare programs, rewarding captive vertical integration over outsourced validation. The shift is most visible in Maryland and Bavaria defense corridors, where prime contractors pre-position approved vendor lists with embedded testing capabilities.
Global Multi Coaxial Connectors Market Segmentation
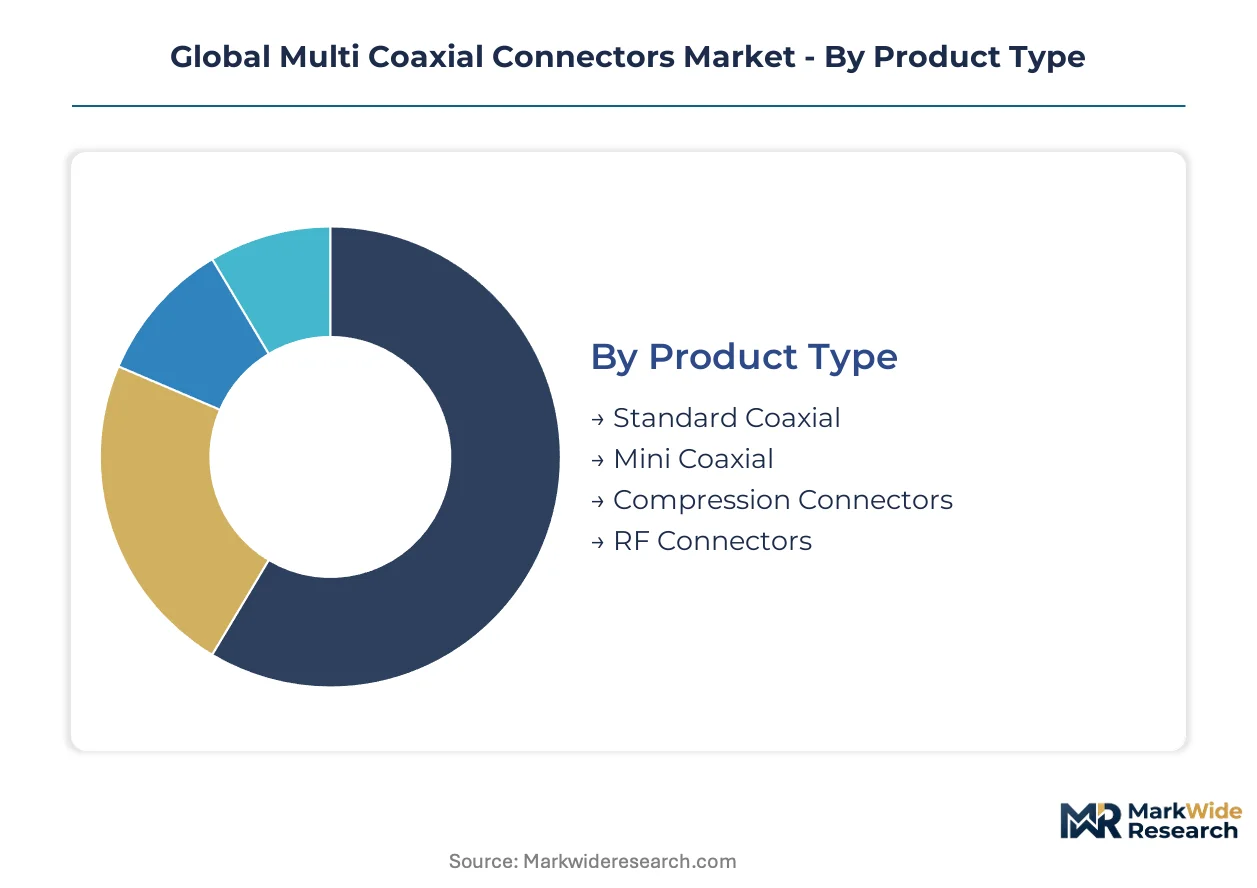
Multi coaxial connectors fragment across four distinct classification axes that determine specification rigor, qualification burden, and margin structure. Product geometry dictates impedance tolerance and shielding bandwidth. Application verticals impose divergent certification regimes from FDA medical device clearances to MIL-STD-810 environmental compliance.
Product Type:
Cost tier stratification separates legacy volume products from precision RF variants that command premium positioning in defense and aerospace channels.
- RF Connectors:Precision-machined interfaces achieve VSWR below 1.2:1 through millimeter-wave frequencies with beryllium copper center contacts and gold-over-nickel plating. Pentagon electronic warfare programs and South Korean 5G base station manufacturers concentrate procurement of these variants where signal integrity failures carry mission-critical consequences.
- Standard Coaxial:The largest installed base persists in legacy broadcast infrastructure and cable television distribution networks with 50-ohm or 75-ohm impedance ratings and brass or zinc die-cast housings. Replacement demand concentrates in North American headend facilities where coaxial trunk lines remain economically entrenched against fiber substitution.
- Mini Coaxial:Sub-miniature push-on interfaces reclaim PCB real estate in portable diagnostic equipment with snap-lock retention replacing threaded coupling. German handheld ultrasound OEMs and South Korean endoscopic system manufacturers drive specification convergence across point-of-care imaging categories.
- Compression Connectors:Field-installable designs with captive center pins and weatherproof sealing dominate telecom outdoor plant installations where technician skill levels vary. German railway signaling contractors specify these for trackside coaxial drops requiring tool-free assembly.
Standard coaxial holds installed capacity. RF connectors are rotating up the share rankings.
Application:
End-use verticals impose qualification timelines that stretch from weeks for commercial telecom to years for airborne equipment certification.
- Military Equipment:Shielded multi-coaxial assemblies for signal intelligence platforms require vendor-owned environmental testing and DO-160 airborne certification. United States and United Kingdom defense corridors in Maryland and Bavaria compress supplier qualification cycles through pre-approved vendor lists with embedded validation capabilities.
- Medical Devices:FDA 21 CFR Part 820 quality systems and EU MDR technical documentation lock in cable assembly partnerships with imaging equipment manufacturers. German diagnostic OEMs specify nickel-PTFE finishes to satisfy REACH Annex XVII substance restrictions on cadmium and hexavalent chromium.
- Aerospace:MIL-STD-810 testing and DO-160 certification impose six-figure validation costs that exclude mid-tier entrants from commercial aviation and satellite programs.
- Telecommunications:FCC equipment authorization rules for 5G millimeter-wave deployments mandate stricter performance thresholds that pull connector demand into South Korean and German manufacturing hubs.
Telecommunications commands volume throughput. Military equipment claims the steepest expansion trajectory.
Installation Type:
Mounting geometry determines labor content, field serviceability, and integration density in constrained mechanical envelopes.
- PCB Mounting:Surface-mount and through-hole configurations with integrated retention clips address space constraints in miniaturized medical electronics. South Korean RF front-end module manufacturers specify these for 5G smartphone baseband integration.
- Cable Assemblies:Pre-terminated harnesses with overmolded strain relief dominate industrial automation and defense platform integration where installation labor costs exceed material costs.
- Panel Mount:Bulkhead interfaces with EMI gaskets and jackscrew retention secure bulkhead penetrations in ruggedized enclosures for German railway signaling and Swiss tunnel communication systems.
- Inline:Barrel connectors for field splicing and repair scenarios preserve system availability in remote telecom infrastructure where technician dispatch costs dominate lifecycle economics.
Cable assemblies hold installed capacity. PCB mounting is rotating up the share rankings.
End User:
Customer type determines procurement modality, contract structure, and technical support intensity across the product lifecycle.
- Defense Contractors:Prime contractors in United States and European electronic warfare corridors mandate captive vertical integration with vendor-owned testing rather than third-party laboratory certification. This procurement pattern compresses qualification timelines and rewards approved vendor list positioning.
- Healthcare Manufacturers:FDA-regulated supply chains lock in cable assembly partnerships through medical-grade certification pathways that span quality system audits and biocompatibility documentation.
- Telecom Providers:South Korean and German 5G infrastructure deployers concentrate demand for precision RF connectors where FCC and CE marking requirements filter non-compliant suppliers from authorized vendor pools.
- Aerospace Companies:Commercial aviation and satellite manufacturers impose DO-160 environmental testing and traceability requirements that sustain specialist supplier ecosystems.
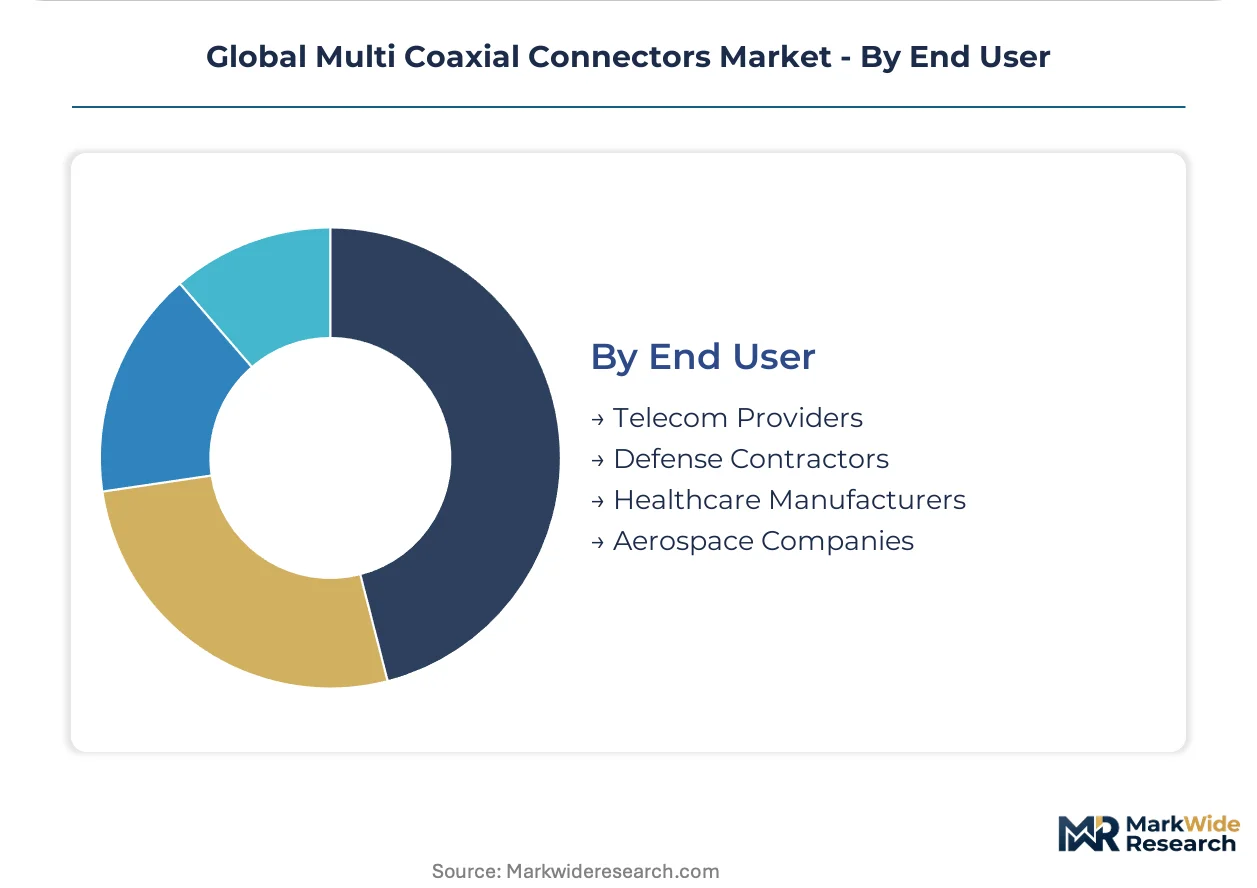
Telecom providers hold installed capacity. Defense contractors are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Swiss precision manufacturing corridors while South Korean volume producers compress margins through scale economies in 5G infrastructure components.
United States
Pentagon electronic warfare programs and FCC millimeter-wave equipment authorizations drive demand for precision RF connectors. Defense procurement offices in Maryland mandate vendor-owned environmental testing rather than third-party laboratory certification. Baltimore-Washington defense corridor suppliers compress qualification timelines through pre-approved vendor lists with embedded validation capabilities.
Germany
Industrial automation OEMs and railway signaling contractors anchor demand for fiber-coaxial hybrid interconnects. ECHA REACH Annex XVII enforcement actions filter non-compliant Asian suppliers from medical and automotive channels. Munich-Stuttgart industrial belt manufacturers consolidate sourcing to pre-qualified European plating houses with documented nickel-PTFE finish compliance.
South Korea
5G base station manufacturers and RF front-end module producers concentrate procurement of PCB-mount mini coaxial formats. FCC equipment authorization rules for millimeter-wave deployments pull connector demand into Seoul-Incheon manufacturing hubs. Domestic producers leverage scale economies to supply global telecom infrastructure deployers.
Switzerland
Railway signaling networks and tunnel communication systems specify hybrid electromagnetic-optical interconnects with ruggedized housings. Swissmedic medical device regulations align with EU MDR technical documentation standards for diagnostic equipment manufacturers. Zurich-Bern corridor suppliers dominate alpine infrastructure projects requiring EMI-gasketed panel mount configurations.
Japan
METI procurement preferences for JIS-standard interconnects reinforce insularity in domestic base station supply chains. Beryllium copper and high-purity PTFE specialty chemical processors concentrate input supply among Osaka-Nagoya industrial zone manufacturers. Domestic vendors maintain captive positions in public infrastructure procurement despite export market constraints.
Global Multi Coaxial Connectors Market Competitive Environment
Vertically integrated defense specialists and diversified industrial conglomerates split the market along qualification-intensity lines. Consolidation patterns favor suppliers with captive environmental testing capabilities over outsourced validation models. Three archetypes dominate: precision RF specialists with aerospace certifications, diversified interconnect conglomerates with medical-grade cable assembly portfolios, and regional scale producers serving telecom infrastructure. Competitive moves center on backward integration into plating and material processing, plus geographic expansion through Mexico and Southeast Asia assembly footprints.
Among diversified interconnect conglomerates, Amphenol Corporation, TE Connectivity, and HUBER+SUHNER occupy positions that exemplify contrasting strategic emphases. Amphenol represents the vertically integrated archetype with captive manufacturing footprints spanning multiple geographies. TE Connectivity anchors the medical-grade certification pathway through FDA-regulated supply chain partnerships. HUBER+SUHNER exemplifies specialization in fiber-coaxial hybrid portfolios for transportation infrastructure. These three entities collectively illustrate how qualification intensity, geographic scope, and application focus segment competitive positioning in precision interconnect markets.
| Leading Market Players |
|---|
| Amphenol Corporation |
| HUBER+SUHNER |
| Molex |
| Laird Connectivity |
| HARTING |
| Murata Manufacturing |
| Southwest Microwave |
| Japan Aviation Electronics |
| TE Connectivity |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor shapes cost dynamics across the multi coaxial connector supply chain, with container rate volatility feeding into both raw material procurement and downstream price stratification between configured-to-order RF assemblies and standard catalog items.
Pricing Analysis
The customization-premium spread separates precision-machined RF connectors from standard coaxial variants by a factor reflecting certification intensity and material grade. Pricing stratifies across premium, standard, and economy tiers where MIL-STD-810 qualified assemblies command substantial premiums over commercial-grade alternatives. Cost compression in standard coaxial lines is intensifying as South Korean volume producers expand PCB-mount miniaturized formats. Telecom infrastructure deployers exhibit highest price sensitivity, while defense contractors prioritize performance guarantees over unit economics.
Supply Chain Analysis
Extended payment terms from German automotive Tier-1s and supply-chain finance facilities anchored by Swiss railway contractors redistribute working capital burdens across the supplier base. Manufacturing concentrates in Germany, South Korea, and Japan where beryllium copper and high-purity PTFE feedstock availability rests on Osaka-Nagoya specialty chemical processors. Single-source vulnerability in Japanese beryllium copper supply exposes connector manufacturers to input disruption. Distribution runs through authorized distributor networks in North America and Western Europe, with direct OEM relationships dominating defense and medical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The multi coaxial connector market sits at a platform-economics inflection where fiber-coaxial hybrid architectures collapse traditional boundaries between optical and RF interconnect procurement specifications, rewarding suppliers with cross-domain certification portfolios.
For Market Incumbents: Harden environmental testing capabilities through captive laboratory investment rather than outsourced validation, as Pentagon procurement offices and NATO defense agencies now mandate vendor-owned MIL-STD-810 certification. Deepen backward integration into nickel-PTFE plating operations to satisfy ECHA REACH Annex XVII enforcement timelines and lock out non-compliant Asian competitors from European medical and automotive channels. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized electronics manufacturing corridor, where Pune and Chennai industrial zones offer captive supply opportunities for automation OEMs with lower qualification barriers than aerospace or defense segments. Target fiber-coaxial hybrid interconnects for railway signaling networks, leveraging tool-free compression connector designs to bypass entrenched European incumbents in Swiss and German infrastructure projects. For Investors and Strategic Acquirers: Precision RF specialists with embedded DO-160 airborne certification represent the most defensible acquisition archetype, given six-figure validation costs that exclude mid-tier entrants from commercial aviation and satellite programs. Monitor FCC millimeter-wave spectrum allocation announcements and ECHA substance restriction enforcement actions as primary inflection indicators for product roadmap viability and market access eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Environmental Testing Investment | Pentagon procurement offices now mandate vendor-owned MIL-STD-810 validation rather than third-party laboratory certification. |
| Backward Integration into Nickel-PTFE Plating | ECHA REACH Annex XVII enforcement actions filter non-compliant Asian shell suppliers from European medical and automotive channels. |
| Fiber-Coaxial Hybrid Portfolio Development | Swiss and German railway signaling networks integrate hybrid interconnects combining optical and RF pathways within single ruggedized housings. |
| India Manufacturing Footprint Expansion | PLI scheme incentives for electronics manufacturing draw connector assembly investment toward Pune and Chennai industrial zones. |
| Medical-Grade Certification Pathway Investment | FDA 21 CFR Part 820 quality systems and EU MDR technical documentation lock in cable assembly partnerships with imaging equipment manufacturers. |
Study Parameters
Desk research of customs trade databases, SEC filings from diversified interconnect conglomerates, and ECHA substance restriction enforcement records preceded structured interviews with defense procurement officers, biomedical engineers at German diagnostic OEMs, RF front-end module designers at South Korean telecom manufacturers, and railway signaling contractors in Switzerland. Primary fieldwork with these stakeholders combined with secondary validation against FCC equipment authorization databases and METI public infrastructure procurement records. Bottom-up demand modeling across installation types and end-user categories was triangulated against top-down supply-side capacity assessments.
Assumptions regarding sustained 5G millimeter-wave deployment momentum, continued ECHA enforcement of REACH Annex XVII substance restrictions, and stable Pentagon electronic warfare procurement budgets were held fixed across the projection horizon, while variables including raw material input costs and cross-border certification timelines were stress-tested across sensitivity bands. The analytical framework modeled product type, application vertical, installation geometry, and end-user procurement modality as primary segmentation dimensions. CAGRs were derived from installed base replacement cycles and new platform adoption curves, with RF simulation talent scarcity and fiber-optic substitution pressure incorporated as demand-side constraints.
Stress conditions across beryllium copper supply disruption, FCC spectrum reallocation, and ECHA substance restriction expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and boundary conditions. Macroeconomic contraction, regulatory enforcement acceleration, or breakthrough fiber-optic cost reductions would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Automotive Data Connectors Market
Connectors
Cable Connectors and Adapters Market
Connectors
Mexico Connector Market
Connectors
IC Socket Market
Connectors
Telecom Mounting Hardware Market
Connectors
Underwater Connectors Market
Connectors
Magnetic Connector Market
Connectors
Terminal Pins Market
Connectors
PCI-E Connectors Market
Connectors
Relay Sockets Market
Connectors
LCP Connectors Market
Connectors
Middle East Connector Market
Connectors
USB Type-C Market
Connectors
Global Board to Board (BTB) Connectors Market
Connectors
Connector Kits Market
Connectors
Global Fiber Optic Connectors Market