
 Shipboard Cable Market | 2026-2036
Shipboard Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Shipboard Cable Market Insights
Naval defense agencies are reorganizing procurement priorities toward integrated power and communication systems aboard next-generation warships. Prysmian Group leverages its submarine cable expertise to extend into naval shipboard solutions with specialized armored constructions. Nexans sustains a dominant position in European naval programs through its mastery of halogen-free fire-resistant compounds. Sumitomo Electric Industries anchors Asian supply chains with vertically integrated copper processing and marine-grade insulation compounding.
Shipboard cables are purpose-built electrical conductors engineered for maritime environments, typically featuring tinned copper stranding, cross-linked polyethylene or ethylene propylene rubber insulation, and braided metallic armor to withstand salt corrosion, mechanical abrasion, and hydrocarbon exposure. These cables distribute power, transmit control signals, and enable data communications across vessels where failure risks catastrophic operational loss. Power cables and fiber optic cables represent the most dynamic segments, with offshore platforms and naval vessels driving premium-grade demand where voltage ratings and electromagnetic immunity determine contract awards. Control cables and instrumentation cables occupy mature, specification-intensive niches where incumbent suppliers compete on catalog breadth and classification society approvals.
The International Maritime Organization enforces SOLAS fire safety protocols that dictate low-smoke zero-halogen material specifications for all passenger vessel installations, directly elevating compound costs and supplier qualification barriers. IEC 60092 series standards and classification rules from Lloyd's Register and DNV govern electrical system certification, creating fragmented compliance obligations across flag states and build yards. Stakeholders must monitor evolving naval electrification architectures and alternative fuel propulsion systems that will redefine cable thermal ratings and shielding requirements.
Market Dynamics
Fleet electrification architectures and alternative fuel propulsion systems are redefining thermal ratings and electromagnetic shielding requirements across naval and commercial vessel programs. Shipbuilders now specify cables capable of handling higher power densities while maintaining fire-resistance certifications under revised maritime safety protocols.
Growth Catalysts
- SOLAS Fire Safety Mandates:The International Maritime Organization's revised protocols now require low-smoke zero-halogen compounds for all passenger vessel installations, creating mandatory upgrade cycles across existing fleets.
- Copper Processing Integration:Asian cable manufacturers with captive copper refining and marine-grade insulation compounding capabilities capture procurement contracts for LNG carrier and container ship programs.
- Naval Fleet Modernization:Defense agencies in South Korea, Japan, and the United States are accelerating integrated power and communication system deployments aboard next-generation warships.
Market Restraints
- Halogen-Free Compound Costs:Fire-resistant low-smoke insulation materials carry 40-60% cost premiums over standard marine cables, compressing margins for specification-grade suppliers.
- Classification Society Fragmentation:IEC 60092 series standards, Lloyd's Register rules, and DNV requirements create overlapping certification obligations that extend qualification timelines and raise compliance expenditures.
- Copper Price Volatility:Tinned copper stranding constitutes 60-70% of raw material costs, exposing manufacturers to London Metal Exchange fluctuations without effective hedging mechanisms.
Strategic Opportunities
- Offshore Platform Electrification:North Sea and Gulf of Mexico oilfield operators are replacing diesel generator systems with subsea power distribution networks requiring specialized armored cable constructions.
- Alternative Fuel Vessel Standards:Ammonia and hydrogen propulsion architectures under development at classification societies will necessitate entirely new cable thermal rating categories.
- Direct Shipyard Contracting:Hyundai Heavy Industries and Samsung Heavy Industries are consolidating supplier relationships through multi-year framework agreements that bypass traditional distributor channels.
Industry Challenges
- Electromagnetic Compatibility Engineering:Naval electrification architectures demand specialized shielding expertise that exceeds traditional marine cable design capabilities, creating talent acquisition bottlenecks.
- Classification Society Approval Timelines:Lloyd's Register and DNV certification processes for novel compound formulations extend 18-24 months, delaying product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shipboard Cable Market |
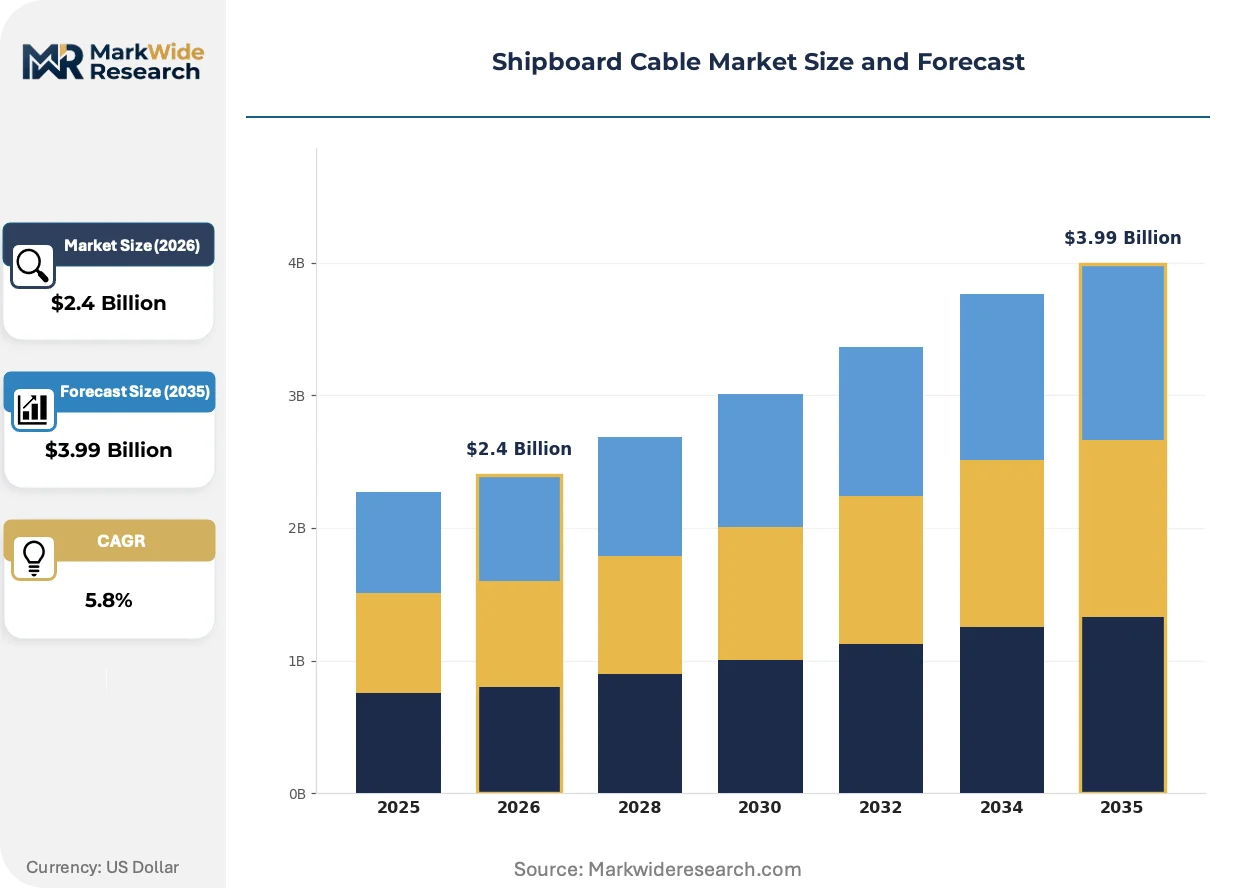
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Cables, Control Cables, Instrumentation Cables, Communication Cables, Fiber Optic Cables Technology: XLPE Insulation, PVC Insulation, EPR Insulation, Rubber Insulation, Teflon Insulation Application: Commercial Vessels, Naval Vessels, Offshore Platforms, Submersibles, Research Ships End User: Shipbuilders, Maritime Operators, Offshore Contractors, Defense Agencies, Research Institutions |
| Companies Covered | Prysmian Group, Nexans, LS Cable and System, Sumitomo Electric Industries, Furukawa Electric, Leoni AG, TE Connectivity, Eaton Corporation, Hengtong Optic-Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shipboard Cable Market Trends and Innovations
Material science advances and procurement model evolution are compressing product lifecycles while elevating performance thresholds. Three developments are restructuring competitive positioning across fire-resistant, high-voltage, and data transmission segments.
Cross-linked polyethylene insulation formulations with enhanced thermal stability are fragmenting the traditional ethylene propylene rubber dominance in medium-voltage shipboard applications. Korean and Japanese shipyards specify these compounds for electric propulsion systems operating at 6.6kV and above. The technology is fragmenting supplier hierarchies by rewarding compound chemistry capabilities over conventional cable manufacturing scale.
REACH restrictions on halogenated flame retardants are accelerating low-smoke zero-halogen material transitions across European-flagged vessels. ECHA substance evaluations have disqualified several legacy brominated compounds from newbuild approvals. German and Norwegian shipowners now mandate third-party smoke toxicity testing beyond baseline IEC certification, forcing reformulation investments.
Integrated power and data cable bundles are displacing separate power and fiber optic installations in naval combatant programs. Shipbuilders in South Korea and the United States specify these constructions to reduce cable count, weight, and electromagnetic interference risks. This consolidation is most visible in frigate and destroyer programs where space constraints and signature management priorities dominate design decisions.
Shipboard Cable Market Segmentation
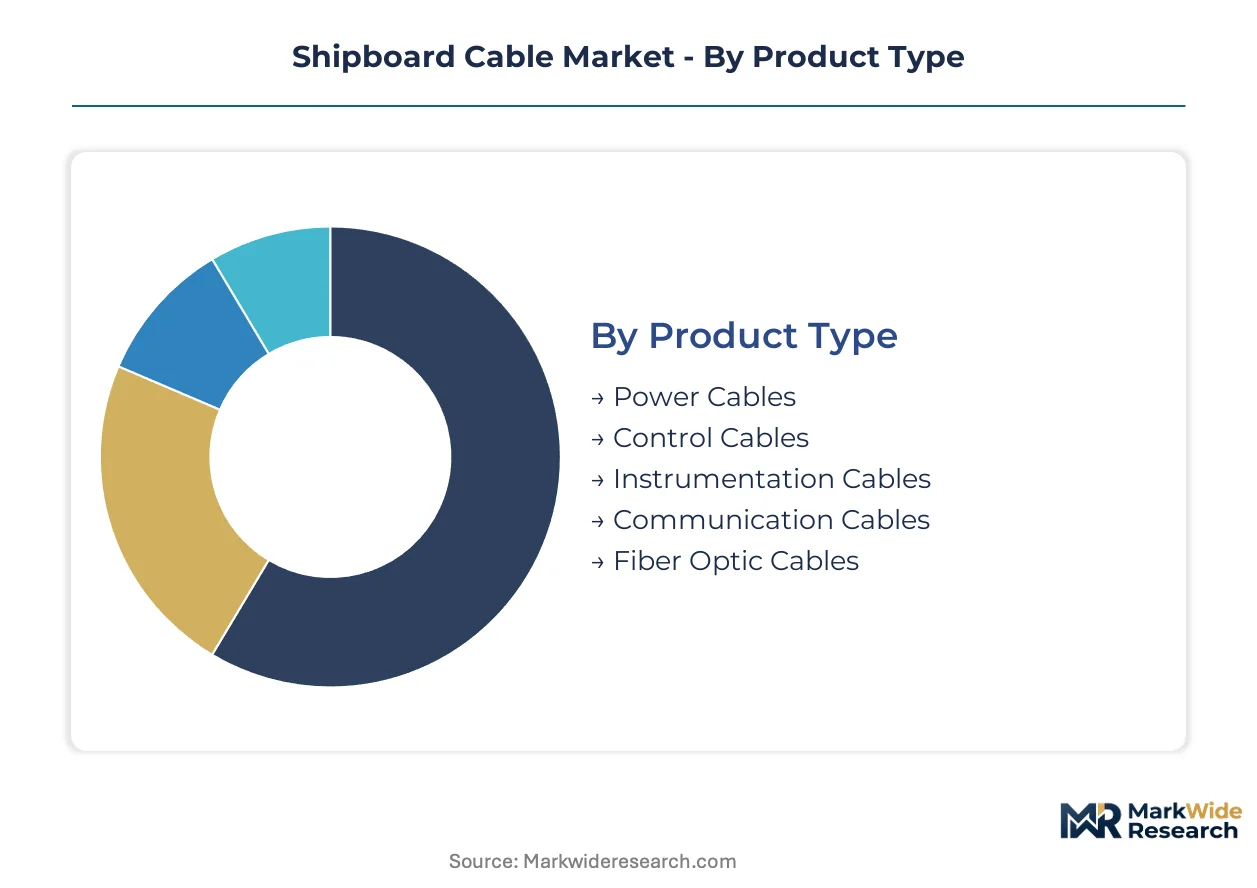
Shipboard cable procurement patterns diverge sharply across product architectures and end-use specifications. Margin pools concentrate where thermal ratings, fire-resistance certifications, and electromagnetic shielding requirements intersect with naval electrification programs.
Product Type:
Power cables and fiber optic constructions command the widest margin spreads, driven by voltage density requirements and data transmission specifications in modern vessel architectures.
- Power Cables:These conductors feature cross-linked polyethylene or ethylene propylene rubber insulation rated for 6.6kV and above in electric propulsion systems. South Korean shipyards specify enhanced thermal stability formulations for LNG carrier and container ship programs where power density demands are escalating.
- Fiber Optic Cables:Marine-grade optical fibers with armored protective layers enable high-bandwidth data transmission across integrated shipboard networks. Naval combatant programs in the United States and South Korea are consolidating power and data bundles to reduce electromagnetic interference risks and cable count.
- Control Cables:Multi-conductor assemblies for signal transmission between navigation, propulsion, and safety systems.
- Instrumentation Cables:Shielded pairs for sensor data acquisition in engine monitoring and process control applications.
- Communication Cables:Twisted-pair and coaxial constructions for internal shipboard voice and data networks.
Power cables hold installed capacity. Fiber optic cables are rotating up the share rankings.
Technology:
Compound chemistry capabilities determine supplier competitiveness as thermal rating thresholds escalate across medium-voltage applications.
- XLPE Insulation:Cross-linked polyethylene formulations with enhanced thermal stability are fragmenting traditional EPR dominance in medium-voltage shipboard segments. Korean and Japanese shipyards specify these compounds for electric propulsion systems operating at elevated voltages.
- EPR Insulation:Ethylene propylene rubber maintains penetration in legacy naval programs where proven field performance outweighs material transition costs. European defense procurement continues favoring EPR for halogen-free fire-resistant specifications under REACH-compliant formulations.
- PVC Insulation:Standard marine-grade polyvinyl chloride for non-critical power distribution in commercial vessel auxiliary systems.
- Rubber Insulation:Flexible constructions for temporary power and portable equipment connections in offshore platform maintenance operations.
- Teflon Insulation:High-temperature fluoropolymer compounds for specialized military and research vessel applications requiring extreme thermal tolerance.
XLPE formulations are climbing the fastest as shipyards prioritize power density optimization.
Application:
Naval vessel and offshore platform segments generate premium pricing through specification intensity and certification barriers.
- Naval Vessels:Next-generation warship programs demand integrated power and communication architectures with specialized electromagnetic shielding. Defense agencies in South Korea, Japan, and the United States are accelerating procurement cycles for frigate and destroyer construction.
- Offshore Platforms:North Sea and Gulf of Mexico operators are replacing diesel generator systems with subsea power distribution networks requiring armored cable constructions rated for hydrocarbon exposure and mechanical abrasion.
- Commercial Vessels:Passenger and cargo ships subject to SOLAS fire safety mandates driving low-smoke zero-halogen material transitions.
- Submersibles:Deep-sea exploration and military submarine programs requiring pressure-resistant cable sealing and corrosion protection.
- Research Ships:Scientific vessel fleets with specialized instrumentation and data transmission requirements for oceanographic survey operations.
Naval vessels anchor specification-grade revenue. Offshore platforms are expanding most quickly amid electrification investments.
End User:
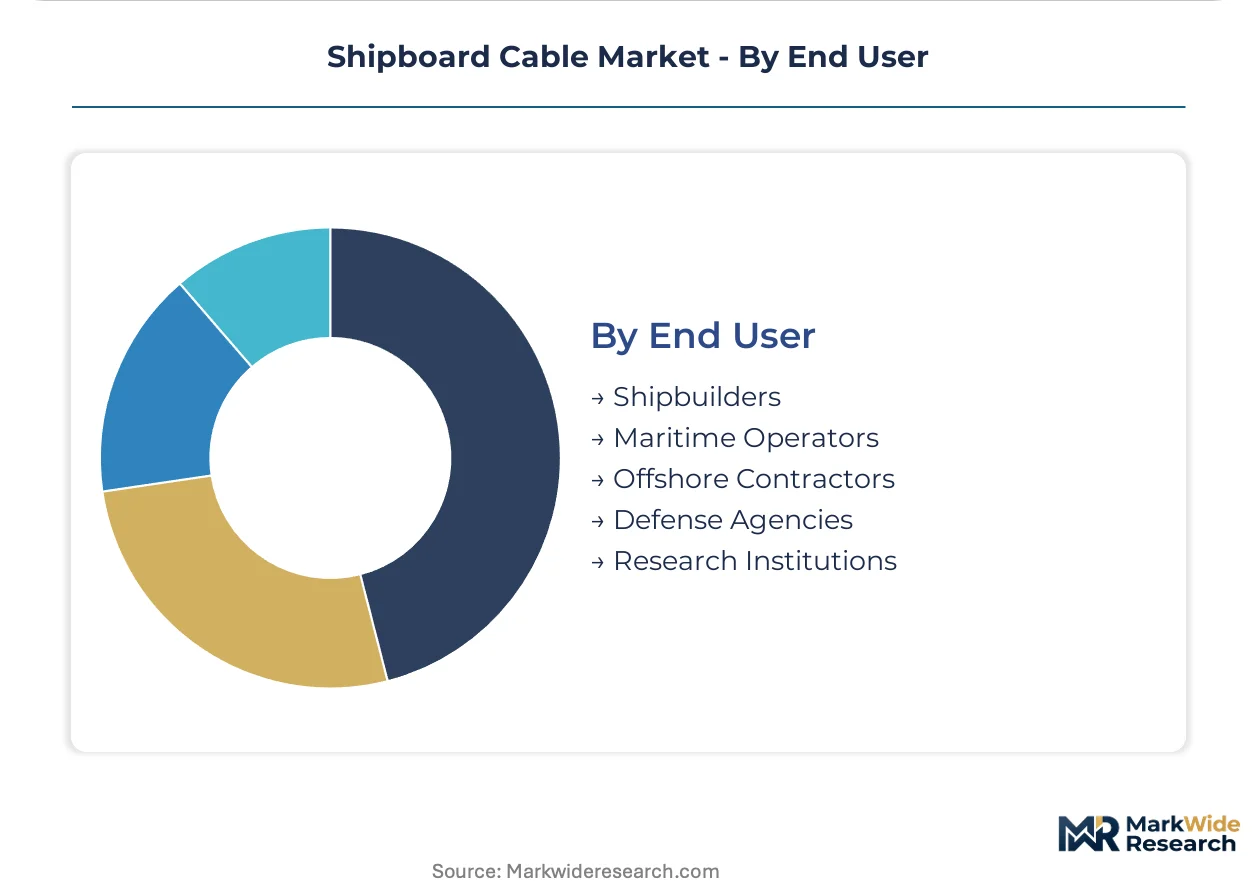
Direct shipyard contracting is consolidating procurement relationships and bypassing traditional distribution channels for high-volume programs.
- Shipbuilders:Hyundai Heavy Industries and Samsung Heavy Industries are executing multi-year framework agreements that capture cable procurement for LNG carrier and container ship construction. These direct relationships reward manufacturers with vertically integrated copper processing and marine-grade insulation compounding.
- Defense Agencies:Naval procurement organizations in South Korea, Japan, and the United States are reorganizing priorities toward integrated power and communication systems with stringent electromagnetic compatibility requirements.
- Maritime Operators:Fleet owners managing SOLAS compliance upgrade cycles for existing passenger and commercial vessels.
- Offshore Contractors:Oilfield service companies specifying armored cables for platform electrification and subsea power distribution.
- Research Institutions:Government and academic oceanographic organizations with specialized requirements for deep-sea exploration vessels.
Shipbuilders dominate volume capture. Defense agencies are rotating up the share rankings through next-generation warship programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean cable exports supply shipyards across East Asia, the Middle East, and Europe as fleet modernization accelerates. Chinese manufacturers capture domestic newbuild demand while penetrating Southeast Asian markets. European suppliers face REACH-mandated compound transitions that elevate production costs against Asian competitors.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries anchor LNG carrier and container ship cable procurement at Ulsan and Geoje shipbuilding complexes. The Korea Register of Shipping enforces enhanced fire-resistance standards for electric propulsion systems. Busan-Ulsan corridor manufacturers leverage captive copper refining and marine-grade insulation compounding to secure multi-year framework agreements.
China
Jiangsu and Zhejiang province cable fabricators supply domestic shipyards building the world's largest commercial vessel output. GB standards administered by SAMR mandate low-smoke halogen-free specifications for passenger vessels under revised maritime safety protocols. Shanghai and Ningbo industrial clusters concentrate production of armored power cables for offshore platform electrification projects.
Japan
Naval shipbuilders at Yokosuka and Kure specify integrated power and communication architectures for next-generation destroyer programs. METI promotes domestic cable manufacturing through procurement preferences for defense applications. Nagoya and Osaka industrial zones maintain EPR insulation expertise for legacy naval programs requiring proven field performance.
Germany
North Sea offshore platform operators replace diesel generators with subsea power distribution networks requiring specialized armored constructions. ECHA REACH restrictions disqualify legacy brominated flame retardants, forcing reformulation investments at cable compounders. Hamburg and Bremen port clusters concentrate maritime engineering procurement for commercial vessel newbuilds and retrofit cycles.
United States
Navy shipyards at Newport News and Bath Iron Works accelerate integrated power system deployments for frigate and destroyer construction. The Coast Guard enforces SOLAS-aligned fire safety protocols for passenger vessel inspections. Gulf of Mexico offshore contractors specify hydrocarbon-resistant cables for platform electrification investments amid subsea power distribution expansion.
Shipboard Cable Market Competitive Landscape
Player mix skews toward integrated cable-electronics conglomerates with captive materials processing and specialized marine engineering units. Market structure concentrates around three to five vertically positioned suppliers controlling compound chemistry, copper processing, and classification society certification relationships. Two strategic archetypes dominate: Asian manufacturers with backward integration into copper refining and marine insulation compounding, and European specialists with halogen-free fire-resistant formulation mastery. Competitive moves center on multi-year shipyard framework agreements and alternative fuel vessel standard development at classification societies.
Among European specialists, Nexans and Prysmian Group exemplify the premium-tier archetype through submarine cable expertise extension into naval shipboard solutions. Sumitomo Electric Industries anchors the Asian integrated model with vertically positioned copper processing and marine-grade insulation capabilities. These three entities occupy positions where electromagnetic shielding engineering and fire-resistance certification timelines determine contract capture in next-generation warship and LNG carrier programs.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| LS Cable and System |
| Sumitomo Electric Industries |
| Furukawa Electric |
| Leoni AG |
| TE Connectivity |
| Eaton Corporation |
| Hengtong Optic-Electric |
| Others |
Pricing and Supply Chain Analysis
IEC 60092 series standards and Lloyd's Register certification requirements gate both supplier qualification timelines and price differentiation simultaneously, compressing margin pools for non-certified manufacturers while rewarding incumbents with established classification society relationships. Korean and Japanese shipyards exploit this dual gating mechanism to extract volume discounts from qualified suppliers.
Pricing Analysis
XLPE-to-EPR-to-PVC generational pricing gaps structure the shipboard cable market, with cross-linked polyethylene formulations commanding 25-35% premiums over ethylene propylene rubber and 60-80% over standard PVC. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and electromagnetic shielding complexity. Cost compression in halogen-free compound tiers is intensifying because REACH-mandated reformulation investments have not yet achieved scale efficiencies. Commercial vessel operators exhibit highest price sensitivity, while naval defense agencies prioritize performance specifications over unit economics.
Supply Chain Analysis
Strategic stockpiling of tinned copper rod and marine-grade insulation compounds dominates inventory strategy among Korean and Japanese manufacturers, insulating against London Metal Exchange volatility. Supply concentrates in South Korea, Japan, and China, with Busan-Ulsan, Nagoya-Osaka, and Shanghai-Ningbo industrial clusters anchoring production. Raw material dependencies draw from Chilean copper concentrate, German halogen-free compound formulations, and domestic silicone rubber processing. Single-source vulnerability in specialized electromagnetic shielding engineering creates qualification bottlenecks. Distribution runs through direct shipyard framework agreements that bypass traditional marine distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless power transmission architectures and integrated optical bus systems threaten incumbent cable suppliers with partial substitution across naval electrification programs. Defense agencies and commercial shipbuilders are evaluating these alternatives for weight reduction and maintenance simplification.
For Market Incumbents: Shield market position by deepening backward integration into captive copper refining and marine-grade insulation compounding to offset halogen-free material cost premiums. Accelerate electromagnetic compatibility engineering talent acquisition to defend against wireless substitution threats in next-generation warship programs. Prioritize multi-year framework agreements with Hyundai Heavy Industries and Samsung Heavy Industries that lock out emerging competitors.
For New Entrants and Emerging Players: Anchor in offshore platform electrification white space, where North Sea and Gulf of Mexico operators demand specialized armored constructions outside established naval supply relationships. Target subsea power distribution cable segments where certification barriers remain lower than combatant vessel specifications. Pursue direct contracting with oilfield service companies rather than competing for shipbuilder framework agreements.
For Investors and Strategic Acquirers: SOLAS fire safety mandate expansion reshapes the acquisition landscape by elevating compound chemistry capabilities above manufacturing scale in valuation frameworks. Long-term viability centers on suppliers with demonstrated halogen-free formulation mastery and classification society pre-approval relationships. Monitor Lloyd's Register and DNV certification pipeline backlogs as inflection indicators for product commercialization velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Classification Society Pre-Approval Investment | Lloyd's Register and DNV pre-certification compresses product commercialization timelines against competitors. |
| Halogen-Free Compound Formulation Partnership | Collaboration with German or Norwegian chemical specialists addresses REACH compliance without captive R&D expenditure. |
| Direct Shipyard Framework Agreement | Hyundai Heavy Industries multi-year contracts bypass distributor margins and lock volume commitments. |
| Electromagnetic Shielding Engineering Acquisition | Specialized talent pools in South Korean defense electronics clusters enable naval combatant cable bundling. |
| Alternative Fuel Vessel Standard Participation | Active role in ammonia and hydrogen propulsion cable rating development at classification societies shapes future specifications. |
Research Methodology
Operator-level perspectives from shipyard procurement directors, cable manufacturing plant managers, classification society surveyors, and naval systems integration engineers anchored the qualitative base. Primary interview insights combined with secondary validation from Lloyd's Register rule filings, DNV certification databases, Korea Register of Shipping technical bulletins, and customs trade records for copper rod and marine cable exports. Bottom-up segment sizing and top-down market triangulation cross-validated volume and value estimates.
Sensitivity analysis across copper price volatility scenarios, certification timeline delays, and alternative fuel vessel adoption curves stress-tested forecast robustness. Segmentation dimensions modeled include insulation technology tier, vessel application type, voltage rating category, and end-user procurement channel. CAGRs derived from historical shipbuilding orderbook analysis and projected fleet electrification investment cycles. Industry-specific inputs incorporated shipyard capacity utilization rates and naval defense budget allocation patterns.
Material uncertainties — copper price spikes exceeding hedging coverage, classification society rule revisions for ammonia propulsion, and wireless power transmission technology maturation — sit outside the modeled envelope. Forecasts reflect assumptions about SOLAS mandate enforcement consistency and shipbuilder consolidation trajectories. Revision becomes warranted when alternative fuel vessel order ratios cross threshold penetration in Korean and Japanese newbuild programs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Solar Cable Market
Cables
Cable Tray Market
Cables
XLPE Cables Market
Cables
Copper Cabling Systems Market
Cables
Cable Management System Market
Cables
Submarine Cabling Systems Market
Cables
Middle East Cable Market
Cables
North America Coaxial Cable Market
Cables
United States Cable Accessories Market
Cables
Network Cable Tester Market
Cables
Cable Testers Market
Cables
Cable Detector Market
Cables
Downhole Cables Market
Cables
Military Fiber Optic Cables Market
Cables
UK Cables Market
Cables
Multicore Cables Market