
 Latin America Connector Market | 2026-2036
Latin America Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Connector Market Insights
Automotive OEMs is unwinding legacy procurement patterns as industrial automation buyers scale connector volumes for smart factory retrofits. TE Connectivity leverages its PCB mount portfolio to dominate Mexico's automotive tier-one supply base. Amphenol Corporation anchors regional RF connector demand through specialized wireless infrastructure partnerships. Molex competes aggressively in wire-to-board configurations serving Brazil's telecommunications expansion.
A connector is an electromechanical device engineered to join electrical terminations for signal or power transmission, typically rated by contact pitch, current-carrying capacity, and insertion cycle durability. Circular connectors lead industrial automation deployments across Latin America due to their IP67 sealing ratings and vibration resistance in harsh environments. Rectangular connectors capture expanding margin pools in data communication applications where high-density pin configurations support server rack consolidation. Fiber optic technology represents the fastest-growing segment as energy management utilities deploy optical links for grid monitoring across remote transmission corridors.
INMETRO in Brazil and NOM standards in Mexico shape product certification requirements for electrical connectors entering regional supply chains. ECHA REACH compliance obligations for contact plating materials directly influence supplier qualification timelines for European-exporting manufacturers. Stakeholders must monitor evolving automotive electrification standards and cross-border tariff structures to align capacity investments with demand migration patterns.
Market Dynamics
Automotive electrification is restructuring connector demand across Latin America as OEMs convert assembly lines from internal combustion to battery-electric architectures, forcing suppliers to retool contact plating specifications and thermal management ratings for high-voltage bus applications.
Growth Catalysts
- INMETRO Certification Mandates:Brazil's tightening electrical safety standards for automotive components are accelerating replacement cycles in aftermarket distribution channels.
- EV Powertrain Assembly:Mexican automotive OEMs are expanding procurement of high-voltage interconnect systems for battery pack and inverter integration.
- Optical Grid Monitoring:Energy utilities across the Andean corridor are deploying fiber optic connectors for real-time transmission line diagnostics in remote terrain.
Market Restraints
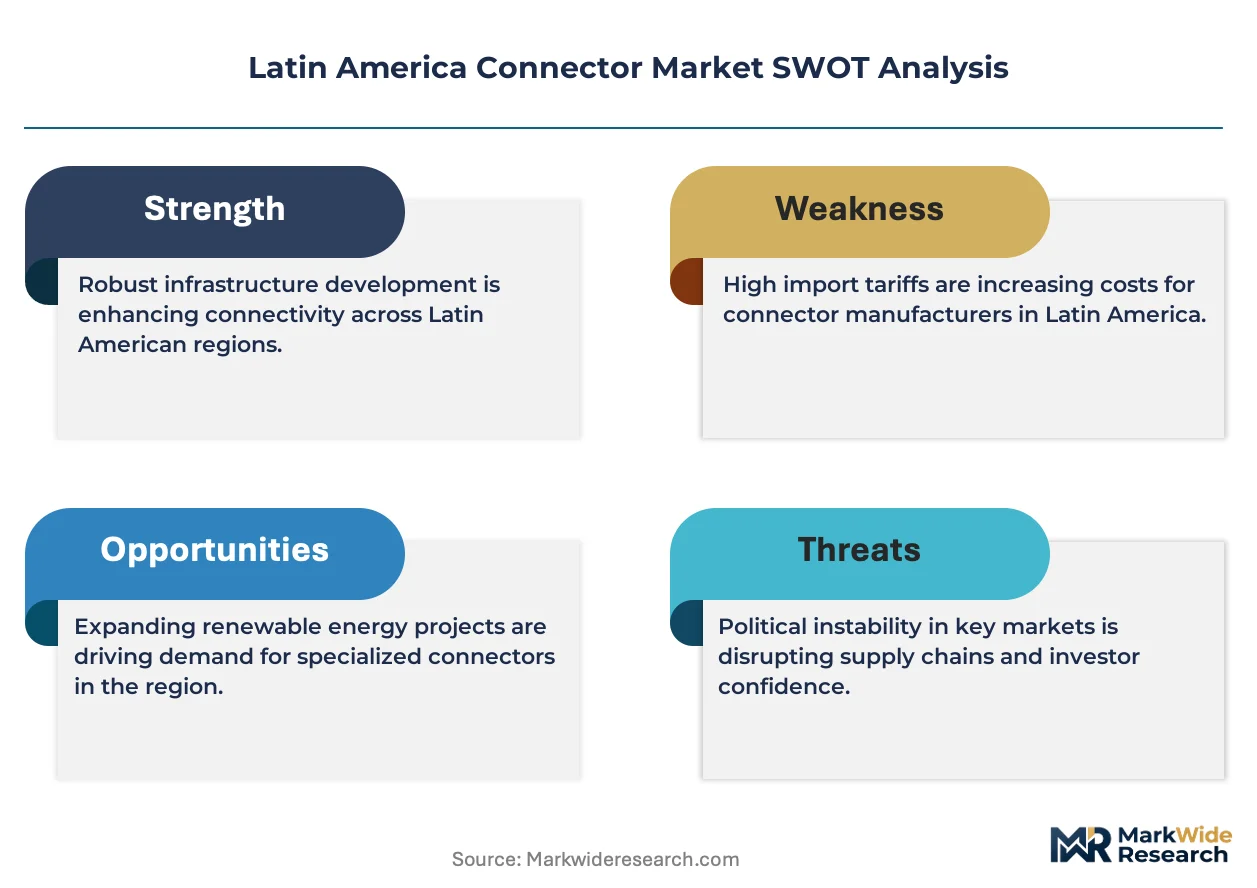
- Copper-Alloy Price Volatility:Contact material input costs fluctuate with London Metal Exchange pricing, compressing margin stability for mid-tier manufacturers.
- Single-Source Concentration:Specialty dielectric compounds for high-temperature automotive applications concentrate among Japanese and German chemical suppliers.
- Legacy Interoperability Barriers:Existing factory automation infrastructure in Brazilian heavy industry relies on proprietary connector footprints that resist standardization.
Strategic Opportunities
- Colombian Renewable Energy:Wind and solar farm construction in the Guajira Peninsula is creating demand for harsh-environment circular connectors with IP6K9K sealing.
- 5G Infrastructure Deployment:Chilean and Argentine telecommunications carriers are scaling RF connector volumes for small cell densification in Santiago and Buenos Aires metropolitan zones.
- Nearshoring Incentives:Mexico's IMMEX program and Brazil's Rota 2030 automotive policy are redirecting connector procurement toward regional manufacturing clusters.
Industry Challenges
- High-Voltage Certification Timelines:NOM electrical safety approvals in Mexico require 14-18 month validation cycles for new automotive connector families.
- Specialized Tooling Capital Requirements:Precision stamping equipment for miniaturized contact pitch configurations demands seven-figure upfront investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Connector Market |
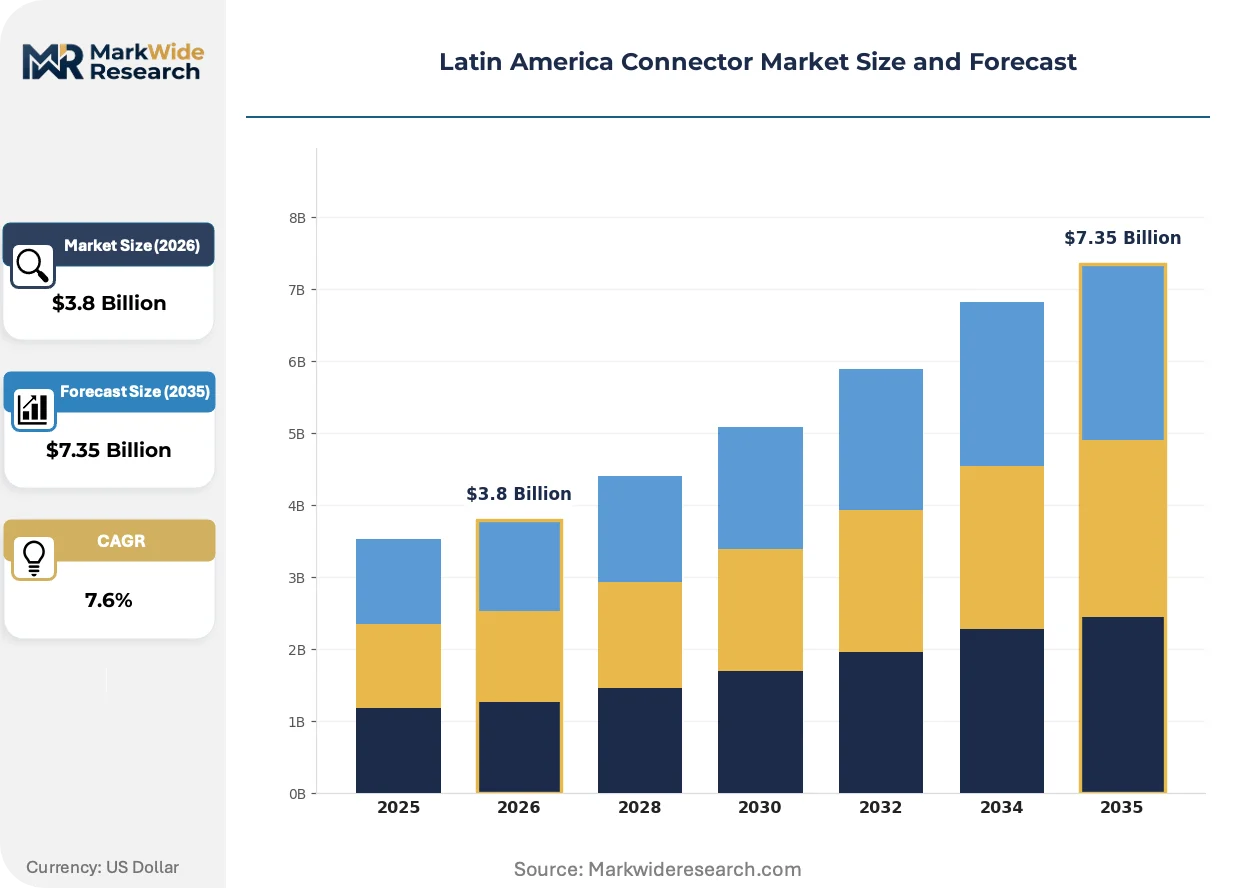
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Terminal Blocks, Circular Connectors, Rectangular Connectors, RF Connectors End User: Automotive OEMs, Telecommunications, Industrial Automation, Consumer Electronics Technology: PCB Mount, Wire-to-Board, Wire-to-Wire, Fiber Optic Application: Transportation, Energy Management, Data Communication, Medical Devices |
| Companies Covered | TE Connectivity, Amphenol Corporation, Molex, Huber+Suhner AG, ITT Inc., Smiths Interconnect, Fischer Connectors SA, Aptiv PLC, Phoenix Contact, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Connector Market Trends and Innovations
Connector architectures across Latin America are bifurcating between legacy industrial specifications and next-generation electrification requirements, with suppliers racing to bridge compatibility gaps without duplicating SKU proliferation.
Miniaturized high-current contact systems are fragmenting traditional connector footprints as automotive OEMs demand 30-50% space reduction for battery management system integration. Tier-one suppliers in Querétaro are adopting 0.64mm terminal systems for power distribution modules. This compression is fragmenting supplier tiers between precision stamping specialists and commodity assembly houses.
NOM standards in Mexico and INMETRO protocols in Brazil are tightening creepage and clearance requirements for high-voltage automotive connectors above 60V DC. Manufacturers must submit accelerated thermal cycling test data under revised protocols. The compliance burden falls heaviest on wire-to-board configurations serving hybrid powertrain applications.
Direct sourcing from connector manufacturers is displacing traditional electronics distributor intermediaries among large automotive OEMs in the Bajío region. Tier-one assemblers now negotiate annual volume agreements for PCB mount and sealed circular families. This channel compression is most pronounced in Guanajuato's powertrain component cluster.
Latin America Connector Market Segmentation
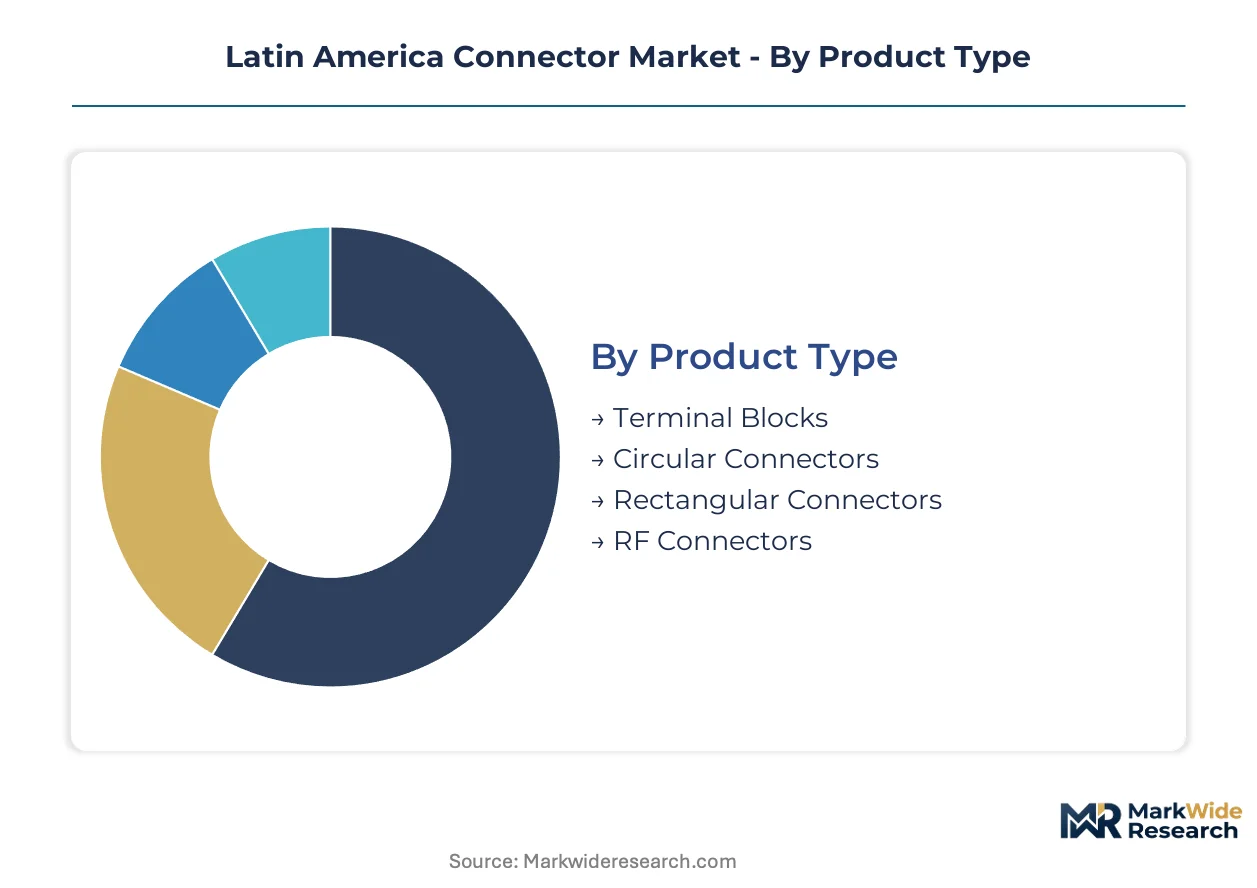
Connector procurement patterns across Latin America fragment sharply across voltage ratings, sealing specifications, and certification requirements. Suppliers must align product portfolios with divergent technical standards spanning Brazilian INMETRO protocols and Mexican NOM electrical safety mandates.
Product Type:
Margin pools concentrate in sealed industrial configurations where IP ratings and vibration resistance command pricing premiums over commodity interconnects.
- Circular Connectors:IP67-rated cylindrical housings with threaded coupling mechanisms withstand dust ingress and high-pressure washdown. Demand clusters in Colombia's Guajira wind farms and Brazilian mining automation where IP6K9K sealing protects against thermal shock and chemical exposure.
- Rectangular Connectors:High-density pin arrays in D-sub and modular formats support rack-mounted server consolidation. Mexican data centers near Querétaro are standardizing on these for power distribution units and signal backplanes in hyperscale facilities.
- Terminal Blocks:Screw-clamp and spring-cage termination systems dominate panel wiring in Brazilian heavy industry retrofits.
- RF Connectors:Coaxial interfaces for sub-6GHz and millimeter-wave frequencies anchor 5G small cell deployments in Santiago and Buenos Aires.
The dominant share belongs to Circular Connectors, while Rectangular Connectors are gaining share fastest in data communication infrastructure.
End User:
Volume concentration tracks automotive electrification investment corridors where OEMs are converting assembly lines to battery-electric architectures.
- Automotive OEMs:High-voltage interconnect systems rated above 60V DC for battery pack, inverter, and charging module integration. Mexican OEMs in Guanajuato's powertrain cluster are procuring sealed circular families for underhood thermal management.
- Industrial Automation:M8 and M12 sensor connectors with PROFINET and EtherCAT compatibility. Brazilian steel and petrochemical plants are retrofitting legacy fieldbus infrastructure with IP67-rated distributed I/O modules.
- Telecommunications:Fiber optic and copper backhaul connectors for 4G/5G radio access network densification.
- Consumer Electronics:Miniaturized board-to-board and wire-to-board configurations for white goods and mobile device manufacturing.
Automotive OEMs command the largest procurement volumes, with Industrial Automation expanding most quickly as smart factory investments accelerate across the region.
Technology:
Application requirements are driving divergence between precision-stamped miniaturized contacts and ruggedized fiber optic terminations.
- PCB Mount:Surface-mount and through-hole headers, receptacles, and card-edge connectors with 0.64mm to 2.54mm pitch ranges. Tier-one suppliers in Querétaro dominate this category for automotive power distribution module integration.
- Fiber Optic:Single-mode and multimode ferrule connectors for SC, LC, and MPO interfaces. Andean energy utilities are deploying these for transmission line monitoring across remote terrain where electromagnetic interference defeats copper solutions.
- Wire-to-Board:Crimp-terminated discrete wire assemblies mating to PCB headers. Brazilian telecommunications expansion drives demand for these in base station power feeds.
- Wire-to-Wire:In-line splices and disconnectable housings for harness branching in transportation applications.
PCB Mount retains the largest installed base, though Fiber Optic shows the steepest expansion trajectory as grid modernization investments multiply.
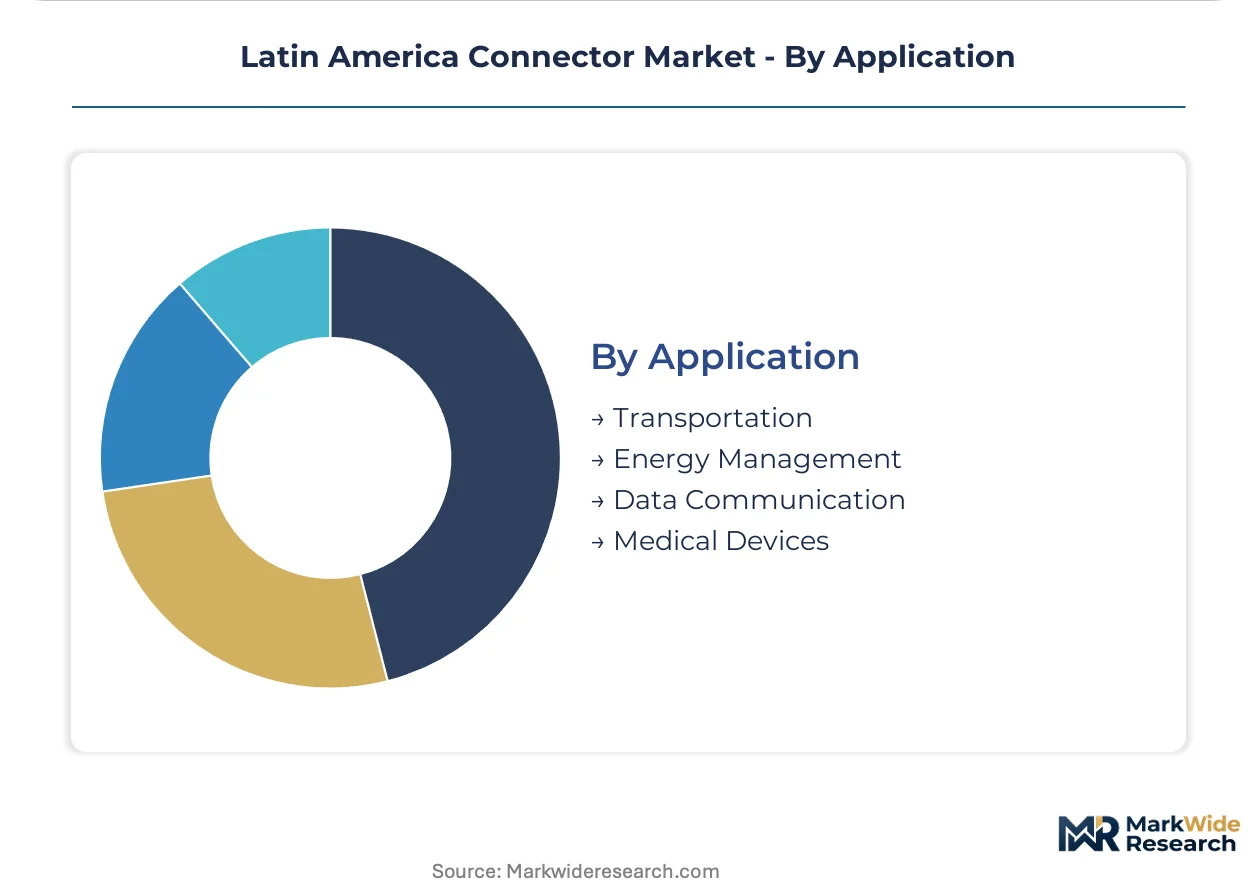
Application:
Certification complexity varies sharply across sectors, with medical and automotive applications imposing the longest validation timelines.
- Transportation:Sealed circular and rectangular connectors for commercial vehicle, rail, and electric powertrain systems. Mexican IMMEX program incentives are concentrating procurement in Bajío region manufacturing clusters.
- Energy Management:High-voltage interconnects and fiber optic links for substation automation and renewable generation. Colombian solar farm construction is driving demand for harsh-environment circular connectors with extended temperature ratings.
- Data Communication:Backplane, mezzanine, and I/O connectors for server, storage, and networking equipment.
- Medical Devices:Sterilizable disposable and reusable connectors for diagnostic and therapeutic equipment. ANVISA registration requirements in Brazil extend supplier qualification cycles.
Transportation applications generate the highest absolute volumes, while Energy Management is climbing the fastest on renewable infrastructure buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico exports connector-intensive automotive assemblies to North American OEMs, while Brazil feeds regional aftermarket distribution networks across Mercosur. Trade corridors concentrate procurement in manufacturing clusters near certification authorities.
Brazil
Automotive electrification and mining automation drive connector demand in São Paulo and Minas Gerais. INMETRO certification mandates for electrical safety components extend supplier qualification timelines to 18 months. The São Paulo industrial corridor hosts stamped-contact manufacturers serving heavy equipment OEMs.
Mexico
EV powertrain assembly and 5G infrastructure deployment accelerate procurement in Guanajuato and Querétaro. NOM electrical safety standards require accelerated thermal cycling validation for high-voltage automotive connectors. The Bajío region concentrates tier-one connector consumption for battery pack integration.
Argentina
Telecommunications expansion and agricultural machinery modernization sustain demand in Buenos Aires and Córdoba. The national communications regulator imposes electromagnetic compatibility testing for RF connector deployments. Buenos Aires anchors 5G small cell densification projects requiring sub-6GHz coaxial interfaces.
Chile
Renewable energy transmission and data center construction propel fiber optic and high-voltage interconnect demand. The Ministry of Energy mandates grid monitoring standards that favor optical connectors in remote Andean corridors. Santiago's metropolitan zone concentrates hyperscale facility builds requiring rectangular power distribution connectors.
Colombia
Wind farm construction in the Guajira Peninsula and solar installations in the Andean foothills create demand for harsh-environment sealing. The national mining and energy planning unit specifies IP6K9K-rated circular connectors for coastal renewable sites. Bogotá-based distributors coordinate procurement for utility-scale generation projects.
Latin America Connector Market Competitive Landscape
Player mix skews toward diversified electromechanical conglomerates with established certification expertise. Market structure concentrates among three global suppliers controlling automotive tier-one relationships. Two strategic archetypes dominate: precision stamping specialists serving miniaturized automotive specifications, and sealed industrial specialists capturing renewable energy and mining applications. Competitive moves center on direct OEM contracting to displace distributor intermediaries, and regional certification pre-qualification to accelerate NOM and INMETRO approval cycles.
Among Switzerland-based specialists, Huber+Suhner AG occupies a position exemplifying RF and fiber optic expertise for telecommunications infrastructure. Fischer Connectors SA represents the sealed industrial archetype with cylindrical housing configurations. TE Connectivity anchors the diversified conglomerate tier with broad PCB mount and automotive portfolios. These three entities exemplify how geographic origin and naming conventions signal strategic positioning without requiring specific product claims.
| Leading Market Players |
|---|
| TE Connectivity |
| Amphenol Corporation |
| Molex |
| Huber+Suhner AG |
| ITT Inc. |
| Smiths Interconnect |
| Fischer Connectors SA |
| Aptiv PLC |
| Phoenix Contact |
| Others |
Pricing and Supply Chain Analysis
Copper-alloy substitution in contact plating systems simultaneously redraws raw material sourcing maps across Chile and Peru and compresses margin structures for mid-tier stamping houses serving Brazilian automotive OEMs. This input transition forces suppliers to rebalance between London Metal Exchange exposure and long-term offtake contracts with Andean mining consortiums.
Pricing Analysis
Current-generation high-voltage automotive connectors command substantial premiums over legacy 12V architectures and prior-generation industrial circular formats. Three-tier pricing structure across INMETRO-certified premium, NOM-standard mid-grade, and uncertified economy levels segments the market. Cost compression in wire-to-board configurations is intensifying because Brazilian telecommunications carriers are consolidating procurement volumes. Automotive OEMs in Guanajuato exhibit the lowest price sensitivity due to electrification mandates, while aftermarket distributors in São Paulo remain highly cost-conscious.
Supply Chain Analysis
Inventory cycles for specialty dielectric compounds now stretch 16-20 weeks, exposing Mexican tier-one assemblers to production line stoppages. Manufacturing concentrates in China, Germany, and Japan for precision stamping equipment and high-temperature polymer feedstocks. Supply chains rest on beryllium copper strip, liquid crystal polymer resin, and gold-palladium plating salts. Single-source vulnerability in Japanese chemical suppliers for automotive-grade dielectrics threatens regional capacity expansion timelines. Distribution runs through direct OEM contracting that displaces traditional electronics distributor networks in the Bajío region.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified high-voltage interconnect engineering talent pools remain critically thin across Latin America, constraining how quickly suppliers can scale NOM and INMETRO approval capacities for EV powertrain programs.
For Market Incumbents: Fortify certification pre-qualification capabilities to compress 14-18 month NOM validation cycles for new automotive connector families. Deepen backward integration into precision stamping operations near Querétaro to offset copper-alloy price volatility. Channel control through direct OEM annual volume agreements protects margin pools against distributor disintermediation threats from TE Connectivity and Amphenol. For New Entrants and Emerging Players: Differentiate on IP6K9K sealing expertise for Colombian wind farm and solar installations where harsh-environment specifications outstrip incumbent portfolio breadth. Target Colombian renewable energy procurement as the most penetrable geography given infrastructure buildout timelines and limited local supplier presence. Pursue utility-scale EPC partnerships as the primary go-to-market angle rather than automotive tier-one qualification. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision stamping specialists in São Paulo and Monterrey holding automotive certification relationships but lacking fiber optic technology portfolios. Long-term viability hinges on bridging legacy industrial connector capabilities with electrification-ready high-voltage architectures. Watch INMETRO protocol revisions for high-voltage creepage and clearance requirements as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| INMETRO Certification Pre-Qualification | Accelerates 18-month Brazilian electrical safety approval timelines for automotive connector families. |
| Direct OEM Contracting Expansion | Displaces distributor intermediaries in Guanajuato powertrain clusters for PCB mount and sealed circular volumes. |
| Colombian Renewable Energy Partnership | Captures IP6K9K circular connector demand from Guajira wind farm and Andean solar construction projects. |
| Copper-Alloy Backward Integration | Reduces London Metal Exchange price exposure for mid-tier Brazilian stamping operations. |
| Fiber Optic Capability Acquisition | Addresses Andean utility grid monitoring demand where electromagnetic interference defeats copper solutions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade databases, SEC 10-K filings, and INMETRO certification registries to establish baseline market sizing. Primary interviews engaged tier-one automotive procurement directors, connector manufacturer plant managers in Querétaro and São Paulo, and utility grid engineering leads across the Andean corridor. Bottom-up triangulation of SKU-level shipment data with top-down macroeconomic indicators validates volume estimates.
Segmentation dimensions modeled span product type, end user industry, mounting technology, and application sector across the projection horizon. CAGRs derive from regression analysis of historical procurement patterns against electrification investment trajectories and renewable infrastructure buildout schedules. Industry-specific inputs include vehicle production forecasts from IHS Markit registration data and utility transmission line investment disclosures from Colombian and Chilean energy ministries.
Material uncertainties — copper-alloy price volatility, NOM protocol revision timing, and nearshoring policy shifts — sit outside the modeled envelope. Forecasts reflect assumptions regarding certification timeline stability and OEM electrification commitment durability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Middle East Connector Market
Connectors
SATA Connector Market
Connectors
DIN Connectors Market
Connectors
Telecom Mounting Hardware Market
Connectors
Connector and Terminal Systems for Harsh Environment Wiring Market
Connectors
Filtered Connectors Market
Connectors
Circular Waterproof Connector Market
Connectors
Liquid Cooling Connector Market
Connectors
Middle East and Africa Hazardous Location Connectors Market
Connectors
LCP Connectors Market
Connectors
Micro-Miniature Co-Axial Adapter Market
Connectors
Relay Sockets Market
Connectors
China Connector Market
Connectors
Press Fit Connector Market
Connectors
India Connector Market
Connectors
Mexico Connector Market