
 Unit Dose Manufacturing Market | 2026-2036
Unit Dose Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Unit Dose Manufacturing Market Intelligence
Single-dose sterile specification upgrades is unwinding legacy multi-dose formats across oncology and biologics packaging. Gerresheimer AG leverages its glass and polymer platform to dominate high-barrier vial production for sensitive injectables. Catalent, Inc. anchors North American capacity through integrated clinical-to-commercial fill-finish services. Lonza Group Ltd. extends its position via specialized containment technologies for potent compounds.
Unit dose manufacturing produces individually packaged pharmaceutical doses in ready-to-administer formats such as prefilled syringes with specified fill volumes and barrier-coated blister packs. This format eliminates in-hospital repackaging, reduces contamination risk, and enables precise tracking through serialized primary packaging. Injectable delivery mode commands premium positioning due to cold-chain requirements and aseptic processing complexity. Specialty medications application segments attract outsized investment as patient-specific dosing and limited-distribution networks reshape fulfillment models. Oral unit dose retains volume leadership in generic drugs where cost-efficient blister automation sustains margin pools.
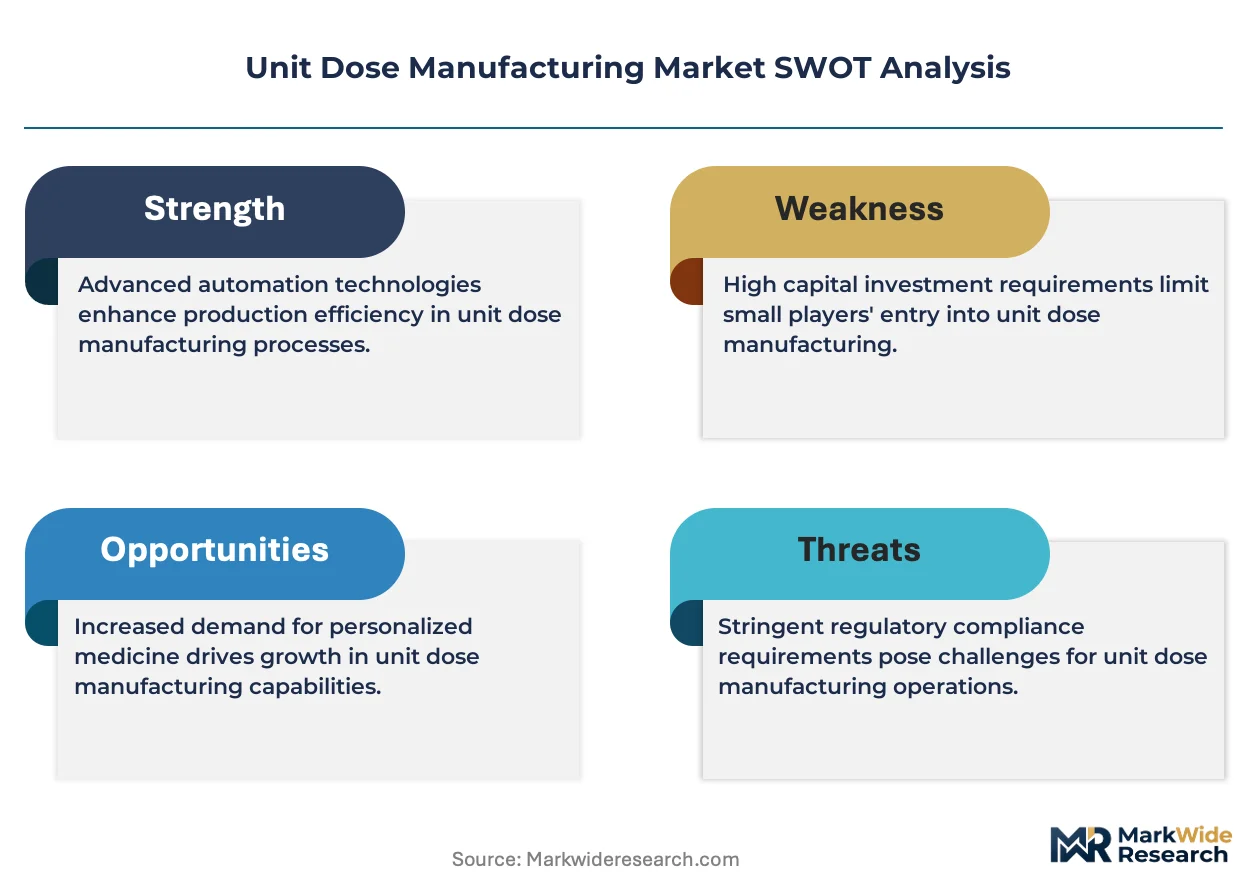
FDA serialization mandates under the Drug Supply Chain Security Act and EU FMD traceability requirements compel packaging line retrofits and data infrastructure spending. The US national pharmaceutical regulator enforces cGMP standards for aseptic processing that filter market access to validated manufacturers. Stakeholders must weigh captive unit dose investments against contract manufacturing partnerships as regulatory complexity and product mix fragmentation intensify.
Market Dynamics
Serialization mandates under the Drug Supply Chain Security Act are forcing pharmaceutical packaging lines into expensive retrofit cycles while hospital pharmacies simultaneously abandon bulk repackaging for pre-verified unit dose formats.
Growth Catalysts
- FDA DSCSA compliance deadlines:Track-and-trace requirements are compelling manufacturers to deploy serialized primary packaging, expanding demand for integrated fill-finish and labeling infrastructure.
- Oncology biologics expansion:Patient-specific dosing regimens for monoclonal antibodies and cell therapies require flexible batch sizes that only unit dose lines can accommodate efficiently.
- Germany's pharmaceutical packaging cluster:Concentrated glass and polymer expertise around Mainz and Müllheim anchors European supply security for high-barrier vials and prefilled syringes.
Market Restraints
- Specialized polymer resin shortages:Cyclic olefin polymers and multilayer barrier films face supply tightness from limited chemical plant capacity in Belgium and the Netherlands.
- Aseptic validation timelines:FDA cGMP facility inspections for sterile processing create 18-24 month approval bottlenecks that freeze capacity expansion decisions.
- Lyophilized format competition:Freeze-dried bulk packaging retains cost advantages for stable biologics, constraining unit dose penetration in non-injectable categories.
Strategic Opportunities
- India's contract manufacturing expansion:CDSCO regulatory alignment with ICH standards is enabling Indian facilities to capture EU and US-bound unit dose outsourcing.
- Prefilled auto-injector convergence:Combination product regulations are creating integrated device-drug opportunities for rheumatology and endocrinology applications.
- EU FMD repository data monetization:Serialized pack-level traceability infrastructure enables anti-counterfeiting analytics and patient adherence services as secondary revenue streams.
Industry Challenges
- Aseptic processing technician scarcity:Qualified personnel for isolator operations and environmental monitoring command 40% wage premiums, constraining line utilization rates.
- Legacy ERP integration with serialization:Brownfield packaging sites face data architecture fragmentation when connecting line-level equipment to enterprise traceability systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unit Dose Manufacturing Market |
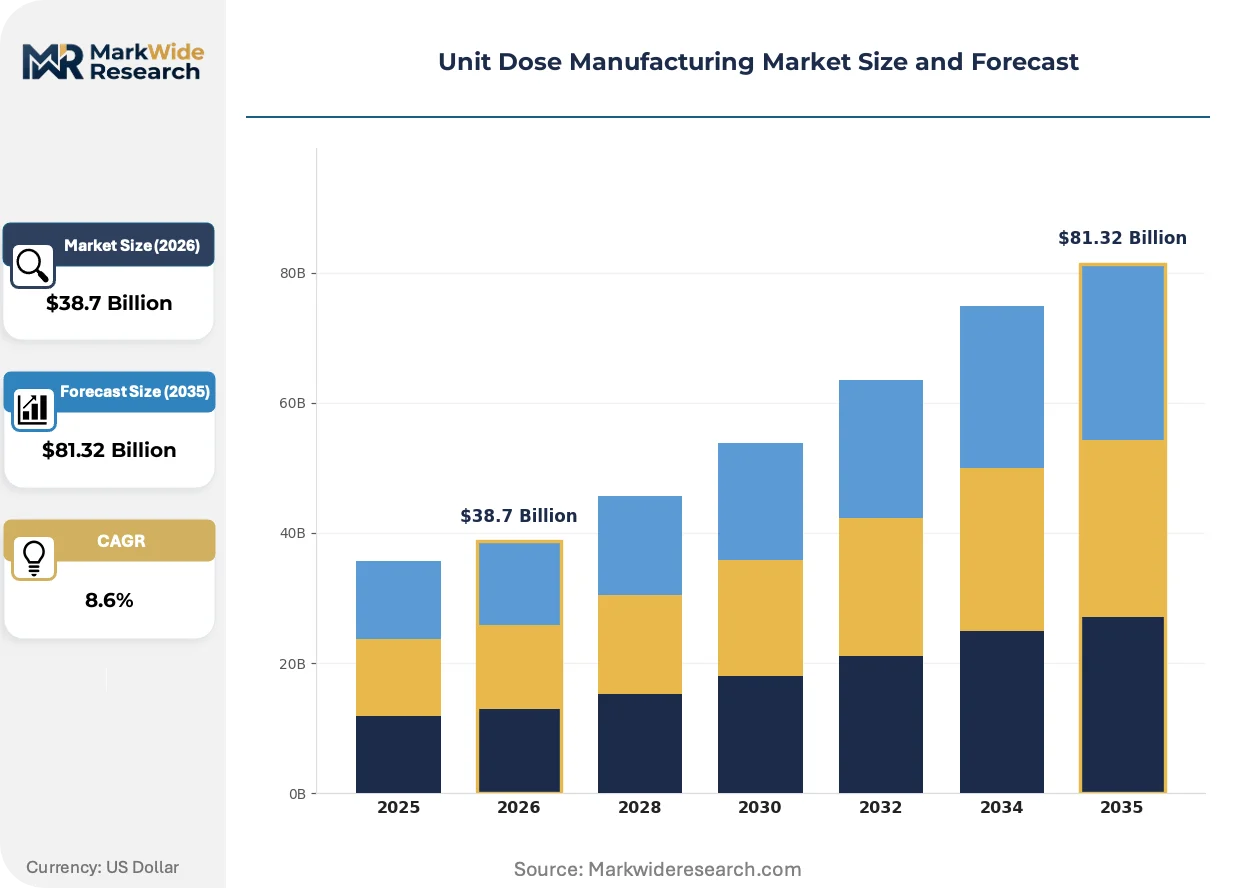
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pills, Capsules, Syringes, Vials Application: Pharmaceutical, Biologics, Generic Drugs, Specialty Medications Delivery Mode: Oral, Injectable, Transdermal, Inhalation End User: Hospitals, Pharmacies, Long-term Care Facilities, Home Care Providers |
| Companies Covered | Gerresheimer AG, Schott AG, Catalent, Inc., Lonza Group Ltd., Amcor plc, West Pharmaceutical Services, Inc., Stevanato Group, PCI Pharmaceutical Services, Inc., Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unit Dose Manufacturing Market Strategic Shifts & Innovations
Packaging automation is converging with digital health infrastructure to create dose-level data ecosystems that extend beyond manufacturing into patient adherence monitoring and pharmacovigilance signal detection.
Barrier-coated polymer blister films are displacing aluminum cold-form laminates in oral solid dose packaging. Generic manufacturers in Eastern Europe are adopting these materials to reduce line changeover times. The technology is miniaturizing packaging footprints while maintaining 24-month stability data for moisture-sensitive compounds.
EU FMD delegated regulation on safety features is mandating unique identifier verification at pharmacy dispensing points. This compels manufacturers to upgrade aggregation capabilities from case to pallet level. Oncology and orphan drug portfolios face the steepest compliance cost burdens due to low-volume, high-SKU complexity.
Hospital procurement consortia are consolidating supplier panels for prefilled syringes and demanding outcome guarantees on medication error reduction. Integrated delivery networks in the United States are replacing fragmented distributor relationships with direct manufacturer contracts that bundle packaging, logistics, and data services.
Unit Dose Manufacturing Market Segmentation
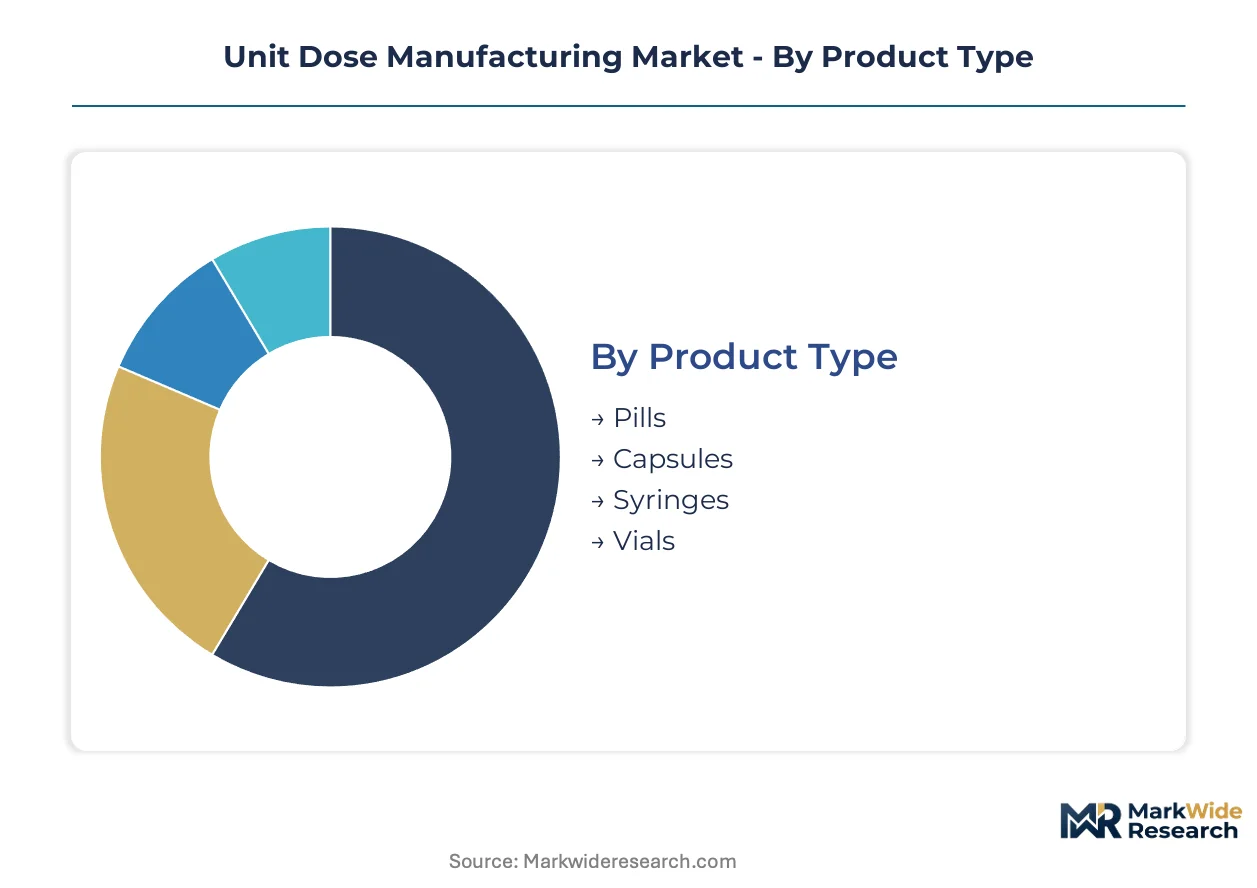
Unit dose manufacturing segments reflect divergent regulatory burdens and automation requirements across delivery formats. Product type and application splits determine capital intensity and margin structures for packaging line investments.
Product Type:
Domestic hospital demand concentrates in syringes and vials for immediate-use sterile applications, while pill and capsule formats serve export-oriented generic supply chains.
- Syringes:Prefilled glass and polymer syringes require validated aseptic fill-finish lines with isolator technology. Demand clusters in Germany and the United States where hospital consortia mandate ready-to-administer injectables for oncology and emergency medicine.
- Vials:Single-dose glass vials with elastomeric closures dominate biologics packaging for monoclonal antibodies. High-barrier specifications from Schott and Gerresheimer anchor European supply security for temperature-sensitive compounds.
- Pills:Blister-packed oral solids serve high-volume generic distribution with cost-efficient thermoforming automation.
- Capsules:Hard gelatin and HPMC capsules occupy specialty nutritional and delayed-release pharmaceutical applications.
Syringes hold the largest share; momentum sits with vials as biologics portfolios expand.
Application:
Cost tier stratification separates premium biologics infrastructure from commoditized generic packaging lines.
- Biologics:Cell therapies and monoclonal antibodies require cold-chain unit dose formats with serialized aggregation to pallet level. FDA DSCSA compliance deadlines are accelerating infrastructure spending for track-and-trace capabilities.
- Specialty Medications:Limited-distribution networks for orphan drugs demand flexible batch sizes and patient-specific labeling. Lonza and Catalent anchor North American and European capacity for potent compound containment.
- Pharmaceutical:Conventional small-molecule drugs sustain volume leadership in oral unit dose blister automation.
- Generic Drugs:Eastern European manufacturers drive adoption of barrier-coated polymer films to reduce aluminum cold-form laminate dependency.
Pharmaceutical commands current volume; biologics represents the fastest-growing trajectory as patient-specific dosing reshapes fulfillment models.
Delivery Mode:
Volume concentration favors oral formats while margin pools concentrate in injectable cold-chain infrastructure.
- Injectable:Prefilled syringes and vials command premium positioning due to aseptic processing complexity and validated cold-chain requirements. Germany's Mainz-Müllheim packaging cluster anchors European supply for high-barrier glass and polymer platforms.
- Oral:Blister-packed tablets and capsules retain volume leadership through automated thermoforming lines serving generic drug distribution.
- Transdermal:Adhesive patch technologies occupy pain management and hormone replacement niches with specialized lamination equipment.
- Inhalation:Unit dose dry powder and metered-dose formats serve respiratory therapy with precise dose uniformity requirements.
Oral formats dominate unit volume; injectable delivery is expanding most quickly as hospital pharmacies abandon bulk repackaging.
End User:
Customer type determines serialization complexity and outcome-based contracting terms.
- Hospitals:Integrated delivery networks in the United States are consolidating supplier panels for prefilled syringes and demanding medication error reduction guarantees. EU FMD repository verification at dispensing points compels aggregation upgrades from case to pallet level.
- Long-term Care Facilities:Medication adherence packaging with calendarized blister cards drives demand for compliance-prompting formats in geriatric care.
- Pharmacies:Community and hospital pharmacy procurement consortia are replacing fragmented distributor relationships with direct manufacturer contracts bundling packaging and data services.
- Home Care Providers:Self-administration trends favor prefilled auto-injectors for rheumatology and endocrinology applications under combination product regulations.
Hospitals represent the largest installed base; home care providers are gaining share fastest as patient-administered biologics expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor established manufacturing clusters over emerging capacity, with specialized polymer resin dependencies creating trade vulnerabilities for packaging-dependent markets. Germany and the United States maintain structural trade surpluses in high-barrier primary packaging, while India and China expand contract manufacturing exports under regulatory convergence programs.
United States
Hospital consortia procurement consolidation drives prefilled syringe demand for oncology and emergency medicine applications. FDA DSCSA serialization deadlines compel packaging line retrofits and enterprise data infrastructure spending. The Boston-Cambridge biologics corridor anchors North American fill-finish capacity for monoclonal antibodies.
Germany
High-barrier glass and polymer expertise concentrates around Mainz and Müllheim for temperature-sensitive injectables. EU FMD delegated regulation mandates unique identifier verification systems at pharmacy dispensing points. Gerresheimer and Schott anchor European supply security for serialized primary packaging.
India
CDSCO regulatory alignment with ICH standards enables contract manufacturing organizations to capture EU and US-bound unit dose outsourcing. Domestic hospital pharmacy automation expands to reduce medication errors in tertiary care networks. The Hyderabad-Bengaluru pharmaceutical corridor scales barrier-coated blister film production for generic export markets.
Switzerland
Specialty medications and orphan drug packaging demand flexible batch sizes from validated containment facilities. Swissmedic enforces stringent aseptic processing standards that filter market access to qualified manufacturers. The Basel biotech cluster integrates fill-finish operations with limited-distribution network logistics.
China
NMPA serialization requirements accelerate domestic packaging line upgrades for track-and-trace compliance. Self-administered biologics expansion drives prefilled auto-injector demand in rheumatology and endocrinology. The Yangtze River Delta concentrates polymer syringe molding capacity for regional hospital supply.
Unit Dose Manufacturing Market Key Industry Players
Concentration sits with integrated packaging specialists that combine glass and polymer platforms with validated aseptic processing capabilities. The vendor base separates into three functional tiers: full-service fill-finish integrators, specialized primary packaging material suppliers, and regional contract manufacturing organizations. Strategic moves center on captive polymer resin supply security and serialization data infrastructure partnerships.
Within the integrated packaging tier, Gerresheimer AG and Schott AG exemplify European material science dominance in high-barrier vial production. Catalent, Inc. occupies a position representing North American clinical-to-commercial fill-finish integration. Lonza Group Ltd. anchors specialized containment capabilities for potent compound handling.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Schott AG |
| Catalent, Inc. |
| Lonza Group Ltd. |
| Amcor plc |
| West Pharmaceutical Services, Inc. |
| Stevanato Group |
| PCI Pharmaceutical Services, Inc. |
| Thermo Fisher Scientific Inc. |
| Others |
Cost & Logistics Intelligence
FDA cGMP certification for aseptic processing gates both supplier qualification and price tier separation in unit dose manufacturing, compelling buyers to pay premiums for validated fill-finish capacity while excluding uncertified competitors from tender participation. Hospital procurement consortia leverage this regulatory filter to consolidate supplier panels, extracting outcome guarantees on medication error reduction alongside volume commitments.
Pricing Analysis
Hospital pharmacy buyers anchor a three-tier pricing structure across premium, standard, and economy levels in unit dose manufacturing. Price differentiation stems from aseptic validation status and cold-chain infrastructure certification, with FDA-inspected facilities commanding substantial premiums over CDSCO-aligned Indian contract manufacturers. Cost compression in oral blister formats is intensifying because Eastern European generic producers are adopting barrier-coated polymer films to displace aluminum laminates. Generic drug distributors exhibit highest price sensitivity, while biologics sponsors prioritize supply security over unit cost.
Supply Chain Analysis
Extended lead times for cyclic olefin polymers and multilayer barrier films signal inventory stress across European packaging lines. Supply concentrates in Germany, the United States, and India, with high-barrier glass and polymer expertise clustering around Mainz-Müllheim, the Boston-Cambridge corridor, and the Hyderabad-Bengaluru pharmaceutical belt. Raw material dependencies center on elastomeric closures, barrier-coated films, and pharmaceutical-grade glass tubing. Single-source vulnerability for specialized polymer resins from Belgium and the Netherlands creates structural exposure. Distribution runs through direct manufacturer contracts with integrated delivery networks, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Serialization infrastructure is transforming unit dose manufacturing into a platform-economics arena where data interoperability between packaging lines and pharmacy dispensing systems determines competitive viability. EU FMD repository integration with hospital ERP systems exemplifies this ecosystem shift, enabling secondary revenue streams from adherence analytics.
For Market Incumbents: Fortify polymer resin supply security through backward integration into cyclic olefin polymer production or long-term offtake agreements with Belgian and Dutch chemical plants. Incumbent packaging specialists face margin pressure from Indian contract manufacturers capturing EU and US-bound outsourcing; defend position by accelerating aggregation capability upgrades from case to pallet level ahead of compliance deadlines.
For New Entrants and Emerging Players: Lead with prefilled auto-injector convergence for self-administered biologics in rheumatology and endocrinology, where combination product regulations create regulatory moats against commodity syringe producers. The home care provider segment offers the most penetrable white space as patient-administered therapies expand. A go-to-market angle bundling device-drug integration with adherence monitoring software captures differentiated positioning.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biologics fill-finish capacity as isolator technology and serialized aggregation infrastructure become table stakes. Long-term viability over the next decade rests on regulatory convergence enabling cross-border outsourcing rather than geographic fragmentation. Target acquisition profiles emphasize validated aseptic processing facilities with existing FDA or EMA inspection history. The signal to watch is CDSCO-EU mutual recognition agreement progress as an inflection indicator for Indian contract manufacturing access.
| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Infrastructure Deployment | FDA DSCSA compliance deadlines compel packaging line retrofits and enterprise data architecture spending. |
| Backward Integration into Polymer Resins | Cyclic olefin polymer supply tightness from Belgium and Netherlands drives captive sourcing strategies. |
| Prefilled Auto-Injector Development | Combination product regulations for rheumatology and endocrinology create integrated device-drug opportunities. |
| EU FMD Repository Data Monetization | Serialized pack-level traceability enables anti-counterfeiting analytics and patient adherence services revenue. |
| Indian Contract Manufacturing Scale-Up | CDSCO regulatory alignment with ICH standards unlocks EU and US-bound unit dose outsourcing capture. |
Research Approach
A spread of perspectives from fill-finish operations directors, regulatory affairs leads at packaging specialists, hospital pharmacy procurement managers, and CDSCO inspection officers converged on the working assumptions shaping this analysis. Primary interviews combined with secondary validation against FDA warning letters, EMA inspection reports, EU FMD delegated regulation texts, and pharmaceutical packaging trade data. Bottom-up capacity modeling and top-down demand triangulation anchored market sizing.
Segmentation dimensions modeled include delivery mode, product type, application category, and regional regulatory cluster across the projection horizon. CAGRs derived from capacity expansion pipelines, regulatory compliance spending trajectories, and biologics portfolio growth rates. Industry-specific forecast inputs incorporated aseptic validation timelines and serialization infrastructure deployment curves.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of DSCSA and FMD deadlines, or abrupt shifts in polymer resin trade flows, would require recalibration. Forecasts reflect documented assumptions regarding hospital pharmacy automation adoption and CDSCO-EU regulatory convergence progress. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Saudi Arabia Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Pharmaceutical Wholesale & Distribution Market
Pharmaceuticals
Global Alpha-Blocker Market
Pharmaceuticals
Injectable Ketamine Market
Pharmaceuticals
Dopamine and Norepinephrine Reuptake Inhibitor Market
Pharmaceuticals
Global Anticoccidial Drugs Market
Pharmaceuticals
China Plasma Protein Therapeutics Market
Pharmaceuticals
Iceland Pharmaceutical Market
Pharmaceuticals
Latin America Pharmaceutical Contract Manufacturing Organization Market
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
Global Finasteride Market
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
United States Insulin Drugs and Delivery Devices Market
Pharmaceuticals
PD-1/PD-L1 Inhibitor Market
Pharmaceuticals
Antibiotic-Associated Diarrhea Treatment Market
Pharmaceuticals
Prothrombin Complex Concentrate (PCC) Market