
 Global Alpha-Blocker Market | 2026-2036
Global Alpha-Blocker Market Size, Share, and Industry Trends Forecast 2026-2036
Global Alpha-Blocker Market Foresight
Buyer concentration among hospital procurement consortia is realigning contract structures for alpha-blocker portfolios. Pfizer Inc. leverages its cardiovascular heritage to sustain institutional formulary presence across North American health systems. Novartis AG anchors its urology franchise through specialty distribution channels in European markets. Merck & Co., Inc. competes on manufacturing scale for oral doxazosin supply to ambulatory surgical networks.
Alpha-blockers constitute a pharmacological class of selective and non-selective antagonists targeting alpha-1 adrenergic receptors, with tamsulosin demonstrating 10-fold selectivity for prostate-specific receptor subtypes to reduce urethral resistance without significant blood pressure effects. These agents serve primary therapeutic roles in lower urinary tract symptom management and essential hypertension control. Tamsulosin dominates current prescription volumes within the product type dimension due to its uroselectivity profile and once-daily dosing convenience. The benign prostatic hyperplasia therapy area generates the deepest margin pools as aging demographics sustain chronic treatment protocols across hospital and specialty clinic end users. Oral administration routes maintain overwhelming preference share, though transdermal delivery formats attract development interest for hypertensive populations with polypharmacy adherence challenges.
The FDA's bioequivalence standards for generic alpha-blockers govern ANDA approval timelines and interchangeability designations that directly shape competitive access. EMA's centralized marketing authorization procedures coordinate pharmacovigilance requirements across EU member states, while India's CDSCO regulates import and local manufacturing licensure for urological active pharmaceutical ingredients. China's NMPA implements domestic clinical trial requirements that condition market entry for foreign-sourced tamsulosin formulations. Stakeholders must monitor evolving pharmacovigilance mandates and regional bioequivalence study protocols to optimize regulatory investment sequencing across manufacturing and commercial footprints.
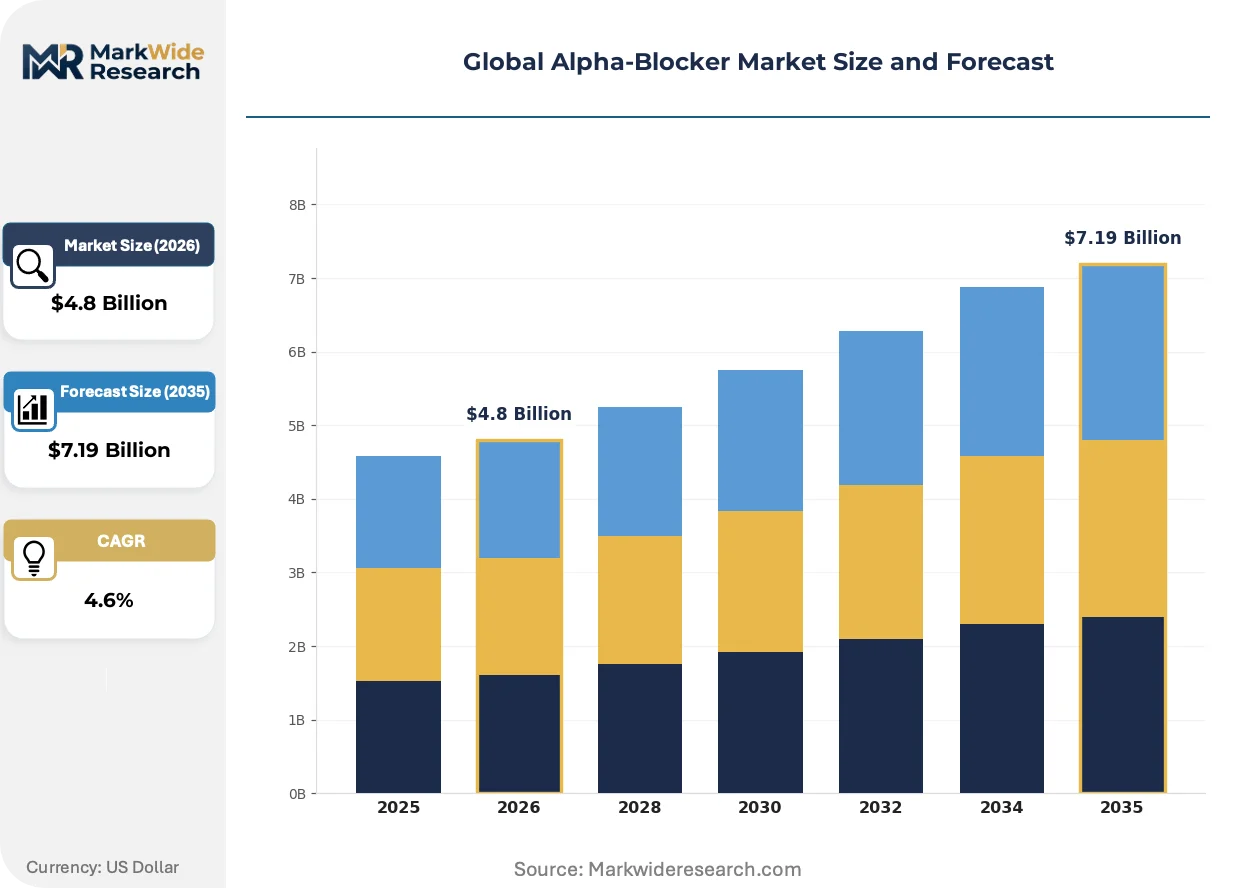
Market Dynamics
Generic tamsulosin formulations are compressing margin structures across oral alpha-blocker portfolios, while hospital procurement consortia in Germany, the United States, and India consolidate purchasing power into multi-year sole-source agreements.
Growth Catalysts
- FDA ANDA Streamlining:Accelerated bioequivalence review timelines for tamsulosin generics shorten market entry windows for qualified manufacturers, expanding formulary access across ambulatory surgical networks.
- India's Tier-2 Hospital Expansion:Diagnostic capacity buildout in secondary cities generates chronic prescription volume for benign prostatic hyperplasia management beyond metropolitan concentration.
- Uroselective Receptor Targeting:Tamsulosin's 10-fold alpha-1a subtype selectivity enables once-daily dosing without orthostatic hypotension, driving physician preference in elderly polypharmacy populations.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Chinese and Indian API suppliers control upstream tamsulosin hydrochloride production, exposing finished dose manufacturers to import licensing delays.
- Substitution by 5-Alpha Reductase Inhibitors:Dutasteride and finasteride compete for BPH market share in patients with prostate volume exceeding thresholds, particularly within Veterans Affairs formularies.
- EMA Pharmacovigilance Burden:Centralized marketing authorization procedures mandate post-authorization safety studies that extend compliance costs for generic entrants across EU member states.
Strategic Opportunities
- Brazil's ANVISA Accelerated Pathway:Priority review designation for essential medicines creates first-mover positioning for bioequivalent alpha-blocker filings in Latin America's largest urology market.
- Transdermal Delivery Development:Patch formulations targeting hypertensive populations with adherence challenges open chronic therapy segments outside traditional oral dominance.
- Japan's PMDA Elderly-Friendly Formulation Incentives:Sakigake designation for modified-release oral disintegrating tablets rewards innovation in geriatric-appropriate dosing formats.
Industry Challenges
- Bioequivalence Study Complexity:Narrow therapeutic index requirements for doxazosin and terazosin mandate extensive pharmacokinetic trials that strain clinical development budgets.
- Formulary Exclusion Mechanics:Pharmacy benefit managers deploy step-therapy protocols that require generic failure before branded alpha-blocker coverage authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Alpha-Blocker Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Doxazosin, Prazosin, Terazosin, Tamsulosin, Alfuzosin Therapy Area: Benign Prostatic Hyperplasia, Hypertension, Raynaud’s Disease, Heart Failure, Migraine Prevention End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Diagnostic Laboratories Route of Administration: Oral, Intravenous, Sublingual, Transdermal |
| Companies Covered | Pfizer Inc., Novartis AG, Merck & Co., Inc., AstraZeneca plc, Johnson & Johnson, Sanofi S.A., Bristol-Myers Squibb Company, Bayer AG, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Alpha-Blocker Market Shifts & Advancements
Extended-release formulation technologies and precision uroselectivity engineering are redefining competitive differentiation in lower urinary tract symptom pharmacotherapy, while regulatory convergence on bioequivalence standards reshapes manufacturing investment priorities.
Modified-release polymer matrix systems for tamsulosin are consolidating manufacturing scale advantages among producers with integrated pellet-coating capabilities. German and United States specialty pharmaceutical contractors are adopting these platforms to secure hospital formulary placement against immediate-release commoditization. The technology is consolidating competitive position around supply security and batch consistency rather than molecule novelty.
REACH authorization requirements for pharmaceutical intermediates are tightening documentation standards for alpha-blocker API imports into European Union member states. ECHA substance evaluation processes now demand enhanced impurity profiling that extends qualification timelines for Asian-sourced raw materials. Contract manufacturers in Italy and Spain are responding by qualifying captive synthesis routes for critical tamsulosin precursors.
Consolidated procurement through hospital purchasing cooperatives is displacing traditional wholesale distribution in North American alpha-blocker fulfillment. Integrated delivery networks in Texas, Florida, and Ohio negotiate direct manufacturer contracts that bypass distributor markups for chronic BPH therapies. This channel compression is most visible within Medicare Advantage plan formularies where total cost of ownership drives therapeutic class decisions.
Global Alpha-Blocker Market Segmentation
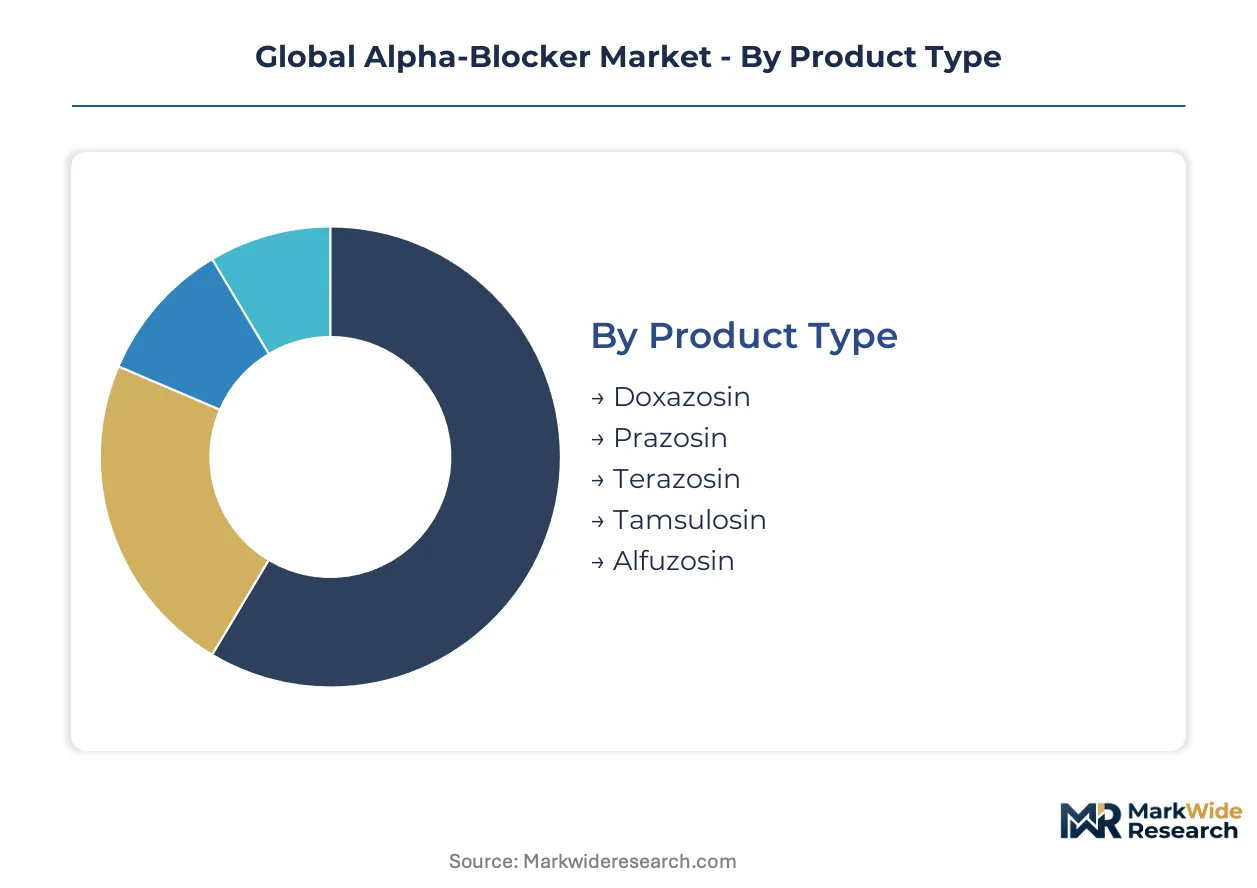
Alpha-blocker market segmentation reveals how therapeutic specialization and delivery innovation concentrate manufacturing investment. Supply chain configuration varies sharply across receptor selectivity profiles and institutional procurement channels.
Product Type:
API synthesis complexity and bioequivalence study requirements cluster manufacturing capacity around select molecules.
- Tamsulosin:Engineered for 10-fold selectivity toward alpha-1a adrenergic receptor subtypes in prostatic tissue. German urology clinics and United States ambulatory surgical networks drive prescription volumes through once-daily extended-release formulations that minimize orthostatic hypotension in elderly populations.
- Doxazosin:Non-selective alpha-1 antagonist with established hypertension and BPH indications. India's tier-2 hospital procurement consortia favor this molecule for dual-indication formularies where cardiovascular comorbidity prevalence expands addressable patient pools.
- Terazosin:First-generation agent with comparable receptor profile to doxazosin; sustained by generic price compression in Veterans Affairs systems.
- Alfuzosin:Extended-release formulations target European markets with EMA-approved modified-release specifications.
- Prazosin:Short-acting profile limits chronic use; concentrated in psychiatric and trauma-related hypertension applications.
Tamsulosin absorbs the bulk of installed capacity; alfuzosin is expanding most quickly through European specialty clinic adoption.
Therapy Area:
Reimbursement coding and chronic treatment protocols determine margin durability across indication categories.
- Benign Prostatic Hyperplasia:Aging demographics in Japan, Germany, and the United States sustain long-duration prescriptions. Medicare Advantage formularies in Florida and Texas prioritize uroselective agents with adherence-friendly dosing to reduce surgical intervention rates.
- Hypertension:Competing against ACE inhibitors and calcium channel blockers in polypharmacy populations. India's CDSCO-authorized generics dominate public hospital procurement through essential medicines list inclusion.
- Raynaud's Disease:Off-label vasodilator use in cold-climate geographies with limited dedicated therapeutic alternatives.
- Heart Failure:Adjunctive afterload reduction in select European protocols; constrained by guideline preference for evidence-based neurohormonal antagonists.
- Migraine Prevention:Niche application in refractory cases; limited formulary penetration outside specialized headache centers.
Benign prostatic hyperplasia commands the deepest margin pools; hypertension generates the highest absolute prescription volumes through broader eligibility.
End User:
Procurement centralization and clinical decision authority reshape channel economics for finished dose supply.
- Hospitals:Integrated delivery networks in Ohio and Texas negotiate direct manufacturer contracts bypassing wholesale distribution. Formulary committees enforce step-therapy protocols requiring generic alpha-blocker failure before branded authorization.
- Specialty Clinics:German urology practices concentrate high-value diagnostic and therapeutic decision-making. EMA pharmacovigilance compliance costs favor established suppliers with dedicated medical liaison infrastructure.
- Ambulatory Surgical Centers:Pre-operative BPH management drives short-course prescribing; CMS reimbursement compression limits premium formulation uptake.
- Diagnostic Laboratories:Minimal direct consumption; influence restricted to biomarker-guided referral patterns for urological consultation.
Hospitals consolidate the majority of contract value; specialty clinics are climbing the fastest through outcome-based reimbursement pilots.
Route of Administration:
Manufacturing asset specificity and patient adherence science determine competitive moats across delivery formats.
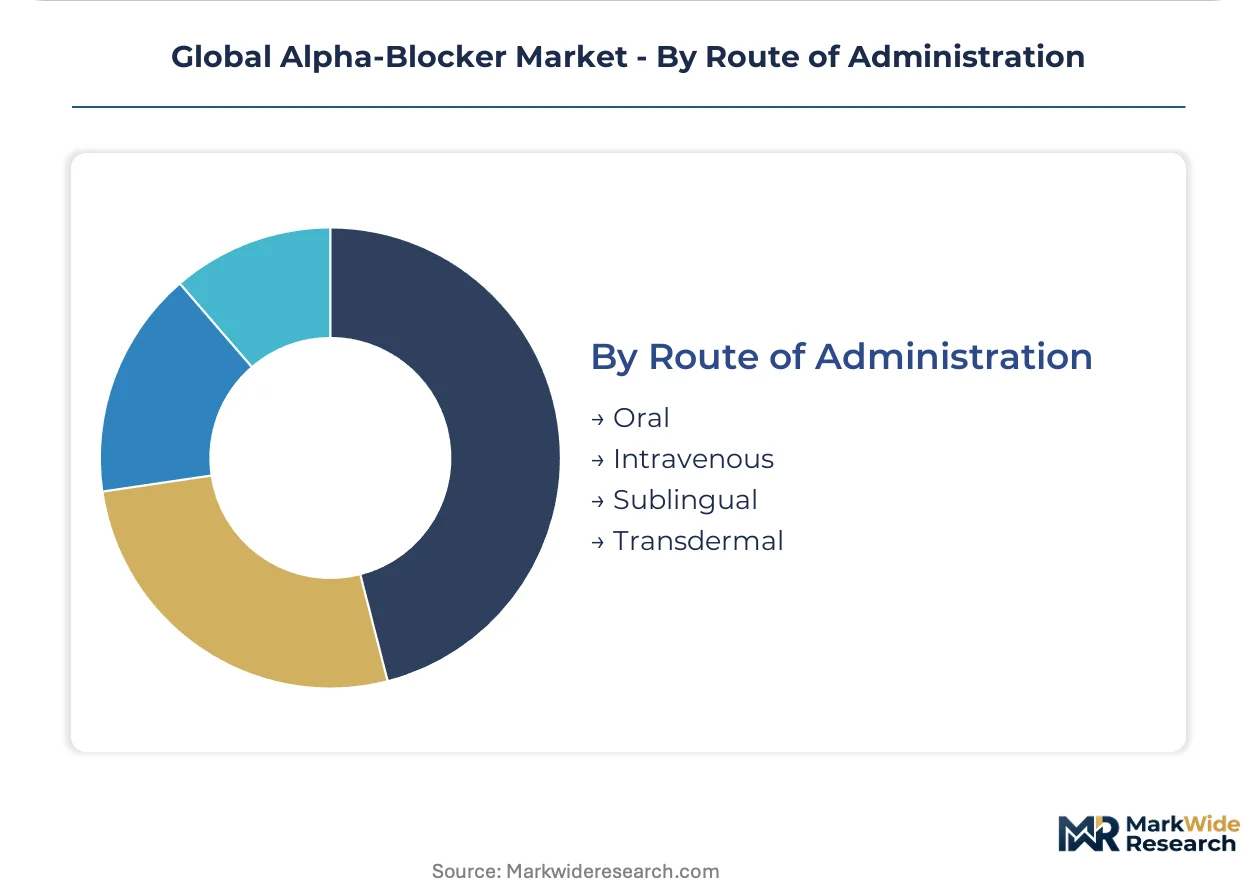
- Oral:Modified-release pellet technology dominates through integrated coating capabilities at Italian and Spanish contract manufacturers. Polymer matrix systems for tamsulosin secure batch consistency advantages against immediate-release commoditization.
- Transdermal:Patch development targets hypertensive populations with swallowing difficulties or complex polypharmacy regimens. Japan's PMDA Sakigake designation incentivizes geriatric-friendly innovation in oral disintegrating alternatives.
- Intravenous:Perioperative hypertensive emergency applications; limited to hospital-critical care settings with parenteral pharmacy infrastructure.
- Sublingual:Rapid-onset niche for acute blood pressure management; constrained by taste masking and mucosal absorption variability.
Oral formulations retain overwhelming capacity share; transdermal development programs are gaining share fastest through geriatric adherence research.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consortia in Germany and the United States concentrate alpha-blocker contract value, while India's tier-2 diagnostic expansion and Japan's geriatric formulation incentives reshape demand geography across the forecast window.
United States
Medicare Advantage formularies in Florida and Texas prioritize uroselective tamsulosin with adherence-friendly dosing to reduce surgical intervention rates. The FDA's streamlined ANDA review pathway accelerates generic bioequivalence approvals for ambulatory surgical networks. Integrated delivery networks in Ohio negotiate direct manufacturer contracts that bypass wholesale distribution markups.
Germany
Urology clinics across Bavaria and North Rhine-Westphalia expand alpha-blocker formularies for benign prostatic hyperplasia management in aging populations. EMA centralized marketing authorization procedures coordinate pharmacovigilance requirements that extend compliance costs for generic entrants. Specialty pharmaceutical contractors in Baden-Württemberg adopt modified-release pellet technology to secure hospital formulary placement.
India
Diagnostic capacity buildout in Maharashtra and Gujarat generates chronic prescription volume for BPH management beyond metropolitan concentration. CDSCO regulates import and local manufacturing licensure for urological active pharmaceutical ingredients with expanding scrutiny. Tier-2 hospital procurement consortia in Karnataka and Tamil Nadu consolidate purchasing power into multi-year sole-source agreements for oral doxazosin supply.
Japan
Aging demographics in the Kanto region sustain long-duration prescriptions for lower urinary tract symptom management. PMDA Sakigake designation incentivizes geriatric-friendly innovation in modified-release oral disintegrating tablet formats. Pharmaceutical development in Osaka and Nagoya clusters targets elderly populations with polypharmacy adherence challenges through novel delivery research.
Brazil
ANVISA's priority review designation for essential medicines creates first-mover positioning opportunities for bioequivalent alpha-blocker filings. Public hospital procurement in São Paulo and Rio de Janeiro concentrates demand for hypertension and BPH dual-indication formularies. Domestic manufacturing investment in Minas Gerais responds to import substitution policies for finished dose urological therapies.
Global Alpha-Blocker Market Competitive Landscape
North American producers anchor one tier of institutional formulary presence; European specialists hold regulatory compliance advantages through dedicated medical liaison infrastructure. The competitive structure consolidates around three strategic tiers: multinational pharmaceutical conglomerates with cardiovascular heritage, regional generic manufacturers with integrated API-to-dose capabilities, and specialty contractors with modified-release polymer expertise. Dominant competitive moves include backward integration into captive tamsulosin precursor synthesis and geographic expansion through Brazil's ANVISA accelerated pathway filings.
Within the multinational tier, Pfizer Inc. and Novartis AG occupy positions defined by institutional heritage and specialty distribution channel density. Merck & Co., Inc. anchors the manufacturing-scale archetype for oral doxazosin supply to ambulatory surgical networks. These three entities exemplify divergent competitive positioning: cardiovascular franchise leverage, European urology channel specialization, and operational scale for generic-compressed portfolios.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Merck & Co., Inc. |
| AstraZeneca plc |
| Johnson & Johnson |
| Sanofi S.A. |
| Bristol-Myers Squibb Company |
| Bayer AG |
| GlaxoSmithKline plc |
| Others |
Supply & Pricing Matrix
Hospital procurement consortia in Germany and the United States are consolidating purchasing power into multi-year sole-source agreements, forcing API manufacturers to qualify captive synthesis routes for tamsulosin precursors and compressing margin structures across oral alpha-blocker portfolios.
Pricing Analysis
Volume concentrates in generic tamsulosin while margin pools in extended-release branded formulations. Pricing stratifies across premium modified-release pellets, standard immediate-release tablets, and economy bulk doxazosin supply. Cost compression in the generic tier intensifies as FDA ANDA approvals accelerate bioequivalent entry. Medicare Advantage formularies in Florida and Texas exhibit the highest price sensitivity; German urology clinics show the lowest due to outcome-based reimbursement pilots.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and Indian API suppliers controlling upstream tamsulosin hydrochloride production. Finished dose manufacturing draws from Italian and Spanish contract manufacturers with integrated pellet-coating capabilities. Supply chain risk centers on ECHA REACH authorization delays for pharmaceutical intermediates. Distribution runs through hospital purchasing cooperatives in Ohio and Texas that bypass traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The alpha-blocker market is transitioning from immediate-release commoditization toward modified-release polymer matrix dominance, with extended-release pellet technology displacing legacy oral formulations in hospital formulary negotiations.
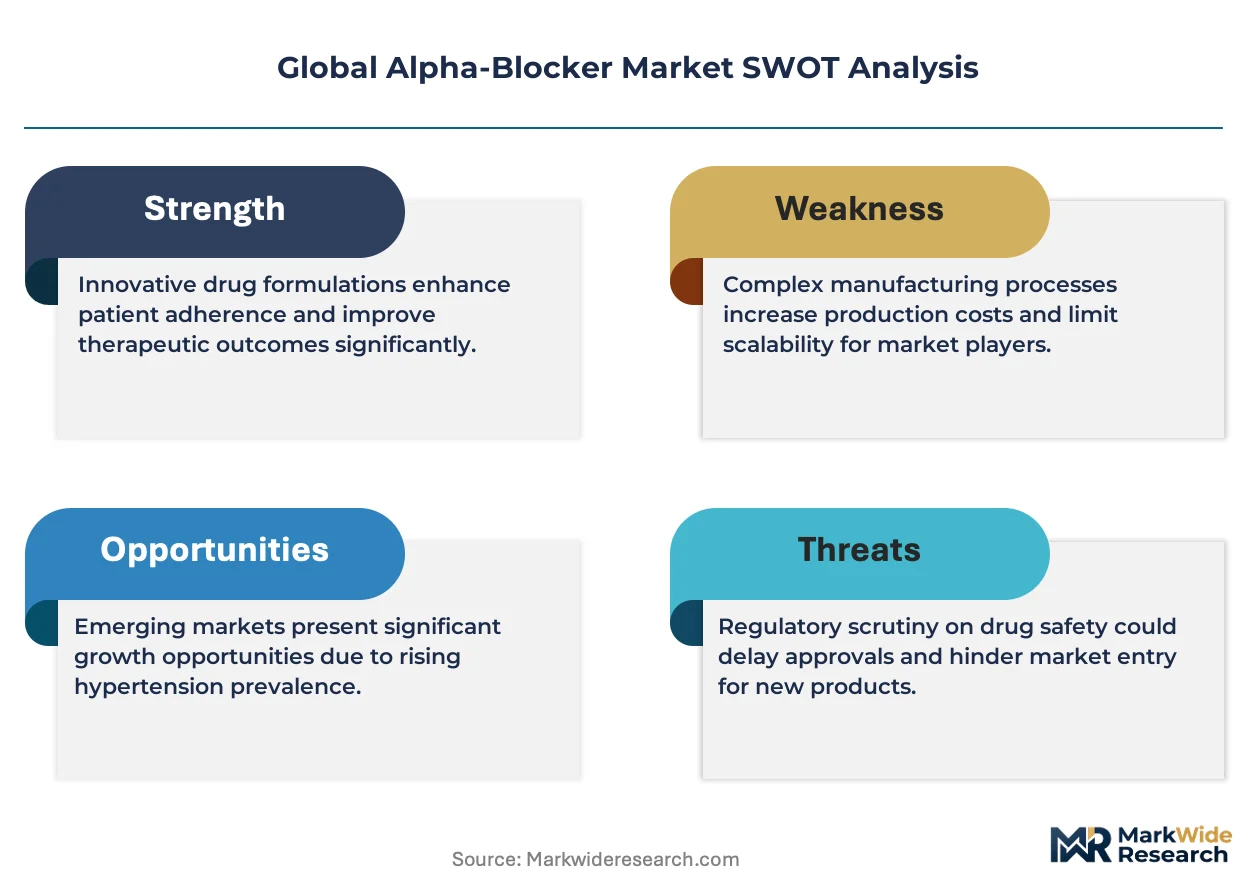
For Market Incumbents: Acquire modified-release polymer coating capabilities to defend against immediate-release commoditization. Secure backward integration into tamsulosin precursor synthesis to mitigate ECHA REACH authorization delays. Anchor institutional formulary presence through dedicated medical liaison infrastructure in German urology clinics. For New Entrants and Emerging Players: ANVISA's priority review designation for essential medicines in Brazil opens a window for bioequivalent alpha-blocker filings in Latin America's largest urology market. Target Japan's PMDA Sakigake pathway for geriatric-friendly oral disintegrating tablet formats. Penetrate India's tier-2 hospital procurement consortia through CDSCO-authorized generic doxazosin supply agreements. For Investors and Strategic Acquirers: The window for entry favors specialty contractors with captive API-to-dose integration. Long-term viability hinges on regulatory compliance infrastructure rather than molecule novelty. Watch for EMA pharmacovigilance burden escalation as the inflection signal for consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Modified-Release Polymer Matrix Development | Secures batch consistency advantages against immediate-release commoditization in German hospital networks. |
| Captive API Synthesis Qualification | Reduces ECHA REACH authorization exposure for Asian-sourced tamsulosin precursors. |
| ANVISA Accelerated Pathway Filing | Captures first-mover positioning in Brazil's public hospital procurement for BPH therapies. |
| PMDA Sakigake Designation Pursuit | Unlocks geriatric formulation incentives for oral disintegrating tablet innovation in Japan. |
| Hospital Procurement Consortium Contracting | Bypasses wholesale distribution markups through direct manufacturer agreements in Texas and Ohio. |
Research Methodology
FDA ANDA filings, EMA centralized marketing authorization procedures, and ClinicalTrials.gov records formed the secondary backbone of this analysis. Primary interviews with formulary directors, hospital procurement managers, regulatory affairs leads, and urology clinic administrators validated supply chain and pricing assumptions. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were triangulated against CDSCO manufacturing licensure data.
Bottom-up segment modeling treated receptor selectivity profiles, therapy area reimbursement coding, and regional regulatory clusters as independent dimensions across the projection horizon. CAGRs were derived from patient population epidemiology, chronic treatment protocol duration, and formulary access expansion trajectories. Forecast inputs included Medicare Advantage enrollment patterns, tier-2 hospital diagnostic capacity buildout rates, and modified-release formulation adoption curves.
The model assumes a particular technology adoption path; alternative pathways for transdermal patch development would alter the outlook. Forecasts reflect assumptions about EMA pharmacovigilance stability and FDA ANDA review timeline consistency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Veterinary Active Pharmaceutical Ingredients Manufacturing Market
Pharmaceuticals
Zimbabwe Pharmaceutical Market
Pharmaceuticals
Compound Glycyrrhizin Injection Market
Pharmaceuticals
Anticholinergic Drugs Market
Pharmaceuticals
Global Fondaparinux Market
Pharmaceuticals
Submucosal Lifting Agent Market
Pharmaceuticals
Empty Capsules Market
Pharmaceuticals
AI Drug Development Market
Pharmaceuticals
Amylin Analogs Market
Pharmaceuticals
Normal Saline for Parenteral Use Market
Pharmaceuticals
Russia Diabetes Drugs Market
Pharmaceuticals
Ion Channel Modulators Market
Pharmaceuticals
Cancer Therapeutics and Biotherapeutics Market
Pharmaceuticals
Estonia Pharmaceutical Market
Pharmaceuticals
Global Genitourinary Drugs Market
Pharmaceuticals
Disease-Modifying Agents Market