
 Global Finasteride Market | 2026-2036
Global Finasteride Market Size, Share, and Industry Trends Forecast 2026-2036
Global Finasteride Market Foresight
Aftermarket generic substitution revenue is tilting toward high-volume oral tablet manufacturers as patent cliffs mature across major markets. Merck & Co., Inc. (MSD) anchors originator brand loyalty through sustained physician education programs in urology. Dr. Reddy's Laboratories Ltd. leverages backward integration into active pharmaceutical ingredient production to control cost structures. Teva Pharmaceutical Industries Ltd. competes on manufacturing scale across multiple dosage strengths and markets.
Finasteride is a synthetic 4-azasteroid compound functioning as a selective type II 5-alpha-reductase inhibitor, blocking testosterone conversion to dihydrotestosterone with approximately 70% systemic reduction of serum DHT at standard dosing. The molecule serves primary commercial purpose in managing androgen-mediated conditions, specifically benign prostatic hyperplasia and androgenic alopecia through hormonal pathway interruption. Tablet formulations dominate volume due to established bioavailability profiles and decades of clinical documentation, while topical gel segments attract reformulation investment targeting localized action with reduced systemic exposure. Therapy area segmentation shows benign prostatic hyperplasia maintaining the largest patient pool, though androgenic alopecia drives higher per-patient lifetime value through chronic cosmetic use.
The US FDA enforces bioequivalence standards under 21 CFR 320 that generic finasteride applicants must satisfy, while India's CDSCO mandates manufacturing facility inspections under Schedule M for export eligibility. The European EMA's REACH framework governs chemical substance registration for API producers supplying the region. Stakeholders must monitor evolving FDA guidance on post-market generic equivalence surveillance and emerging market regulator alignment with ICH quality standards.
Market Dynamics
Patent expiration cascades across major markets are compressing originator margins while redirecting revenue toward API-integrated generic manufacturers capable of meeting FDA bioequivalence standards under 21 CFR 320.
Growth Catalysts
- CDSCO Schedule M compliance:Indian pharmaceutical facilities achieving export certification are capturing expanded generic prescription volumes in regulated markets.
- Topical gel reformulation:Localized delivery systems targeting reduced systemic DHT exposure are opening chronic cosmetic therapy segments beyond oral tablet dominance.
- Hospital urology centers:Physician-prescribed BPH protocols in North American clinical settings sustain demand for standardized 5-mg formulations.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production clusters in specific Asian manufacturing zones create single-source vulnerability for downstream tablet producers.
- EMA REACH registration:Chemical substance compliance costs for European market entry impose capital barriers on mid-scale API suppliers.
- Oral minoxidil substitution:Competing androgenic alopecia therapies with different mechanism profiles threaten finasteride's chronic cosmetic use position.
Strategic Opportunities
- Brazilian ANVISA pathway:Underpenetrated Latin American dermatology markets present volume expansion potential for bioequivalent generic entrants.
- Saudi SFDA localization:Gulf region pharmaceutical manufacturing incentives under Vision 2030 frameworks attract joint venture API investments.
- Telehealth prescription channels:Direct-to-patient platforms for hair loss consultations are bypassing traditional clinic gatekeepers in North American markets.
Industry Challenges
- ICH Q7 certification timelines:Multi-year good manufacturing practice audits delay facility qualification for export-oriented Indian and Chinese producers.
- 5-alpha-reductase inhibitor litigation:Post-marketing adverse event documentation requirements intensify pharmacovigilance resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Finasteride Market |
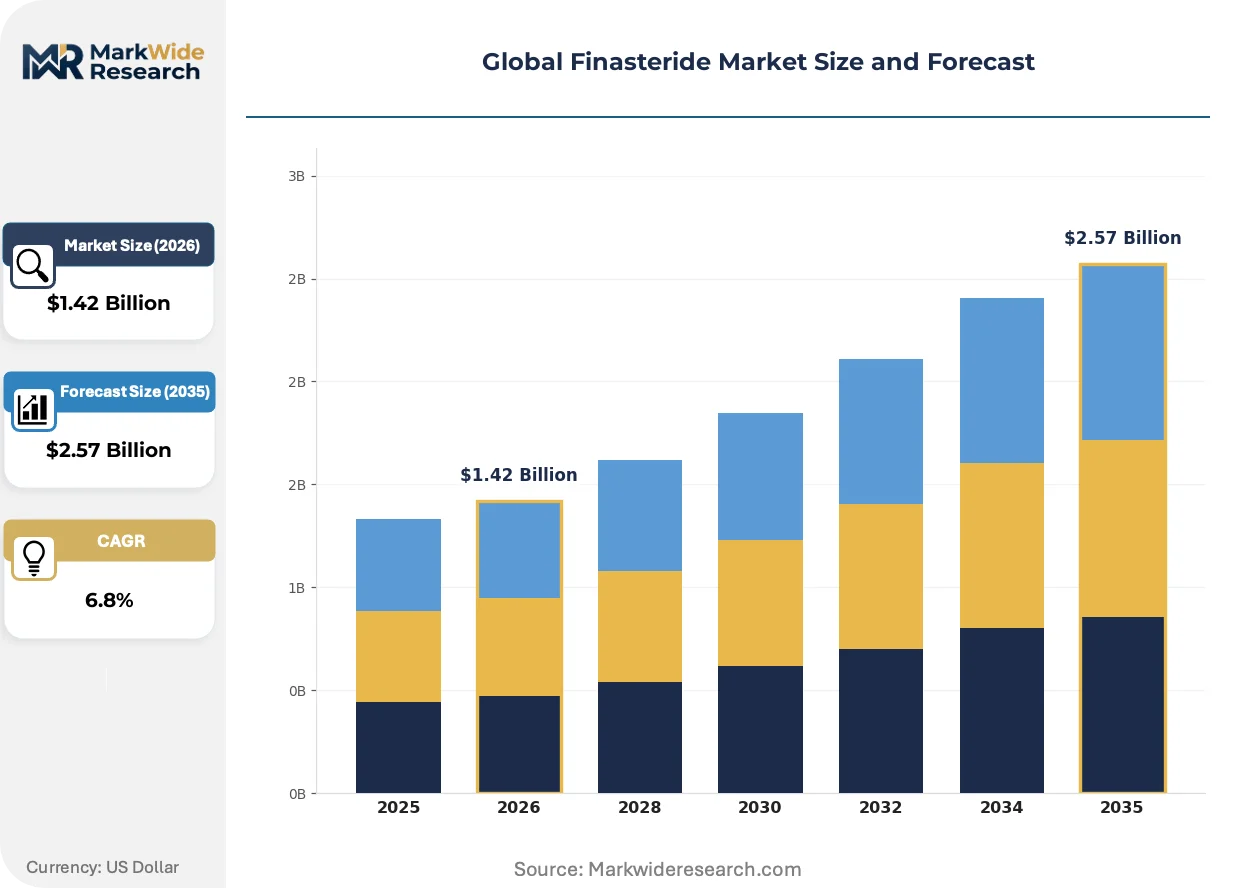
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Oral Solution, Topical Gel, Capsule Therapy Area: Benign Prostatic Hyperplasia, Androgenic Alopecia, Prostate Cancer Prevention, Hormonal Disorders End User: Hospitals, Dermatology Clinics, Urology Centers, Pharmacies Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | Viatris Inc., Dr. Reddy’s Laboratories Ltd., Merck & Co., Inc. (MSD), Aurobindo Pharma Ltd., Cipla Ltd., Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd., Lupin Ltd., Sandoz (Novartis division), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Finasteride Market Shifts & Advancements
Reformulation science and distribution channel restructuring are fragmenting the historical oral-tablet monopoly while regulatory surveillance intensifies across multiple jurisdictions.
Microemulsion-based topical delivery systems are advancing through dermatology pipelines with enhanced follicular penetration profiles. Korean and Japanese cosmetic pharmaceutical developers are accelerating clinical documentation for these formulations. The technology is rendering obsolete the assumption that systemic DHT suppression requires oral bioavailability.
EMA's evolving post-market generic equivalence surveillance guidance is tightening pharmacokinetic monitoring requirements for 5-mg BPH and 1-mg alopecia formulations. European national competent authorities are expanding batch testing protocols. Generic sponsors with limited bioanalytical capacity face compliance cost escalation across Germany, France, and Italy.
Subscription-based replenishment models for chronic alopecia therapy are displacing traditional pharmacy fulfillment in direct-to-consumer channels. North American telehealth platforms are capturing prescription renewal volumes previously routed through dermatology clinics. This behavioral shift concentrates patient data ownership with digital health intermediaries rather than established pharmaceutical distributors.
Global Finasteride Market Segmentation
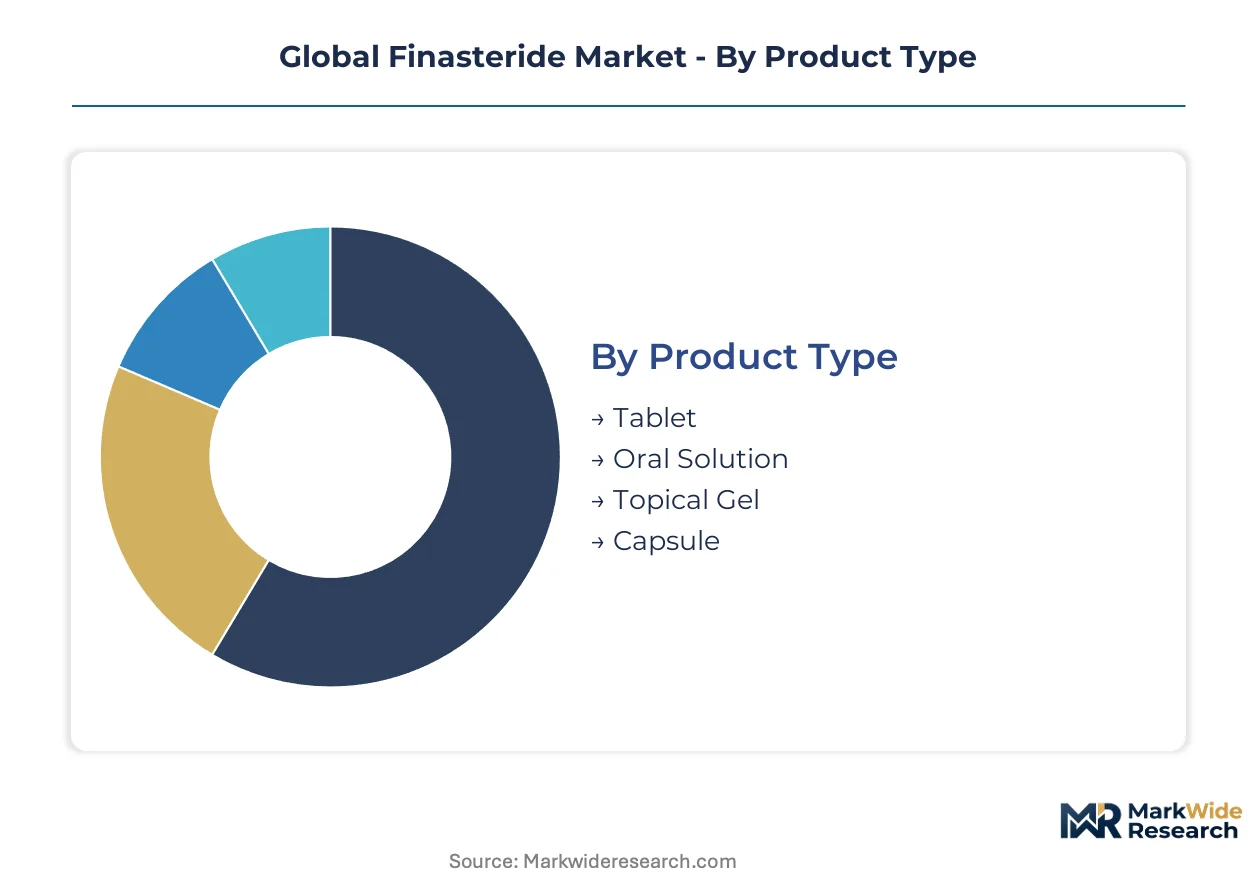
Finasteride market segmentation reflects divergent clinical requirements between urological and dermatological applications, with formulation technology and distribution infrastructure shaping competitive boundaries across each slice.
Product Type:
Use-case spectrum spans chronic daily administration in BPH management to precision cosmetic delivery in hair restoration protocols.
- Tablet:Compressed solid dosage forms with established bioavailability profiles dominate chronic therapy protocols. Hospital urology centers in the United States and Germany standardize on 5-mg tablet regimens for BPH, with FDA 21 CFR 320 bioequivalence requirements reinforcing manufacturing consolidation among API-integrated producers.
- Topical Gel:Microemulsion-based transdermal systems target follicular penetration with reduced systemic DHT exposure. Korean cosmetic pharmaceutical developers and Japanese dermatology clinics are accelerating clinical documentation for these formulations, displacing assumptions that systemic suppression requires oral bioavailability.
- Oral Solution:Liquid formulations serve pediatric hormonal disorder protocols and patients with swallowing difficulties. Compounding pharmacies in Canada and Australia maintain niche production lines for these specialized indications.
- Capsule:Gelatin-encapsulated variants offer taste masking and modified release options. Brazilian ANVISA-registered facilities are expanding capsule capacity for Latin American export markets.
The dominant share belongs to Tablet, while Topical Gel is closing the gap fastest.
Therapy Area:
Cost tier stratification separates acute intervention budgets from lifetime cosmetic expenditure patterns.
- Benign Prostatic Hyperplasia:Chronic 5-mg daily protocols for enlarged prostate management command the largest institutional prescription volumes. Medicare-reimbursed urology centers across the United States sustain demand through standardized treatment algorithms and physician education programs anchored by originator brands.
- Androgenic Alopecia:Cosmetic 1-mg daily regimens generate higher per-patient lifetime value through uninterrupted chronic use. Telehealth platforms in the United States and direct-to-consumer subscription models are capturing renewal volumes previously routed through dermatology clinics.
- Prostate Cancer Prevention:Risk-reduction protocols in high-incidence populations drive preventive prescribing. TGA-registered Australian urologists and Health Canada-approved protocols maintain selective adoption for this indication.
- Hormonal Disorders:Off-label and specialized endocrine applications serve transgender hormone therapy and rare congenital conditions. Compounding specialists in the Netherlands and Switzerland handle these low-volume, high-complexity prescriptions.
Volume concentration rests with Benign Prostatic Hyperplasia, though Androgenic Alopecia claims the steepest expansion trajectory.
End User:
Customer type fragmentation splits between institutional procurement and retail prescription fulfillment.
- Hospitals:Integrated health systems with centralized pharmacy operations negotiate volume contracts for 5-mg BPH formulations. NHS Trusts in the United Kingdom and Kaiser Permanente networks in California exemplify this procurement pattern.
- Dermatology Clinics:Specialized cosmetic practices prescribe 1-mg alopecia protocols with direct pharmacy routing. South Korean dermatology chains and Spanish trichology centers are expanding aesthetic service lines around finasteride maintenance.
- Urology Centers:Physician-owned ambulatory surgical centers maintain loyalty to originator brands through sustained professional education. French and Italian urology associations enforce strict formulary adherence for reimbursed care.
- Pharmacies:Community and mail-order dispensaries handle generic substitution and refill management. CVS Health and Walgreens Boots Alliance networks in North America optimize inventory around high-turnover generic SKUs.
Procurement scale favors Hospitals, while Dermatology Clinics are gaining share fastest.
Distribution Channel:
Supply concentration varies from captive hospital pharmacies to fragmented direct-to-consumer platforms.
- Hospital Pharmacies:Captive dispensaries within integrated delivery networks control formulary access for inpatient and outpatient BPH protocols. German Krankenhaus pharmacies and Japanese university hospital dispensaries maintain tight generic substitution policies.
- Retail Pharmacies:High-street and supermarket-affiliated dispensaries handle the majority of 1-mg cosmetic prescriptions. Boots UK and Shoppers Drug Mart in Canada compete on generic pricing and loyalty program integration.
- Online Pharmacies:Digital fulfillment platforms with prescription verification are displacing traditional pharmacy visits for chronic alopecia therapy. Roman, Hims, and Keeps in the United States concentrate patient data ownership with telehealth intermediaries.
- Direct Sales:Manufacturer-to-institution contracts bypass wholesale distribution for large health systems. Teva and Dr. Reddy's direct account teams serve GPO-negotiated hospital networks in the United States.
Retail Pharmacies retain the dominant position, though Online Pharmacies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with the United States favoring chronic cosmetic regimens while Germany and Japan maintain institutional urology protocols as the dominant channel.
United States
Telehealth platforms and direct-to-consumer subscription models now capture a substantial share of 1-mg alopecia prescriptions, bypassing traditional dermatology gatekeepers. FDA bioequivalence enforcement under 21 CFR 320 continues shaping generic substitution timelines. Manufacturing concentration clusters around New Jersey and North Carolina pharmaceutical corridors.
Germany
Hospital urology centers within integrated Krankenhaus networks sustain standardized 5-mg BPH treatment algorithms with tight formulary adherence. EMA post-market surveillance guidance tightens pharmacokinetic monitoring requirements for generic sponsors. API sourcing flows through Frankfurt-Rhine-Main logistics hubs serving continental distribution.
India
CDSCO Schedule M certification unlocks export eligibility for API-integrated tablet manufacturers targeting regulated markets. Hyderabad and Mumbai pharmaceutical corridors scale active pharmaceutical ingredient production for hair loss and prostate therapies. Backward integration into API production controls cost structures for generic exporters.
China
NMPA manufacturing facility inspections govern domestic production authorization while export-oriented producers align with ICH Q7 quality standards. Zhejiang and Jiangsu province chemical parks concentrate 5-alpha-reductase inhibitor synthesis capacity. Multi-year GMP audit timelines delay facility qualification for Western market entry.
Brazil
ANVISA regulatory pathways present volume expansion potential for bioequivalent generic entrants in underpenetrated dermatology markets. São Paulo and Rio de Janeiro clinical research organizations accelerate local trial documentation for multinational sponsors. Hospital pharmacy procurement consolidation favors standardized 5-mg formulations in public health systems.
Global Finasteride Market Competitive Landscape
Capability concentration sits with originator-brand educators; scale advantage sits with API-integrated generic manufacturers. The market structures around a tiered hierarchy where patent-cliff timing determines margin compression velocity. Three archetypes dominate: backward-integrated Indian pharmaceutical conglomerates, multinational generic volume players, and originator-brand loyalty builders. Competitive moves center on manufacturing scale expansion and telehealth distribution partnerships.
Among API-integrated producers, Dr. Reddy's Laboratories Ltd. and Aurobindo Pharma Ltd. exemplify the backward-integration archetype controlling active pharmaceutical ingredient supply chains. Teva Pharmaceutical Industries Ltd. occupies a position representing multinational generic scale advantage across multiple dosage strengths. Merck & Co., Inc. (MSD) anchors originator-brand positioning through sustained professional education in urology channels.
| Leading Market Players |
|---|
| Viatris Inc. |
| Dr. Reddy's Laboratories Ltd. |
| Merck & Co., Inc. (MSD) |
| Aurobindo Pharma Ltd. |
| Cipla Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Lupin Ltd. |
| Sandoz (Novartis division) |
| Others |
Supply & Pricing Matrix
Frankfurt-Rhine-Main logistics corridors shape cost dynamics across European distribution, amplifying price differentiation between API-integrated manufacturers and formulation-only competitors while compressing margins for non-backward-integrated tablet producers.
Pricing Analysis
Long-term offtake contracts anchor hospital procurement for 5-mg BPH formulations, while spot-market dynamics govern direct-to-consumer 1-mg alopecia channels. Price differentiation rests on FDA bioequivalence certification tier and volume scale commitments, with subscription-based replenishment models facing intensifying cost compression from telehealth platform aggregation. Hospital buyers exhibit lowest price sensitivity due to formulary adherence protocols; cash-pay cosmetic patients demonstrate highest elasticity.
Supply Chain Analysis
Export-control regimes under India's DGFT Schedule M and China's NMPA facility licensing restrict API flow velocity to regulated markets. Active pharmaceutical ingredient production concentrates in Zhejiang and Jiangsu provinces alongside Hyderabad and Mumbai corridors, drawing from 4-azasteroid precursor chemicals and specialized hydrogenation catalysts. Single-source vulnerability in 5-alpha-reductase inhibitor synthesis creates exposure to multi-year GMP audit delays. Distribution runs through captive hospital pharmacies, retail chains, and direct-to-patient telehealth platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Finasteride markets reward service-attach strategies where patient data platforms and subscription logistics layers expand faster than commodity tablet production.
For Market Incumbents: Build regulatory moats through accelerated FDA bioequivalence documentation and EMA REACH registration completion ahead of post-market surveillance tightening. Anchor hospital urology center loyalty through sustained professional education programs. Counter oral minoxidil substitution threats by capturing telehealth platform prescription routing partnerships. For New Entrants and Emerging Players: Pursue Brazilian ANVISA pathway acceleration for underpenetrated Latin American dermatology markets. Target topical gel reformulation segments where Korean and Japanese cosmetic pharmaceutical developers have established clinical precedent. Enter through direct-to-consumer subscription channel partnerships rather than traditional pharmacy distribution. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pharmaceutical conglomerates divesting mature urology portfolios amid patent cliff compression. Prioritize API-integrated manufacturers with CDSCO Schedule M certification and backward integration into 4-azasteroid synthesis. Watch for inflection signals in EMA pharmacovigilance guidance stringency affecting generic sponsor compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| API Backward Integration | Captive 4-azasteroid production insulates margin structures from precursor volatility. |
| Telehealth Platform Partnership | Roman, Hims, and Keeps concentrate patient data ownership away from traditional distributors. |
| Topical Gel Reformulation | Microemulsion delivery systems open chronic cosmetic segments beyond oral tablet dominance. |
| EMA REACH Registration | Chemical substance compliance unlocks European market access for Asian API producers. |
| CDSCO Schedule M Certification | Indian facility inspections enable export eligibility to FDA-regulated markets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with regulatory affairs leads, formulary directors at integrated health systems, API procurement managers, and telehealth platform executives; and secondary validation against FDA 21 CFR 320 filings, EMA submission databases, CDSCO export registration records, and hospital procurement contract disclosures. Bottom-up prescription volume modeling triangulated against top-down pharmaceutical market sizing.
Forecast inputs span therapy area segmentation across BPH and androgenic alopecia, dosage form differentiation between tablet and topical gel, and distribution channel evolution through hospital, retail, and online pharmacy routes. CAGRs derive from patient population epidemiology, patent expiration sequencing, and generic substitution elasticity curves across the analysis window. API production capacity expansion timelines and telehealth prescription growth trajectories anchor forward projections.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement policy and pharmaceutical trade tariff regimes would shift the trajectory. Forecasts reflect assumptions on regulatory alignment timelines and bioequivalence enforcement consistency. Material shifts in FDA post-market generic surveillance guidance or ICH Q7 certification delays would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Anti-Vascular Endothelial Growth Factor Therapeutics Market
Pharmaceuticals
Tinea Versicolor Treatment Market
Pharmaceuticals
Global Eylea Market
Pharmaceuticals
US Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
B7-H3 Antibody Market
Pharmaceuticals
API Contract Manufacturing Market
Pharmaceuticals
India Pharmaceutical Contract Sales Organizations Market
Pharmaceuticals
Antibody Therapy Market
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
Bispecific Antibody Therapeutics Contract Manufacturing Market
Pharmaceuticals
Tapentadol Market
Pharmaceuticals
Alopecia Drugs Market
Pharmaceuticals
Non-Steroidal Anti-Inflammatory API Market
Pharmaceuticals
Propafenone Hcl Extended Release Capsules Market
Pharmaceuticals
North America Hormone Replacement Therapy Market
Pharmaceuticals
Leflunomide Market