
 Italy Drug Delivery Devices Market | 2026-2036
Italy Drug Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Drug Delivery Devices Market Foresight
Glass-to-cyclo-olefin polymer substitution in prefilled syringe barrels is realigning cost structures for Italian biologics packaging. Gerresheimer AG leverages its European polymer conversion capacity to supply Italian pharmaceutical customers with reduced breakage-risk containers. BD sustains manufacturing scale across multiple delivery formats, anchoring hospital procurement contracts through centralized distribution. Ypsomed AG specializes in pen injector platforms for insulin delivery, competing on patient ergonomics against larger diversified suppliers.
Drug delivery devices are engineered systems that administer therapeutic agents through controlled release mechanisms, incorporating precision-machined needles, elastomeric seals, and microprocessor-driven dosing algorithms to achieve bioavailability targets. Prefilled syringes and wearable injectors lead Italian hospital and homecare procurement respectively, with the latter capturing margin pools from biologic therapy expansion. Injectable and transdermal delivery modes dominate Italian reimbursement-eligible prescriptions, while inhalation systems occupy a narrower but defensible position in respiratory therapy maintenance. Diabetes management and cancer treatment applications structure the largest addressable patient bases for device makers operating in Italy.
Italy's Ministry of Health and AIFA govern device market authorization, with CE marking under the EU MDR governing technical conformity for commercial distribution. The EU AI Act and national cybersecurity directives are layering data-protection requirements onto connected delivery platforms, reshaping R&D priorities for device firmware and cloud architecture. Stakeholders must monitor how AIFA's evolving HTA frameworks for self-administration therapies redistribute procurement authority between hospital pharmacy committees and regional homecare networks.
Market Dynamics
Italy's National Health Service reimbursement frameworks are redistributing procurement authority from hospital pharmacy committees to regional homecare networks, accelerating self-administration device adoption among chronic disease patients.
Growth Catalysts
- Regional procurement centralization:Lombardy and Emilia-Romagna's specialized diabetes centers aggregate demand volume for wearable injectors, creating procurement efficiencies that lower per-unit costs for insulin delivery platforms.
- EU MDR compliance pathways:CE marking harmonization under the Medical Device Regulation streamlines market authorization timelines for polymer-based prefilled syringes, reducing technical barriers for Italian biologics packaging suppliers.
- Biologic therapy pipeline expansion:Monoclonal antibody treatments for autoimmune conditions require large-volume subcutaneous delivery, pulling wearable injector demand from oncology clinics into rheumatology practices.
Market Restraints
- Glass barrel supply concentration:Borosilicate glass sourcing for traditional prefilled syringes depends on limited European furnace capacity, exposing Italian pharmaceutical customers to input cost volatility and extended lead times.
- Connected device cybersecurity compliance:The EU AI Act layers data-protection requirements onto infusion pump firmware, forcing R&D budget reallocation toward cloud architecture security rather than core dosing algorithm development.
- Reimbursement fragmentation across regions:AIFA's Health Technology Assessment frameworks vary in implementation between northern and southern Italian regions, creating uneven patient access to self-administration therapies.
Strategic Opportunities
- Southern Italy homecare network expansion:Underpenetrated regions like Sicily and Calabria present whitespace for wearable injector deployment as regional health authorities build outpatient chronic disease management infrastructure.
- Transdermal patch convergence with biosensors:Microneedle array technology combined with continuous glucose monitoring is opening hormone therapy applications beyond diabetes into fertility and endocrine treatment.
- Pharmacy channel direct distribution:Community pharmacy networks are gaining authorization to dispense prefilled pen injectors for self-administration, bypassing hospital procurement committees and capturing patient adherence data.
Industry Challenges
- Polymer conversion talent scarcity:Cyclo-olefin polymer molding expertise concentrates in German and Swiss manufacturing clusters, forcing Italian device makers to compete for specialized polymer engineers or outsource critical barrel production.
- Legacy hospital IT integration:Connected infusion pumps must interface with proprietary electronic health record systems at major Italian teaching hospitals, requiring costly custom API development for each procurement contract.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Drug Delivery Devices Market |
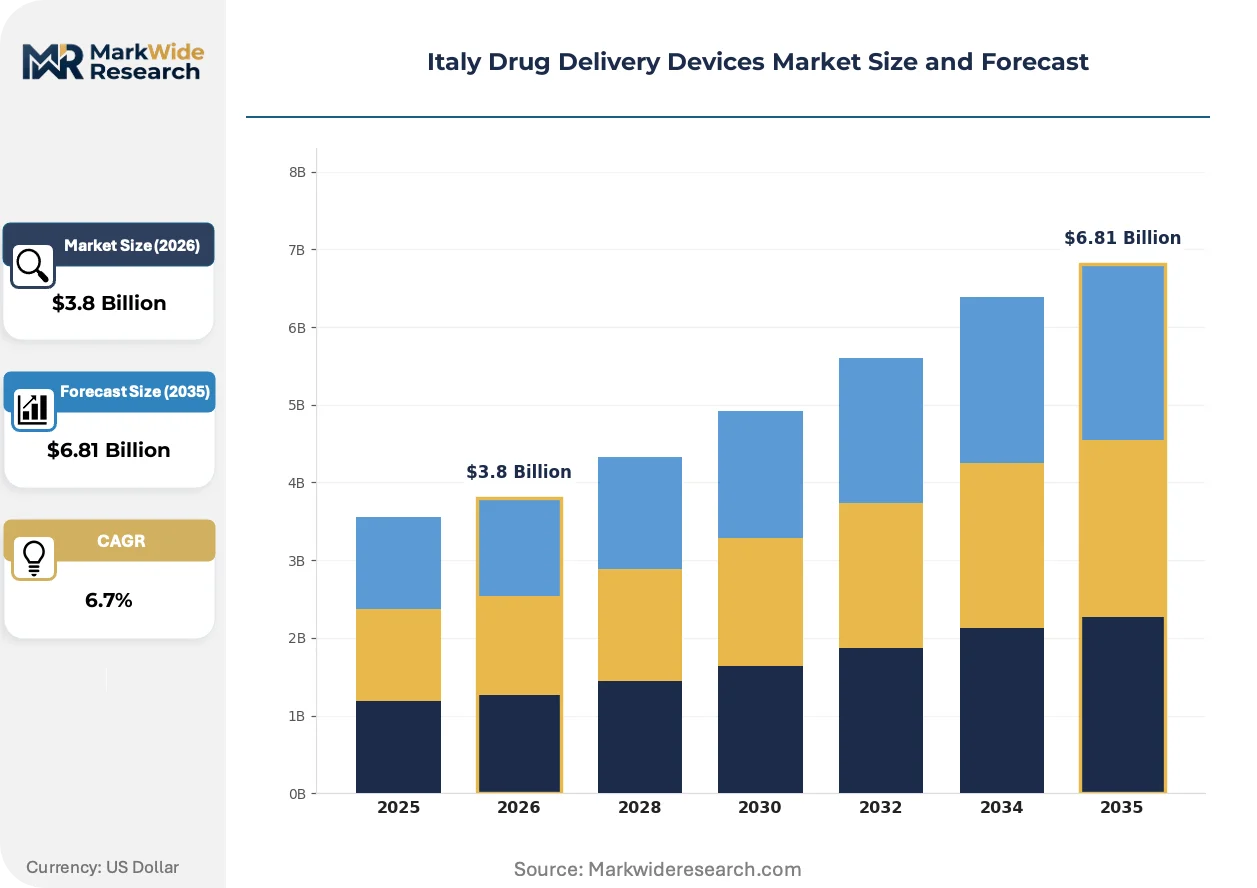
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pumps, Prefilled Syringes, Inhalers, Wearable Injectors Delivery Mode: Injectable, Transdermal, Inhalation, Oral End User: Hospitals, Homecare, Clinics, Pharmacies Application: Diabetes Management, Cancer Treatment, Pain Management, Vaccination |
| Companies Covered | Gerresheimer AG, BD (Becton, Dickinson and Company), Ypsomed AG, Nemera, Terumo Corporation, Pfizer Inc, Novartis AG, Johnson & Johnson, Roche Holding AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Drug Delivery Devices Market Shifts & Advancements
Wearable injector technology is compressing the boundary between acute hospital care and chronic disease management, enabling dose administration outside supervised clinical settings while generating real-world adherence data.
Large-volume wearable injectors are decentralizing biologic drug delivery from infusion centers to patient homes. These devices incorporate microprocessor-driven dosing algorithms and elastomeric drive mechanisms to administer viscous formulations over extended periods. Northern Italy's oncology networks are adopting them rapidly for immunotherapy regimens. The technology is decentralizing site-of-care economics by eliminating nursing supervision hours and facility overhead from treatment costs.
Italy's Ministry of Health is implementing the EU AI Act's risk classification framework for connected delivery devices, mandating algorithmic transparency and post-market surveillance for machine-learning-enabled dosing systems. Device firmware must now document decision pathways for regulatory inspection. Pen injector platforms with Bluetooth connectivity face the steepest compliance burden, as their dose-logging functions qualify as high-risk AI under the implementing guidelines.
Hospital pharmacy committees are unbundling after-sales service contracts from device procurement, purchasing pen injectors and infusion pumps on capital expenditure schedules while negotiating technical support separately. This purchasing behavior is compressing supplier margins on bundled offerings. The shift is most visible in Lombardy's centralized procurement consortia, where tender specifications now separate warranty terms from training and maintenance obligations.
Italy Drug Delivery Devices Market Segmentation
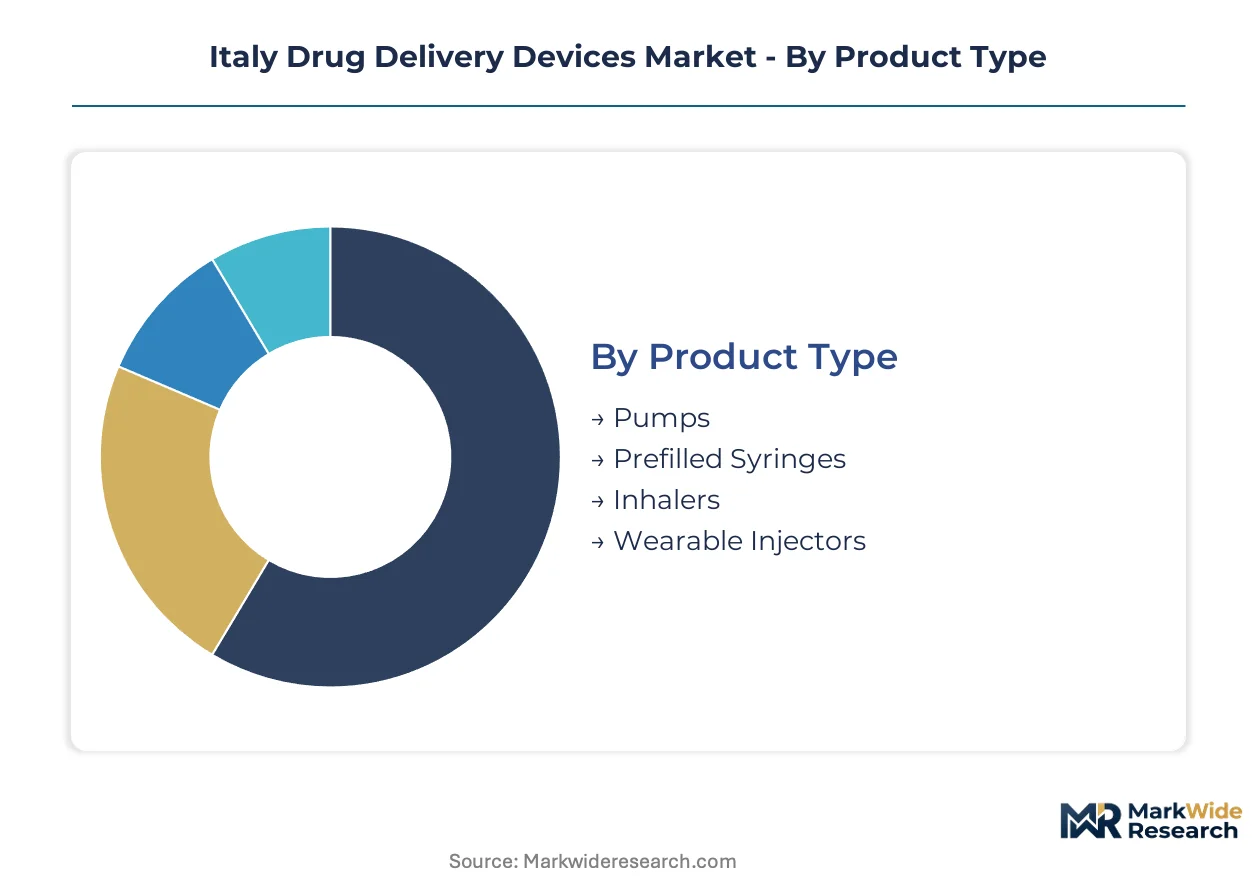
Device segmentation in Italy reflects divergent reimbursement pathways and patient risk profiles. Procurement committees at Lombardy teaching hospitals weight technical specifications differently than regional homecare networks managing chronic disease cohorts across Sicily and Calabria.
Product Type:
Hospital pharmacy committees prioritize device reliability metrics, while homecare procurement emphasizes patient ergonomics and connectivity features.
- Pumps:Electronic infusion pumps incorporate peristaltic or syringe drive mechanisms for precise volumetric delivery in oncology wards. Demand concentrates in Milan's Policlinico and Rome's Gemelli networks, where high-acuity immunotherapy protocols require extended administration cycles. AIFA reimbursement for hospital-based infusion is compressing capital equipment replacement cycles.
- Wearable Injectors:Large-volume patch pumps with elastomeric or motor-driven reservoirs enable subcutaneous biologic delivery outside clinical supervision. Northern Italy's diabetes centers in Bologna and Verona are deploying these for insulin glargine and GLP-1 agonist therapies, pulling procurement authority from hospital pharmacies into regional homecare budgets.
- Prefilled Syringes:Glass or cyclo-olefin polymer barrels with bonded needles dominate vaccine and anticoagulant administration in acute care settings.
- Inhalers:Pressurized metered-dose and dry powder devices serve respiratory maintenance therapy through hospital discharge programs.
Prefilled syringes lead volumes today; wearable injectors are gaining share fastest.
Delivery Mode:
Reimbursement eligibility under Italy's National Health Service varies sharply by administration route, with injectable therapies commanding broader coverage than alternative modalities.
- Injectable:Subcutaneous, intramuscular, and intravenous routes dominate biologic and small-molecule delivery through prefilled syringes, pens, and infusion systems. Injectable formulations capture the largest prescription volume across Lombardy and Emilia-Romagna, driven by monoclonal antibody expansion in autoimmune and oncology indications.
- Transdermal:Microneedle arrays and passive diffusion patches deliver hormones and analgesics through stratum corneum penetration. Sicily's expanding homecare infrastructure is piloting transdermal testosterone and fentanyl programs, bypassing gastrointestinal absorption variability in elderly patient cohorts.
- Inhalation:Pulmonary deposition targets bronchial and alveolar tissue for localized respiratory therapy.
- Oral:Traditional enteral absorption remains relevant for small-molecule maintenance therapies with favorable bioavailability profiles.
Injectable modes dominate prescription counts; transdermal delivery is climbing the fastest as regional homecare networks expand chronic pain and hormone therapy access.
End User:
Procurement scale and technical sophistication separate institutional buyers from distributed retail channels.
- Hospitals:Acute care facilities with centralized pharmacy committees negotiate multi-year device contracts based on total cost of ownership, training infrastructure, and EHR integration requirements. Major procurement volume aggregates at Turin's Molinette and Naples' Federico II complexes, where immunotherapy and surgical anesthesia protocols drive infusion pump and syringe demand.
- Homecare:Regional health authority networks manage chronic disease patients through distributed device deployment and remote monitoring. Emilia-Romagna's pioneering homecare consortia are standardizing wearable injector formularies for diabetes and heart failure populations, shifting site-of-care economics from facility-based to patient-managed administration.
- Clinics:Outpatient specialty centers concentrate vaccination and short-cycle infusion delivery.
- Pharmacies:Community dispensing points are gaining authorization for self-administration device distribution under pharmacist supervision protocols.
Hospitals lead absolute device procurement; homecare networks are expanding most quickly as AIFA reimbursement frameworks redistribute chronic therapy management authority.
Application:
Disease prevalence and therapy innovation cycles determine addressable patient bases and device performance requirements.
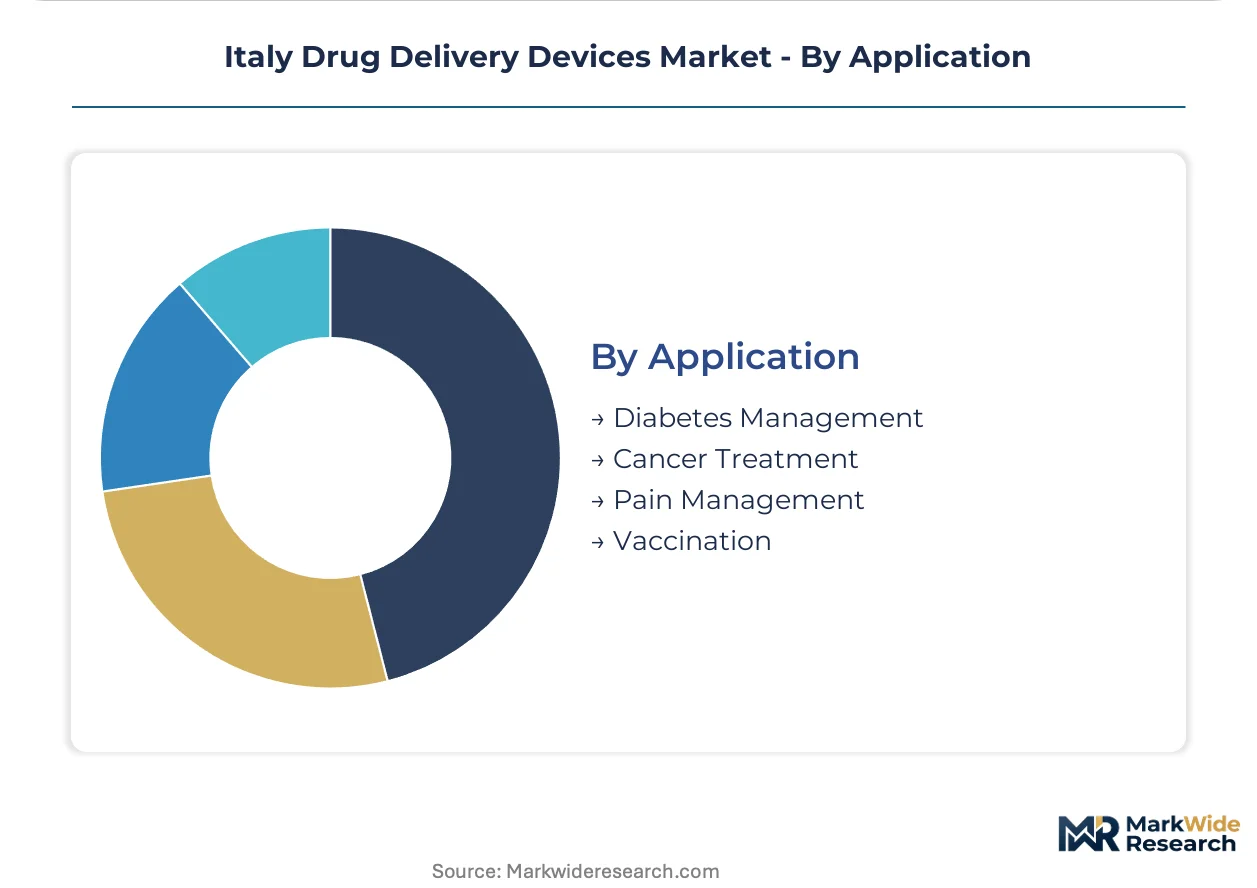
- Diabetes Management:Insulin delivery platforms span disposable pens, reusable pen injectors, and patch pumps with continuous glucose monitoring integration. Italy's aging diabetic population—concentrated in northern industrial regions with longer life expectancy—is driving wearable injector and smart pen adoption as regional health authorities seek to reduce hypoglycemia-related hospital admissions.
- Cancer Treatment:Cytotoxic chemotherapy, immunotherapy, and supportive care agents require precise dosing across infusion center and home settings. Rome's Istituto Nazionale Tumori and Milan's INT are standardizing large-volume wearable injectors for pembrolizumab and trastuzumab subcutaneous formulations, displacing traditional IV infusion for eligible patient cohorts.
- Pain Management:Opioid and non-opioid analgesic delivery employs patient-controlled infusion and transdermal systems.
- Vaccination:Mass immunization programs and routine pediatric schedules sustain prefilled syringe and autoinjector demand.
Diabetes management leads installed device base; cancer treatment applications show the steepest expansion trajectory as subcutaneous biologics displace IV administration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lombardy's pharmaceutical manufacturing corridor anchors procurement volume for drug delivery devices, with Milan's Policlinico and regional homecare networks driving divergent demand specifications across northern Italy.
Lombardy
Milan's concentrated diabetes centers and immunotherapy wards generate dual demand streams for wearable injectors and precision infusion systems. AIFA's regional HTA frameworks accelerate self-administration therapy approvals, redistributing procurement authority toward outpatient networks. The Bergamo-Brescia industrial crescent hosts polymer conversion facilities supplying cyclo-olefin syringe barrels to biologics packagers.
Emilia-Romagna
Bologna's pioneering homecare consortia standardize wearable injector formularies for chronic disease populations, shifting site-of-care economics from hospitals to patient-managed administration. The region's Health Technology Assessment committees negotiate centralized tenders that aggregate demand volume across multiple provinces. Modena and Parma's pharmaceutical clusters concentrate prefilled syringe procurement for vaccine and anticoagulant distribution.
Veneto
Verona's specialized diabetes centers deploy patch pumps for insulin glargine and GLP-1 agonist therapies, pulling device procurement into regional chronic disease budgets. The EU MDR's CE marking harmonization streamlines market authorization for polymer-based delivery systems manufactured in Padua's medical device corridor. Treviso's pharmaceutical packaging suppliers serve northern European customers through established logistics channels.
Lazio
Rome's Istituto Nazionale Tumori and Gemelli hospital network standardize large-volume wearable injectors for subcutaneous immunotherapy, displacing traditional IV infusion for eligible oncology cohorts. The Ministry of Health's implementation of EU AI Act risk classifications mandates algorithmic transparency for connected dosing systems developed in the capital's medical technology research corridor. Latina's emerging device assembly operations target southern European export markets.
Piedmont
Turin's Molinette hospital complex anchors high-acuity infusion pump demand for surgical anesthesia and cytotoxic chemotherapy protocols. Regional health authorities pilot pharmacy channel distribution models for prefilled pen injectors, bypassing traditional hospital procurement committees. Novara's pharmaceutical manufacturing zone concentrates glass barrel sourcing relationships with limited European furnace suppliers.
Italy Drug Delivery Devices Market Competitive Landscape
Global majors compete with regional champions across device format specialization and polymer conversion expertise, creating a tiered structure where diversified conglomerates anchor hospital contracts while mid-cap specialists capture homecare margin pools. Three archetypes dominate: integrated packaging conglomerates with European furnace and polymer molding assets; pen injector specialists competing on patient ergonomics and connectivity features; and diversified medtech giants leveraging centralized distribution scale. Competitive moves concentrate on unbundling service contracts from device procurement and securing polymer engineering talent for next-generation barrel production.
Among German and Swiss-based packaging specialists, Gerresheimer AG and Ypsomed AG occupy positions at opposite ends of the device spectrum. Gerresheimer exemplifies the integrated polymer converter archetype with European capacity for cyclo-olefin syringe barrels, while Ypsomed represents the pen injector specialist model focused on patient-centric design. BD anchors the diversified conglomerate tier, sustaining manufacturing scale across multiple delivery formats through centralized distribution infrastructure that secures multi-year hospital procurement contracts.
| Leading Market Players |
|---|
| Gerresheimer AG |
| BD (Becton, Dickinson and Company) |
| Ypsomed AG |
| Nemera |
| Terumo Corporation |
| Pfizer Inc |
| Novartis AG |
| Johnson & Johnson |
| Roche Holding AG |
| Others |
Supply & Pricing Matrix
Captive polymer conversion capacity in Germany and Switzerland anchors pricing power for Italian device manufacturers sourcing cyclo-olefin syringe barrels. This upstream control insulates suppliers from borosilicate glass furnace volatility while concentrating margin capture among integrated packaging conglomerates serving Lombardy pharmaceutical clusters.
Pricing Analysis
Input-cost pass-through from limited European borosilicate furnace capacity is compressing margins on glass-barrel prefilled syringes. Three-tier pricing structure across premium connectivity-enabled, standard mechanical, and economy disposable tiers differentiates wearable injectors by algorithmic sophistication and after-sales bundling. Pricing pressure stems from AIFA's unbundling of service contracts from device procurement in Lombardy consortia. Hospital pharmacy committees demonstrate lowest price sensitivity due to total-cost-of-ownership frameworks, while regional homecare networks prioritize per-unit acquisition cost.
Supply Chain Analysis
Elevated freight costs from German and Swiss polymer molding centers to Italian pharmaceutical corridors are reshaping sourcing economics for cyclo-olefin barrel procurement. Supply concentrates in Germany, Switzerland, and Belgium for precision-machined drive mechanisms and elastomeric seals. Raw material dependencies encompass medical-grade polymers, borosilicate glass tubing, and stainless-steel cannula stock. Single-source vulnerability pervades cyclo-olefin polymer expertise concentration. Distribution runs through centralized hospital procurement consortia in northern Italy and emerging pharmacy channel networks in southern regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk classification framework for connected dosing systems compounds regulatory-driven demand for algorithmic transparency and post-market surveillance capabilities.
For Market Incumbents: Anchor multi-year hospital contracts through EHR integration investments that raise switching costs for Policlinico and Gemelli networks. Deepen backward integration into cyclo-olefin polymer molding to offset German and Swiss supplier concentration. Defend against pen injector specialists by capturing patient adherence data through Bluetooth-enabled dose logging. For New Entrants and Emerging Players: CE marking harmonization under EU MDR opens a window for polymer-based prefilled syringe suppliers to bypass legacy glass-barrel incumbents. Target Sicily and Calabria homecare infrastructure buildout for wearable injector deployment where procurement authority is decentralizing. Pursue pharmacy channel direct distribution authorization to bypass hospital committee gatekeeping. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap pen injector specialists because AIFA reimbursement fragmentation across Italian regions prevents scale concentration by global majors. Five-to-ten-year viability hinges on connectivity feature differentiation and polymer engineering talent acquisition. Monitor EU AI Act implementing guidelines for algorithmic transparency requirements as inflection indicator for R&D budget reallocation toward firmware compliance.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR harmonization accelerates polymer syringe authorization timelines for Italian biologics packagers. |
| Hospital System Partnership | EHR integration at Molinette and Federico II complexes locks in multi-year infusion pump procurement. |
| Software Companion Development | Bluetooth dose-logging functionality triggers EU AI Act high-risk classification for pen injector platforms. |
| Reimbursement Strategy | AIFA HTA framework navigation determines procurement authority distribution between hospital and homecare networks. |
| Backward Integration | In-house cyclo-olefin molding capacity reduces dependency on German and Swiss polymer converter clusters. |
Research Methodology
Bottom-up hospital and homecare procurement modeling reconciled against top-down device manufacturer shipment tracking forms the analytical core of this study. Primary interviews with hospital pharmacy committee directors, regional homecare network administrators, biomedical engineers at teaching hospitals, and GPO contracts managers combined with secondary validation from AIFA reimbursement databases, EU MDR CE marking registries, and hospital procurement tender records. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map device format demand against polymer conversion capacity, algorithmic firmware development pipelines, and regional reimbursement authorization patterns. Segmentation dimensions encompass product type, delivery mode, end user, and application category across the projection horizon. CAGRs derive from patient population growth trajectories, therapy pipeline expansion rates, and procurement authority redistribution trends. Forecast inputs incorporate immunotherapy protocol adoption and diabetes management decentralization metrics.
Revisions become necessary when EU AI Act implementing guidelines shift algorithmic risk classifications or when AIFA HTA frameworks alter regional reimbursement eligibility. Forecasts reflect documented assumptions regarding polymer supply stability and connected device cybersecurity compliance trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Artificial Tendons and Ligaments Market
Medical Devices
North America Ambulatory Infusion Pumps Market
Medical Devices
Global Live Cell Encapsulation Market
Medical Devices
Capsulotomy Market
Medical Devices
Global Micro Guide Catheters Market
Medical Devices
Organ Preservation Market
Medical Devices
Veterinary Ultrasound Scanners Market
Medical Devices
Self-Destructing Syringe Market
Medical Devices
Global Automatic Pill Dispenser Market
Medical Devices
Spherical IOL Market
Medical Devices
Vascular Boot Market
Medical Devices
Volumetric Arc Therapy Market
Medical Devices
Europe Electric Wheelchair Market
Medical Devices
Global Gastric Balloons Market
Medical Devices
Superficial Radiation Therapy System Market
Medical Devices
Blood Warmer Devices/Sample Warmer Market