
 Iceland Pharmaceutical Market | 2026-2036
Iceland Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Iceland Pharmaceutical Market Foresight
Pharmaceutical distribution through hospital procurement channels is narrowing as Iceland's centralized healthcare purchasing consolidates volume. Sanofi leverages its biologics portfolio to sustain access to Reykjavík's Landspitali University Hospital, the country's largest treatment center. Alvogen anchors the generic pharmaceuticals segment through cost-competitive supply contracts with regional health authorities. Novartis differentiates via specialized oncology and neurology therapies that address Iceland's aging demographic profile.
Iceland pharmaceuticals encompass chemically synthesized and biologically derived medicinal products formulated for disease prevention, diagnosis, and treatment, requiring cold-chain logistics for temperature-sensitive biologics and compliance with European Medicines Agency stability guidelines. Prescription medications dominate value flows through hospital and pharmacy channels, while biologics command premium positioning due to complex manufacturing and stringent storage requirements. Generic pharmaceuticals compete on price within the national reimbursement framework, and oral delivery modes remain the default for chronic disease management in homecare settings.
The Icelandic Medicines Agency enforces marketing authorization aligned with European Medicines Agency standards, while the Ministry of Health sets reimbursement thresholds that directly shape product commercial viability. Iceland's adoption of EU Medical Device Regulation and Falsified Medicines Directive compliance protocols raises barriers for non-European suppliers. Stakeholders must monitor how the national health system's shift toward centralized tendering affects portfolio prioritization and channel economics.
Market Dynamics
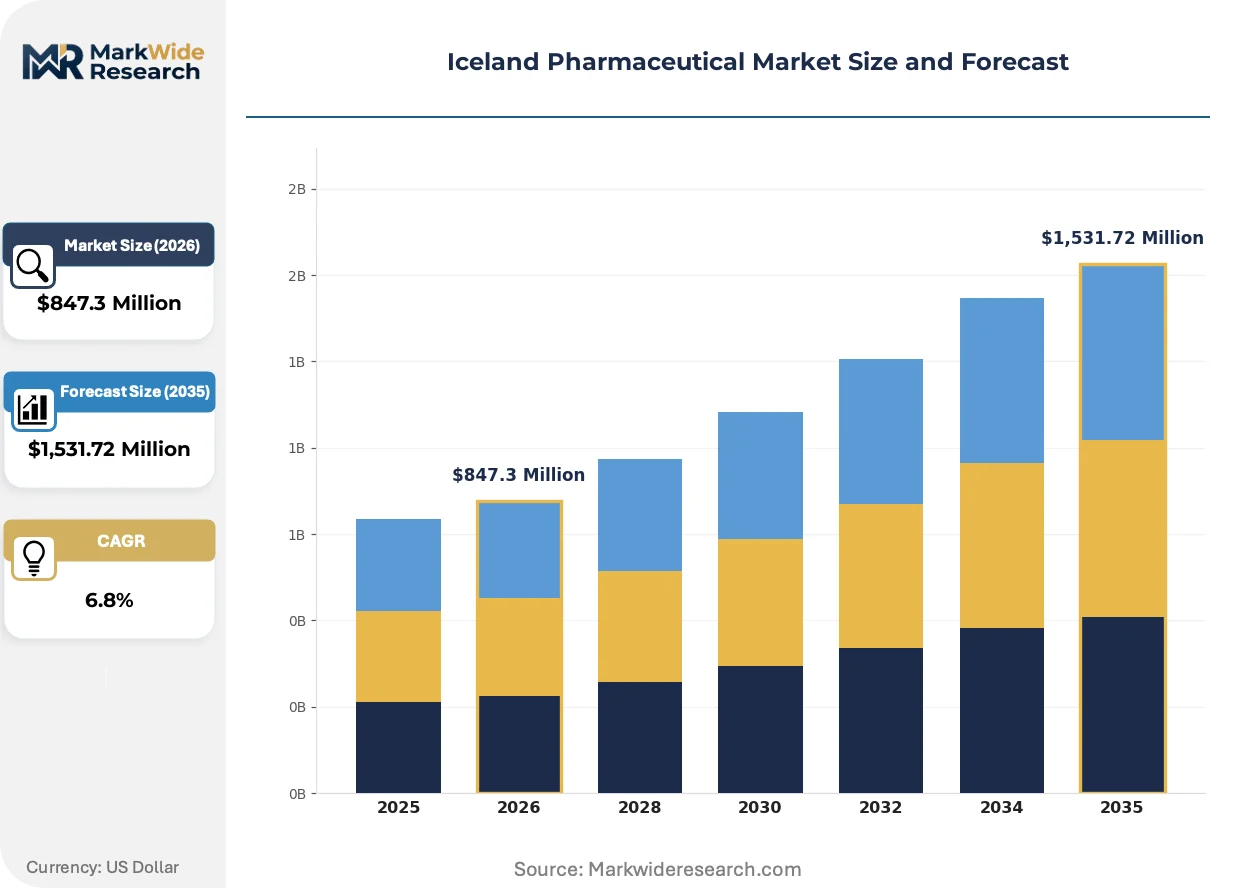
Iceland's national health system is consolidating procurement through centralized tendering, compressing vendor margins while elevating cold-chain biologics requirements. The Icelandic Medicines Agency's alignment with European Medicines Agency standards intensifies compliance costs for imported specialty therapies.
Growth Catalysts
- Centralized Hospital Procurement:Iceland's national health system aggregates volume through Landspitali University Hospital, creating economies of scale for high-cost biologics.
- EMA Alignment:The Icelandic Medicines Agency's adoption of European Medicines Agency marketing authorization standards streamlines cross-border product registration.
- Aging Demographics:Iceland's expanding geriatric population drives demand for chronic disease management therapies administered through Reykjavík's hospital cluster.
Market Restraints
- Import Dependency:Iceland lacks domestic active pharmaceutical ingredient manufacturing, exposing supply chains to currency volatility and shipping disruptions.
- Cold-Chain Infrastructure Gaps:Temperature-sensitive biologics require specialized logistics that strain Iceland's limited pharmaceutical distribution network beyond Reykjavík.
- Reimbursement Compression:The Ministry of Health's centralized price-setting narrows commercial viability for innovative therapies outside national formulary inclusion.
Strategic Opportunities
- Regional Health Authority Contracts:Iceland's decentralized regional health boards outside Reykjavík present untapped procurement channels for specialized therapy providers.
- Homecare Delivery Models:Oral formulations for chronic conditions enable direct-to-patient distribution bypassing hospital-centric administration.
- Falsified Medicines Directive Compliance:Iceland's implementation of EU serialization requirements creates first-mover advantage for track-and-trace technology integrators.
Industry Challenges
- Specialized Cold-Chain Logistics:Biologics distribution requires qualified personnel and equipment scarce in Iceland's peripheral regions.
- Regulatory Timeline Compression:Marketing authorization alignment with European Medicines Agency accelerated review cycles strains submission preparation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iceland Pharmaceutical Market |
| Market Size in 2026 | $847.3 Million |
| Market Size in 2035 | $1,531.72 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Medications, Over-the-Counter Drugs, Biologics, Generic Pharmaceuticals Therapy Area: Cardiovascular, Oncology, Neurology, Endocrinology Delivery Mode: Injectable, Oral, Transdermal, Inhalable End User: Hospitals, Pharmacies, Clinics, Homecare |
| Companies Covered | Sanofi, GlaxoSmithKline, Novartis, Coripharma, Alvogen, Pfizer, Merck & Co., EpiEndo Pharmaceuticals, Johnson & Johnson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iceland Pharmaceutical Market Shifts & Advancements
Digital infrastructure is penetrating Iceland's pharmaceutical supply chain, reshaping how temperature-sensitive products are monitored and distributed. Three developments are altering competitive positioning.
Blockchain-enabled temperature monitoring is virtualizing cold-chain verification for biologics moving through Reykjavík's hospital distribution hub. Landspitali University Hospital pilots distributed ledger systems to replace paper-based custody documentation. This technology is virtualizing compliance workflows while compressing audit preparation cycles for imported specialty therapies.
The Icelandic Medicines Agency's enforcement of EU Falsified Medicines Directive serialization mandates is mandating unit-level traceability for all prescription products. Manufacturers must retrofit packaging lines with aggregation capabilities or risk exclusion from national reimbursement. Oncology and neurology biologics face the steepest compliance investment given their high-value positioning.
Hospital procurement teams are consolidating vendor relationships through multi-year framework agreements that bundle pharmaceuticals with logistics services. Regional health authorities outside Reykjavík are adopting this model, displacing spot purchasing. The Akureyri hospital cluster demonstrates this shift most visibly, centralizing specialty therapy sourcing under single-provider contracts.
Iceland Pharmaceutical Market Segmentation
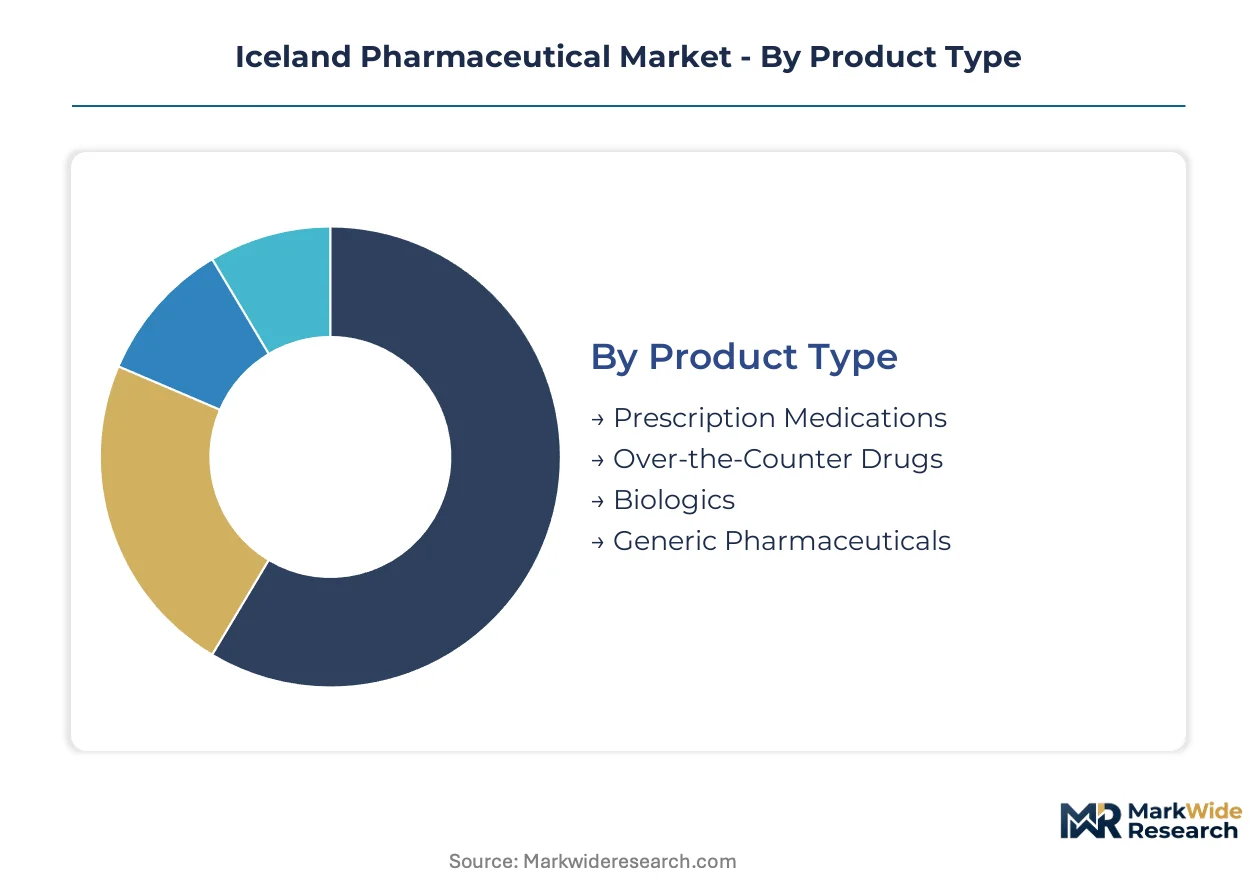
Iceland's pharmaceutical segmentation reveals how procurement centralization and cold-chain logistics reshape competitive positioning across product categories. Distinct channel economics and reimbursement tiers govern commercial viability for each segment cluster.
Product Type:
After-sales service intensity varies sharply across product types, with biologics demanding continuous cold-chain monitoring and generic pharmaceuticals requiring minimal post-distribution support.
- Prescription Medications:Chemically synthesized therapeutic agents subject to Icelandic Medicines Agency marketing authorization and Ministry of Health reimbursement scheduling. Demand concentrates through Landspitali University Hospital's centralized procurement, where formulary inclusion determines commercial access.
- Biologics:Temperature-sensitive protein-based therapies manufactured through recombinant DNA technology requiring validated cold-chain logistics. Reykjavík's hospital cluster absorbs the majority of volume as specialized administration infrastructure concentrates in the capital region.
- Over-the-Counter Drugs:Non-prescription analgesics and self-care products distributed through pharmacy retail networks with minimal regulatory friction.
- Generic Pharmaceuticals:Bioequivalent copies of off-patent molecules competing on price within national tender frameworks.
Prescription medications hold the largest share; momentum sits with biologics as oncology and neurology portfolios expand.
Therapy Area:
Cost tier stratification separates acute intervention therapies from chronic disease management portfolios across Iceland's reimbursement system.
- Cardiovascular:Antihypertensive and anticoagulant therapies dominating chronic prescription volumes through primary care channels.
- Oncology:High-value biologics and targeted small molecules administered through Reykjavík's specialized infusion centers. Landspitali University Hospital's consolidated procurement creates volume concentration for immunotherapy and monoclonal antibody suppliers.
- Neurology:Disease-modifying therapies for multiple sclerosis and Parkinson's disease requiring cold-chain distribution to regional hospital clusters. Akureyri's secondary treatment center generates peripheral demand as patient referral networks extend beyond the capital.
- Endocrinology:Insulin and analog products for diabetes management with established homecare delivery pathways.
Cardiovascular commands the largest prescription volume; neurology exhibits the steepest expansion trajectory as aging demographics drive demand.
Delivery Mode:
Application requirements dictate infrastructure investment, with injectable formats demanding clinical administration while oral formulations enable patient-directed consumption.
- Injectable:Parenteral formulations including intravenous biologics and subcutaneous therapies requiring healthcare professional administration. Hospital and clinic channels dominate as patient self-injection remains limited outside insulin therapy.
- Oral:Tablet and capsule formulations for chronic disease management enabling direct-to-patient distribution through pharmacy networks. Homecare settings represent the primary consumption location as patients manage cardiovascular and endocrine conditions independently.
- Transdermal:Patch-based delivery for pain management and hormone replacement with moderate cold-chain requirements.
- Inhalable:Aerosol and dry powder respiratory therapies distributed through specialized pharmacy channels.
Oral delivery holds the largest share; injectable formats are climbing the fastest as biologics penetration deepens.
End User:
Customer type determines procurement mechanics, with hospitals operating centralized tender processes while pharmacies manage individual prescription fulfillment.
- Hospitals:Institutional purchasers aggregating volume through Landspitali University Hospital's procurement authority and regional health board frameworks. Centralized tendering compresses margins while elevating service requirements for cold-chain biologics.
- Pharmacies:Retail dispensaries fulfilling outpatient prescriptions within national reimbursement price ceilings. Reykjavík's pharmacy density exceeds peripheral regions, creating geographic concentration in capital-area distribution.
- Clinics:Outpatient facilities administering specialty injections and infusions outside full hospital infrastructure.
- Homecare:Direct-to-patient delivery channels for oral chronic therapies bypassing institutional administration.
Hospitals hold the largest share; homecare is gaining share fastest as oral biologics and patient self-administration protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Reykjavík's cold-chain logistics infrastructure underwrites Iceland's pharmaceutical distribution network, connecting the island nation to European and North American supply corridors through temperature-controlled container services.
Capital Region
Landspitali University Hospital and the Icelandic Medicines Agency anchor pharmaceutical demand and regulatory oversight in Reykjavík. The Ministry of Health's centralized procurement authority operates from the capital, setting reimbursement thresholds that determine commercial viability for imported therapies. Reykjavík's hospital cluster absorbs the majority of biologics volume as specialized infusion infrastructure concentrates in the metropolitan area.
Northeastern Region
Akureyri's secondary hospital cluster generates peripheral demand for neurology and oncology therapies as patient referral networks extend beyond the capital. The Icelandic Medicines Agency's EMA-aligned marketing authorization standards apply uniformly, though cold-chain logistics gaps strain distribution to this region. Regional health authorities here are adopting multi-year framework agreements that bundle pharmaceuticals with logistics services, displacing spot purchasing.
Southern Peninsula
The Reykjanes peninsula's logistics hubs support pharmaceutical warehousing and distribution operations serving the broader capital region. Keflavík International Airport's cargo facilities enable time-sensitive biologics imports from European manufacturing centers. Pharmaceutical distributors leverage this infrastructure to maintain cold-chain integrity for temperature-sensitive products entering the national supply chain.
Western Region
Akranes and surrounding municipalities host pharmacy retail networks fulfilling outpatient prescriptions within national reimbursement price ceilings. The region's lower population density creates distribution cost challenges for specialty therapies requiring cold-chain maintenance. Homecare delivery models for oral chronic medications bypass institutional administration here more frequently than in remote northern areas.
Westfjords
Isafjörður and isolated coastal settlements face the steepest cold-chain infrastructure gaps, limiting access to temperature-sensitive biologics. The national health system's centralized tendering compresses margins for suppliers willing to serve this peripheral geography. Telemedicine protocols and periodic specialist visits from Reykjavík partially offset the absence of local infusion capacity.
Iceland Pharmaceutical Market Competitive Landscape
On the supply side, the industry is consolidating around hospital procurement centralization and EMA-aligned regulatory compliance. The vendor base stratifies between multinational biologics manufacturers, regional generic suppliers, and specialized cold-chain logistics integrators. Three archetypes dominate: patent-protected biologics specialists, cost-competitive generic providers, and integrated hospital-contract service bundlers. Competitive intensity centers on multi-year framework agreement capture and Falsified Medicines Directive serialization readiness.
Among multinational pharmaceutical manufacturers, Sanofi, Novartis, and Alvogen occupy distinct positioning within Iceland's procurement structure. Sanofi represents the biologics-specialist archetype through its hospital-centric portfolio. Novartis exemplifies the high-value therapy segment addressing aging demographics. Alvogen anchors the generic-tier competitive set through cost-focused supply contracts with regional health authorities.
| Leading Market Players |
|---|
| Sanofi |
| GlaxoSmithKline |
| Novartis |
| Coripharma |
| Alvogen |
| Pfizer |
| Merck & Co. |
| EpiEndo Pharmaceuticals |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
European active pharmaceutical ingredient manufacturers anchor Iceland's upstream supply base, concentrating margin capture in German and Swiss specialty chemical producers while Icelandic hospital procurement teams extract downstream value through centralized tendering. The Ministry of Health's price-setting authority compresses vendor margins as volume aggregates through Landspitali University Hospital's formulary decisions.
Pricing Analysis
Volume-discount tiering structures dominate Iceland's hospital procurement, with three-tier pricing separating originator biologics from biosimilars and generic substitutes. Price differentiation rests on EMA marketing authorization tier and cold-chain service bundling rather than brand premium alone. Cost compression in the generic tier is intensifying because regional health authorities are consolidating spot purchases into multi-year framework agreements. Regional health boards outside Reykjavík exhibit the highest price sensitivity, while oncology biologics at Landspitali face the lowest due to limited therapeutic alternatives.
Supply Chain Analysis
EU export-control regimes for dual-use biotechnology equipment constrain Iceland's access to advanced manufacturing infrastructure, though finished pharmaceutical imports flow freely under EEA rules. Supply concentrates in Denmark, Germany, and the Netherlands for packaged formulations, with active pharmaceutical ingredients drawing from Indian and Chinese chemical synthesis hubs. Single-source vulnerability pervades temperature-sensitive biologics where qualified cold-chain carriers are scarce. Distribution runs through Keflavík International Airport's cargo terminals into Reykjavík's hospital distribution hub.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iceland's pharmaceutical market represents early-cycle expansion as homecare delivery models for oral chronic therapies penetrate beyond Reykjavík's hospital-centric infrastructure. Aging demographics and EMA-aligned regulatory streamlining provide structural tailwinds for adoption.
For Market Incumbents: Insulate formulary position at Landspitali University Hospital through cold-chain service bundling and serialization-ready packaging investments that preempt Falsified Medicines Directive compliance gaps. Anchor backward integration into European distribution partnerships to offset currency volatility exposure from import-dependent supply structures. The threat of biosimilar substitution in oncology and neurology portfolios demands defensive patent estate management and real-world evidence generation.
For New Entrants and Emerging Players: Build out direct-to-patient distribution capabilities for oral cardiovascular and endocrine therapies that bypass Reykjavík's hospital procurement concentration. The Westfjords and Northeastern regions present the most penetrable geography given cold-chain infrastructure gaps that incumbent biologics suppliers struggle to serve economically. A regional health authority contracting angle, bundling logistics with product supply, unlocks access outside capital-area tender processes.
For Investors and Strategic Acquirers: Capital is best deployed toward cold-chain logistics integrators with EMA-qualified distribution infrastructure and existing regional health board relationships. Long-term viability hinges on Iceland's national health system sustaining centralized procurement expansion while peripheral regions demand specialized therapy access. The signal to watch is Ministry of Health reimbursement schedule revisions for biologics versus biosimilars, which would indicate formulary preference shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Investment | EMA-qualified temperature control secures biologics access to Landspitali's procurement volume. |
| Serialization Compliance Program | Falsified Medicines Directive readiness prevents exclusion from national reimbursement eligibility. |
| Regional Health Authority Partnership | Akureyri and peripheral hospital clusters offer tender capture outside Reykjavík's procurement concentration. |
| Homecare Distribution Buildout | Direct-to-patient oral therapy delivery bypasses institutional administration cost structures. |
| Biosimilar Portfolio Expansion | Cost-competitive substitutes address Ministry of Health price compression in oncology and neurology. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Icelandic Medicines Agency marketing authorization databases, European Medicines Agency submission records, and Ministry of Health procurement disclosures. Primary interviews engaged regulatory affairs leads at multinational pharmaceutical manufacturers, hospital procurement managers at Landspitali University Hospital and Akureyri regional facilities, formulary directors within Iceland's national health system, and cold-chain logistics operators serving Keflavík International Airport cargo terminals. Bottom-up patient population modeling and top-down pharmaceutical trade flow analysis provided cross-validation.
Forecast inputs span therapy area growth trajectories, reimbursement schedule elasticity, and cold-chain infrastructure expansion timelines across the projection horizon. Segmentation dimensions include product type, delivery mode, end-user channel, and regional regulatory cluster. CAGRs derive from trend extrapolation adjusted for formulary inclusion probability and tender outcome modeling. Industry-specific inputs incorporate Icelandic Medicines Agency review cycle durations and EMA centralized procedure adoption rates.
Stress conditions across currency volatility bands, shipping disruption scenarios, and reimbursement compression thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EMA alignment continuity and national health system procurement centralization. Material shifts in Ministry of Health tender evaluation criteria or EU-EEA pharmaceutical trade protocols would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Seropositive Rheumatoid Arthritis Drug Market
Pharmaceuticals
Global Human Rotavirus Vaccine Market
Pharmaceuticals
Respiratory Disease Vaccine Market
Pharmaceuticals
United States Pharmaceutical 3PL Market
Pharmaceuticals
Europe Pharmaceutical Contract Sales Outsourcing (CSO) Market
Pharmaceuticals
Antimetabolite Drugs Market
Pharmaceuticals
Depression Drugs Market
Pharmaceuticals
Drug Designing Tools Market
Pharmaceuticals
Italy Opioids Market
Pharmaceuticals
Asia Pacific Drug Development Market
Pharmaceuticals
Liver Cancer Drug Market
Pharmaceuticals
Myasthenia Gravis Therapeutics Market
Pharmaceuticals
Human Combination Vaccines Market
Pharmaceuticals
Plasma-Derived Protein Therapies Market
Pharmaceuticals
Sterile Dosage Form Market
Pharmaceuticals
Propofol Market