
 Latin America Pharmaceutical Contract Manufacturing Organization Market | 2026-2036
Latin America Pharmaceutical Contract Manufacturing Organization Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Pharmaceutical Contract Manufacturing Organization Market Foresight
Buyer concentration among large pharmaceutical multinationals is realigning contract negotiation leverage toward sponsors with global volume commitments. Catalent Inc leverages its integrated biologics network to secure long-term sterile manufacturing agreements across Brazil and Mexico. Thermo Fisher Scientific Inc anchors regional capacity through specialized cold-chain fill-finish infrastructure. Lonza Group AG differentiates via advanced therapy medicinal product platforms that serve emerging cell and gene therapy developers.
Pharmaceutical contract manufacturing organizations provide outsourced drug substance and drug product services spanning synthesis, formulation, packaging, and analytical release under sponsor quality systems. Facilities operate under ICH Q7 API guidelines and country-specific GMP frameworks with environmental monitoring, process validation, and batch record review as core operational parameters. API Manufacturing and sterile injectables capture the dominant margin pools given technical barriers and capital intensity. Fill-Finish Technology and advanced therapy medicinal products represent the fastest-expanding technology segments as biologics developers seek specialized capacity that branded generics manufacturers rarely possess in-house.
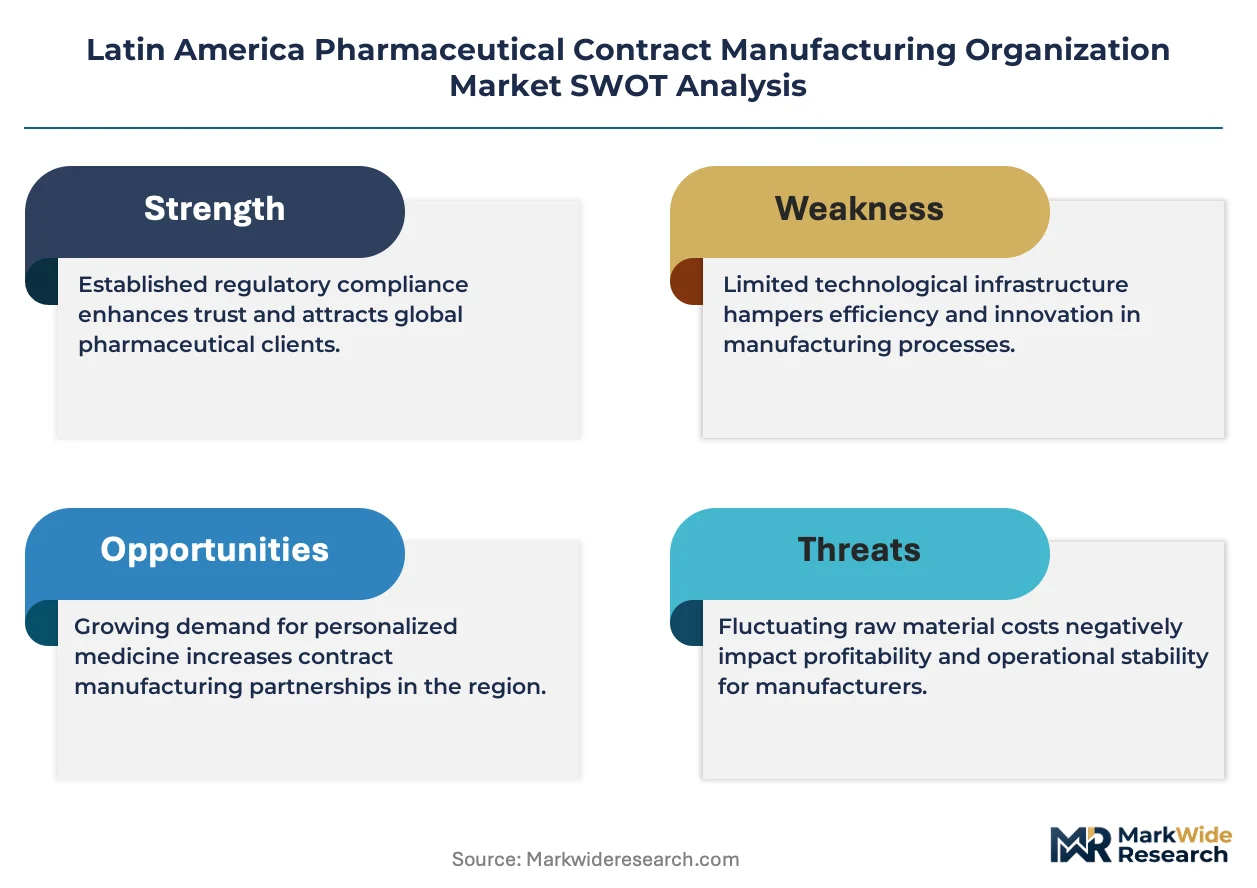
ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia enforce harmonized GMP standards that determine facility approval timelines and cross-border supply eligibility. These regulators conduct risk-based inspections that directly shape capital allocation decisions for new capacity investments. Sponsors must monitor regulatory divergence between Mercosur and Pacific Alliance frameworks when designing multi-country supply strategies.
Market Dynamics
ANVISA's intensified GMP inspection protocols are forcing sponsor companies to consolidate sterile manufacturing partnerships with CDMOs possessing validated aseptic fill-finish capabilities in São Paulo and Buenos Aires.
Growth Catalysts
- Biologics capacity scarcity:Regional developers lack in-house viral vector production for cell and gene therapies, creating captive demand for outsourced ATMP platforms.
- COFEPRIS harmonization:Mexico's alignment with ICH Q7 guidelines accelerates cross-border API sourcing approvals for generic drug sponsors.
- Argentina's cost arbitrage:Buenos Aires manufacturing clusters offer 30-40% operating cost advantages versus US East Coast equivalents for sterile injectable production.
Market Restraints
- Single-source API dependency:Regional formulators rely heavily on Chinese KSM imports, exposing margin stability to shipping lane disruptions and customs delays.
- Capital intensity barriers:Isolator-based aseptic processing lines require $50-80 million per installation, constraining mid-tier CDMO expansion.
- ANVISA inspection backlog:Risk-based facility approval queues extend 18-24 months, freezing capacity utilization for greenfield investments.
Strategic Opportunities
- Colombia's underdeveloped sterile infrastructure:INVIMA's streamlined GMP certification pathway attracts sponsors seeking alternatives to saturated Brazilian capacity.
- Cold-chain biosimilar fill-finish:mAb developers require specialized -70°C storage integration that legacy generic facilities cannot support.
- Mercosur regulatory convergence:Mutual recognition agreements between Brazil, Argentina, and Uruguay reduce duplicate facility audits for multi-country supply strategies.
Industry Challenges
- Aseptic operator certification gaps:Regional training programs produce insufficient personnel qualified in isolator technology and restricted access barrier systems.
- Legacy quality system integration:Paper-based batch records at acquired facilities conflict with sponsor demands for real-time electronic data capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Pharmaceutical Contract Manufacturing Organization Market |
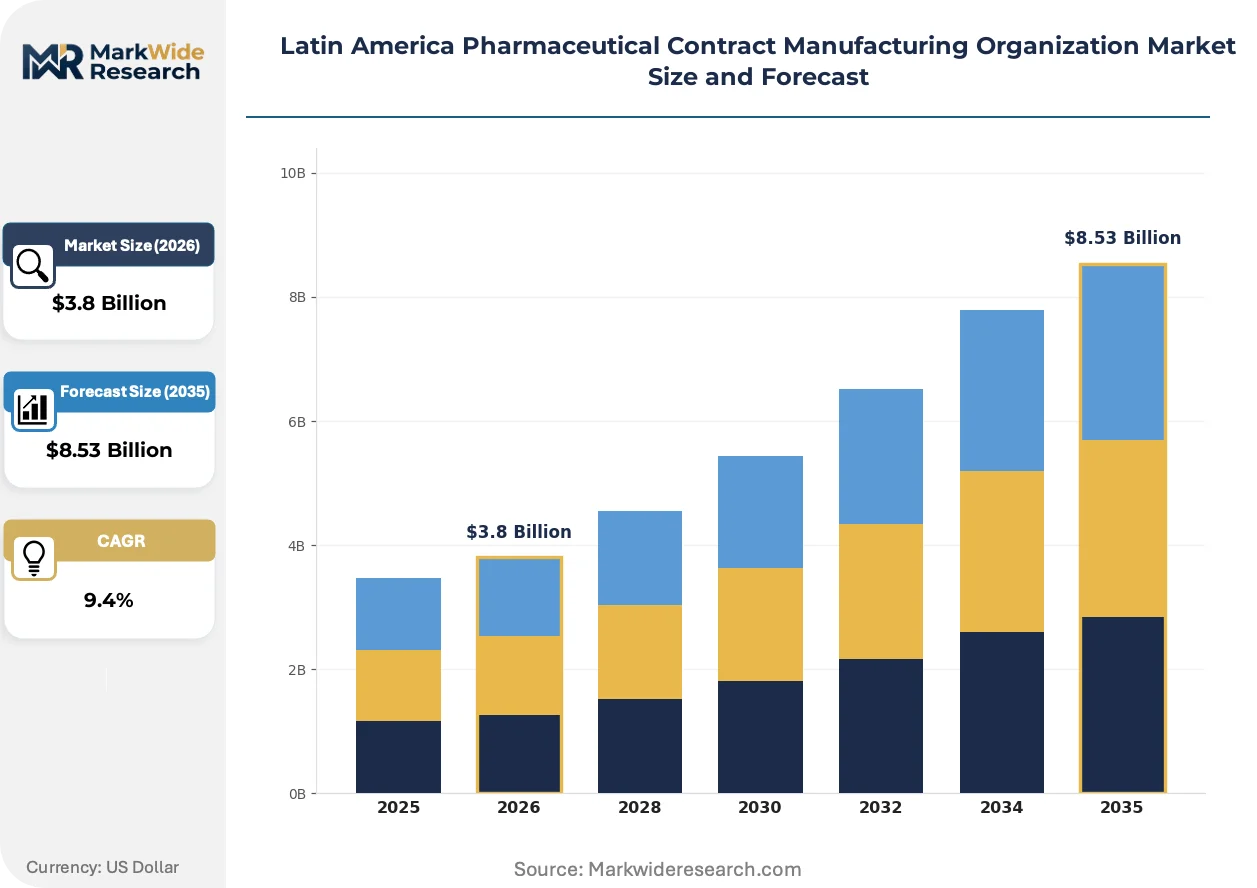
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: API Manufacturing, Formulation Development, Packaging Services, Quality Control End User: Pharmaceutical Companies, Biotech Firms, Virtual Companies, Generics Manufacturers Product Type: Sterile Injectables, Oral Solids, Topicals, Biologics Technology: Continuous Manufacturing, Advanced Therapy Medicinal Products, Fill-Finish Technology, Lyophilization |
| Companies Covered | Catalent Inc, Thermo Fisher Scientific Inc, Lonza Group AG, Boehringer Ingelheim Group, Pfizer CentreSource, Baxter Biopharma Solutions, Acino International AG, Eurofarma Laboratorios S.A., Famar SA, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Pharmaceutical Contract Manufacturing Organization Market Shifts & Advancements
Continuous manufacturing platforms and single-use bioreactor systems are displacing stainless-steel batch operations across Latin American biologics capacity expansions.
Single-use bioreactor technology eliminates CIP/SIP validation cycles and reduces cross-contamination risks for multi-product CDMO facilities. Mid-sized biotech sponsors in Brazil and Mexico are adopting 2000L disposable systems for Phase III mAb production. This shift is rewriting capital deployment patterns, as facilities redirect investment from fixed equipment toward flexible, product-dedicated suites.
ANVISA's implementation of risk-based GMP inspection schedules aligns with PIC/S membership standards and ICH Q9 quality risk management principles. Facilities with prior FDA or EMA approvals receive accelerated domestic certification timelines. Sterile injectable manufacturers with existing US regulatory history capture disproportionate sponsor interest for high-value biologics contracts.
Sponsor procurement teams are consolidating vendor panels from 15-20 CDMO relationships toward 3-5 strategic partnerships with integrated drug substance-to-drug product capabilities. Large pharmaceutical multinationals now demand dedicated capacity blocks and joint technology transfer teams. This concentration is most pronounced among Brazil-based generic drug sponsors seeking supply security for ANDA submissions to FDA.
Latin America Pharmaceutical Contract Manufacturing Organization Market Segmentation
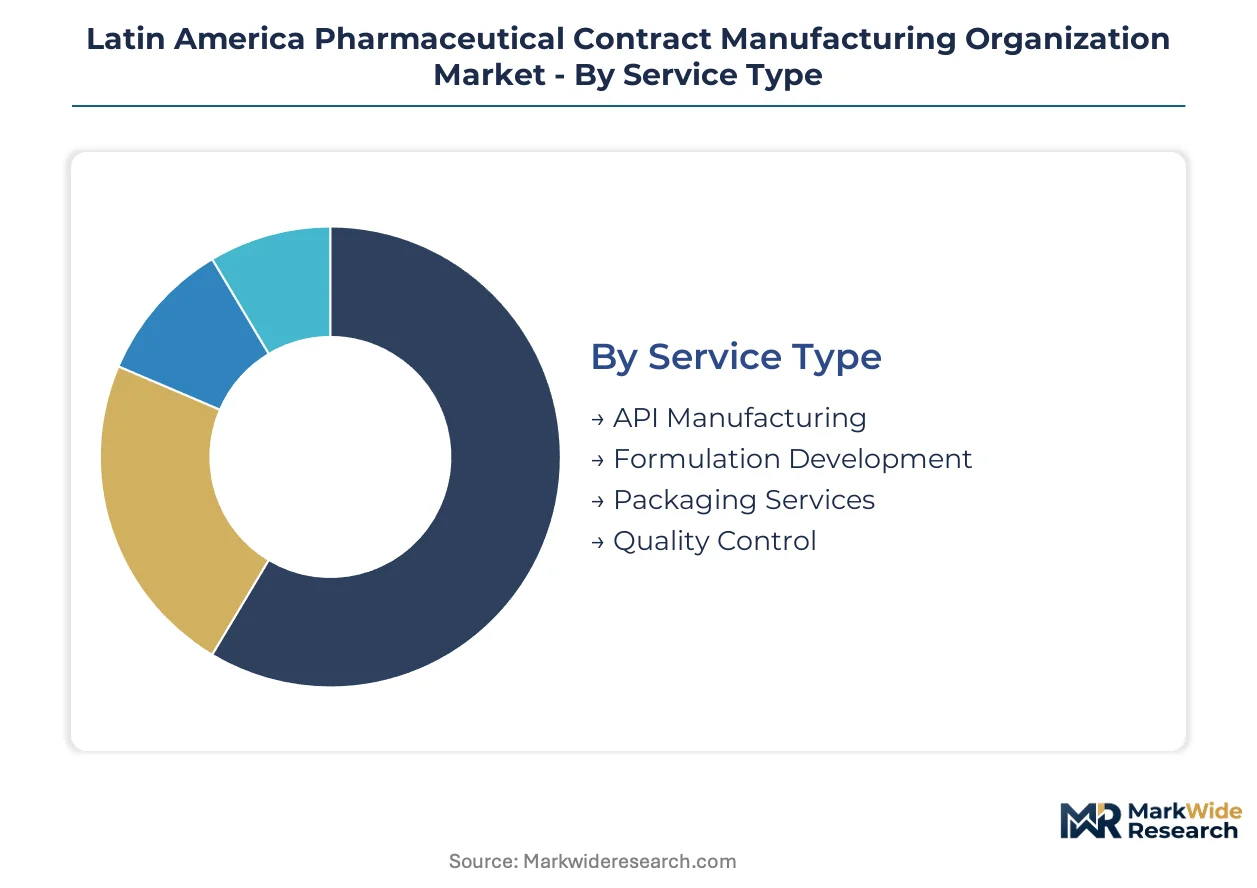
Segmentation reveals how CDMOs allocate capital across distinct capability tiers. Service specialization and technology intensity determine contract pricing power. Understanding these divisions exposes where sponsor procurement teams concentrate vendor consolidation efforts.
Service Type:
Supply concentration favors integrated drug substance-to-drug product providers over standalone service operators.
- API Manufacturing:Active pharmaceutical ingredient synthesis demands ICH Q7-compliant facilities with dedicated reactor trains. Mexican and Brazilian sponsors source complex synthetic intermediates from CDMOs with validated KSM supply chains. ANVISA's tightened GMP protocols are forcing consolidation toward São Paulo-based manufacturers with prior FDA approval histories.
- Formulation Development:Preclinical-to-clinical scale-up services bridge discovery chemistry and commercial manufacturing. Buenos Aires clusters attract Phase I-II sponsors seeking 30-40% cost arbitrage versus US equivalents. Regional biotech firms lack in-house formulation scientists, creating captive demand for outsourced development.
- Packaging Services:Secondary packaging and serialization for Brazil's track-and-trace requirements.
- Quality Control:Release testing and stability studies under sponsor quality systems.
Today's leader: API Manufacturing. Tomorrow's challenger: Formulation Development.
End User:
Customer type determines contract structure complexity and volume commitment terms.
- Pharmaceutical Companies:Large multinationals demand dedicated capacity blocks and joint technology transfer teams. These sponsors consolidate vendor panels from 15-20 relationships toward 3-5 strategic partnerships with integrated capabilities.
- Biotech Firms:Emerging developers lack in-house viral vector production for cell and gene therapies. Mid-sized Brazilian and Mexican biotechs adopt 2000L single-use bioreactor systems for Phase III mAb production, rewriting capital deployment patterns toward flexible suites.
- Virtual Companies:Asset-light developers outsourcing entire manufacturing operations.
- Generics Manufacturers:Brazil-based ANDA sponsors seeking supply security for FDA submissions.
Pharmaceutical Companies anchor current revenue. Biotech Firms are climbing the fastest.
Product Type:
Margin pools concentrate where technical barriers and capital intensity exclude commodity competition.
- Sterile Injectables:Aseptic fill-finish operations command premium contract terms given isolator technology requirements. CDMOs in São Paulo and Buenos Aires with validated capabilities capture disproportionate sponsor interest. Isolator-based processing lines require $50-80 million per installation, constraining mid-tier expansion.
- Biologics:Monoclonal antibody and biosimilar production requires specialized -70°C cold-chain integration. Legacy generic facilities cannot support mAb developers' storage requirements, creating technology-driven supplier selection.
- Oral Solids:Tablet and capsule manufacturing for high-volume generic portfolios.
- Topicals:Cream, ointment, and transdermal formulation services.
Sterile Injectables dominate contract value. Biologics show the steepest expansion trajectory.
Technology:
Platform selection determines facility flexibility and multi-product campaign economics.
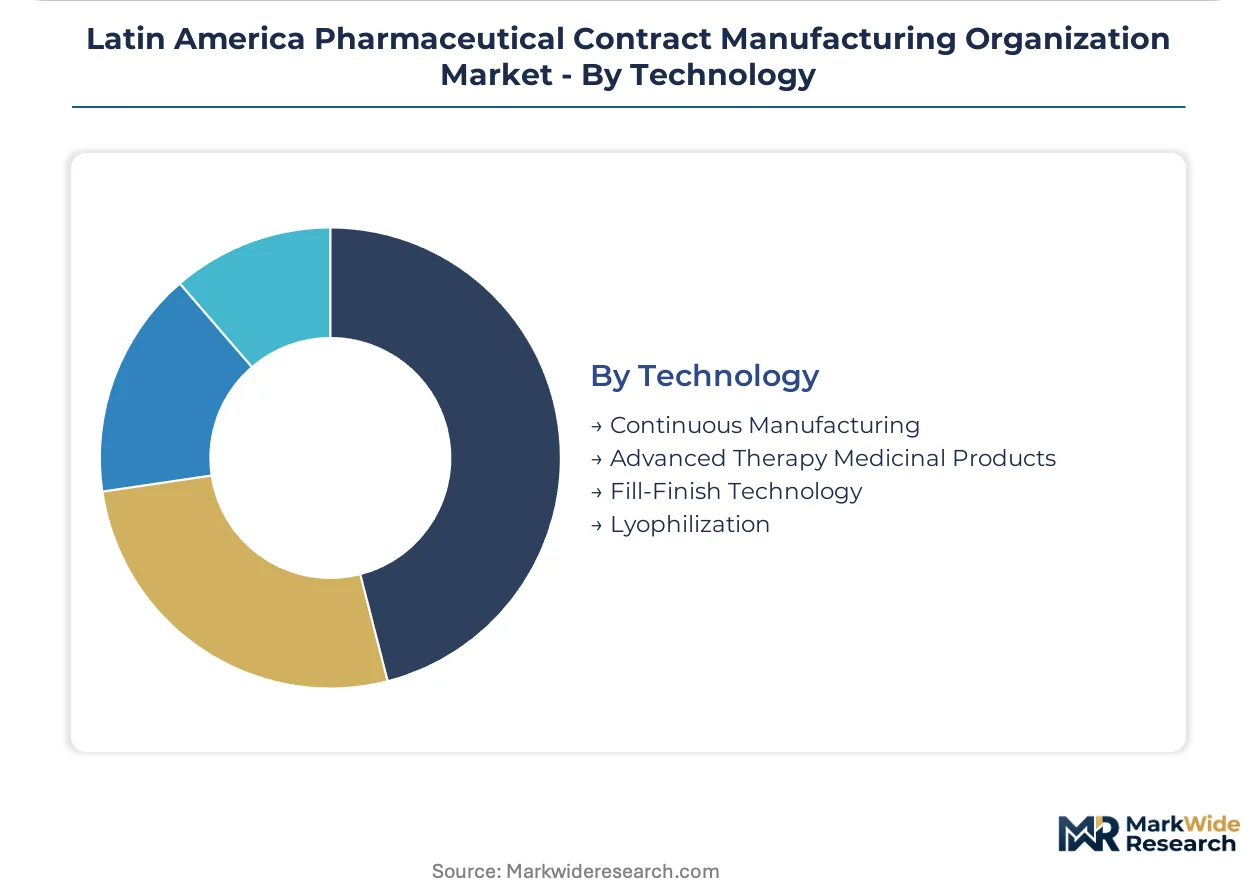
- Advanced Therapy Medicinal Products:Cell and gene therapy platforms serve developers lacking in-house viral vector production. Lonza Group AG differentiates via ATMP capabilities that emerging regional developers cannot replicate internally.
- Fill-Finish Technology:Aseptic processing and closed-system vial filling for biologics stability. Catalent Inc leverages integrated networks to secure long-term sterile manufacturing agreements across Brazil and Mexico.
- Continuous Manufacturing:Flow chemistry platforms displacing batch operations in API synthesis.
- Lyophilization:Freeze-drying capacity for thermally sensitive parenteral products.
Fill-Finish Technology anchors current infrastructure investment. Advanced Therapy Medicinal Products gain share fastest as cell and gene therapy pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled aseptic technicians and pharmaceutical engineers concentrate in São Paulo, Buenos Aires, and Mexico City, anchoring sterile manufacturing capacity across the region. This talent distribution shapes where CDMOs expand isolator-based fill-finish lines and where sponsors consolidate partnership decisions.
Brazil
ANVISA's risk-based GMP inspection protocols force generic drug sponsors toward CDMOs with validated sterile capabilities. The regulator's 18-24 month approval backlog for greenfield facilities concentrates expansion among existing São Paulo manufacturers with prior FDA histories. São Paulo's Osasco industrial corridor hosts the dominant share of isolator-equipped aseptic processing lines serving biologics developers.
Mexico
COFEPRIS alignment with ICH Q7 guidelines accelerates cross-border API sourcing approvals for generic drug manufacturers. The regulator's harmonization with international standards reduces duplicate documentation for sponsors filing ANDAs with FDA. Mexico City and Querétaro manufacturing clusters attract sterile injectable investments from sponsors seeking proximity to US distribution networks.
Argentina
Buenos Aires manufacturing clusters offer 30-40% operating cost advantages versus US East Coast equivalents for sterile injectable production. The national pharmaceutical regulator enforces PIC/S-aligned GMP standards that facilitate Mercosur cross-border supply eligibility. Pilar and Garín industrial zones concentrate fill-finish capacity expansion as Brazilian sponsors seek cost arbitrage for high-volume generic portfolios.
Colombia
INVIMA's streamlined GMP certification pathway attracts sponsors seeking alternatives to saturated Brazilian sterile infrastructure. The regulator's risk-based inspection model reduces facility approval timelines versus ANVISA's extended queues. Bogotá's Fontibón industrial district emerges as a secondary fill-finish hub for mid-tier CDMOs avoiding São Paulo capacity constraints.
Chile
Santiago's pharmaceutical manufacturing base remains concentrated in oral solid dosage forms with limited sterile injectable infrastructure. The national health regulator enforces ICH-aligned standards that support regional export eligibility for established facilities. Quilicura and Pudahuel industrial zones host formulation development services rather than commercial-scale aseptic production.
Latin America Pharmaceutical Contract Manufacturing Organization Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists for sponsor contracts across Latin America. The market structure concentrates among integrated drug substance-to-drug product providers with validated regulatory histories in multiple jurisdictions. Three archetypes dominate: global CDMO networks with regional sterile capacity, Latin America-focused generics manufacturers with CDMO divisions, and emerging biologics specialists with single-use platform investments. Competitive moves center on dedicated capacity block agreements and joint technology transfer team deployments.
Among global network operators, Catalent Inc, Thermo Fisher Scientific Inc, and Lonza Group AG exemplify the integrated capability archetype. These companies occupy positions where sponsor procurement teams consolidate vendor panels toward strategic partnerships with end-to-end service coverage. Their presence anchors premium contract terms for sterile injectable and advanced therapy medicinal product platforms that regional mid-tier competitors cannot replicate.
| Leading Market Players |
|---|
| Catalent Inc |
| Thermo Fisher Scientific Inc |
| Lonza Group AG |
| Boehringer Ingelheim Group |
| Pfizer CentreSource |
| Baxter Biopharma Solutions |
| Acino International AG |
| Eurofarma Laboratorios S.A. |
| Famar SA |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up CDMO specialists in São Paulo and Buenos Aires impose stricter capacity allocation discipline than family-owned Mexican mid-caps, compressing spot-market pricing for non-dedicated sterile manufacturing slots while elevating long-term contract premiums for validated isolator suites.
Pricing Analysis
Bundled drug substance-to-drug product services command 25-40% contract premiums over unbundled standalone offerings across São Paulo and Mexico City facilities. Price differentiation rests on FDA approval history and ANVISA inspection track record as dual certification tiers. Cost compression in commodity oral solid dosage runs through aggressive Chinese API import competition. Virtual biotech firms exhibit highest price sensitivity, while large pharmaceutical multinationals prioritize supply security over unit economics.
Supply Chain Analysis
Direct-to-sponsor channels handle multinational volume commitments, while regional distributor networks serve mid-tier generic manufacturers across Brazil, Mexico, and Argentina. Active pharmaceutical ingredient supply draws from validated Chinese and Indian KSM sources, with key starting material dependencies concentrated in Zhejiang and Gujarat manufacturing clusters. Single-source API vulnerability from East Asian shipping lane disruptions poses structural risk. Distribution runs through cold-chain logistics partnerships anchored in São Paulo and Mexico City.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through isolator technology premiums and single-use bioreactor cost-down curves, with sterile injectable capacity scarcity supporting pricing power across São Paulo and Buenos Aires clusters.
For Market Incumbents: Lock in dedicated capacity blocks with Brazilian generic sponsors filing ANDAs to FDA, preempting emerging biologics specialists from capturing sponsor procurement consolidation. Expand Buenos Aires fill-finish lines to exploit 30-40% operating cost arbitrage versus US East Coast equivalents. ANVISA's 18-24 month greenfield approval backlog protects existing São Paulo facilities from new entrant capacity.
For New Entrants and Emerging Players: COFEPRIS alignment with ICH Q7 guidelines in Mexico opens a window for API manufacturing specialists to capture cross-border sourcing approvals from generic drug sponsors. Target Colombia's underdeveloped sterile infrastructure, where INVIMA's streamlined GMP certification pathway avoids São Paulo capacity saturation. Lead with single-use bioreactor platforms for Phase III mAb production to differentiate from legacy stainless-steel batch operations.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier CDMOs lacking FDA approval histories but possessing ANVISA-validated isolator capacity. Long-term viability hinges on Mercosur regulatory convergence enabling multi-country supply strategies across Brazil, Argentina, and Uruguay. Watch for ANVISA inspection backlog clearance as inflection signal for greenfield investment viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Certification | ANVISA risk-based inspections accelerate approvals for facilities with prior FDA histories. |
| Single-Use Bioreactor Deployment | Disposable 2000L systems eliminate CIP/SIP cycles for Brazilian Phase III mAb sponsors. |
| Mercosur Regulatory Convergence | Mutual recognition agreements reduce duplicate facility audits across Brazil and Argentina. |
| Cold-Chain Fill-Finish Integration | Specialized -70°C storage capacity attracts biosimilar developers away from legacy generic facilities. |
| Joint Technology Transfer Teams | Dedicated sponsor collaboration structures secure long-term sterile manufacturing agreements. |
Research Methodology
Coverage spans Brazil, Mexico, Argentina, Colombia, and Chile, with primary inputs from each market's regulatory cluster and manufacturing corridor. The analysis combines structured interviews with drug development executives, regulatory affairs leads at ANVISA and COFEPRIS, sterile manufacturing plant managers, and hospital procurement directors with secondary validation from FDA filing databases, ANVISA inspection records, ClinicalTrials.gov entries, and regional customs trade data. Bottom-up capacity utilization models and top-down sponsor spending estimates undergo rigorous triangulation.
Granularity extends to service type, end-user archetype, product category, and technology platform across the projection horizon. Segmentation dimensions include API manufacturing versus fill-finish specialization, pharmaceutical company versus biotech firm customer tiers, sterile injectable versus biologics product types, and advanced therapy medicinal product versus continuous manufacturing technology platforms. CAGRs derive from facility expansion pipelines, sponsor outsourcing intention surveys, and regulatory approval timeline trajectories. Forecast inputs incorporate ANVISA inspection backlog dynamics and single-use bioreactor adoption curves.
Revisions become necessary when ANVISA implements accelerated inspection protocols, Mercosur regulatory harmonization stalls, or Chinese KSM supply disruptions trigger API sourcing shifts. Forecasts reflect documented assumptions regarding sponsor procurement consolidation rates and isolator technology investment cycles. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
US Transdermal Drug Delivery System Market
Pharmaceuticals
Tenecteplase Drugs Market
Pharmaceuticals
Epigenetics Drugs and Diagnostic Technologies Market
Pharmaceuticals
Small Molecules Contract Development and Manufacturing Organization Market
Pharmaceuticals
Global Corticosteroids Market
Pharmaceuticals
Asia-Pacific Contraceptives Market
Pharmaceuticals
Global Plasma Derived Therapy Market
Pharmaceuticals
Europe Pharmaceutical Contract Sales Outsourcing (CSO) Market
Pharmaceuticals
Germany Pharmaceutical Cold Chain Logistics Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
Global Bronchodilators Market
Pharmaceuticals
Mycoses Treatment Market
Pharmaceuticals
Amlodipine Besylate Market
Pharmaceuticals
Middle East and Africa Laxative Market
Pharmaceuticals
Atypical Antipsychotic Market
Pharmaceuticals
Human Papillomavirus (HPV) Vaccine Market