
 Alkylating Agents Market | 2026-2036
Alkylating Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Alkylating Agents Market Outlook
Buyer concentration among hospital networks and large oncology group purchasing organizations is hardening as health systems consolidate formulary control. Pfizer Inc. leverages its institutional sales infrastructure to sustain direct relationships with integrated delivery networks. Novartis AG anchors its position through specialized oncology distribution channels that serve concentrated buyer clusters. Teva Pharmaceutical Industries Ltd. competes aggressively on generic cyclophosphamide and ifosfamide volumes within these tightening procurement structures.
Alkylating agents constitute a class of cytotoxic compounds characterized by electrophilic alkyl groups that covalently bind DNA bases, inducing cross-links and strand breaks that disrupt replication in rapidly dividing cells; nitrogen mustard derivatives and oxazaphosphorines remain the dominant chemical architectures, typically administered via intravenous infusion with established dosing protocols calibrated to body surface area. Among product types, cyclophosphamide occupies the largest revenue pool due to its breadth across oncology and autoimmune protocols, while ifosfamide carves a specialized niche in sarcoma regimens where mesna co-administration protects against hemorrhagic cystitis. Hospital end users command the dominant share of volume throughput, though research labs represent a higher-margin channel for investigational combinations and biomarker-directed trials.
FDA oncology guidance and EMA's Committee for Medicinal Products for Human Use shape clinical trial endpoints and labeling requirements that determine market access for new alkylating formulations, while ISO 13485 and GMP standards govern manufacturing consistency for sterile injectable production. The EPA and OSHA frameworks regulate handling protocols and occupational exposure limits for cytotoxic compound manufacturing facilities. Stakeholders must monitor evolving biosimilar pathways and pharmacovigilance requirements that will reshape competitive positioning in institutional procurement.
Market Dynamics
Hospital network consolidation is compressing formulary autonomy into fewer procurement committees, concentrating purchasing power among integrated delivery networks that negotiate directly with manufacturers for alkylating agent volumes.
Growth Catalysts
- FDA Accelerated Approval:Compressed oncology trial timelines enable faster market entry for novel alkylating formulations, expanding therapeutic options for hematologic malignancies.
- Medicare Reimbursement Stability:Sustained coverage for established agents like cyclophosphamide and bendamustine preserves high-volume utilization across US hospital networks.
- Hematologic Malignancy Protocols:Expanding oncology departments are standardizing alkylating-based regimens as first-line therapy, driving institutional procurement commitments.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Sterile injectable manufacturing for oxazaphosphorines depends on concentrated Asian API suppliers, exposing supply chains to geopolitical disruption.
- REACH Compliance Burden:ECHA registration requirements for cytotoxic compound handling impose documentation costs that disadvantage smaller European manufacturers.
- CAR-T Cell Therapy Substitution:Cellular immunotherapies are displacing alkylating agents in select lymphoma indications, threatening volume erosion in premium oncology segments.
Strategic Opportunities
- Biosimilar Pathway Expansion:FDA and EMA evolving guidance for complex generic alkylating formulations creates entry routes for cost-competitive manufacturers.
- Research Laboratory Channel:Biomarker-directed trial demand for investigational combinations offers higher-margin positioning outside commoditized hospital procurement.
- India CDSCO Streamlining:Centralized oncology drug approval processes are reducing time-to-market for manufacturers targeting hospital networks in Mumbai and Delhi clusters.
Industry Challenges
- Sterile Injectable Manufacturing Expertise:GMP-compliant aseptic processing capabilities for cytotoxic compounds remain scarce, constraining capacity expansion.
- Pharmacovigilance Integration:Post-market safety monitoring requirements for alkylating agents demand specialized adverse event reporting infrastructure that smaller manufacturers struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alkylating Agents Market |
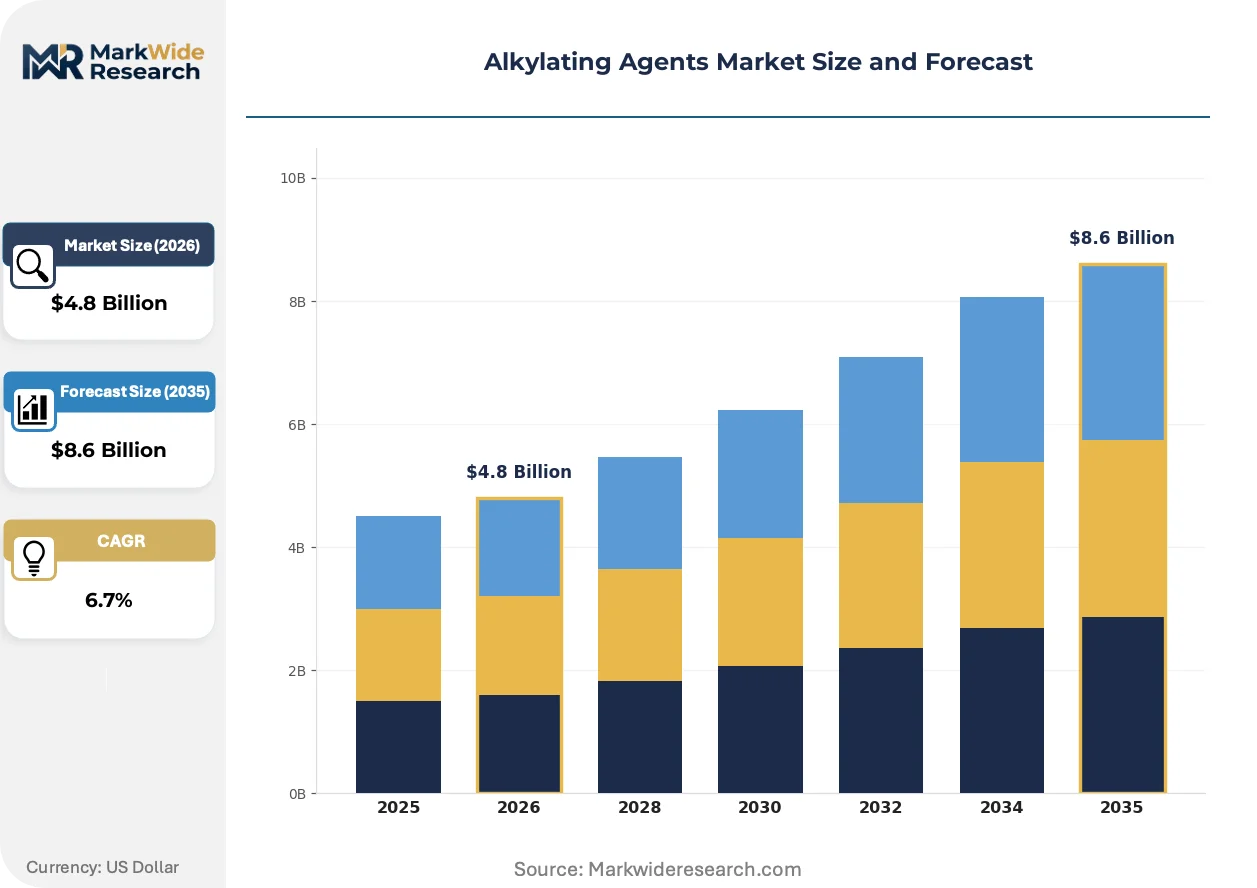
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chlorambucil, Cyclophosphamide, Ifosfamide, Busulfan Application: Cancer Treatment, Autoimmune Disorders, Organ Transplantation, Hormonal Therapy End User: Hospitals, Clinics, Research Labs, Long-term Care Facilities Distribution Channel: Pharmacies, Online Pharmacies, Direct Sales, Wholesalers |
| Companies Covered | Pfizer Inc., Novartis AG, Teva Pharmaceutical Industries Ltd., AstraZeneca, Sanofi, Merck & Co., Inc., GlaxoSmithKline plc, Fresenius Kabi AG, Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alkylating Agents Market Strategic Shifts
Alkylating agent development is pivoting toward precision delivery mechanisms that minimize off-target toxicity while preserving DNA cross-linking efficacy against malignant cells.
Antibody-drug conjugates incorporating alkylating payloads is converging with companion diagnostic screening to identify patients with specific tumor antigen profiles. Academic medical centers in Boston and Heidelberg are piloting these combinations in early-phase trials. This convergence is compressing the traditional separation between chemotherapy and targeted therapy categories in hospital formularies.
EMA's Committee for Medicinal Products for Human Use has tightened requirements for oncology trial endpoints, mandating overall survival data alongside progression-free survival for full marketing authorization. Manufacturers must now design larger, longer trials to satisfy labeling standards. European hospital networks are delaying adoption of agents lacking comprehensive survival data, privileging established cyclophosphamide regimens.
Integrated delivery networks are consolidating formulary control through centralized pharmacy and therapeutics committees that override individual physician preferences. Regional hospital systems in Texas and Pennsylvania are deploying this model to standardize alkylating agent selection across dozens of facilities. This concentration is most visible in the United States, where three-tier health system hierarchies now dominate oncology drug procurement decisions.
Alkylating Agents Market Segmentation
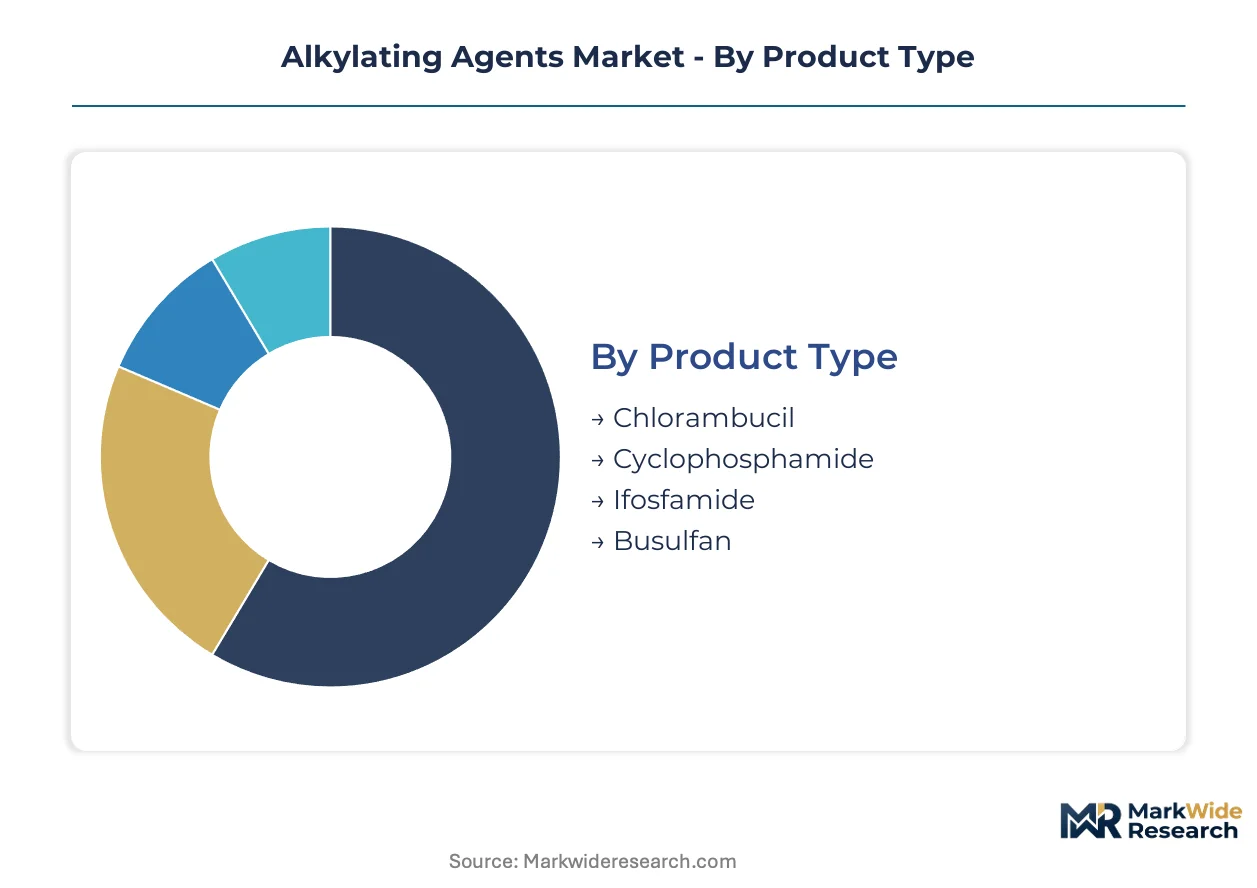
Alkylating agent procurement decisions pivot on clinical protocol requirements, reimbursement pathways, and sterile supply chain reliability. Hospital formulary committees evaluate each segment through the lens of therapeutic index, administration logistics, and total cost of care across oncology and autoimmune indications.
Product Type:
Cost tier stratification separates high-volume generics from specialized hospital-administered agents with complex handling requirements.
- Cyclophosphamide:Oxazaphosphorine prodrug activated by hepatic CYP450 enzymes to phosphoramide mustard, the DNA cross-linking metabolite. Demand concentrates in United States hospital networks where Medicare reimbursement sustains high-volume utilization across lymphoma, leukemia, and autoimmune protocols; procurement committees favor its established safety profile and broad compendia listings.
- Ifosfamide:Structural isomer of cyclophosphamide requiring mesna co-administration to prevent urothelial toxicity from acrolein metabolites. Sarcoma treatment centers in Germany and United States drive specialized demand; institutional buyers accept premium pricing for mesna-bundled procurement to mitigate hemorrhagic cystitis risk.
- Chlorambucil:Nitrogen mustard derivative with oral bioavailability serving chronic lymphocytic leukemia maintenance protocols.
- Busulfan:Alkylsulfonate agent penetrating blood-brain barrier for conditioning regimens prior to hematopoietic stem cell transplantation.
Volume sits with cyclophosphamide; growth tilts toward ifosfamide as sarcoma protocols expand in academic medical centers.
Application:
Maturity curves diverge sharply between commoditized oncology indications and emerging autoimmune deployment.
- Cancer Treatment:Hematologic malignancy protocols—lymphoma, leukemia, multiple myeloma—constitute the dominant revenue pool. United States integrated delivery networks standardize cyclophosphamide-based regimens as first-line therapy, while German university hospitals anchor European demand for dose-intensive conditioning protocols.
- Autoimmune Disorders:Off-label deployment in lupus nephritis, vasculitis, and severe rheumatoid arthritis is gaining share fastest as rheumatology-hematology collaboration expands in United States academic centers; prior authorization requirements constrain but do not block reimbursement.
- Organ Transplantation:Busulfan-containing conditioning regimens for allogeneic stem cell transplantation.
- Hormonal Therapy:Historical use in metastatic breast cancer, now largely supplanted by targeted endocrine agents.
Revenue concentrates in cancer treatment; autoimmune applications are climbing the fastest as rheumatology formularies loosen.
End User:
Customer type determines margin structure, with research channels commanding premium pricing over commoditized hospital procurement.
- Hospitals:Inpatient oncology units and infusion centers handle the majority of intravenous alkylating agent administration. Three-tier United States health system hierarchies—academic medical centers, community hospital networks, rural access hospitals—stratify procurement sophistication and formulary autonomy.
- Research Labs:Biomarker-directed trial demand for investigational combinations offers higher-margin positioning outside commoditized procurement; Boston and Heidelberg academic medical centers pilot antibody-drug conjugates with alkylating payloads.
- Clinics:Community oncology practices administering oral chlorambucil and cyclophosphamide.
- Long-term Care Facilities:Limited role in palliative oncology and chronic immunosuppression.
Procurement volume aggregates at hospitals; margin expansion favors research labs with companion diagnostic requirements.
Distribution Channel:
Supply chain configuration directly shapes pricing power and inventory risk allocation between manufacturers and institutional buyers.
- Direct Sales:Manufacturer relationships with integrated delivery networks bypass distributor markups for high-volume cyclophosphamide and bendamustine contracts. Pfizer and Novartis field organizations negotiate directly with United States hospital system pharmacy and therapeutics committees.
- Wholesalers:McKesson, AmerisourceBergen, and Cardinal Health distribute generic oxazaphosphorines to fragmented community hospital and clinic accounts; consolidated buying groups extract volume discounts.
- Pharmacies:Retail and specialty pharmacy channels for oral chlorambucil and maintenance cyclophosphamide.
- Online Pharmacies:Emerging channel for patient-directed oral agent fulfillment with cold-chain logistics requirements.
Contract volume flows through direct sales; channel development is expanding most quickly in online pharmacy infrastructure for oral agents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital network consolidation concentrates alkylating agent procurement in select markets where integrated delivery systems command pricing leverage. Medicare reimbursement stability sustains high-volume utilization in the United States, while European university hospitals anchor demand for specialized conditioning protocols.
United States
Three-tier health system hierarchies dominate oncology drug procurement, with academic medical centers, community networks, and rural access hospitals stratifying formulary sophistication. FDA accelerated approval pathways compress development timelines for novel alkylating formulations. The Texas Medical Center in Houston and Pennsylvania health systems standardize cyclophosphamide-based regimens across dozens of facilities.
Germany
University hospitals in Heidelberg and Berlin anchor European demand for dose-intensive conditioning protocols prior to hematopoietic stem cell transplantation. EMA Committee for Medicinal Products for Human Use mandates overall survival data alongside progression-free survival for full marketing authorization. The Heidelberg academic medical center pilots antibody-drug conjugates with alkylating payloads in early-phase trials.
India
Centralized oncology drug approval processes through CDSCO reduce time-to-market for manufacturers targeting hospital networks in Mumbai and Delhi clusters. REACH compliance burdens for cytotoxic compound handling impose documentation costs that disadvantage smaller European manufacturers, creating opportunity for Indian suppliers. The Mumbai hospital corridor expands procurement of alkylating-based regimens for hematologic malignancies.
Japan
PMDA oncology guidance shapes clinical trial endpoints and labeling requirements that determine market access for new alkylating formulations. METI frameworks support manufacturing consistency for sterile injectable production. The Kanto region around Tokyo concentrates hospital end users commanding dominant volume throughput.
Switzerland
Swissmedic standards govern manufacturing consistency for sterile injectable production serving European hospital networks. Specialized oncology distribution channels serve concentrated buyer clusters across the Basel and Zurich pharmaceutical corridors. Swiss hospital procurement committees privilege established agents with comprehensive survival data.
Alkylating Agents Market Competitive Environment
United States producers anchor one tier; European specialists hold differentiated positions through regulatory sophistication. The vendor base stratifies across three tiers: diversified pharmaceutical conglomerates with institutional sales infrastructure, specialized oncology distributors serving concentrated buyer clusters, and generic manufacturers competing on oxazaphosphorine volumes. Strategic archetypes include formulary-integrated incumbents, mesna-bundled specialists, and cost-positioned volume players. Dominant competitive moves include direct contracting with integrated delivery networks and backward integration into sterile injectable manufacturing capabilities.
Within the diversified pharmaceutical tier, Pfizer Inc. and Novartis AG occupy positions sustained through institutional sales infrastructure and specialized oncology distribution channels respectively. Teva Pharmaceutical Industries Ltd. exemplifies the generic volume archetype, competing on cyclophosphamide and ifosfamide procurement within tightening hospital formulary structures. These three entities represent the spectrum of competitive positioning from premium institutional relationships to commoditized volume capture.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| AstraZeneca |
| Sanofi |
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Fresenius Kabi AG |
| Bristol-Myers Squibb |
| Others |
Value Chain & Pricing Dynamics
Active pharmaceutical ingredient costs for oxazaphosphorines cascade through three pricing tiers as sterile injectable manufacturing expertise concentrates among GMP-certified facilities in India and China, with freight and cold-chain logistics adding differential premiums to landed costs in United States and European hospital networks.
Pricing Analysis
High-volume cyclophosphamide procurement concentrates in commoditized contract tiers where Teva and Fresenius Kabi compete on generic unit economics, while ifosfamide-mesna bundles and novel antibody-drug conjugates command premium positioning in academic medical centers. Price differentiation rests on GMP certification tier and sterile manufacturing capability scarcity rather than brand equity alone. Cost compression in the generic oxazaphosphorine tier is intensifying as Indian CDSCO-approved manufacturers expand capacity. Community hospital networks exhibit highest price sensitivity; research laboratories demonstrate lowest sensitivity due to biomarker-directed trial budgets.
Supply Chain Analysis
Cold-chain freight costs for cytotoxic sterile injectables impose geographic premiums that amplify price spreads between Asian manufacturing hubs and end-user hospitals in the United States and Germany. API production concentrates in India and China, with final formulation and aseptic fill-finish anchored in United States and European facilities. Raw material dependencies span phosphorus oxychloride, ethylene oxide, and specialized excipients for lyophilization. Single-source vulnerability in mesna co-formulation supply creates exposure for ifosfamide regimens. Distribution runs through McKesson and AmerisourceBergen for fragmented accounts, while direct manufacturer contracts dominate integrated delivery network procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance and FDA sterile manufacturing standards have erected regulatory moats that favor incumbent players with established pharmacovigilance infrastructure and GMP-certified capacity, raising effective barriers for undercapitalized entrants.
For Market Incumbents: Extend formulary integration through direct contracting with Texas and Pennsylvania health system hierarchies, locking in cyclophosphamide volume commitments before biosimilar pathways mature. Deepen backward integration into API manufacturing to offset Asian supply chain exposure. Prioritize mesna-bundled ifosfamide positioning in sarcoma centers to defend margin against CAR-T substitution in lymphoma segments. For New Entrants and Emerging Players: Capture the research laboratory channel in Boston and Heidelberg academic medical centers, where biomarker-directed trial demand for antibody-drug conjugate payloads escapes commoditized hospital procurement. Target CDSCO streamlined approval pathways for Mumbai and Delhi hospital network entry. Lead with companion diagnostic partnerships rather than standalone alkylating formulations to bypass entrenched formulary control. For Investors and Strategic Acquirers: FDA accelerated approval pathway utilization rates for novel alkylating payloads are the leading indicator that precision delivery mechanisms will reshape competitive positioning within the analysis window. Long-term viability favors manufacturers with captive sterile injectable capacity and established integrated delivery network relationships. Watch for consolidation signals when European REACH compliance burdens force smaller manufacturers toward distressed divestiture.| Strategic Initiative | Industry Significance |
|---|---|
| GMP-Certified Capacity Expansion | FDA and EMA sterile manufacturing standards constrain qualified suppliers, privileging early movers in aseptic cytotoxic processing. |
| Companion Diagnostic Partnership | Antibody-drug conjugate development in Boston and Heidelberg trials requires biomarker screening infrastructure for patient selection. |
| Direct IDN Contracting | Three-tier United States health system hierarchies in Texas and Pennsylvania consolidate procurement through centralized pharmacy committees. |
| Backward API Integration | Phosphorus oxychloride and ethylene oxide supply concentration in India and China creates exposure for formulation-dependent manufacturers. |
| CDSCO Regulatory Pathway Navigation | Centralized oncology approval processes in India reduce time-to-market for manufacturers targeting Mumbai and Delhi hospital clusters. |
Study Parameters
FDA filings, EMA Committee for Medicinal Products for Human Use opinions, and ClinicalTrials.gov protocol databases formed the secondary backbone, cross-referenced with primary interviews involving hospital formulary directors, GPO contracts managers, sterile manufacturing plant managers, and regulatory affairs leads at alkylating agent manufacturers. Bottom-up segmentation modeling triangulated against top-down therapeutic class expenditure analysis derived from Medicare claims patterns and European hospital procurement databases.
Historical trendline analysis tracked cyclophosphamide, ifosfamide, and bendamustine utilization patterns across United States integrated delivery networks and German university hospitals, with projection frameworks modeling patient population incidence, protocol standardization rates, and substitution dynamics from cellular immunotherapies. Segmentation dimensions spanned product type, application indication, end-user channel, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted volume forecasts and pricing tier trajectories calibrated to reimbursement stability assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CAR-T therapy substitution rates, REACH compliance burden evolution, and Asian API supply disruption scenarios. Forecasts reflect documented assumptions regarding Medicare reimbursement continuity and EMA labeling requirement stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Subcutaneous Immunoglobulin Market
Pharmaceuticals
Omeprazole Market
Pharmaceuticals
Pharma PLM Market
Pharmaceuticals
Dermatological Drugs Market
Pharmaceuticals
Sleeping Medications Market
Pharmaceuticals
Anti Obesity Prescription Drugs Market
Pharmaceuticals
Global Divalproex Sodium Market
Pharmaceuticals
Anti-Obesity Drugs Market
Pharmaceuticals
Asia-Pacific Anesthesia Drugs Market
Pharmaceuticals
Thin Film Drug Manufacturing Market
Pharmaceuticals
Anastrozole Tablets Market
Pharmaceuticals
Middle East and Africa Anti-Fungal Agents Market
Pharmaceuticals
Ceftriaxone Sodium (API) Market
Pharmaceuticals
Zoldonat Injection Market
Pharmaceuticals
TNF Inhibitors Market
Pharmaceuticals
BRAF-MEK Inhibitors Market