
 Global Anticoccidial Drugs Market | 2026-2036
Global Anticoccidial Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anticoccidial Drugs Market Foresight
Veterinary pharmaceutical distribution is tilting toward direct partnerships between manufacturers and integrated poultry producers, bypassing traditional wholesale layers. MSD Animal Health leverages its broad ionophore portfolio to sustain long-term supply contracts with multinational protein companies. Zoetis anchors its position through geographic dominance in Latin American markets where coccidiosis pressure remains severe year-round.
Anticoccidial drugs are veterinary parasiticides formulated as ionophores, chemical agents, synthetic compounds, or herbal extracts to prevent or treat protozoan infections caused by Eimeria species in livestock, typically administered at precise dosage rates measured in grams per ton of feed. Their primary commercial purpose is safeguarding feed conversion ratios and mortality rates in intensive animal production systems where subclinical coccidiosis erodes profit margins. The ionophore category occupies the largest revenue share due to decades of proven efficacy and established resistance management protocols, while synthetic compounds represent the fastest-expanding segment as regulatory pressure on ionophore residues intensifies across major protein-exporting jurisdictions. Feed manufacturers constitute the most concentrated end-user channel, capturing substantial margin pools through premix formulation and medicated feed licensing.
The FDA Center for Veterinary Medicine oversees anticoccidial approval pathways and residue tolerance thresholds in the United States, while the EMA's Committee for Medicinal Products for Veterinary Use shapes European market access through benefit-risk assessments that increasingly scrutinize ionophore cross-resistance with human therapeutics. China's NMPA and Ministry of Agriculture enforce GB standards for veterinary drug maximum residue limits, creating divergent compliance requirements for exporters serving multiple protein markets. Stakeholders must monitor evolving regulatory divergence between major import jurisdictions to anticipate which formulation classes will retain market access and where reformulation investments will yield sustainable returns.
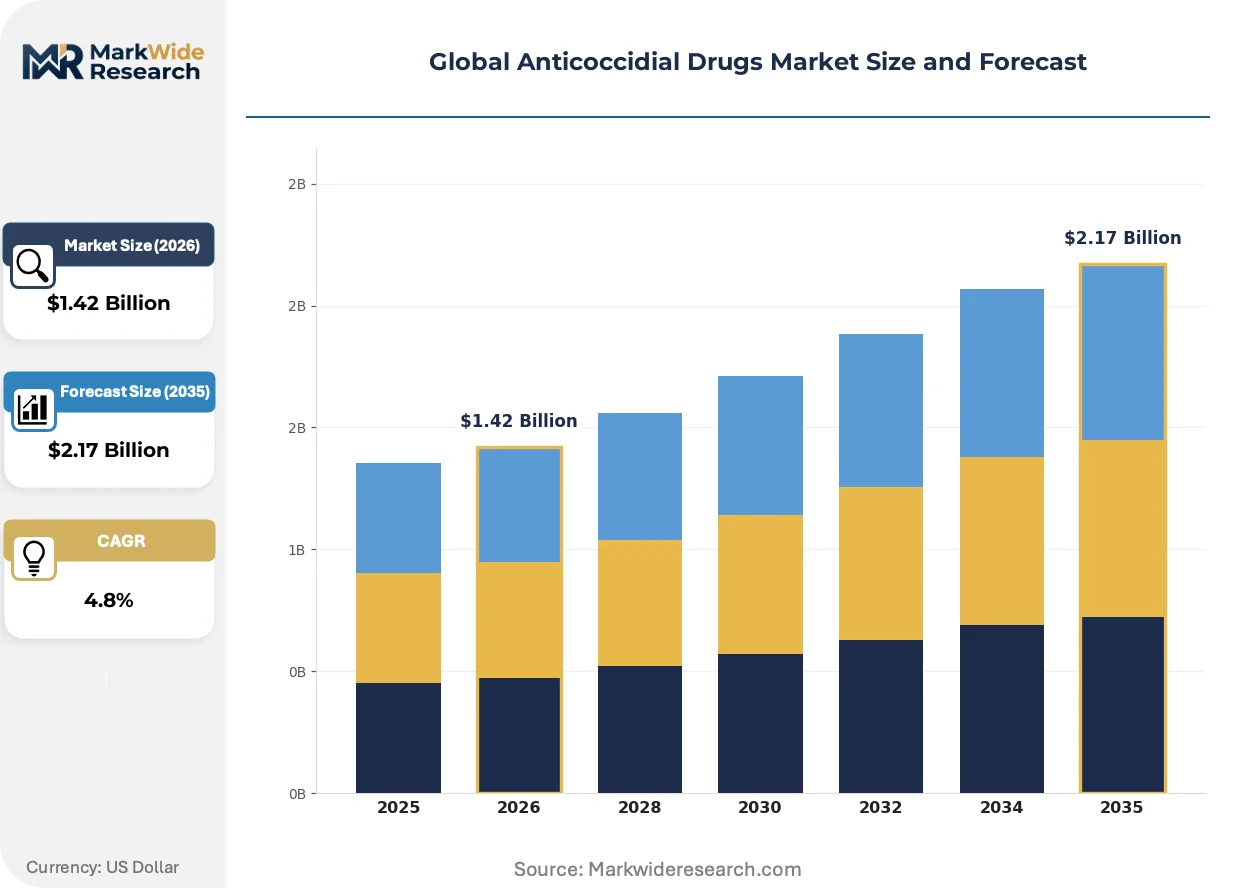
Market Dynamics
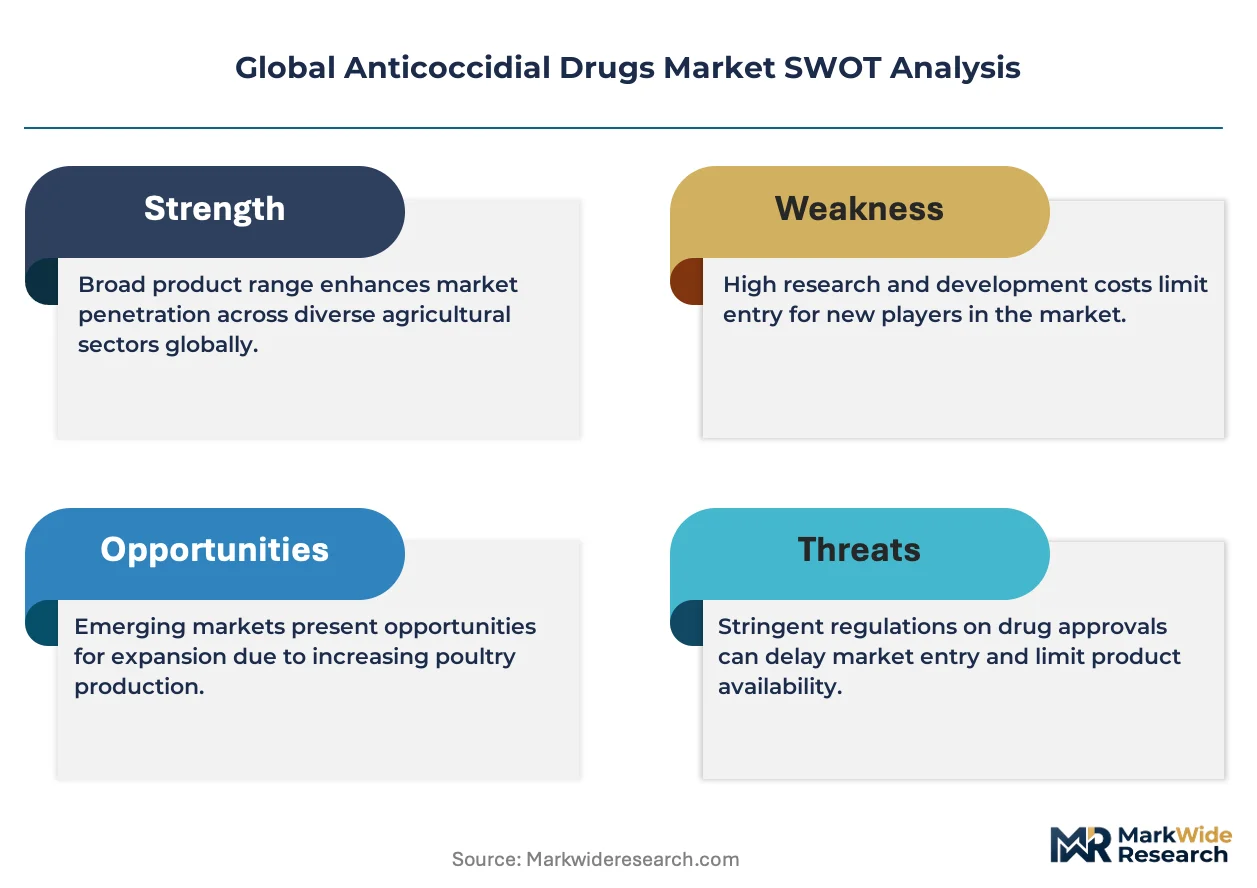
Regulatory pressure on ionophore residues is fragmenting formulation strategies across major protein-exporting jurisdictions, forcing manufacturers to maintain parallel development tracks for synthetic alternatives while defending existing ionophore positions in permissive markets.
Growth Catalysts
- Intensification in Brazilian broiler operations:Large-scale vertical integration of poultry chains in Mato Grosso and Paraná is standardizing prophylactic medication protocols, embedding anticoccidial drugs into mandatory feed formulations.
- REACH-aligned residue scrutiny:The European Chemicals Agency's expanding substance evaluation program is accelerating regulatory acceptance pathways for synthetic anticoccidials that demonstrate reduced cross-resistance risk with human antimicrobials.
- Precision dosing technologies:Automated feed mill control systems enabling gram-per-ton accuracy are reducing medication waste and improving efficacy validation, strengthening the economic case for preventive coccidiosis programs.
Market Restraints
- Active pharmaceutical ingredient concentration:Three Chinese manufacturers control over 70 percent of salinomycin and monensin technical-grade supply, creating vulnerability to export licensing disruptions or environmental compliance shutdowns.
- Feed-grade premix margin compression:Consolidation among North American feed manufacturers has compressed formulation fees, transferring price pressure upstream to API suppliers and toll compounders.
- Herbal extract substitution:Oregano-based and saponin-rich phytogenic feed additives are capturing trial budgets in European organic poultry operations, though efficacy consistency remains unproven at commercial scale.
Strategic Opportunities
- Vietnamese integrated poultry expansion:CP Group and Dabaco are building million-bird-per-week processing complexes in Dong Nai and Binh Phuoc, creating demand for long-term supply contracts with residue-compliant formulation suppliers.
- Dual-use synthetic ionophores:Compounds with demonstrated efficacy against both Eimeria tenella and necrotic enteritis are commanding formulation premiums in markets where antibiotic growth promoters face parallel restrictions.
- Direct manufacturer-procurement partnerships:Bypassing traditional veterinary wholesale channels through feed mill direct relationships is capturing margin pools and locking in multi-year volume commitments.
Industry Challenges
- Residue testing laboratory capacity:Third-party analytical services for maximum residue limit verification face 6-12 month backlogs in Southeast Asian export certification hubs, delaying market access for new formulation submissions.
- Cross-resistance surveillance infrastructure:Field isolate monitoring for Eimeria resistance patterns requires sustained investment in regional diagnostic networks that lack standardized methodology across national veterinary services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anticoccidial Drugs Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ionophores, Chemical Agents, Synthetic Compounds, Herbal Extracts Application: Poultry, Aquaculture, Swine, Pet Animals, Laboratory Animals End User: Veterinary Clinics, Feed Manufacturers, Pharmaceutical Companies, Research Institutions Formulation: Powder, Premix, Injectable, Oral Solution, Tablet |
| Companies Covered | MSD Animal Health, Huvepharma, Elanco, Vetoquinol SA, Ceva, Zoetis, Phibro Animal Health Corporation, Virbac, Boehringer Ingelheim International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anticoccidial Drugs Market Shifts & Advancements
Digital feed formulation platforms are compressing the cycle between field resistance detection and medication protocol adjustment, while regulatory divergence between major import jurisdictions is multiplying the number of parallel product registrations required for global suppliers.
RNA interference-based coccidiosis vaccines are virtualizing the traditional preventive medication model by inducing species-specific immune responses without chemical residues. Layer operations in the Netherlands and Denmark are adopting these platforms as EFSA residue thresholds tighten. This technology is virtualizing the economics of coccidiosis control by eliminating withdrawal period logistics and enabling uninterrupted export certification.
The FDA Center for Veterinary Medicine's revised guidance on combination anticoccidial approvals is extending development timelines for fixed-dose ionophore-synthetic products. Sponsors must now demonstrate non-interference pharmacokinetics for each component, adding 18-24 months to registration pathways. U.S. broiler integrators are responding by accelerating reliance on single-entity rotation programs rather than awaiting combination product availability.
Integrated poultry processors are consolidating feed medication procurement under centralized veterinary technical teams, displacing decentralized decision-making at individual complex levels. This concentration is visible across Thai and Indonesian operations where Charoen Pokphand and Japfa Comfeed have established regional pharmaceutical tender committees. The shift compresses supplier relationships toward a handful of contracted manufacturers with comprehensive residue documentation capabilities.
Global Anticoccidial Drugs Market Segmentation
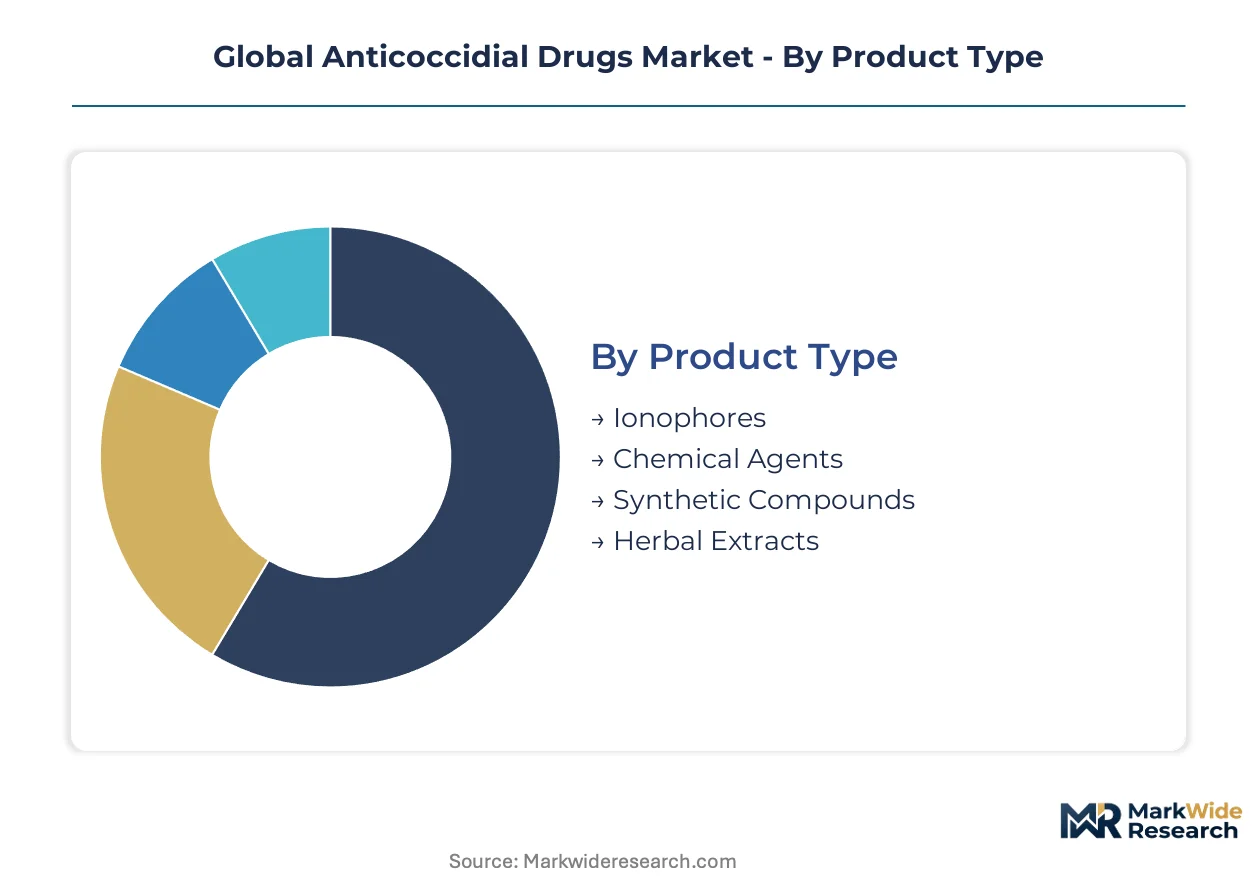
Anticoccidial drug markets fragment across formulation chemistry, species application, and procurement channel, with each dimension carrying distinct margin structures and regulatory exposure. Understanding turnover velocity across these axes clarifies where inventory risk concentrates and where long-term contracts prove sustainable.
Product Type:
Ionophores rotate through feed mills on quarterly cycles tied to flock turnover, while synthetic compounds and herbal alternatives move more slowly as integrators validate efficacy before protocol commitment.
- Ionophores:Polyether antibiotics including monensin, salinomycin, and lasalocid disrupt Eimeria ion transport across cell membranes. Brazilian and Thai broiler integrates specify these in 90-day supply contracts due to decades of field-proven resistance management protocols.
- Synthetic Compounds:Chemical entities such as nicarbazin and diclazuril target specific Eimeria life-cycle stages with precision. REACH-aligned residue scrutiny in EU protein-exporting operations is redirecting procurement budgets toward these alternatives as ionophore cross-resistance risks intensify regulatory review.
- Chemical Agents:Non-ionophore antimicrobials with broader protozoal coverage occupy niche positions in rotation programs where species-specific resistance patterns demand periodic substitution.
- Herbal Extracts:Phytogenic formulations derived from oregano, saponin-rich plants, and essential oil blends serve organic-certified operations in Denmark and the Netherlands where synthetic residue limits are most restrictive.
Ionophores anchor the volume base while synthetic compounds gain share at the steepest rate.
Application:
Species-specific pharmacokinetics and withdrawal period economics create tiered pricing structures, with poultry commanding formulation premiums due to flock density and infection pressure intensity.
- Poultry:Broiler, layer, and breeder operations consume the majority of anticoccidial tonnage, driven by intensification in Mato Grosso and Paraná where vertical integration standardizes prophylactic medication across million-bird complexes.
- Aquaculture:Shrimp and finfish farming in Vietnamese Mekong Delta provinces employs anticoccidials against emerging Eimeria-like pathogens, though formulation registration lags terrestrial livestock by several development cycles.
- Swine:Isospora suis control in farrowing operations represents a concentrated seasonal demand pattern tied to breeding calendar synchronization in Danish and Spanish production systems.
- Pet Animals:Companion animal coccidiosis treatment occupies a premium-priced segment where veterinary prescription channels sustain higher margins than feed-grade formulations.
- Laboratory Animals:Specific-pathogen-free colony maintenance in research facilities demands residue-free certification that excludes most commercial ionophore products.
Poultry applications dominate current procurement volumes while aquaculture represents the most rapidly expanding frontier for formulation registration investment.
End User:
Procurement concentration varies sharply by channel, with feed manufacturers consolidating purchasing power while research institutions fragment across small-lot specialty orders.
- Feed Manufacturers:Premix compounders in Vietnam and Indonesia centralize medication procurement for integrated poultry chains, capturing margin pools through gram-per-ton formulation precision and residue documentation services.
- Veterinary Clinics:Small animal practitioners in urban Brazil and Mexico dispense individual-dose therapies, generating higher per-unit revenue than bulk feed-grade channels despite smaller absolute volumes.
- Pharmaceutical Companies:API toll manufacturers and finished-dose repackagers serve as intermediaries in markets where direct manufacturer-producer relationships remain underdeveloped.
- Research Institutions:Academic and contract research organizations drive demand for analytical-grade reference materials and experimental formulations with batch-specific purity certification.
Feed manufacturers command the largest absolute tonnage while veterinary clinics sustain the highest margin per kilogram of active ingredient.
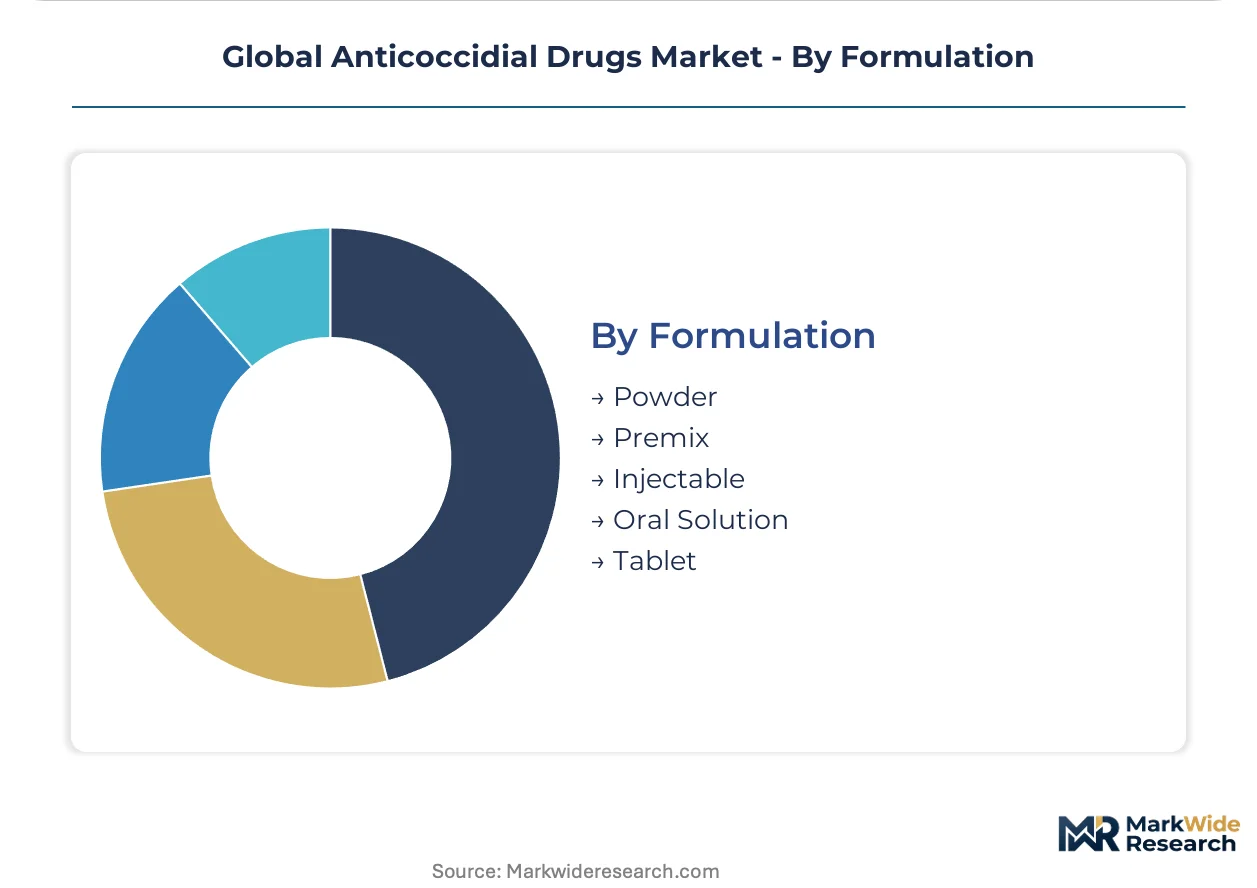
Formulation:
Physical presentation determines distribution economics, with premix formulations dominating high-volume channels and injectable formats reserved for therapeutic intervention where feed intake is compromised.
- Premix:Concentrated ionophore or synthetic active ingredients blended with carriers enable precise feed mill dosing at 0.5-5 grams per ton, forming the backbone of prophylactic programs in Brazilian and Southeast Asian integrated operations.
- Powder:Water-soluble formulations facilitate administration in young chicks before full feed consumption stabilizes, particularly in Indonesian backyard-to-commercial transition farms.
- Oral Solution:Ready-to-use liquid concentrates support flock-wide treatment during acute outbreak phases where rapid therapeutic plasma levels override preventive protocol preferences.
- Injectable:Parenteral formulations serve individual animal value preservation in breeding stock and high-genetic-merit layers where mortality carries disproportionate economic consequence.
- Tablet:Unit-dose solid forms target companion animal and small ruminant applications where precise weight-based dosing and owner compliance considerations predominate.
Premix formulations capture the majority of commercial volume while oral solutions demonstrate the most rapid adoption acceleration in outbreak-responsive procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos grain terminal underwrites Brazil's dominance in protein-export corridors, channeling medicated feed formulations from Mato Grosso processing clusters to European and Asian buyers. This logistics backbone shapes anticoccidial procurement patterns across the Atlantic basin.
United States
Integrated broiler operations in the Delmarva Peninsula and Georgia Piedmont standardize ionophore rotation protocols through centralized veterinary oversight. The FDA Center for Veterinary Medicine's residue tolerance thresholds shape formulation registration priorities, particularly for export-oriented complexes supplying Canadian and Mexican markets. Tyson Foods and Pilgrim's Pride processing hubs in Arkansas and North Carolina anchor multi-year supply contracts with premix compounders.
Brazil
Vertical poultry integration in Mato Grosso and Paraná embeds anticoccidial prophylaxis into mandatory feed formulations across million-bird complexes. ANVISA's veterinary medicinal product regulations align with EU residue standards for export certification, accelerating synthetic compound trials alongside established ionophore programs. JBS and BRF processing clusters near Dourados and Londrina concentrate procurement decisions under technical directors with direct manufacturer relationships.
China
Technical-grade salinomycin and monensin API production concentrates in Shandong and Jiangsu provinces, supplying global feed premix manufacturers. The NMPA and Ministry of Agriculture enforce GB standards for veterinary drug maximum residue limits that diverge from Western export requirements, creating parallel compliance tracks for domestic versus international-facing operations. Environmental compliance shutdowns at key manufacturers periodically disrupt ionophore supply chains.
Germany
Layer operations in Lower Saxony and North Rhine-Westphalia pilot RNA interference vaccines as EFSA residue thresholds tighten under REACH-aligned scrutiny. The EMA's Committee for Medicinal Products for Veterinary Use shapes European market access through benefit-risk assessments that scrutinize ionophore cross-resistance with human therapeutics. Big Dutchman and Lohmann Tierzucht breeding facilities near Hannover demand residue-free certification for export stock.
Vietnam
CP Group and Dabaco are building million-bird-per-week processing complexes in Dong Nai and Binh Phuoc provinces, creating concentrated demand for long-term anticoccidial supply contracts. The country's national pharmaceutical regulator enforces maximum residue limits aligned with EU and Japanese import standards, favoring suppliers with comprehensive documentation capabilities. Mekong Delta shrimp farming operations represent an emerging frontier for Eimeria-like pathogen formulations.
Global Anticoccidial Drugs Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in API and toll-manufacturing niches. The vendor base stratifies across multinational pharmaceutical houses with broad ionophore portfolios, mid-scale regional compounders serving integrated poultry chains, and Chinese API manufacturers controlling technical-grade supply. Three archetypes dominate: residue-documentation specialists capturing centralized procurement tenders, rotation-program advisors embedding into veterinary technical teams, and direct-manufacturing partners bypassing wholesale channels. Competitive positioning hardens through multi-year volume commitments and geographic exclusivity arrangements rather than price competition.
Within the multinational platform tier, MSD Animal Health and Zoetis exemplify divergent geographic anchoring strategies. MSD leverages its broad ionophore portfolio to sustain long-term supply contracts with multinational protein companies across Atlantic basin markets. Zoetis anchors its position through dominance in Latin American markets where coccidiosis pressure remains severe year-round. Huvepharma occupies a position bridging European regulatory sophistication with emerging market volume scale. These three entities represent the consolidation endpoint toward which regional compounders and API toll manufacturers increasingly orient their partnership strategies.
| Leading Market Players |
|---|
| MSD Animal Health |
| Huvepharma |
| Elanco |
| Vetoquinol SA |
| Ceva |
| Zoetis |
| Phibro Animal Health Corporation |
| Virbac |
| Boehringer Ingelheim International GmbH |
| Others |
Supply & Pricing Matrix
Shandong and Jiangsu provinces in China concentrate technical-grade salinomycin and monensin API production, and their environmental compliance shutdowns periodically tighten ionophore supply. This concentration hands pricing power to the three manufacturers controlling over 70 percent of global technical-grade supply, while downstream feed premix compounders absorb margin compression through consolidated procurement.
Pricing Analysis
Three-tier pricing structure across residue-certified premium, standard feed-grade, and economy generic levels separates formulation tiers. Price differentiation hinges on EMA-compliant documentation depth and volume scale commitments from integrated poultry chains. Cost compression in the standard tier is intensifying because North American feed manufacturer consolidation transfers pricing pressure upstream. Small-scale Vietnamese backyard-to-commercial transition farms exhibit the highest price sensitivity, while Brazilian million-bird complexes prioritize residue certification over unit cost.
Supply Chain Analysis
Tariff exposure between China and major protein-importing jurisdictions dominates supply chain risk planning for API-dependent formulators. Geographic supply concentration centers on Chinese technical-grade production, Brazilian premix compounding, and Southeast Asian toll manufacturing. Raw material dependencies include salinomycin fermentation feedstocks, monensin precursors, and carrier substrates for gram-per-ton precision dosing. Single-source vulnerability at the API tier creates disruption exposure when environmental inspectors shutter Shandong facilities. Distribution runs through direct manufacturer-procurement partnerships that bypass traditional veterinary wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anticoccidial market is approaching a platform-economics inflection where RNA interference vaccines and precision dosing technologies interoperate to displace chemical-centric prevention models. Ecosystem consolidation around digital feed formulation platforms is compressing supplier relationships toward documentation-specialist partners.
For Market Incumbents: Build regulatory documentation moats by embedding residue-testing laboratory partnerships into centralized procurement tenders. Deepen backward integration into synthetic compound R&D to offset ionophore cross-resistance scrutiny from EMA benefit-risk assessments. Capture multi-year volume commitments from Vietnamese integrated poultry expansions before regional compounders establish local toll-manufacturing relationships. For New Entrants and Emerging Players: Establish a beachhead in Vietnamese aquaculture formulations where Eimeria-like pathogen registration lags terrestrial livestock by several development cycles. Target organic-certified layer operations in Denmark and the Netherlands with phytogenic extract portfolios that bypass synthetic residue limits. Pursue direct feed mill relationships in Indonesian backyard-to-commercial transition zones where decentralized procurement still permits supplier switching. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because divergence between EU REACH-aligned residue standards and permissive export markets creates parallel product registration demand. Acquisition candidates include regional compounders with captive API toll-manufacturing relationships and comprehensive Southeast Asian documentation capabilities. Monitor FDA guidance evolution on combination anticoccidial approvals as the inflection signal for synthetic compound valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic API Production | Reduces ionophore cross-resistance exposure as EMA scrutiny intensifies on polyether antibiotics. |
| Residue-Testing Laboratory Partnership | Captures centralized procurement tenders from Thai and Indonesian poultry integrators requiring documentation. |
| RNA Interference Vaccine Platform Development | Virtualizes coccidiosis economics for Dutch and Danish layer operations facing EFSA threshold tightening. |
| Direct Feed Mill Relationship Establishment | Bypasses veterinary wholesale margin extraction in Vietnamese and Brazilian integrated poultry chains. |
| Phytogenic Extract Portfolio Expansion | Targets organic-certified operations where oregano-based alternatives displace synthetic compounds. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with feed mill procurement directors, veterinary technical team leads, API toll-manufacturing plant managers, and regulatory affairs specialists at multinational pharmaceutical houses. Secondary validation drew from FDA Center for Veterinary Medicine guidance documents, EMA Committee for Medicinal Products for Veterinary Use benefit-risk assessments, ANVISA veterinary medicinal product regulations, and customs trade data on technical-grade ionophore shipments. Bottom-up volume estimates from individual facility medication protocols were triangulated against top-down market sizing derived from premix formulation licensing records.
Calibration against historical flock turnover cycles and regulatory approval timelines anchored the analytical framework across the analysis window. Segmentation dimensions modeled include formulation chemistry class, species application, procurement channel concentration, and regional regulatory cluster alignment. CAGRs were derived from projecting feed conversion ratio economics and infection pressure intensity across intensifying production systems. Forecast inputs incorporated precision dosing technology adoption curves and RNA interference vaccine trial expansion in EU layer operations.
Stress conditions across API supply disruption scenarios, EMA ionophore restriction acceleration, and phytogenic substitution efficacy thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding flock density expansion rates and residue limit harmonization patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Middle East and Africa Adenomyosis Drugs Market
Pharmaceuticals
India Pharmaceutical Market
Pharmaceuticals
OTC Cough, Cold & Allergy Medicine Market
Pharmaceuticals
Paracetamol IV Market
Pharmaceuticals
Global Shingles Vaccine Market
Pharmaceuticals
Long-Acting Insulin Market
Pharmaceuticals
Global Vasopressin Market
Pharmaceuticals
Ginkgo Leaf Extract and Dipyridamole Injection Market
Pharmaceuticals
Triamcinolone Ointment Chlorofluorocarbons Market
Pharmaceuticals
Sildenafil Drug Market
Pharmaceuticals
Mild Laxatives Market
Pharmaceuticals
Drug-Loaded Oral Thin Films Market
Pharmaceuticals
Global Pneumococcal Vaccines Market
Pharmaceuticals
New Zealand Diabetes Drugs Market
Pharmaceuticals
Tramadol Drug Market
Pharmaceuticals
Hard Empty HPMC Capsule Market