
 Antibiotic-Associated Diarrhea Treatment Market | 2026-2036
Antibiotic-Associated Diarrhea Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Antibiotic-Associated Diarrhea Treatment Market Analytics
North American manufacturing capacity for live biotherapeutic products is fragmenting as specialty fermentation facilities multiply across the United States and Canada. Pfizer sustains broad antimicrobial portfolio depth through internal R&D programs targeting Clostridioides difficile recurrence. Merck & Co dominates the vaccines segment with its established hospital formulary relationships. Cosmo Pharmaceuticals specializes in targeted delivery formulations for colonic conditions, leveraging MMX technology to differentiate from conventional oral therapies.
Antibiotic-associated diarrhea treatment encompasses therapeutic interventions designed to prevent or manage gastrointestinal disturbances arising from dysbiosis induced by systemic antibacterial agents, typically involving live microbial preparations, adsorbent polymers, or antisecretory compounds formulated for colonic delivery. These therapies function by restoring commensal flora balance, neutralizing bacterial toxins, or modulating intestinal fluid secretion to reduce severity and duration of symptoms. Probiotics occupy the largest revenue share due to established over-the-counter availability and physician familiarity, though enzymatic therapy represents the fastest-expanding category as novel microbiome modulators advance through clinical pipelines. Hospitals command the dominant end-user channel, while long-term care facilities emerge as a concentrated growth pocket given elevated antibiotic exposure rates among elderly populations with recurrent infection risk.
FDA oversight of live biotherapeutic products under the Biologics License Application pathway shapes development timelines and manufacturing standards for entrants targeting the United States market. EMA's evolving guidance on fecal microbiota products under the Advanced Therapy Medicinal Products framework creates parallel compliance requirements for European market access. The WHO essential medicines list inclusion criteria for pediatric diarrhea management further influence national procurement priorities across multiple geographies. Stakeholders must monitor regulatory divergence between jurisdictions as microbiome-based therapies transition from orphan indications toward broader prophylactic use in high-risk antibiotic populations.
Market Dynamics
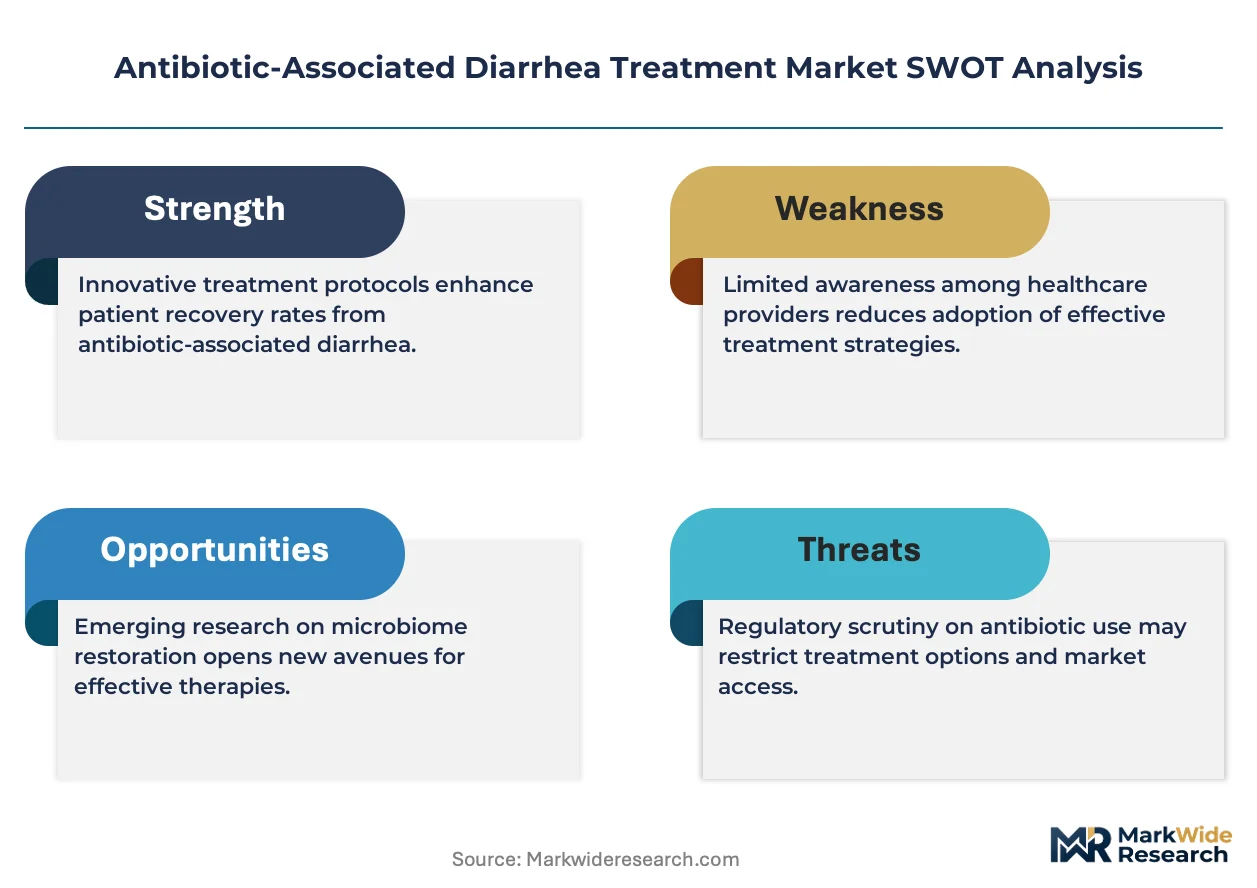
FDA's Biologics License Application pathway for live biotherapeutic products is compressing development timelines while elevating manufacturing standards, forcing developers to build captive fermentation capacity or cede United States market access to established microbiome platforms.
Growth Catalysts
- Biologics License Application pathway:FDA's streamlined framework accelerates commercialization timelines for microbiome-based therapies, reducing regulatory uncertainty for developers targeting recurrent Clostridioides difficile infection.
- Long-term care facilities:Elevated antibiotic exposure rates among elderly populations with recurrent infection risk create concentrated demand pockets for prophylactic live biotherapeutic products.
- MMX colonic delivery technology:Targeted-release formulations improve therapeutic efficacy in the lower gastrointestinal tract, differentiating specialty offerings from conventional oral therapies.
Market Restraints
- Specialty fermentation capacity scarcity:North American manufacturing infrastructure for live biotherapeutic products remains fragmented, with limited contract development and manufacturing organizations possessing validated anaerobic fermentation capabilities.
- EMA Advanced Therapy Medicinal Products divergence:Evolving European guidance on fecal microbiota products creates parallel compliance requirements that extend market access timelines beyond United States approval cycles.
- Over-the-counter probiotic substitution:Established physician familiarity with non-prescription microbial preparations limits pricing power for novel prescription microbiome modulators in outpatient settings.
Strategic Opportunities
- Pediatric diarrhea management:WHO essential medicines list inclusion criteria influence national procurement priorities across multiple geographies, creating pathway for pediatric-specific live biotherapeutic formulations.
- Prophylactic high-risk populations:Transition from orphan indication positioning toward broader prevention use in antibiotic-exposed patients represents addressable white space for developers with robust safety databases.
- Hospital formulary integration:Deepened relationships with pharmacy and therapeutics committees enable preferred positioning for targeted therapies over conventional adsorbent polymers in inpatient protocols.
Industry Challenges
- Anaerobic fermentation expertise scarcity:Limited talent pools with validated experience in live biotherapeutic manufacturing constrain scale-up velocity for emerging developers.
- Cross-jurisdictional regulatory harmonization:Divergent microbiome product classification between FDA biologics framework and EMA advanced therapy pathways complicates global development strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibiotic-Associated Diarrhea Treatment Market |
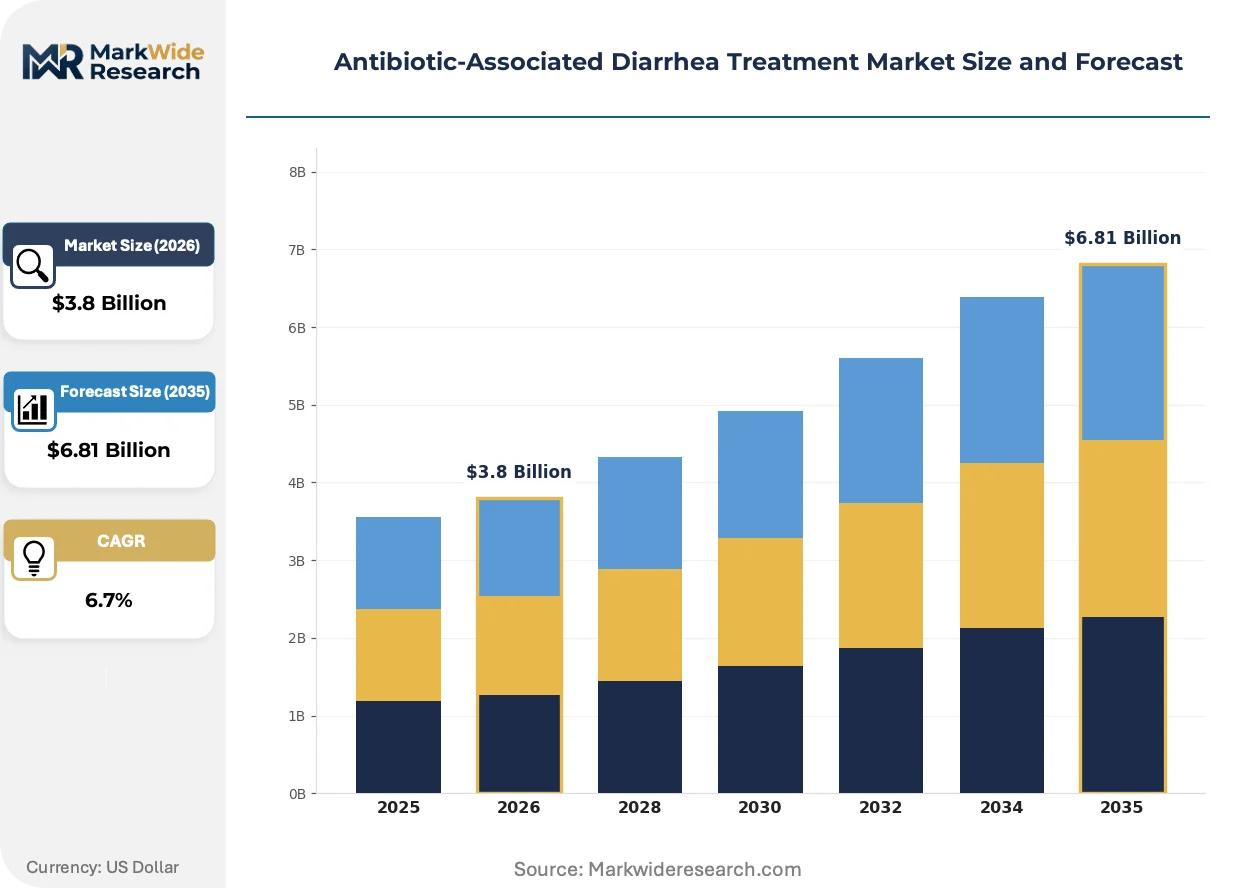
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Antibiotics, Antisecretory Agents, Enzymatic Therapy End User: Hospitals, Outpatient Clinics, Long-term Care Facilities, Home Care Administration Route: Oral, Intravenous, Topical, Rectal Age Group: Pediatrics, Adults, Geriatrics, Others |
| Companies Covered | Merck & Co, Pfizer, TECHLAB, Aurobindo Pharma, CutisPharma, Cosmo Pharmaceuticals, Manav Drugs, F. Hoffmann-La Roche, Bausch Health Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibiotic-Associated Diarrhea Treatment Market Evolving Landscape
Live biotherapeutic manufacturing is digitizing quality control systems, with artificial intelligence-driven process analytics replacing batch-release testing paradigms. This shift compresses production cycles while tightening contamination detection thresholds.
Continuous bioprocessing technology is digitizing fermentation monitoring through real-time metabolite sensing and automated feedback loops. Contract manufacturers in Massachusetts and North Carolina deploy these platforms to reduce batch failure rates. The technology is digitizing compliance documentation, enabling electronic batch records that satisfy FDA validation requirements without manual transcription.
EMA's evolving Advanced Therapy Medicinal Products framework reclassifies fecal microbiota preparations as regulated therapeutics rather than tissue transplants. This industrial consequence forces European developers to adopt pharmaceutical-grade manufacturing standards previously reserved for recombinant biologics. German and Dutch developers respond by retrofitting existing good manufacturing practice facilities with anaerobic isolation technology.
Hospital procurement committees now unbundle prophylactic microbiome therapies from bundled infection-control contracts, creating direct purchasing relationships with live biotherapeutic suppliers. This pattern displaces traditional group purchasing organization intermediaries in tertiary academic medical centers. The shift concentrates in United States health systems with established antimicrobial stewardship programs and dedicated gastroenterology pharmacy specialists.
Antibiotic-Associated Diarrhea Treatment Market Segmentation
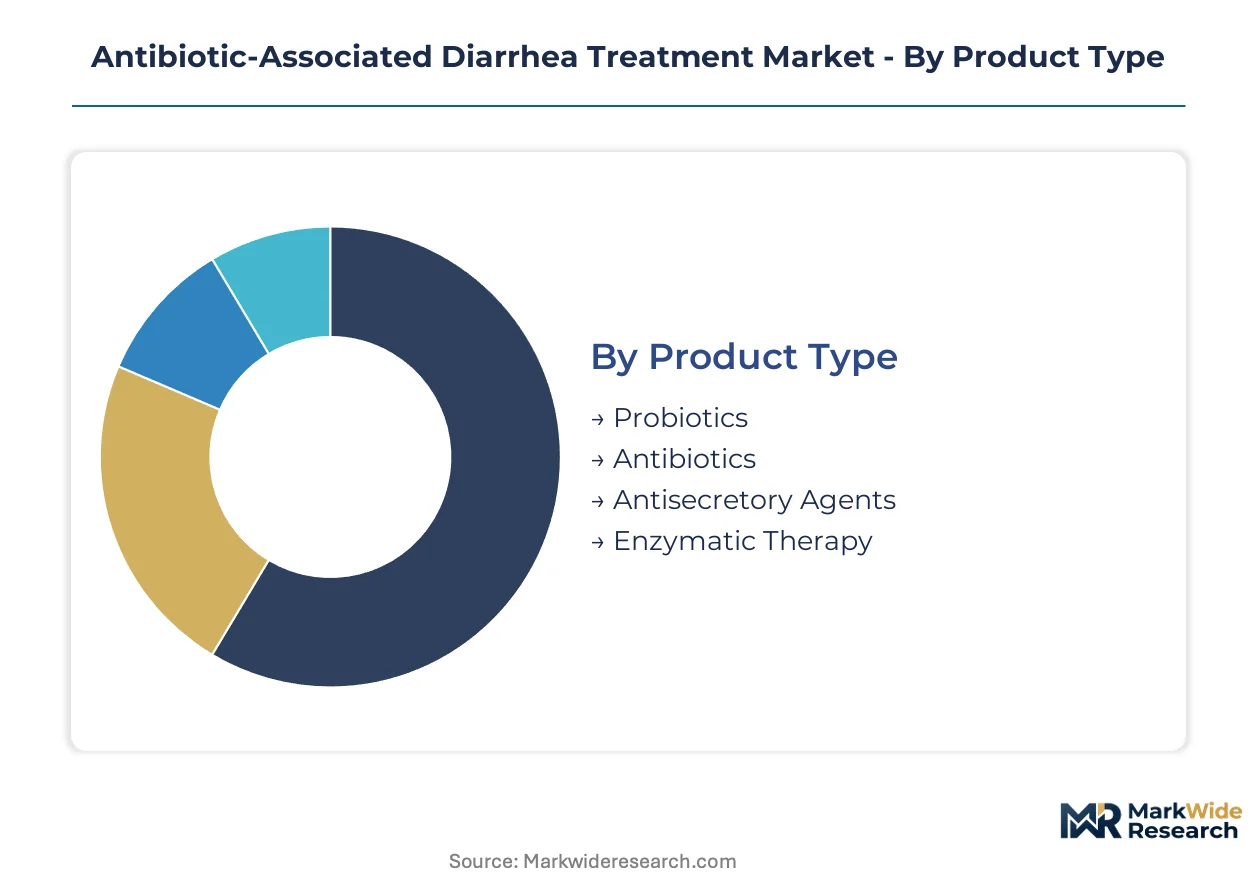
Segmentation in the antibiotic-associated diarrhea treatment market reveals distinct service intensity profiles across product categories and care settings. Manufacturers must calibrate distribution investments and clinical support resources differently for hospital formulary integrations versus over-the-counter retail channels.
Product Type:
After-sales service intensity varies sharply across product categories, with live biotherapeutics requiring cold-chain logistics support and clinical education that commodity probiotics do not demand.
- Probiotics:Formulations containing live microbial cultures such as Lactobacillus and Bifidobacterium strains. Demand concentrates in United States retail pharmacies and direct-to-consumer channels driven by established physician familiarity and over-the-counter accessibility.
- Enzymatic Therapy:Novel microbiome modulators utilizing targeted enzymatic activity to restore commensal flora balance. Demand concentrates in academic medical centers with antimicrobial stewardship programs, driven by FDA's Biologics License Application pathway accelerating commercialization timelines for developers targeting recurrent Clostridioides difficile infection.
- Antibiotics:Narrow-spectrum antibacterial agents including fidaxomicin and vancomycin formulations for severe cases.
- Antisecretory Agents:Adsorbent polymers and fluid-modulating compounds formulated for symptom management.
Probiotics holds the largest share; momentum sits with enzymatic therapy.
End User:
Customer acquisition economics diverge substantially across care settings, with hospital procurement committees demanding outcome data that home care distributors rarely require.
- Hospitals:Tertiary academic medical centers and community hospital systems with dedicated gastroenterology pharmacy specialists. Demand concentrates in United States health systems with established antimicrobial stewardship programs, driven by unbundling of prophylactic microbiome therapies from bundled infection-control contracts creating direct purchasing relationships with live biotherapeutic suppliers.
- Long-term Care Facilities:Skilled nursing facilities and assisted living centers serving elderly populations with elevated antibiotic exposure rates. Demand concentrates in United States geriatric care networks, driven by recurrent infection risk creating concentrated demand pockets for prophylactic live biotherapeutic products.
- Outpatient Clinics:Ambulatory gastroenterology practices and primary care settings managing non-severe presentations.
- Home Care:Self-administered therapies distributed through retail pharmacies and mail-order channels.
Hospitals command the dominant channel; long-term care facilities are expanding most quickly.
Administration Route:
Manufacturing complexity and regulatory burden scale with delivery sophistication, from standard oral formulations to specialized colonic targeting systems.
- Oral:Standard tablet, capsule, and liquid formulations for systemic delivery. Demand concentrates in outpatient and retail settings across the United States, Canada, and Germany, driven by patient preference for non-invasive administration and established reimbursement pathways.
- Rectal:Targeted-release formulations utilizing MMX colonic delivery technology for lower gastrointestinal tract efficacy. Demand concentrates in hospital inpatient protocols and specialty gastroenterology clinics in the United States and Italy, driven by differentiated therapeutic outcomes compared to conventional oral therapies.
- Intravenous:Parenteral delivery reserved for severe, refractory cases requiring rapid systemic intervention.
- Topical:Limited application for localized mucosal conditions in specific patient populations.
Oral delivery holds the largest share; rectal formulations are gaining share fastest.
Age Group:
Regulatory requirements and formulation specifications tighten for vulnerable populations, with pediatric and geriatric segments demanding dedicated clinical evidence packages.
- Adults:Working-age populations receiving standard antibiotic courses in outpatient and inpatient settings. Demand concentrates in United States employer-sponsored health plans and European national health systems, driven by high antibiotic prescription rates and established gastroenterology infrastructure.
- Geriatrics:Elderly populations with compromised immune function and polypharmacy profiles. Demand concentrates in United States Medicare-covered long-term care facilities and Japanese geriatric hospitals, driven by elevated antibiotic exposure rates and recurrent infection risk.
- Pediatrics:Infants and children requiring age-appropriate dosing and formulation modifications.
- Others:Immunocompromised and specialized patient populations with unique therapeutic requirements.
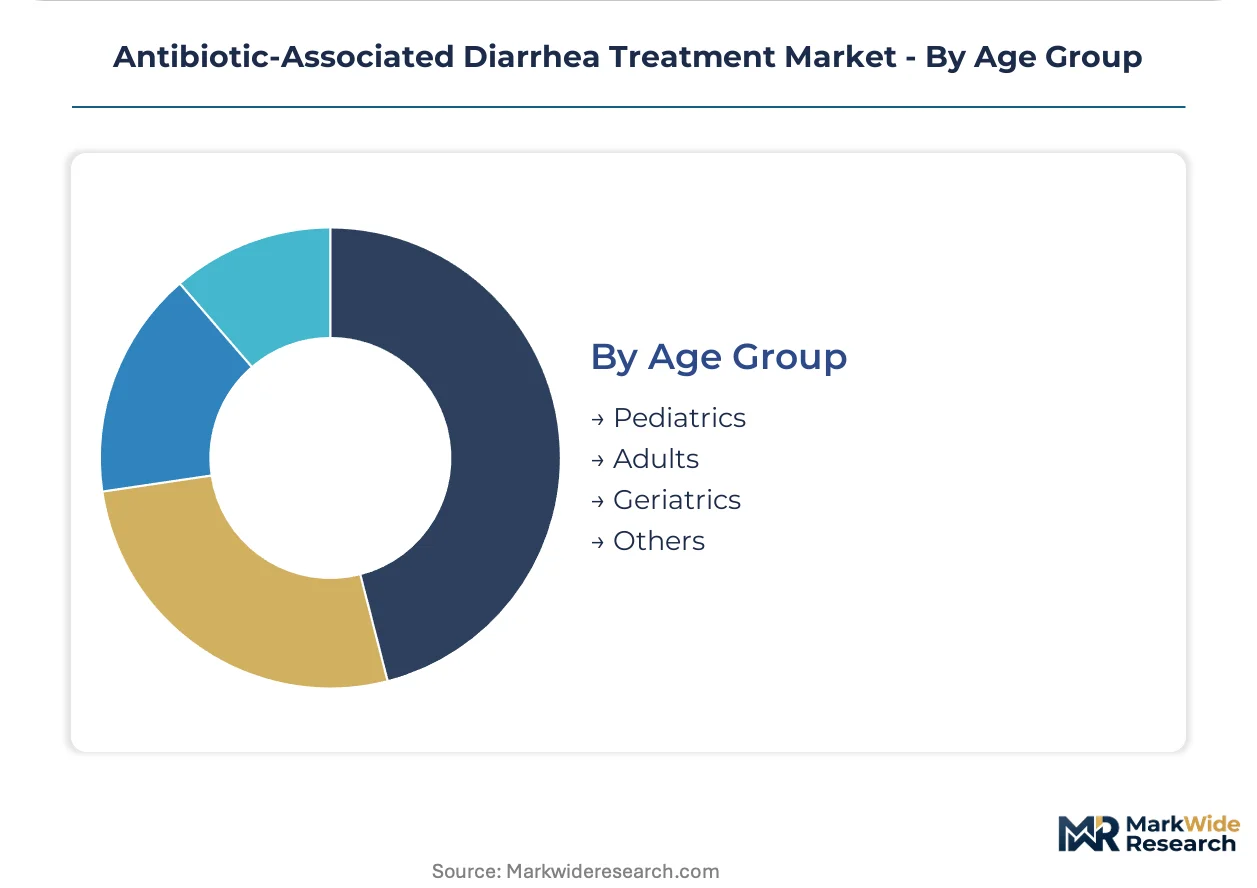
Adults holds the largest share; geriatrics shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's Biologics License Application pathway anchors commercialization timelines for developers targeting the United States market. Manufacturing capacity for live biotherapeutic products fragments across North America as specialty fermentation facilities multiply. Regulatory divergence between FDA and EMA frameworks complicates global development strategies for microbiome-based therapies.
United States
Hospital procurement committees unbundle prophylactic microbiome therapies from bundled infection-control contracts, creating direct purchasing relationships with live biotherapeutic suppliers. FDA's streamlined approval pathways accelerate commercialization for developers targeting recurrent Clostridioides difficile infection. Massachusetts and North Carolina host contract manufacturers deploying continuous bioprocessing technology with real-time metabolite sensing.
Germany
German developers retrofit existing good manufacturing practice facilities with anaerobic isolation technology to meet EMA's Advanced Therapy Medicinal Products framework requirements. The country's national pharmaceutical regulator reclassifies fecal microbiota preparations as regulated therapeutics rather than tissue transplants. Bavaria and North Rhine-Westphalia concentrate pharmaceutical-grade manufacturing infrastructure for microbiome modulators.
Japan
Japanese geriatric hospitals drive demand for prophylactic live biotherapeutic products among elderly populations with elevated antibiotic exposure rates. PMDA oversight shapes clinical trial design for pediatric-specific formulations targeting WHO essential medicines list inclusion. Kanto region around Tokyo anchors gastroenterology infrastructure and antimicrobial stewardship program adoption.
Canada
Canadian specialty fermentation capacity expands alongside United States facilities, with Health Canada aligning microbiome product classification with FDA biologics frameworks where feasible. Long-term care networks create concentrated demand pockets for prophylactic therapies among antibiotic-exposed elderly populations. Ontario and Quebec host emerging anaerobic fermentation expertise pools.
India
Indian pharmaceutical manufacturers supply narrow-spectrum antibacterial agents including fidaxomicin formulations for severe antibiotic-associated diarrhea cases. CDSCO regulatory pathways for biosimilars influence development strategies for live biotherapeutic entrants. Maharashtra and Gujarat concentrate contract manufacturing capacity for conventional oral therapies distributed to outpatient markets.
Antibiotic-Associated Diarrhea Treatment Market Competitive Landscape
Capability concentration sits with specialty fermentation developers possessing validated anaerobic manufacturing expertise; scale advantage sits with established pharmaceutical platforms with hospital formulary relationships. The market structures around three tiers: large-cap diversified pharmaceutials with antimicrobial portfolios, mid-cap targeted delivery specialists with colonic formulation technology, and emerging microbiome platforms building captive manufacturing capacity. Dominant competitive moves include backward integration into fermentation capacity and strategic partnerships with academic medical centers for clinical evidence generation.
Among large-cap diversified pharmaceuticals, Merck & Co and Pfizer occupy positions shaped by hospital formulary depth and internal R&D targeting Clostridioides difficile recurrence. Cosmo Pharmaceuticals exemplifies the targeted delivery specialist archetype, leveraging MMX technology to differentiate from conventional oral therapies. These three anchors represent distinct competitive vectors: vaccine and biologics scale, broad antimicrobial portfolio breadth, and colonic-specific formulation expertise.
| Leading Market Players |
|---|
| Merck & Co |
| Pfizer |
| TECHLAB |
| Aurobindo Pharma |
| CutisPharma |
| Cosmo Pharmaceuticals |
| Manav Drugs |
| F. Hoffmann-La Roche |
| Bausch Health Companies |
| Others |
Value Network & Pricing Analysis
Undercapacity in North American anaerobic fermentation facilities is compressing supplier margins while elevating pricing power for validated contract manufacturers serving FDA-regulated live biotherapeutic developers.
Pricing Analysis
United States prescription microbiome therapies command substantial premiums over German and Indian-sourced alternatives due to cold-chain logistics costs and BLA compliance overhead. Three-tier pricing structure across premium live biotherapeutics, standard probiotic formulations, and economy adsorbent polymers reflects certification-grade differentiation. Pricing pressure stems from over-the-counter probiotic substitution in outpatient settings. Long-term care facilities exhibit highest price sensitivity; academic medical centers with dedicated stewardship programs demonstrate lowest sensitivity due to outcome-based procurement protocols.
Supply Chain Analysis
Tariff exposure between United States and Chinese fermentation equipment suppliers dominates supply chain risk planning for emerging microbiome developers. Manufacturing capacity concentrates in United States, Germany, and Canada, with Indian suppliers providing narrow-spectrum antibiotic APIs. Raw material dependencies span pharmaceutical-grade fermentation media, anaerobic isolation chamber components, and cryopreservation excipients. Single-source vulnerability persists for validated CDMOs with FDA-inspected anaerobic capacity. Distribution runs through hospital procurement committees unbundling from group purchasing organizations, supplemented by direct-to-facility cold-chain logistics for live biotherapeutics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across manufacturing capability tiers creates entry niches for specialists, as hospital procurement unbundling from bundled infection-control contracts generates direct purchasing relationships with targeted therapy suppliers.
For Market Incumbents: Entrench formulary positioning by deepening antimicrobial stewardship program partnerships and securing captive anaerobic fermentation capacity in Massachusetts or North Carolina clusters. Invest in MMX colonic delivery technology patents to defend against generic probiotic substitution threats. Prioritize backward integration into pharmaceutical-grade fermentation infrastructure over reliance on fragmented CDMO networks. For New Entrants and Emerging Players: Pediatric-specific live biotherapeutic formulations for WHO essential medicines list inclusion represent the most penetrable entry point, given limited competition and national procurement pathway leverage. Long-term care facility networks in United States geriatric care markets offer concentrated demand pockets with lower formulary barrier complexity. Pursue academic medical center clinical evidence partnerships as primary go-to-market anchor before retail channel expansion. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across live biotherapeutic manufacturing as FDA BLA requirements force pharmaceutical-grade facility retrofits. Five-to-ten year viability favors developers with validated anaerobic capacity and established hospital formulary relationships over platform technologies without manufacturing assets. Monitor EMA Advanced Therapy Medicinal Products framework harmonization progress as inflection signal for European market access timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Fermentation Capacity Buildout | BLA-compliant anaerobic facilities in United States clusters reduce reliance on scarce CDMO slots. |
| Hospital Formulary Partnership | Direct relationships with pharmacy and therapeutics committees displace group purchasing organization intermediaries. |
| Pediatric Formulation Development | WHO essential medicines list inclusion opens national procurement pathways across multiple geographies. |
| MMX Technology Licensing | Colonic delivery differentiation commands premium positioning against conventional oral therapies. |
| Continuous Bioprocessing Adoption | AI-driven process analytics in North Carolina and Massachusetts facilities compress batch release cycles. |
Research Methodology
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists anchors the qualitative findings. Secondary validation draws from FDA BLA filings, EMA Advanced Therapy Medicinal Products submissions, ClinicalTrials.gov records, and hospital formulary databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation converge across the analysis window.
Calibration against historical approval timelines and commercial uptake curves shapes the projection framework. Segmentation dimensions span product type, end-user channel, administration route, and age group, with regional regulatory cluster as cross-cutting variable. CAGRs derive from fitted growth curves applied to baseline penetration rates, incorporating antimicrobial stewardship program adoption as demand-side input and manufacturing capacity expansion as supply-side constraint.
Practitioners should monitor FDA guidance evolution on live biotherapeutic classification and EMA harmonization progress for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Ebola Drug and Vaccine Market
Pharmaceuticals
Asia-Pacific Sodium-Dependent Glucose Cotransporter 2 (SGLT-2) Market
Pharmaceuticals
Global Ebola Virus Vaccine Market
Pharmaceuticals
Rheumatology Therapeutics Market
Pharmaceuticals
Peptide Therapeutics Market
Pharmaceuticals
Thrombosis Drugs Market
Pharmaceuticals
Global Pediatric Drugs Market
Pharmaceuticals
Differentiated Thyroid Cancer Therapeutics Market
Pharmaceuticals
Korea Pharmaceutical Market
Pharmaceuticals
Global Viral Vaccines Market
Pharmaceuticals
Hydroxycarbamide Market
Pharmaceuticals
Global Ovulation Inducing Drugs Market
Pharmaceuticals
Josamycin Market
Pharmaceuticals
Middle-East and Africa Meglitinide Market
Pharmaceuticals
Global Cyclosporine Market
Pharmaceuticals
Antidotes Market