
 Pharmaceutical Wholesale & Distribution Market | 2026-2036
Pharmaceutical Wholesale & Distribution Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Wholesale & Distribution Market Insights
India's cold chain infrastructure build-out for temperature-sensitive biologics is fragmenting the traditional hub-and-spoke distribution model across South Asia. McKesson Corporation leverages its specialty pharmaceutical division to sustain dominance in oncology and rheumatology distribution networks. AmerisourceBergen Corporation anchors its competitive position through compliance-intensive cell and gene therapy logistics. Cardinal Health, Inc. differentiates via integrated inventory management systems serving hospital systems and ambulatory surgery centers.
Pharmaceutical wholesale and distribution encompasses the procurement, storage, transportation, and delivery of medicinal products from manufacturers to end-point dispensers, requiring validated cold chain protocols with temperature monitoring at 2-8°C for biologics and controlled ambient conditions for small-molecule drugs. The primary purpose is ensuring uninterrupted, compliant supply of therapies to healthcare institutions while maintaining chain-of-custody documentation and serialization traceability. Prescription drugs occupy the largest value pool within product type segmentation, though biologics command disproportionate margin concentration due to handling complexity and limited distributor certification. Retail pharmacies remain the highest-volume channel, yet online pharmacies represent the fastest structural expansion as direct-to-patient delivery models gain regulatory traction.
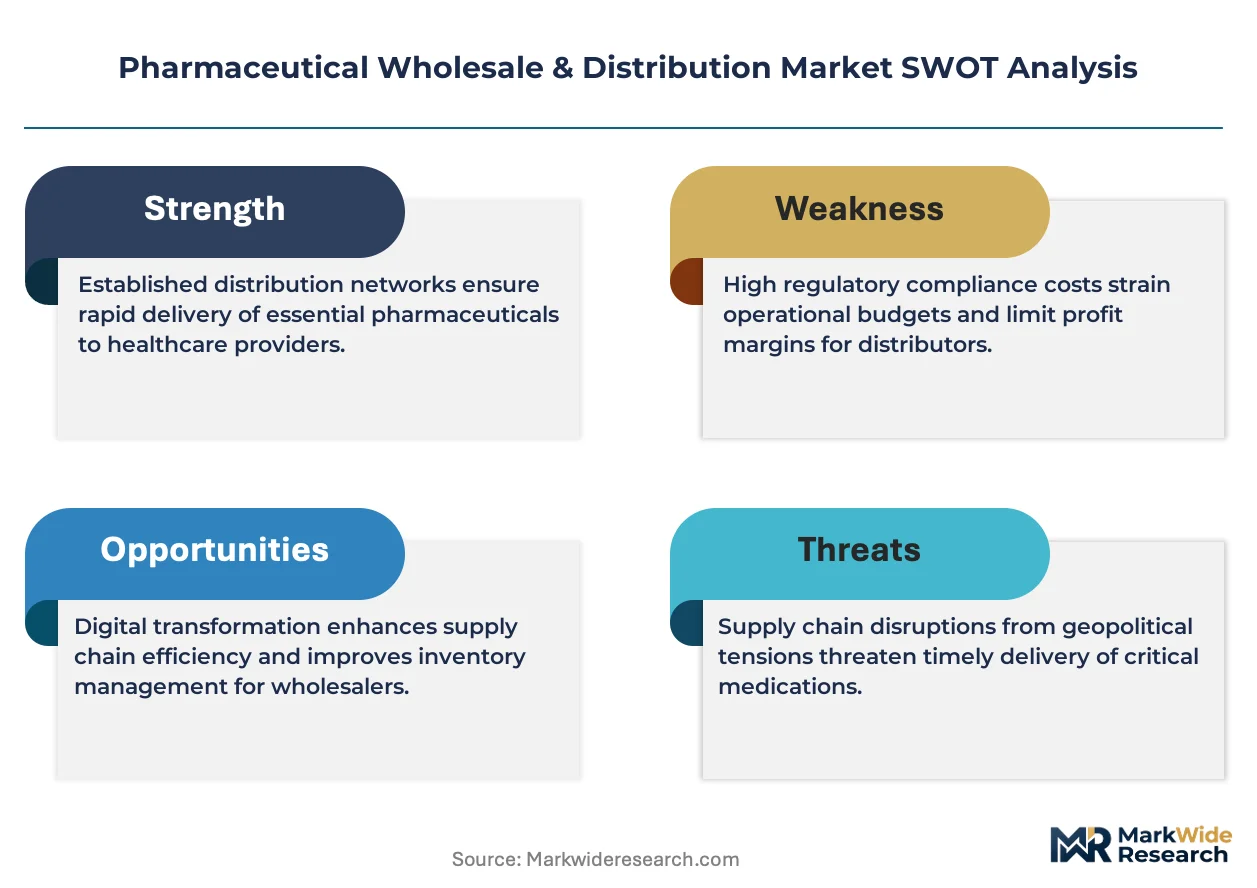
FDA serialization mandates under DSCSA, EU Falsified Medicines Directive (FMD) verification requirements, and WHO Good Distribution Practice (GDP) guidelines collectively elevate compliance costs while creating barriers to informal channel entry. These frameworks reshape competitive dynamics by favoring distributors with capital-intensive track-and-trace infrastructure over regional operators lacking serialization capabilities. Stakeholders must monitor evolving temperature excursion protocols for mRNA therapeutics and decide whether to build captive cold chain assets or outsource to qualified third-party logistics providers.
Market Dynamics
Specialty biologics procurement by hospital systems is concentrating purchasing power and forcing distributors to invest in validated cold chain infrastructure or exit high-margin therapeutic categories entirely.
Growth Catalysts
- FDA DSCSA Serialization Mandate:Track-and-trace requirements for unit-level verification are consolidating distributor tiers by excluding uncapitalized regional operators from prescription drug channels.
- Cell and Gene Therapy Logistics:Cryogenic transport requirements at minus 150 degrees Celsius are creating certified-handler scarcity that rewards early infrastructure investors with captive oncology and rare disease contracts.
- India Cold Chain Build-Out:Temperature-controlled warehousing expansion across South Asia is fragmenting hub-and-spoke models and enabling direct manufacturer-to-hospital distribution for biologics.
Market Restraints
- Refrigerant Cost Volatility:Specialized phase-change materials and dry ice sourcing for mRNA therapeutics expose distributors to input price swings that compress margin on fixed-fee logistics contracts.
- EU FMD Verification Infrastructure:Serial number authentication systems required at dispensing points impose capital burdens that disproportionately burden mid-tier wholesalers lacking enterprise IT scale.
- Biologics Handling Certification Scarcity:Limited WHO GDP-accredited cold chain facilities concentrate qualified capacity in fewer hands, creating bottlenecks for temperature-sensitive product launches.
Strategic Opportunities
- Direct-to-Patient Delivery Models:Regulatory traction for home infusion and specialty pharmacy shipping is opening last-mile logistics contracts previously held by retail pharmacy networks.
- AI-Enabled Temperature Monitoring:Predictive analytics converging with IoT sensor networks enables real-time excursion prevention that reduces product loss and differentiates service offerings.
- Brazil ANVISA Cold Chain Harmonization:Alignment with international GDP standards is creating upgrade demand for Latin American distributors seeking access to imported biologics portfolios.
Industry Challenges
- Serialization System Integration:Legacy warehouse management platforms require costly retrofitting to interface with FDA-mandated verification router systems, stretching implementation timelines.
- Cryogenic Handler Training Pipelines:Qualified technicians for liquid nitrogen logistics remain scarce, forcing distributors to build in-house certification programs or outsource to limited third-party providers.
- Multi-Temperature Lane Optimization:Simultaneous handling of ambient small-molecule, refrigerated biologic, and frozen gene therapy shipments within single distribution networks demands complex routing algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Wholesale & Distribution Market |
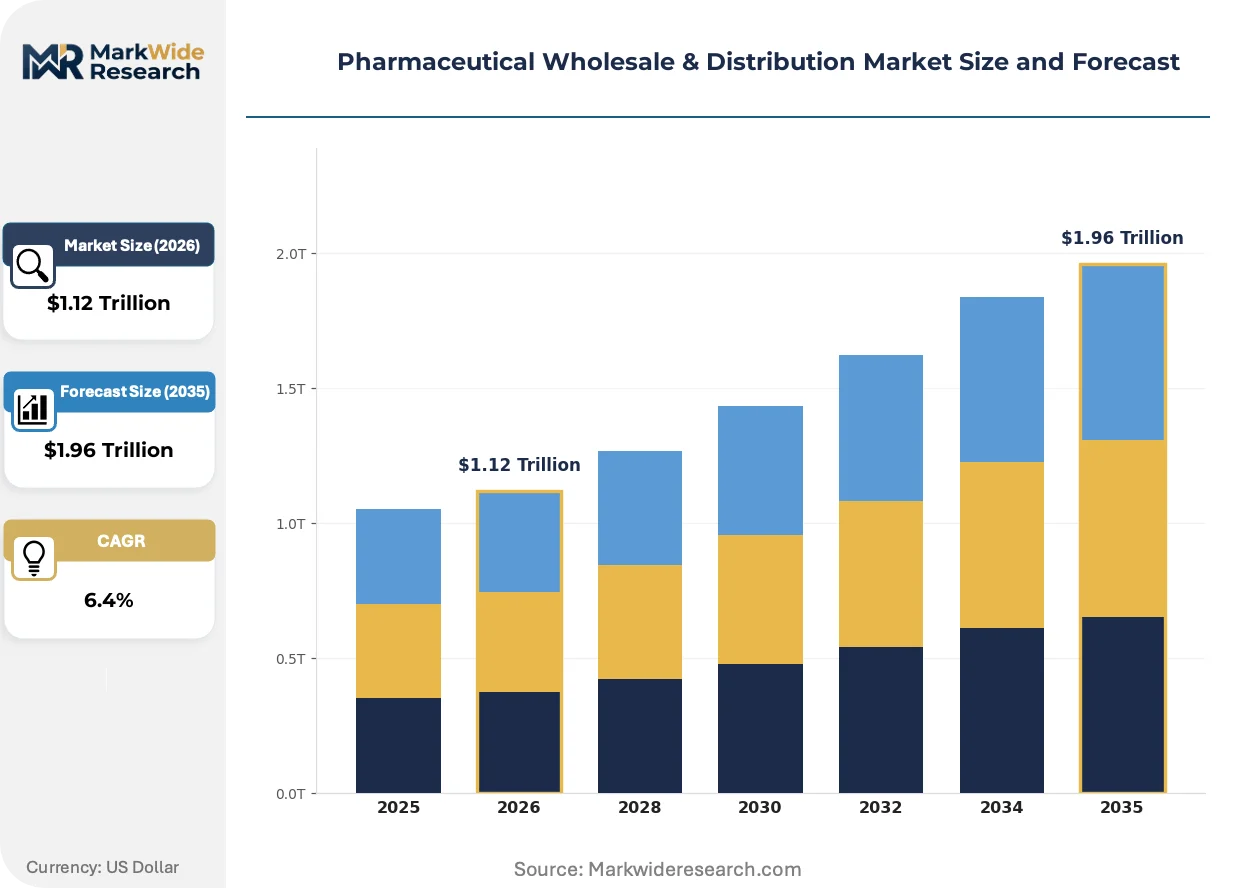
| Market Size in 2026 | $1.12 Trillion |
| Market Size in 2035 | $1.96 Trillion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, OTC Products, Biologics, Vaccines Distribution Channel: Retail Pharmacies, Hospitals, Clinics, Online Pharmacies Customer Type: Healthcare Providers, Distributors, Pharmacies, Wholesalers End User: Patients, Healthcare Institutions, Research Facilities, Care Homes |
| Companies Covered | China Resources Pharmaceutical Group Ltd., SUZUKEN CO. LTD., McKesson Corporation, Owens and Minor Inc., Shanghai Fosun Pharmaceutical Group Co. Ltd., AmerisourceBergen Corporation, Alfresa Holdings Corp., FFF Enterprises Inc., Cardinal Health, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Wholesale & Distribution Market Trends and Innovations
Real-time visibility infrastructure and predictive logistics platforms are compressing decision cycles across pharmaceutical distribution networks. These capabilities are redefining competitive advantage around exception prevention rather than exception response.
Blockchain-enabled chain-of-custody documentation is collapsing audit trail verification timelines from weeks to minutes. Hospital systems and specialty pharmacies are adopting this technology fastest where biologics value concentration justifies implementation cost. The structural consequence is collapsing insurance and liability overhead for high-value shipments as immutable records reduce dispute resolution friction.
EMA's strengthened GDP guidelines for controlled ambient products now mandate continuous temperature monitoring even for small-molecule drugs previously exempt from cold chain protocols. This regulatory expansion forces distributors to retrofit ambient warehousing with sensor networks or surrender volume to compliant competitors. Generic drug wholesalers across Germany and France are responding by consolidating into shared validation infrastructure to spread compliance costs.
Hospital procurement teams are consolidating vendor lists and demanding outcome-based logistics contracts that penalize temperature excursions and delivery failures. This buyer behavior shift displaces traditional fee-for-service arrangements with performance-guaranteed partnerships. The United States oncology center segment exhibits this pattern most acutely, where biologics spoilage costs have driven direct distributor accountability for product integrity.
Pharmaceutical Wholesale & Distribution Market Segmentation
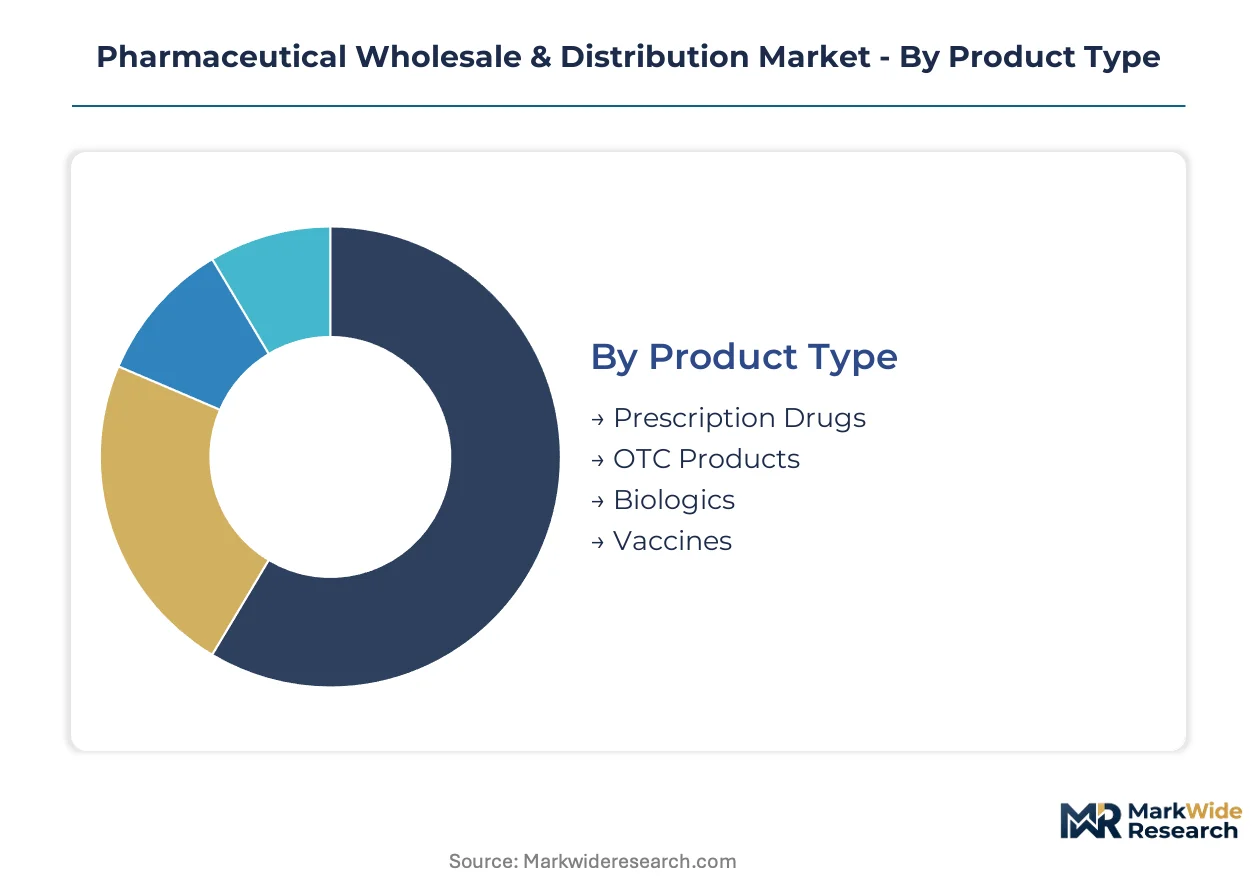
Segmentation in pharmaceutical distribution determines infrastructure requirements, margin structures, and compliance protocols. Cycle times vary dramatically across product types and channels, dictating working capital intensity and cold chain investment priorities.
Product Type:
Inventory velocity diverges sharply across this category, with small-molecule generics turning weekly while cell therapies require patient-matched fulfillment cycles measured in days.
- Prescription Drugs:Small-molecule formulations dominate transaction volumes through retail and hospital channels. Chronic disease maintenance therapies in the United States drive replenishment frequency, though generic price compression limits distributor margin capture.
- Biologics:Temperature-sensitive proteins and monoclonal antibodies demand validated 2-8°C cold chain infrastructure with continuous monitoring. Hospital procurement of oncology and immunology biologics concentrates purchasing power among distributors with GDP-accredited facilities.
- OTC Products:Ambient storage requirements and high SKU density characterize this segment, with convenience-driven replenishment cycles through retail pharmacy networks.
- Vaccines:Ultra-cold requirements for mRNA formulations and strict lot-level traceability under DSCSA mandate specialized handling protocols.
Prescription drugs anchor the volume base while biologics gains share at the steepest rate.
Distribution Channel:
Channel economics stratify by fulfillment complexity, with direct-to-patient models commanding premium service fees against traditional wholesale arrangements.
- Retail Pharmacies:Community-based dispensing networks handle the highest prescription volumes, requiring frequent just-in-time replenishment from regional distribution centers. Independent pharmacy consolidation in the United States is concentrating buyer power.
- Hospitals:Acute care institutions procure high-value specialty biologics through committed distribution partnerships, demanding 24-hour emergency availability and temperature excursion guarantees.
- Clinics:Outpatient infusion centers and physician offices represent fragmented demand with irregular ordering patterns.
- Online Pharmacies:Direct-to-patient shipping models bypass traditional wholesale tiers, requiring last-mile cold chain capabilities and patient signature verification.
Retail pharmacies still process the greatest prescription throughput, yet online pharmacies are climbing the fastest as home delivery gains regulatory traction.
Customer Type:
Margin capture potential varies by customer sophistication, with integrated health systems extracting volume discounts unavailable to fragmented independent buyers.
- Healthcare Providers:Hospital systems and integrated delivery networks negotiate outcome-based logistics contracts with penalty clauses for temperature excursions.
- Distributors:Secondary and tertiary wholesalers operate on thinner spreads, dependent upon primary distributor credit terms and inventory access.
- Pharmacies:Retail and specialty pharmacy buyers prioritize generic substitution incentives and rebate pass-through structures.
- Wholesalers:Regional operators face DSCSA compliance barriers that favor consolidation toward capitalized national platforms.
Healthcare providers drive the most demanding service requirements, while distributors face the steepest margin compression from serialization mandates.
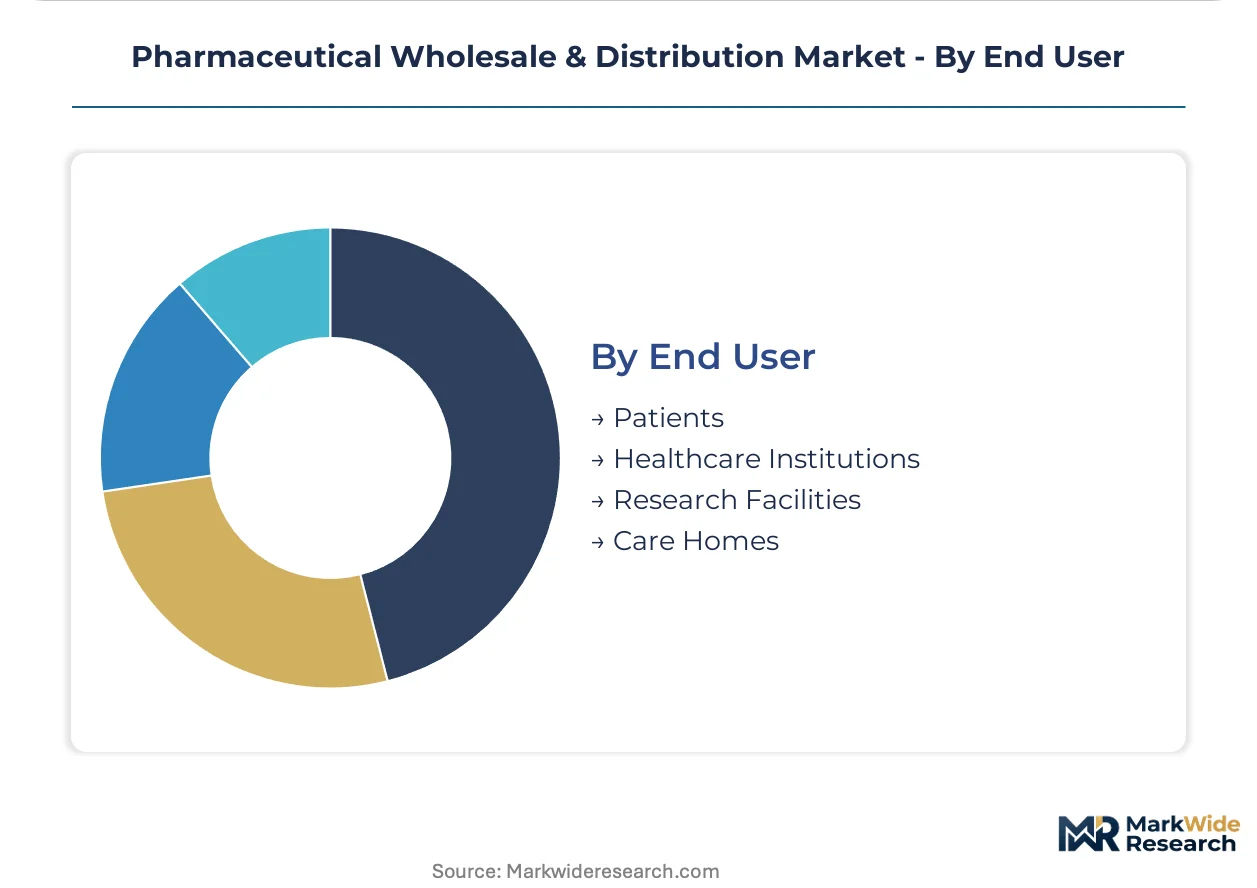
End User:
Ultimate consumption patterns determine packaging configurations, with institutional bulk formats diverging from patient-specific unit doses.
- Patients:Individual recipients of specialty therapies require patient-specific labeling, adherence packaging, and direct delivery coordination.
- Healthcare Institutions:Hospitals and health systems purchase in bulk quantities with formulary-driven generic substitution protocols.
- Research Facilities:Clinical trial supply chains demand chain-of-custody documentation and investigational product handling certification.
- Care Homes:Long-term care facilities generate steady demand for chronic disease medications with simplified administration packaging.
Healthcare institutions generate the largest order values, though patients receiving specialty therapies represent the fastest-expanding service requirement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA serialization mandates under DSCSA are reshaping distribution infrastructure requirements across the United States, while parallel regulatory frameworks in Europe and Asia-Pacific create divergent compliance cost structures for multinational operators.
United States
Hospital procurement consolidation is concentrating purchasing power among integrated delivery networks in Texas and Florida. FDA DSCSA unit-level verification deadlines are forcing regional wholesalers to merge or exit prescription drug channels entirely. McKesson Corporation anchors specialty oncology distribution from its Memphis and Louisville hubs.
Germany
EMA strengthened GDP guidelines now mandate continuous temperature monitoring for controlled ambient small-molecule drugs. Generic drug wholesalers in Bavaria and North Rhine-Westphalia are pooling validation infrastructure to spread compliance costs. The Frankfurt-Rhine-Main cluster hosts the densest concentration of GDP-accredited cold chain facilities in Europe.
India
Temperature-controlled warehousing expansion for biologics is fragmenting traditional hub-and-spoke models across Maharashtra and Gujarat. CDSCO alignment with WHO GDP standards is accelerating cold chain certification demand for export-oriented distributors. Hyderabad and Bangalore are emerging as specialized logistics clusters for temperature-sensitive pharmaceutical exports.
Japan
PMDA serialization requirements for prescription drugs are consolidating distributor tiers toward capitalized national platforms. Suzuken Co. Ltd. anchors wholesale networks serving Tokyo and Osaka metropolitan hospitals. The Kansai region exhibits the highest density of specialty pharmacy distribution points for oncology biologics.
Brazil
ANVISA cold chain harmonization with international GDP standards is creating upgrade demand for distributors seeking access to imported biologics portfolios. São Paulo and Rio de Janeiro concentrate qualified cold storage capacity for temperature-sensitive therapies. Hospital procurement teams in Southeast Brazil are consolidating vendor lists toward certified handlers.
Pharmaceutical Wholesale & Distribution Market Competitive Landscape
Integrated healthcare conglomerates and specialized pharmaceutical distributors split the market between scale-driven procurement leverage and compliance-intensive service differentiation. Three archetypes dominate: national full-line wholesalers with serialization infrastructure, specialty distributors with certified cold chain assets, and diversified healthcare conglomerates with captive distribution networks. M&A activity concentrates among mid-tier wholesalers seeking DSCSA compliance scale, while strategic partnerships between distributors and third-party logistics providers address cryogenic handler scarcity.
Within the integrated conglomerate tier, China Resources Pharmaceutical Group Ltd. and Shanghai Fosun Pharmaceutical Group Co. Ltd. exemplify state-affiliated operators with backward integration into manufacturing and forward control over hospital procurement channels. Among specialized wholesale operators, McKesson Corporation, AmerisourceBergen Corporation, and Cardinal Health, Inc. represent the capital-intensive archetype with enterprise-scale track-and-trace infrastructure and specialty pharmacy distribution networks. Suzuken Co. Ltd. anchors the Japan-centric model of regional dominance through dense last-mile coverage and hospital system integration.
| Leading Market Players |
|---|
| China Resources Pharmaceutical Group Ltd. |
| SUZUKEN CO. LTD. |
| McKesson Corporation |
| Owens and Minor Inc. |
| Shanghai Fosun Pharmaceutical Group Co. Ltd. |
| AmerisourceBergen Corporation |
| Alfresa Holdings Corp. |
| FFF Enterprises Inc. |
| Cardinal Health, Inc. |
| Others |
Pricing and Supply Chain Analysis
The Memphis-Louisville pharmaceutical freight corridor anchors North American distribution economics, where fuel and refrigerant cost swings compress margins for regional operators while rewarding national platforms with volume-negotiated carrier contracts and multi-temperature lane optimization capabilities.
Pricing Analysis
Price spreads between United States and Indian distribution markets reflect cold chain infrastructure gaps, with WHO GDP-certified handlers commanding premium-mid-economy pricing differentiation based on validation tier and temperature monitoring sophistication. Generic small-molecule wholesalers face intensifying cost compression as hospital procurement consolidation extracts volume rebates, while biologics distributors preserve margin through scarcity of cryogenic-certified technicians. Independent retail pharmacies exhibit highest price sensitivity due to reimbursement pressure, whereas integrated delivery networks prioritize performance guarantees over unit cost.
Supply Chain Analysis
Extended payment terms from hospital procurement teams now stretch 90-120 days, forcing distributors to deploy supply-chain finance facilities or surrender working capital advantage to better-capitalized competitors. Manufacturing concentration in India and China for active pharmaceutical ingredients creates API sourcing vulnerability, while specialized phase-change materials and dry ice for mRNA logistics introduce commodity price volatility. Single-source dependency on qualified liquid nitrogen handlers for gene therapy shipments constitutes the dominant structural risk. Distribution runs through hub-and-spoke regional centers for retail pharmacy replenishment, with direct-to-hospital models gaining share for specialty biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation across Texas and Florida health systems has shifted negotiating leverage toward buyers, fragmenting vendor lists and demanding outcome-based contracts with temperature excursion penalties.
For Market Incumbents: Harden serialization infrastructure against FDA DSCSA verification deadlines to exclude undercapitalized regional competitors from prescription drug channels. Deepen backward integration into captive cold chain assets for cell and gene therapy categories, as qualified cryogenic handler scarcity threatens service continuity for oncology contracts. For New Entrants and Emerging Players: Establish a beachhead in Brazil's ANVISA harmonization upgrade cycle, where GDP-certified cold storage capacity remains undersupplied for imported biologics distribution. Target Southeast Brazil hospital procurement teams consolidating vendor lists toward certified handlers, leveraging third-party logistics partnerships to bypass capital-intensive infrastructure buildout. For Investors and Strategic Acquirers: Mid-tier wholesalers with partial DSCSA compliance infrastructure represent the most actionable acquisition archetype, as regulatory deadlines force exit-or-merge decisions. Monitor FDA enforcement patterns around unit-level verification as the signal indicating consolidation velocity and distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Infrastructure Certification | WHO GDP accreditation unlocks oncology biologics contracts with hospital procurement teams. |
| Serialization System Integration | FDA DSCSA-compliant track-and-trace platforms exclude non-compliant regional competitors from channels. |
| Specialty Pharmacy Network Expansion | Direct-to-patient delivery capabilities capture last-mile logistics contracts from retail networks. |
| Cryogenic Handler Training Pipeline | In-house liquid nitrogen certification programs secure captive capacity for gene therapy distribution. |
| AI-Enabled Temperature Monitoring | Predictive IoT analytics reduce product loss and differentiate service offerings for biologics shippers. |
Research Methodology
A standing panel of hospital procurement managers, specialty pharmacy operators, cold chain logistics directors, and regulatory affairs leads provided ongoing calibration across primary fieldwork, supplemented by FDA DSCSA guidance documents, EMA GDP inspection reports, WHO distribution practice guidelines, and customs trade data for temperature-sensitive pharmaceutical flows. Bottom-up distributor capacity modeling triangulated against top-down prescription volume projections.
Scenario-bracketing around refrigerant cost volatility and serialization compliance timelines framed the analytical approach across the projection horizon. Segmentation dimensions encompassed product type, distribution channel, customer sophistication tier, and regional regulatory cluster. CAGRs derived from weighted average of historical infrastructure investment patterns and forward-looking biologics launch pipelines, with cell and gene therapy logistics penetration serving as a primary demand-side input.
Sensitivities concentrate around FDA enforcement intensity for DSCSA deadlines, cryogenic handler certification pipeline expansion rates, and hospital procurement consolidation velocity. Forecasts reflect documented assumptions regarding regulatory timeline adherence and infrastructure investment continuity. Macroeconomic contraction affecting healthcare capital expenditure, regulatory deadline extensions, or breakthroughs in ambient-stable biologic formulations would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Sterile Injectable Drugs Market
Pharmaceuticals
Flunarizine Hydrochloride Market
Pharmaceuticals
Europe Pharmaceutical Market
Pharmaceuticals
Famotidine Market
Pharmaceuticals
Asia-Pacific Human Papillomavirus Vaccine Market
Pharmaceuticals
Esomeprazole Market
Pharmaceuticals
Lipid Injectable Market
Pharmaceuticals
Global Acyclovir Market
Pharmaceuticals
Retinal Drugs and Biologics Market
Pharmaceuticals
Thin Film Drug Manufacturing Market
Pharmaceuticals
Opioid Analgesics Market
Pharmaceuticals
Thrombosis Drugs Market
Pharmaceuticals
Global Atosiban Market
Pharmaceuticals
OTC Analgesic Market
Pharmaceuticals
Liquid Filled Hard Capsules Market
Pharmaceuticals
Lamotrigine API Market