
 Injectable Ketamine Market | 2026-2036
Injectable Ketamine Market Size, Share, and Industry Trends Forecast 2026-2036
Injectable Ketamine Market Analytics
The capital-intensity divergence between sterile solution manufacturers and lyophilized powder specialists is unwinding competitive stability in injectable ketamine supply. Pfizer leverages captive parenteral manufacturing networks across North American hospital systems. Hikma Pharmaceuticals anchors its position through vertically integrated sterile injectable capacity in the Middle East and Europe. Fresenius Kabi dominates hospital-grade anesthesia procurement with dedicated critical-care distribution channels.
Injectable ketamine refers to sterile ketamine hydrochloride formulations administered parenterally, typically at concentrations of 50 mg/mL or 100 mg/mL for intravenous or intramuscular delivery, functioning as a dissociative anesthetic and rapid-acting antidepressant in clinical settings. The therapy area segment shows depression and PTSD applications outpacing traditional anesthesia volumes as esketamine regulatory pathways expand psychiatric administration. Intravenous delivery mode retains the largest revenue pool due to hospital protocol standardization, while subcutaneous formulations attract outpatient clinic investment for chronic pain management.
FDA REMS protocols and EMA pharmacovigilance frameworks constrain manufacturing standards and prescriber certification requirements for esketamine and racemic ketamine products. The Drug Enforcement Administration's Schedule III classification in the United States imposes quota-based production limits that shape supply allocation across anesthesia and psychiatric indications. Stakeholders must monitor evolving DEA manufacturing quotas against expanding depression clinic networks to calibrate capacity investments.
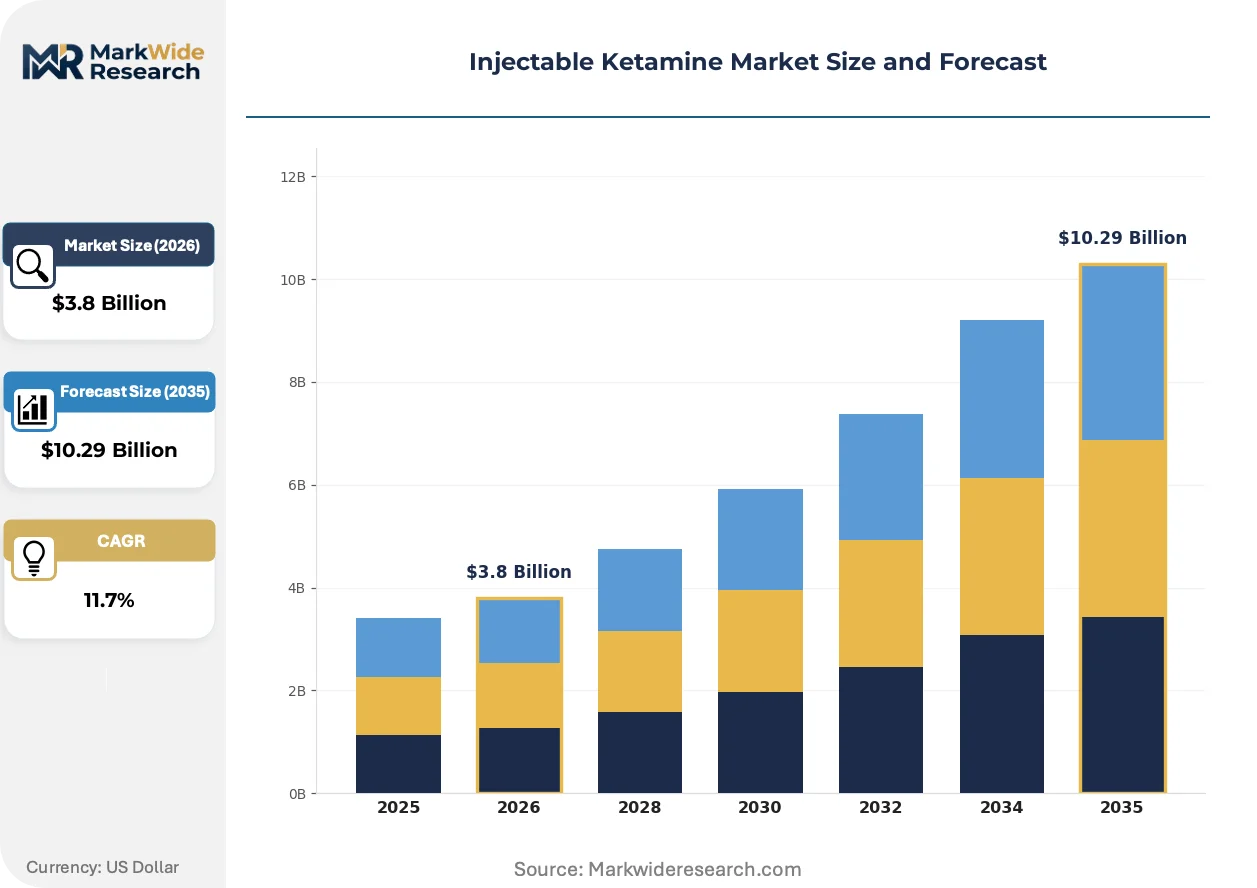
Market Dynamics
The Injectable Ketamine Market is bifurcating between hospital anesthesia procurement and outpatient psychiatric administration, with DEA Schedule III quotas forcing manufacturers to allocate sterile capacity across competing therapeutic areas.
Growth Catalysts
- FDA REMS certification expansion:The Risk Evaluation and Mitigation Strategy framework for esketamine is training prescribers in certified treatment centers, expanding the addressable patient base for intravenous depression protocols.
- Lyophilized powder manufacturing:Advanced freeze-drying technologies are extending shelf stability and reducing cold-chain dependency for clinic networks in the United States.
- Psychiatric clinic density:Specialized ketamine infusion centers in California, Texas, and Florida are creating concentrated demand pockets that justify dedicated distribution infrastructure.
Market Restraints
- DEA quota allocation rigidity:Annual production limits for Schedule III substances constrain supply elasticity when psychiatric demand surges beyond anesthesia baselines.
- Sterile API concentration:Active pharmaceutical ingredient synthesis for injectable-grade ketamine concentrates among specialized chemical manufacturers in India and China, creating single-source vulnerability.
- Esketamine patent exclusivity:Johnson & Johnson's intellectual property position on the S-enantiomer formulation limits generic substitution in depression indications.
Strategic Opportunities
- Subcutaneous delivery innovation:Needle-free jet injectors and micro-needle arrays are opening home-administration pathways for chronic pain patients outside clinic settings.
- EMA centralized procedure alignment:The European Medicines Agency's mutual recognition framework is streamlining cross-border psychiatric protocol approvals in Germany, France, and the Netherlands.
- Veterans Affairs integration:The US Department of Veterans Affairs is embedding ketamine protocols into PTSD treatment pathways at medical centers across the Southeast and Pacific Northwest.
Industry Challenges
- Sterile manufacturing workforce scarcity:Aseptic processing technicians with parenteral drug experience command premium wages in biologics hubs, diverting talent from generic injectable facilities.
- REMS compliance infrastructure:Certified treatment center requirements demand patient monitoring systems and prescriber training programs that inflate operational overhead for clinic operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Injectable Ketamine Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sterile Solutions, Lyophilized Powder, Injectable Devices, Vials Therapy Area: Chronic Pain, Depression, Anesthesia, PTSD Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Inhalation End User: Hospitals, Clinics, Rehabilitation Centers, Homecare |
| Companies Covered | Pfizer, Hikma Pharmaceuticals, Teva Pharmaceutical Industries, Fresenius Kabi, Johnson & Johnson, Sun Pharmaceuticals, Troikaa Pharmaceuticals, Greenco Biologicals, Viatris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Injectable Ketamine Market Evolving Landscape
Injectable ketamine delivery is diversifying beyond intravenous infusion toward patient-administered alternatives, while regulatory frameworks simultaneously tighten manufacturing standards and expand prescriber pools.
Ready-to-use prefilled syringe formats are fragmenting traditional vial-and-diluent workflows in hospital anesthesia suites. Surgical centers in the United States are adopting these single-unit presentations to reduce compounding errors and pharmacy labor. This format shift is fragmenting procurement patterns, with group purchasing organizations now negotiating separate contracts for presentation types rather than active ingredient volumes alone.
The FDA's updated guidance on complex generic injectables is elevating bioequivalence demonstration requirements for racemic ketamine alternatives. Manufacturers must now conduct more extensive pharmacokinetic studies to prove therapeutic equivalence to reference listed drugs. This regulatory tightening most affects ANDA filers targeting the 50 mg/mL anesthesia segment, forcing extended development timelines and higher clinical trial investment.
Psychiatric practices are consolidating purchasing through specialty pharmacy intermediaries rather than direct wholesaler relationships. These intermediaries aggregate demand across multiple clinic locations and negotiate volume-based pricing with sterile injectable distributors. The intermediation trend is most pronounced in metropolitan corridors of New York, Illinois, and Massachusetts, where clinic density supports hub-and-spoke distribution models.
Injectable Ketamine Market Segmentation
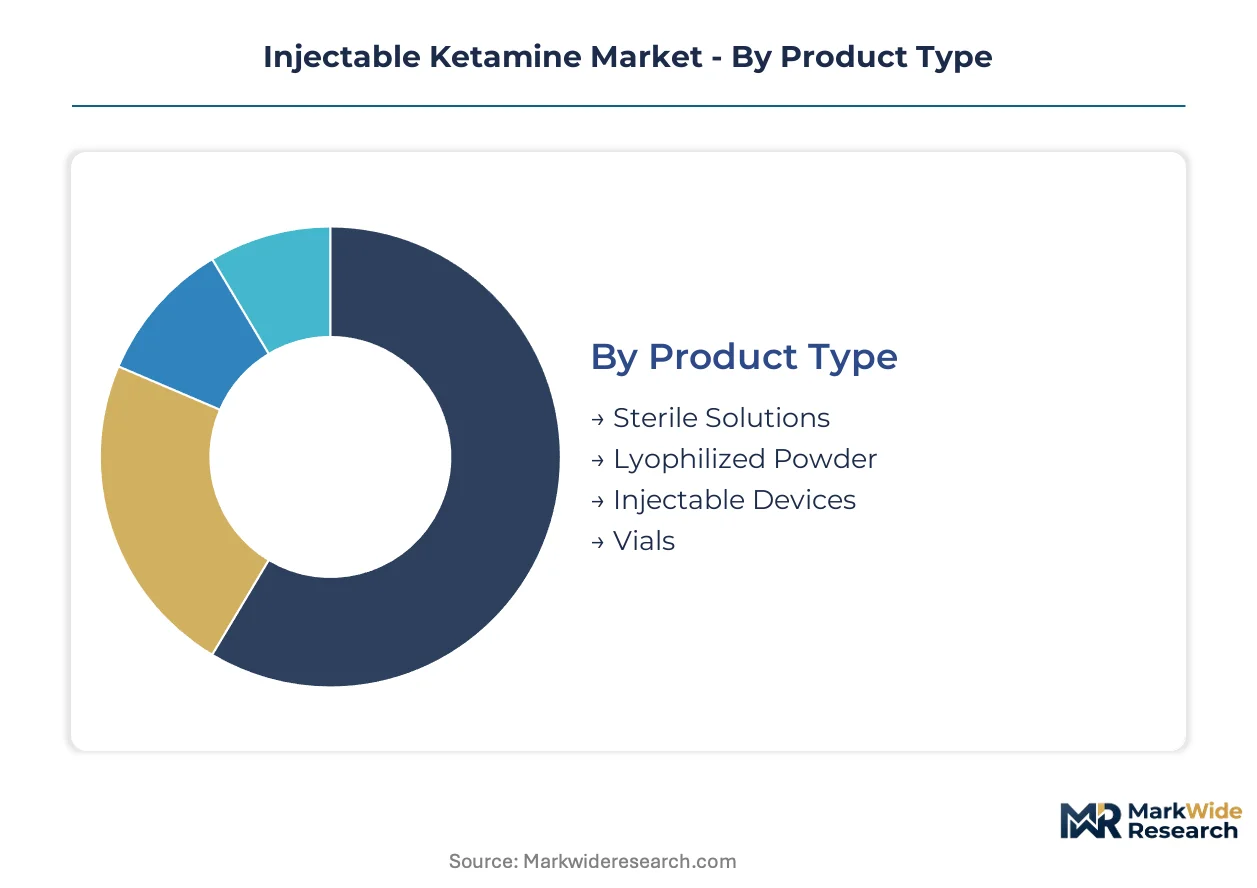
Injectable ketamine procurement patterns diverge sharply across therapeutic applications and institutional settings. Manufacturers calibrate sterile capacity, presentation formats, and distribution channels against distinct compliance requirements and administration protocols.
Product Type:
Domestic production concentrates in sterile solutions for hospital anesthesia suites, while lyophilized powder capacity serves export markets and psychiatric clinic networks with extended shelf-life requirements.
- Sterile Solutions:Ready-to-administer liquid formulations at 50 mg/mL and 100 mg/mL concentrations dominate operating room workflows. US hospital systems under FDA REMS protocols absorb the majority of domestic output, with Fresenius Kabi and Pfizer anchoring supply through captive parenteral networks.
- Lyophilized Powder:Freeze-dried ketamine hydrochloride extends stability beyond 24 months and reduces cold-chain dependency for outpatient clinics. California, Texas, and Florida psychiatric networks are driving concentrated demand for reconstitution-flexible formats that support variable dosing protocols.
- Injectable Devices:Prefilled syringes and auto-injector platforms are fragmenting traditional vial-based procurement in ambulatory surgical centers.
- Vials:Multi-dose glass containers retain cost advantage in high-volume anesthesia procurement through group purchasing organization contracts.
Sterile solutions command the established base. The steepest expansion runs through lyophilized powder.
Therapy Area:
Cost tier differentiation separates commodity anesthesia procurement from premium-priced psychiatric administration under REMS certification requirements.
- Chronic Pain:Off-label ketamine infusion protocols for neuropathic and complex regional pain syndromes are expanding through specialty pain clinics in Illinois and Massachusetts. Subcutaneous delivery innovation is opening home-administration pathways outside traditional clinic settings.
- Depression:Esketamine nasal spray and racemic ketamine IV protocols under FDA REMS are the fastest-climbing revenue segment. Johnson & Johnson's Spravato certification network and independent ketamine infusion centers in New York metropolitan corridors are driving prescriber pool expansion.
- Anesthesia:Traditional dissociative anesthetic applications in emergency departments and surgical suites represent the volume foundation.
- PTSD:Veterans Affairs medical centers across the Southeast and Pacific Northwest are embedding ketamine protocols into standardized PTSD treatment pathways.
Anesthesia commands the established base. The steepest expansion runs through depression.
Delivery Mode:
Application-specific administration requirements dictate device investment and prescriber training intensity across institutional settings.
- Intravenous:Precision-controlled infusion pumps in hospital anesthesia suites and certified psychiatric treatment centers enable titrated dosing with continuous monitoring. This mode retains the largest revenue pool due to protocol standardization and REMS compliance infrastructure.
- Subcutaneous:Micro-needle arrays and needle-free jet injectors are attracting outpatient clinic investment for chronic pain patients seeking alternatives to IV clinic visits. Device manufacturers are targeting home-administration regulatory pathways.
- Intramuscular:Emergency department and battlefield anesthesia applications favor rapid-onset IM delivery without vascular access requirements.
- Inhalation:Nebulized and intranasal formulations remain investigational for psychiatric indications outside esketamine's approved pathway.
Intravenous delivery commands the established base. The steepest expansion runs through subcutaneous innovation.
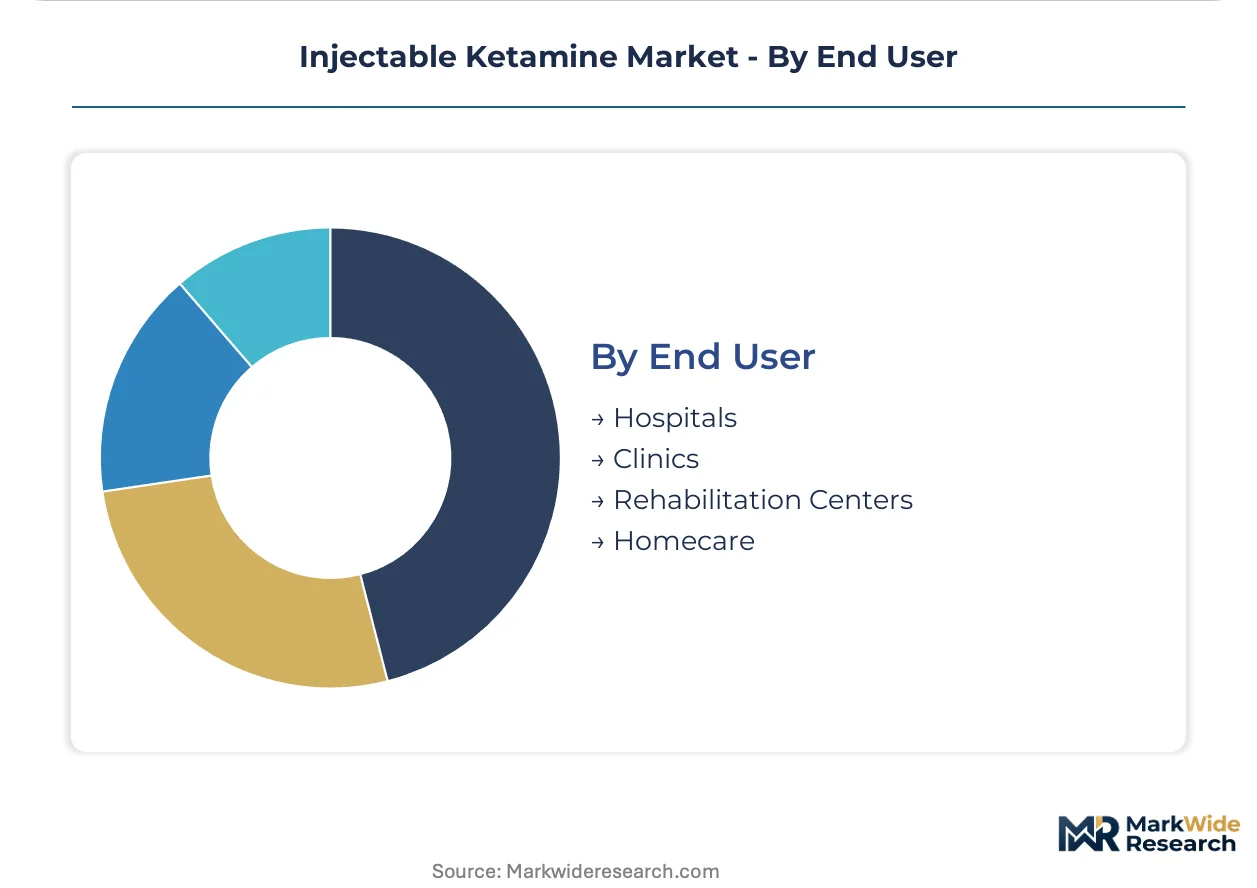
End User:
Customer type determines procurement scale, pricing leverage, and compliance overhead across the supply chain.
- Hospitals:Integrated delivery networks and academic medical centers negotiate multi-year anesthesia contracts through group purchasing organizations. DEA Schedule III quota allocation prioritizes hospital procurement under established surgical volume baselines.
- Clinics:Specialized ketamine infusion centers and psychiatric practices are consolidating purchasing through specialty pharmacy intermediaries rather than direct wholesaler relationships. Hub-and-spoke distribution models concentrate in metropolitan corridors.
- Rehabilitation Centers:Sub-acute facilities are adopting ketamine protocols for chronic pain and mood disorder comorbidities in post-surgical recovery populations.
- Homecare:Subcutaneous device approval would unlock direct-to-patient delivery for chronic pain management outside institutional settings.
Hospitals command the established base. The steepest expansion runs through clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in India by a factor reflecting DEA quota scarcity against API manufacturing abundance. German hospital networks command premium positioning through EMA centralized certification pathways. Chinese export volumes face tariff friction that Japanese domestic producers bypass entirely.
United States
Psychiatric clinic density in California, Texas, and Florida drives concentrated lyophilized powder procurement. FDA REMS protocols for esketamine mandate certified treatment center infrastructure that inflates operational overhead. The Veterans Affairs medical centers across the Southeast and Pacific Northwest embed ketamine protocols into standardized PTSD treatment pathways.
Germany
EMA pharmacovigilance frameworks align cross-border psychiatric protocol approvals with France and the Netherlands. The country's national pharmaceutical regulator enforces manufacturing standards that exceed baseline EU requirements. Hospital networks in Bavaria and North Rhine-Westphalia anchor anesthesia procurement through group purchasing organization contracts.
China
Active pharmaceutical ingredient synthesis for injectable-grade ketamine concentrates among specialized chemical manufacturers in Jiangsu and Zhejiang provinces. NMPA oversight of sterile manufacturing facilities shapes export qualification timelines. The Yangtze River Delta region hosts multiple API specialists serving international generic injectable formulators.
India
CDSCO licensing requirements for Schedule H substances constrain domestic formulation capacity expansion. Sterile API production clusters in Hyderabad and Ahmedabad supply global generic injectable manufacturers. Export-oriented manufacturers face pricing pressure from US buyers negotiating volume-based contracts.
United Kingdom
NHS England's specialized commissioning frameworks determine reimbursement for ketamine depression protocols in London and Southeast hospital trusts. MHRA post-Brexit regulatory autonomy creates divergence from EMA centralized procedures. Academic medical centers in Greater Manchester and the Midlands pilot subcutaneous delivery innovation for chronic pain management.
Injectable Ketamine Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with sterile manufacturing expertise separating premium-positioned suppliers from commodity API sources. The market structure concentrates around three tiers: multinational parenteral specialists with captive hospital networks, vertically integrated generic injectable manufacturers, and regional API-to-formulation specialists. Pfizer exemplifies the first archetype through North American distribution infrastructure. Hikma Pharmaceuticals represents the second through Middle East and European sterile capacity. Strategic moves center on REMS compliance infrastructure investment and lyophilized powder capacity expansion for psychiatric clinic networks.
Among the named multinational specialists, Pfizer, Hikma Pharmaceuticals, and Fresenius Kabi occupy positions reflecting distinct geographic and capability anchors. Pfizer represents the hospital-captive distribution model with North American parenteral network control. Hikma Pharmaceuticals exemplifies vertically integrated sterile injectable capacity spanning Middle Eastern and European manufacturing bases. Fresenius Kabi anchors critical-care anesthesia procurement through dedicated hospital-grade distribution channels. Johnson & Johnson's position reflects esketamine patent exclusivity rather than generic injectable manufacturing scale. These company patterns illustrate how regulatory compliance infrastructure and sterile manufacturing certification separate sustainable competitive positions from commodity API trading.
| Leading Market Players |
|---|
| Pfizer |
| Hikma Pharmaceuticals |
| Teva Pharmaceutical Industries |
| Fresenius Kabi |
| Johnson & Johnson |
| Sun Pharmaceuticals |
| Troikaa Pharmaceuticals |
| Greenco Biologicals |
| Viatris |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between hospital systems and sterile injectable manufacturers lock in DEA quota allocation visibility while insulating psychiatric clinic networks from spot-market volatility in lyophilized powder supply. These contracts tether pricing stability to captive parenteral manufacturing networks, creating divergent cost structures across anesthesia procurement and depression protocol administration.
Pricing Analysis
The customization-premium spread between standard 50 mg/mL anesthesia vials and patient-specific compounded formulations for psychiatric infusion centers exceeds threefold. Three-tier pricing structure across REMS-certified, hospital-grade, and export-generic levels segments buyers by compliance overhead and volume commitment. Pricing pressure stems from DEA quota scarcity against expanding clinic network demand, compressing margins for non-integrated distributors. Academic medical centers exhibit lowest price sensitivity due to bundled procurement through group purchasing organizations, while independent ketamine infusion centers in metropolitan corridors face acute cost transparency.
Supply Chain Analysis
Inventory cycles for sterile API extend six to nine months from Indian and Chinese chemical manufacturers through European formulation sites to United States distribution hubs. Active pharmaceutical ingredient synthesis concentrates in Jiangsu and Zhejiang provinces, with sterile finishing capacity anchored in Germany and the United States. Supply chain risk centers on single-source vulnerability for Schedule III quota allocation under DEA manufacturing limits. Distribution runs through specialty pharmacy intermediaries consolidating psychiatric clinic demand in hub-and-spoke models across California, Texas, and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sustainable positioning in this market hinges on scarce aseptic processing certification and REMS compliance infrastructure, assets that concentrate among established parenteral specialists. New capacity entrants face eighteen-to-twenty-four month qualification timelines that entrench incumbent advantage.
For Market Incumbents: Fortify sterile manufacturing certification through EMA centralized procedure alignment and DEA quota allocation negotiation, defending against API-to-formulation specialists in India and China seeking backward integration into finished dose supply. Prioritize lyophilized powder capacity expansion in United States distribution hubs to capture psychiatric clinic network growth. For New Entrants and Emerging Players: FDA REMS certification fast-track for subcutaneous delivery devices offers the most penetrable entry vector, targeting chronic pain home-administration pathways outside established IV clinic infrastructure. Sub-specialty pain networks in Illinois and Massachusetts present consolidated demand pockets for micro-needle array platforms seeking regulatory approval outside hospital settings. For Investors and Strategic Acquirers: Regional API-to-formulation specialists with captive sterile capacity in Hyderabad and Ahmedabad represent the optimal acquisition archetype, offering vertical control over supply from chemical synthesis through finished dose. Monitor DEA manufacturing quota expansion announcements as the critical inflection signal for capacity investment viability across the analysis window.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Compliance Infrastructure Investment | Certified treatment center networks unlock esketamine and racemic ketamine psychiatric protocol expansion under FDA mandates. |
| Lyophilized Powder Capacity Expansion | Freeze-dried formulations reduce cold-chain dependency for California and Texas clinic networks with extended shelf stability. |
| Subcutaneous Device Regulatory Pathway | Needle-free jet injectors enable home-administration for chronic pain patients outside institutional infusion settings. |
| Specialty Pharmacy Intermediary Partnership | Hub-and-spoke distribution models consolidate purchasing power across New York and Massachusetts metropolitan clinic corridors. |
| Veterans Affairs Protocol Integration | Southeast and Pacific Northwest medical centers embed ketamine into standardized PTSD treatment pathways with federal procurement scale. |
Research Methodology
Initial hypotheses were tested against primary input from regulatory affairs leads at sterile injectable manufacturers, hospital procurement managers in academic medical centers, and psychiatric clinic operators, then refined through secondary validation against FDA REMS program documentation, DEA quota allocation records, and EMA pharmacovigilance frameworks. Bottom-up demand modeling across therapy areas and delivery modes was triangulated with top-down market sizing from sterile API trade flows and finished dose import data.
Variance decomposition across the projection horizon isolates volume drivers by therapy area, product format, and end-user institution type, with CAGRs derived from segmented growth rate reconciliation against macro healthcare expenditure trends. Modeled inputs include DEA Schedule III quota expansion scenarios, psychiatric clinic network density projections, and subcutaneous device approval timelines.
Decision-makers should treat outputs as directional under assumptions of stable DEA regulatory frameworks and continued REMS certification expansion; material deviation in quota allocation policy or esketamine patent litigation outcomes would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Pharmaceutical Elixir Market
Pharmaceuticals
United States Pharmaceutical 3PL Market
Pharmaceuticals
In-Silico Drug Discovery Market
Pharmaceuticals
Fusion Inhibitors Market
Pharmaceuticals
Global Rx to OTC Switches Market
Pharmaceuticals
Tranquilizer Drugs Market
Pharmaceuticals
Teriflunomide Market
Pharmaceuticals
Dual Migraine Treatment Market
Pharmaceuticals
Intranasal Migraine Drugs Market
Pharmaceuticals
Pantoprazole Market
Pharmaceuticals
South Africa Diabetes Drugs Market
Pharmaceuticals
Computer-Aided Drug Discovery Market
Pharmaceuticals
Asia-Pacific Meglitinide Market
Pharmaceuticals
Zoldonat Injection Market
Pharmaceuticals
Global Lidocaine Transdermal Patch Market
Pharmaceuticals
North America Dipeptide Peptidase 4 (Dpp-4) Inhibitors Market