
 Prothrombin Complex Concentrate (PCC) Market | 2026-2036
Prothrombin Complex Concentrate (PCC) Market Size, Share, and Industry Trends Forecast 2026-2036
Prothrombin Complex Concentrate (PCC) Market Intelligence
The divergence in plasma collection and fractionation scale is rotating competitive dynamics among manufacturers. CSL Behring leverages its extensive global plasma collection network to ensure a consistent supply of critical raw material. Grifols S.A. sustains its market position through deep specialization in a broad portfolio of plasma-derived therapies. Octapharma AG competes by focusing its portfolio on hematology and critical care indications for hospital settings.
Prothrombin Complex Concentrate is a sterile, lyophilized product derived from large pools of human plasma. It contains a standardized, concentrated mix of vitamin K-dependent coagulation factors—typically II, VII, IX, and X—designed for rapid hemostasis. The 4-Factor PCC product segment leads the market, offering more complete and balanced hemostatic correction than older 3-Factor PCC formulations, especially for warfarin reversal. Among indications, trauma-induced coagulopathy represents the fastest-growing application area, complementing established use in treating congenital bleeding disorders like hemophilia.
Market access is governed by stringent regulations from national health authorities like the US FDA, the European Medicines Agency (EMA), and China's NMPA. These bodies enforce strict guidelines on plasma sourcing, viral inactivation processes, and batch-to-batch consistency to ensure product safety and efficacy. Future success for manufacturers depends on securing stable, high-quality plasma supplies and effectively navigating disparate reimbursement frameworks across national hospital systems.
Market Dynamics
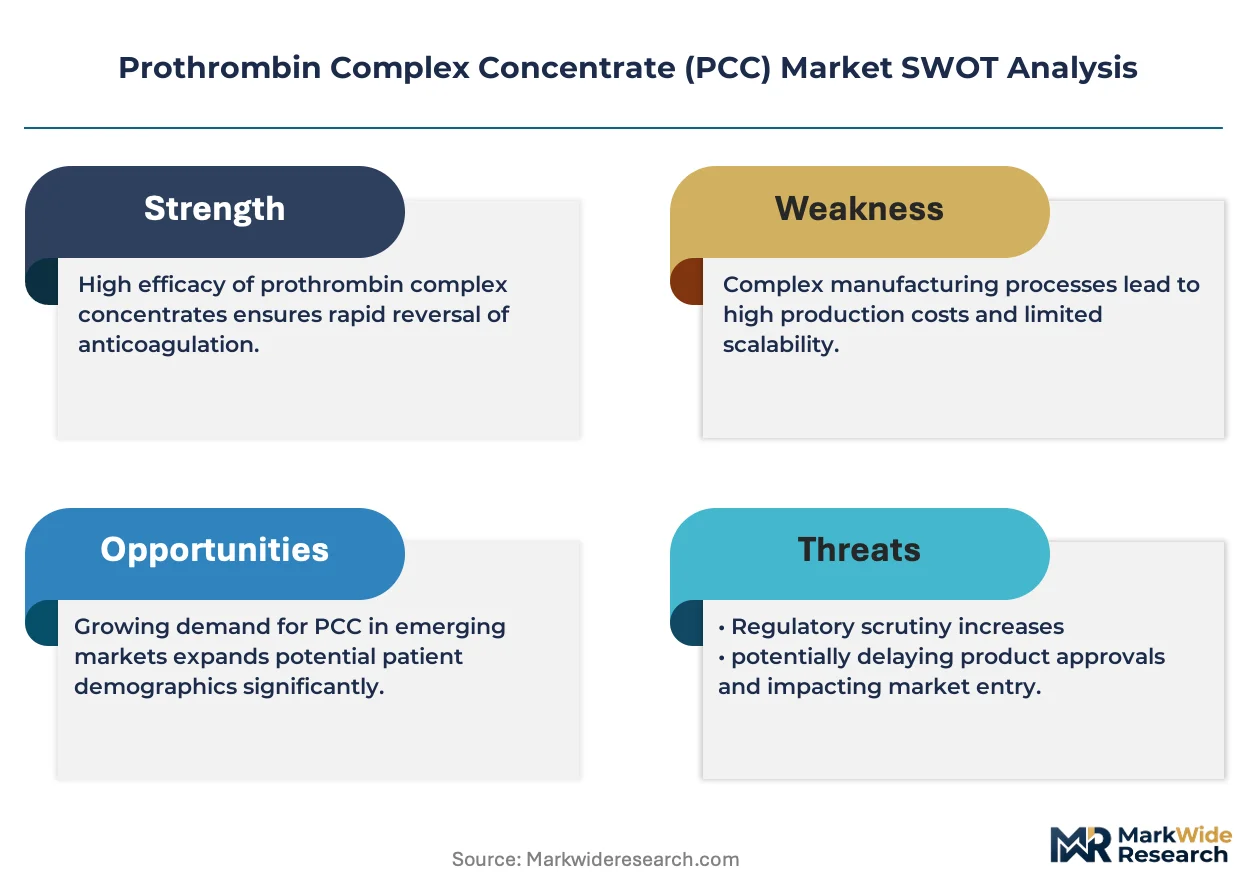
The market's central tension lies in securing a vast, consistent supply of human plasma while simultaneously mastering the highly specialized, capital-intensive fractionation processes required to produce safe and effective concentrates. This dynamic favors large-scale, vertically integrated manufacturers who can control the supply chain from donor to final product.
Growth Catalysts
- Anticoagulant Reversal:High use of anticoagulants in aging populations creates steady demand for PCC as a rapid reversal agent in emergency medicine.
- Trauma Care Advancement:Modern trauma protocols increasingly incorporate PCC for managing severe hemorrhage, moving it into front-line critical care applications.
- Supportive Regulatory Guidance:The FDA's framework for blood product development and EMA's focus on plasma safety encourage innovation in safer PCC formulations.
Market Restraints
- Plasma Supply Volatility:The supply chain's reliance on a limited human plasma donor base creates vulnerability to collection disruptions and sourcing risks.
- Inherent Thrombotic Risk:The clinical risk of thromboembolic events necessitates careful patient selection and monitoring, restricting PCC's broader application.
- Complex Regulatory Pathways:Securing approvals from agencies like the EMA or NMPA is a lengthy and costly process, creating high barriers to market entry.
Strategic Opportunities
- Emerging Market Penetration:Developing trauma care systems in nations like Brazil and India offer significant growth potential for PCC manufacturers.
- New Surgical Applications:Formalizing PCC use through clinical trials for perioperative bleeding in cardiac surgery presents a substantial new market segment.
- Recombinant Factor Innovation:Long-term investment in non-plasma-derived recombinant coagulation factors could circumvent sourcing volatility and enhance product safety.
Industry Challenges
- Cold Chain Logistics:Maintaining the integrity of the cold chain from plasma collection to final product distribution is a complex and costly operational challenge.
- Manufacturing Compliance Burden:Adhering to stringent viral inactivation and batch consistency standards set by regulators like the PMDA in Japan requires significant ongoing investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prothrombin Complex Concentrate (PCC) Market |
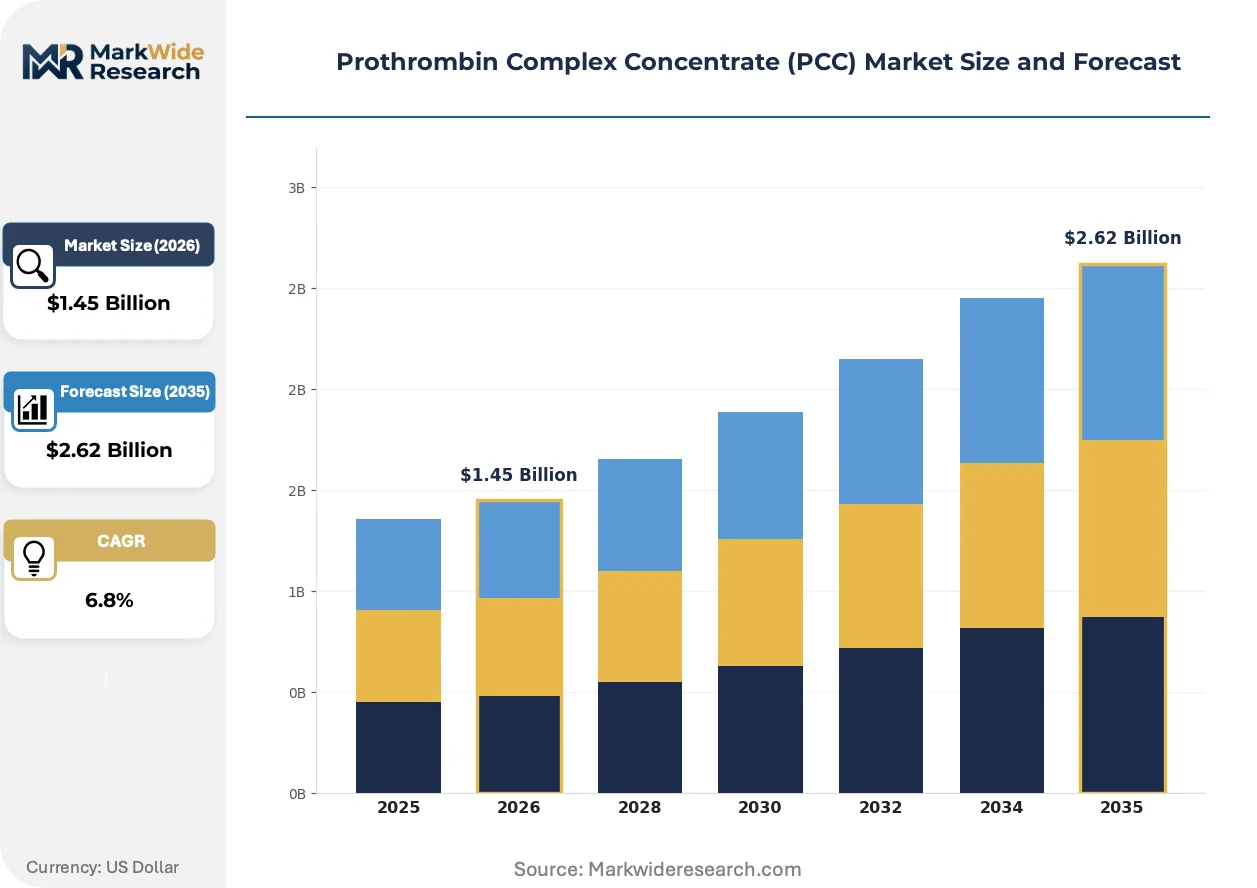
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 4-Factor PCC, 3-Factor PCC, Activated PCC, Non-Activated PCC Indication: Warfarin Reversal, Hemophilia Treatment, Vitamin K Deficiency, Liver Disease Coagulopathy, Trauma-Induced Coagulopathy End User: Hospitals, Specialty Clinics, Emergency Care Units, Blood Banks Administration Route: Intravenous, Intramuscular, Subcutaneous, Oral |
| Companies Covered | CSL Behring, Grifols S.A., Octapharma AG, Takeda Pharmaceutical Company Limited, Kedrion Biopharma, Sanquin, China Biologic Products Holdings, Inc., Nihon Pharmaceutical Co. Ltd., Biotest AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prothrombin Complex Concentrate (PCC) Market Strategic Shifts & Innovations
Product evolution is centered on enhancing safety and precision, moving beyond broad-spectrum hemostasis toward targeted, evidence-guided interventions. This shift is driven by a convergence of advanced diagnostics, stricter regulatory oversight, and refined clinical protocols in emergency medicine.
Advanced purification techniques, such as chromatography and nanofiltration, are now standard for improving the safety of plasma-derived PCC. Critical care physicians and hematologists are increasingly specifying products that utilize these modern processes. This focus on purity is decomposing the monolithic product category, creating a clear distinction between older formulations and newer, safer concentrates.
The European Medicines Agency (EMA) has intensified its oversight of plasma-derived medicinal products, mandating greater transparency in plasma sourcing and donor traceability. This regulatory pressure compels manufacturers to invest in sophisticated quality management and supply chain tracking systems. Hospital procurement departments in the EU are most affected, now prioritizing suppliers who can provide robust documentation of compliance with these stringent standards.
A notable shift in clinical practice involves moving from fixed-dosing regimens to individualized therapy guided by point-of-care viscoelastic tests like ROTEM. This disrupts traditional administration protocols by enabling physicians to titrate PCC dosage based on a patient's specific coagulation profile. The practice is most advanced within major trauma centers in the United States and Germany, optimizing efficacy while minimizing risks.
Prothrombin Complex Concentrate (PCC) Market Segmentation
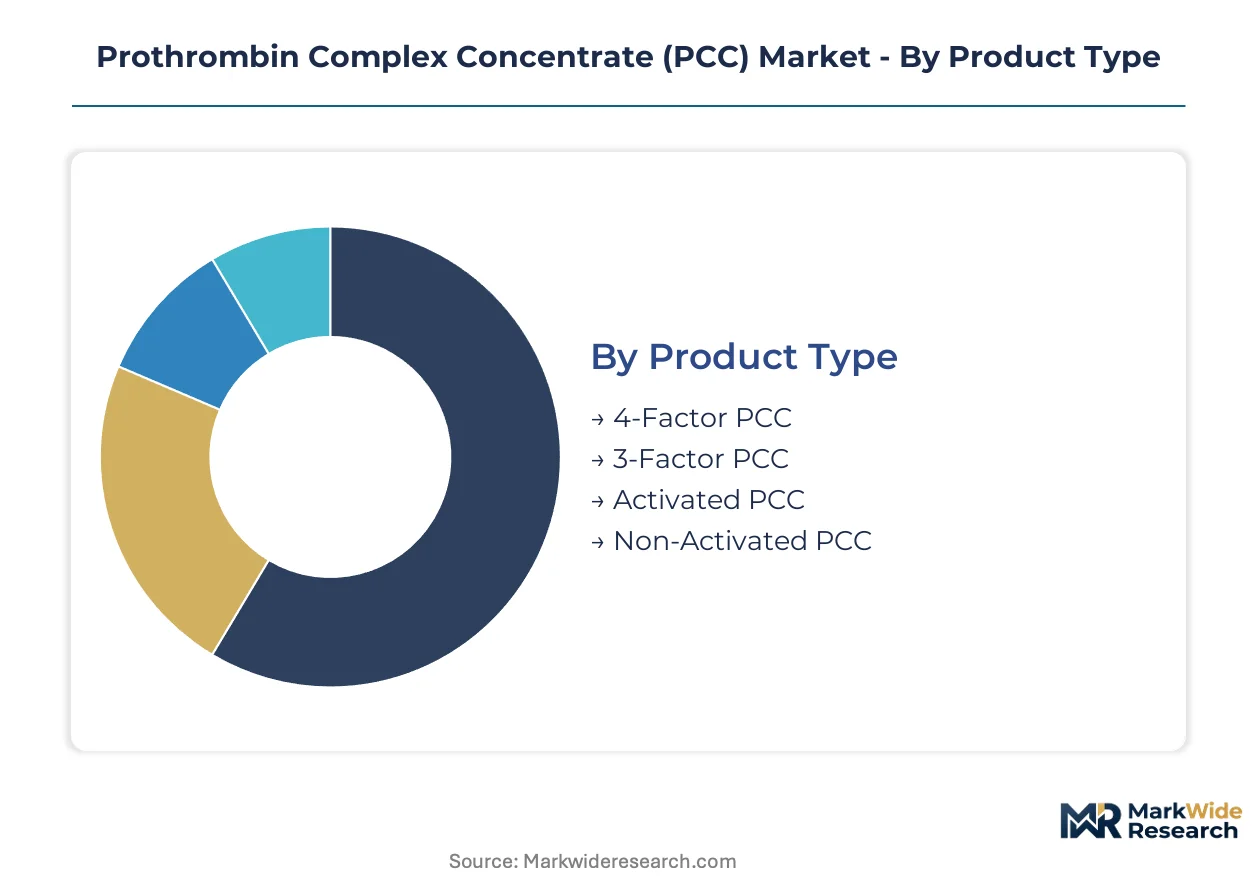
The Prothrombin Complex Concentrate (PCC) market is analyzed across various segments to understand demand drivers and competitive dynamics. Each category reveals distinct patterns in product preference, clinical application, end-user needs, and administration methods. This granular view helps manufacturers align product development and market strategies with evolving healthcare requirements.
Product Type:
Substitution pressure is most pronounced within the product type segment, where newer, more complete formulations are supplanting older standards.
- 4-Factor PCC:This product contains concentrated factors II, VII, IX, and X, providing comprehensive hemostatic correction. Demand is concentrated in emergency care units across the United States for rapid warfarin reversal due to its balanced factor profile.
- 3-Factor PCC:Comprising factors II, IX, and X, this older formulation lacks factor VII, offering less complete reversal of anticoagulant effects. Its use is declining as healthcare providers in Germany and France increasingly adopt 4-Factor alternatives for critical bleeding.
- Activated PCC:This specialized formulation contains activated coagulation factors, bypassing the need for endogenous factor activation. It is typically reserved for patients with inhibitors to factor VIII or IX, particularly in hemophilia treatment.
- Non-Activated PCC:Standard non-activated PCC requires endogenous activation of its coagulation factors to exert its hemostatic effect. This is the most common form of PCC used for general anticoagulant reversal and vitamin K deficiency.
4-Factor PCC anchors the volume base while Activated PCC gains share at the steepest rate.
Indication:
The application of Prothrombin Complex Concentrate varies significantly by clinical urgency and patient profile, influencing procurement decisions across different healthcare settings.
- Warfarin Reversal:This is a primary application for PCC, providing rapid correction of coagulopathy induced by vitamin K antagonists. Emergency departments in countries like the United States and the United Kingdom drive significant consumption for acute bleeding events.
- Trauma-Induced Coagulopathy:PCC is increasingly used in severe trauma cases to manage life-threatening hemorrhage and correct coagulopathy. Major trauma centers in Germany and Australia are adopting PCC as a front-line therapy, driven by advancements in critical care protocols.
- Hemophilia Treatment:PCC can be employed in hemophilia patients, particularly those with inhibitors, as a bypassing agent to achieve hemostasis. This application requires careful patient selection and monitoring due to thrombotic risks.
- Vitamin K Deficiency:Patients with severe vitamin K deficiency, often due to malabsorption or liver disease, can receive PCC for rapid correction of coagulopathy. This is typically used in acute settings where immediate hemostasis is required.
- Liver Disease Coagulopathy:PCC is considered for bleeding episodes or before invasive procedures in patients with severe liver disease and associated coagulopathy. The decision to administer PCC requires careful assessment of the patient's overall coagulation status.
Warfarin Reversal remains the largest application, with Trauma-Induced Coagulopathy expanding most quickly.
End User:
End-user segments reveal distinct volume consumption patterns, with large institutional settings dominating procurement.
- Hospitals:These institutions represent the largest end-user segment for PCC, encompassing emergency rooms, intensive care units, and surgical departments. Hospitals in Japan and Canada are major consumers, driven by a high volume of complex medical cases.
- Emergency Care Units:Often integrated within hospitals but also standalone, these units demand rapid access to PCC for urgent anticoagulant reversal and acute bleeding management. Their focus on time-sensitive interventions drives consistent product demand.
- Specialty Clinics:Hematology and coagulation disorder clinics utilize PCC for managing specific patient populations, including hemophilia patients with inhibitors. These clinics often have specialized expertise in complex bleeding disorders.
- Blood Banks:While not direct end-users for patient administration, blood banks play a critical role in the supply chain, processing plasma and ensuring product availability for hospitals. They are essential for maintaining the raw material supply for PCC manufacturing.
Hospitals represent the primary procurement channel, while Emergency Care Units exhibit significant expansion in urgent care settings.
Administration Route:
Supply concentration for administration routes primarily reflects the established clinical practice for rapid systemic delivery of coagulation factors.
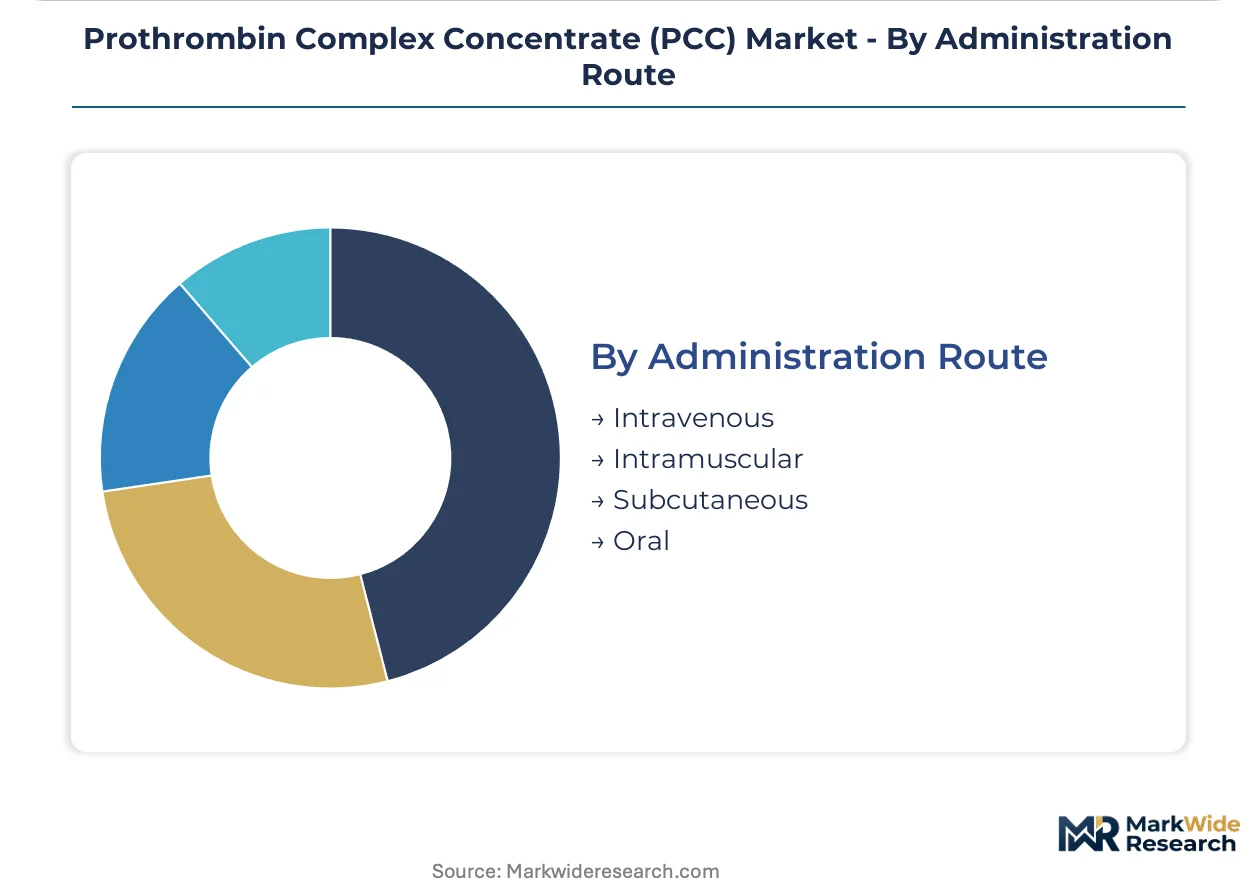
- Intravenous:This is the standard and most effective route for PCC administration, ensuring rapid systemic delivery of coagulation factors directly into the bloodstream. It is universally adopted in critical care settings for immediate hemostatic effect.
- Intramuscular:Intramuscular administration is generally not recommended for PCC due to potential for local hematoma formation and slower, less predictable absorption. Clinical guidelines rarely support this route for PCC.
- Subcutaneous:Similar to intramuscular, subcutaneous administration is not a standard route for PCC due to its protein nature and the need for rapid systemic action. It carries risks of local reactions and insufficient absorption.
- Oral:Oral administration is entirely unsuitable for Prothrombin Complex Concentrate, as the protein components would be digested in the gastrointestinal tract. PCC requires direct entry into the bloodstream for therapeutic effect.
Intravenous administration holds the dominant position, though research into alternative routes continues for specific patient populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for Prothrombin Complex Concentrate varies significantly across geographies, reflecting diverse healthcare priorities and regulatory landscapes. Developed nations prioritize rapid anticoagulant reversal and trauma care, while emerging markets focus on building foundational critical care capabilities. This differential drives distinct demand patterns globally for PCC products.
United States
The United States exhibits substantial demand for PCC, driven by its high volume of anticoagulant use and sophisticated trauma care infrastructure. The FDA's framework for blood product development encourages innovation in safer PCC formulations and ensures product quality. Major trauma centers in key cities like Chicago and New York actively integrate PCC into modern critical care protocols.
Germany
Germany shows strong demand for 4-Factor PCC, driven by its advanced critical care protocols and increasing adoption for acute bleeding. The EMA's stringent oversight of plasma-derived medicinal products mandates greater transparency in plasma sourcing. Major trauma centers in cities like Munich and Berlin are adopting PCC as a front-line therapy.
Japan
Japanese hospitals represent a significant end-user segment for PCC, driven by a high volume of complex medical cases requiring rapid hemostasis. The PMDA's stringent standards for viral inactivation and batch consistency require substantial ongoing investment from manufacturers. Hospitals in the Tokyo metropolitan area and Kansai region are major consumers, ensuring product availability for critical care.
China
China's market for PCC is expanding as its trauma care systems develop and anticoagulant use grows among its large population. The NMPA enforces strict guidelines on plasma sourcing, viral inactivation processes, and batch-to-batch consistency for product safety. Rapidly expanding healthcare infrastructure in major cities like Shanghai and Beijing is boosting PCC utilization.
Brazil
Brazil presents significant growth potential for PCC manufacturers due to its developing trauma care systems and increasing access to advanced medical treatments. ANVISA, the national health surveillance agency, regulates blood products to ensure safety and efficacy within the country. Major hospitals in São Paulo and Rio de Janeiro are integrating PCC into emergency medicine for rapid hemostasis.
Prothrombin Complex Concentrate (PCC) Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive landscape for Prothrombin Complex Concentrate. This market structure favors large-scale, vertically integrated manufacturers who control the supply chain from plasma donor to final product. Strategic archetypes include plasma fractionators, critical care specialists, and niche hemophilia treatment providers. Key competitive moves involve capacity expansion and deepening vertical integration.
Within the integrated plasma fractionator archetype, CSL Behring and Grifols S.A. exemplify companies leveraging extensive global plasma collection networks to ensure consistent raw material supply. CSL Behring, an Australian-headquartered biopharmaceutical firm, benefits from its broad portfolio of plasma-derived therapies and strong market access. Spanish multinational Grifols S.A. sustains its market position through deep specialization across various plasma-derived products, including a strong presence in diagnostics. Octapharma AG, a Swiss-based human protein manufacturer, occupies a position focused on hematology and critical care indications for hospital settings, emphasizing product purity and safety.
| Leading Market Players |
|---|
| CSL Behring |
| Grifols S.A. |
| Octapharma AG |
| Takeda Pharmaceutical Company Limited |
| Kedrion Biopharma |
| Sanquin |
| China Biologic Products Holdings, Inc. |
| Nihon Pharmaceutical Co. Ltd. |
| Biotest AG |
| Others |
Cost & Logistics Intelligence
The 12-month lead time for establishing new plasma collection centers directly influences the supply chain's rigidity and market pricing power, particularly for vertically integrated manufacturers.
Pricing Analysis
Long-term contract-based purchasing dominates the Prothrombin Complex Concentrate market, reflecting the need for stable supply in critical care. Price differentiation stems from advanced purification techniques, ensuring product safety, and the manufacturer's demonstrated regulatory compliance with bodies like the EMA. Pricing softness emerges from hospital procurement departments balancing budget constraints with clinical efficacy. Emergency care units exhibit high price sensitivity for standard 4-Factor PCC, while hemophilia treatment centers prioritize specialized Activated PCC formulations.
Supply Chain Analysis
Maintaining precise inventory levels for Prothrombin Complex Concentrate is critical due to its short shelf life and the complex cold chain logistics. Supply concentration centers in the United States for plasma collection and European countries like Switzerland and Austria for advanced fractionation. The supply chain relies heavily on human plasma, creating vulnerability to collection disruptions. Distribution primarily runs through specialized pharmaceutical logistics networks directly to hospitals and emergency care units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Prothrombin Complex Concentrate market is undergoing a high-growth disruption, driven by advancements in point-of-care viscoelastic testing. This technological inflection enables more precise, individualized therapy, expanding PCC's application in critical care.
For Market Incumbents: Fortify plasma collection networks through strategic investments in donor centers to mitigate supply volatility. Invest in next-generation purification techniques and advanced diagnostics to maintain product superiority against emerging recombinant factor innovation. Deepen vertical integration into plasma fractionation to enhance control over raw material quality and cost. Prioritize R&D in formulations that offer enhanced safety profiles and targeted hemostatic correction.
For New Entrants and Emerging Players: Anchor in developing trauma care systems within emerging markets like Brazil and India. Target perioperative bleeding applications in cardiac surgery, where formalizing PCC use through clinical trials presents a substantial new segment. A penetrable segment exists in providing cost-effective 4-Factor PCC to hospitals in regions with nascent critical care infrastructure. Go-to-market strategies should emphasize clinical education and local partnership to build trust and market share.
For Investors and Strategic Acquirers: Carve-out targets emerge from larger pharmaceutical conglomerates seeking to divest non-core plasma-derived assets. The market demonstrates long-term viability as an essential critical care therapy with expanding indications over the next decade. Acquisition targets include specialized plasma fractionators with robust regulatory compliance and established market access in key regions. A signal to watch is increased M&A activity focused on securing stable, high-quality plasma collection networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Validates new PCC applications in perioperative bleeding. |
| Regulatory Approval Pathway | Secures market access for advanced PCC formulations in China. |
| Manufacturing Scale-Up | Ensures consistent supply of plasma-derived products for global demand. |
| Pipeline Diversification | Reduces reliance on human plasma through recombinant factor development. |
| Hospital System Partnership | Expands PCC adoption through integrated critical care protocols. |
Research Approach
Operator-level perspectives from hematologists, critical care physicians, and hospital procurement managers anchored the qualitative base for this analysis. Primary interviews were combined with secondary validation from sources including FDA filings, EMA submissions, and clinical trial registries. This approach ensured a robust understanding of market dynamics through bottom-up and top-down triangulation. Regulatory affairs specialists also provided critical insights into market access challenges.
Sensitivity analysis was applied to key variables to model market evolution over the projection horizon. The framework segmented the market by product type, indication, end-user, administration route, and regional regulatory compliance. Compound annual growth rates were derived from historical trends, projected demand drivers, and expert consensus. Key forecast inputs included anticoagulant prescription rates in aging populations and global trauma incidence rates.
Material uncertainties — including unforeseen changes in global plasma supply or rapid adoption of non-plasma alternatives — sit outside the modeled envelope. Forecasts reflect assumptions documented at the time of study. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
US Pharmacy Market
Pharmaceuticals
Pharmaceuticals Lipids Market
Pharmaceuticals
Gardasil (HPV Vaccine) Market
Pharmaceuticals
Flavors Into Over-The-Counter (OTC) Pharmaceuticals Market
Pharmaceuticals
Anti-Platelet Agents Market
Pharmaceuticals
Posaconazole Market
Pharmaceuticals
Pembrolizumab Market
Pharmaceuticals
Anti Obesity Prescription Drugs Market
Pharmaceuticals
Mexico Dimenhydrinate Market
Pharmaceuticals
Global DPT Vaccine Market
Pharmaceuticals
Propofol Market
Pharmaceuticals
Aminophylline Market
Pharmaceuticals
Global Interstitial Cystitis Drugs Market
Pharmaceuticals
Antiandrogens Market
Pharmaceuticals
Anti-Inflammatory Biologics Market
Pharmaceuticals
Global Lipid Disorder Treatment Market