
 Saudi Arabia Insulin Drugs and Delivery Devices Market | 2026-2036
Saudi Arabia Insulin Drugs and Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Insulin Drugs and Delivery Devices Market Insights
A shortage of certified diabetes educators is redrawing how manufacturers deploy training resources across the Kingdom. Novo Nordisk A/S leverages its educator networks to sustain pen-needle adherence in outpatient settings. Sanofi anchors insulin glargine volume through hospital formulary contracts in the Eastern Province. Eli Lilly and Company competes via differentiated rapid-acting analog positioning in private endocrinology clinics.
Insulin drugs and delivery devices comprise biologically active peptide formulations and mechanical or electronic systems engineered to achieve subcutaneous or intravenous glycemic control with specified pharmacokinetic profiles. These products serve to replicate endogenous insulin secretion patterns in patients with impaired pancreatic beta-cell function. Insulin pumps command premium positioning due to algorithm-enabled closed-loop integration, while disposable syringes occupy the cost-sensitive volume tier in government reimbursement channels. Home care represents the fastest-growing end-user channel as SFDA-cleared connected pens enable remote dose logging and physician oversight.
SFDA device registration rules and MOHAP reimbursement protocols jointly determine which delivery technologies reach Saudi patients through public procurement. The country's national pharmaceutical regulator enforces stability-testing requirements that filter out non-compliant biosimilar entrants. Stakeholders must monitor how the PLI scheme's local manufacturing incentives reshape supplier qualification criteria for insulin fill-finish operations.
Market Dynamics
SFDA registration requirements for connected insulin delivery devices are tightening quality benchmarks and accelerating hospital procurement cycles across the Kingdom's tertiary care networks.
Growth Catalysts
- MOHAP Reimbursement Protocols:Expanded coverage for insulin pumps in government channels pulls patients toward algorithm-enabled closed-loop systems.
- Home Care Migration:SFDA-cleared connected pens enable remote dose logging, shifting patient volume from outpatient clinics to monitored residential settings.
- Eastern Province Hospital Formulary Expansion:Volume commitments from integrated delivery networks anchor insulin analog procurement at scale.
Market Restraints
- Certified Diabetes Educator Scarcity:Limited training capacity constrains patient onboarding for advanced delivery devices outside Riyadh and Jeddah.
- Biosimilar Stability-Testing Failures:SFDA fill-finish requirements filter non-compliant entrants, concentrating supply among established manufacturers.
- Disposable Syringe Price Compression:Government tender mechanisms cap margins on volume-tier products, squeezing distributor economics.
Strategic Opportunities
- PLI Scheme Local Manufacturing:Production-linked incentives reshape supplier qualification criteria for insulin fill-finish operations within Saudi borders.
- Private Endocrinology Clinic Networks:Rapid-acting analog positioning targets unmet need in Jeddah's specialist outpatient sector.
- Remote Physician Oversight Integration:Connected pen data streams merge with hospital electronic records, creating adherence-monitoring revenue pools.
Industry Challenges
- Algorithm Validation Timelines:Closed-loop insulin pump software requires extended SFDA clinical evidence review, delaying market entry.
- Legacy Device Inventory Stranded:Non-connected pen-needle systems face obsolescence as hospitals prioritize dose-logging capabilities in procurement specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Insulin Drugs and Delivery Devices Market |
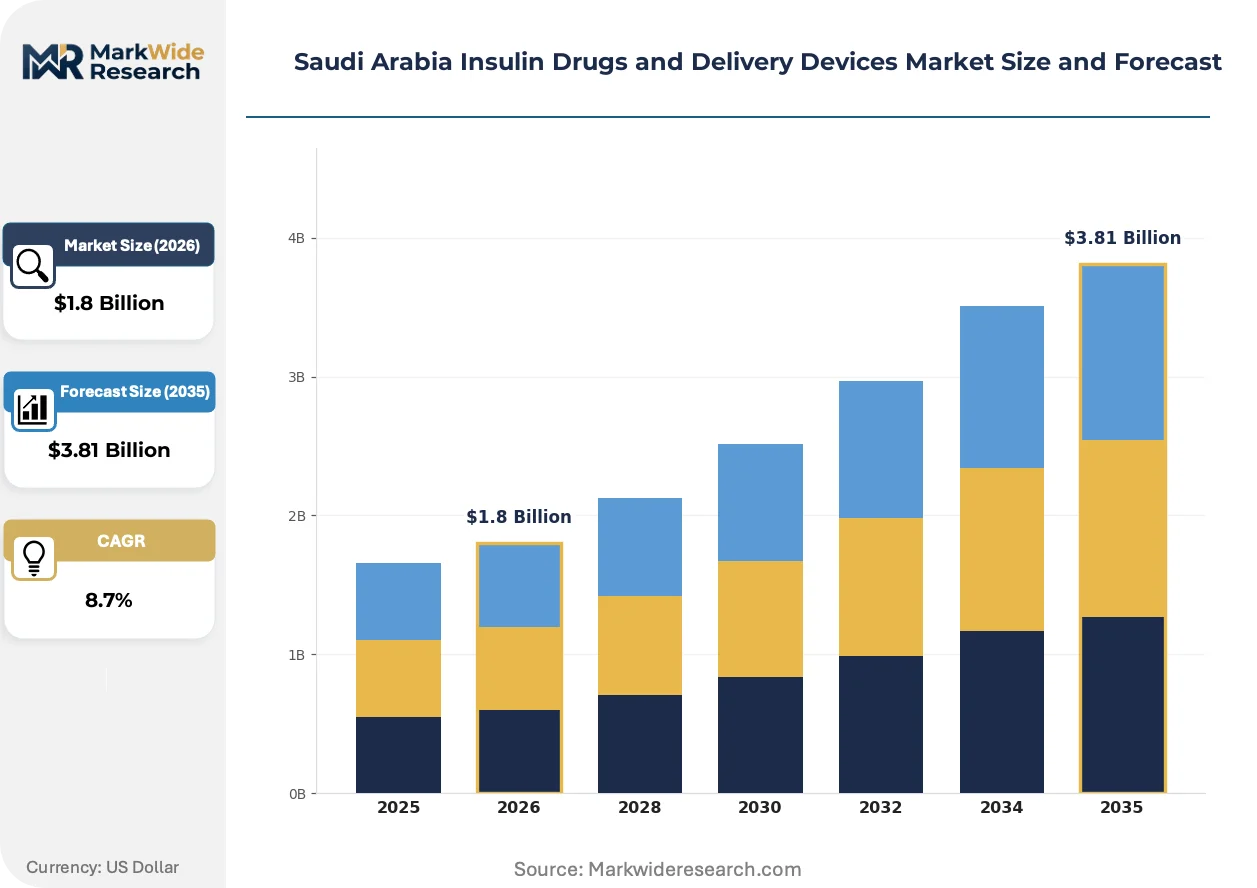
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pens, Insulin Pumps, Disposable Syringes, Vials Delivery Mode: Injectable, Continuous Infusion, Pre-filled, Jet Injector End User: Hospitals, Clinics, Home Care, Pharmacies Therapy Area: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Pre-diabetes |
| Companies Covered | Medtronic plc, Becton Dickinson, Novo Nordisk A/S, Boehringer Ingelheim Pharma, F. Hoffmann-La Roche AG, Sanofi, Abbott Laboratories, DexCom, Inc., Eli Lilly and Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Insulin Drugs and Delivery Devices Market Trends and Innovations
Device miniaturization and regulatory digitization are compressing development cycles while reshaping how manufacturers deploy training and service resources across the Kingdom's care continuum.
Continuous glucose monitoring sensors paired with patch pumps is miniaturizing the wearable footprint for Type 1 patients in Riyadh's pediatric endocrinology units. Adolescent user adoption is outpacing adult cohorts by a significant margin. This convergence is compressing the distinction between consumer wellness devices and prescription-grade therapeutic systems, forcing manufacturers to recertify under stricter SFDA stability protocols.
SFDA's tightened registration requirements for connected devices now mandate real-world evidence submissions alongside traditional bench testing. Manufacturers must demonstrate interoperability with Ministry of Health electronic health record architectures. Private hospital networks in Jeddah are responding by consolidating procurement around vendors with pre-validated data integration pathways.
Patient self-management behaviors are fragmenting traditional pharmacy-channel dependence as direct-to-clinic subscription models for insulin consumables gain traction. Specialist endocrinology practices are unbundling device provision from drug dispensing, creating parallel supply paths. This disintermediation is most visible in the Eastern Province, where integrated delivery networks negotiate combined device-drug contracts bypassing retail pharmacy intermediaries.
Saudi Arabia Insulin Drugs and Delivery Devices Market Segmentation
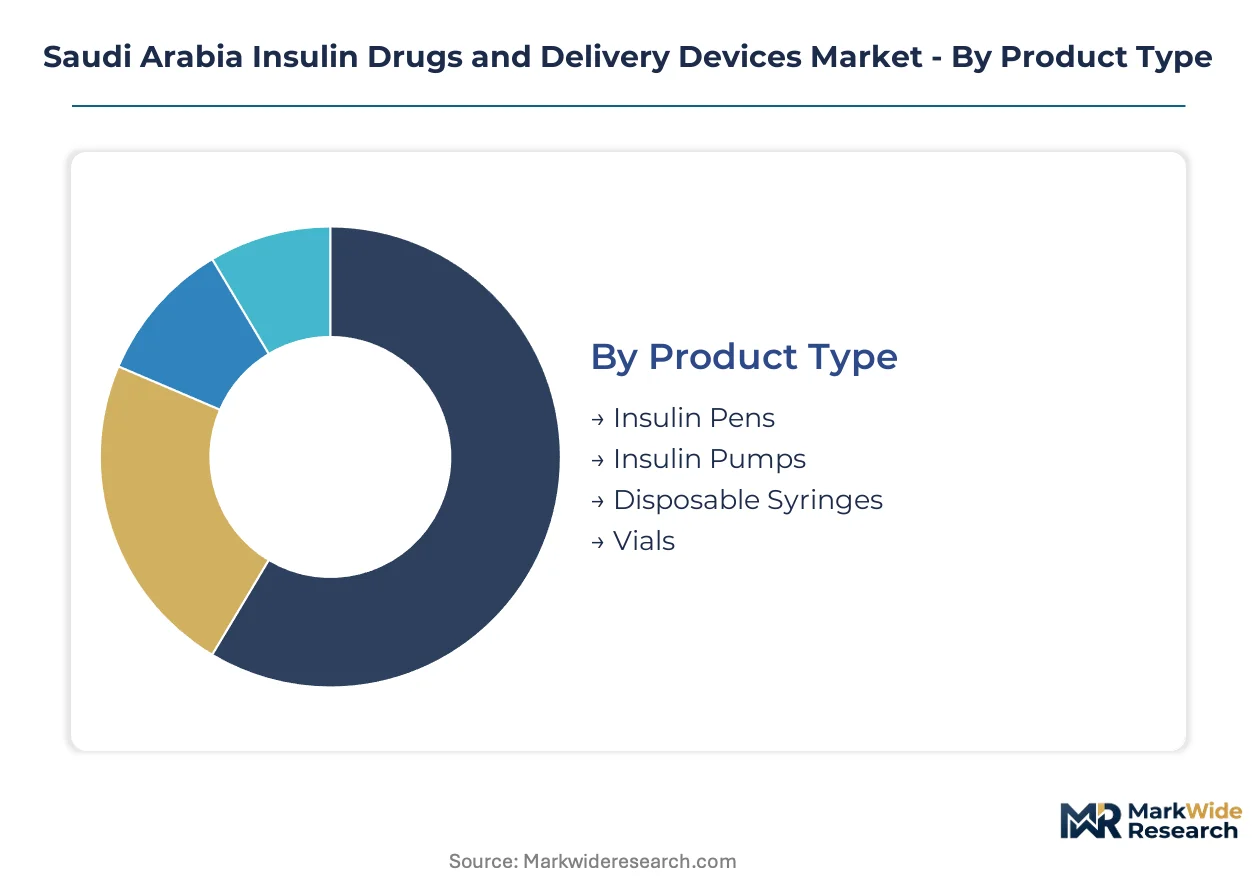
Segmentation in the Saudi insulin market exposes where procurement power concentrates and which channels absorb technology premiums. Manufacturers calibrate their SFDA registration investments and educator deployment against these fracture lines.
Product Type:
Margin pools concentrate in algorithm-enabled systems that command reimbursement premiums through MOHAP protocols, while volume tiers compete on tender economics.
- Insulin Pens:Reusable and disposable pen systems deliver precise dose increments through spring-loaded mechanisms. Demand clusters in Riyadh's tertiary care centers where outpatient volume justifies educator-staffed training programs. Connected variants with Bluetooth logging are displacing legacy models in private hospital procurement specifications.
- Insulin Pumps:Battery-powered infusion devices with programmable basal-bolus profiles represent the technology frontier. Jeddah's private endocrinology clinics drive adoption as closed-loop integration with continuous glucose monitors commands premium positioning. SFDA registration timelines for algorithm validation create supply bottlenecks.
- Disposable Syringes:Single-use plastic barrel systems with integrated needles serve cost-sensitive government channels. Eastern Province hospital networks anchor volume through centralized tender mechanisms.
- Vials:Multi-dose glass or polymer containers for manual syringe withdrawal retain share in pharmacy-dispensed analog prescriptions.
Insulin pumps hold installed capacity. Insulin pens are rotating up the share rankings.
Delivery Mode:
Application requirements diverge sharply between acute inpatient settings and self-managed residential care, fragmenting supplier qualification pathways.
- Injectable:Subcutaneous delivery via pen, syringe, or vial-needle combinations dominates outpatient prescribing. Home care migration in Dammam and Khobar is pulling volume toward patient-administered formats with remote monitoring capabilities.
- Continuous Infusion:Pump-mediated basal delivery with patient-triggered bolus capability serves intensive insulin regimens. Pediatric endocrinology units in Riyadh's specialist hospitals concentrate demand as adolescent Type 1 cohorts expand.
- Pre-filled:Factory-sealed disposable pens eliminate dose preparation steps. Private clinic networks favor these for patient onboarding efficiency where educator time is scarce.
- Jet Injector:Needle-free pressure-driven systems penetrate skin through high-velocity liquid streams. Niche positioning addresses needle-phobic patients in premium Jeddah practices.
Injectable formats hold installed capacity. Continuous infusion is rotating up the share rankings.
End User:
Customer type determines pricing architecture, with institutional procurement favoring bundled contracts and retail channels fragmenting toward subscription models.
- Hospitals:Integrated delivery networks in the Eastern Province negotiate combined device-drug formulary contracts. SFDA stability requirements for connected systems filter supplier pools.
- Clinics:Specialist endocrinology practices in Jeddah unbundle device provision from drug dispensing. Direct-to-clinic subscription models for consumables are gaining traction.
- Home Care:Remote dose logging through SFDA-cleared connected pens enables physician oversight without clinic visits. This channel is expanding most quickly as reimbursement protocols adapt.
- Pharmacies:Retail intermediaries face disintermediation pressure as integrated networks consolidate procurement. Government tender mechanisms cap margins on volume-tier syringes.
Hospitals hold installed capacity. Home care is rotating up the share rankings.
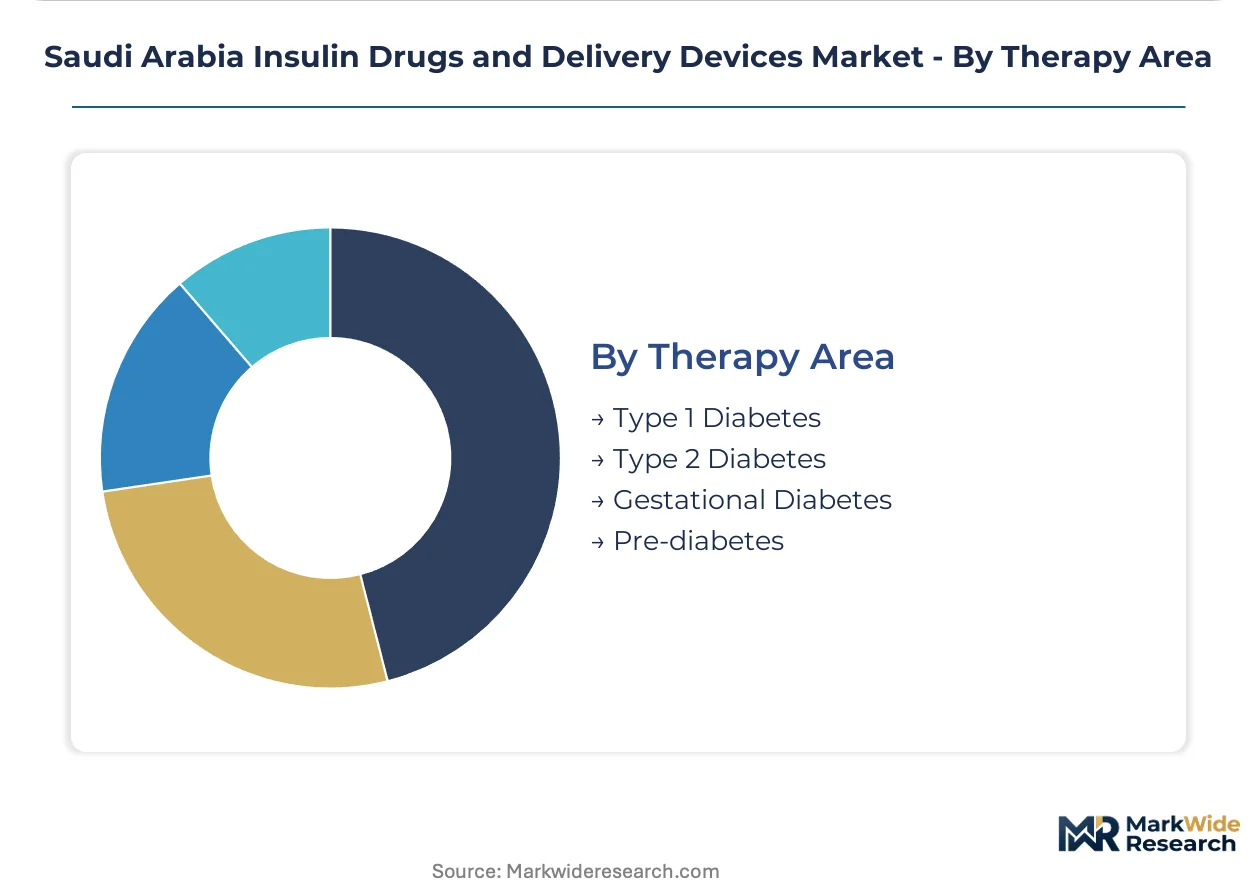
Therapy Area:
Maturity gradients separate established treatment paradigms from emerging prevention protocols, reshaping clinical trial investment and educator deployment.
- Type 1 Diabetes:Absolute insulin deficiency requiring exogenous replacement anchors premium pump and analog demand. Pediatric units in Riyadh concentrate technology adoption.
- Type 2 Diabetes:Progressive beta-cell failure drives the volume base for pen-needle systems and basal analogs. Eastern Province hospital networks manage large outpatient cohorts.
- Gestational Diabetes:Temporary insulin requirements during pregnancy favor short-acting analogs with tight glycemic targets. Maternity units in Jeddah's private hospitals concentrate demand.
- Pre-diabetes:Lifestyle intervention with occasional pharmacologic escalation represents a nascent prevention frontier. Screening expansion through primary care is slowly building addressable incidence.
Type 2 Diabetes holds installed capacity. Home care applications for Type 1 are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA registration protocols and MOHAP reimbursement frameworks anchor procurement decisions across Saudi Arabia's care networks. Regional demand clusters around tertiary hubs where integrated delivery systems concentrate volume.
Riyadh
Pediatric endocrinology units drive premium pump adoption among adolescent Type 1 cohorts. SFDA-cleared connected pens enable remote dose logging for outpatient monitoring. King Faisal Specialist Hospital anchors technology diffusion through educator-staffed training programs.
Eastern Province
Hospital formulary contracts concentrate insulin analog procurement at scale across Dammam and Khobar. Government tender mechanisms cap margins on disposable syringes while pulling volume toward bundled device-drug agreements. Aramco-operated health networks anchor private sector demand.
Jeddah
Private endocrinology clinics unbundle device provision from drug dispensing through direct-to-clinic subscription models. Specialist practices favor pre-filled disposable pens for patient onboarding efficiency. Red Sea coastal corridors concentrate premium rapid-acting analog positioning.
Western Region
Makkah and Madinah pilgrimage health infrastructure manages transient diabetic populations through portable pen-needle systems. MOHAP mobile clinic protocols standardize SFDA-cleared devices for temporary glycemic control. Seasonal patient volumes strain educator deployment capacity.
NEOM Northwest
Emerging smart city infrastructure trials closed-loop integration between continuous glucose monitors and algorithm-enabled pumps. PLI scheme incentives attract fill-finish manufacturing investment for regional supply security. Regulatory sandbox provisions accelerate SFDA validation timelines for connected devices.
Saudi Arabia Insulin Drugs and Delivery Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational pharmaceutical conglomerates commanding hospital formulary access while regional distributors handle last-mile logistics. The structure rewards scale in SFDA registration navigation and educator network deployment. Two archetypes dominate: algorithm-integrated pump specialists and basal analog volume players. Competitive moves center on MOHAP contract consolidation and backward integration into local fill-finish capacity.
Among the integrated leaders, Novo Nordisk A/S and Sanofi occupy positions exemplifying educator-network and formulary-contract archetypes respectively. Eli Lilly and Company represents rapid-acting analog differentiation in private clinic channels. These three anchors demonstrate how multinational scale combines with Saudi-specific regulatory navigation to secure procurement access across the Kingdom's tiered care system.
| Leading Market Players |
|---|
| Medtronic plc |
| Becton Dickinson |
| Novo Nordisk A/S |
| Boehringer Ingelheim Pharma |
| F. Hoffmann-La Roche AG |
| Sanofi |
| Abbott Laboratories |
| DexCom, Inc. |
| Eli Lilly and Company |
| Others |
Pricing and Supply Chain Analysis
Connected pen-needle systems replacing legacy disposable models are simultaneously relocating manufacturing investment toward Saudi fill-finish capacity under PLI incentives and compressing margins on non-Bluetooth devices in government tender channels. This substitution dynamic concentrates pricing power with algorithm-integrated pump manufacturers while fragmenting procurement across subscription-based clinic models and bundled hospital contracts.
Pricing Analysis
Long-term formulary contracts with integrated delivery networks anchor insulin analog procurement, while spot purchasing for consumables persists in retail pharmacy channels. Three-tier pricing structure across premium closed-loop systems, standard connected pens, and economy disposable syringes reflects MOHAP reimbursement tiers and SFDA certification levels. Cost compression in the syringe tier is intensifying because government tender mechanisms cap distributor margins. Government procurement committees exhibit highest price sensitivity, whereas private endocrinology clinics in Jeddah prioritize patient onboarding efficiency over per-unit cost.
Supply Chain Analysis
Red Sea transit corridors and Jeddah Islamic Port throughput capacity constitute critical chokepoints for imported active pharmaceutical ingredients and finished device assemblies. Manufacturing concentration in Denmark, France, and the United States feeds Saudi demand, with fill-finish operations increasingly shifting to local PLI-qualified facilities. Supply chains draw from recombinant insulin bulk, precision pen-needle polymers, and lithium-ion pump batteries. Single-source vulnerability in algorithm-integrated pump controllers creates procurement risk for hospital networks. Distribution runs through regional distributor networks with direct-to-clinic subscription models gaining share in private channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's insulin market represents an early-cycle expansion story as SFDA-cleared connected devices enable remote patient monitoring and shift volume from outpatient clinics to reimbursed home care settings.
For Market Incumbents: Consolidate formulary position through educator network density in Riyadh and Jeddah tertiary centers to defend against biosimilar entrants and algorithm-enabled pump specialists. Deepen backward integration into local fill-finish capacity under PLI scheme incentives to secure supplier qualification for government procurement. Channel control through direct-to-clinic subscription models for consumables protects margin pools as retail pharmacy intermediaries face disintermediation. For New Entrants and Emerging Players: Differentiate on closed-loop algorithm validation timelines and pre-certified data integration with Ministry of Health electronic health record architectures. Target the Western Region pilgrimage health infrastructure where seasonal diabetic patient volumes strain existing educator deployment and portable pen-needle systems face procurement standardization pressure. A go-to-market angle through NEOM regulatory sandbox provisions accelerates SFDA validation for connected devices before national rollout. For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional distributors holding exclusive SFDA registration rights for multinational manufacturers but lacking connected device service capabilities. Long-term viability over a five-to-ten year horizon hinges on local manufacturing qualification and educator network scalability rather than pure import licensing. Acquisition targets include mid-cap distributors with established hospital formulary access and underinvested service infrastructure. The signal to watch is MOHAP reimbursement protocol expansion for home care remote monitoring, which would re-rate connected pen and pump adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Pathway Acceleration | Pre-validation with Ministry of Health EHR architectures shortens hospital procurement cycles for connected devices. |
| Local Fill-Finish Manufacturing Scale-Up | PLI scheme qualification reshapes supplier criteria and secures government contract eligibility for insulin operations. |
| Diabetes Educator Network Expansion | Training capacity deployment outside Riyadh and Jeddah unlocks patient onboarding for algorithm-enabled delivery systems. |
| Direct-to-Clinic Subscription Model | Unbundling device provision from drug dispensing bypasses retail pharmacy intermediaries in private endocrinology channels. |
| Closed-Loop Algorithm Clinical Validation | Real-world evidence submissions satisfy tightened SFDA registration requirements for connected insulin pumps. |
Research Methodology
A spread of perspectives from hospital procurement managers, formulary directors, regulatory affairs specialists, and diabetes educator network leads converged on the working assumptions underpinning this analysis. Primary fieldwork with SFDA registration consultants and Ministry of Health reimbursement officers combined with secondary validation from SFDA device filings, MOHAP procurement bulletins, hospital tender databases, and PLI scheme qualification records. Bottom-up volume estimates by product type and delivery mode triangulated against top-down market sizing through the analysis window.
Segmentation dimensions modeled include insulin delivery technology tier, administration route, end-user channel type, and patient therapy area across the projection horizon. CAGRs were derived from fitted growth curves applied to disclosed procurement volumes and reimbursement expansion trajectories. Forecast inputs incorporated SFDA registration pipeline timelines, educator deployment scaling assumptions, and connected device interoperability certification status.
The analysis sits within stated boundaries; outcomes outside sustained MOHAP reimbursement expansion for home care monitoring and PLI scheme continuity would require recalibration. Forecasts reflect documented assumptions regarding algorithm validation timelines and biosimilar stability-testing clearance rates. Practitioners should keep alternative scenarios live as SFDA registration protocol amendments and educator workforce development trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Parathyroid Hormone Market
Pharmaceuticals
Antimetabolite Drugs Market
Pharmaceuticals
Canine Dilated Cardiomyopathy Drugs Market
Pharmaceuticals
Global Pharmaceutical Drug Delivery Market
Pharmaceuticals
Hepatitis B Treatment Market
Pharmaceuticals
Inhaled Nitric Oxide Market
Pharmaceuticals
Triamcinolone Ointment Chlorofluorocarbons Market
Pharmaceuticals
HPV Vaccines Market
Pharmaceuticals
Global BHK Rabies Vaccine Market
Pharmaceuticals
Cough Cold and Allergy Hay Fever Remedies in Mexico Market
Pharmaceuticals
Global Equine Pharmaceuticals and Supplements Market
Pharmaceuticals
Myocardial Infarction Drugs Market
Pharmaceuticals
Dermatological Drugs Market
Pharmaceuticals
Australia Schizophrenia Drugs Market
Pharmaceuticals
Hydroxypropyl Methylcellulose (HPMC) Capsules Market
Pharmaceuticals
Antiviral Drugs Market