
 United States Insulin Drugs and Delivery Devices Market | 2026-2036
United States Insulin Drugs and Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United States Insulin Drugs and Delivery Devices Market Analytics
The Medicare Diabetes Prevention Program expansion is restructuring reimbursement pathways for insulin-dependent beneficiaries. Novo Nordisk anchors the long-acting insulin segment through manufacturing scale and GLP-1 portfolio breadth. Eli Lilly and Company leverages biosimilar insulin development to compete on price in Medicaid channels. Sanofi sustains brand loyalty in the premixed insulin category through pharmacy benefit manager formulary positioning.
United States Insulin Drugs and Delivery Devices comprise recombinant human and analog insulin formulations paired with mechanical or electronic delivery systems engineered for subcutaneous depot absorption with pharmacokinetic profiles ranging from 15-minute onset to 24-hour basal coverage. Their primary purpose is glycemic control in patients with absolute or relative insulin deficiency. Rapid-acting insulin commands premium pricing in pump-compatible configurations while long-acting insulin dominates total prescription volume through once-daily basal regimens. Continuous glucose monitors represent the fastest-growing device category as closed-loop algorithm integration with insulin pumps deepens.
FDA bioequivalence standards for biosimilar insulin and CMS national coverage determinations for continuous glucose monitoring shape product development priorities and market access conditions. State Medicaid programs and commercial payers reference FDA labeling and ADA clinical guidelines in prior authorization protocols. Stakeholders must monitor CMS technology add-on payment decisions for artificial pancreas systems and state-level insulin copay cap legislation that alters patient out-of-pocket exposure.
Market Dynamics
The Medicare Diabetes Prevention Program expansion is restructuring reimbursement pathways for insulin-dependent beneficiaries. Hospital systems and integrated delivery networks are expanding insulin procurement for outpatient chronic disease management while the FDA's evolving biosimilar approval framework accelerates generic insulin entry.
Growth Catalysts
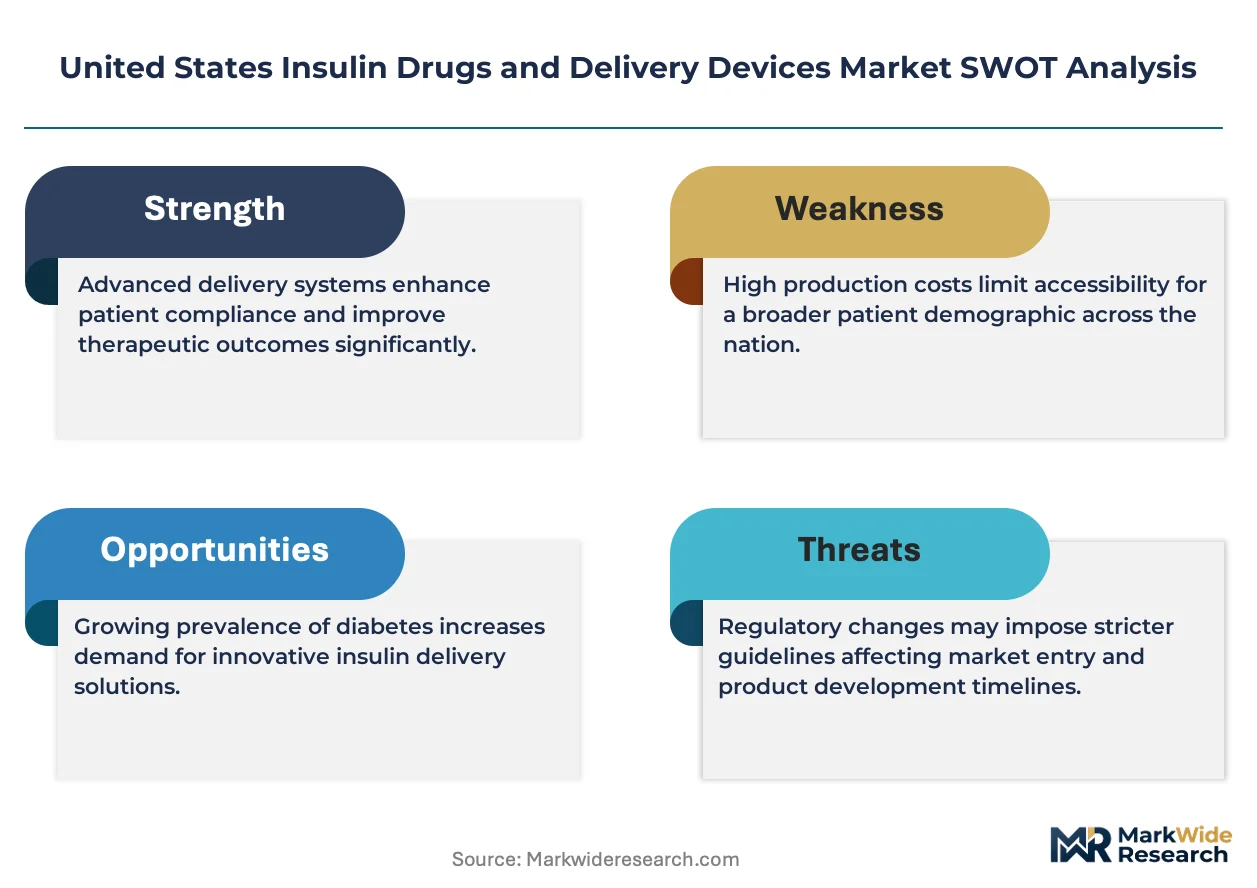
- Biologics Price Competition and Innovation Act:The FDA's streamlined biosimilar approval pathway reduces time-to-market for generic insulin formulations.
- Medicare-eligible populations:Diabetes prevalence in Florida, Texas, and California drives concentrated demand volume across these states.
- Closed-loop algorithm integration:Continuous glucose monitors paired with insulin pumps are deepening automated glycemic control capabilities.
Market Restraints
- Pharmacy benefit manager concentration:Three PBMs control formulary access for over 80% of covered lives, creating gatekeeper friction for new entrants.
- Biologic manufacturing complexity:Recombinant protein production requires specialized facilities with limited contract manufacturing capacity.
- State Medicaid variability:Prior authorization protocols differ across 50 state programs, fragmenting market access.
Strategic Opportunities
- Artificial pancreas systems:CMS technology add-on payment decisions for closed-loop devices create reimbursement tailwinds.
- State-level insulin copay caps:Legislation in multiple states alters patient out-of-pocket exposure and volume elasticity.
- GLP-1 portfolio convergence:Dual-hormone pump systems integrating insulin with glucagon-like peptide-1 agonists represent unclaimed white space.
Industry Challenges
- Endocrinologist workforce scarcity:Specialized diabetes care providers are concentrated in urban academic centers, limiting rural access.
- Legacy pump system interoperability:Proprietary communication protocols between devices create switching costs for patients.
- CGM calibration complexity:Sensor accuracy requirements demand extensive clinical validation timelines for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Insulin Drugs and Delivery Devices Market |
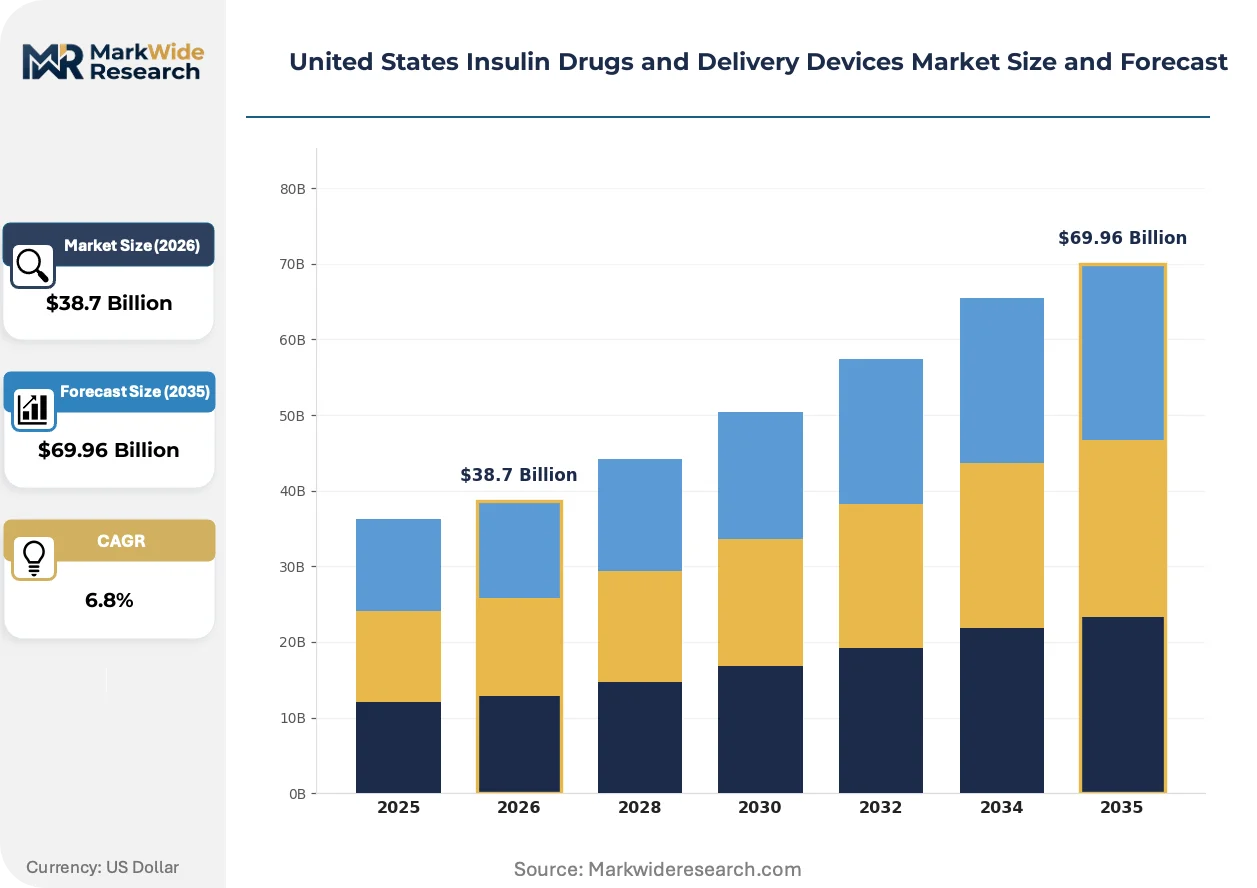
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid-Acting Insulin, Long-Acting Insulin, Premixed Insulin, Inhaled Insulin Device Type: Insulin Pens, Insulin Pumps, Continuous Glucose Monitors, Jet Injectors Administration Route: Subcutaneous, Intravenous, Inhalation, Oral Patient Type: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Insulin-Dependent |
| Companies Covered | Novo Nordisk, Eli Lilly and Company, Sanofi, Medtronic, Insulet Corporation, Tandem Diabetes Care, Ypsomed, Becton Dickinson and Company, Embecta Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Insulin Drugs and Delivery Devices Market Evolving Landscape
Algorithm-driven automation is absorbing clinical decision-making from patients and providers. Three interconnected developments are compressing the gap between glucose sensing and insulin delivery while redistributing economic value across the supply chain.
Closed-loop control systems are absorbing the cognitive burden of basal rate adjustments from Type 1 diabetes patients. Endocrinology practices in the Northeast and Pacific Northwest are piloting these systems at the fastest adoption rates. The technology is absorbing market share from conventional multiple daily injection regimens by reducing hypoglycemic events and HbA1c variability.
CMS national coverage determinations for continuous glucose monitoring are expanding qualifying criteria beyond intensive insulin users. The industrial consequence is a doubling of addressable lives for device manufacturers. Medicare Advantage plans in California and Florida are responding with preferred tier placement for integrated pump-CGM systems.
Patients are consolidating purchasing decisions through integrated delivery networks rather than retail pharmacies. Hospital-owned specialty pharmacies are displacing independent channels for insulin and device fulfillment. This concentration is most visible in Texas and Florida where vertically structured health systems dominate regional markets.
United States Insulin Drugs and Delivery Devices Market Segmentation
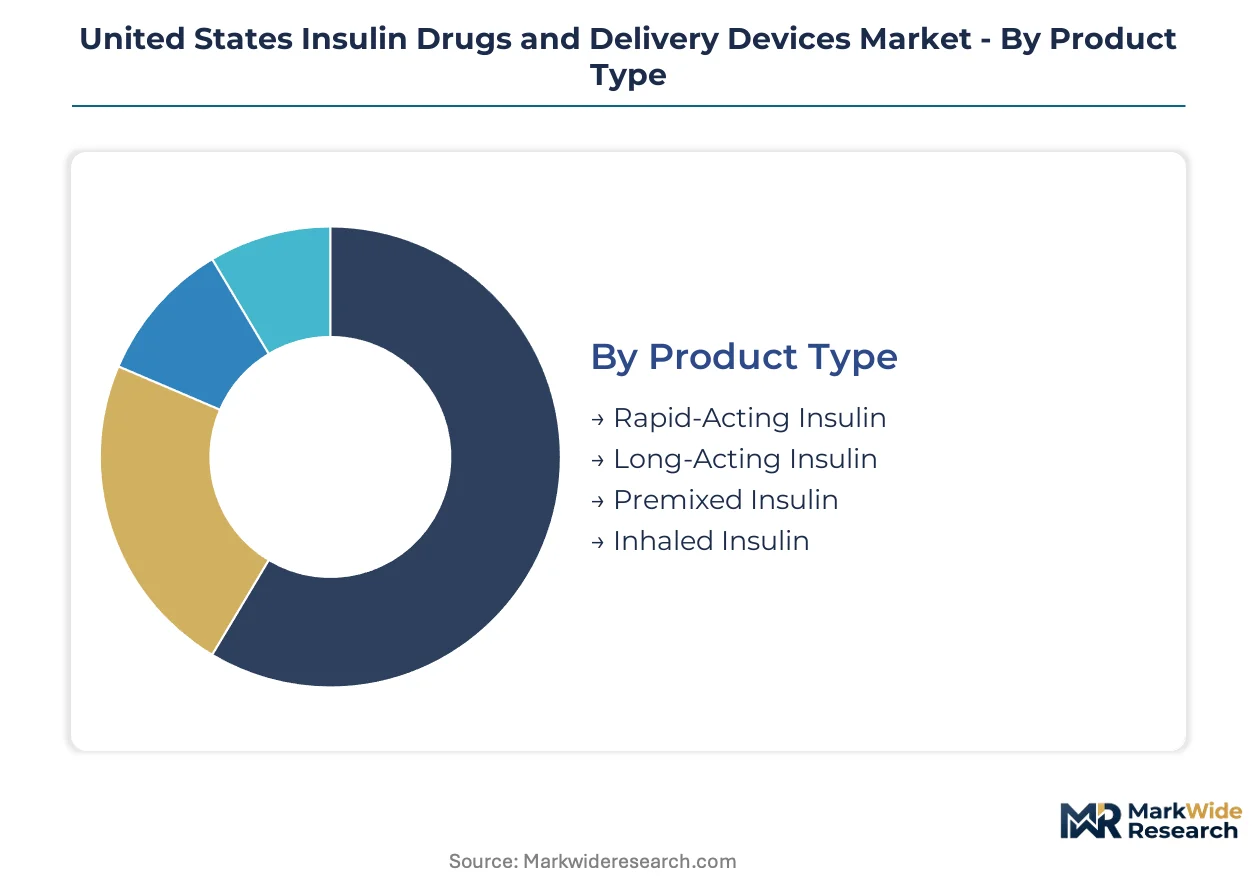
Insulin market segmentation reveals distinct procurement patterns across standalone pharmaceutical products versus integrated delivery ecosystems. Hospital systems and specialty pharmacies calibrate inventory differently for each category based on reimbursement pathways and patient adherence profiles.
Product Type:
Rapid-acting and long-acting formulations anchor standalone prescribing while premixed and inhaled variants embed into broader diabetes management protocols.
- Rapid-Acting Insulin:Analog formulations with 15-minute onset engineered for meal-time glycemic spikes. Demand concentrates in pump-compatible configurations across Medicare Advantage plans in Florida and California where closed-loop system adoption is deepest.
- Long-Acting Insulin:Basal coverage extending 24 hours through glargine or degludec molecular structures. Volume leadership in Texas Medicaid programs reflects once-daily adherence advantages for working-age populations with irregular schedules.
- Premixed Insulin:Fixed-ratio combinations of intermediate and rapid-acting components for simplified regimens. Pharmacy benefit manager formularies in the Southeast favor these for Type 2 initiation protocols.
- Inhaled Insulin:Pulmonary delivery systems bypassing injection barriers for needle-averse patients. Limited to specific FDA-approved devices with restricted pulmonary function requirements.
Volume placements concentrate in Long-Acting Insulin; the faster expansion belongs to Rapid-Acting Insulin.
Device Type:
Cost tier stratification separates premium automated systems from standard mechanical delivery and economy disposable options.
- Insulin Pens:Reusable and disposable injection platforms with dose-dialing precision. Dominant in retail pharmacy fulfillment across suburban and rural markets where pump penetration remains limited.
- Insulin Pumps:Electronic basal-bolus delivery with programmable profiles. Northeast academic medical centers and Pacific Northwest endocrinology practices drive replacement cycles for closed-loop integration.
- Continuous Glucose Monitors:Factory-calibrated sensors with real-time data transmission. CMS national coverage expansion beyond intensive insulin users doubles addressable lives for manufacturers.
- Jet Injectors:Needle-free pressure delivery for specific patient populations. Niche positioning in pediatric and trypanophobia cases with limited formulary placement.
Insulin Pens capture the highest prescription volume; Continuous Glucose Monitors are climbing the fastest on algorithm integration tailwinds.
Administration Route:
Application context determines route selection — outpatient self-management favors subcutaneous while acute settings deploy intravenous for rapid titration.
- Subcutaneous:Depot absorption into adipose tissue via pen, pump, or syringe. Standard for all ambulatory insulin-dependent patients across home and clinic settings.
- Intravenous:Immediate bioavailability for critical care glycemic control. Hospital pharmacy procurement concentrates in surgical and ICU units with end-tidal CO2 monitoring protocols.
- Inhalation:Pulmonary absorption through technosphere particle delivery. Restricted to specific patient profiles with adequate lung function per FDA labeling.
- Oral:Gastrointestinal delivery platforms in developmental stages with bioavailability challenges. No commercial insulin products currently approved in this category.
Subcutaneous delivery dominates prescription volume; inhalation routes show steepest expansion trajectory on patient preference data.
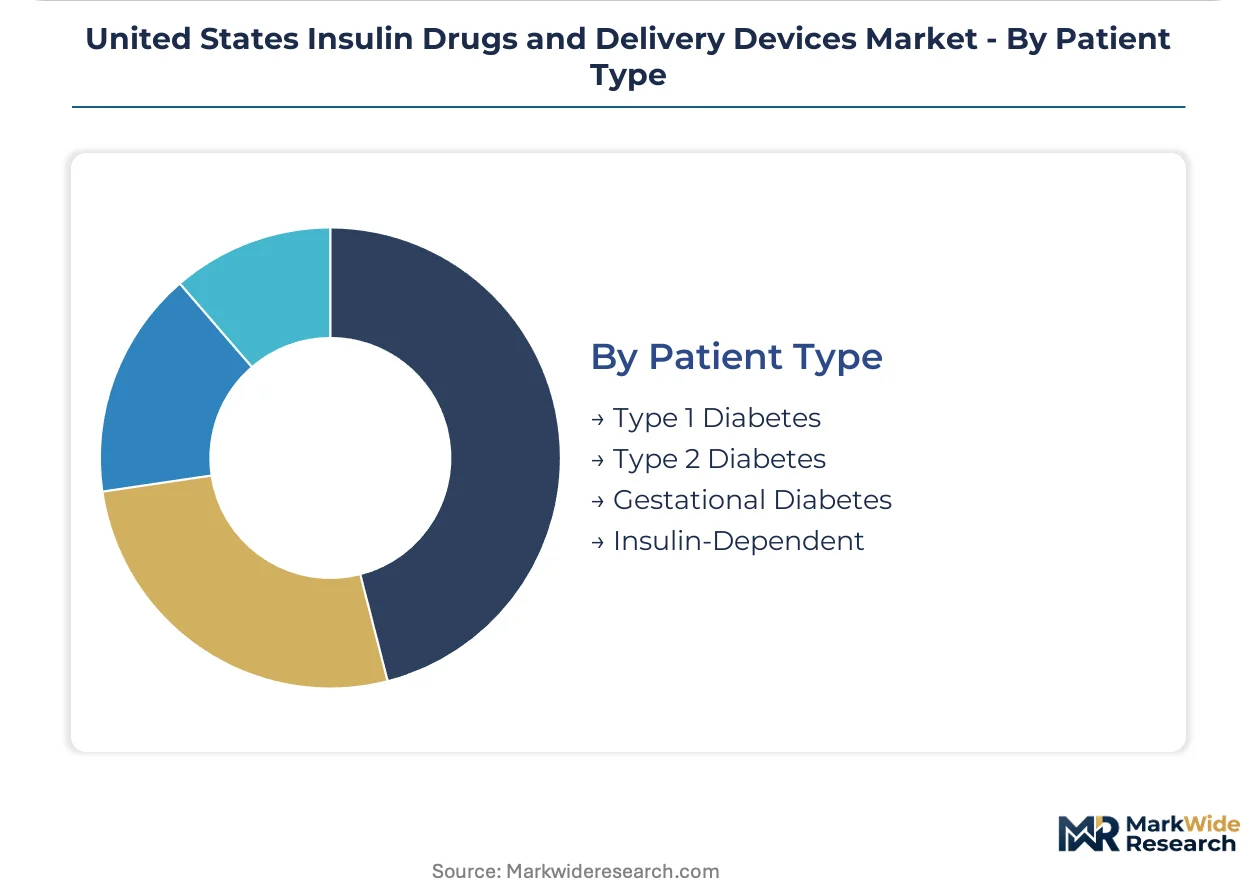
Patient Type:
Customer type segmentation aligns product configuration with disease duration, beta-cell reserve, and comorbidity burden.
- Type 1 Diabetes:Absolute insulin deficiency requiring exogenous replacement from diagnosis. Pediatric endocrinology centers in California and Massachusetts drive pump-CGM integration adoption.
- Type 2 Diabetes:Progressive insulin resistance with relative deficiency. Texas and Florida Medicare populations generate volume for basal insulin intensification protocols.
- Gestational Diabetes:Hyperglycemia during pregnancy requiring short-term glycemic control. Maternal-fetal medicine practices prioritize human insulin for safety profile certainty.
- Insulin-Dependent:Categorical designation spanning Type 1 and insulin-requiring Type 2 for reimbursement qualification. Medicaid prior authorization frameworks use this classification for preferred drug list placement.
Type 2 Diabetes accounts for the largest patient volume; Type 1 Diabetes is gaining share fastest on technology-enabled care model expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Diego anchors insulin pump innovation through Tandem Diabetes Care's headquarters and the surrounding medtech corridor. The metro's concentration of continuous glucose monitoring specialists feeds algorithm development pipelines. California's Medicaid expansion and Medicare Advantage penetration create overlapping reimbursement laboratories for device manufacturers.
California
Pediatric endocrinology centers in Los Angeles and San Francisco drive closed-loop system adoption for Type 1 diabetes management. Medi-Cal's preferred drug list for insulin analogs shapes manufacturer rebate negotiations. The Bay Area's digital health cluster produces interoperability software linking pumps with electronic health records.
Texas
Houston's Texas Medical Center generates volume for basal insulin intensification protocols among working-age Type 2 populations. State Medicaid prior authorization frameworks favor once-daily long-acting formulations for adherence advantages. Dallas-Fort Worth hospital systems consolidate insulin procurement through vertically structured specialty pharmacies.
Florida
Medicare-eligible populations in Miami-Dade and Broward counties concentrate demand for premixed insulin initiation regimens. State-level insulin copay cap legislation alters patient out-of-pocket exposure and volume elasticity. Jacksonville's integrated delivery networks displace independent retail channels for device fulfillment.
Massachusetts
Boston's academic medical centers pilot artificial pancreas systems at the fastest adoption rates nationally. MassHealth's coverage determinations for continuous glucose monitoring influence CMS national policy trajectories. The Route 128 corridor hosts contract manufacturers for recombinant protein production.
Ohio
Cleveland Clinic's endocrinology workforce trains rural extension providers across the Midwest. State Medicaid managed care contracts reference FDA biosimilar labeling in formulary placement decisions. Cincinnati's hospital systems expand outpatient chronic disease management procurement for insulin-dependent populations.
United States Insulin Drugs and Delivery Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the insulin delivery technology stack. The market consolidates around three strategic archetypes: diversified pharmaceutical conglomerates with GLP-1 portfolio breadth, pure-play device specialists with closed-loop algorithm capabilities, and biosimilar developers competing on price in Medicaid channels. Competitive moves concentrate on formulary positioning through pharmacy benefit manager negotiations and vertical integration into continuous glucose monitoring sensor production.
Within the diversified pharmaceutical tier, Novo Nordisk and Eli Lilly and Company exemplify contrasting strategic postures. Novo Nordisk occupies a position anchored in long-acting insulin manufacturing scale and Nordic operational heritage. Eli Lilly and Company represents the Indianapolis-based competitor leveraging biosimilar development pipelines to compete on price. Sanofi sits within the European multinational archetype with sustained brand loyalty in premixed insulin categories.
| Leading Market Players |
|---|
| Novo Nordisk |
| Eli Lilly and Company |
| Sanofi |
| Medtronic |
| Insulet Corporation |
| Tandem Diabetes Care |
| Ypsomed |
| Becton Dickinson and Company |
| Embecta Corp. |
| Others |
Value Network & Pricing Analysis
Closed-loop algorithm premiums diverge sharply from commodity basal insulin pricing, with the former commanding reimbursement advantages through CMS technology add-on payments while the latter faces Medicaid formulary compression. This bifurcation concentrates manufacturing investment in automated delivery ecosystems and fragments procurement across hospital-owned specialty pharmacies versus retail channels.
Pricing Analysis
Outcome-linked reimbursement anchors insulin pump-CGM bundles through Medicare Advantage quality metrics and hospital readmission reduction incentives. Price differentiation separates FDA-designated breakthrough devices with closed-loop algorithms from standard multiple daily injection regimens lacking connectivity features. Pricing pressure stems from state Medicaid biosimilar substitution mandates accelerating glargine and lispro commoditization. Uninsured and underinsured populations in Texas and Florida exhibit highest price sensitivity, while commercially covered Type 1 patients in California and Massachusetts demonstrate lowest elasticity for integrated systems.
Supply Chain Analysis
Single-source vulnerability sits with Chinese recombinant protein fermentation capacity and Indian active pharmaceutical ingredient synthesis for biosimilar insulin precursors. Domestic manufacturing draws from Danish and German engineering for precision pump components, while sensor electronics feed from Taiwanese semiconductor foundries. Tariff exposure on Chinese bioprocessing equipment threatens contract manufacturing expansion timelines. Distribution runs through vertically integrated hospital specialty pharmacies displacing independent retail fulfillment, particularly in Florida and Texas where integrated delivery networks dominate regional markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmacy benefit manager consolidation into three dominant entities is compressing formulary access fees and forcing subscale insulin manufacturers toward exit or acquisition. This concentration dynamic rewards players with manufacturing scale and integrated device portfolios.
For Market Incumbents: Extend closed-loop algorithm capabilities into dual-hormone systems combining insulin with GLP-1 agonists to preempt biosimilar price erosion in basal categories. Secure backward integration into continuous glucose monitoring sensor production to capture margin pools currently flowing to specialized component suppliers. The threat of Sanofi and Eli Lilly biosimilar undercutting in Medicaid channels demands defensive rebate positioning in Medicare Advantage preferred tiers. For New Entrants and Emerging Players: Artificial pancreas software modules represent the most penetrable wedge for technology-first challengers lacking manufacturing scale. Target rural extension clinics in Ohio and Texas where endocrinologist scarcity creates demand for automated glycemic management without specialist oversight. A reimbursement-first go-to-market angle leveraging state-level insulin copay cap legislation alters patient out-of-pocket exposure and volume elasticity in ways that favor new device entrants. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play algorithm developers given CMS national coverage determination expansion for continuous glucose monitoring beyond intensive insulin users. Long-term viability across a decade horizon favors acquisition targets with FDA breakthrough device designation and hospital system pilot contracts in Massachusetts or California. The signal to watch is CMS technology add-on payment decisions for artificial pancreas systems, which would validate reimbursement infrastructure for closed-loop platforms.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates review timelines for closed-loop algorithm submissions from Tandem Diabetes Care and Medtronic. |
| Hospital System Partnership | Florida and Texas integrated delivery networks consolidate insulin procurement through captive specialty pharmacies. |
| Backward Integration into Sensor Production | Insulet Corporation and Ypsomed capture margin pools from CGM component suppliers through in-house manufacturing. |
| Reimbursement Strategy | Medicare Advantage plans in California respond to CMS coverage expansion with preferred tier placement for pump-CGM bundles. |
| Software Companion Development | Interoperability platforms linking pumps with electronic health records emerge from Bay Area digital health clusters. |
Research Methodology
Independent corroboration across endocrinology practice administrators, hospital pharmacy procurement directors, and pharmacy benefit manager formulary leads underwrites the qualitative findings. Primary fieldwork with biomedical engineers at pump manufacturers and GPO contracts managers at Texas Medical Center and Cleveland Clinic supplemented secondary validation through FDA 510(k) filings, CMS national coverage determinations, and state Medicaid preferred drug list updates. Bottom-up prescription volume modeling triangulates against top-down manufacturer revenue disclosures across the analysis window.
Rate-of-change decomposition separates volume drivers from price mix effects across insulin product type, device connectivity tier, patient diabetes classification, and regional reimbursement cluster dimensions. CAGRs derive from segmented growth rate aggregation rather than single-point extrapolation, with forecast inputs incorporating biosimilar approval timelines under the Biologics Price Competition and Innovation Act and state-level copay cap legislative trajectories.
Several conditions sit outside the modeled scope, including unforeseen FDA safety actions on approved devices, disruptive non-insulin diabetes therapies altering treatment paradigms, and macroeconomic shifts affecting Medicare Advantage plan participation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Sustained Release Drugs Market
Pharmaceuticals
TNF Inhibitors Market
Pharmaceuticals
Global Parkinson's Disease Drugs Market
Pharmaceuticals
Authorized Generics Market
Pharmaceuticals
Pharmaceutical Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Meperidine Market
Pharmaceuticals
Sweden Pharmaceutical Market
Pharmaceuticals
Latin America Sodium-Glucose Cotransport-2 (SGLT-2) Inhibitor Market
Pharmaceuticals
Global Rotavirus Vaccine Market
Pharmaceuticals
Alprazolam Powder Market
Pharmaceuticals
Global Cyclosporine Market
Pharmaceuticals
Middle East and Africa Gastrointestinal Drugs Market
Pharmaceuticals
Global Interleukin Inhibitors Market
Pharmaceuticals
Global Opioid Induced Constipation Market
Pharmaceuticals
Europe Vaccines Market
Pharmaceuticals
Pharma 4.0 Market