
 Contract Manufacturing Services Market | 2026-2036
Contract Manufacturing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Contract Manufacturing Services Market Intelligence
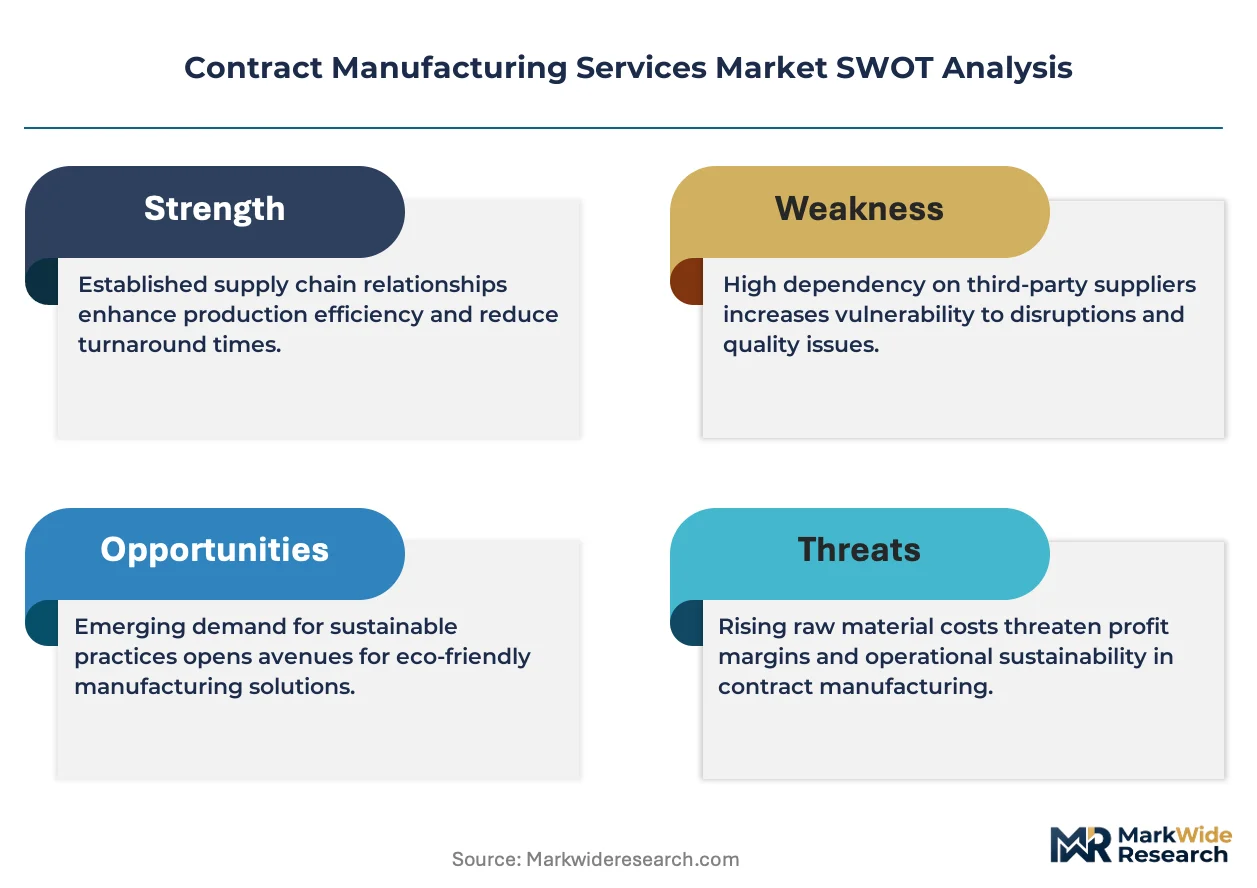
EU Medical Device Regulation is expanding compliance costs for European contract manufacturers serving medtech OEMs. Jabil Inc. leverages vertical integration across electronics and healthcare to sustain margin resilience in regulated verticals. Flex Ltd. anchors its competitive position through geographic diversification across Mexico, India, and Eastern Europe. Sanmina Corporation specializes in complex optical and RF assemblies where engineering density creates defensible positioning.
Contract manufacturing services encompass third-party production arrangements where OEMs delegate fabrication, assembly, or full product realization to external partners, typically governed by formal quality agreements specifying tolerance bands, statistical process control thresholds, and lot traceability protocols. The model transfers fixed asset risk from brand owners while granting access to specialized equipment and process expertise. Electronics contract manufacturing occupies the largest value pool within service type segmentation, driven by semiconductor packaging complexity and miniaturization requirements. Pharmaceutical contract manufacturing records the fastest expansion trajectory as biologics capacity scarcity pushes sponsors toward Lonza and Catalent. Prototype manufacturing within production capability segmentation commands premium pricing due to engineering intensity and low volume flexibility.
FDA enforces current Good Manufacturing Practice through facility inspections and warning letters that determine market access for pharmaceutical and medical device contract manufacturers. CE marking under EU MDR requires notified body involvement for higher-risk device classes, extending validation timelines. China's NMPA aligns with ICH Q7 guidelines for active pharmaceutical ingredient contract manufacturing, harmonizing inspection protocols. Stakeholders must monitor regulatory divergence between FDA's risk-based quality approach and EU MDR's stricter clinical evidence requirements when selecting contract manufacturing partners.
Market Dynamics
Biologics capacity scarcity is forcing pharmaceutical sponsors to externalize manufacturing assets, while FDA's Quality Management System Regulation tightens documentation burdens for medical device contract manufacturers simultaneously.
Growth Catalysts
- Biologics pipeline expansion:Cell and gene therapy candidates require specialized sterile fill-finish capacity that sponsors lack in-house. Lonza and Catalent capture this demand through dedicated multi-product facilities.
- EU Medical Device Regulation:MDR's stricter clinical evidence requirements push medtech OEMs toward contract manufacturers with established notified body relationships and validated quality systems.
- Yangtze River Delta concentration:Foxconn and Pegatron anchor electronics clusters serving Apple and Dell, creating supplier network effects that attract component vendors and reduce logistics costs.
Market Restraints
- Specialized input cost volatility:Rare earth elements and semiconductor-grade chemicals face price swings that compress contract manufacturer margins on fixed-price agreements.
- Single-source geography risk:China's dominance in active pharmaceutical ingredient synthesis creates supply vulnerability when NMPA inspection backlogs delay facility approvals.
- Technical limitation in continuous bioprocessing:Real-time release testing and perfusion culture systems remain immature for commercial-scale monoclonal antibody production.
Strategic Opportunities
- India's PLI scheme for medical devices:Production-linked incentives attract contract manufacturers to Gujarat and Karnataka clusters for export-oriented orthopedic and diagnostic equipment.
- Regulatory tailwind from FDA's advanced manufacturing:Quality-by-design and process analytical technology adoption create differentiation for contract manufacturers investing in digital twins.
- Technology convergence of additive manufacturing and RF engineering:3D-printed antenna substrates enable rapid prototyping for aerospace and defense electronics contract manufacturers.
Industry Challenges
- Bioprocess engineering talent gap:Cell culture specialists and downstream purification experts command premium compensation, constraining facility expansion timelines.
- ISO 13485 certification timeline compression:Medical device contract manufacturers face 12-18 month notified body queues that delay new program launches.
- Legacy MES integration complexity:Pharmaceutical sponsors require SAP or Wonderware connectivity that forces expensive retrofitting of established contract manufacturing sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contract Manufacturing Services Market |
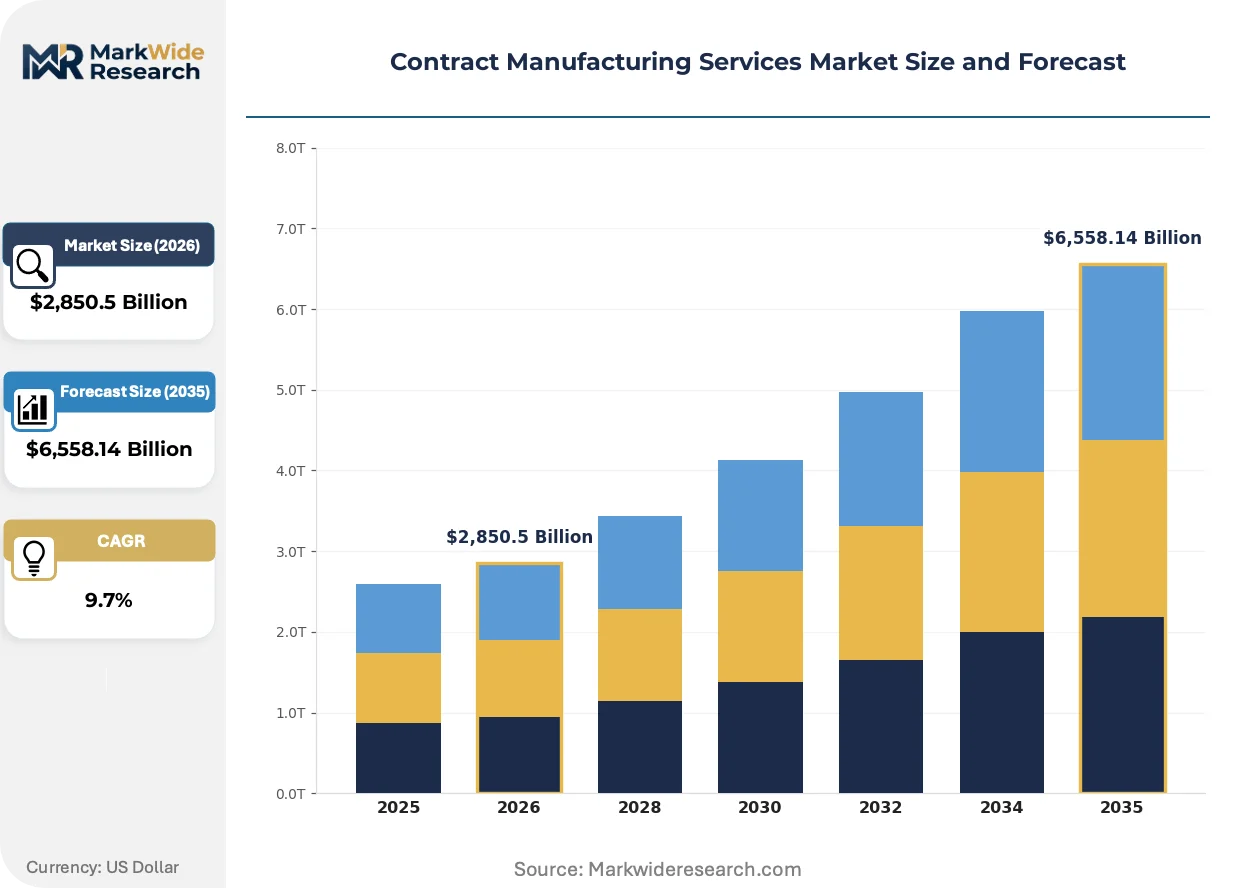
| Market Size in 2026 | $2,850.5 Billion |
| Market Size in 2035 | $6,558.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Electronics, Pharmaceuticals, Food Processing, Consumer Goods Industry Vertical: Aerospace, Automotive, Medical Devices, Cosmetics Production Capability: Mass Production, Batch Production, Prototype Manufacturing, Custom Manufacturing Quality Standard: ISO Certification, GMP Compliance, CE Marking, FDA Approval |
| Companies Covered | Jabil Inc., Flex Ltd., Celestica Inc., Benchmark Electronics, Inc., Sanmina Corporation, Proto Labs, Xometry, Catalent Pharma Solutions Inc., Lonza Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contract Manufacturing Services Market Strategic Shifts & Innovations
Digital thread architectures are compressing design-to-manufacturing handoffs, while regulatory convergence around ICH Q7 guidelines harmonizes inspection protocols across FDA, EMA, and NMPA jurisdictions.
Continuous bioprocessing is consolidating upstream cell culture and downstream purification into integrated perfusion systems. Biologics contract manufacturers adopt this technology to reduce facility footprint and improve product consistency. The shift is compressing batch cycle times from weeks to days, enabling capacity-constrained sponsors to accelerate clinical supply.
REACH substance restrictions are forcing electronics contract manufacturers to substitute halogenated flame retardants in printed circuit board laminates. The industrial consequence is qualification of phosphorus-based alternatives that require revised thermal profiling during reflow soldering. Medical device and automotive segments in Germany and France face the tightest compliance deadlines.
Engineering services unbundling is separating prototype development from volume manufacturing contracts. Aerospace and defense OEMs now source initial units from specialized model shops before transferring to high-volume electronics contract manufacturers. This bifurcation is most visible in Southern California and Israel, where rapid prototyping clusters serve satellite and drone programs.
Contract Manufacturing Services Market Segmentation
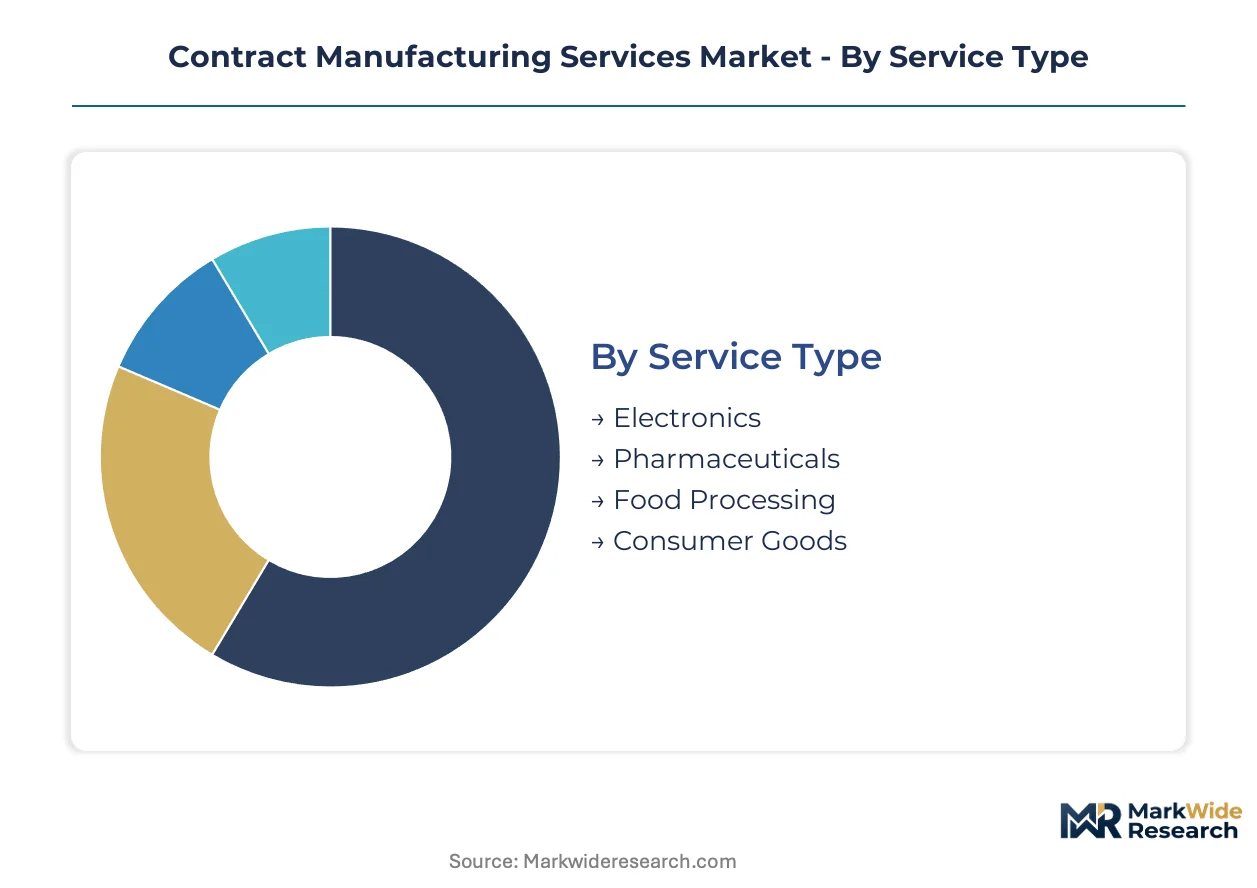
Contract manufacturing services fragment across service types, industry verticals, production capabilities, and quality standards. Each dimension shapes supplier selection criteria, margin structures, and regulatory exposure for OEM sponsors.
Service Type:
Electronics and pharmaceuticals concentrate capital investment and specialized talent pools, while food processing and consumer goods compete on scale economics and geographic proximity to end markets.
- Electronics:Semiconductor packaging, printed circuit board assembly, and system integration dominate value capture. Demand clusters in China's Yangtze River Delta and Mexico's Baja California corridor, where Foxconn and Jabil operate multi-facility campuses serving Apple and Dell.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis, sterile fill-finish, and biologics manufacturing require containment infrastructure and validated cleanrooms. Lonza and Catalent capture biologics capacity scarcity as cell therapy pipelines thicken.
- Food Processing:Co-packing, thermal processing, and private-label formulation serve retail and foodservice channels. Regional players dominate due to perishability constraints and local taste preferences.
- Consumer Goods:Personal care, household products, and apparel assembly compete on labor arbitrage and logistics optimization. Southeast Asia and Central America attract volume seeking tariff advantages.
Electronics absorbs the bulk of installed capacity; pharmaceuticals is expanding most quickly.
Industry Vertical:
Regulatory intensity and engineering complexity vary sharply across verticals, dictating certification requirements and pricing power for contract manufacturers.
- Medical Devices:Class II and III devices require FDA QSR compliance and ISO 13485 certification. EU MDR's stricter clinical evidence requirements push OEMs toward contract manufacturers with established notified body relationships.
- Aerospace:AS9100 certification and NADCAP accreditation for special processes filter supplier bases. Precision machining and composite fabrication concentrate in Wichita, Kansas and Toulouse, France.
- Automotive:IATF 16949 quality standards and just-in-sequence delivery requirements dominate OEM procurement. Mexico and Eastern Europe attract powertrain and electronics module assembly.
- Cosmetics:Formulation, filling, and packaging services compete on speed-to-market for trend-driven SKU proliferation. FDA cosmetic facility registration requirements are tightening post-Modernization of Cosmetics Regulation Act.
Medical Devices commands premium pricing tiers; Aerospace is gaining share fastest among regulated verticals.
Production Capability:
Volume scale and flexibility tradeoffs determine facility configuration and customer mix for contract manufacturers.
- Mass Production:High-volume, low-mix lines optimize unit economics through automation and dedicated tooling. Electronics and automotive verticals concentrate demand in multi-million-unit programs.
- Prototype Manufacturing:Low-volume, high-engineering-intensity work commands premium pricing for design validation and clinical builds. Southern California and Israel clusters serve aerospace and medtech development programs.
- Batch Production:Mid-scale campaigns suit pharmaceutical campaigns and seasonal consumer goods with changeover flexibility requirements.
- Custom Manufacturing:Engineer-to-order configurations serve industrial equipment and specialized medical devices with patient-specific or application-unique requirements.
Mass Production absorbs the bulk of installed capacity; Prototype Manufacturing climbs the fastest as unbundling from volume manufacturing accelerates.
Quality Standard:
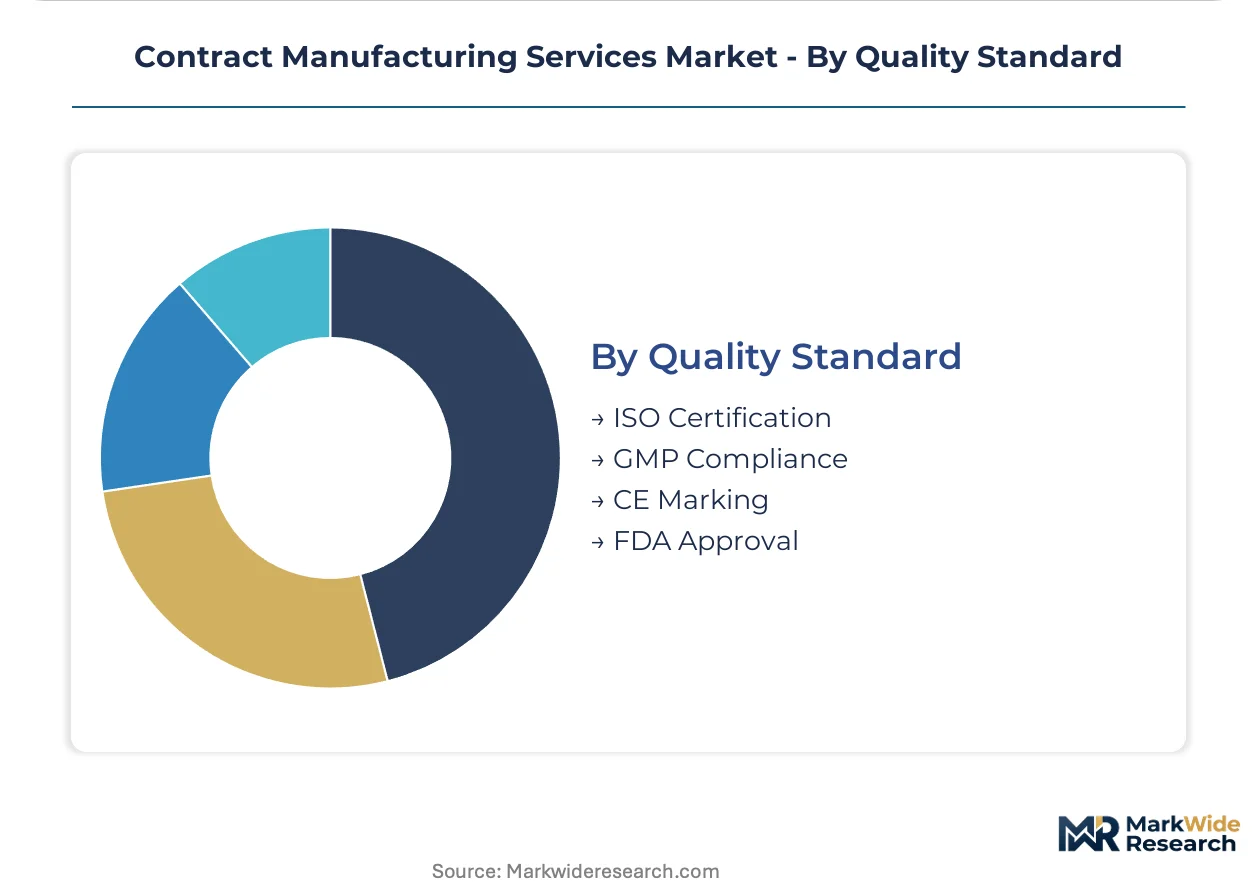
Certification tier determines market access and margin structure across regulated and non-regulated end markets.
- FDA Approval:Facility inspections and warning letter history determine pharmaceutical and medical device contract manufacturer viability. Current Good Manufacturing Practice enforcement intensifies documentation burdens.
- ISO Certification:ISO 9001 base quality management and ISO 13485 medical device specialization filter supplier bases. Certification maintenance costs scale with facility complexity.
- GMP Compliance:ICH Q7 harmonization across FDA, EMA, and NMPA jurisdictions reduces audit redundancy for active pharmaceutical ingredient manufacturers.
- CE Marking:EU MDR notified body involvement extends validation timelines for higher-risk device classes, favoring contract manufacturers with established European regulatory infrastructure.
FDA Approval commands the steepest compliance investment; GMP Compliance is climbing the fastest as regulatory convergence reduces multi-market friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones anchor the highest concentration of electronics contract manufacturing capacity globally. Tax incentives and bonded logistics zones in Suzhou and Kunshan attract component suppliers to cluster around Foxconn and Pegatron assembly campuses. This spatial concentration reduces inbound logistics costs and compresses prototype-to-production timelines for OEM sponsors.
United States
Biologics capacity scarcity drives pharmaceutical sponsors toward external manufacturing partners in Massachusetts and North Carolina research corridors. FDA's Quality Management System Regulation intensifies documentation burdens for medical device contract manufacturers seeking 510(k) clearance. Boston-Cambridge and Research Triangle Park clusters concentrate cell therapy CDMOs serving emerging gene therapy pipelines.
Germany
REACH substance restrictions force electronics contract manufacturers to qualify phosphorus-based flame retardants for printed circuit board laminates. EU Medical Device Regulation's stricter clinical evidence requirements push medtech OEMs toward contract manufacturers with established notified body relationships. Baden-Württemberg's precision engineering corridor concentrates automotive and industrial automation contract manufacturing.
India
Production-linked incentive schemes for medical devices attract contract manufacturers to Gujarat and Karnataka clusters for export-oriented orthopedic equipment. CDSCO alignment with ICH Q7 guidelines harmonizes active pharmaceutical ingredient inspection protocols with FDA and EMA standards. Hyderabad's pharmaceutical corridor and Bengaluru's electronics manufacturing zone anchor divergent specialization tracks.
Mexico
Nearshoring momentum accelerates electronics and automotive contract manufacturing expansion across Baja California and Nuevo León. IATF 16949 quality standards and just-in-sequence delivery requirements dominate OEM procurement for powertrain module assembly. Tijuana and Monterrey industrial parks concentrate capacity serving US West Coast and Texas-based OEM supply chains.
Switzerland
Swissmedic's stringent pharmaceutical manufacturing standards sustain premium positioning for biologics contract manufacturers serving European and US markets. Geneva and Basel pharmaceutical corridors concentrate sterile fill-finish capacity for monoclonal antibody and cell therapy production. Precision engineering traditions extend into medical device contract manufacturing for orthopedic and diagnostic equipment.
Contract Manufacturing Services Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market strata. Electronics and healthcare verticals concentrate revenue among vertically integrated multi-nationals with cross-border facility networks. Three archetypes dominate: scale-driven mass producers, engineering-intensive prototype specialists, and regulatory-certified pharmaceutical CDMOs. Capacity expansion and geographic diversification constitute the dominant competitive moves as sponsors seek supply chain resilience.
Among US-based diversified manufacturers, Jabil Inc. and Flex Ltd. exemplify multi-vertical conglomerates spanning electronics assembly and healthcare equipment. Swiss Lonza Group AG anchors the pharmaceutical CDMO archetype with biologics manufacturing specialization. These three entities represent contrasting strategic postures: diversified vertical coverage versus focused therapeutic domain expertise versus hybrid electronics-healthcare integration.
| Leading Market Players |
|---|
| Jabil Inc. |
| Flex Ltd. |
| Celestica Inc. |
| Benchmark Electronics, Inc. |
| Sanmina Corporation |
| Proto Labs |
| Xometry |
| Catalent Pharma Solutions Inc. |
| Lonza Group AG |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between FDA-validated pharmaceutical CDMOs and commodity electronics assemblers manifests in divergent margin structures and supplier network configurations. Premium-tier biologics manufacturers command fixed-price multi-year contracts with cost-plus escalation clauses, while electronics contract manufacturers absorb rare earth volatility through spot-market hedging and Yangtze River Delta logistics clustering.
Pricing Analysis
Lead-time compression commands explicit premiums in pharmaceutical sterile fill-finish, where sponsors pay surcharges for accelerated slot access during clinical trial recruitment windows. Electronics contract manufacturing operates on three-tier pricing structure across premium, standard, and economy levels differentiated by volume commitment scale and engineering service bundling. Cost compression in consumer electronics assembly is intensifying because OEMs consolidate supplier panels and mandate annual productivity improvements. Small-batch prototype buyers exhibit highest price sensitivity, while gene therapy sponsors demonstrate inelastic demand for qualified biologics capacity.
Supply Chain Analysis
Dual-sourcing mandates from medical device OEMs now require contract manufacturers to qualify redundant cleanroom facilities across FDA and EMA jurisdictions simultaneously. Active pharmaceutical ingredient synthesis draws from India, China, and Switzerland, with sterile fill-finish capacity clustering in Massachusetts, North Carolina, and Basel. Rare earth elements, semiconductor-grade chemicals, and bioprocess resins constitute critical input dependencies. Single-source geography risk concentrates in China's dominance of API intermediates. Distribution runs through bonded logistics zones in Suzhou and direct-to-plant milk runs for automotive just-in-sequence programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contract manufacturing services constitute a vertical-integration race where control over specialized bioprocess engineering talent and sterile capacity has become the decisive upstream lever. Players are pursuing backward integration into raw material synthesis and downstream into packaging and logistics to capture margin pools.
For Market Incumbents: Acquire bioprocess engineering talent pools through dedicated training partnerships with MIT and ETH Zurich rather than market-rate recruitment. Expand sterile fill-finish capacity in Research Triangle Park and Basel corridors to preempt gene therapy CDMO demand. Cell therapy pipeline sponsors represent the emerging threat requiring defensive positioning. FDA Quality Management System Regulation compliance infrastructure serves as the critical certification lever for medical device verticals.
For New Entrants and Emerging Players: Specialized model shops serving Southern California aerospace clusters offer the most penetrable entry channel before scaling to volume manufacturing. Target India's Gujarat medical device production-linked incentive zones for orthopedic equipment export capacity. Prototype-to-production handoff services for drone and satellite programs provide specific go-to-market traction with defense primes.
For Investors and Strategic Acquirers: Re-rating potential sits with pharmaceutical CDMOs possessing both FDA and EMA biologics facility approvals given EU MDR's stricter clinical evidence requirements extending validation timelines. Long-term viability over the coming decade hinges on continuous bioprocessing technology adoption and digital twin integration. Acquisition target archetype: mid-scale sterile manufacturers with underutilized capacity and established notified body relationships. Signal to watch is NMPA inspection backlog resolution pace indicating China API supply normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | FDA QSR and EU MDR dual compliance opens access to premium medical device OEM procurement panels. |
| Continuous Bioprocessing Adoption | Perfusion culture systems reduce facility footprint and accelerate batch cycle times for capacity-constrained sponsors. |
| Geographic Diversification | Mexico and India manufacturing footprints mitigate tariff exposure and single-source China dependency risks. |
| Engineering Services Unbundling | Separate prototype development contracts capture premium pricing before volume manufacturing transfer. |
| Digital Thread Architecture | SAP and Wonderware MES integration satisfies pharmaceutical sponsor connectivity requirements for facility selection. |
Research Approach
Multi-period observation of biologics capacity utilization rates, FDA warning letter issuance patterns, and electronics bill-of-materials cost indices anchored the trend analysis, supplemented by interviews with contract manufacturing procurement directors, pharmaceutical sponsor supply chain executives, regulatory affairs leads, and CDSCO inspection officials. Secondary validation incorporated FDA 483 observation databases, EMA GMP inspection reports, NMPA facility approval records, and SEC 10-K filings from diversified manufacturers. Bottom-up facility capacity modeling and top-down OEM outsourcing spend estimates were triangulated.
Input-output matrices mapped service type segmentation against industry vertical demand across the analysis window, with pharmaceutical CDMO expansion, electronics miniaturization requirements, and medical device regulatory convergence as core demand drivers. Treatment modality, device classification tier, production capability scale, and regional regulatory cluster dimensions structured the segmentation. CAGRs were derived from facility expansion announcements, sponsor pipeline disclosures, and qualified capacity scarcity indicators.
Caveats apply where NMPA inspection backlog resolution, REACH substance restriction implementation timelines, or continuous bioprocessing technology maturation could materially shift the outlook. Deviation in biologics pipeline advancement rates or FDA enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Global Acute Hospital Care Market
Healthcare Services
Healthcare CRO Services Market
Healthcare Services
Nutraceutical Contract Manufacturing Services Market
Healthcare Services
Long Term Care Market
Healthcare Services
Vaccine Transport Carrier Market
Healthcare Services
Biopharmaceutical Third Party Logistics (3PL) Market
Healthcare Services
Funeral and Cremation Services Market
Healthcare Services
Global Healthcare Provider Network Management Market
Healthcare Services
Bruxism Management Market
Healthcare Services
Prescription Delivery Services Market
Healthcare Services
Assisted Living Market
Healthcare Services
EMEA Home Infusion Services Market
Healthcare Services
Kids Sports Injury Treatment Market
Healthcare Services
Healthcare Revenue Cycle Management (RCM) Outsourcing Market
Healthcare Services
US Acute Hospital Care Market
Healthcare Services
Immunoassay CDMO Market