
 Dopamine and Norepinephrine Reuptake Inhibitor Market | 2026-2036
Dopamine and Norepinephrine Reuptake Inhibitor Market Size, Share, and Industry Trends Forecast 2026-2036
Dopamine and Norepinephrine Reuptake Inhibitor Market Outlook
Outpatient psychiatric clinics are rotating toward first-line use of dopamine and norepinephrine reuptake inhibitors as hospital formularies tighten prior authorization requirements. Pfizer Inc. leverages its established CNS commercial infrastructure to sustain institutional contracts across academic medical centers. Eli Lilly and Company anchors its position through deep R&D investment in novel neurotransmitter modulation platforms. GlaxoSmithKline Plc. competes via specialized distribution networks that control specialty pharmacy access.
Dopamine and norepinephrine reuptake inhibitors constitute a pharmacological class that blocks presynaptic monoamine transporters, elevating synaptic concentrations of both catecholamines to treat attention-deficit hyperactivity disorder and major depressive disorder; extended-release formulations dominate prescribing patterns due to improved compliance profiles. Atomoxetine occupies the largest revenue pool among product types, reflecting its established pediatric and adult ADHD labeling. Oral administration routes lead volume distribution, though transdermal delivery systems attract development investment for patients with swallowing difficulties or gastric intolerance. Hospital pharmacies channel the majority of initial prescriptions, yet specialty pharmacies capture higher-margin refill volumes for chronic therapy maintenance.
The FDA governs new drug approvals and post-market surveillance through risk evaluation and mitigation strategies, while the DEA schedules controlled substances that constrain manufacturing quotas and distribution tracking. EMA's centralized marketing authorization procedure shapes European market entry timelines, particularly for pediatric indication extensions. Stakeholders must monitor evolving pharmacovigilance requirements for cardiovascular safety signals as regulatory scrutiny intensifies for agents with noradrenergic activity profiles.
Market Dynamics
Outpatient psychiatric clinics are rotating prescribing authority away from hospital-based psychiatrists as reimbursement frameworks favor community-based chronic disease management. This structural shift compresses institutional formulary control while elevating specialty pharmacy influence over long-term adherence.
Growth Catalysts
- FDA Streamlined Review Pathways:Accelerated approval designations for psychiatric indications compress development timelines and reduce regulatory capital requirements for novel monoamine modulators.
- Pediatric Labeling Expansions:Extended-release formulations targeting adolescent ADHD populations unlock new prescriber segments in academic medical center outpatient departments.
- Chronic Disease Infrastructure:United States care coordination programs embed psychiatric medication management within primary care workflows, sustaining therapeutic adherence through integrated health systems.
Market Restraints
- DEA Manufacturing Quotas:Controlled substance scheduling constrains production volume flexibility and creates supply bottlenecks during demand surges.
- Cardiovascular Safety Surveillance:EMA pharmacovigilance requirements mandate costly post-market monitoring for noradrenergic activity signals, elevating compliance expenditures.
- Generic Atomoxetine Substitution:Patent expiration erosion of reference product pricing compresses revenue pools available for novel mechanism investment.
Strategic Opportunities
- Transdermal Delivery Systems:Patch-based administration targets patients with dysphagia or gastric intolerance, opening adherence improvements in geriatric and pediatric segments.
- Specialty Pharmacy Channel Control:Direct distribution partnerships bypass wholesale markups and capture refill margin concentration for chronic maintenance therapy.
- IRB Streamlined Pediatric Trials:Institutional review board efficiency initiatives accelerate adolescent indication expansion timelines for existing adult-approved agents.
Industry Challenges
- Psychopharmacology Talent Scarcity:Clinical investigator shortages in CNS drug development extend trial recruitment timelines and inflate site costs.
- Legacy EHR Integration:Electronic health record interoperability gaps between hospital and outpatient systems fragment prescription tracking and adherence monitoring.
- Multi-Jurisdictional Labeling Harmonization:Divergent FDA and EMA pediatric indication requirements force duplicative clinical program investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dopamine and Norepinephrine Reuptake Inhibitor Market |
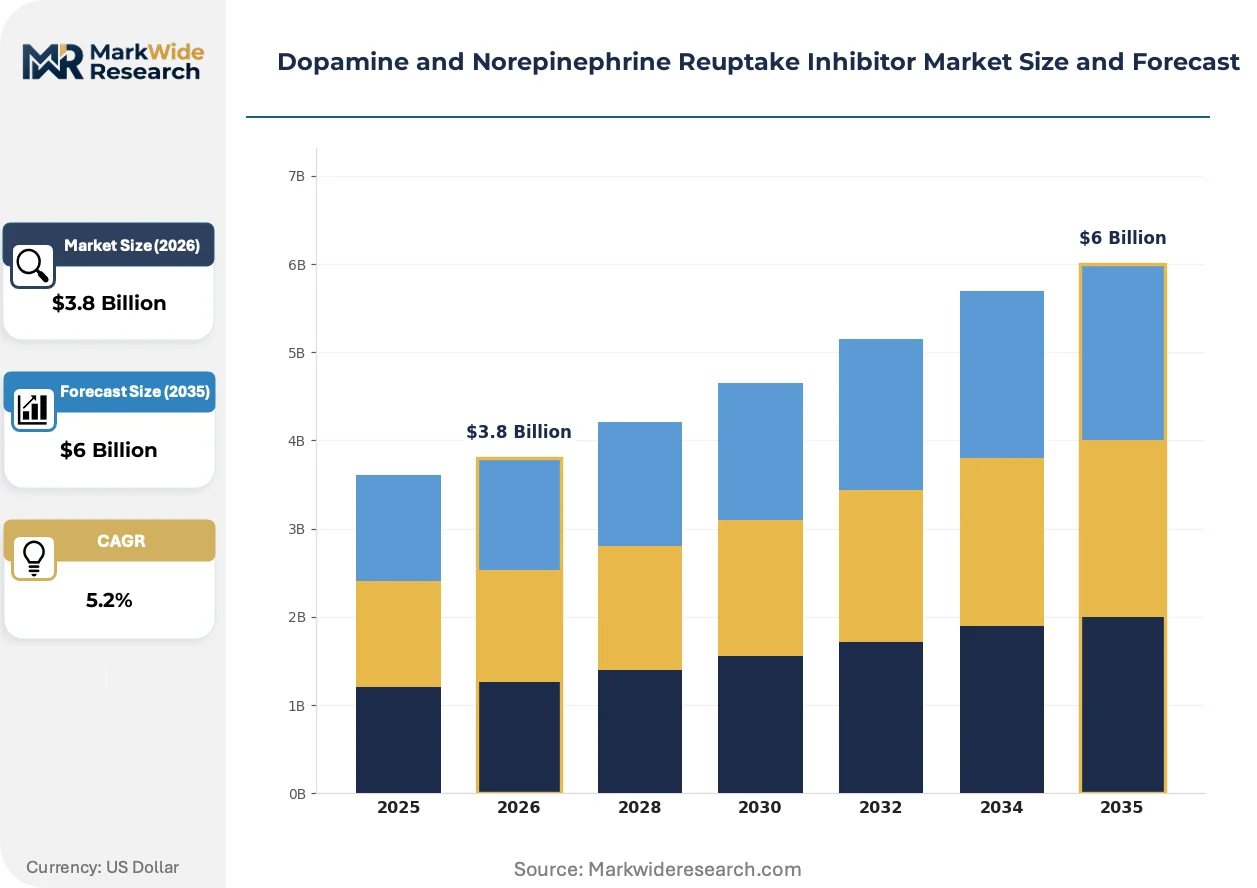
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Atomoxetine, Desipramine, Reboxetine, Venlafaxine End User: Hospitals, Clinics, Patients, Physicians Administration Route: Oral, Intravenous, Subcutaneous, Transdermal Distribution Channel: Retail Pharmacies, Online Pharmacies, Hospital Pharmacies, Speciality Pharmacies |
| Companies Covered | Pfizer Inc., Eli Lilly and Company, GlaxoSmithKline Plc., Teva Pharmaceutical Industries Ltd., H. Lundbeck A/S, Viatris Inc., Novartis AG, Takeda Pharmaceutical Co. Ltd., AstraZeneca Plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dopamine and Norepinephrine Reuptake Inhibitor Market Strategic Shifts
Formulation science and regulatory pathway innovation are compressing development cycles while channel restructuring redistributes economic capture between institutional and retail pharmacy settings.
Extended-release oral delivery systems incorporating osmotic pump technology are supplanting immediate-release tablets in first-line ADHD prescribing. Academic medical center outpatient clinics now prioritize once-daily regimens that reduce school-day dosing burdens. This shift is supplanting multi-dose compliance failures and reducing emergency department visits for medication management complications.
EMA's centralized marketing authorization procedure now mandates pediatric investigation plans as binding pre-submission requirements for all new psychiatric indications. This regulatory architecture forces sponsors to commit to adolescent trials before adult approval, altering capital allocation across development portfolios. European market entry timelines for ADHD extensions now hinge on juvenile toxicology study completion rather than adult efficacy data alone.
Specialty pharmacies are capturing refill volume concentration through hub-and-spoke distribution models that displace traditional retail chain fulfillment. These channels embed adherence counseling and prior authorization management services that hospital discharge programs struggle to replicate. The United States exhibits the most pronounced channel migration, where vertically integrated health plans steer chronic psychiatric maintenance toward captive specialty pharmacy networks.
Dopamine and Norepinephrine Reuptake Inhibitor Market Segmentation
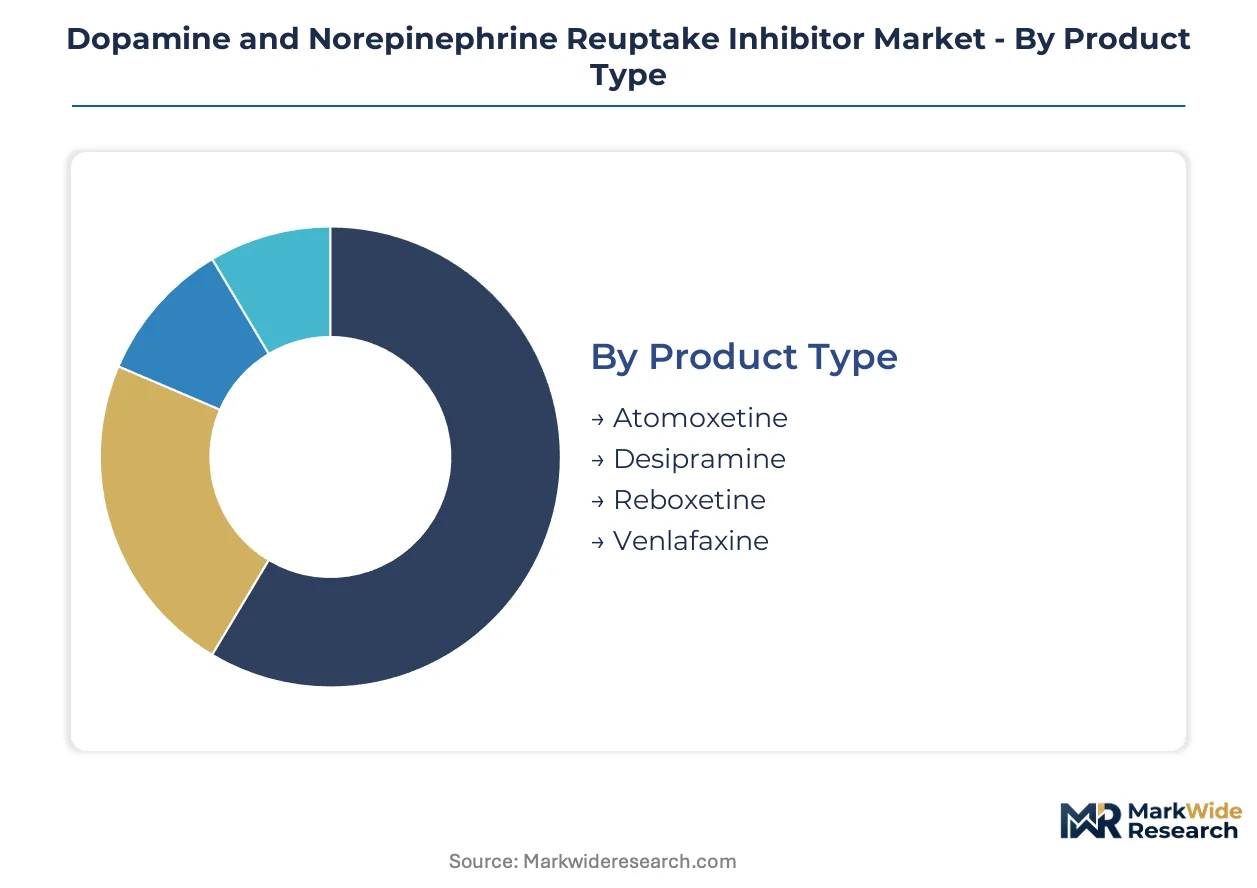
Segmentation in the dopamine and norepinephrine reuptake inhibitor market reveals how formulation characteristics, prescriber settings, and channel economics fragment commercial opportunity. Understanding these divisions enables targeted resource allocation across development portfolios and distribution investments.
Product Type:
Atomoxetine faces the most intense substitution pressure from generic entrants, while newer entrants in the class compete on differentiated pharmacokinetic profiles and expanded indication labeling.
- Atomoxetine:Selective norepinephrine reuptake inhibitor with established pediatric and adult ADHD labeling across FDA and EMA jurisdictions. United States academic medical centers concentrate demand for branded formulations despite generic erosion, driven by institutional formulary inertia and prior authorization frameworks that favor reference products. Supply constraints from DEA manufacturing quotas periodically disrupt availability.
- Venlafaxine:Serotonin-norepinephrine reuptake inhibitor with broader antidepressant labeling that extends prescriber reach beyond psychiatrists to primary care physicians. European markets exhibit stronger venlafaxine utilization relative to atomoxetine, reflecting EMA pediatric investigation plan requirements that have accelerated adolescent indication expansions. Extended-release formulations dominate new prescriptions.
- Desipramine:Tricyclic antidepressant with noradrenergic activity retains niche utilization in treatment-resistant depression protocols.
- Reboxetine:Selective norepinephrine reuptake inhibitor with restricted geographic availability, concentrated in European markets where EMA centralized authorization enabled broader access.
Atomoxetine anchors the volume base while venlafaxine gains share at the steepest rate through primary care channel expansion.
End User:
Cost tier stratification separates institutional purchasers with formulary control from individual patients bearing out-of-pocket exposure.
- Hospitals:Academic medical centers and general hospitals channel initial prescriptions through discharge protocols and emergency department referrals. United States institutions face tightening prior authorization requirements that compress inpatient initiation volumes. EHR integration gaps between hospital and outpatient systems fragment continuity of care.
- Clinics:Outpatient psychiatric clinics concentrate chronic disease management as reimbursement frameworks favor community-based care. These settings prioritize once-daily extended-release formulations that reduce dosing burden. Specialty pharmacy partnerships enable direct refill capture.
- Physicians:Individual practitioners in solo or small-group settings represent fragmented demand with limited formulary leverage.
- Patients:Direct-to-consumer channels emerge for established maintenance therapy with stable dosing regimens.
Hospitals anchor the volume base while clinics gain share at the steepest rate as reimbursement migrates toward outpatient settings.
Administration Route:
Application-driven selection separates chronic maintenance regimens from acute intervention scenarios.
- Oral:Immediate-release and extended-release tablets dominate prescribing patterns due to manufacturing scale and patient familiarity. Osmotic pump technology enables once-daily dosing that improves school-day compliance in pediatric ADHD populations. United States formularies prioritize oral routes for cost containment.
- Transdermal:Patch-based delivery targets patients with dysphagia, gastric intolerance, or adherence challenges in geriatric and pediatric segments. Development investment concentrates on modified release kinetics that match circadian symptom patterns. EMA pharmacovigilance requirements for cardiovascular safety surveillance elevate regulatory hurdles.
- Intravenous:Reserved for acute psychiatric settings with supervised administration protocols.
- Subcutaneous:Limited current utilization, with development programs exploring depot formulations for long-acting maintenance.
Oral routes anchor the volume base while transdermal delivery gains share at the steepest rate through adherence-focused differentiation.
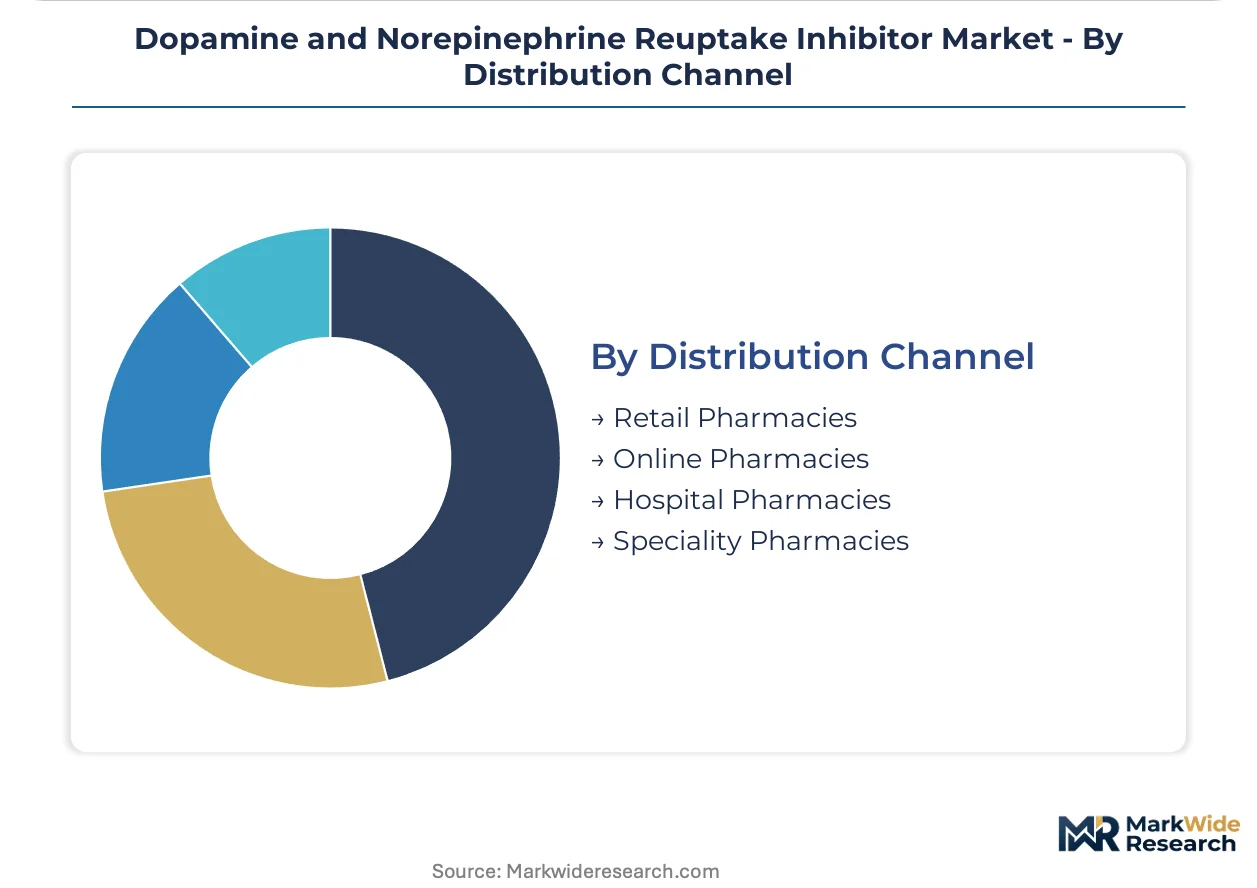
Distribution Channel:
Margin concentration varies sharply across channels, with specialty pharmacies capturing higher-value refill economics.
- Specialty Pharmacies:Hub-and-spoke distribution models embed adherence counseling, prior authorization management, and patient assistance program navigation. United States vertically integrated health plans steer chronic psychiatric maintenance toward captive specialty networks. These channels capture refill volume concentration that hospital discharge programs cannot replicate.
- Hospital Pharmacies:Channel the majority of initial prescriptions but struggle with long-term adherence monitoring. Institutional formulary control tightens as reimbursement frameworks shift risk to outpatient settings.
- Retail Pharmacies:Face displacement from specialty pharmacy networks for chronic maintenance therapy.
- Online Pharmacies:Emerging channel for established patients with stable regimens and limited prescriber interaction requirements.
Hospital pharmacies anchor the volume base while specialty pharmacies gain share at the steepest rate through chronic therapy margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for dopamine and norepinephrine reuptake inhibitors clusters in jurisdictions with established pharmaceutical infrastructure and favorable regulatory frameworks for CNS drug production. The United States anchors commercial volume through integrated health systems and specialty pharmacy networks. European markets concentrate development activity around EMA centralized procedures. Asian manufacturing hubs supply active pharmaceutical ingredients while expanding domestic formulation capabilities.
United States
Academic medical centers in Boston, New York, and California drive prescription volumes for extended-release ADHD formulations. FDA streamlined review pathways accelerate pediatric indication expansions through breakthrough therapy designations. The Research Triangle Park cluster in North Carolina hosts contract manufacturing organizations producing osmotic pump technology for once-daily regimens.
Germany
Outpatient psychiatric clinics in Bavaria and North Rhine-Westphalia prioritize venlafaxine prescribing for treatment-resistant depression protocols. EMA pharmacovigilance requirements mandate cardiovascular safety monitoring that elevates post-market compliance costs. The Frankfurt-Rhine-Main biotech corridor concentrates clinical trial sites for adolescent ADHD studies.
Japan
PMDA consultations for pediatric investigation plans compress development timelines for novel monoamine modulators. Tokyo and Osaka academic hospitals channel initial prescriptions through discharge protocols with embedded specialty pharmacy handoffs. The Kansai region hosts formulation development facilities targeting transdermal delivery systems for geriatric populations.
India
CDSCO approvals for generic atomoxetine formulations expand access while compressing pricing for reference products. Maharashtra and Gujarat manufacturing clusters supply active pharmaceutical ingredients to multinational sponsors. Bangalore's clinical research organizations accelerate recruitment for multinational ADHD trials through pediatric site networks.
Switzerland
Swissmedic marketing authorizations for psychiatric indications leverage EMA centralized assessments while maintaining independent pediatric safety requirements. Basel and Zurich host headquarters operations for companies with CNS-focused R&D portfolios. The country's contract research sector specializes in juvenile toxicology studies required for European market entry.
Dopamine and Norepinephrine Reuptake Inhibitor Market Competitive Environment
Concentration sits with diversified pharmaceutical conglomerates that leverage established CNS commercial infrastructure across institutional and outpatient channels. The market structure reflects tiered competition between originator manufacturers defending patent-protected formulations and generic entrants exploiting regulatory pathway efficiencies. Three archetypes dominate: multinational conglomerates with psychiatric portfolios, specialty-focused CNS developers, and vertically integrated generic manufacturers. Competitive dynamics center on portfolio diversification through novel delivery mechanisms and geographic expansion via pediatric indication harmonization.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and Eli Lilly and Company exemplify archetypes that anchor commercial positions through institutional formulary relationships. Takeda Pharmaceutical Co. Ltd. occupies a position within the specialty-focused tier, representing developers concentrating neurotransmitter modulation platforms. These companies sit within a competitive matrix where extended-release formulation patents and specialty pharmacy channel control determine margin capture for chronic maintenance therapy.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Eli Lilly and Company |
| GlaxoSmithKline Plc. |
| Teva Pharmaceutical Industries Ltd. |
| H. Lundbeck A/S |
| Viatris Inc. |
| Novartis AG |
| Takeda Pharmaceutical Co. Ltd. |
| AstraZeneca Plc. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between specialty pharmacy networks and branded manufacturers lock in supply access for extended-release formulations while anchoring price visibility across the reimbursement cycle. These contracts insulate atomoxetine reference products from spot-market volatility even as generic substitution erodes tier-one pricing in retail channels.
Pricing Analysis
DEA manufacturing quotas dictate the pricing tier structure for controlled substance formulations, creating artificial scarcity premiums that separate DEA-scheduled inventory from non-controlled alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by formulation complexity, with osmotic pump technology commanding brand premiums over immediate-release tablets. Cost compression in the generic atomoxetine tier is intensifying because CDSCO approvals from Indian manufacturers expand supply, while academic medical centers exhibit the lowest price sensitivity due to formulary inertia.
Supply Chain Analysis
Active pharmaceutical ingredient synthesis for norepinephrine reuptake inhibitors concentrates in Maharashtra and Gujarat, India, with formulation finishing in Research Triangle Park, North Carolina and the Frankfurt-Rhine-Main corridor. The supply chain draws from specialized chemical precursors including chiral amine intermediates and osmotic pump membrane polymers, with single-source vulnerability concentrated in juvenile toxicology study capacity for European pediatric indication expansion. Distribution runs through hub-and-spoke specialty pharmacy networks that displace traditional wholesale channels for chronic maintenance therapy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA streamlined review pathways for psychiatric indications compress development timelines, transforming this market into a high-growth disruption where regulatory capital efficiency determines competitive survival.
For Market Incumbents: Fortify institutional formulary control through embedded specialty pharmacy partnerships that capture refill volume concentration beyond hospital discharge. Deepen backward integration into osmotic pump manufacturing capacity in the Research Triangle Park cluster to defend against supply disruption from DEA quota constraints. For New Entrants and Emerging Players: FDA breakthrough therapy designation fast-track opens prescriber access in academic medical center outpatient clinics where prior authorization frameworks favor novel mechanisms over generic substitution. Target transdermal delivery development for geriatric populations with dysphagia, leveraging adherence-focused differentiation to bypass oral formulation commoditization. For Investors and Strategic Acquirers: Capital is best deployed toward specialty-focused CNS developers with pediatric investigation plan commitments already filed under EMA centralized procedures. Watch for inflection signals in specialty pharmacy channel consolidation, as vertically integrated health plan capture of chronic psychiatric maintenance determines margin concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Investigation Plan Filing | EMA centralized procedure mandates adolescent trials before adult approval, altering capital allocation timing. |
| Specialty Pharmacy Partnership | Hub-and-spoke distribution embeds adherence counseling that hospital discharge programs cannot replicate. |
| Transdermal Delivery Development | Patch-based administration targets geriatric dysphagia patients with circadian-aligned release kinetics. |
| DEA Quota Positioning | Manufacturing allocation agreements secure production volume for controlled substance formulations. |
| IRB Efficiency Investment | Streamlined institutional review board processes accelerate adolescent indication expansion timelines. |
Study Parameters
Desk research of FDA approval databases, EMA centralized assessment reports, and ClinicalTrials.gov registries preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors at academic medical centers, and specialty pharmacy procurement managers. Secondary validation drew from SEC 10-K filings of CNS-focused pharmaceutical conglomerates, CMS Medicare Part D utilization data, and DEA manufacturing quota publications. Bottom-up prescription volume modeling triangulated against top-down market sizing from reimbursement framework analysis.
Variance decomposition across the projection horizon isolates volume drivers by administration route, patient population, and regional regulatory cluster. The analytical framework segments by product type, end user setting, distribution channel, and geographic market, with CAGRs derived from prescriber adoption curve modeling and patent expiration erosion schedules. Forecast inputs incorporate DEA scheduling trajectory assumptions and EMA pediatric investigation plan completion timelines.
Decision-makers should treat outputs as directional under stable DEA quota allocation and unaltered FDA review pathway velocity; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as cardiovascular safety surveillance requirements and generic substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Aminoglycosides Market
Pharmaceuticals
Monkeypox Vaccine and Treatment Market
Pharmaceuticals
Bendamustin Market
Pharmaceuticals
Posaconazole Market
Pharmaceuticals
Peptide Therapeutics Market
Pharmaceuticals
Global Histone Deacetylase Inhibitors Market
Pharmaceuticals
Myocardial Infarction Drugs Market
Pharmaceuticals
Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Europe Veterinary Pharmaceuticals Market
Pharmaceuticals
Global 3D Printed Drugs Market
Pharmaceuticals
Synthetic Drugs Market
Pharmaceuticals
Tinea Versicolor Treatment Market
Pharmaceuticals
Hard Empty HPMC Capsule Market
Pharmaceuticals
Rosuvastatin Market
Pharmaceuticals
Global Antipyretic Drugs for Children Market
Pharmaceuticals
Penicillin Market