
 Underfloor Heating Actuator Market | 2026-2036
Underfloor Heating Actuator Market Size, Share, and Industry Trends Forecast 2026-2036
Underfloor Heating Actuator Market Analysis
IP54-rated and higher actuator specifications is collapsing into the mainstream as building codes tighten across Europe. Robert Bosch GmbH leverages its automotive-grade manufacturing discipline to produce actuators with extended cycle life. Schneider Electric anchors its position through deep integration with building management software platforms. Siemens AG dominates specification sheets for large commercial installations through its certified installer networks.
An underfloor heating actuator is an electromechanical or thermostatic device that modulates fluid flow through manifold circuits in hydronic heating systems, typically operating at 24V AC or battery-powered wireless configurations with stroke lengths of 2.5–4.5 mm. Its primary purpose is to enable zoned temperature control that reduces energy consumption and improves thermal comfort in residential and commercial buildings. Electronic actuators and smart control types are capturing margin pools as digital thermostats replace legacy thermostatic heads. The retrofit installation segment sustains volume in mature European housing stocks where full system replacement remains uneconomical.
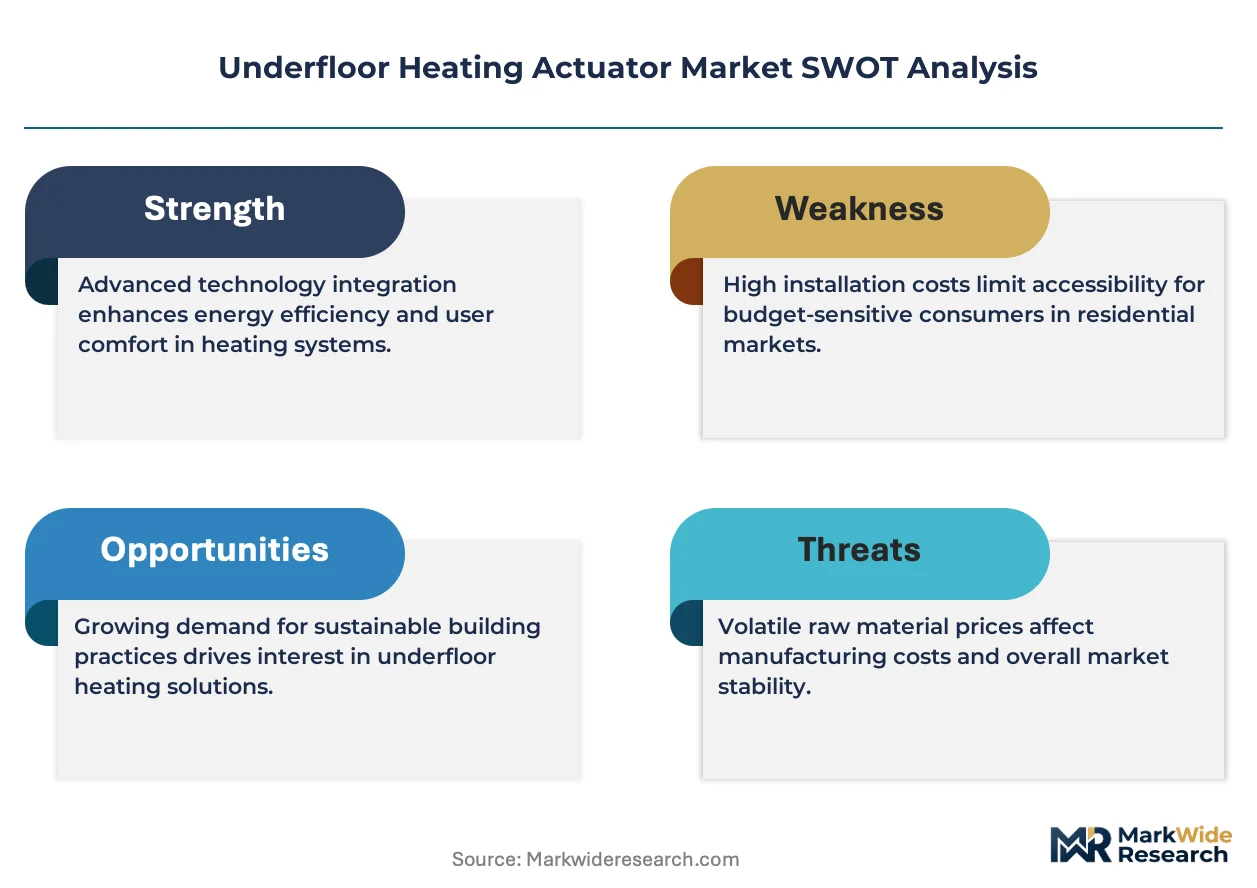
The EU Green Deal and F-Gas Regulation shape product roadmaps by mandating lower-carbon heating systems and refrigerant transitions that elevate demand for precise zone control. Ecodesign requirements and CE marking under the MDR framework enforce minimum efficiency thresholds that filter out uncertified imports. Stakeholders must monitor how the CSRD disclosure rules alter procurement criteria for commercial developers seeking Scope 3 emissions reductions from building operations.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing product development cycles as manufacturers race to certify actuators for low-carbon hydronic systems before efficiency mandates tighten further.
Growth Catalysts
- Retrofit incentives:France and the Netherlands have broadened subsidy programs for residential heating upgrades, channeling volume toward wireless actuator configurations that minimize installation disruption in existing buildings.
- REACH compliance:Restrictions on hazardous substances in electrical components are filtering out low-cost imports, consolidating demand around IP54-rated and higher specifications that satisfy Ecodesign requirements.
- Smart home integration:Residential developers across Germany are specifying actuators with native BACnet and Modbus protocols to enable centralized zone control through building management platforms.
Market Restraints
- Copper and brass input costs:Valve body materials face price volatility that compresses margins on standard-grade actuators, forcing tier-two suppliers toward plastic-composite alternatives with shorter cycle life.
- CE marking friction:The MDR framework's expanded technical documentation requirements extend certification timelines by four to six months for battery-powered wireless variants.
- Thermostatic head substitution:Basic wax-element thermostatic actuators retain share in price-sensitive Eastern European renovation markets where full electronic control remains uneconomical.
Strategic Opportunities
- CSRD disclosure alignment:Commercial developers seeking Scope 3 emissions reductions are elevating procurement criteria for actuators with embedded energy-monitoring capabilities that feed sustainability reporting.
- Heat pump convergence:Hybrid systems combining air-source heat pumps with underfloor distribution require actuators capable of managing wider temperature differentials, opening specification windows for high-stroke electronic variants.
- Installer channel digitization:Wholesale platforms serving certified heating engineers are adding actuator SKUs with QR-code commissioning guides, reducing field support burdens for manufacturers.
Industry Challenges
- Embedded firmware expertise:The shift toward battery-powered wireless actuators demands RF engineering and low-power design capabilities that legacy thermostatic manufacturers lack in-house.
- Legacy manifold compatibility:Retrofit installations require adapters for M30x1.5 and M28x1.5 valve interfaces, complicating inventory management for distributors serving mixed housing stocks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underfloor Heating Actuator Market |
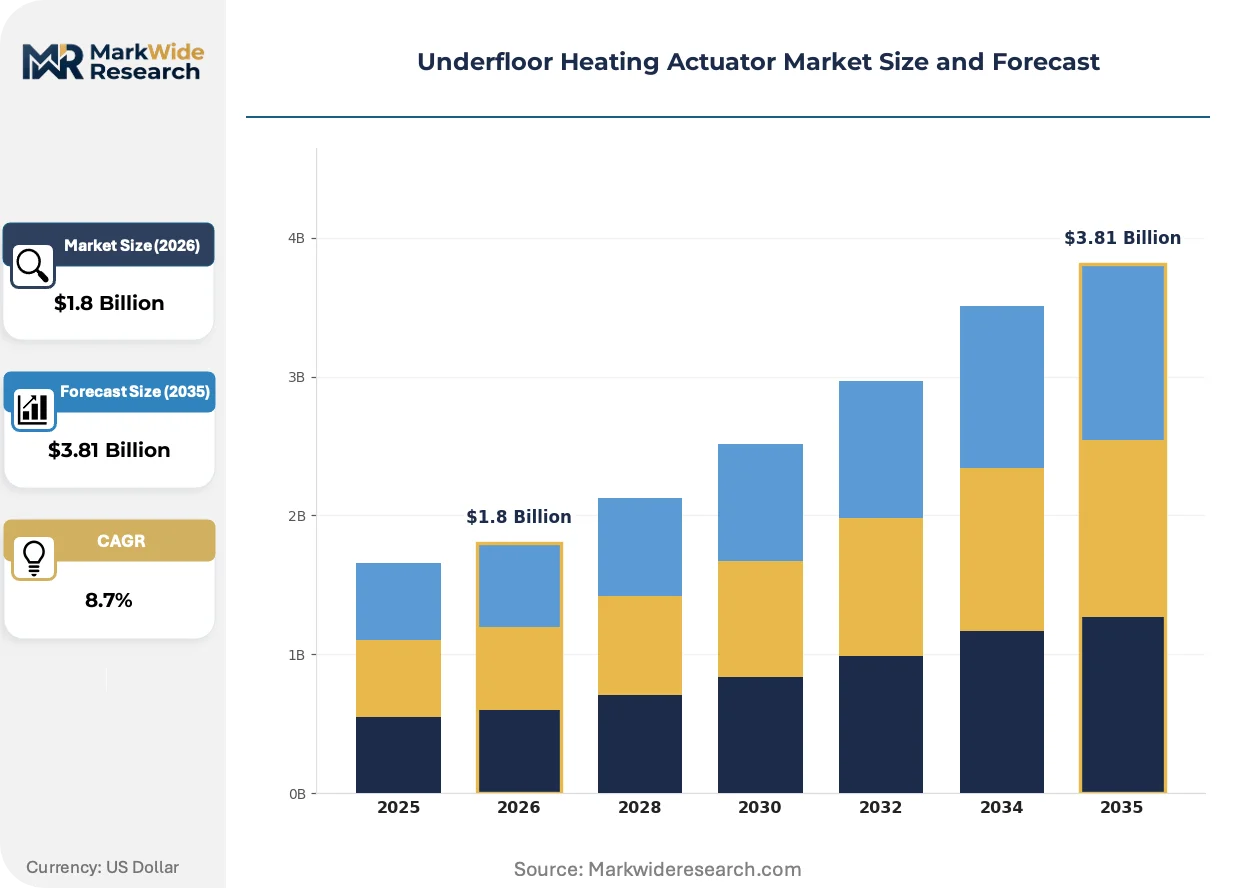
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermostatic Actuators, Electronic Actuators, Motorized Valves, Wired Actuators End User: Residential, Commercial, Industrial, Renovation Control Type: Manual, Automatic, Smart, Remote Installation Type: New Build, Retrofit, Underfloor, Surface Mounted |
| Companies Covered | Robert Bosch GmbH, Schneider Electric, Resideo Technologies Inc., Rehau Ltd, Mitsubishi Electric Corporation, nVent Electric, Siemens AG, Emerson Electric Co., Danfoss, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underfloor Heating Actuator Market Emerging Trajectories
Product architectures are diverging between premium electronic actuators with full BMS integration and stripped-down wireless units for cost-driven renovation segments. This split is reshaping R&D allocation and channel strategy simultaneously.
Electronic actuator technology is bifurcating between hardwired 24V AC units for new commercial construction and battery-powered Zigbee/Thread variants for residential retrofit. German residential developers favor hardwired configurations for reliability, while Dutch renovation specialists specify wireless to avoid concrete core drilling. The market is bifurcating into two margin tiers: integrated premium products with decade-long cycle life and disposable economy units for single-renovation cycles.
The F-Gas Regulation's refrigerant phase-down is accelerating heat pump deployment across Northern Europe, which in turn elevates demand for actuators rated to 70°C flow temperatures. Equipment manufacturers are redesigning valve seals and wax elements to accommodate higher thermal loads without stroke degradation. French commercial specifiers now require temperature certification documentation that exceeds baseline CE marking thresholds.
Specification authority is migrating from wholesale distributors toward certified installer networks that bundle actuator selection with commissioning services. Siemens AG and Schneider Electric have tightened direct relationships with mechanical contractors in Germany and Belgium, disintermediating traditional HVAC merchants. This channel compression concentrates volume with suppliers offering training academies and field support infrastructure.
Underfloor Heating Actuator Market Segmentation
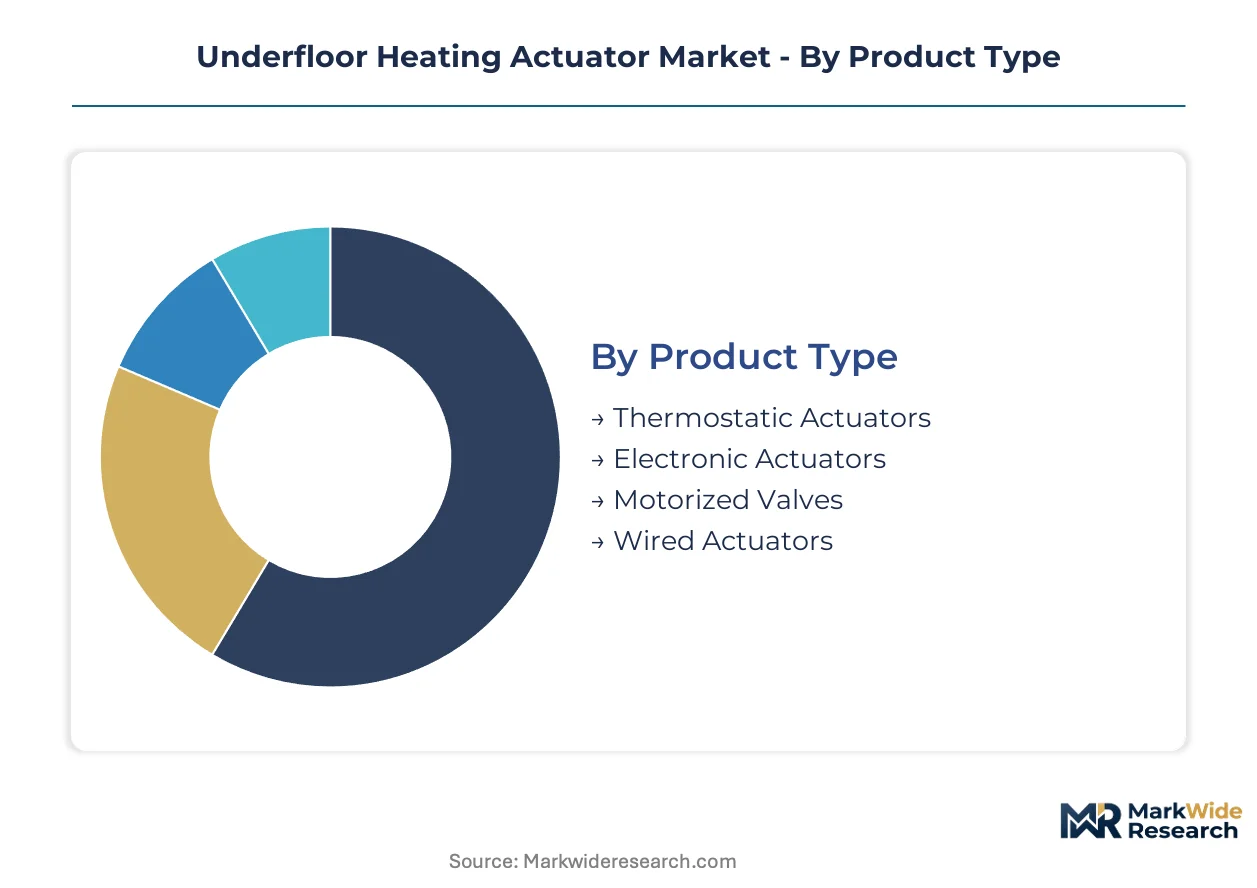
Segmentation in the underfloor heating actuator market reveals how regulatory pressure and installation economics split demand across technical specifications. Product architectures diverge sharply between premium electronic variants with embedded sensors and basic thermostatic heads serving price-sensitive renovation channels.
Product Type:
CE marking under the MDR framework and Ecodesign requirements enforce minimum efficiency thresholds that filter uncertified imports, concentrating procurement around IP54-rated specifications.
- Electronic Actuators:These devices incorporate position feedback sensors and low-power microcontrollers for precise flow modulation. German residential developers specify hardwired 24V AC configurations with native BACnet protocols for centralized zone control through building management platforms.
- Thermostatic Actuators:Wax-element mechanisms provide passive temperature-responsive valve operation without electrical infrastructure. Basic configurations retain share in Eastern European renovation markets where full electronic control remains uneconomical for single-renovation cycles.
- Motorized Valves:Electromechanical rotary actuators integrate directly with manifold assemblies for high-flow commercial applications.
- Wired Actuators:Hardwired power and signal connections deliver reliability for new construction where concealed cabling is feasible.
Electronic actuators handle the majority of throughput in new commercial construction; thermostatic variants are gaining share fastest in residential retrofit channels.
End User:
Customer procurement authority varies by project scale, with certified installer networks displacing wholesale distributors in large commercial specifications.
- Residential:Single-family and multi-unit housing drives volume for wireless battery-powered configurations that minimize installation disruption. Dutch renovation specialists favor Zigbee-enabled actuators to avoid concrete core drilling in existing floor slabs.
- Commercial:Office, hospitality, and healthcare facilities require actuators with embedded energy-monitoring capabilities that feed CSRD-aligned sustainability reporting for Scope 3 emissions reductions.
- Renovation:Retrofit installations in mature European housing stocks sustain demand for adapter-compatible actuators serving mixed M30x1.5 and M28x1.5 valve interfaces.
- Industrial:Warehouse and manufacturing applications specify high-stroke variants capable of managing wider temperature differentials in hybrid heat pump systems.
Residential channels generate the highest unit volumes; commercial specifications command the steepest expansion trajectory as ESG disclosure mandates tighten.
Control Type:
Integration depth with building management software platforms determines margin capture, with smart configurations commanding premium positioning over manual alternatives.
- Smart:Thread and Zigbee mesh networking enables cloud-connected zone control through digital thermostat ecosystems. French and Dutch retrofit incentives channel volume toward these configurations as building codes tighten.
- Automatic:Programmable schedules and occupancy sensors reduce energy consumption without full BMS integration.
- Remote:Mobile application interfaces provide off-site monitoring and adjustment capabilities for property management portfolios.
- Manual:Direct user adjustment serves backup and override functions in hybrid control architectures.
Smart control types dominate specification sheets for new German residential developments; automatic configurations expand most quickly in mid-market commercial retrofits.
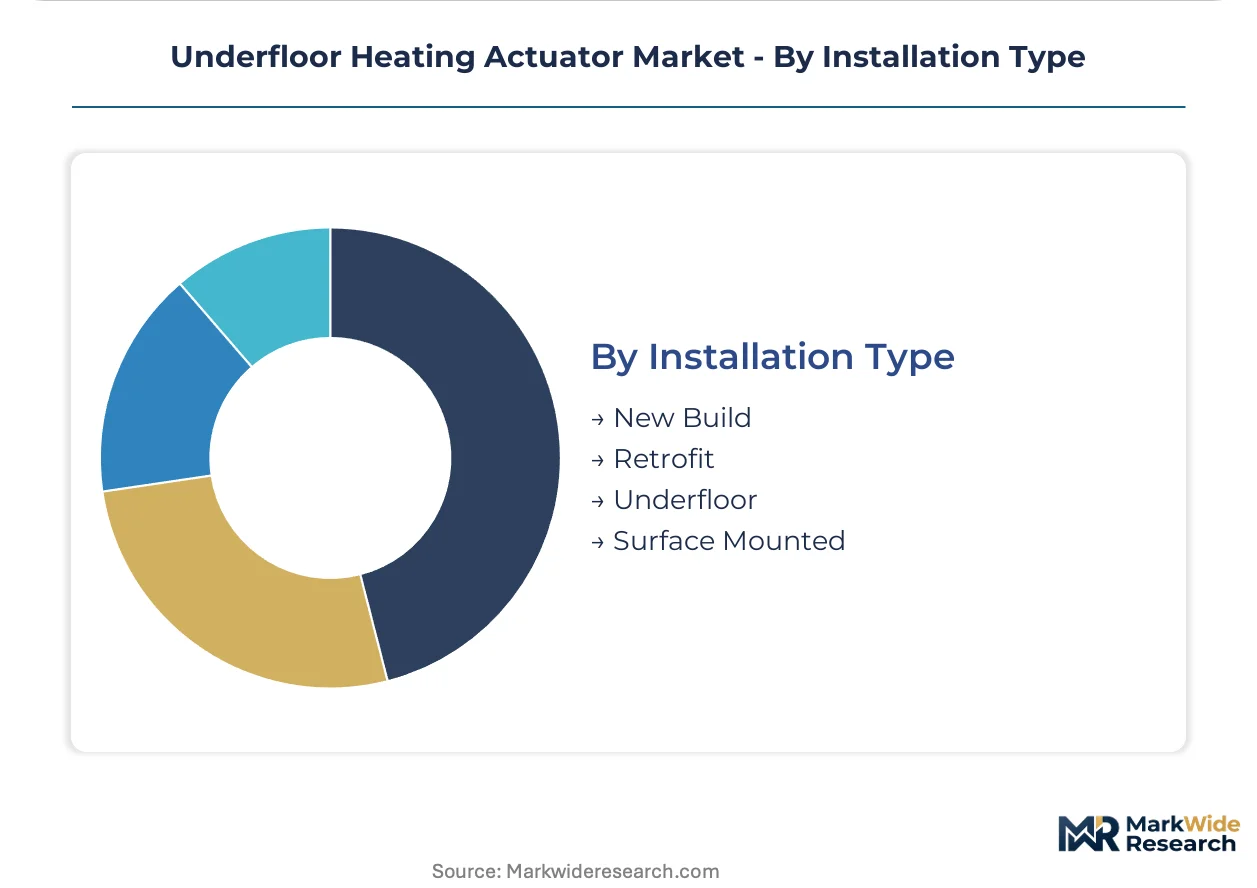
Installation Type:
Construction phase determines infrastructure constraints, with new builds accommodating hardwired systems and retrofits demanding wireless or surface-mounted solutions.
- New Build:Concealed installation during construction enables 24V AC hardwired actuators with decade-long cycle life. Belgian and German developers specify these configurations for reliability and minimal maintenance liability.
- Retrofit:Existing buildings require battery-powered wireless actuators or surface-mounted wiring routes that avoid structural modification. The F-Gas Regulation's heat pump acceleration elevates demand for temperature-rated variants in these applications.
- Underfloor:Embedded manifold locations demand compact actuator footprints and corrosion-resistant materials.
- Surface Mounted:Exposed installation prioritizes aesthetic housing designs and accessible maintenance access.
New build installations anchor volume in Northern European markets; retrofit configurations climb the fastest as France and Netherlands broaden subsidy programs for residential heating upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing clusters in Germany, France, and the Netherlands dominate European supply chains for underfloor heating actuators. These three countries generate the bulk of specification authority through their certified installer networks and building code enforcement regimes.
Germany
Residential developers in Bavaria and North Rhine-Westphalia are specifying hardwired 24V AC actuators with native BACnet protocols for smart home integration. The KBA and federal building efficiency standards under the EU Green Deal mandate IP54-rated minimum specifications for all new multi-unit construction. Stuttgart's industrial corridor hosts precision actuator assembly operations serving certified mechanical contractor networks across the DACH region.
France
Retrofit incentives through the MaPrimeRénov program are channeling volume toward wireless battery-powered configurations in the Île-de-France and Auvergne-Rhône-Alpes regions. ANSM and national building regulators now require temperature certification documentation exceeding baseline CE marking thresholds for commercial installations. Lyon has emerged as a distribution hub connecting Mediterranean renovation specialists with Northern European component suppliers.
Netherlands
Dutch renovation specialists favor Zigbee-enabled actuators to avoid concrete core drilling in Amsterdam and Rotterdam's dense housing stocks. The national subsidy framework for residential heating upgrades under the EU Green Deal prioritizes wireless configurations that minimize installation disruption. Eindhoven's technology corridor supports RF engineering capabilities for low-power wireless actuator development.
United Kingdom
Post-Brexit regulatory divergence is creating certification friction for battery-powered wireless variants entering British markets from EU manufacturing bases. The UK's Building Regulations Part L efficiency standards align closely with Ecodesign requirements but extend technical documentation timelines. London's commercial development pipeline specifies actuators with embedded energy-monitoring capabilities for sustainability reporting compliance.
Belgium
Brussels-based commercial developers are elevating procurement criteria for actuators feeding CSRD-aligned Scope 3 emissions reductions. Flemish and Walloon regional building codes enforce minimum efficiency thresholds that filter uncertified imports from Eastern European suppliers. Antwerp's port infrastructure serves as the primary entry point for valve body materials facing copper and brass price volatility.
Underfloor Heating Actuator Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the underfloor heating actuator market. The vendor base splits between diversified industrial conglomerates with building management software integration capabilities and specialized electromechanical component manufacturers serving price-sensitive renovation channels. Three strategic archetypes dominate: automotive-grade precision manufacturers leveraging transferable manufacturing discipline, building automation specialists anchoring specification authority through certified installer networks, and wireless connectivity specialists capturing retrofit volume through low-power RF engineering. Competitive moves concentrate on strategic partnerships with wholesale platforms and geographic expansion through training academy investments.
Among diversified industrial conglomerates, Robert Bosch GmbH, Schneider Electric, and Siemens AG exemplify contrasting approaches to specification capture. Bosch represents the automotive-grade precision archetype with transferable manufacturing discipline from adjacent mobility sectors. Schneider Electric occupies a position emphasizing building management software platform integration. Siemens AG anchors the certified installer network model, concentrating volume through direct mechanical contractor relationships that disintermediate traditional HVAC merchants.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Schneider Electric |
| Resideo Technologies Inc. |
| Rehau Ltd |
| Mitsubishi Electric Corporation |
| nVent Electric |
| Siemens AG |
| Emerson Electric Co. |
| Danfoss |
| Others |
Supply Flow & Price Mechanics
Plastic-composite valve body substitution for copper and brass is rerouting component sourcing from Antwerp's metal traders toward polymer compounders in Germany while compressing margins on standard-grade actuators and forcing tier-two suppliers into shorter-cycle-life positioning. This material transition simultaneously concentrates supply geography in Stuttgart's industrial corridor and fragments pricing power across certification tiers.
Pricing Analysis
EU Ecodesign requirements and CE marking under the MDR framework dictate the pricing tier structure by filtering uncertified imports and anchoring premium positioning to IP54-rated specifications and above. Pricing stratifies across certified electronic variants with embedded energy monitoring, standard hardwired 24V AC configurations, and economy thermostatic heads for Eastern European renovation channels. Cost compression in the economy tier is intensifying because REACH compliance restricts hazardous substances in electrical components. Residential retrofit buyers in France and the Netherlands exhibit highest price sensitivity, while German commercial developers purchasing through certified installer networks show lowest sensitivity to unit cost.
Supply Chain Analysis
Inventory management complexity for M30x1.5 and M28x1.5 valve interface adapters extends lead times for distributors serving mixed European housing stocks. Component manufacturing clusters in Germany, France, and the Netherlands dominate supply, drawing from copper and brass foundries in Belgium, polymer compounders in Germany, and RF engineering capabilities in Eindhoven. Single-source vulnerability sits with precision actuator assembly operations concentrated in Stuttgart's industrial corridor. Distribution runs through certified installer networks that bundle actuator selection with commissioning services, disintermediating traditional HVAC merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commissioning service contracts and firmware update subscriptions represent the fastest-expanding recurring-revenue layer in this market, outpacing hardware unit growth as CSRD disclosure rules elevate demand for embedded energy-monitoring capabilities that feed sustainability reporting.
For Market Incumbents: Secure specification authority by tightening direct relationships with mechanical contractors in Germany and Belgium through training academy investments that disintermediate wholesale distributors. Deepen backward integration into valve body manufacturing to offset copper and brass price volatility threatening margins on standard-grade actuators. Battery-powered wireless actuator development demands RF engineering capabilities that legacy thermostatic manufacturers lack in-house. For New Entrants and Emerging Players: Anchor in Dutch and French retrofit channels where subsidy programs for residential heating upgrades channel volume toward wireless configurations that minimize installation disruption. The Zigbee-enabled residential retrofit segment offers lowest barrier to entry given minimal certification documentation requirements compared to commercial specifications. Partner with wholesale platforms serving certified heating engineers to add actuator SKUs with QR-code commissioning guides that reduce field support burdens. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors automotive-grade precision manufacturers with transferable manufacturing discipline from adjacent mobility sectors. Long-term viability over the next decade hinges on embedded firmware expertise for battery-powered wireless variants and native BACnet protocol integration for building management software platforms. Watch for heat pump deployment acceleration across Northern Europe as the inflection indicator elevating demand for actuators rated to 70°C flow temperatures.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Installer Network Expansion | Siemens AG and Schneider Electric concentrate volume through direct mechanical contractor relationships that disintermediate traditional HVAC merchants. |
| Wireless RF Engineering Capability Buildout | Eindhoven's technology corridor supports low-power design capabilities that legacy thermostatic manufacturers lack for battery-powered actuator development. |
| Embedded Energy Monitoring Integration | Commercial developers seeking CSRD-aligned Scope 3 emissions reductions elevate procurement criteria for actuators feeding sustainability reporting. |
| Heat Pump Temperature Rating Certification | French commercial specifiers now require documentation exceeding baseline CE marking thresholds as the F-Gas Regulation accelerates heat pump deployment. |
| Valve Interface Adapter Standardization | Retrofit installations in mixed European housing stocks sustain demand for M30x1.5 and M28x1.5 compatible configurations complicating inventory management. |
Methodological Framework
Desk research of Ecodesign directive documentation, CE marking technical files under the MDR framework, and F-Gas Regulation implementation guidance preceded structured interviews with product managers at building automation specialists, procurement leads at German residential developers, and certified heating engineers in France and the Netherlands. Primary fieldwork with mechanical contractors and wholesale platform operators combined with secondary validation through customs trade data for valve body materials and SEC filings from diversified industrial conglomerates. Bottom-up unit economics triangulated against top-down market sizing across product type, control type, and installation type segmentation dimensions.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects in electronic versus thermostatic actuator categories. The analytical framework models product type, end user, control type, and installation type segmentation with specific attention to hardwired versus wireless power configurations and BACnet protocol integration depth. CAGRs were derived from installed base growth in Northern European housing stocks and replacement cycle analysis for existing manifold systems. Forecast inputs incorporate retrofit incentive program budgets in France and the Netherlands alongside heat pump deployment trajectories mandated by the EU Green Deal.
Material uncertainties — regulatory timeline shifts for CSRD disclosure enforcement, copper and brass commodity price volatility, and refrigerant transition pace under the F-Gas Regulation — sit outside the modeled envelope. Forecasts reflect assumptions about certified installer network expansion rates and wireless protocol standardization adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
United States Building Automation Controls Market
Building Automation Systems
US Commercial Building Automation Market
Building Automation Systems
Collapsible Gates Market
Building Automation Systems
Automated Daylight Harvesting Systems Market
Building Automation Systems
Platform Screen Door System Market
Building Automation Systems
Global Enterprise Building Solutions Market
Building Automation Systems
Elevator Modernization Market
Building Automation Systems
Building Automation System Market
Building Automation Systems
Building Automation and Control System Market
Building Automation Systems
Global Modularization Market
Building Automation Systems
Europe Building Automation Systems Market
Building Automation Systems
Zero Energy Buildings Market
Building Automation Systems
Global Solar Shading Systems Market
Building Automation Systems
LAMEA Building Automation System Market
Building Automation Systems
Traction Elevator Market
Building Automation Systems
Computer-Aided Facility Management (CAFM) Market