
 US Commercial Building Automation Market | 2026-2036
US Commercial Building Automation Market Size, Share, and Industry Trends Forecast 2026-2036
US Commercial Building Automation Market Insights
Energy Star certification tiering is unwinding legacy specification standards across the US commercial building automation sector. Johnson Controls International PLC leverages its vertical integration across HVAC and controls to anchor large-scale retrofit projects in major metropolitan districts. Honeywell International Inc competes through deep R&D intensity in wireless sensing architectures, while Schneider Electric SE specializes in open-protocol integration platforms that reduce vendor lock-in for facility managers.
US commercial building automation encompasses the networked hardware, software, and control systems that regulate environmental conditions, security, and energy consumption in non-residential structures, typically operating through BACnet or Modbus communication protocols with sensor response thresholds measured in sub-minute intervals. HVAC Control dominates product-type revenue due to the thermal load intensity of large commercial footprints and the maturity of variable refrigerant flow integration. IoT Solutions within technology segmentation represents the fastest-expanding category as edge computing architectures reduce latency for real-time occupancy-based adjustments. Energy Management applications command premium margin pools where utility demand-response programs create recurring software revenue streams.
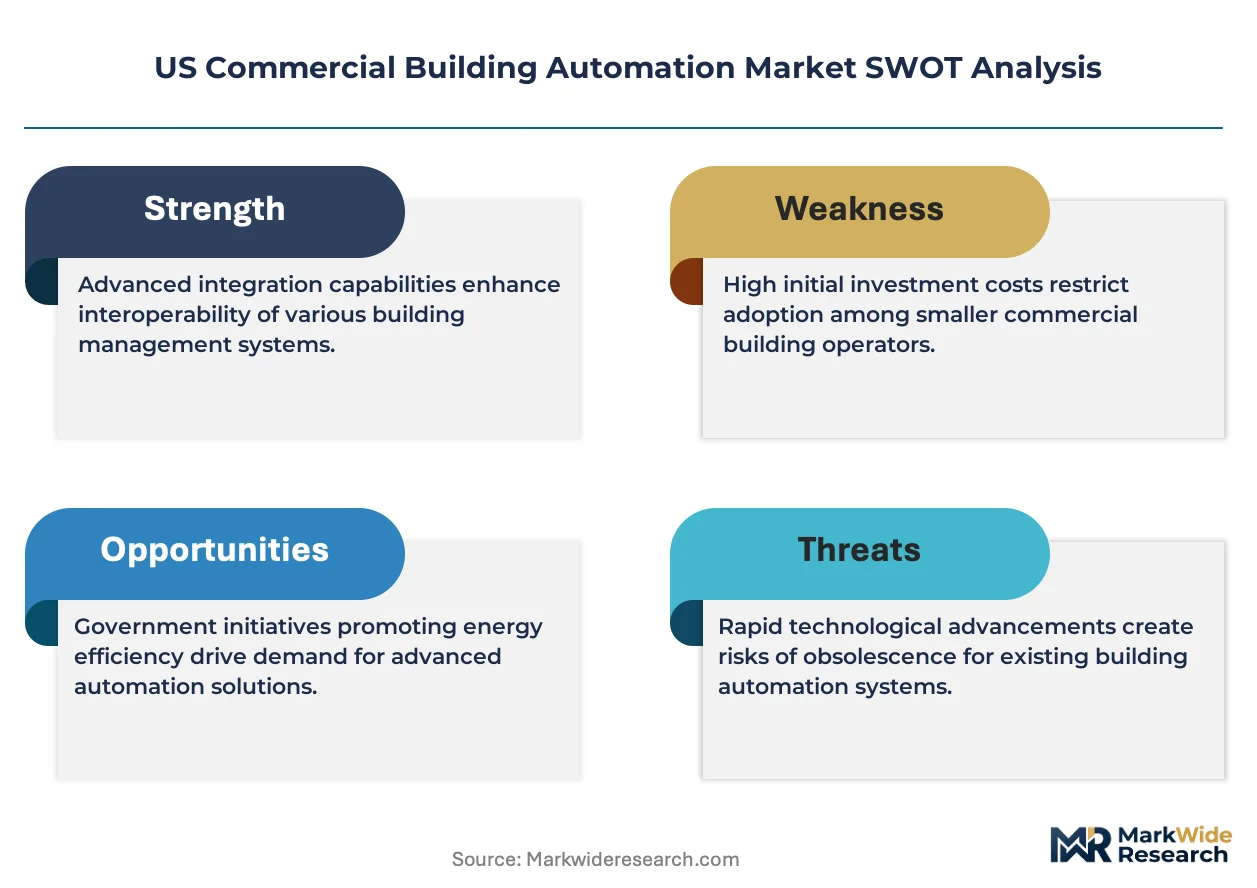
ASHRAE Standard 90.1, the EPA's Energy Star certification framework, and the Inflation Reduction Act collectively tighten efficiency baselines and subsidize upgrade cycles across US commercial stock. OSHA indoor air quality guidelines further accelerate sensor deployment density in high-occupancy buildings. Stakeholders must monitor state-level building code adoption timelines and utility rate structures to time capital deployment across fragmented municipal jurisdictions.
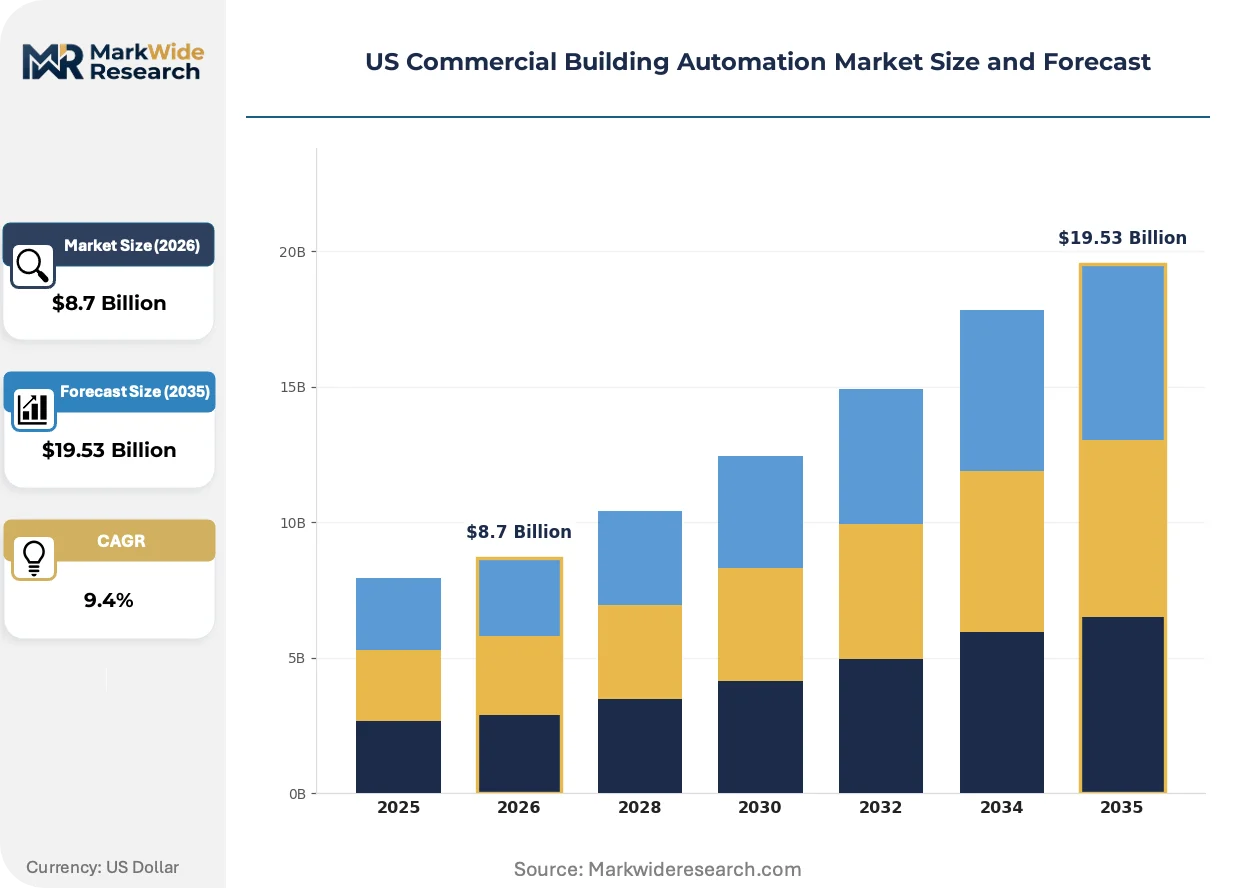
Market Dynamics
The Inflation Reduction Act's tax credit architecture is compressing payback periods for building automation retrofits, triggering a wave of system replacements across aging commercial stock that previously failed ROI thresholds.
Growth Catalysts
- Healthcare facility modernization:Hospital networks are mandating integrated environmental controls to meet Joint Commission standards for patient safety and infection control, driving bundled HVAC-security-lighting procurements.
- OSHA indoor air quality enforcement:Revised ventilation guidelines are forcing high-occupancy buildings to deploy denser sensor networks with real-time CO2 and particulate monitoring.
- Texas-California-New York corridor concentration:Commercial construction permitting in these three metro clusters accounts for disproportionate system demand, creating localized supply chain scale effects.
Market Restraints
- Semiconductor input volatility:Edge computing controllers and wireless sensors depend on specialized microcontrollers whose lead times remain extended, compressing system integrator margins.
- Protocol fragmentation:BACnet, Modbus, and proprietary vendor stacks create integration friction that extends commissioning timelines and elevates engineering costs for multi-vendor deployments.
- Skilled technician scarcity:Certified controls programmers and building systems engineers are concentrated in legacy markets, constraining deployment velocity in secondary metros.
Strategic Opportunities
- Energy-as-a-service models:Third-party ownership structures for building automation hardware are unlocking capital-constrained segments including municipal buildings and small commercial portfolios.
- Grid-interactive efficient buildings:FERC Order 2222 compliance pathways are creating software revenue streams through automated demand-response participation in wholesale power markets.
- Midwest secondary market penetration:Chicago, Detroit, and Minneapolis building stock lags coastal automation density, presenting first-mover advantages for retrofit specialists.
Industry Challenges
- Legacy system integration complexity:Pneumatic-to-digital control migrations require custom engineering that extends project timelines and elevates risk of performance shortfalls.
- Cybersecurity certification delays:UL 2900 and IEC 62443 compliance timelines for connected building systems are elongating product release cycles and elevating R&D overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Commercial Building Automation Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lighting Control, HVAC Control, Security Systems, Energy Management End User: Office Spaces, Retail Outlets, Educational Institutions, Healthcare Facilities Technology: Wireless Protocols, Wired Protocols, IoT Solutions, Cloud-Based Systems Application: Indoor Air Quality, Energy Efficiency, Lighting Optimization, Security Monitoring |
| Companies Covered | Johnson Controls International PLC, Honeywell International Inc, Schneider Electric SE, Siemens AG, ABB Ltd, Emerson Electric Co, Trane Inc, Carrier Global Corporation, Texas Instruments Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Commercial Building Automation Market Trends and Innovations
Edge-native processing architectures are displacing cloud-dependent control loops, enabling sub-second response times that unlock new application categories in dynamic load management.
Wireless sensor mesh networks are miniaturizing hardware footprints while extending battery life beyond ten years. Healthcare and laboratory facilities are adopting these devices fastest, replacing wired infrastructure that disrupted sterile environments. The technology is miniaturizing deployment costs, compressing the minimum viable project size and opening automation to sub-50,000-square-foot buildings previously excluded from system economics.
EPA Energy Star certification tiering is tightening baseline specifications for commercial HVAC controls, disqualifying legacy single-zone systems from federal procurement and incentive eligibility. Equipment manufacturers are responding with native multi-zone variable air volume integration as standard rather than upgrade. New construction in California and New York faces the steepest compliance ramps.
Facility managers are consolidating vendor relationships to reduce interoperability failure points, favoring single-source environmental platforms over best-of-breed component assembly. This preference shift is compressing the addressable market for standalone controls specialists and elevating bundled service contract values. The pattern is most pronounced in Class A office and life science real estate verticals.
US Commercial Building Automation Market Segmentation
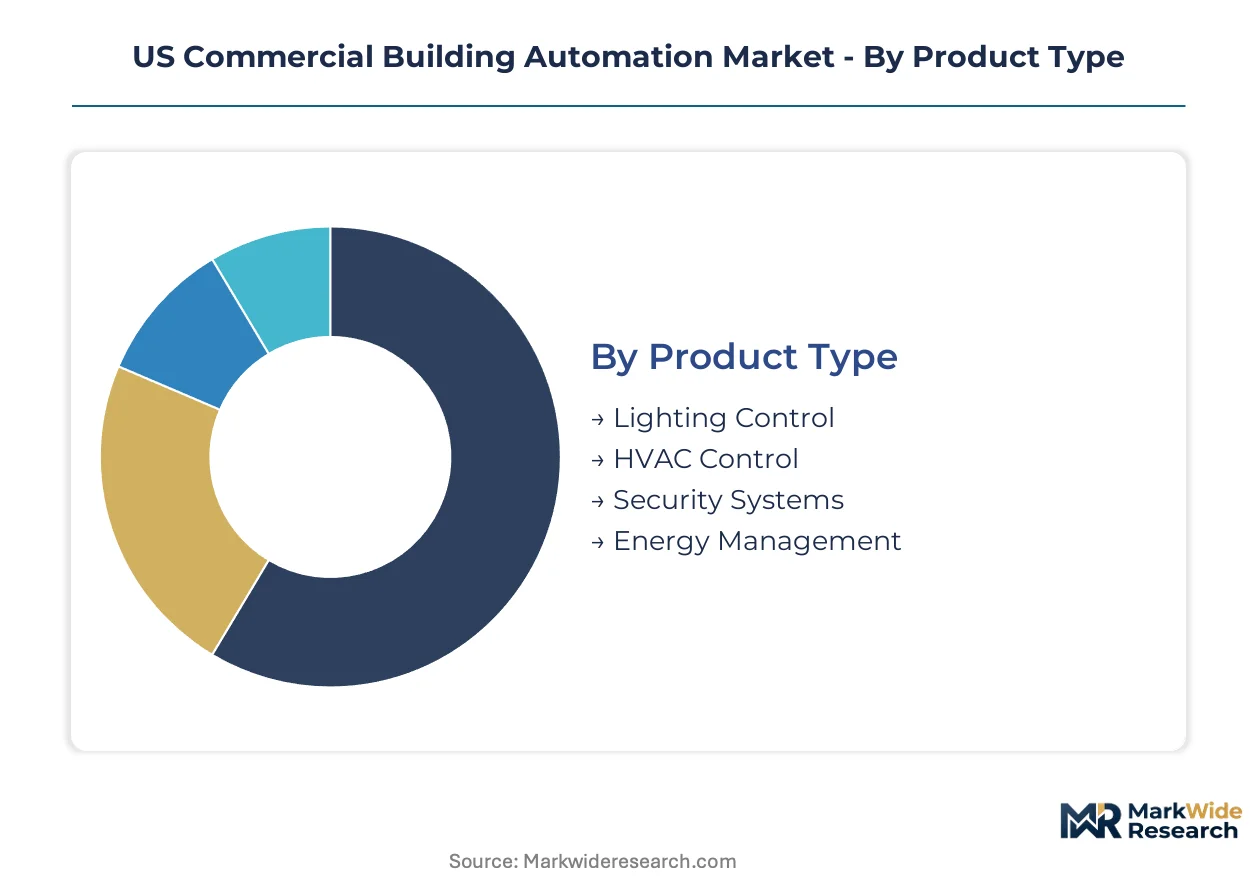
Segmentation in US commercial building automation reveals how technology maturity, regulatory pressure, and facility type reshape procurement patterns. Distinct margin profiles emerge across product categories and end-use verticals, with retrofit versus new construction dynamics creating divergent competitive arenas.
Product Type:
Premium margin pools concentrate in systems that integrate across multiple building functions rather than standalone point solutions.
- HVAC Control:Variable refrigerant flow systems and multi-zone variable air volume controllers dominate specification sheets for large commercial footprints. Demand clusters in Texas and California metro corridors where thermal load intensity and Title 24 energy codes drive replacement cycles.
- Energy Management:Software platforms with utility demand-response integration command recurring revenue streams through automated load curtailment contracts. Healthcare facilities and Class A office towers in New York prioritize these systems to capture FERC Order 2222 participation revenue.
- Lighting Control:Daylight harvesting and occupancy-based dimming systems reduce electrical load in high-density workspaces.
- Security Systems:Integrated access control and video analytics platforms serve life science and government facility verticals with stringent compliance requirements.
The dominant share belongs to HVAC Control, while Energy Management is closing the gap fastest.
End User:
Application complexity and regulatory scrutiny determine willingness to pay for integrated versus siloed automation architectures.
- Healthcare Facilities:Joint Commission standards for infection control and patient safety mandate integrated environmental monitoring with sub-minute sensor response thresholds. Hospital networks in California and Texas are bundling HVAC, security, and lighting procurements to reduce vendor failure points.
- Office Spaces:Class A commercial towers compete for tenant retention through wellness certifications and utility cost transparency. New York and Chicago landlords deploy dense sensor networks to meet WELL Building standards and differentiate lease rates.
- Educational Institutions:K-12 districts and university systems leverage EPA Energy Star certification pathways to access federal incentive funding for modernization.
- Retail Outlets:Franchise operators prioritize low-touch commissioning and standardized equipment packages across distributed footprints.
Healthcare Facilities command the highest per-square-foot automation spend, with Office Spaces expanding most quickly as return-to-office policies reshape tenant expectations.
Technology:
Deployment velocity hinges on the tradeoff between installation disruption and long-term interoperability flexibility.
- IoT Solutions:Edge-native processing architectures enable sub-second response times for dynamic load management without cloud dependency. Healthcare and laboratory facilities in California adopt wireless sensor meshes fastest, replacing wired infrastructure that disrupted sterile environments.
- Wireless Protocols:Battery-extended mesh networks miniaturize hardware footprints and compress minimum viable project sizes below 50,000 square feet.
- Cloud-Based Systems:Centralized analytics platforms serve multi-site operators seeking portfolio-level energy benchmarking and predictive maintenance.
- Wired Protocols:BACnet and Modbus hardwired installations persist in new construction where conduit access is cost-effective.
Wired Protocols retain installed base dominance, though IoT Solutions is gaining share fastest as battery life extension opens sub-50,000-square-foot buildings to automation economics.
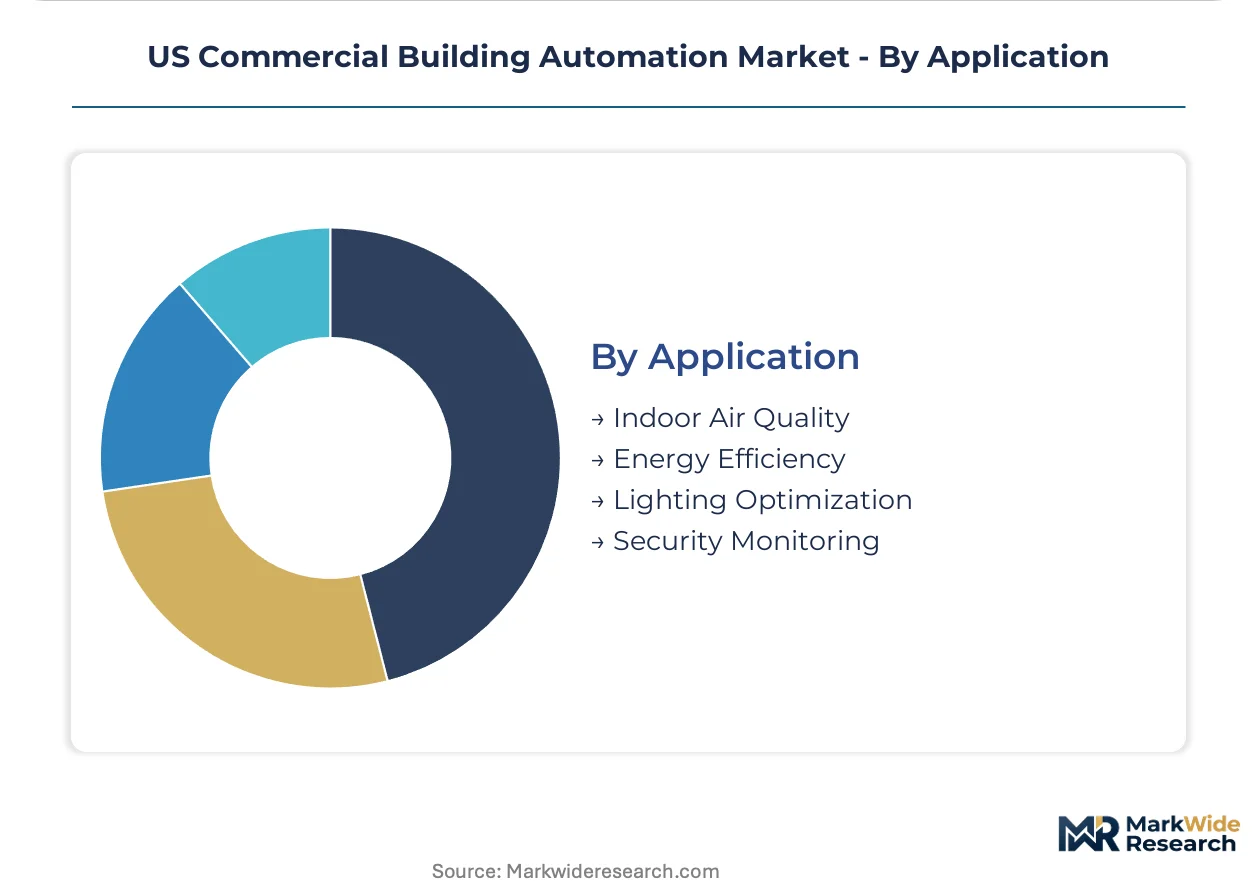
Application:
Regulatory enforcement timelines and utility rate structures determine which use cases justify capital deployment in fragmented municipal jurisdictions.
- Indoor Air Quality:OSHA revised ventilation guidelines force high-occupancy buildings to deploy denser CO2 and particulate sensor networks. New York and California school districts face accelerated compliance deadlines that compress procurement cycles.
- Energy Efficiency:Inflation Reduction Act tax credits compress payback periods for building automation retrofits across aging commercial stock.
- Security Monitoring:Integrated access and video analytics serve government and life science facilities with stringent credentialing requirements.
- Lighting Optimization:Daylight-responsive controls satisfy ASHRAE 90.1 baseline specifications in new construction.
Energy Efficiency captures the largest addressable retrofit opportunity, while Indoor Air Quality is climbing the fastest as OSHA enforcement tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
System integrators and controls manufacturers cluster along three metropolitan corridors where commercial construction permitting and retrofit incentive density create localized scale effects. Texas, California, and New York metro areas generate disproportionate demand concentration.
Texas Corridor
Dallas-Fort Worth and Houston thermal load intensity drives variable refrigerant flow system procurement for large commercial footprints. ERCOT grid volatility accelerates automated demand-response deployments. Austin's life science real estate expansion bundles integrated HVAC-security-lighting systems to meet stringent credentialing requirements.
California
Title 24 energy codes mandate multi-zone variable air volume integration as baseline specification. CARB emissions regulations compress payback periods for building electrification retrofits. San Francisco and Los Angeles Class A office towers deploy dense sensor networks to capture FERC Order 2222 participation revenue.
New York Metro
Local Law 97 carbon caps force building owners into accelerated automation upgrade cycles. NYSERDA incentive programs subsidize pneumatic-to-digital control migrations across aging Manhattan commercial stock. Brooklyn and Queens secondary market buildings present first-mover opportunities for wireless sensor mesh deployment.
Illinois
Chicago building automation density lags coastal markets, creating retrofit specialist entry points. ComEd utility rate structures favor automated load curtailment contracts for large commercial customers. The Loop and West Loop submarkets concentrate Class A office demand for wellness certification-driven sensor deployment.
Florida
Miami-Dade humidity control requirements sustain premium HVAC control specification intensity. FPL demand-response programs create recurring software revenue pools for energy management platforms. Orlando healthcare facility expansion mandates Joint Commission-compliant integrated environmental monitoring systems.
US Commercial Building Automation Market Competitive Landscape
Concentration sits with diversified industrial conglomerates that leverage captive HVAC equipment production to anchor bundled service contracts. Three distinct archetypes populate the competitive terrain: full-stack environmental platform providers, component specialists with deep protocol expertise, and software-native entrants attacking the energy management application layer. Consolidation pressure operates through vertical integration into upstream sensor manufacturing and strategic partnerships with utility demand-response aggregators.
Among the full-stack platform providers, Johnson Controls International PLC, Honeywell International Inc, and Schneider Electric SE exemplify divergent strategic positioning. Johnson Controls leverages backward integration across HVAC and controls to capture large-scale retrofit projects. Honeywell anchors wireless sensing architecture development through sustained R&D intensity. Schneider Electric occupies a position emphasizing open-protocol integration platforms that reduce vendor lock-in friction for facility managers.
| Leading Market Players |
|---|
| Johnson Controls International PLC |
| Honeywell International Inc |
| Schneider Electric SE |
| Siemens AG |
| ABB Ltd |
| Emerson Electric Co |
| Trane Inc |
| Carrier Global Corporation |
| Texas Instruments Incorporated |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Taiwanese microcontroller foundries shapes both component availability floors and system integrator margin structures across the US commercial building automation sector. Scale concentration in edge computing chip production transmits directly into pricing power for wireless sensor modules and BACnet controllers, compressing procurement flexibility for mid-tier automation vendors.
Pricing Analysis
EPA Energy Star certification dictates the pricing tier structure across HVAC control and energy management platforms. Three-tier pricing structure across premium, standard, and economy levels separates multi-zone variable air volume systems with native demand-response integration from single-zone pneumatic retrofits and bare-bones thermostat replacements. Cost compression in the economy tier is intensifying because semiconductor input volatility extends lead times for specialized microcontrollers. Small commercial portfolios and municipal buildings exhibit the highest price sensitivity, while healthcare networks and Class A office landlords prioritize certification compliance over upfront capital outlay.
Supply Chain Analysis
Strategic stockpiling of wireless communication chipsets and edge computing controllers dominates inventory strategy among tier-one system integrators serving the Texas-California-New York corridor. Manufacturing concentration rests on Taiwan for microcontroller fabrication, Mexico for enclosure and assembly operations, and domestic US facilities for final system integration and commissioning. Raw material dependencies include lithium for battery-extended sensor meshes, copper for BACnet wiring infrastructure, and rare earth elements for magnetic components in HVAC actuators. Single-source vulnerability in Taiwanese semiconductor foundries represents the dominant structural risk. Distribution runs through authorized controls distributors and direct OEM relationships with large facility management conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US commercial building automation market sits in a cyclical recovery phase driven by Inflation Reduction Act subsidy windows compressing retrofit payback periods. Federal tax credit eligibility resets and state-level building code adoption timelines create discrete demand pulses that favor prepared capital deployment.
For Market Incumbents: Consolidate backward integration into sensor manufacturing to capture margin pools currently flowing to Taiwanese semiconductor vendors. Lock in long-term supply agreements with Mexican assembly facilities before regional capacity tightens. The threat of software-native energy management entrants attacking the application layer demands defensive certification investment in UL 2900 and IEC 62443 cybersecurity compliance to elongate competitor product release cycles.
For New Entrants and Emerging Players: Lead with wireless sensor mesh architectures targeting the Midwest secondary market corridor where Chicago, Detroit, and Minneapolis building stock lags coastal automation density. The sub-50,000-square-foot commercial segment presents the most penetrable white space as battery life extension collapses minimum viable project thresholds. A channel partnership strategy with regional mechanical contractors bypasses incumbent direct sales forces concentrated in legacy metro markets.
For Investors and Strategic Acquirers: Open-protocol integration specialists with demonstrated BACnet and Modbus interoperability expertise command scarcity premiums in a market consolidating around bundled environmental platforms. Long-term viability over the projection horizon hinges on grid-interactive efficient building software capabilities aligned with FERC Order 2222 compliance pathways. Watch utility demand-response program enrollment velocity across Texas ERCOT territory as the primary inflection indicator for energy management platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Grid-Interactive Software Development | FERC Order 2222 participation revenue streams differentiate energy management platforms in wholesale power markets. |
| Cybersecurity Certification Investment | UL 2900 and IEC 62443 compliance timelines filter out undercapitalized competitors from connected building procurements. |
| Wireless Sensor Mesh Deployment | Battery-extended architectures open sub-50,000-square-foot buildings previously excluded from automation economics. |
| Energy-as-a-Service Model Launch | Third-party ownership structures unlock capital-constrained municipal and small commercial building segments. |
| Midwest Market Channel Expansion | Chicago and Detroit retrofit density gaps present first-mover advantages before coastal incumbents reallocate sales resources. |
Research Methodology
Cross-validation between primary interviews with facility managers, controls programmers, and utility demand-response aggregators anchors the qualitative findings against secondary validation from EPA Energy Star databases, FERC interconnection filings, and ASHRAE standard documentation. Bottom-up triangulation across product-type shipment data and top-down reconciliation against commercial construction permitting records in Texas, California, and New York metro corridors ensures dimensional consistency. Secondary sources include SEC 10-K disclosures from diversified industrial conglomerates, NREL building stock characterization studies, and OSHA indoor air quality enforcement timelines.
Sensitivity analysis around Inflation Reduction Act tax credit persistence and semiconductor lead time volatility stress-tests the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-use vertical, technology deployment architecture, and application use case, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derive from regression against historical retrofit penetration rates and new construction automation specification intensity, incorporating utility rate structure trajectories and state-level building code adoption schedules as forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained federal incentive funding and stable utility demand-response program structures would require recalibration. Forecasts reflect assumptions regarding OSHA enforcement timeline acceleration and Title 24 energy code stringency progression. Practitioners should keep alternative scenarios live as ERCOT grid volatility patterns and Taiwanese semiconductor capacity allocation priorities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Global Door Closers Market
Building Automation Systems
Global Platform Screen Doors for Subway Lines Market
Building Automation Systems
Zero Energy Buildings Market
Building Automation Systems
Global Nordic Building Automation and Control Market
Building Automation Systems
Automated Daylight Harvesting Systems Market
Building Automation Systems
Commercial Building Automation Systems Market
Building Automation Systems
Underfloor Heating Actuator Market
Building Automation Systems
Platform Screen Door System Market
Building Automation Systems
Integrated Building Management Systems Market
Building Automation Systems
Tunnel Automation Market
Building Automation Systems
Escalator Market
Building Automation Systems
Platform Lifts Market
Building Automation Systems
Signage Market
Building Automation Systems
Collapsible Gates Market
Building Automation Systems
Electrochromic Glass Market
Building Automation Systems
Building Management System Market