
 Traction Elevator Market | 2026-2036
Traction Elevator Market Size, Share, and Industry Trends Forecast 2026-2036
Traction Elevator Market Analysis
Buyer concentration across commercial real estate portfolios is rebalancing toward institutional property managers and multinational facility operators. Otis Elevator Company leverages its service network density to lock in long-term maintenance contracts. KONE Corporation anchors its position through machine room-less traction systems tailored for constrained shaft spaces. Schindler Group competes on digital integration, embedding predictive diagnostics into its elevator controllers.
A traction elevator uses steel ropes and a sheave driven by an electric motor to raise and lower a car within a hoistway, typically achieving speeds above 2.5 meters per second for mid-rise and high-rise structures. The primary purpose is safe vertical transportation of passengers and goods in buildings where hydraulic systems prove impractical due to height or energy constraints. Passenger elevators dominate value generation across new construction, while modernization of aging traction fleets in North American and European building stock represents a durable margin pool. Smart elevator technology, integrating destination dispatch and IoT monitoring, captures premium pricing from commercial landlords seeking operational efficiency.
Regulatory oversight spans the EU's Machinery Directive and CE marking requirements for elevator safety components, the U.S. ASME A17.1 code enforced by local authorities having jurisdiction, and China's GB 7588 standard administered by SAMR. These frameworks mandate brake redundancy, door protection systems, and energy consumption disclosure, directly shaping R&D priorities and market access conditions. Stakeholders must monitor evolving cybersecurity requirements for connected elevator systems as building codes begin addressing networked infrastructure risks.
Market Dynamics
The EU's Ecodesign framework is forcing wholesale replacement of legacy traction drives, compressing upgrade cycles and redirecting capital flows from new construction toward modernization services.
Growth Catalysts
- Urban densification in high-rise residential:Vertical construction in Mumbai, Shanghai, and São Paulo generates sustained demand for high-speed traction systems exceeding 2.5 meters per second.
- Machine room-less technology:Permanent magnet synchronous motors eliminate overhead machinery requirements, opening retrofit opportunities in constrained shaft spaces across aging European building stock.
- China's GB 7588 enforcement:Stricter brake redundancy and door protection mandates under SAMR administration accelerate fleet replacement timelines.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings from Chinese export controls destabilize permanent magnet motor production economics.
- Supply concentration in controller electronics:Specialized variable frequency drive components concentrate among German and Japanese semiconductor fabricators, creating single-source vulnerability.
- Technical ceiling on rope-free systems:Linear motor elevators remain confined to low-rise applications below 100 meters, blocking substitution in supertall structures.
Strategic Opportunities
- India's Smart Cities Mission:Transit-oriented development in Bangalore, Hyderabad, and Pune creates bundled elevator-escalator procurement for metro-adjacent commercial towers.
- Cybersecurity certification:Emerging IEC 62443 compliance requirements for connected elevator systems open premium service tiers for predictive maintenance platforms.
- Destination dispatch convergence:Integration with building access control and HVAC scheduling enables energy arbitrage in LEED-certified commercial portfolios.
Industry Challenges
- Field technician scarcity:Electromechanical apprenticeship programs in Germany, Japan, and the United States fail to match retirement rates among rope-splice specialists.
- Legacy controller obsolescence:Proprietary 1990s-era relay logic systems resist integration with IoT monitoring, forcing complete controller replacement rather than modular upgrade.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traction Elevator Market |
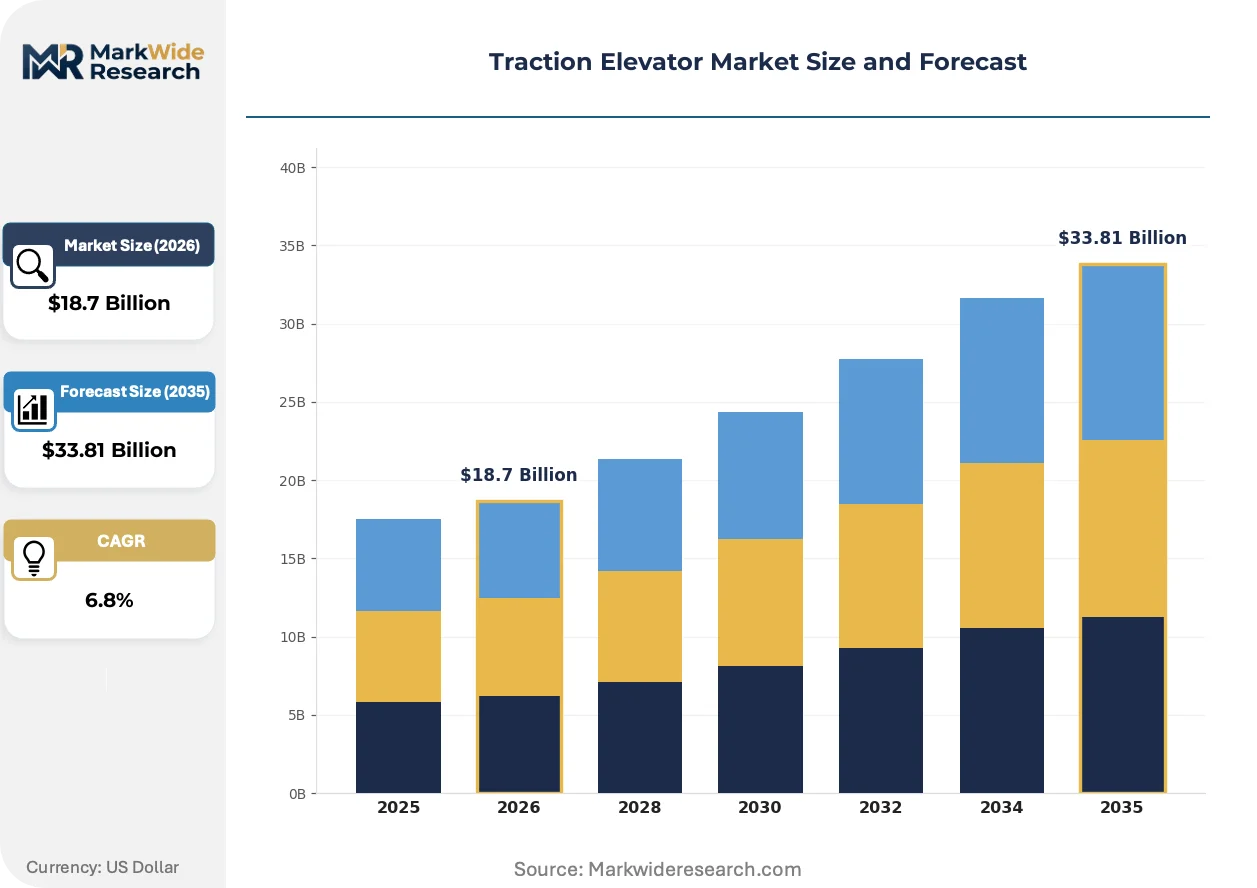
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Elevators, Freight Elevators, Service Elevators, Vehicle Elevators Technology: Hydraulic, Electric, Machine Room-Less, Smart Elevators End User: Residential Buildings, Commercial Spaces, Industrial Facilities, Hospitals Installation Type: New Installations, Modernizations, Upgrades, Maintenance |
| Companies Covered | Thyssenkrupp Elevator, Mitsubishi Electric, Otis Elevator Company, ESCON Elevators, Hitachi Ltd., KONE Corporation, Fujitec Co., Ltd., Delta Elevator, Schindler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traction Elevator Market Emerging Trajectories
Digitalization is penetrating every layer of traction elevator architecture, from motor control algorithms to predictive service platforms. Three developments are compressing competitive differentiation timelines.
Carbon-fiber reinforced polymer (CFRP) ropes are replacing traditional steel wire configurations in high-rise installations. Developers of supertall towers in Dubai and Kuala Lumpur specify CFRP for its superior strength-to-weight ratio and corrosion immunity. This material transition is converging with machine room-less designs to eliminate both overhead machinery and heavy counterweight assemblies.
The EU's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in machine room cooling systems. Traction elevator manufacturers must redesign thermal management for regenerative drives and permanent magnet motors. Commercial landlords in Frankfurt, Paris, and Milan face accelerated equipment refresh timelines to maintain lease certification compliance.
Facility managers now unbundle long-term maintenance from initial equipment procurement. Institutional property operators in Singapore and Sydney negotiate separate service contracts with specialized regional providers rather than accepting captive OEM agreements. This disintermediation compresses manufacturer service margins while elevating third-party certification requirements under ASME A17.1 and local authority enforcement.
Traction Elevator Market Segmentation
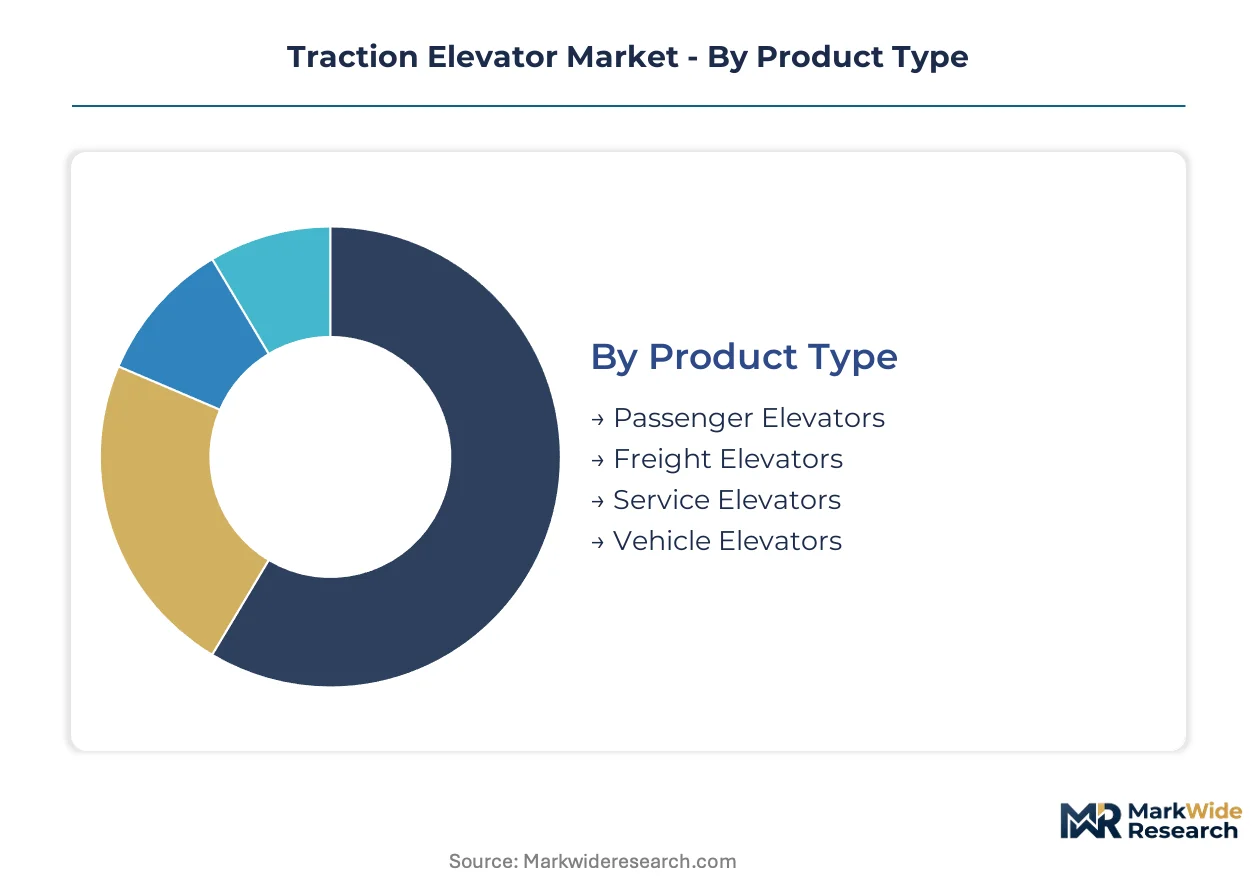
Traction elevator procurement follows distinct technical and economic logics across building types and life-cycle stages. Segment boundaries determine supplier specialization, margin structure, and service attachment rates.
Product Type:
Building height and traffic density dictate cabin specifications, door configurations, and drive system ratings.
- Passenger Elevators:Configured for 630-2,500 kilogram capacity with variable frequency drive control and destination dispatch options. Demand concentrates in Shanghai and Mumbai high-rise residential towers where developers specify speeds above 3.5 meters per second to minimize shaft count per floor plate.
- Freight Elevators:Reinforced platform designs with 3,000-10,000 kilogram load ratings and vertical bi-parting doors. Warehouse-to-office conversions in Frankfurt and Amsterdam drive specification of heavy-duty traction systems with precision leveling for pallet jack traffic.
- Service Elevators:Compact dumbwaiter-scale units through full-size cabin configurations for housekeeping and catering logistics. Boutique hotels in Paris and Milan specify integrated card-access control for back-of-house traffic separation.
- Vehicle Elevators:Specialized platform systems with 5,000-30,000 kilogram ratings for automobile transport between parking levels. Automated parking structures in Tokyo and Singapore require redundant brake systems under local fire safety codes.
Volume sits with passenger configurations; growth tilts toward freight systems in logistics-adjacent commercial redevelopment.
Technology:
Shaft constraints and energy accounting determine motor topology and control architecture selection.
- Electric:Geared and gearless traction drives with AC induction or permanent magnet synchronous motors. Aging building stock in Chicago and New York retains these systems for their proven service infrastructure and technician familiarity.
- Machine Room-Less:Permanent magnet motors mounted within the hoistway eliminate overhead machinery requirements. Retrofit demand in London and Berlin centers on constrained Victorian and interwar building cores where shaft expansion is structurally impossible.
- Hydraulic:Piston-driven systems for low-rise applications below 20 meters. Warehouse districts in São Paulo and Mexico City specify these for cost-sensitive installations where speed requirements remain modest.
- Smart Elevators:Destination dispatch, predictive maintenance, and building management system integration. Premium office towers in Sydney and Singapore mandate these for LEED certification and tenant experience differentiation.
Electric systems anchor current installed base; machine room-less configurations are expanding most quickly in European modernization programs.
End User:
Occupancy patterns and regulatory exposure shape reliability specifications and inspection protocols.
- Residential Buildings:Mid-rise and high-rise towers with 2-8 units per floor. Developer procurement in Bangalore and Hyderabad bundles elevator specification with facade and MEP packages under fixed-price contracts.
- Commercial Spaces:Office towers, retail complexes, and mixed-use developments with high peak-traffic requirements. Asset managers in Frankfurt and Amsterdam negotiate performance-based maintenance with uptime guarantees exceeding 99.5 percent.
- Industrial Facilities:Manufacturing plants and distribution centers with heavy-load and hazardous-environment specifications. Chemical processing sites in Ludwigshafen require explosion-proof controllers under ATEX directives.
- Hospitals:Bed elevators with 2,500 kilogram minimum capacity, horizontal sliding doors, and emergency power integration. NHS trusts in London specify these with antimicrobial cabin surfaces and stretcher accommodation.
Commercial installations generate highest service contract attachment; hospital specifications command steepest premium pricing.
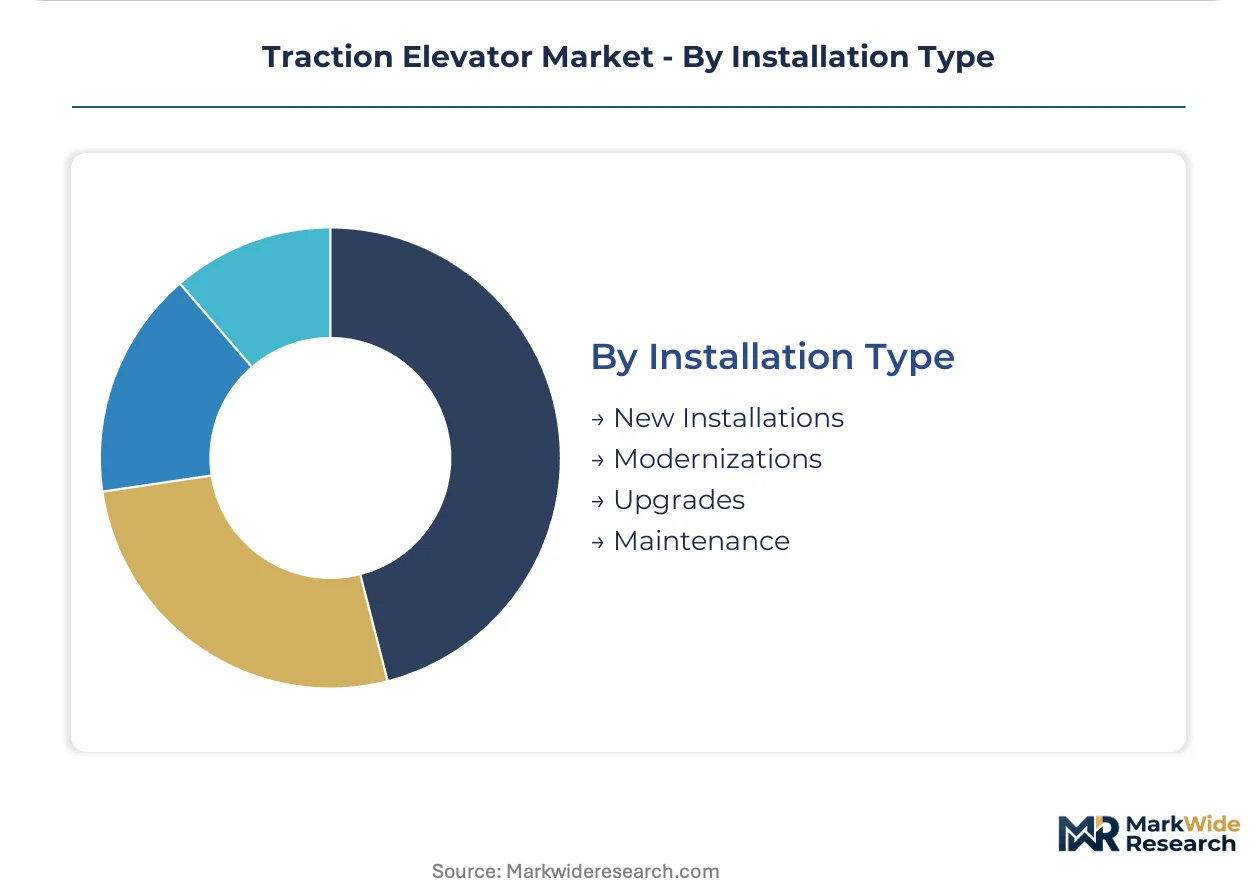
Installation Type:
Capital allocation shifts between new construction and existing building economics.
- New Installations:Greenfield specification integrated with structural and MEP design. Developer procurement in Dubai and Kuala Lumpur front-loads equipment decisions to secure construction financing.
- Modernizations:Complete drive, controller, and cabin replacement within existing shafts. European regulatory pressure under Ecodesign and F-Gas rules accelerates replacement timelines in Paris and Milan office portfolios.
- Upgrades:Partial component replacement—door operators, controllers, or safety systems—without full modernization. Budget-constrained building associations in Berlin favor these for phased capital deployment.
- Maintenance:Scheduled inspection, adjustment, and component replacement under long-term contracts. Institutional property operators in Singapore increasingly unbundle these from initial equipment procurement.
Modernization revenue is climbing the fastest in mature European and North American building stock; new installations concentrate in Asian urban expansion corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium deposits in China's Inner Mongolia anchor permanent magnet motor supply chains for traction elevator manufacturing worldwide.
China
Shanghai and Shenzhen high-rise residential towers drive specifications exceeding 3.5 meters per second. SAMR enforces GB 7588 brake redundancy mandates that accelerate fleet replacement timelines. The Yangtze River Delta cluster concentrates machine room-less production for export markets.
Germany
Frankfurt and Amsterdam warehouse-to-office conversions generate demand for heavy-duty freight systems. The F-Gas Regulation phases down hydrofluorocarbon refrigerants in machine room cooling. Bavarian engineering centers refine regenerative drive thermal management for EU Ecodesign compliance.
United States
Chicago and New York retain aging geared traction systems requiring controller modernization. ASME A17.1 code enforcement by local authorities mandates door protection upgrades. The Midwest corridor sustains technician apprenticeship programs for rope-splice specialization.
India
Bangalore and Hyderabad transit-oriented development creates bundled elevator-escalator procurement. The Smart Cities Mission channels infrastructure investment into metro-adjacent commercial towers. Maharashtra developer procurement bundles elevator specification with facade and MEP packages.
Japan
Tokyo automated parking structures require redundant brake systems under local fire safety codes. METI efficiency standards push regenerative drive adoption in commercial portfolios. The Kansai region maintains precision manufacturing for compact machine room-less configurations.
Traction Elevator Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue smart elevator integration and predictive maintenance platforms. The market structure consolidates around three strategic archetypes: diversified industrial conglomerates with captive elevator divisions, pure-play vertical transportation specialists, and regional fabricators serving modernization demand. Dominant competitive moves include geographic expansion through distribution partnerships and portfolio diversification into escalator and moving walk systems.
Among diversified industrial groups, Thyssenkrupp Elevator and Hitachi Ltd. exemplify conglomerate-backed scale advantages. Mitsubishi Electric and Fujitec Co., Ltd. represent Japanese precision-engineering heritage in high-speed traction applications. KONE Corporation and Schindler Group occupy positions as pure-play specialists with concentrated vertical transportation portfolios.
| Leading Market Players |
|---|
| Thyssenkrupp Elevator |
| Mitsubishi Electric |
| Otis Elevator Company |
| ESCON Elevators |
| Hitachi Ltd. |
| KONE Corporation |
| Fujitec Co., Ltd. |
| Delta Elevator |
| Schindler Group |
| Others |
Supply Flow & Price Mechanics
Rope-splice technician scarcity in Germany and Japan widens labor-cost differentials between premium OEM service contracts and third-party maintenance tiers, compressing margins on standard-grade modernization packages while sustaining premium pricing for factory-authorized programs.
Pricing Analysis
Volume concentrates in passenger elevator new installations where project-based bidding compresses equipment margins, while aftermarket service and modernization yield superior returns through long-term contract structures. Pricing stratifies across factory-authorized premium tiers, independent service provider standard tiers, and economy-grade component-replacement offerings, with differentiation driven by certification level under ASME A17.1 and GB 7588 plus geographic delivery cost to remote high-rise sites. Cost compression in the standard tier is intensifying because facility managers unbundle maintenance from initial procurement, forcing OEMs to compete on labor rates rather than captive service lock-in. Public housing authorities and budget-constrained building associations exhibit highest price sensitivity; supertall developers and hospital systems show lowest sensitivity due to uptime guarantee requirements and regulatory liability exposure.
Supply Chain Analysis
Refurbishment flows for legacy controllers and regenerative drive units create secondary component markets that buffer new-production lead times for modernization contractors. Permanent magnet motor production concentrates in China, Germany, and Japan, drawing from neodymium and dysprosium feedstocks anchored in Chinese Inner Mongolia processing facilities. Controller electronics hinge on specialized variable frequency drive components from German and Japanese semiconductor fabricators, creating single-source vulnerability for traction system OEMs. Distribution runs through authorized dealer networks for new installations and direct regional service branches for aftermarket maintenance, with third-party certifiers gaining share in European modernization markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Field technician retirement curves outpace apprenticeship completions, constraining service capacity and propping pricing power for firms with captive training pipelines.
For Market Incumbents: Cement market position by deepening backward integration into permanent magnet motor production and expanding machine room-less manufacturing footprint in the Yangtze River Delta. Defend against third-party service disintermediation through cybersecurity certification investments under emerging IEC 62443 frameworks that lock out non-authorized maintainers from predictive diagnostics platforms. For New Entrants and Emerging Players: Boutique hotel operators in secondary European cities represent an underserved buyer archetype seeking integrated card-access service elevators with antimicrobial cabin specifications. Penetrate this segment through destination dispatch convergence partnerships with building access control vendors, bypassing incumbent OEM sales channels that prioritize volume commercial towers over fragmented hospitality procurement. For Investors and Strategic Acquirers: Re-rating potential sits with regional fabricators possessing GB 7588 certification and established SAMR relationships given China's enforcement acceleration of brake redundancy mandates. Long-term viability favors targets with modernization service density in aging North American and European building stock. Monitor field technician apprenticeship graduation rates versus retirement curves as the inflection indicator for service margin compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | IEC 62443 compliance creates service tier differentiation and locks out unauthorized maintainers from predictive platforms. |
| Permanent Magnet Motor Backward Integration | Captive neodymium supply hedges Chinese export control volatility and stabilizes machine room-less production economics. |
| Regional Service Branch Expansion | Direct technician deployment in Bangalore and Hyderabad captures Smart Cities Mission bundled procurement opportunities. |
| Destination Dispatch Platform Partnership | Integration with HVAC scheduling and building access control enables energy arbitrage in LEED-certified commercial portfolios. |
| Controller Refurbishment Capability Buildout | Secondary component markets buffer new-production lead times and capture budget-constrained modernization demand. |
Methodological Framework
Multi-period observation of installation permit filings, service contract renewal rates, and neodymium price movements anchored the trend analysis, supplemented by interviews with elevator OEM product managers, facility management directors at institutional property operators, SAMR compliance officers, and rope-splice technician apprenticeship coordinators. Secondary validation drew from ASME A17.1 code revision dockets, EU Ecodesign implementing measures, Chinese customs trade data for permanent magnet exports, and SEC filings from listed vertical transportation groups. Bottom-up project pipeline assessment and top-down building stock aging analysis were triangulated against manufacturer order backlogs.
Segment-weighting approaches applied product type, technology architecture, end-user vertical, and installation life-cycle stage as dimensional anchors across the modeling period. CAGRs were derived from regression against urban densification indices, regulatory enforcement timelines, and rare earth magnet cost trajectories. Forecast inputs incorporated machine room-less adoption curves in European retrofit markets and destination dispatch penetration rates in premium commercial new construction.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese rare earth export policy shifts, field technician training pipeline failures, and cybersecurity standard evolution. Practitioners should monitor SAMR inspection enforcement intensity, F-Gas Regulation phase-down compliance deadlines, and third-party service certification adoption rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Building-To-Grid Technology Market
Building Automation Systems
Global HVAC Controls Market
Building Automation Systems
Architecture Smart Glass Market
Building Automation Systems
Platform Screen Door System Market
Building Automation Systems
Automated Daylight Harvesting Systems Market
Building Automation Systems
Energy Efficient Elevators Market
Building Automation Systems
China Revolving Doors Market
Building Automation Systems
Tunnel Automation Market
Building Automation Systems
Europe HVAC Controls Market
Building Automation Systems
Dumbwaiter Lifts Market
Building Automation Systems
Automated Infrastructure Management (AIM) Solutions Market
Building Automation Systems
Europe Building Automation Systems Market
Building Automation Systems
Smart Building Solutions Market
Building Automation Systems
Signage Market
Building Automation Systems
Electrochromic Glass Market
Building Automation Systems
Global Solar Shading Systems Market