
 Coil Thread Insert Market | 2026-2036
Coil Thread Insert Market Size, Share, and Industry Trends Forecast 2026-2036
Coil Thread Insert Market Outlook
Buyer concentration among aerospace OEMs and Tier-1 automotive suppliers is expanding, pulling procurement volumes toward long-term vendor-managed inventory contracts. Wilhelm Böllhoff GmbH & Co. KG leverages its dual-brand structure across Böllhoff Group operations to dominate European distribution channels for helical inserts. STANLEY Engineered Fastening anchors North American supply through captive aerospace certification programs. KATO Fastening Systems specializes in metric thread repair solutions for Japanese machinery exporters.
A coil thread insert is a helically coiled wire element installed into a tapped hole to create a wear-resistant, high-strength internal thread, typically manufactured from 304 stainless steel wire cold-formed into a diamond cross-section and then coiled to precise pitch dimensions. Its primary purpose is to restore stripped threads, distribute loads across a greater surface area, and protect soft parent materials such as aluminum or magnesium alloys in high-vibration environments. Helicoil-type inserts command the largest product share due to decades of aerospace specification lock-in, while stainless steel material grades capture the dominant margin pool because of corrosion-resistance premiums in marine and chemical processing applications. Electronics assembly represents the fastest-growing application segment as miniaturized devices require precision thread reinforcement in lightweight housings.
REACH in Europe restricts hexavalent chromium surface treatments, pushing suppliers toward passivated stainless steel finishes. The EPA enforces stricter volatile organic compound limits on thread-locking adhesive systems used during insert installation. FAA airworthiness directives mandate traceable lot documentation for all fasteners installed in commercial aircraft structures. Stakeholders must monitor evolving material certification timelines across these regulatory frameworks to avoid supply disqualification.
Market Dynamics
Aerospace OEM fastener standardization programs are compressing supplier qualification timelines while simultaneously extending contract durations, concentrating procurement power among a shrinking pool of certified helical insert manufacturers.
Growth Catalysts
- FAA Airworthiness Directives:Mandates for traceable lot documentation in commercial aircraft structures are locking in premium-grade stainless steel insert demand across US-based MRO networks.
- Germany's Precision Manufacturing Corridor:Automotive and machinery clusters in Baden-Württemberg and Bavaria are sourcing high-volume stainless steel contracts, anchoring European volume concentration.
- Electronics Miniaturization:Precision thread reinforcement requirements in lightweight device housings are pulling helical inserts into consumer electronics assembly lines.
Market Restraints
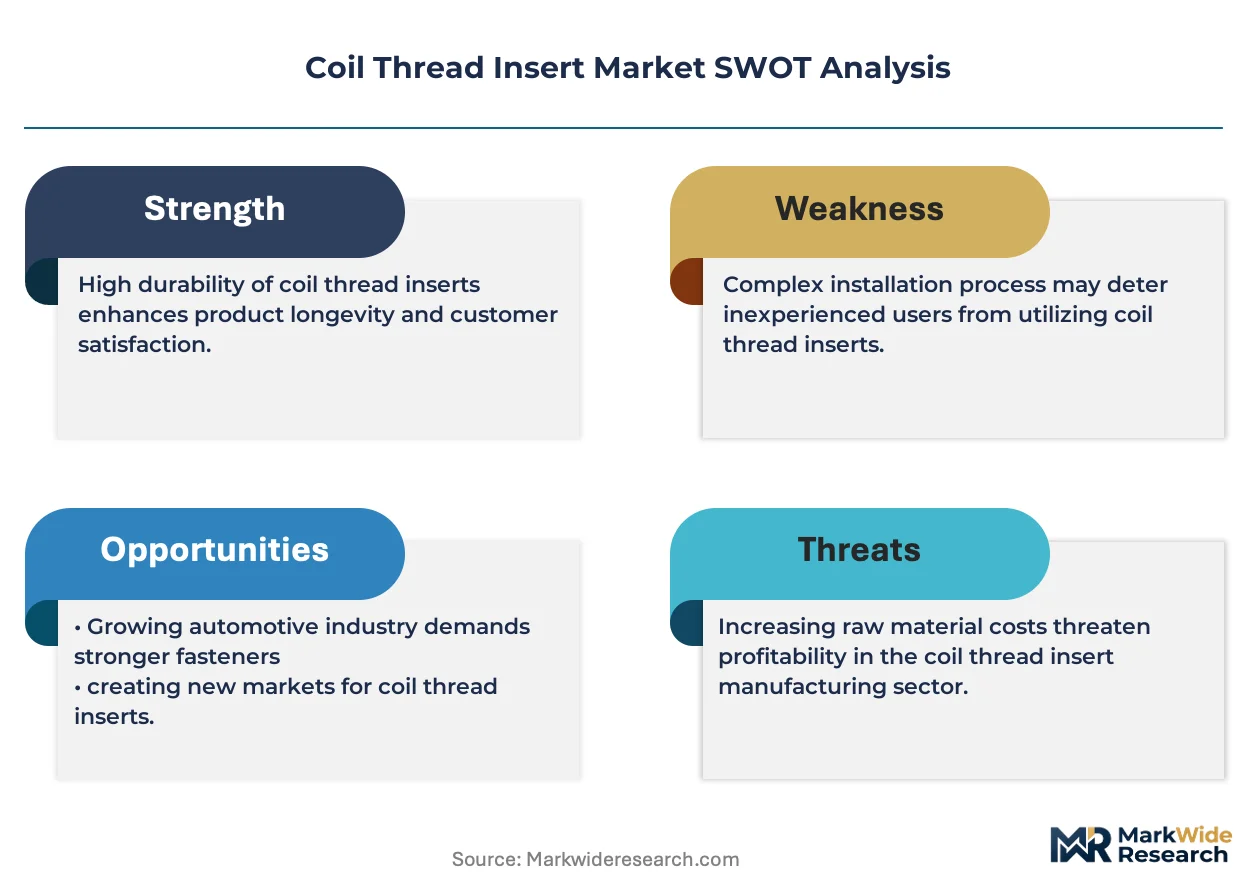
- REACH Compliance Costs:ECHA restrictions on hexavalent chromium surface treatments are forcing costly transitions to passivated stainless steel finishes, eroding margin pools for mid-tier suppliers.
- Raw Material Concentration:Cold-drawn 304 stainless steel wire supply concentrates among a handful of European and East Asian metallurgical producers, creating input price volatility exposure.
- Adhesive System Substitution:EPA volatile organic compound limits on thread-locking compounds used during insert installation are pushing some buyers toward mechanical locking alternatives.
Strategic Opportunities
- Japanese Machinery Exporters:Metric thread repair solutions remain underpenetrated among precision equipment OEMs shipping to Southeast Asian assembly markets.
- Marine Corrosion-Resistance Premiums:Duplex and super-duplex stainless grades command pricing power in offshore platform maintenance contracts subject to salt-spray specifications.
- Vendor-Managed Inventory Contracts:Long-term supply agreements with Tier-1 automotive suppliers are displacing spot purchasing in high-volume production environments.
Industry Challenges
- Lot Traceability Systems:FAA and EASA documentation requirements demand capital-intensive serialization infrastructure that smaller contract manufacturers struggle to fund.
- Cross-Border Certification Timelines:Divergent material approval schedules between EPA industrial emissions rules and REACH substance restrictions create supply disqualification risks for multi-jurisdictional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coil Thread Insert Market |
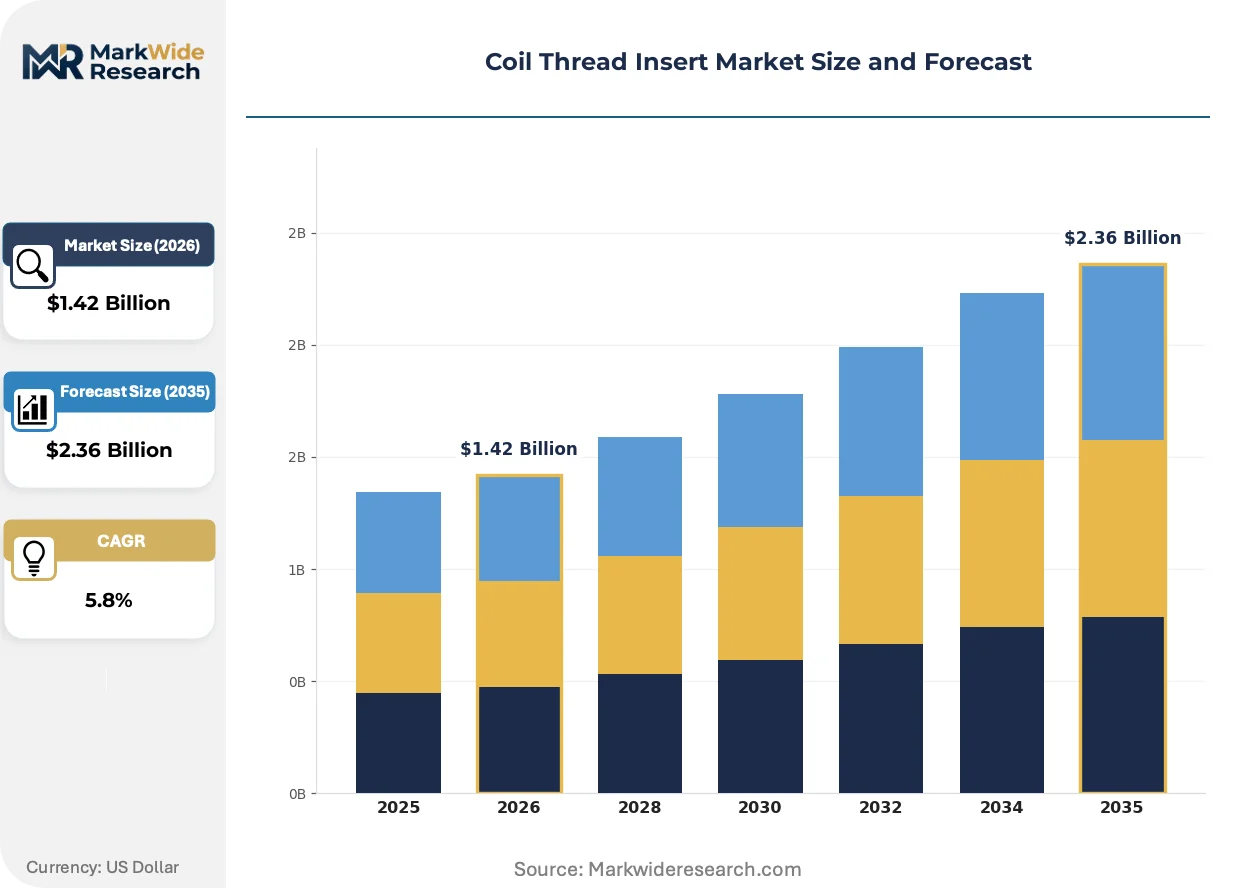
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helicoil, Recoil, Kato, Others Material: Stainless Steel, Carbon Steel, Brass, Aluminum Application: Aerospace, Automotive, Machinery, Electronics Size: Metric, Imperial, Custom, Standard |
| Companies Covered | Wilhelm Böllhoff GmbH & Co. KG, STANLEY Engineered Fastening, KATO Fastening Systems, Amecoil, Recoil, Tool Components (E-Z LOK), Helical Wire, Bossard Group, Böllhoff Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coil Thread Insert Market Strategic Shifts
Helical insert manufacturing is absorbing digital traceability requirements and advanced surface treatment protocols that were previously confined to aerospace tier-1 suppliers, compressing capability gaps across the supplier base.
Smart coating deposition systems are absorbing quality control functions previously handled by offline inspection stations. Aerospace fastener distributors in the US and Germany are adopting these platforms to reduce lot rejection rates. The technology is absorbing middle-tier quality assurance roles, forcing workforce retraining investments across European supply chains.
REACH substance restrictions are eliminating hexavalent chromium conversion coatings from European-sourced inserts. Suppliers are pivoting toward citric acid passivation and thin-film ceramic coatings to maintain corrosion-resistance ratings. Marine and chemical processing applications in Nordic markets are experiencing the most acute formulation transition pressures.
Buyer consolidation among aerospace OEMs is compressing supplier switching cycles from annual to multi-year frameworks. Vendor-managed inventory agreements now dominate procurement in Germany's automotive belt, displacing traditional purchase-order systems. This behavioral shift is most visible in precision manufacturing clusters where OEMs seek single-source accountability for threaded fastening systems.
Coil Thread Insert Market Segmentation
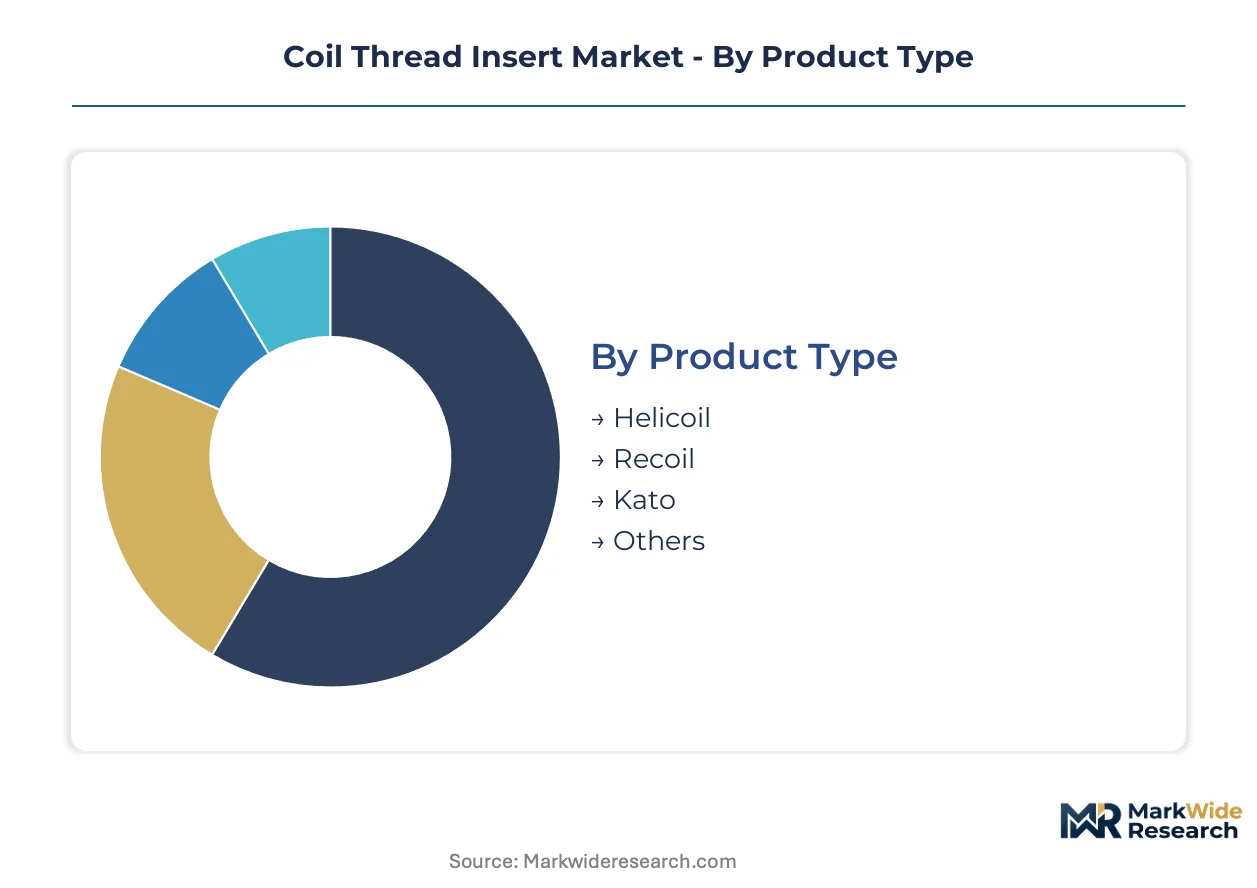
Coil thread insert segmentation reflects divergent capital requirements across manufacturing technologies, material metallurgy, and certification tiers. Aerospace-grade helical inserts demand precision coiling equipment and lot-traceability infrastructure that commodity thread repair kits do not require.
Product Type:
Capital intensity escalates with aerospace specification lock-in and precision coiling tolerances.
- Helicoil:Diamond-cross-section wire cold-formed into helical geometry with precise pitch control. Aerospace OEMs in Germany's Baden-Württemberg corridor source these under long-term vendor-managed inventory contracts for airframe assembly.
- Recoil:Tangless helical design eliminating break-off tangs during installation. Automotive Tier-1 suppliers in Bavaria favor these for engine block thread repair where debris exclusion is critical.
- Kato:Metric-dominant tangless inserts serving Japanese machinery exporters shipping precision equipment to Southeast Asian assembly markets.
- Others:Specialty profiles including locking coil variants and oversized repair inserts for damaged parent material restoration.
Helicoil absorbs the bulk of installed capacity; Electronics assembly applications are expanding most quickly.
Material:
Raw material sourcing concentration determines margin volatility and certification pathway costs.
- Stainless Steel:Cold-drawn 304 wire dominates aerospace and marine applications. REACH restrictions on hexavalent chromium push suppliers toward citric acid passivation for European chemical processing contracts.
- Carbon Steel:Lower-cost substrate for general machinery maintenance where corrosion exposure is limited. Spot purchasing patterns persist in this tier.
- Brass:Non-sparking properties suit oilfield and explosive atmosphere installations. Niche demand concentrates in North Sea platform maintenance.
- Aluminum:Lightweight inserts for electronics housings where galvanic compatibility with parent material is essential.
Stainless steel commands the dominant margin pool; Aluminum is climbing the fastest on miniaturization trends.
Application:
End-use certification requirements stratify supplier capability and contract duration.
- Aerospace:FAA airworthiness directives mandate traceable lot documentation for all commercial aircraft installations. US-based MRO networks lock in premium-grade stainless steel demand through serialized inventory systems.
- Automotive:Germany's precision manufacturing corridor sources high-volume stainless contracts for powertrain and chassis assembly. Vendor-managed inventory agreements displace spot purchasing.
- Machinery:Metric thread repair demand from Japanese OEMs remains underpenetrated in Southeast Asian service markets.
- Electronics:Miniaturized device housings require precision thread reinforcement in magnesium and aluminum alloys. Consumer electronics assembly lines are pulling helical inserts into new volume tiers.
Aerospace anchors premium pricing; Electronics is gaining share fastest on lightweight housing demand.
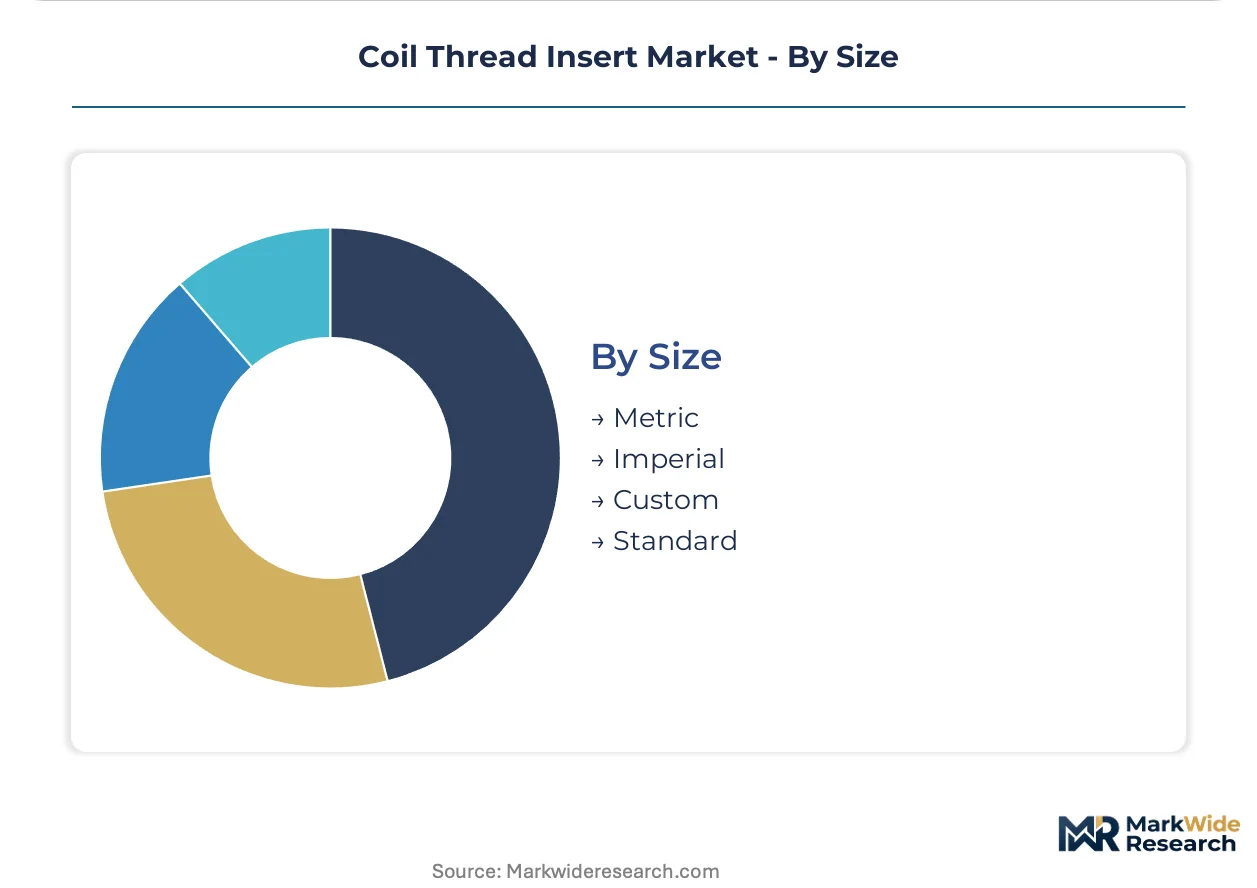
Size:
Dimensional standardization affects tooling amortization and regional manufacturing footprint.
- Metric:ISO-standard threads dominate European and Asian machinery OEM specifications. German automotive clusters standardize on M6 through M12 ranges for production efficiency.
- Imperial:UNF and UNC profiles retain aerospace specification lock-in across US-based OEMs and their Tier-1 supply bases.
- Custom:Non-standard pitches and lengths for legacy equipment maintenance and specialized tooling interfaces.
- Standard:Off-the-shelf dimensions for general industrial maintenance and aftermarket repair channels.
Metric specifications absorb the bulk of production volume; Custom sizes show steepest expansion trajectory on legacy fleet maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement volumes concentrate where aerospace OEMs and automotive Tier-1 suppliers enforce vendor-managed inventory frameworks. Germany's precision manufacturing corridor and US-based MRO networks lock in premium-grade stainless steel demand through serialized supply agreements.
United States
FAA airworthiness directives mandate traceable lot documentation for all commercial aircraft installations. EPA volatile organic compound limits on thread-locking adhesive systems push some buyers toward mechanical locking alternatives. US-based MRO networks anchor North American premium-grade stainless steel insert demand through serialized inventory systems.
Germany
Automotive and machinery clusters in Baden-Württemberg and Bavaria source high-volume stainless steel contracts under long-term supply agreements. ECHA REACH restrictions on hexavalent chromium surface treatments force costly transitions to passivated stainless steel finishes. The precision manufacturing corridor displaces spot purchasing with vendor-managed inventory frameworks across powertrain and chassis assembly.
Japan
Metric thread repair solutions serve precision equipment OEMs shipping to Southeast Asian assembly markets. METI industrial standards govern material certification pathways for threaded fastening systems. Machinery exporters in the Chubu and Kansai regions pull helical inserts into miniaturized device housing applications.
China
Domestic aerospace and electronics assembly expansion pulls precision thread reinforcement into new volume tiers. MIIT standards and GB certification requirements tighten material traceability for threaded insert suppliers. Yangtze River Delta manufacturing clusters absorb smart coating deposition systems to reduce lot rejection rates.
United Kingdom
Aerospace tier-1 supply bases retain UNF and UNC profile specifications for legacy airframe programs. The country's national aerospace regulator enforces documentation standards aligned with EASA frameworks. Midlands-based precision engineering clusters source helical inserts for defense and commercial aviation maintenance contracts.
Coil Thread Insert Market Competitive Environment
German producers anchor the premium-tier certification vector; Japanese specialists hold metric-standard dominance. The vendor base stratifies across three capability tiers: aerospace-certified manufacturers with lot-traceability infrastructure, automotive-volume suppliers under vendor-managed contracts, and maintenance-channel distributors serving spot-purchase aftermarket demand. Strategic moves concentrate on backward integration into cold-drawn wire supply and geographic expansion through distribution partnerships.
Among European-based fabricators, Wilhelm Böllhoff GmbH & Co. KG occupies a position exemplifying dual-brand distribution architecture, while STANLEY Engineered Fastening represents North American aerospace certification lock-in. KATO Fastening Systems sits within the metric-specialist tier serving Japanese machinery export markets. These three anchors illustrate how geographic origin and regulatory alignment shape competitive positioning across certification-intensive procurement channels.
| Leading Market Players |
|---|
| Wilhelm Böllhoff GmbH & Co. KG |
| STANLEY Engineered Fastening |
| KATO Fastening Systems |
| Amecoil |
| Recoil |
| Tool Components (E-Z LOK) |
| Helical Wire |
| Bossard Group |
| Böllhoff Group |
| Others |
Value Chain & Pricing Dynamics
REACH substance restrictions on hexavalent chromium surface treatments gate qualified supply for European aerospace and chemical processing contracts, simultaneously compressing mid-tier supplier margins and elevating premium-tier pricing power for passivated stainless steel finish capabilities.
Pricing Analysis
The volume-mass split separates high-volume automotive contracts from premium aerospace installations. Three-tier pricing structure across aerospace-certified, automotive-production, and maintenance-economy levels stratifies the market, with FAA lot-traceability requirements and REACH-compliant passivation driving price differentiation. Pricing pressure stems from raw material volatility in cold-drawn 304 stainless steel wire, squeezing mid-tier fabricators serving spot-purchase maintenance channels. Tier-1 automotive suppliers in Germany exhibit lowest price sensitivity due to vendor-managed inventory lock-in, while aftermarket distributors face acute cost compression.
Supply Chain Analysis
Domestic-content mandates in China's MIIT standards and US aerospace procurement guidelines are reshaping sourcing patterns for precision coiling equipment and certified wire feedstock. Manufacturing concentrates in Germany, Japan, and China, with cold-drawn 304 stainless steel wire, diamond-cross-section forming dies, and citric acid passivation chemistry as critical input dependencies. Single-source vulnerability runs through European metallurgical producers of aerospace-grade wire. Distribution feeds from captive aerospace certification programs in North America and dual-brand distribution architectures across European industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with backward integration into cold-drawn wire supply representing the decisive lever separating premium-tier certifiers from margin-compressed assemblers.
For Market Incumbents: Acquire captive cold-drawn wire production capacity to secure input cost stability against European metallurgical supply concentration. Expand lot-traceability serialization infrastructure to defend aerospace certification tiers from emerging Asian competitors with MIIT-compliant documentation systems. Lock in multi-year vendor-managed inventory contracts with Germany's automotive clusters before spot-purchase channels consolidate. For New Entrants and Emerging Players: EPA volatile organic compound limits on thread-locking adhesive systems open a window for mechanical-locking insert designs in US-based MRO networks. Target metric thread repair white space among Japanese machinery exporters shipping to underpenetrated Southeast Asian assembly markets. Lead with citric acid passivation capabilities to bypass REACH hexavalent chromium restrictions without legacy coating infrastructure. For Investors and Strategic Acquirers: Vendor-managed inventory contract signings with Baden-Württemberg automotive OEMs are the leading indicator that mid-tier European fabricators are securing revenue visibility for premium valuations. Prioritize acquisition targets with dual aerospace-automotive certification and existing cold-drawn wire supply relationships. Watch for MIIT standard harmonization with FAA documentation requirements as the signal for Chinese supplier competitive viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wire Supply | Captive 304 stainless steel feedstock secures margin control against European metallurgical oligopoly pricing. |
| Smart Coating Deposition System Deployment | Aerospace distributors in Germany and the US adopt these platforms to compress lot rejection rates. |
| REACH-Compliant Passivation Transition | Citric acid and thin-film ceramic coating capabilities unlock European chemical processing contract access. |
| Vendor-Managed Inventory Expansion | Long-term agreements with Bavarian Tier-1 suppliers displace spot purchasing in high-volume environments. |
| Metric Standard Specialization | Japanese machinery exporters in Chubu and Kansai regions pull specialized suppliers into Southeast Asian markets. |
Study Parameters
Multi-period observation of FAA airworthiness directive implementation timelines, REACH substance restriction phase-ins, and EPA volatile organic compound enforcement patterns anchored the trend analysis, supplemented by interviews with aerospace fastener procurement managers, automotive Tier-1 supply chain directors, helical insert manufacturing engineers, and European metallurgical wire sales executives. Secondary validation drew from ECHA substance restriction databases, FAA airworthiness directive filings, EPA emission standard registers, and customs trade data for cold-drawn stainless steel wire. Bottom-up capacity assessments across German precision manufacturing corridors triangulated against top-down demand modeling from aerospace OEM fastener standardization programs.
Input-output matrices mapped cold-drawn wire supply volumes through precision coiling capacity to end-use demand across aerospace, automotive, machinery, and electronics segments over the projection horizon. Segmentation dimensions included product type, material grade, application certification tier, and dimensional standard. CAGRs were derived from elasticity-adjusted demand curves incorporating electronics miniaturization penetration rates and REACH compliance cost pass-through assumptions. Industry-specific forecast inputs encompassed aerospace OEM vendor consolidation timelines and German automotive production cluster inventory turnover patterns.
The model assumes a particular technology adoption path for smart coating deposition systems; alternative pathways for ceramic thin-film surface treatment would alter the outlook for quality control infrastructure investment. Forecasts reflect documented assumptions regarding FAA-EASA documentation harmonization and MIIT standard evolution. Raw material price volatility in nickel-alloyed stainless grades and divergent cross-border certification timelines represent specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Global Scarifiers Market
Tools
Post Drivers Market
Tools
Core Shooter Machine Market
Tools
Mold Racks Market
Tools
Adjustable Gripping Hand Tools Market
Tools
Handheld Engraving Machine Market
Tools
Rotary Tools Market
Tools
Cordless Trim Routers Market
Tools
Tape Measure Market
Tools
Leather Cutting Machine Market
Tools
Theodolite Market
Tools
3D Milling Machines Market
Tools
Cutting Tools Market
Tools
CNC Leather Cutting Machine Market
Tools
Cutting Tool Inserts Market
Tools
Assembly Fastening Tool Market