
 United States Residential Heating Equipment Market | 2026-2036
United States Residential Heating Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
United States Residential Heating Equipment Market Analytics
Net-zero-minded homeowners is reorganizing demand away from conventional fossil-fuel systems toward electric and hybrid alternatives. Carrier Global Corporation leverages its broad distribution network and contractor training infrastructure to sustain retrofit market leadership. Lennox International Inc. anchors its position in the premium furnace segment through extensive dealer exclusivity programs. Rheem Manufacturing Company competes aggressively on price in the replacement cycle while building heat pump manufacturing capacity.
Residential heating equipment encompasses furnaces, boilers, heat pumps, and radiant heaters designed to maintain indoor thermal comfort in single-family and multifamily dwellings, typically rated by Annual Fuel Utilization Efficiency or Heating Seasonal Performance Factor metrics. These systems employ combustion, electric resistance, or vapor-compression refrigeration cycles to transfer thermal energy, with ducted forced-air and hydronic distribution dominating American housing stock. Heat pumps now claim the fastest expansion trajectory among product types, supported by utility electrification incentives and cold-climate compressor innovations that extend operational range below zero Fahrenheit. Natural gas retains volume leadership in existing housing but faces structural pressure as municipalities restrict new hookups and homeowners weigh total cost of ownership against electrification pathways. The fuel type dimension increasingly splits between legacy hydrocarbon infrastructure and grid-dependent electric systems, with propane and oil retreating to rural markets lacking pipeline access.
The EPA regulates residential appliance emissions through New Source Performance Standards, while the Department of Energy administers minimum efficiency mandates through its Appliance and Equipment Standards Program. State-level regulators in California, New York, and Washington enforce building electrification targets that directly constrain fossil-fuel heating in new construction. Stakeholders must track the trajectory of IRA-linked tax credits and rebate programs, as their renewal structure will determine whether heat pump economics sustain contractor conversion rates or revert to replacement-parity with conventional furnaces.
Market Dynamics
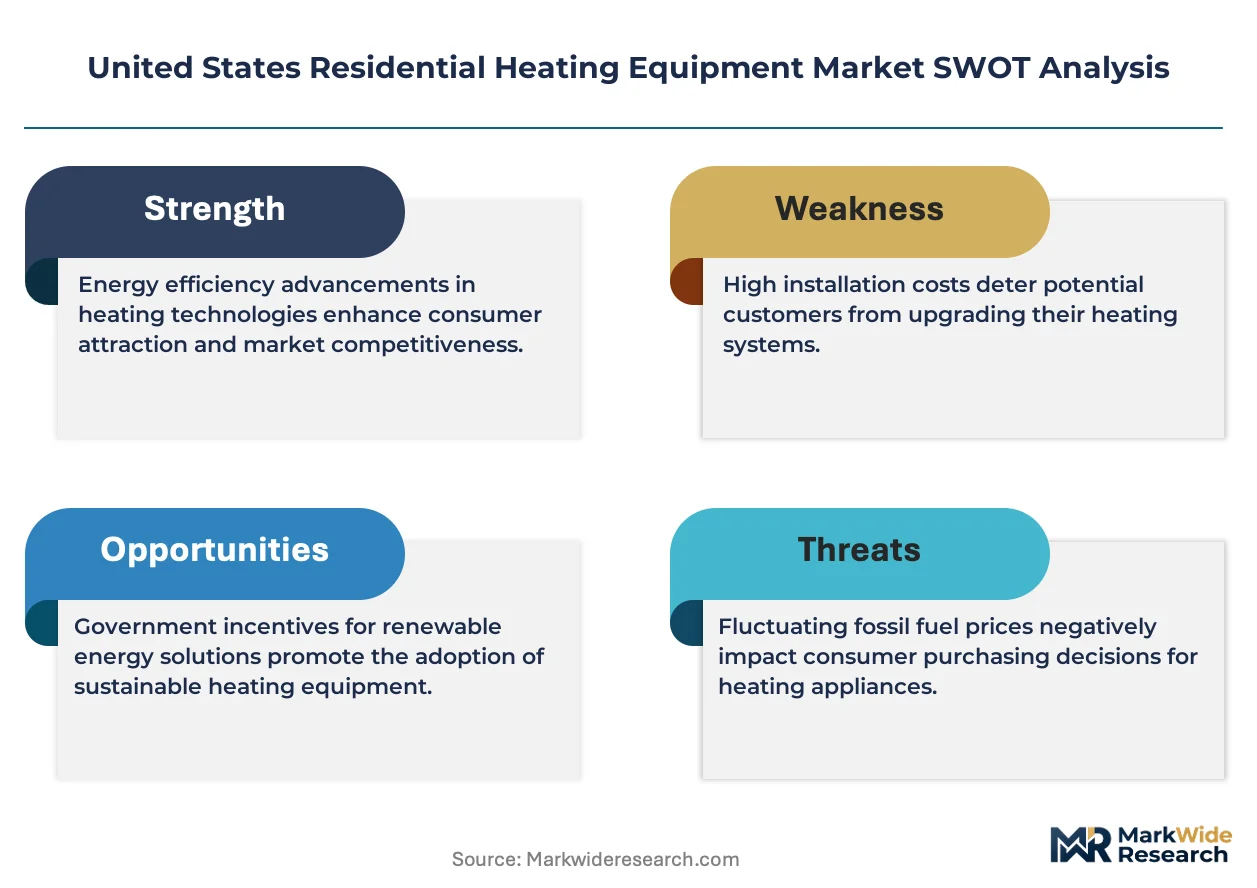
The electrification mandate from state building codes is compressing the replacement window for fossil-fuel furnaces while cold-climate heat pump performance improvements expand the addressable geography for electric systems. This dual pressure is restructuring contractor training priorities and utility rebate program design across the country.
Growth Catalysts
- Inflation Reduction Act tax credits:The 30% federal credit for heat pump installations is lowering first-cost barriers in Midwest and Northeast states where electric resistance heating previously dominated.
- Cold-climate compressor innovation:Variable-speed scroll and rotary compressors with enhanced vapor injection now maintain capacity at minus 13°F, extending heat pump viability into Minnesota and Wisconsin.
- Texas single-family construction:New housing starts in Dallas-Fort Worth and Houston are absorbing heat pump inventory as builders pre-wire for all-electric operation.
Market Restraints
- Copper and aluminum price volatility:Coil and heat exchanger manufacturing faces input cost swings that compress OEM margins during bidding seasons.
- Refrigerant supply concentration:Domestic R-410A and R-32 blending capacity concentrates in Texas and Louisiana, creating hurricane exposure for national distribution.
- Grid interconnection queues:Utility transformer upgrade backlogs in Arizona and Nevada delay heat pump commissioning even after equipment delivery.
Strategic Opportunities
- Hybrid dual-fuel systems:Pairing electric heat pumps with propane backup captures rural markets in Maine and Vermont beyond natural gas pipeline reach.
- Utility-managed demand response:Smart thermostat integration allows grid operators to modulate residential heating loads during peak winter events.
- Massachusetts and New York electrification mandates:State-level bans on fossil-fuel heating in new construction by 2030 are accelerating contractor certification programs.
Industry Challenges
- Heat pump technician certification gaps:EPA Section 608 handling credentials and low-GWP refrigerant safety training lag behind equipment shipment volumes.
- Legacy ductwork incompatibility:1970s-era forced-air systems in Midwest housing stock require resizing or replacement to match heat pump airflow requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Residential Heating Equipment Market |
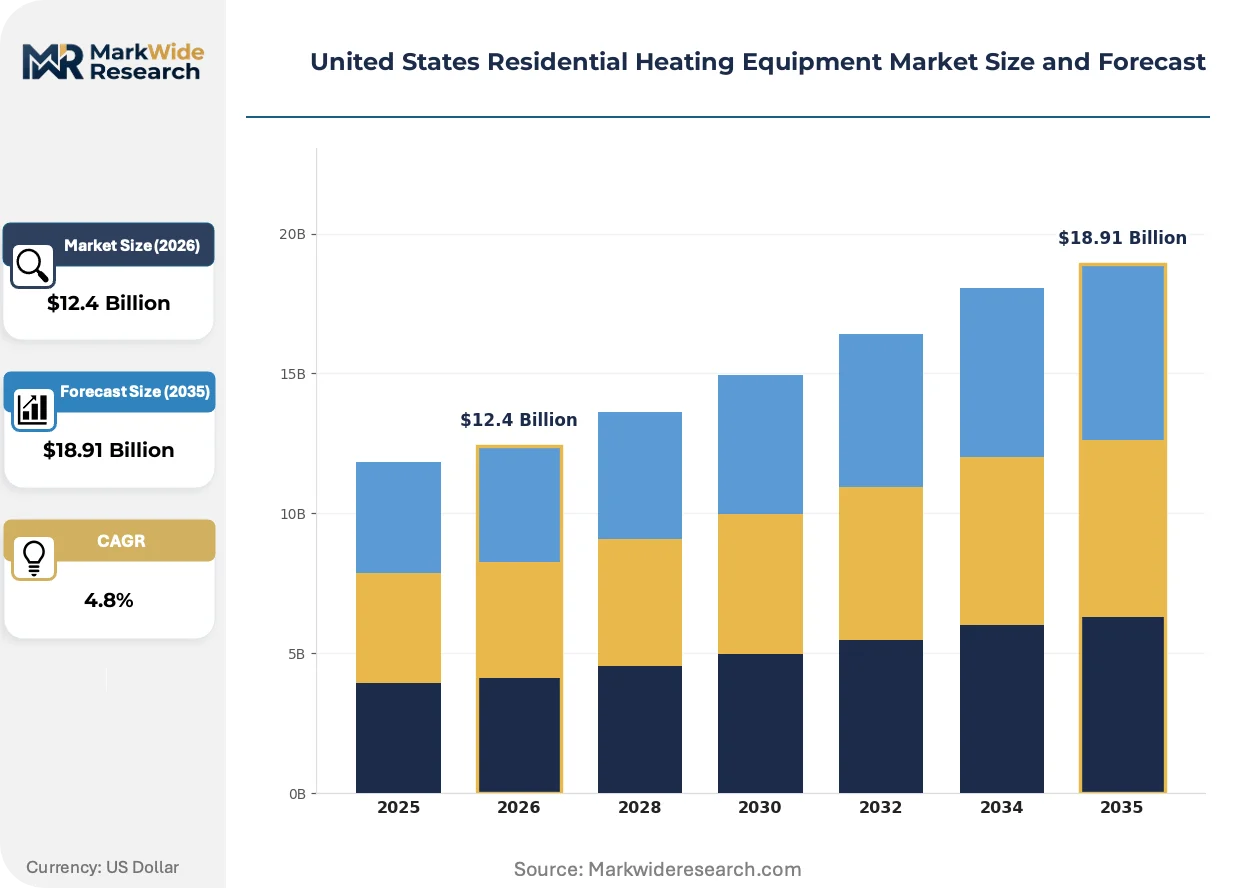
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $18.91 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Furnaces, Boilers, Heat Pumps, Radiant Heaters Fuel Type: Natural Gas, Electricity, Propane, Oil Installation Type: Central Heating, Localized Heating, Hybrid Systems, Smart Systems End User: Homeowners, Renters, Property Managers, Builders |
| Companies Covered | Carrier Global Corporation, Lennox International Inc., Trane Technologies plc, Robert Bosch LLC, Rheem Manufacturing Company, Johnson Controls International plc, Daikin Industries Ltd., A.O. Smith Corporation, Bradford White Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Residential Heating Equipment Market Evolving Landscape
Cold-climate heat pump engineering is splitting the product landscape into distinct performance tiers while state electrification policies accelerate replacement cycles. Distribution channels are adapting to handle more complex installation requirements and tighter contractor specialization.
Variable-capacity heat pump technology is bifurcating the residential market into cold-climate-certified systems and standard-efficiency units. Northeast homeowners facing sub-zero temperatures are specifying units with third-party NEEP Cold Climate certification, while Sun Belt installers default to lower-cost single-stage equipment. This performance divide is compressing the mid-market segment and forcing distributors to carry dual inventory positions.
The EPA's updated New Source Performance Standards for residential furnaces are tightening NOx emission limits in 2026-compliant equipment. California Air Resources Board rules already exceed federal stringency, creating a bifurcated regulatory landscape where manufacturers maintain separate product lines. The compliance burden falls heaviest on natural gas furnace producers serving the replacement market in legacy housing stock.
Homeowner purchasing behavior is fragmentating between emergency replacement decisions and planned electrification upgrades. Texas and Florida buyers facing sudden compressor failures default to like-for-like swaps, while Minnesota and Colorado households schedule pre-winter assessments that incorporate load calculations and duct sealing. This timing divergence is stretching distributor inventory models across seasonal demand peaks.
United States Residential Heating Equipment Market Segmentation
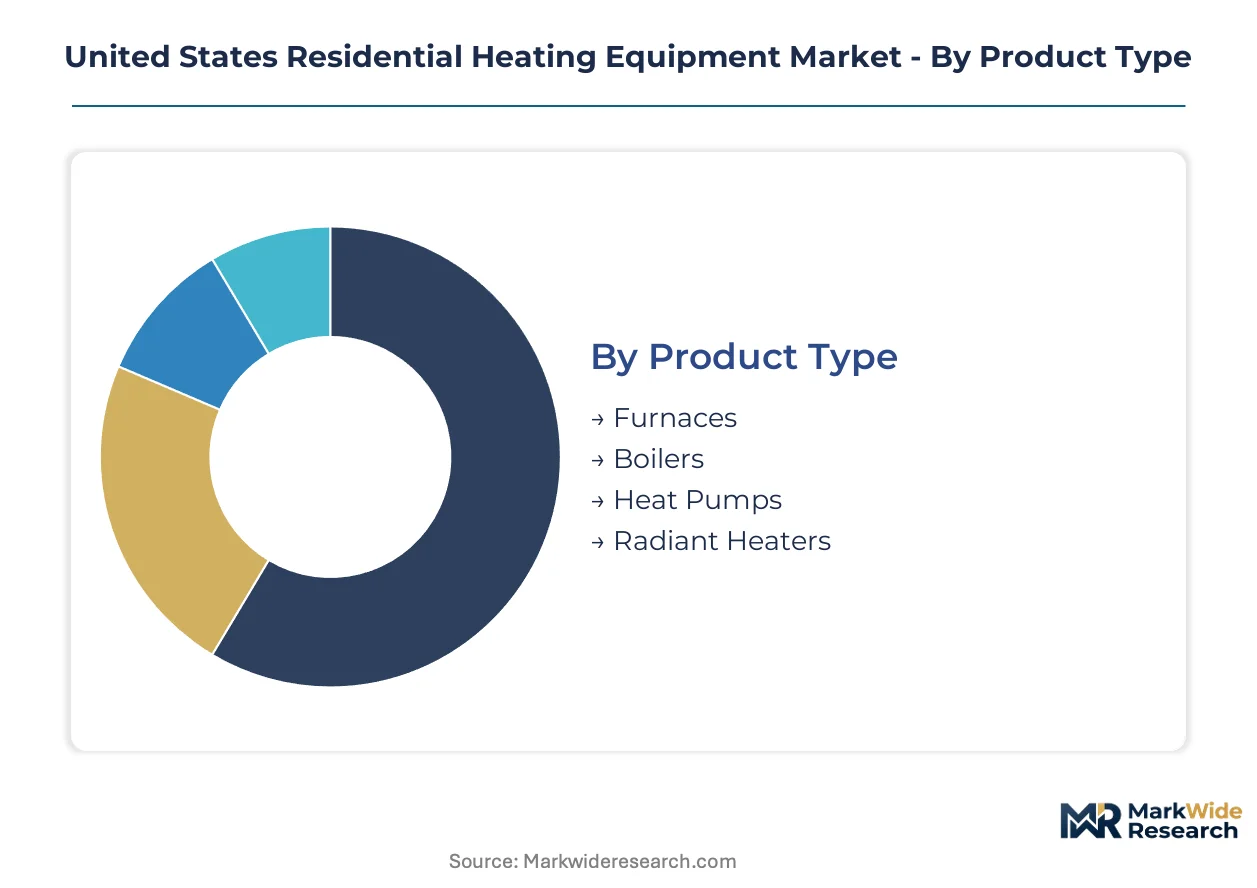
Segmentation in the United States residential heating equipment market reveals how contractor recommendations, utility rebate structures, and building code compliance requirements fragment demand across distinct technical and customer profiles. Understanding these divisions exposes where electrification mandates and cold-climate performance standards create pricing power or commoditization pressure.
Product Type:
Distribution channels specialize by product complexity, with furnaces and boilers flowing through established HVAC contractor networks while heat pumps increasingly route through utility-direct programs and electrification-focused installers.
- Furnaces:Forced-air combustion systems rated by Annual Fuel Utilization Efficiency dominate replacement cycles in legacy housing across the Midwest and Northeast. Demand concentrates in Minnesota, Wisconsin, and Michigan where natural gas infrastructure remains entrenched and homeowners prioritize winter reliability over electrification.
- Boilers:Hydronic heating systems distribute hot water or steam through baseboard radiators or in-floor tubing, maintaining strongholds in older Northeast housing stock. Installation concentrates in Massachusetts, New York, and Pennsylvania where century-old multifamily buildings resist ductwork retrofit economics.
- Heat Pumps:Vapor-compression systems now extend operational range below zero Fahrenheit through cold-climate compressor innovation.
- Radiant Heaters:Electric resistance and hydronic floor systems serve supplemental and zonal applications in Sun Belt additions and bathroom remodels.
By volume, furnaces lead. By growth pace, heat pumps are expanding most quickly.
Fuel Type:
Cost tier stratification splits the market between legacy hydrocarbon infrastructure with depreciated connection costs and grid-dependent electric systems bearing full capital recovery through rate base.
- Natural Gas:Pipeline-delivered methane retains volume leadership through existing housing stock but faces structural pressure as California, New York, and Washington municipalities restrict new hookups. Demand concentrates in Texas, Ohio, and Illinois where distribution networks are dense and heating degree-days justify combustion economics.
- Electricity:Grid-powered systems split between resistance heating in older Sun Belt construction and heat pumps in new electrification corridors. IRA-linked tax credits are compressing lifecycle cost gaps in Arizona, Nevada, and Colorado where utility rates remain moderate.
- Propane:Tank-stored liquefied petroleum gas serves rural markets beyond natural gas pipeline reach in Maine, Vermont, and upstate New York.
- Oil:Distillate fuel oil retreats to isolated rural pockets in northern New England where propane conversion economics remain unfavorable.
Natural gas still commands the largest installed base. Electricity is gaining share fastest where state mandates and rebate stacking alter total cost of ownership calculations.
Installation Type:
Application complexity determines whether projects route through national home improvement retailers, regional HVAC distributors, or specialized electrification contractors with heat pump certification.
- Central Heating:Whole-house ducted or hydronic systems require load calculation, permitting, and professional installation, concentrating demand through dealer-exclusive contractor networks in suburban single-family markets.
- Localized Heating:Zonal mini-splits, baseboard units, and wall furnaces serve additions, accessory dwelling units, and hard-to-condition spaces with lower capital barriers and faster permitting.
- Hybrid Systems:Dual-fuel configurations pairing electric heat pumps with fossil-fuel backup capture rural markets in cold climates beyond grid capacity for full electrification.
- Smart Systems:Wi-Fi-enabled thermostats and utility-managed demand response integration are concentrating in new construction across Texas and Florida where builders pre-wire for connected home packages.
Central heating retains the revenue concentration. Smart systems are climbing the fastest as utility rebate programs mandate connected controls for incentive eligibility.
End User:
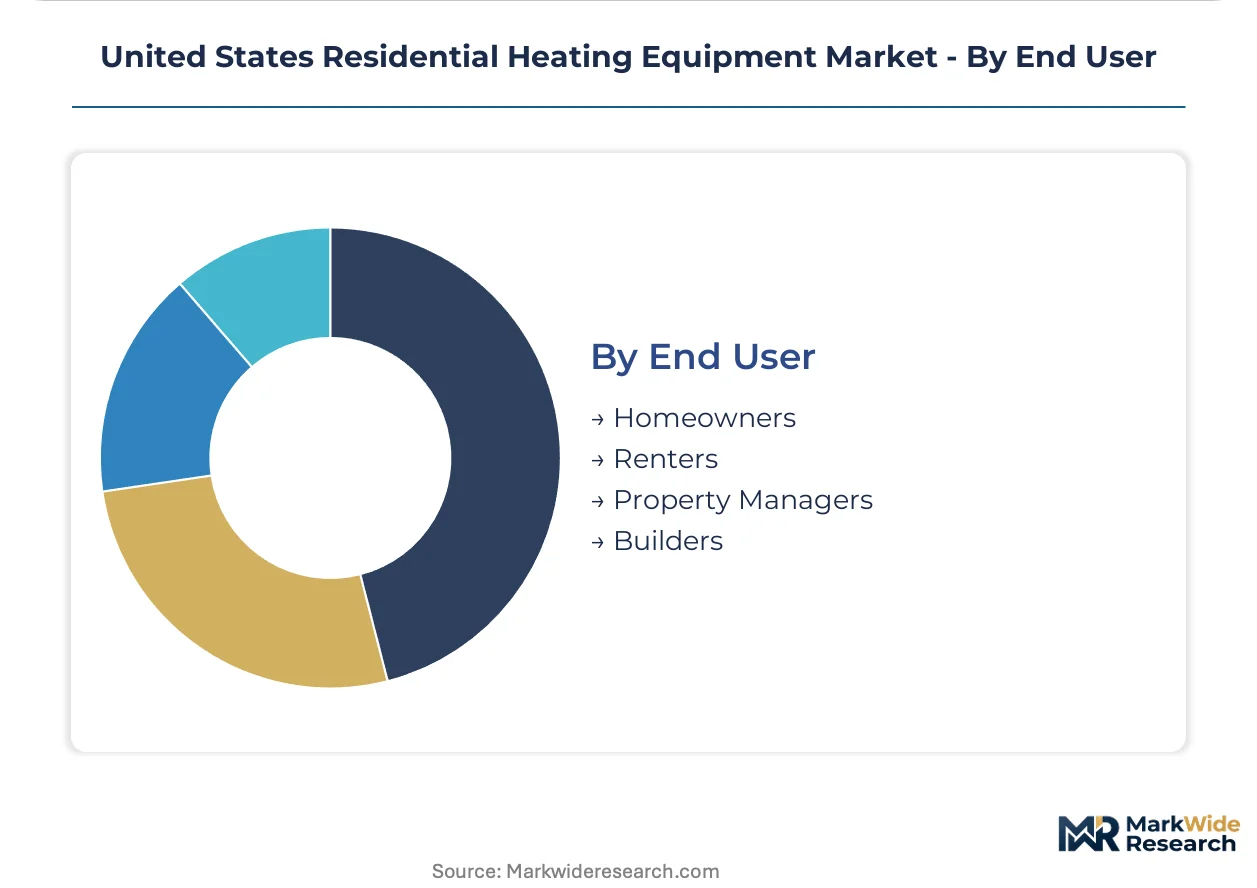
Customer type shapes procurement timing, financing method, and sensitivity to operating cost versus first-cost tradeoffs across the replacement and new construction cycles.
- Homeowners:Owner-occupiers drive the replacement market through emergency failures and planned pre-winter upgrades, with electrification-minded households in Massachusetts and Colorado scheduling load calculations and duct sealing assessments.
- Renters:Tenants exercise minimal equipment influence, though utility-bill-conscious renters in multifamily housing increasingly select properties with heat pump heating over electric resistance.
- Property Managers:Portfolio operators of multifamily and single-family rental units prioritize equipment standardization and contractor volume pricing across replacement cycles.
- Builders:Production and custom homebuilders in Dallas-Fort Worth, Houston, and Phoenix are specifying heat pumps as default equipment in new single-family construction where all-electric pre-wiring reduces field complexity.
Homeowners generate the largest transaction volume. Builders are expanding fastest as electrification mandates in California, New York, and Washington foreclose fossil-fuel options in new construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian manufacturers export cold-climate heat pump components to Minnesota and Wisconsin distributors, while Mexican assembly plants serve Texas and Arizona builders with cost-optimized furnace and heat pump units for new single-family construction.
Northeast Corridor
Massachusetts and New York electrification mandates accelerate boiler-to-heat pump conversions in century-old multifamily housing. The EPA's updated New Source Performance Standards tighten NOx emission limits for replacement furnaces. Boston and New York City contractors prioritize NEEP Cold Climate-certified heat pumps for sub-zero reliability.
Midwest Manufacturing Belt
Minnesota, Wisconsin, and Michigan homeowners replace aging natural gas furnaces ahead of winter reliability concerns. IRA-linked tax credits compress lifecycle cost gaps for electric heat pumps in states previously dominated by electric resistance heating. Minneapolis-St. Paul distributors stock variable-speed scroll compressors rated to minus 13°F.
Texas Gulf Coast
Dallas-Fort Worth and Houston single-family construction absorbs heat pump inventory as builders pre-wire for all-electric operation. Texas grid interconnection queues delay transformer upgrades required for heat pump commissioning. Houston distributors manage hurricane-season supply chain exposure for refrigerant blending capacity concentrated along the Louisiana border.
Southwest Sun Belt
Arizona and Nevada heat pump penetration climbs from a low base as utility rebate programs stack with federal incentives. Grid transformer upgrade backlogs in Phoenix and Las Vegas delay equipment commissioning. Tucson and Albuquerque contractors specialize in hybrid dual-fuel systems pairing heat pumps with propane backup for rural markets beyond natural gas pipeline reach.
Pacific Northwest
Washington state building electrification targets constrain fossil-fuel heating in new construction by 2030. Seattle and Portland utilities mandate connected smart thermostat integration for rebate eligibility. Spokane and Boise installers face legacy ductwork incompatibility challenges in 1970s-era housing stock requiring resizing for heat pump airflow requirements.
United States Residential Heating Equipment Market Competitive Landscape
Listed leaders compete with private specialists across distribution channel access and contractor training infrastructure. The vendor base concentrates around furnace and heat pump manufacturers with established dealer networks, while mid-tier challengers compete on price in replacement cycles. Three archetypes dominate: diversified climate-control conglomerates with broad product portfolios, premium furnace specialists with dealer exclusivity programs, and aggressive price competitors building heat pump manufacturing capacity. Capacity expansion and strategic partnerships represent the dominant competitive moves as electrification mandates reshape product mix requirements.
Within the diversified climate-control tier, Carrier Global Corporation and Trane Technologies plc occupy positions sustained by broad distribution networks and contractor training infrastructure. Lennox International Inc. exemplifies the premium furnace specialist archetype through extensive dealer exclusivity arrangements. Rheem Manufacturing Company represents the price-competitive challenger building heat pump capacity to capture replacement cycle volume.
| Leading Market Players |
|---|
| Carrier Global Corporation |
| Lennox International Inc. |
| Trane Technologies plc |
| Robert Bosch LLC |
| Rheem Manufacturing Company |
| Johnson Controls International plc |
| Daikin Industries Ltd. |
| A.O. Smith Corporation |
| Bradford White Corporation |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts between OEMs and refrigerant blenders lock in supply access and price visibility for heat pump manufacturers facing volatile copper and aluminum coil costs. These arrangements concentrate pricing power with Texas and Louisiana chemical processors while compressing margins for furnace assemblers exposed to spot aluminum markets.
Pricing Analysis
Cold-climate-certified heat pumps command a technology-generation pricing gap over standard-efficiency units designed for Sun Belt applications. Three-tier pricing structure across premium NEEP-certified, standard variable-speed, and economy single-stage levels splits the market by certification grade and compressor performance. Price erosion runs through the economy tier as Chinese manufacturers expand coil and compressor exports to Arizona and Nevada distributors. Homebuilders in Texas and Florida exhibit the highest price sensitivity, while Minnesota homeowners facing sub-zero reliability concerns prioritize performance over first cost.
Supply Chain Analysis
China and Mexico anchor heat pump component manufacturing, with Chinese factories supplying scroll compressors and Mexican assembly plants producing cost-optimized furnace units for Texas builders. Domestic production draws from copper coil stock concentrated in Ohio and Tennessee, plus aluminum heat exchanger sheet from Kentucky rolling mills. Hurricane exposure along the Texas-Louisiana chemical corridor creates single-source vulnerability for R-410A and R-32 refrigerant blending. Distribution runs through regional HVAC distributors in Minneapolis-St. Paul, Dallas-Fort Worth, and Phoenix who manage inventory for contractor dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from utility-managed demand response programs and extended warranty contracts is expanding faster than hardware sales as electrification mandates increase installation complexity. This recurring-revenue layer rewards manufacturers with connected thermostat platforms and certified technician networks.
For Market Incumbents: Consolidate dealer exclusivity arrangements in the Midwest replacement market where aging furnace stock creates captive retrofit demand. Acquire cold-climate heat pump certification capacity to defend against Korean and Japanese entrants targeting Minnesota and Wisconsin. Channel control through contractor training infrastructure remains the priority lever against price competitors.
For New Entrants and Emerging Players: Lead with hybrid dual-fuel systems capturing rural Vermont and Maine markets beyond natural gas pipeline reach where electrification mandates create compliance gaps. The most penetrable segment lies in propane backup configurations for cold-climate heat pumps. A utility-direct go-to-market angle bypasses established distributor relationships in Arizona and Nevada rebate programs.
For Investors and Strategic Acquirers: Regional electrification contractors with EPA Section 608 certification pipelines and utility rebate program access represent the highest-conviction acquisition archetype. Long-term viability hinges on IRA-linked incentive renewal structures sustaining heat pump conversion economics against replacement-parity with gas furnaces. The signal to watch is Massachusetts and New York contractor certification program graduation rates as a leading indicator of installation capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Climate Certification Investment | NEEP certification unlocks utility rebate eligibility in Minnesota and Wisconsin markets. |
| Refrigerant Blending Capacity Expansion | Domestic R-32 production reduces hurricane exposure along Texas-Louisiana corridor. |
| Contractor Training Infrastructure Buildout | EPA Section 608 credential pipelines address technician certification gaps in heat pump rollout. |
| Utility Demand Response Partnership | Smart thermostat integration enables grid operators to modulate residential heating loads. |
| Hybrid Dual-Fuel Product Line Launch | Propane backup configurations capture rural Maine and Vermont markets beyond pipeline reach. |
Research Methodology
A standing panel of HVAC contractor owners, utility electrification program managers, regional distributor purchasing directors, and EPA certification trainers provided ongoing calibration across primary interviews. Secondary validation drew from DOE Appliance and Equipment Standards Program filings, EIA residential energy consumption surveys, state building code electrification mandate texts, and utility rebate program databases. Bottom-up equipment shipment data triangulated against top-down construction permit and replacement cycle estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation by product type, fuel source, installation complexity, and regional heating degree-day profiles. CAGRs derived from equipment shipment trajectories, construction start forecasts, and regulatory compliance timeline assumptions. Cold-climate compressor performance improvements and IRA incentive renewal probability served as scenario-weighted inputs.
The analysis sits within stated boundaries; outcomes outside sustained federal tax credit structures or accelerated grid interconnection timelines would require recalibration. Forecasts reflect assumptions regarding copper price stability, refrigerant supply continuity, and state electrification mandate enforcement intensity. Recalibration cycles align with material shifts in EPA emissions standards, utility rebate program redesigns, and cold-climate heat pump technology breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
High Pressure Heat Exchanger Market
HVAC Equipment
Compact Fan Coils Market
HVAC Equipment
HVAC Centrifugal Compressors Market
HVAC Equipment
Variable Air Volume Box Market
HVAC Equipment
United States Heat Exchanger Market
HVAC Equipment
Residential Furnaces Market
HVAC Equipment
HVAC Chillers Market
HVAC Equipment
Asia-Pacific Industrial Heat Pump Market
HVAC Equipment
Compressed Air Treatment Equipment Market
HVAC Equipment
Chilled Beams Market
HVAC Equipment
Underfloor Air Distribution Systems Market
HVAC Equipment
United States HVAC Equipment and Services Market
HVAC Equipment
Mexico Compressed Air Treatment Equipment Market
HVAC Equipment
Automatic Ducting Machine Market
HVAC Equipment
Canada Outdoor Air Source Heat Pump Market
HVAC Equipment
Japan HVAC Market