
 Automatic Slack Adjusters Market | 2026-2036
Automatic Slack Adjusters Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Slack Adjusters Market Outlook
The split between premium and commodity tiers in automatic slack adjusters is hardening on material grade and sensor integration. ZF Group leverages its integrated brake-system architecture to command premium positioning in electronic-adjustment modules. Haldex anchors its portfolio through geographic density in European OEM channels, while STEMCO Products Inc. competes aggressively on aftermarket reach across North American fleet accounts.
Automatic slack adjusters are self-actuating mechanisms that maintain optimal brake-chamber pushrod stroke within a specified tolerance, typically manufactured from ductile iron housings with hardened steel internal gearing to withstand cyclic loading in commercial braking systems. Their primary purpose is to compensate for lining wear and prevent manual adjustment, thereby preserving stopping distance compliance under FMVSS 121. Heavy-duty installations dominate value capture given their exposure to severe-duty cycles and regulatory inspection frequency, while electronic technology represents the fastest-expanding margin pool as fleets integrate telematics-linked brake monitoring. Pneumatic systems retain volume leadership in retrofit channels where fleet operators prioritize capital efficiency over connected diagnostics.
NHTSA enforces stroke-length thresholds through periodic roadside inspections, compelling carriers to replace non-compliant adjusters rather than repair. The EPA's Phase 2 greenhouse-gas standards for heavy-duty trucks indirectly sustain demand by extending vehicle lifecycles and accelerating brake-system refresh intervals. OEMs and aftermarket distributors must monitor how impending revisions to FMVSS 121 affect electronic adjuster certification pathways and warranty liability structures.
Market Dynamics
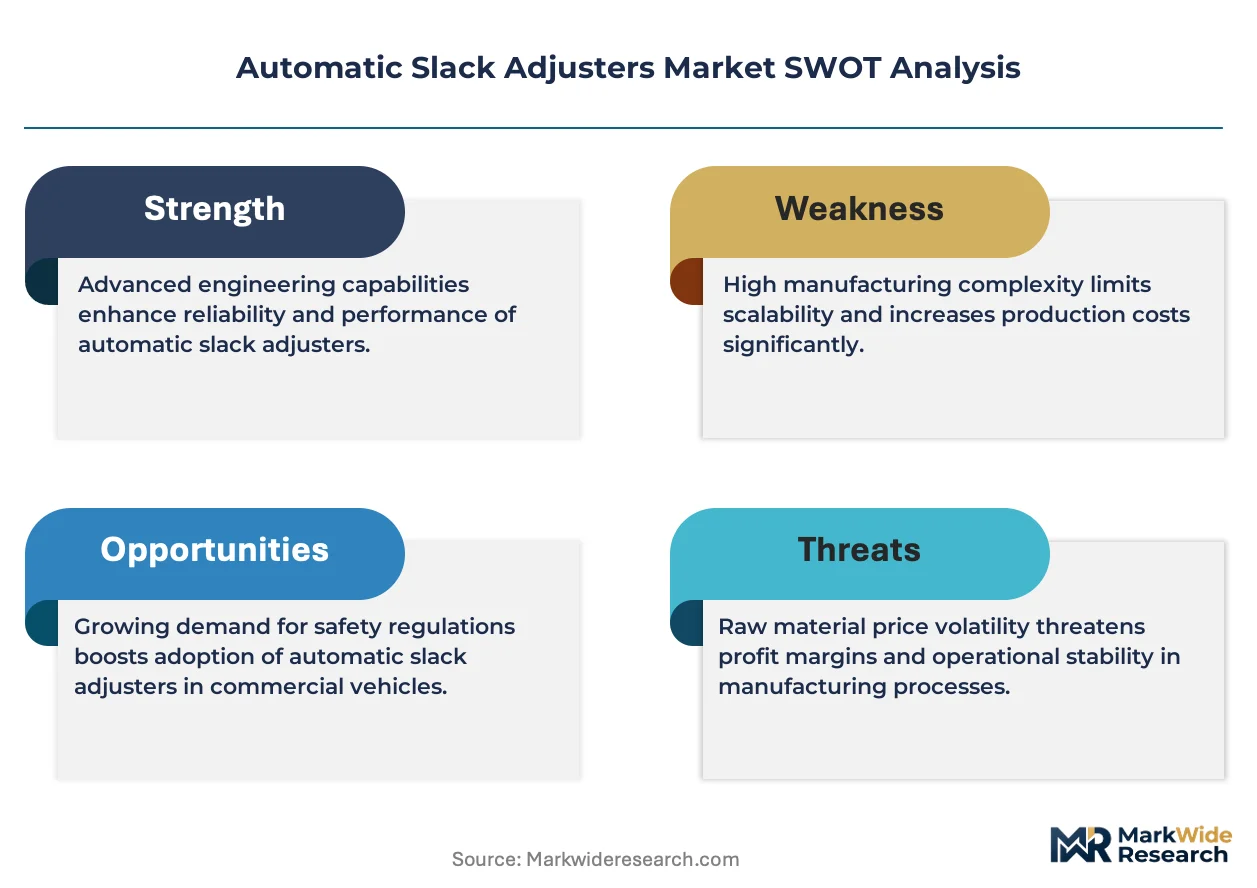
The Automatic Slack Adjusters Market is being fundamentally restructured by NHTSA's tightening stroke-length enforcement, which compels fleet operators to replace rather than repair non-compliant units and accelerates replacement cycles across commercial vehicle parc.
Growth Catalysts
- FMVSS 121 Stroke Compliance:NHTSA's roadside inspection protocols mandate precise pushrod stroke tolerances, forcing carriers into proactive adjuster replacement schedules to avoid out-of-service violations.
- Telematics Integration:Fleet management platforms now embed brake-health monitoring, creating pull-through demand for electronic adjusters capable of real-time stroke reporting.
- Extended Vehicle Lifecycles:EPA Phase 2 greenhouse-gas standards prolong heavy-duty truck operational life, multiplying brake-system refresh intervals and adjuster replacement frequency.
Market Restraints
- Raw Material Volatility:Ductile iron casting feedstock and hardened steel gearing face price instability from scrap metal market fluctuations and energy-intensive foundry operations.
- Supplier Concentration:Precision machining capacity for internal gearing clusters concentrates in Midwestern US manufacturing corridors, creating geographic vulnerability to regional labor disruptions.
- Pneumatic System Persistence:Retrofit channels favor mechanical adjusters for capital-constrained fleets, slowing electronic adjuster penetration in secondary vehicle markets.
Strategic Opportunities
- Connected Adjuster Platforms:Convergence of CAN bus communication protocols with predictive maintenance algorithms enables outcome-based brake service contracts for large fleet accounts.
- Aftermarket Channel Expansion:Independent distributors serving owner-operator segments remain underpenetrated by electronic adjuster SKUs, presenting white-space for product line extension.
- State-Level Inspection Harmonization:California's adoption of enhanced brake-performance testing for heavy-duty vehicles signals potential regulatory tailwind for premium adjuster categories.
Industry Challenges
- Calibration Technician Scarcity:Electronic adjuster installation and diagnostic programming require specialized training that vocational programs have not scaled to match fleet demand.
- Legacy System Integration:Mixed fleets operating both pneumatic and electronic brake platforms face complexity in standardizing maintenance protocols and spare parts inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Slack Adjusters Market |
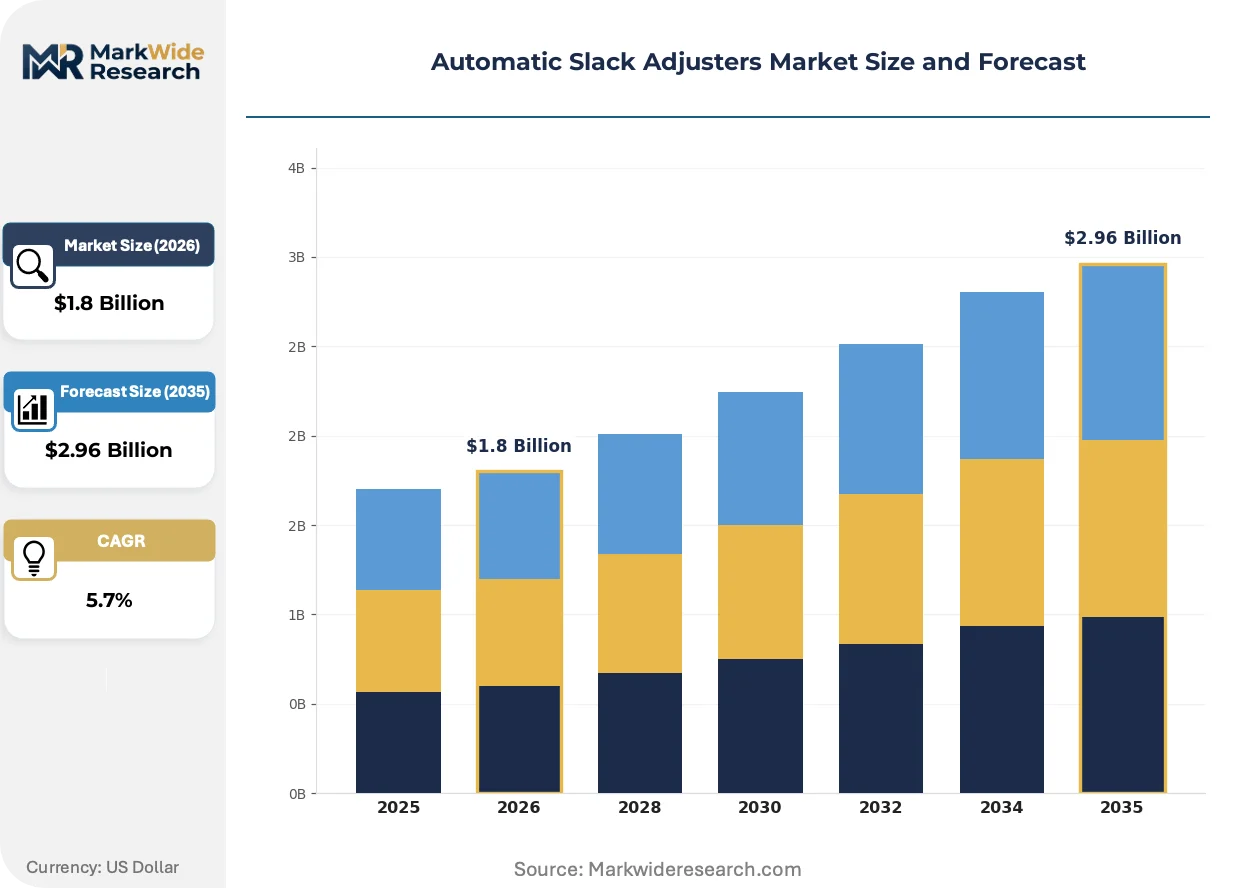
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty, Medium-Duty, Light-Duty, Specialty Technology: Pneumatic, Hydraulic, Electronic, Mechanical End User: OEMs, Aftermarket Providers, Fleet Operators, Maintenance Shops Installation: On-Highway, Off-Highway, Rail, Others |
| Companies Covered | ZF Group, STEMCO Products Inc., Knorr-Bremse AG, TSE Brakes Inc., MEI Brakes, Haldex, Bendix, Ferdinand Bilstein GmbH, Meritor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Slack Adjusters Market Strategic Shifts
Electronic stroke sensing is actively displacing mechanical indication methods across new vehicle platforms, while regulatory pressure on brake performance transparency accelerates connected hardware deployment.
Sensor-integrated automatic slack adjusters are overtaking purely mechanical units in OEM brake system architectures. Heavy-duty truck manufacturers specify electronic adjusters with built-in position feedback for factory-installed air brake systems. This capability compression is collapsing the historical separation between brake hardware and fleet telematics infrastructure.
NHTSA's updated Federal Motor Vehicle Safety Standards impose stricter documentation requirements for brake stroke maintenance records. Carriers must now retain adjustment history for inspection audit trails, driving demand for adjusters with embedded data-logging functionality. Long-haul freight operators in the United States are responding by specifying certified electronic units with tamper-evident calibration.
Fleet procurement departments now unbundle brake component sourcing from vehicle acquisition contracts, creating direct purchasing relationships with adjuster manufacturers. This disintermediation bypasses traditional OEM captive parts channels and compresses distributor margins. The pattern is most pronounced among for-hire trucking fleets operating more than 500 power units, where centralized maintenance authority enables volume aggregation.
Automatic Slack Adjusters Market Segmentation
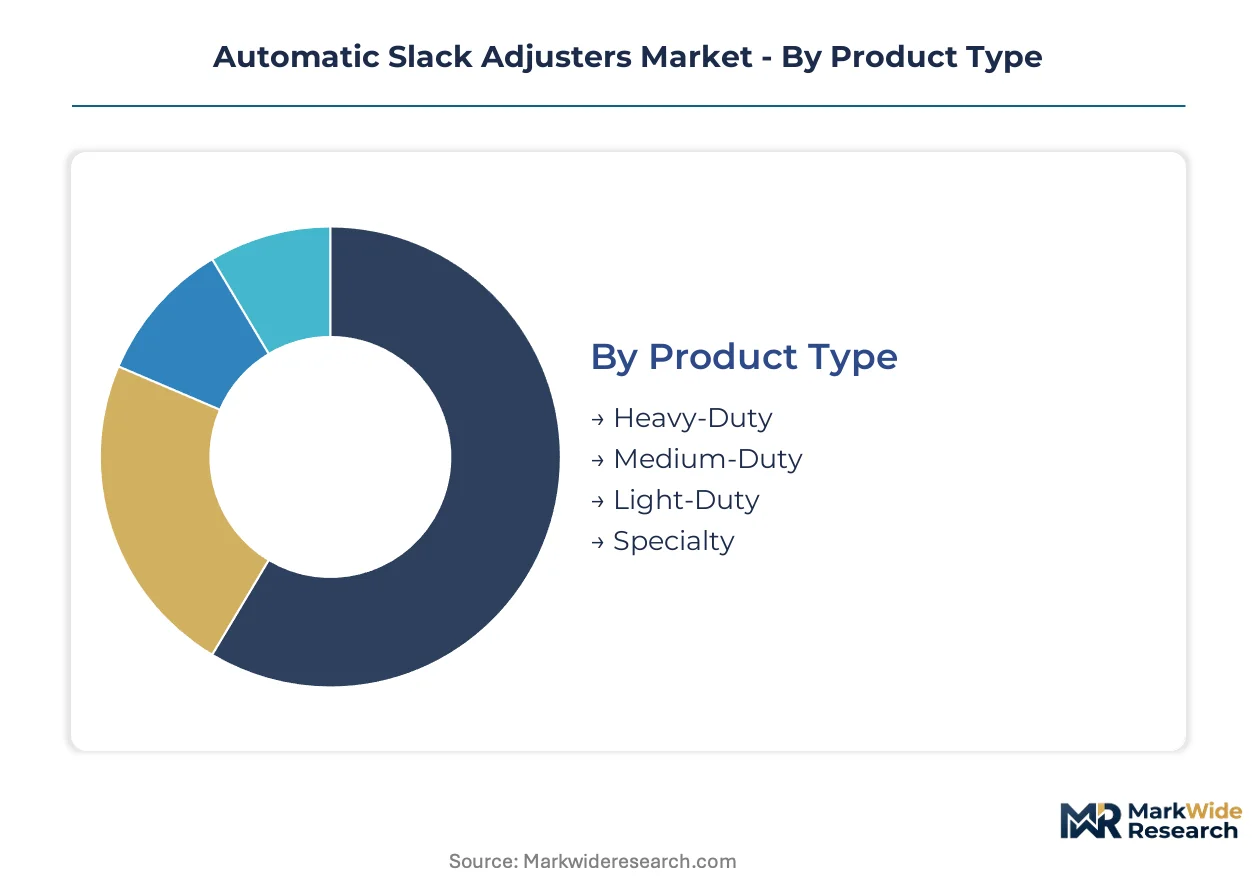
Segmentation in automatic slack adjusters reveals how brake-system architecture, duty-cycle severity, and procurement channel structure fragment demand. Each dimension exposes different margin pools and competitive entry points for component suppliers.
Product Type:
Customization intensifies with vehicle gross weight rating, as housing material grade, gearing tolerance, and sensor integration scale disproportionately across duty classes.
- Heavy-Duty:Ductile iron housings with induction-hardened steel gearing withstand sustained thermal cycling from 80,000-pound gross combination weights. Demand concentrates in United States long-haul freight fleets where NHTSA roadside inspection frequency compels proactive replacement schedules.
- Medium-Duty:Hybrid material specifications balance cost against Class 6-7 delivery truck duty cycles. Urban freight operators in California specify these units for stop-and-go routing where brake heat dissipation requirements fall below heavy-duty thresholds but exceed light-duty capacity.
- Light-Duty:Simplified mechanical architectures serve final-mile delivery vans and utility trucks.
- Specialty:Custom stroke-length configurations address fire apparatus, refuse collection, and military vehicle braking systems.
Leading the category by volume: Heavy-Duty. Growing fastest: Medium-Duty.
Technology:
Cost tier stratification separates legacy pneumatic systems from sensor-integrated electronic platforms, with hydraulic and mechanical architectures occupying intermediate price-performance positions.
- Pneumatic:Compressed-air actuation through diaphragm chambers dominates installed base across aging commercial vehicle parc. Retrofit channels in the United States favor these units for capital-constrained owner-operators prioritizing functional compliance over telematics connectivity.
- Electronic:CAN bus-integrated stroke sensors enable real-time brake health telemetry to fleet management platforms. Large for-hire carriers operating 500-plus power units specify these units to compress maintenance intervals and satisfy FMVSS 121 documentation requirements.
- Hydraulic:Fluid-pressure systems serve medium-duty applications where air brake infrastructure is absent.
- Mechanical:Manual adjustment mechanisms persist in legacy vehicle populations and developing market segments.
Volume leadership: Pneumatic. Steepest expansion trajectory: Electronic.
End User:
Procurement authority concentration varies sharply across this dimension, with centralized fleet purchasing creating volume aggregation unavailable through fragmented maintenance shop channels.
- OEMs:Factory-installed specifications on new heavy-duty trucks increasingly mandate electronic adjusters with embedded position feedback. Brake system integrators in the United States specify these units to align with vehicle telematics architectures and warranty liability structures.
- Fleet Operators:Direct sourcing relationships with adjuster manufacturers bypass traditional distributor networks. National trucking carriers leverage centralized maintenance authority to aggregate volume and compress per-unit acquisition costs below OEM captive parts pricing.
- Aftermarket Providers:Independent distributors serve replacement demand across vehicle lifecycle extension scenarios.
- Maintenance Shops:Repair facilities handle reactive replacement triggered by inspection failures.
Contract value concentration: Fleet Operators. Channel expansion opportunity: Aftermarket Providers.
Installation:
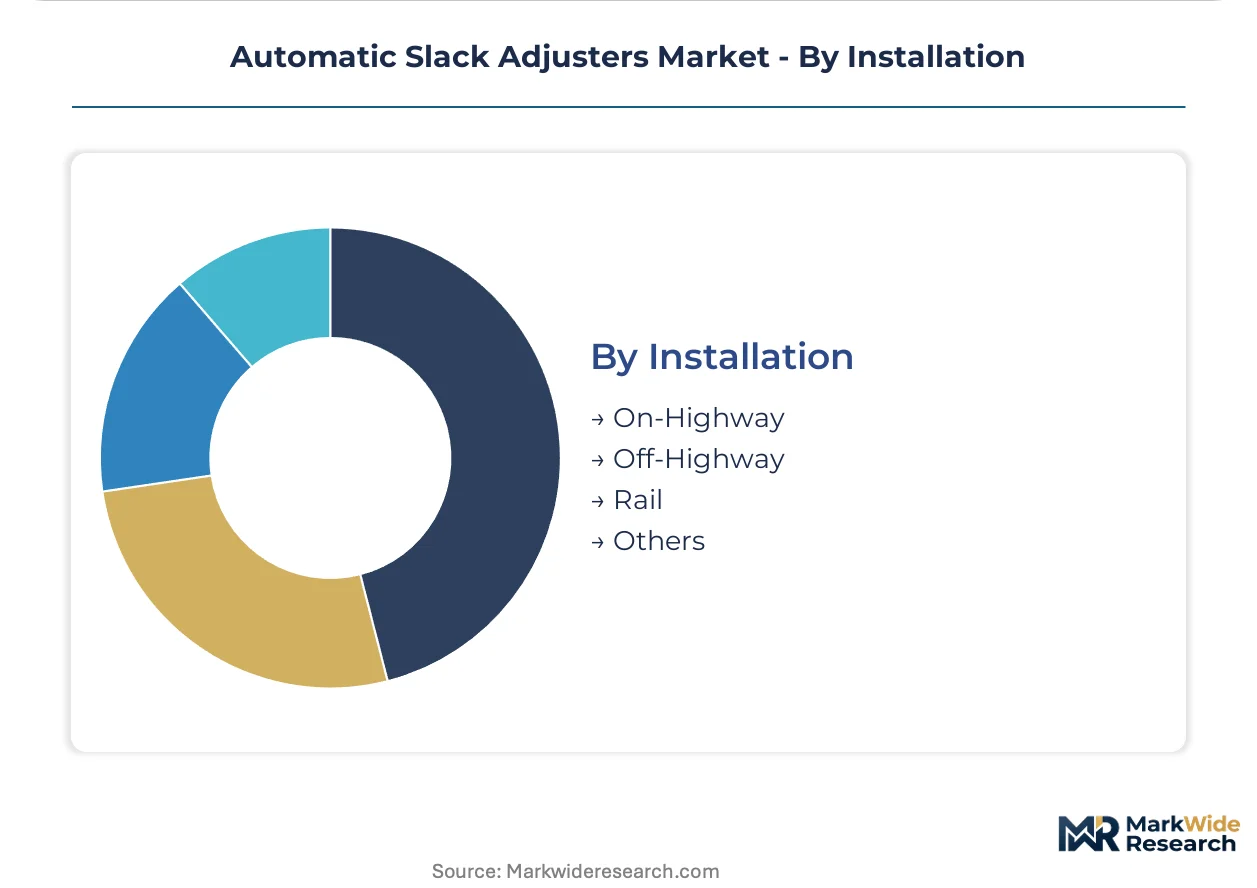
Application environment dictates corrosion resistance specifications, with off-highway and rail installations requiring sealed housing architectures absent from standard on-highway designs.
- On-Highway:Standard-duty sealing and surface treatments address controlled road salt exposure and predictable thermal cycling. Interstate freight corridors in the United States sustain replacement demand through mandatory periodic inspection protocols.
- Off-Highway:Mining, construction, and agricultural vehicles require enhanced particulate sealing and impact-resistant housing geometries. These specifications command material cost premiums justified by extended service intervals in remote operating environments.
- Rail:Locomotive and freight car braking systems specify specialized stroke tolerances and mounting interfaces.
- Others:Marine, military, and industrial stationary applications occupy niche demand pockets.
Unit volume leader: On-Highway. Margin premium capture: Off-Highway.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit's automotive manufacturing corridor sustains the heaviest concentration of automatic slack adjuster demand through its dense network of heavy-duty truck assembly plants and fleet operator headquarters. The market's geographic footprint tracks commercial vehicle production nodes and freight corridor density across North America, Europe, and Asia-Pacific.
United States
Long-haul freight volumes along Interstate corridors generate replacement demand as NHTSA roadside inspection protocols enforce strict stroke-length compliance. The EPA's Phase 2 greenhouse-gas standards extend vehicle lifecycles, accelerating brake-system refresh intervals. Manufacturing clusters in Michigan and Ohio supply precision-machined gearing components to domestic OEM channels.
Germany
Commercial vehicle OEMs in Baden-Württemberg and Bavaria specify electronic adjusters with embedded position feedback for factory-installed air brake systems. The KBA enforces rigorous brake-performance certification that elevates material grade requirements. Stuttgart's automotive engineering ecosystem drives sensor-integrated adjuster development for export markets.
China
Domestic heavy-duty truck production in Shandong and Hubei provinces absorbs mechanical adjuster volumes for cost-sensitive fleet operators. MIIT's evolving commercial vehicle safety standards create compliance windows for electronic technology adoption. Yangtze River Delta manufacturing corridors concentrate ductile iron foundry capacity for housing production.
Japan
Premium heavy-duty truck manufacturers in Aichi and Kanagawa prefectures integrate electronic adjusters with vehicle telematics architectures. METI's industrial standards for commercial vehicle components emphasize precision tolerance specifications. Nagoya's automotive supplier network exports adjuster subassemblies to Southeast Asian assembly plants.
Mexico
Cross-border freight operations between Nuevo León and Texas sustain aftermarket replacement cycles for US-specification vehicles. The country's national automotive regulator aligns commercial vehicle safety protocols with FMVSS benchmarks. Monterrey's industrial corridor hosts stamping and machining operations serving North American OEM supply chains.
Automatic Slack Adjusters Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the automatic slack adjuster market, creating a tiered structure where integrated brake-system suppliers hold premium positions while component specialists capture aftermarket volume. The vendor base concentrates around three strategic archetypes: diversified automotive suppliers with captive brake-system integration, dedicated adjuster manufacturers with geographic density in regional aftermarket channels, and precision machining specialists supplying internal gearing clusters. Competitive moves center on backward integration into foundry operations and strategic partnerships with fleet telematics platforms.
Among diversified automotive suppliers, ZF Group and Knorr-Bremse AG exemplify the integrated-systems archetype through their brake-system architecture capabilities. Haldex occupies a position within the dedicated component tier, while STEMCO Products Inc. anchors the North American aftermarket channel. Ferdinand Bilstein GmbH represents the European aftermarket specialist archetype. These named entities illustrate how competitive positioning stratifies across technology integration levels and geographic channel control rather than manufacturing scale alone.
| Leading Market Players |
|---|
| ZF Group |
| STEMCO Products Inc. |
| Knorr-Bremse AG |
| TSE Brakes Inc. |
| MEI Brakes |
| Haldex |
| Bendix |
| Ferdinand Bilstein GmbH |
| Meritor |
| Others |
Value Chain & Pricing Dynamics
Backward integration into ductile iron foundry operations anchors both supply security and pricing power for tier-one automatic slack adjuster manufacturers serving NHTSA-regulated fleet operators. Captive housing production insulates premium suppliers from scrap metal volatility while enabling three-tier pricing differentiation across electronic, pneumatic, and mechanical architectures.
Pricing Analysis
Outcome-based pricing tied to brake-system uptime and FMVSS 121 compliance documentation anchors value capture for electronic adjuster tiers. Three-tier pricing structure across premium sensor-integrated, standard pneumatic, and economy mechanical levels separates certified fleet-specification units from retrofit channel commodities. Price differentiation hinges on NHTSA certification grade and telematics integration depth. Cost compression in the mechanical tier is intensifying because capital-constrained owner-operators prioritize functional compliance over connected diagnostics. Aftermarket distributors exhibit highest price sensitivity; OEM brake-system integrators show lowest.
Supply Chain Analysis
Dual-sourcing requirements from large fleet operators mandate multi-supplier qualification for precision-machined gearing clusters, fragmenting procurement across domestic and import channels. Manufacturing concentrates in the United States, Germany, and China for ductile iron housings, hardened steel gearing, and sensor module assembly respectively. Raw material dependencies draw from scrap metal feedstock, induction-hardened steel bar stock, and automotive-grade semiconductor components. Single-source vulnerability concentrates in Midwestern US machining corridors for internal gearing. Distribution runs through OEM captive parts networks, national fleet direct contracts, and independent aftermarket distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is reshaping competitive positioning as players pursue captive foundry capacity to secure ductile iron supply and compress housing costs below spot-market sourcing.
For Market Incumbents: Anchor market position through backward integration into precision machining capacity and certification investment for NHTSA electronic adjuster pathways. Defensive consolidation should prioritize captive gearing production in Michigan and Ohio manufacturing corridors to offset emerging competition from sensor-integrated platform entrants. Threat substitution from hydraulic brake architectures in medium-duty segments demands proactive pneumatic-to-electronic product line migration. For New Entrants and Emerging Players: Capture white-space in independent aftermarket channels serving owner-operator segments underpenetrated by electronic adjuster SKUs. The most penetrable target sits in California state-level inspection harmonization creating compliance-driven upgrade cycles. Go-to-market execution should leverage direct fleet relationships bypassing traditional OEM captive parts networks through telematics platform partnerships. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified brake-system suppliers seeking electronic adjuster capabilities. Long-term viability favors precision machining specialists with captive foundry operations and NHTSA certification infrastructure already in place. The signal to watch is NHTSA's impending FMVSS 121 revision timeline accelerating electronic adjuster mandate adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Operations | Captive ductile iron supply insulates margins from scrap metal volatility in NHTSA-regulated markets. |
| Telematics Platform Partnership | CAN bus integration with fleet management systems enables real-time brake health monitoring and predictive maintenance contracts. |
| NHTSA Certification Investment | Electronic adjuster approval pathways secure OEM factory-install specifications and warranty liability coverage. |
| Aftermarket Channel Expansion | Independent distributor relationships penetrate owner-operator segments underserved by electronic SKU availability. |
| Geographic Manufacturing Footprint | Midwestern US machining corridors reduce logistics exposure for precision gearing component supply. |
Study Parameters
Multi-period observation of NHTSA roadside inspection citation rates, fleet brake maintenance interval compression, and electronic adjuster installation penetration anchored the trend analysis, supplemented by interviews with fleet maintenance directors, OEM brake-system procurement managers, aftermarket distributor category buyers, and precision machining operations heads. Secondary validation drew from NHTSA FMVSS 121 regulatory filings, EPA Phase 2 greenhouse-gas compliance documentation, vehicle production databases, and heavy-duty truck registration data. Bottom-up channel volume estimates triangulated against top-down commercial vehicle parc modeling.
The input-output matrix framed demand as a function of vehicle-in-operation stock, inspection enforcement intensity, and technology substitution elasticities across the projection horizon. Segmentation dimensions modeled include duty class, adjuster technology, procurement channel, and installation environment. CAGRs derived from regression against historical replacement cycle data and regulatory compliance cost trajectories. Industry-specific forecast inputs incorporated NHTSA stroke-length tolerance evolution and fleet telematics adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NHTSA regulatory revision timing and scrap metal price volatility. Deviation in NHTSA electronic adjuster mandate adoption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electro-Mech Systems
Rigid Metal Electrical Conduit Market
Electro-Mech Systems
Escalators and Moving Walkways Market
Electro-Mech Systems
Elevator Door-Motor Market
Electro-Mech Systems
Agitator Drive Units Market
Electro-Mech Systems
Electric Overhead Travelling (EOT) Cranes Market
Electro-Mech Systems
Rodless Cylinders Market
Electro-Mech Systems
HVAC Relay Market
Electro-Mech Systems
Light Gauge Framing System Market
Electro-Mech Systems
Mechanical Auger Boring Machine Market
Electro-Mech Systems
Hydraulic Cab Tilt System Market
Electro-Mech Systems
Tubular Motors Market
Electro-Mech Systems
Wiring Duct Market
Electro-Mech Systems
Electric Winch Market
Electro-Mech Systems
Movable Scaffolding System Market