
 Deep Hole Drilling Machines Market | 2026-2036
Deep Hole Drilling Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Deep Hole Drilling Machines Market Intelligence
High-pressure coolant integration is tilting deep hole drilling toward unattended automation and tighter bore tolerances. Tibo Tiefbohrtechnik leverages its German engineering base to dominate precision gundrill systems for medical and aerospace workpieces. Okuma sustains competitive positioning through CNC platform integration that bundles drilling with mill-turn operations. Precihole anchors its presence in India with cost-optimized BTA drilling solutions serving domestic defense and oil field contractors.
Deep hole drilling machines execute holes with length-to-diameter ratios exceeding 10:1, typically using single-lip gundrills or BTA tools fed through high-pressure coolant systems that evacuate chips and stabilize cutting temperatures. CNC Drilling Systems command the largest product segment due to programmable repeatability and reduced setup times across batch production. BTA Drilling Equipment captures expanding share in oil well drilling and large-diameter hydraulic cylinder applications where metal removal rates dominate cycle economics. Hybrid Techniques combining electrical discharge with mechanical drilling are gaining traction in superalloy aerospace structures where conventional cutting faces tool life constraints.
CE marking under the EU Machinery Directive governs safety interlocks and emergency stop protocols for machines sold across Europe, while OSHA lockout/tagout standards shape electrical and pneumatic safeguarding for US installations. ISO 10816 vibration monitoring standards increasingly appear in procurement specifications for predictive maintenance integration. Stakeholders must weigh coolant system architecture against emerging MEE emissions regulations in China and evolving EPA effluent guidelines for metalworking fluids in the United States.
Market Dynamics
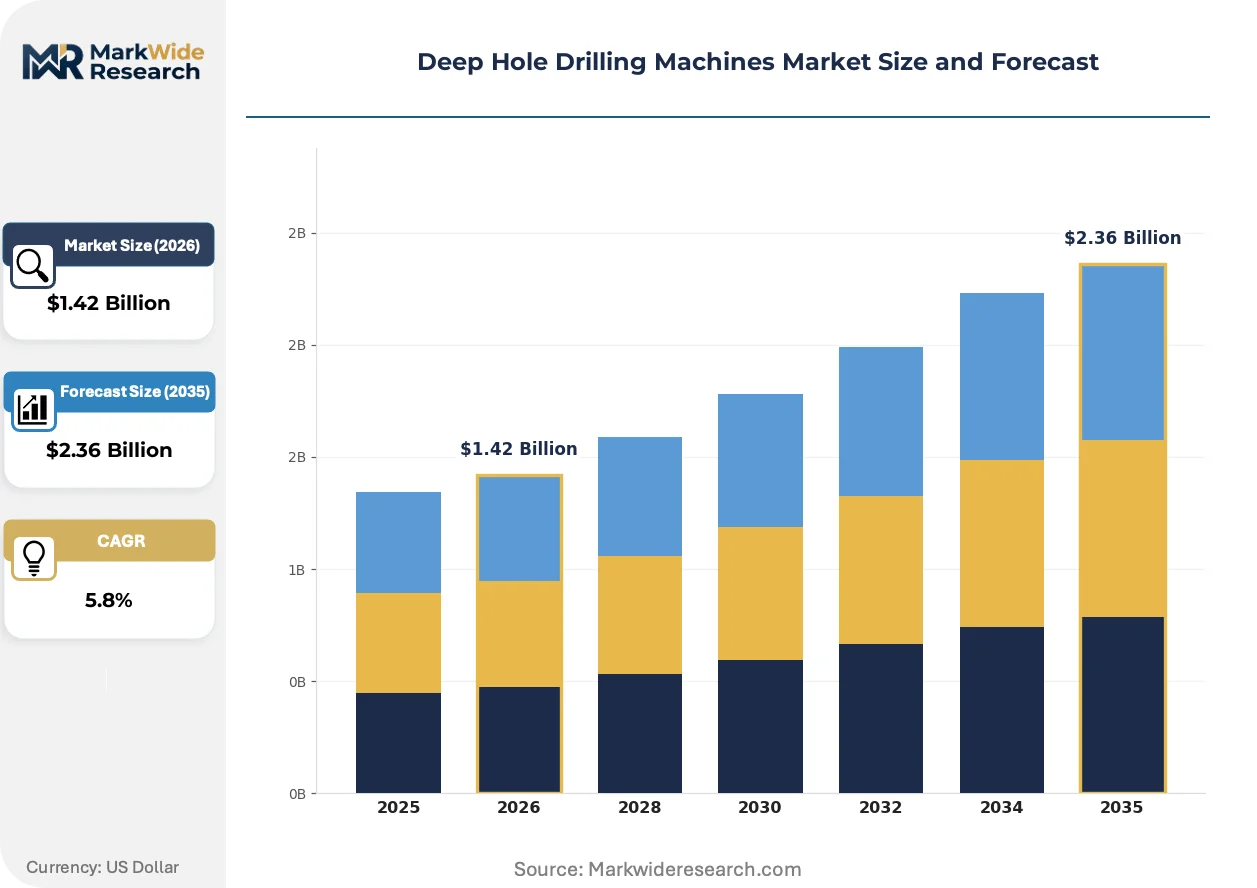
High-pressure coolant architectures and CNC integration are compressing setup times while extending unmanned machining windows, fundamentally altering how manufacturers justify capital deployment in precision drilling operations.
Growth Catalysts
- Aerospace turbine demand:Precision deep hole drilling for nickel superalloy engine components is accelerating as OEMs push thermal efficiency targets. German manufacturing clusters supply specialized gundrill systems to this vertical.
- EU Machinery Directive compliance:CE marking mandates for safety interlocks and emergency stop protocols are standardizing machine architectures, reducing cross-border certification friction for equipment vendors.
- Hybrid EDM-mechanical drilling:Electrical discharge augmentation is penetrating superalloy aerospace structures where conventional cutting faces tool life constraints, opening new application envelopes.
Market Restraints
- Tungsten carbide supply concentration:Cutting tool substrate sourcing clusters in Chinese and Austrian suppliers, exposing machine builders to input cost volatility and geopolitical friction.
- MEE emissions compliance:China's Ministry of Ecology and Environment is tightening coolant mist and effluent standards, forcing architectural redesign of high-pressure delivery systems.
- Additive manufacturing substitution:Directed energy deposition and powder bed fusion are displacing drilled cooling channels in select aerospace heat exchanger applications.
Strategic Opportunities
- Indian defense localization:Cost-optimized BTA drilling solutions can capture volume from domestic oil field contractors and ordnance suppliers under import substitution policies.
- ISO 10816 integration:Vibration monitoring standards are appearing in procurement specifications, creating predictive maintenance attach revenue for machine vendors.
- Mill-turn platform convergence:Bundling deep hole drilling with multi-axis turning is compressing floor space requirements and work-in-process inventory for medical implant manufacturers.
Industry Challenges
- Gundrill regrinding technician scarcity:Single-lip tool geometry restoration requires specialized craft skills that vocational pipelines are failing to replenish at sufficient rates.
- Legacy CNC retrofit complexity:Integrating modern coolant-through spindles with aging machine architectures demands custom mechanical engineering that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deep Hole Drilling Machines Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Drilling Machines, CNC Drilling Systems, Rotary Drilling Machines, BTA Drilling Equipment Technology: High-Pressure Coolant, Hybrid Techniques, Electrical Discharge Machining, Ultrasonic Drilling End User: Aerospace, Automotive, Oil & Gas, Defense Application: Tool Manufacturing, Component Fabrication, Oil Well Drilling, Aerospace Structures |
| Companies Covered | Tibo Tiefbohrtechnik, Okuma, Precihole, Waldrich Coburg, Mazak, DeHoff (Kays Engineering), Sunnen Products Company, Fives Group, TARUS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deep Hole Drilling Machines Market Strategic Shifts & Innovations
Digital twin architectures and real-time process monitoring are virtualizing machine behavior before metal cutting begins, compressing trial-and-error cycles that historically dominated deep hole drilling process development.
Sensor-embedded gundrills with wireless telemetry are virtualizing tool condition monitoring, transmitting vibration and temperature data to cloud analytics platforms. Aerospace precision machine shops in Germany and the United States are piloting these systems for unmanned night shifts. The technology is virtualizing the role of floor supervisors, enabling single operators to oversee multiple cells simultaneously.
EPA effluent guidelines for metalworking fluids are tightening discharge limits for facilities in the United States, forcing coolant system redesigns toward closed-loop filtration. Machine builders are responding with vacuum-assisted chip evacuation that reduces fluid carryout. Oil well drilling contractors in Texas and North Dakota are prioritizing equipment with this architecture to preempt regulatory enforcement.
Service unbundling is fragmenting the traditional machine sale, with buyers separating hardware procurement from process parameter optimization contracts. Medical device manufacturers in Switzerland and Japan are engaging independent drilling specialists to program their acquired machines rather than relying on vendor applications teams. This pattern concentrates in high-mix, low-volume production environments where part-specific expertise outweighs generic machine training.
Deep Hole Drilling Machines Market Segmentation
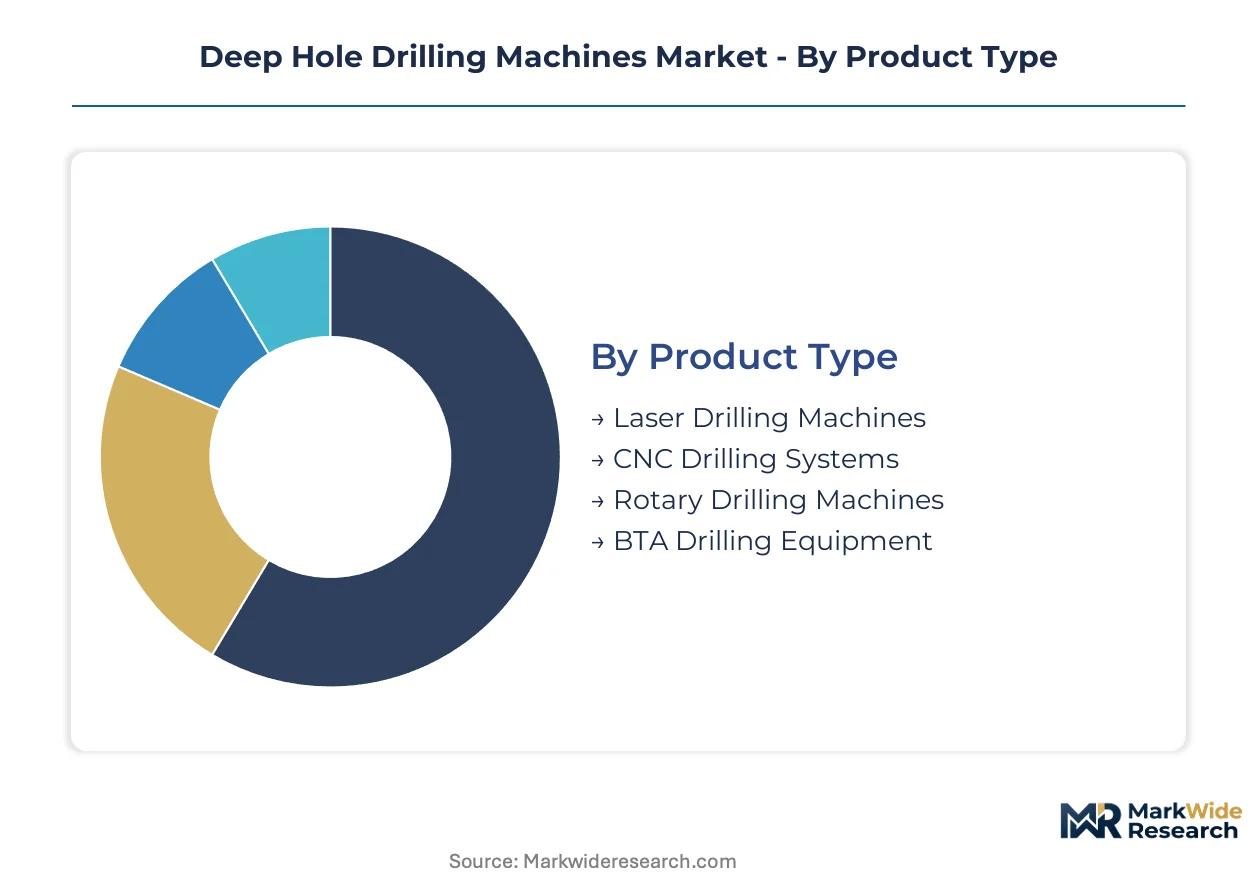
Deep hole drilling machines serve divergent precision requirements across aerospace turbine blades, automotive fuel injectors, and oil well casings. Segment boundaries reflect trade-offs between programmable flexibility, metal removal rates, and coolant system architecture.
Product Type:
Machine configurations span from programmable multi-axis platforms to dedicated rotary systems optimized for specific length-to-diameter ratios.
- CNC Drilling Systems:Programmable multi-axis platforms integrate with mill-turn centers for medical implant and aerospace component batches. German precision machine shops specify these systems for nickel superalloy turbine blades requiring repeatability across unmanned shifts.
- BTA Drilling Equipment:Boring and trepanning association tools feed coolant through the tool body for high metal removal in large-diameter hydraulic cylinders. Indian oil field contractors and defense ordnance suppliers under import substitution policies are expanding procurement of these systems.
- Laser Drilling Machines:Thermal ablation systems machine cooling holes in turbine airfoils without mechanical tool contact.
- Rotary Drilling Machines:Conventional spindle architectures serve cost-sensitive applications with less stringent straightness tolerances.
Established volume favors CNC Drilling Systems; emerging adoption favors BTA Drilling Equipment.
Technology:
Process innovations address tool life limitations in superalloys and coolant emissions compliance.
- High-Pressure Coolant:Delivered at pressures exceeding 200 bar through tool channels, this architecture evacuates chips and stabilizes cutting temperatures in gundrill operations. EPA effluent guidelines in the United States and MEE emissions standards in China are forcing architectural redesigns toward closed-loop filtration.
- Hybrid Techniques:Electrical discharge augmentation combined with mechanical drilling penetrates gamma titanium aluminide and single-crystal superalloys where conventional cutting faces catastrophic tool wear. Aerospace structures with internal cooling channel networks in Germany and the United States are piloting these methods.
- Electrical Discharge Machining:Spark erosion processes machine conductive materials without cutting force, preserving thin-walled geometries.
- Ultrasonic Drilling:High-frequency vibration superposition reduces cutting forces in brittle ceramic matrix composites.
Process maturity favors High-Pressure Coolant; steepest expansion trajectory belongs to Hybrid Techniques.
End User:
Vertical demand patterns concentrate in precision-critical and regulated industries.
- Aerospace:Turbine engine OEMs and tier suppliers demand length-to-diameter ratios exceeding 100:1 for cooling channels in nickel superalloy combustors. FAA airworthiness standards and EASA certification requirements propagate these specifications through supply chains in the United States and Europe.
- Defense:Domestic sourcing mandates in India and geopolitical supply chain restructuring are redirecting procurement toward localized BTA drilling capacity for artillery barrels and armor components.
- Automotive:Fuel injection systems and transmission valve bodies require precision deep holes in hardened steels.
- Oil & Gas:Directional drilling contractors specify robust equipment for downhole tool manufacturing and well completion hardware.
Technology pull favors Aerospace; policy tailwinds favor Defense.
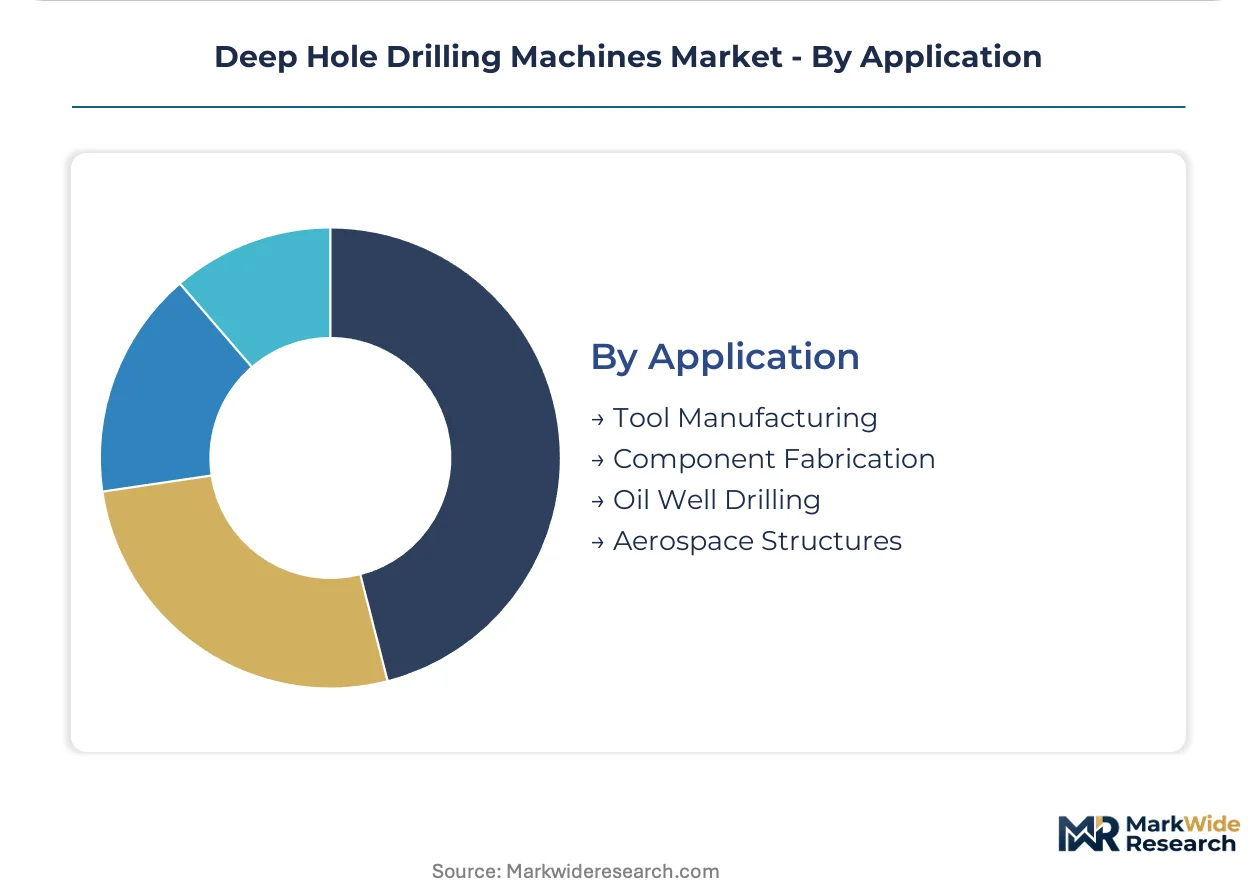
Application:
Use cases differentiate between tool production, finished component fabrication, and energy extraction infrastructure.
- Aerospace Structures:Wing spars, landing gear struts, and engine mounts incorporate deep holes for hydraulic routing and weight reduction. CE marking under the EU Machinery Directive governs safety interlocks for equipment serving this vertical in Europe.
- Oil Well Drilling:Drill collar and heavy weight drill pipe manufacturing demands BTA equipment capable of handling 30-foot workpieces. Texas and North Dakota contractors prioritize vacuum-assisted chip evacuation to preempt EPA enforcement on metalworking fluid discharge.
- Tool Manufacturing:Gun drills and reamers require precision holes for coolant delivery in their own production.
- Component Fabrication:General precision machining shops serve diversified industrial demand.
Specification intensity favors Aerospace Structures; volume scale favors Oil Well Drilling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision machine tool exports flow primarily to aerospace clusters in the United States and defense contractors in India, establishing a trade corridor that shapes regional equipment specifications and compliance requirements.
United States
Aerospace turbine OEMs in Connecticut and Texas drive demand for nickel superalloy drilling systems with length-to-diameter ratios exceeding 100:1. FAA airworthiness standards propagate these specifications through tier supplier networks. Wichita, Kansas and Hartford, Connecticut host precision machining clusters where unmanned night shifts operate sensor-embedded gundrill systems.
Germany
Advanced manufacturing clusters in Baden-Württemberg and Bavaria supply specialized gundrill systems to global aerospace and medical device markets. CE marking under the EU Machinery Directive governs safety interlocks and emergency stop protocols for equipment sold across Europe. Stuttgart and Munich anchor precision machine tool production serving turbine engine manufacturers worldwide.
India
Domestic defense localization policies redirect procurement toward localized BTA drilling capacity for artillery barrels and ordnance components. Import substitution mandates under the PLI scheme accelerate capacity buildout among domestic machine tool fabricators. Pune and Bengaluru host emerging precision manufacturing clusters serving oil field contractors and defense suppliers.
China
Domestic machine tool builders capture volume in standard BTA equipment for hydraulic cylinder and oil well drilling applications. MEE emissions standards tighten coolant mist and effluent requirements, forcing architectural redesign of high-pressure delivery systems. Shanghai and Shenyang anchor manufacturing clusters where closed-loop filtration systems are becoming procurement prerequisites.
Japan
Medical device manufacturers in Osaka and Nagoya demand mill-turn platforms bundling deep hole drilling with multi-axis turning for implant production. METI industrial policy supports precision machining technology development through subsidized R&D consortia. Tokyo-Yokohama clusters specialize in high-mix, low-volume production environments requiring programmable repeatability.
Deep Hole Drilling Machines Market Key Industry Players
On the supply side, the industry is tiered between precision specialists serving aerospace and medical verticals and scale-oriented fabricators addressing oil field and defense volume. German engineering-intensive players occupy the premium tier, while Indian and Chinese builders compete on cost-optimized architectures. Strategic moves center on geographic expansion into defense localization markets and technology licensing for hybrid EDM-mechanical process integration.
Among German precision specialists, Tibo Tiefbohrtechnik and Waldrich Coburg exemplify the engineering-intensive archetype serving aerospace turbine applications. Japanese CNC platform builders including Okuma and Mazak occupy positions bundling drilling with mill-turn operations. At the cost-optimized end, Precihole represents Indian fabricators capturing volume from domestic defense and oil field contractors under import substitution policies.
| Leading Market Players |
|---|
| Tibo Tiefbohrtechnik |
| Okuma |
| Precihole |
| Waldrich Coburg |
| Mazak |
| DeHoff (Kays Engineering) |
| Sunnen Products Company |
| Fives Group |
| TARUS |
| Others |
Cost & Logistics Intelligence
Undercapacity in Indian defense machine tool fabrication is compressing supplier margins while inflating delivery premiums for BTA drilling systems, creating divergent pricing postures between cost-optimized domestic builders and German engineering-intensive exporters.
Pricing Analysis
Technology-generation pricing gaps separate sensor-embedded gundrill systems with wireless telemetry from conventional CNC platforms and legacy mechanical architectures. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking certification intensity, coolant system architecture sophistication, and after-sales service bundling. Cost compression in standard-tier equipment is intensifying because Indian and Chinese fabricators are expanding capacity for hydraulic cylinder applications. Defense contractors in India exhibit highest price sensitivity due to fixed-budget procurement protocols, while aerospace turbine OEMs in Germany and the United States prioritize performance guarantees over unit cost.
Supply Chain Analysis
Export-control regimes limiting flows of high-precision spindle bearings and linear motion systems from Germany and Japan constrain capacity expansion among second-tier machine builders. Tungsten carbide substrate sourcing draws from Chinese and Austrian suppliers, while high-pressure coolant pumps and filtration systems rest on German and Italian component flows. Single-source vulnerability concentrates in gamma titanium aluminide cutting tool coatings for superalloy aerospace applications. Distribution runs through OEM-direct channels for large aerospace contracts and specialized machine tool distributors serving mid-tier precision shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Additive manufacturing substitution for internal cooling channels in aerospace heat exchangers threatens drilling volume, forcing incumbents to defend application scope through hybrid process integration.
For Market Incumbents: Entrench proprietary positions in sensor-embedded gundrill telemetry by acquiring wireless data analytics specialists, while backward integration into tungsten carbide substrate production mitigates Chinese supply volatility. CE marking certification investments create switching costs for European aerospace customers facing EU Machinery Directive audits. For New Entrants and Emerging Players: Establish a beachhead in Indian defense BTA drilling by partnering with domestic fabricators under PLI scheme localization mandates, targeting artillery barrel and ordnance component contracts. Process parameter optimization service unbundling offers a go-to-market angle for medical device manufacturers in Switzerland and Japan seeking independent drilling expertise. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among machine builders bundling predictive maintenance contracts with hardware sales, as ISO 10816 vibration monitoring standardization creates attach-rate expansion. Long-term viability over a five-to-ten year window favors precision specialists with aerospace medical dual-vertical exposure. Watch hybrid EDM-mechanical drilling adoption rates in single-crystal superalloy applications as inflection signal for next-generation platform displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Process Integration | EDM-mechanical drilling penetration in gamma titanium aluminide preserves aerospace application scope against additive substitution. |
| Sensor-Embedded Tool Development | Wireless telemetry gundrills enable unmanned night shifts for German precision shops facing technician scarcity. |
| Defense Localization Partnerships | Indian PLI scheme alignment captures artillery barrel and ordnance volume under import substitution mandates. |
| Closed-Loop Coolant Architecture | Vacuum-assisted chip evacuation preempts EPA enforcement for Texas and North Dakota oil well drilling contractors. |
| Predictive Maintenance Platform | ISO 10816 vibration monitoring bundling generates attach revenue from medical implant manufacturers in Japan. |
Research Approach
Initial hypotheses were tested against primary input from maintenance directors at aerospace precision shops, OEM procurement teams specifying turbine component equipment, aftermarket service heads at German machine tool builders, and defense ordnance procurement officers in India, then refined against customs trade data, SEC filings from listed industrial equipment manufacturers, EU Machinery Directive implementation reports, and production statistics from Baden-Württemberg manufacturing clusters. Bottom-up segment sizing triangulated with top-down macro industrial production indices validated volume estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling CNC drilling systems, BTA equipment, laser drilling machines, and rotary systems against high-pressure coolant, hybrid EDM-mechanical, and ultrasonic technology penetration curves. Aerospace turbine demand intensity, defense localization policy implementation rates, and MEE emissions compliance timelines served as industry-specific forecast inputs. CAGRs derived from segment-level growth rate reconciliation with macro machinery investment cycles.
Stress conditions across tungsten carbide price volatility, additive manufacturing substitution rates, and EU Machinery Directive enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding aerospace production ramp schedules and defense procurement continuity. Material shifts in PLI scheme localization requirements or EPA effluent guideline enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
US Waterjet Cutting Machines Market
Construction Equipment
Hybrid Construction Equipment Market
Construction Equipment
Mobile Light Tower Market
Construction Equipment
Demolition Vessels Market
Construction Equipment
Compact Loaders Market
Construction Equipment
Global Scaffolding Market
Construction Equipment
Welding Equipment Market
Construction Equipment
Heavy Construction Equipment Market
Construction Equipment
Road Marking Equipment Market
Construction Equipment
Crane Rail Market
Construction Equipment
Track Mounted Gangway Market
Construction Equipment
Portable Welding Generators Market
Construction Equipment
Europe Stud Welding Machine Market
Construction Equipment
Earthmoving Equipment Market
Construction Equipment
Rockbreakers Market
Construction Equipment
Grinding Machinery Market