
 Platform Screen Door System Market | 2026-2036
Platform Screen Door System Market Size, Share, and Industry Trends Forecast 2026-2036
Platform Screen Door System Market Analysis
Metro systems is shifting toward fully automated lines with climate-controlled platforms, drawing investment from specialized engineering firms. Nabtesco Corporation leverages precision motion control expertise to dominate high-reliability door mechanisms for Asian transit networks. Fangda Group anchors its position through vertical manufacturing integration spanning aluminum extrusion to final assembly. Shanghai Jiacheng Railway International specializes in turnkey platform edge solutions for China's accelerating subway build-out.
A platform screen door system comprises mechanically interlocking barrier panels installed along station platform edges, typically fabricated from tempered safety glass and aluminum framing with integrated sensing arrays and programmable logic controllers. These systems create a sealed partition between passenger waiting areas and train tracks, enabling HVAC containment, suicide prevention, and debris exclusion while synchronizing door operation with rolling stock arrival. Automatic product types capture the dominant share as urban rail operators prioritize unattended train operation compatibility, while retrofit installations represent the fastest-expanding segment where legacy stations require barrier upgrades without structural reconstruction. Manual and semi-automatic variants retain niche positions in budget-constrained markets and heritage rail contexts where full automation remains economically prohibitive.
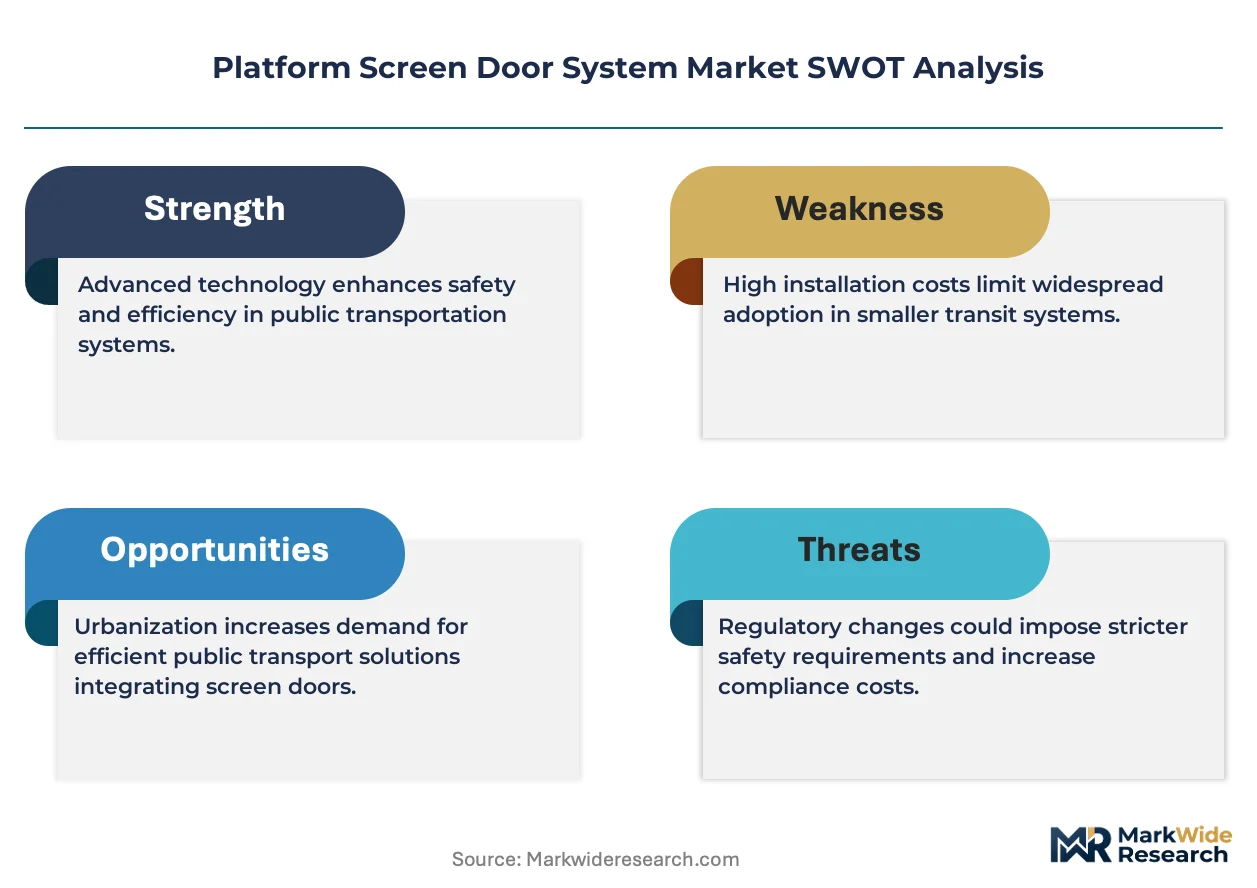
China's GB standards for urban rail safety and the EU's CE marking requirements under the Machinery Directive shape product certification pathways and cross-border market access for door system manufacturers. Japan's METI energy efficiency guidelines and the F-Gas Regulation in Europe further influence material selection for door sealing components and drive system specifications. Stakeholders must monitor evolving national rail safety mandates and electrification timelines to align R&D roadmaps with procurement cycles that extend across multi-year infrastructure planning horizons.
Market Dynamics
Urban rail operators are converging on fully automated train operation, forcing platform screen door manufacturers to synchronize barrier systems with driverless rolling stock control architectures. This operational shift compresses procurement cycles and elevates reliability specifications above cost considerations.
Growth Catalysts
- China's dual carbon goals:The Ministry of Ecology and Environment mandates energy-efficient transit infrastructure, accelerating electrified subway builds that bundle platform screen doors as standard equipment.
- Unattended train operation compatibility:Metro systems in dense corridors require barrier systems that interface with centralized traffic control, creating specification pull for automatic door mechanisms.
- Retrofit installations:Legacy stations without structural reconstruction capacity drive demand for modular barrier upgrades that seal platform edges without foundation work.
Market Restraints
- Tempered safety glass supply concentration:Specialty glass fabrication clusters in East Asian manufacturing hubs, exposing procurement to regional logistics disruptions.
- GB standards compliance friction:China's urban rail safety certification requires extensive in-country testing, extending market access timelines for foreign manufacturers.
- Escalating aluminum framing costs:Primary aluminum price volatility directly impacts platform screen door bill-of-materials, compressing margin on fixed-price transit contracts.
Strategic Opportunities
- India's urban rail expansion:Metro construction in tier-one cities lacks indigenous platform screen door manufacturing, creating import substitution openings for established Asian suppliers.
- HVAC containment integration:Converging climate control and barrier systems allows door manufacturers to capture platform environmental management value previously held by separate contractors.
- EU F-Gas Regulation alignment:Door sealing material specifications that eliminate high-global-warming-potential compounds qualify for green public procurement preference in European transit tenders.
Industry Challenges
- Programmable logic controller programming expertise:Shortage of rail-certified automation engineers delays commissioning and extends project handover timelines.
- Legacy signaling system interfacing:Older metro networks operate proprietary communication protocols, forcing costly custom integration work for each retrofit installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Platform Screen Door System Market |
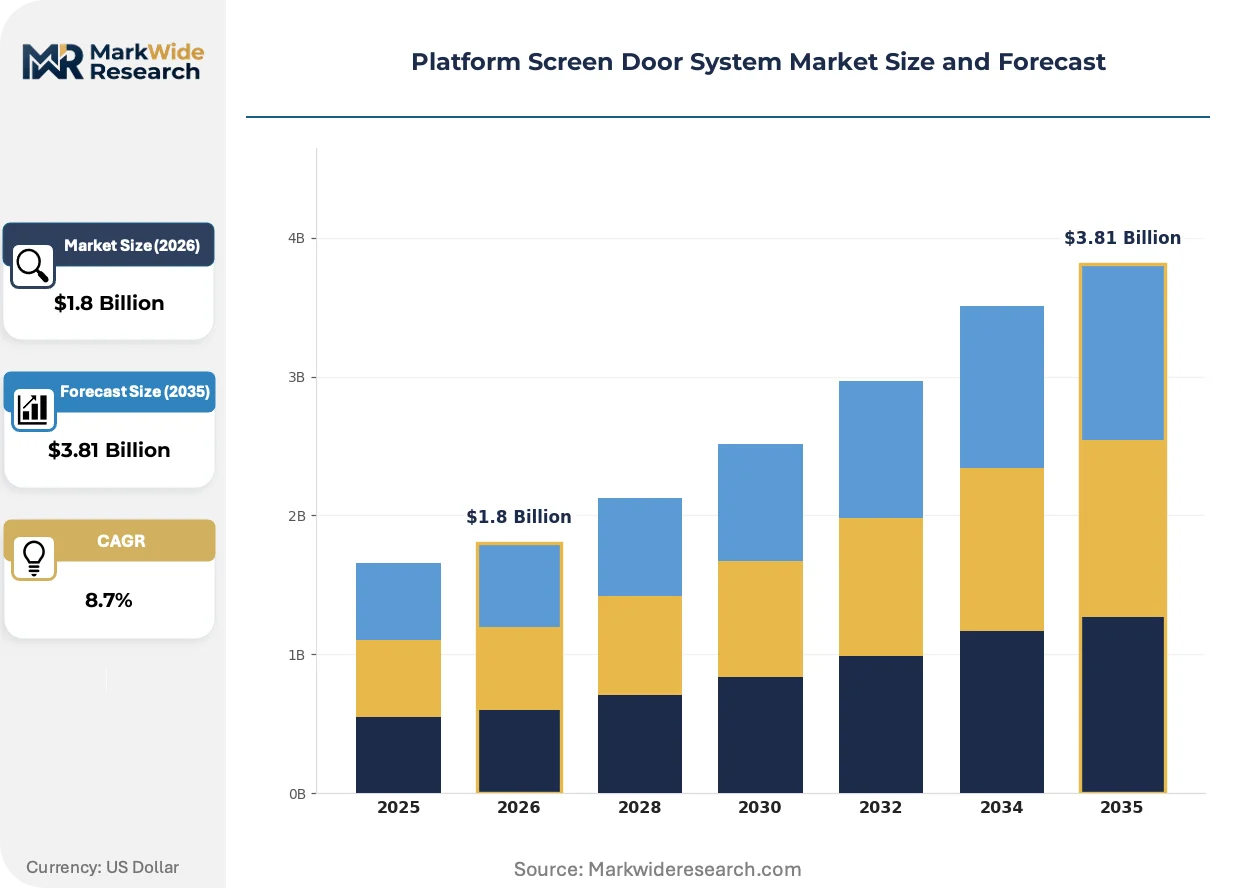
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Manual, Semi-Automatic, Custom Installation Type: New Build, Retrofit, Modular, Expansion End User: Transportation Agencies, Metro Systems, Airports, Rail Operators Operation Mode: Passive, Active, Hybrid, Emergency |
| Companies Covered | Shanghai Jiacheng Railway International, Stanley Access Technologies, Nabtesco Corporation, Manusa, Gilgen Door Systems, Fangda Group, Horton Automatics, Nanjing Kangni, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Platform Screen Door System Market Emerging Trajectories
Platform screen door technology is bifurcating between premium fully automated systems and cost-optimized modular retrofits, with control architecture choices determining competitive positioning more than mechanical design differentiation.
Edge computing-enabled sensing arrays are decentralizing diagnostic and safety decision-making away from centralized station control rooms. Asian transit operators deploying driverless lines are adopting these distributed architectures fastest. This shift is decentralizing maintenance responsibility to door subsystem vendors and compressing response times for fault isolation.
Europe's F-Gas Regulation is banning hydrofluorocarbon-based sealing compounds from 2027, forcing material reformulation across door gasket supply chains. Manufacturers are qualifying silicone and EPDM alternatives that maintain pressure integrity across temperature cycling. The regulation most affects retrofit projects in Germany and France, where existing gasket inventories must be exhausted before compliant replacements enter service.
Transit authorities are unbundling lifecycle service contracts from initial equipment procurement, creating standalone aftermarket revenue streams for specialized maintenance firms. Door mechanism overhaul and glass replacement are separating from original manufacturer relationships. This pattern is most advanced in Japan, where METI guidelines encourage competitive servicing to reduce long-term public infrastructure costs.
Platform Screen Door System Market Segmentation
Platform screen door procurement patterns diverge sharply between greenfield metro construction and legacy station modernization, with specification requirements varying by automation level and climate control integration. Understanding these segment boundaries clarifies where engineering complexity concentrates and where cost-optimized solutions gain traction.
Product Type:
Retrofit cycles and unattended train operation rollouts are reshaping product specifications across transit networks, with reliability premiums commanding procurement priority over initial capital outlay.
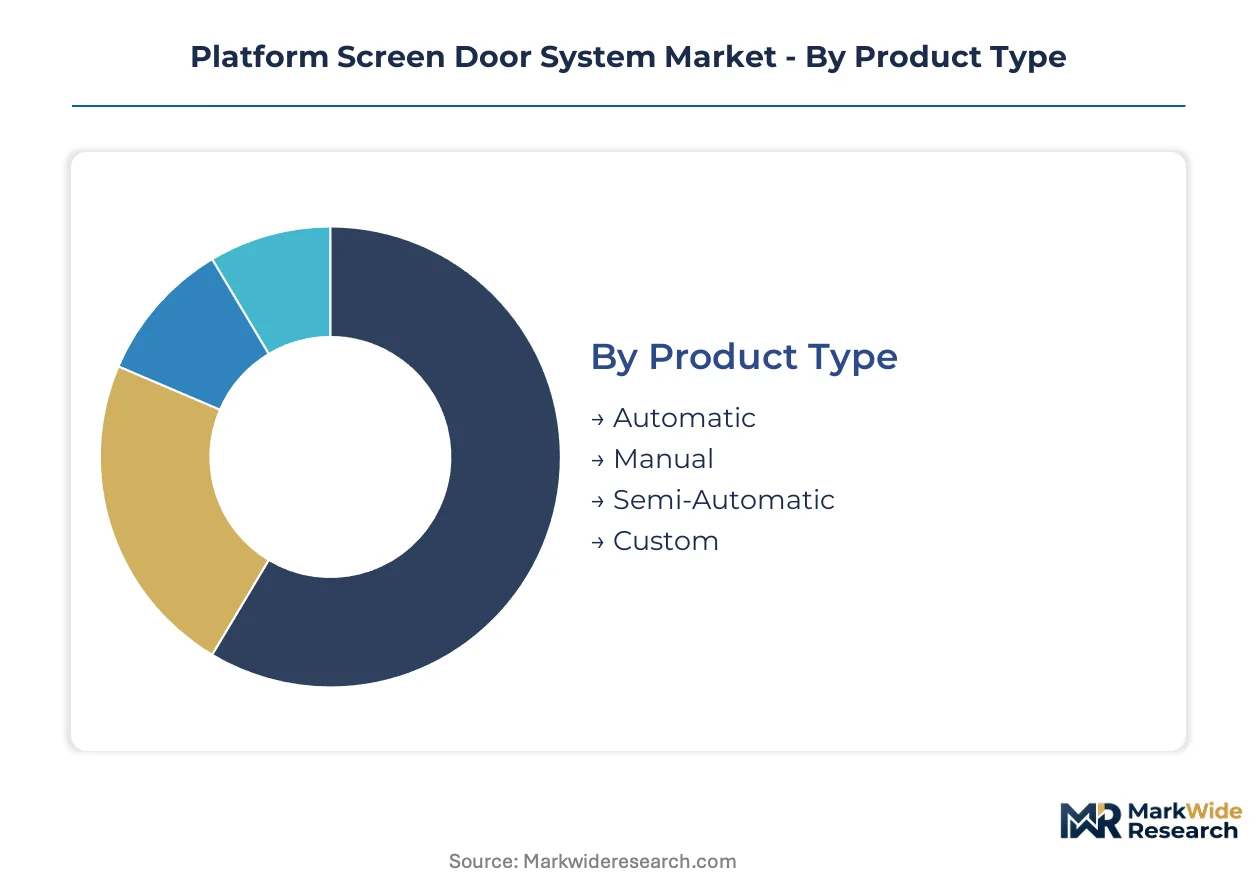
- Automatic:These systems integrate programmable logic controllers with centralized traffic management for driverless operation, synchronizing barrier movement with rolling stock positioning. Metro systems in China's tier-one cities specify automatic doors as standard for new subway lines, driven by MEE mandates for fully electrified, unattended infrastructure.
- Manual:Station staff operate barrier panels through local control interfaces, requiring human verification of train alignment before release. Heritage rail operators in budget-constrained markets deploy manual variants where automation investment exceeds operational savings.
- Semi-Automatic:Hybrid control architectures combine automated sensing with operator override capabilities for exceptional conditions.
- Custom:Bespoke engineering addresses non-standard platform geometries or specialized climate sealing requirements.
Volume placements concentrate in Automatic; the faster expansion belongs to Custom.
Installation Type:
Cost tier differentiation separates foundation-dependent deployments from surface-mounted alternatives, with structural constraints dictating viable upgrade pathways.
- New Build:Integrated platform edge construction embeds door mechanisms and sensing arrays during station shell erection, enabling seamless HVAC containment and optimized traffic flow design. Greenfield metro projects in India and Southeast Asia bundle screen doors with initial infrastructure procurement.
- Retrofit:Modular barrier systems attach to existing platform edges without structural modification, sealing track access while preserving original concrete work. Legacy stations across Europe's established networks drive demand as F-Gas Regulation compliance forces gasket replacement cycles.
- Modular:Prefabricated panel assemblies reduce on-site installation duration for capacity-constrained construction windows.
- Expansion:Incremental door deployment extends coverage as platform lengthening accommodates longer train formations.
New Build captures the largest contract values; Retrofit is climbing the fastest as aging infrastructure reaches replacement horizons.
End User:
Customer type determines specification stringency, with public safety mandates varying across regulatory jurisdictions and operational risk profiles.
- Metro Systems:Urban rail operators specify platform screen doors for suicide prevention, climate control efficiency, and debris exclusion in high-frequency service corridors. China's subway network extensions under dual carbon targets represent the dominant demand concentration globally.
- Transportation Agencies:Multi-modal authorities coordinate barrier standardization across integrated transit networks, prioritizing interoperability.
- Rail Operators:Intercity and commuter services adopt modified platform edge protection for selective high-traffic stations.
- Airports:Automated people mover systems at hub airports deploy compact screen door variants for climate-controlled terminal connections.
Metro Systems absorb the deepest volume; Airports are gaining share fastest as APM deployments multiply.
Operation Mode:
Margin structures vary by system complexity, with distributed intelligence architectures commanding premium positioning against centralized alternatives.
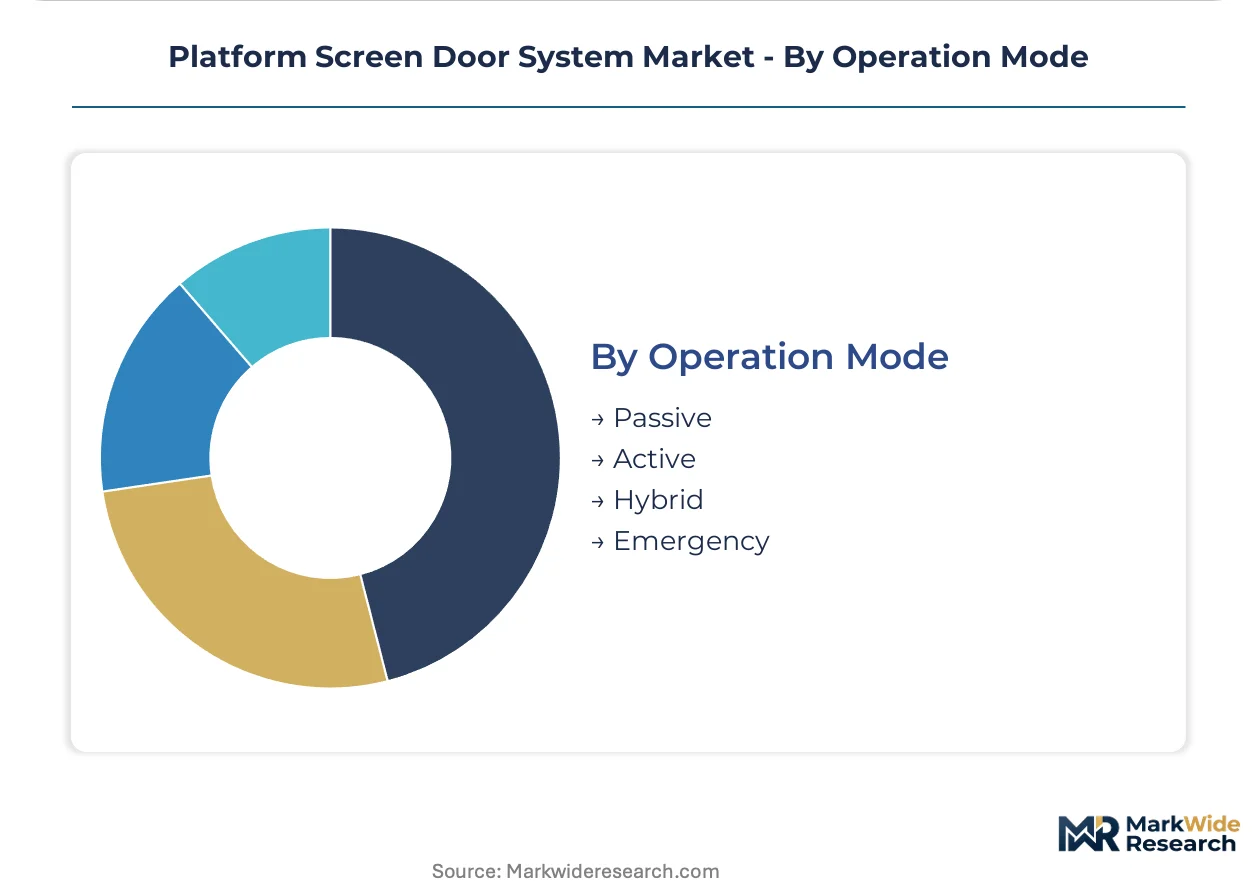
- Active:Real-time sensor networks continuously monitor platform edge conditions, triggering barrier response without centralized command latency. Asian transit operators deploying driverless lines favor active systems for fault isolation speed.
- Passive:Mechanical interlocks and pressure-sensitive edges provide baseline protection without continuous electronic supervision.
- Hybrid:Dual-mode architectures switch between active monitoring and passive fallback during system maintenance or emergency conditions.
- Emergency:Rapid-release mechanisms enable manual barrier override for evacuation scenarios, required by GB standards and EU Machinery Directive compliance.
Active systems dominate new procurement; Hybrid configurations show the steepest expansion trajectory as operators seek operational flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangshan Deep Water Port's bonded logistics zones concentrate specialty glass and aluminum component stockpiles for transit infrastructure suppliers serving Asia-Pacific build-outs.
China
Beijing and Shanghai subway extensions absorb the deepest procurement volumes for automatic platform screen doors under MEE electrification mandates. GB standards for urban rail safety require extensive in-country testing, extending certification timelines for foreign manufacturers. Shenzhen's manufacturing clusters supply tempered safety glass and aluminum framing to door system assemblers in the Pearl River Delta.
Japan
Tokyo Metro and Osaka Municipal Subway drive demand for edge-computing-enabled sensing arrays on driverless lines. METI energy efficiency guidelines influence material selection for door sealing components and drive system specifications. Kansai industrial corridors host precision motion control engineering firms supplying high-reliability door mechanisms.
Germany
Berlin and Munich retrofit programs upgrade legacy stations with F-Gas-compliant gasket materials ahead of the 2027 ban. CE marking requirements under the EU Machinery Directive shape product certification pathways for barrier system manufacturers. Ruhr Valley industrial zones fabricate aluminum framing and programmable logic controller assemblies for European transit networks.
India
Delhi Metro and Mumbai Metro Corporation specify platform screen doors for new-build corridors lacking indigenous manufacturing capacity. The country's national rail safety regulator mandates suicide prevention barriers for high-frequency urban lines. Gujarat's special economic zones attract component suppliers serving import substitution opportunities in tier-one city expansions.
United States
New York MTA and Washington Metro evaluate retrofit barriers for climate-controlled platform environments. The Federal Transit Administration's safety directives influence procurement specifications for automated people mover systems at hub airports. Chicago's freight rail manufacturing heritage supports specialized engineering consultancies for transit door integration projects.
Platform Screen Door System Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with precision engineering firms commanding premium positioning in high-reliability automatic systems while aluminum fabricators compete on cost for modular retrofit installations. Market concentration varies by automation tier, with unattended train operation compatibility requirements filtering out generalist suppliers. Three archetypes dominate: Japanese precision motion control specialists, Chinese vertically integrated metalwork conglomerates, and European sealing technology providers. Competitive moves center on backward integration into specialty glass supply and geographic expansion through rail project joint ventures in Southeast Asia and the Middle East.
Among Japanese precision engineering houses, Nabtesco Corporation occupies a position exemplifying high-reliability door mechanism specialization for Asian transit networks. Chinese fabricators Fangda Group and Shanghai Jiacheng Railway International represent contrasting approaches to vertical manufacturing integration and turnkey platform edge solutions respectively. These three anchors illustrate how control architecture expertise and captive aluminum extrusion capacity determine competitive positioning more than mechanical design differentiation alone.
| Leading Market Players |
|---|
| Shanghai Jiacheng Railway International |
| Stanley Access Technologies |
| Nabtesco Corporation |
| Manusa |
| Gilgen Door Systems |
| Fangda Group |
| Horton Automatics |
| Nanjing Kangni |
| Panasonic Corporation |
| Others |
Supply Flow & Price Mechanics
Captive aluminum extrusion capacity in Chinese manufacturing clusters anchors both supply security and pricing power for platform screen door assemblers serving Asia-Pacific transit build-outs. This backward integration into primary metalwork insulates tier-one suppliers from commodity volatility while compressing procurement timelines for state-backed metro projects.
Pricing Analysis
Short lead-time premiums command pricing power for automatic door systems synchronizing with driverless rolling stock deployments in China's tier-one cities. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified European mechanisms from GB-compliant domestic assemblies and modular retrofit kits. Pricing pressure stems from fixed-price transit contracts absorbing aluminum framing cost volatility. Budget-constrained heritage rail operators exhibit highest price sensitivity; unattended train operation mandates render metro authorities least sensitive.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from state transit authorities, bypassing distribution intermediaries for multi-station procurement bundles. Tempered safety glass fabrication concentrates in China, Japan, and South Korea; aluminum framing draws from Pearl River Delta extrusion mills. Supply chain risk centers on single-source vulnerability for specialty glass substrates. Distribution runs through project-specific joint ventures pairing mechanism specialists with local installation contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story: China's GB standards for urban rail safety erect testing-duration barriers that extend market access timelines for foreign manufacturers, entrenching domestic incumbents with in-country certification infrastructure.
For Market Incumbents: Cement position through captive supply of tempered safety glass and aluminum framing to defend margin against commodity volatility. Deepen backward integration into programmable logic controller programming expertise to address rail-certified automation engineer shortages threatening project handover timelines. Monitor emerging Indian metro procurement for import substitution openings by emerging Asian suppliers. For New Entrants and Emerging Players: Launch via modular retrofit distribution partnerships targeting Europe's F-Gas Regulation-driven gasket replacement cycles in Germany and France. White-space concentrates in India's tier-one city metro expansions lacking indigenous platform screen door manufacturing; penetrate through joint ventures with Gujarat special economic zone component suppliers. Position on HVAC containment integration to capture platform environmental management value from separate contractors. For Investors and Strategic Acquirers: Exit pathways concentrate in precision motion control engineering acquisitions by diversified industrial conglomerates seeking rail automation exposure. Long-term viability favors vertically integrated assemblers with captive metalwork and certified control architecture expertise. Watch India's national rail safety regulator mandates for suicide prevention barriers as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Glass Supply | Captive tempered safety glass capacity insulates margin from East Asian logistics disruptions. |
| GB Standards Certification Infrastructure Investment | In-country testing capabilities accelerate market access for China's urban rail procurement cycles. |
| HVAC Containment System Integration | Converging climate control and barrier systems captures platform environmental management value. |
| Edge Computing Sensing Array Development | Distributed diagnostic architectures align with Asian transit operator driverless line deployments. |
| Lifecycle Service Contract Unbundling | Standalone aftermarket revenue streams separate door mechanism overhaul from original manufacturer relationships. |
Methodological Framework
Multi-period observation of metro procurement cycles, aluminum price volatility, and regulatory compliance timelines anchored the trend analysis, supplemented by interviews with transit authority engineering directors, platform screen door procurement managers, rail-certified automation engineers, and HVAC systems integrators. Secondary validation drew from Ministry of Ecology and Environment electrification mandates, GB standards documentation, EU Machinery Directive filings, METI energy efficiency guidelines, and customs trade data for specialty glass and aluminum components. Bottom-up project pipeline aggregation triangulated against top-down infrastructure spending forecasts.
Input-output matrices modeled platform screen door demand across product type, installation mode, end user category, and operation mode dimensions throughout the forecast period. CAGRs derived from regression analysis of historical metro extension timelines against electrification policy trajectories. Industry-specific forecast inputs incorporated unattended train operation rollout schedules and F-Gas Regulation compliance deadlines for sealing material specifications.
The model assumes a particular technology adoption path; alternative pathways for edge computing-enabled distributed sensing architectures would alter the outlook for centralized control system demand. Forecasts reflect assumptions regarding aluminum price stabilization, GB standards enforcement consistency, and India metro construction pace. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Global HVAC Controls Market
Building Automation Systems
Building Automation System Market
Building Automation Systems
Computer-Aided Facility Management (CAFM) Market
Building Automation Systems
Smart Building Solutions Market
Building Automation Systems
Rotary Sprinkler System Market
Building Automation Systems
Global Platform Screen Doors for Subway Lines Market
Building Automation Systems
Integrated Building Management Systems Market
Building Automation Systems
Automated Infrastructure Management (AIM) Solutions Market
Building Automation Systems
Intelligent Building Automation Technologies Market
Building Automation Systems
Elevator Modernization Market
Building Automation Systems
Automated Daylight Harvesting Systems Market
Building Automation Systems
Building Automation and Control System Market
Building Automation Systems
Building Information Management System Market
Building Automation Systems
Underfloor Heating Actuator Market
Building Automation Systems
Dumbwaiter Lifts Market
Building Automation Systems
Global Modularization Market