
 Building Automation System Market | 2026-2036
Building Automation System Market Size, Share, and Industry Trends Forecast 2026-2036
Building Automation System Market Analysis
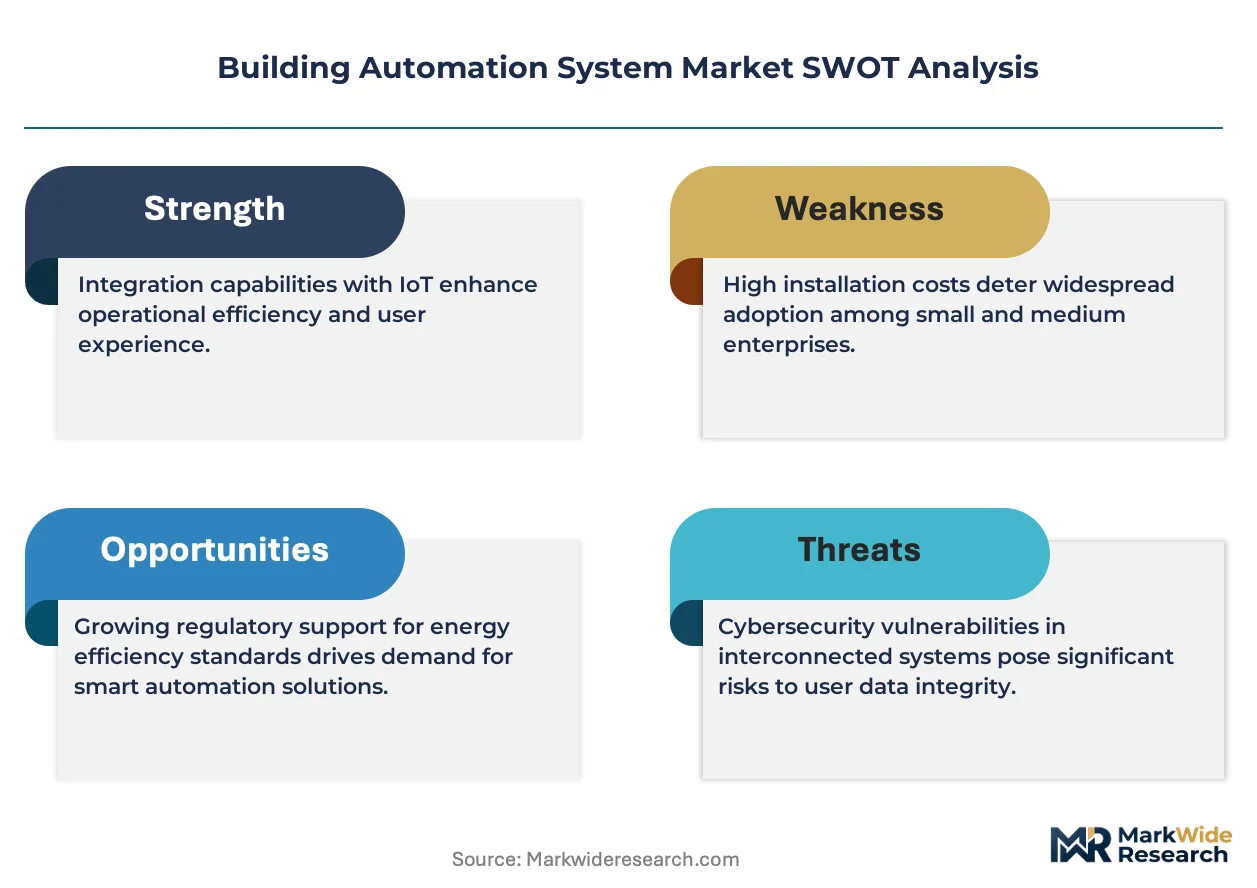
The performance gap between premium integrated platforms and commodity point solutions is expanding. Johnson Controls International plc leverages its captive supply of sensors and controllers to dominate high-performance commercial installations. Siemens AG anchors its position through deep backward integration into building energy analytics software. Honeywell International Inc. competes on brand strength and channel control across North American healthcare and educational facilities.
A building automation system integrates electromechanical, electronic, and software components to monitor and control a structure's heating, ventilation, air conditioning, lighting, and security subsystems, typically operating through protocols such as BACnet or Modbus over IP networks with response latencies under 100 milliseconds. Its primary purpose is to reduce operational energy expenditure while maintaining occupant comfort and safety compliance. HVAC Control occupies the largest margin pool due to persistent regulatory pressure on thermal efficiency, while Energy Management represents the fastest-growing application as owners pursue real-time carbon accounting. BACnet leads the technology dimension because of its interoperability mandate in many public-sector procurement specifications.
The EU Green Deal and F-Gas Regulation shape product roadmaps by phasing down hydrofluorocarbon refrigerants and mandating building performance certificates across member states. In the United States, ASHRAE Standard 90.1 and EPA ENERGY STAR certification programs drive retrofit demand by penalizing structures that exceed prescribed energy use intensity thresholds. Stakeholders must monitor whether emerging federal building performance standards in the United States will harmonize with European carbon disclosure rules or fragment procurement requirements across jurisdictions.
Market Dynamics
The retrofit imperative across aging commercial building stock is compressing sales cycles and forcing incumbent vendors to re-architect service delivery models around performance guarantees rather than hardware shipments.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is compelling building owners across Germany and France to replace HVAC infrastructure with lower-global-warming-potential alternatives.
- Smart city infrastructure:Municipalities in China are bundling building automation into district-scale energy management platforms, creating anchor demand for integrated control systems.
- Edge computing architectures:On-premise processing of sensor data is reducing latency below 50 milliseconds, enabling real-time demand response that grid operators in California now compensate.
Market Restraints
- Semiconductor supply concentration:Taiwan-based foundries control critical microcontroller production, exposing HVAC controller manufacturers to 26-week lead times during capacity crunches.
- Copper and rare earth volatility:Neodymium price swings of 40% annually are compressing margins on permanent-magnet motor drives used in variable air volume systems.
- Interoperability friction:Legacy Modbus installations resist seamless BACnet/IP migration, forcing costly gateway deployments that extend payback periods beyond capital committee thresholds.
Strategic Opportunities
- India's Energy Conservation Building Code:Mandatory energy audits for commercial structures exceeding 100 kW connected load are creating first-time automation demand in Mumbai and Bangalore.
- Digital twin convergence:Physics-based building models fused with live sensor streams are enabling predictive maintenance contracts that capture 15-year lifecycle value.
- Utility demand response programs:Aggregators in Texas and Australia are recruiting commercial buildings as virtual power plant assets, compensating automated load curtailment above prevailing electricity tariffs.
Industry Challenges
- Controls engineering talent scarcity:The pipeline of technicians proficient in both HVAC thermodynamics and IT network administration is failing to match deployment velocity in major metros.
- Cybersecurity certification timelines:UL 2900-2-3 testing for building automation software extends product launch schedules by 8-14 months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building Automation System Market |
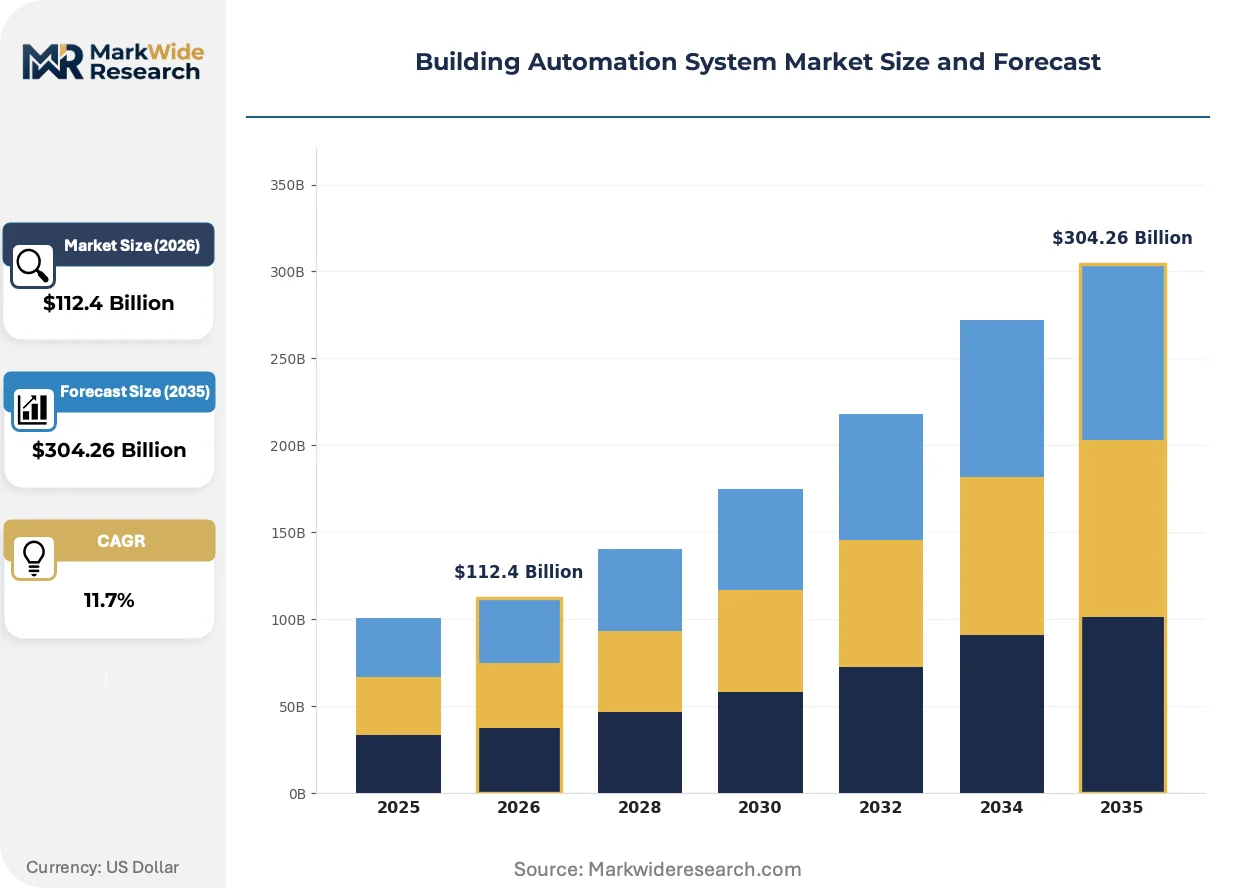
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $304.26 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lighting Control, HVAC Control, Security Systems, Energy Management Technology: BACnet, Zigbee, Modbus, KNX End User: Commercial Buildings, Industrial Facilities, Residential Homes, Educational Institutions Application: Energy Efficiency, Security Monitoring, Comfort Control, Automated Lighting |
| Companies Covered | Johnson Controls International plc, Emerson Electric Co., Siemens AG, Carrier Global Corporation, Delta Electronics, Inc., Schneider Electric SE, ABB Ltd, Rockwell Automation, Inc., Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building Automation System Market Emerging Trajectories
Wireless mesh networking is severing the historical dependency on structured cabling, while artificial intelligence inference at the edge is collapsing the distinction between sensing, control, and optimization layers.
Native IP connectivity is overtaking fieldbus architectures as the default specification in new commercial construction. Wireless BACnet/SC eliminates the cost and disruption of pulling wire through existing walls, cutting retrofit labor by 60%. Healthcare facility managers in the United States are specifying wireless for infection-control zones where penetrations are prohibited, compressing project timelines from quarters to weeks.
The EU Green Deal's building performance certificate mandate is forcing disclosure of actual energy consumption against theoretical design targets. Asset managers in Germany and the Netherlands now face portfolio write-downs when buildings fall below Class C ratings, redirecting capital toward sensor-rich automation that documents continuous compliance. The regulatory pressure is most acute in office assets over 1,000 square meters, where public listing requirements expose underperformance to tenant markets.
Facility managers are consolidating vendor relationships to reduce interface complexity, compressing the typical supplier roster from seven specialized contractors to two integrated platform providers. This concentration is displacing point-solution specialists in favor of vendors with captive software stacks and 24/7 remote operations centers. The shift is most visible in United States educational facilities, where unified procurement across K-12 districts is aggregating demand and sharpening price negotiation leverage.
Building Automation System Market Segmentation
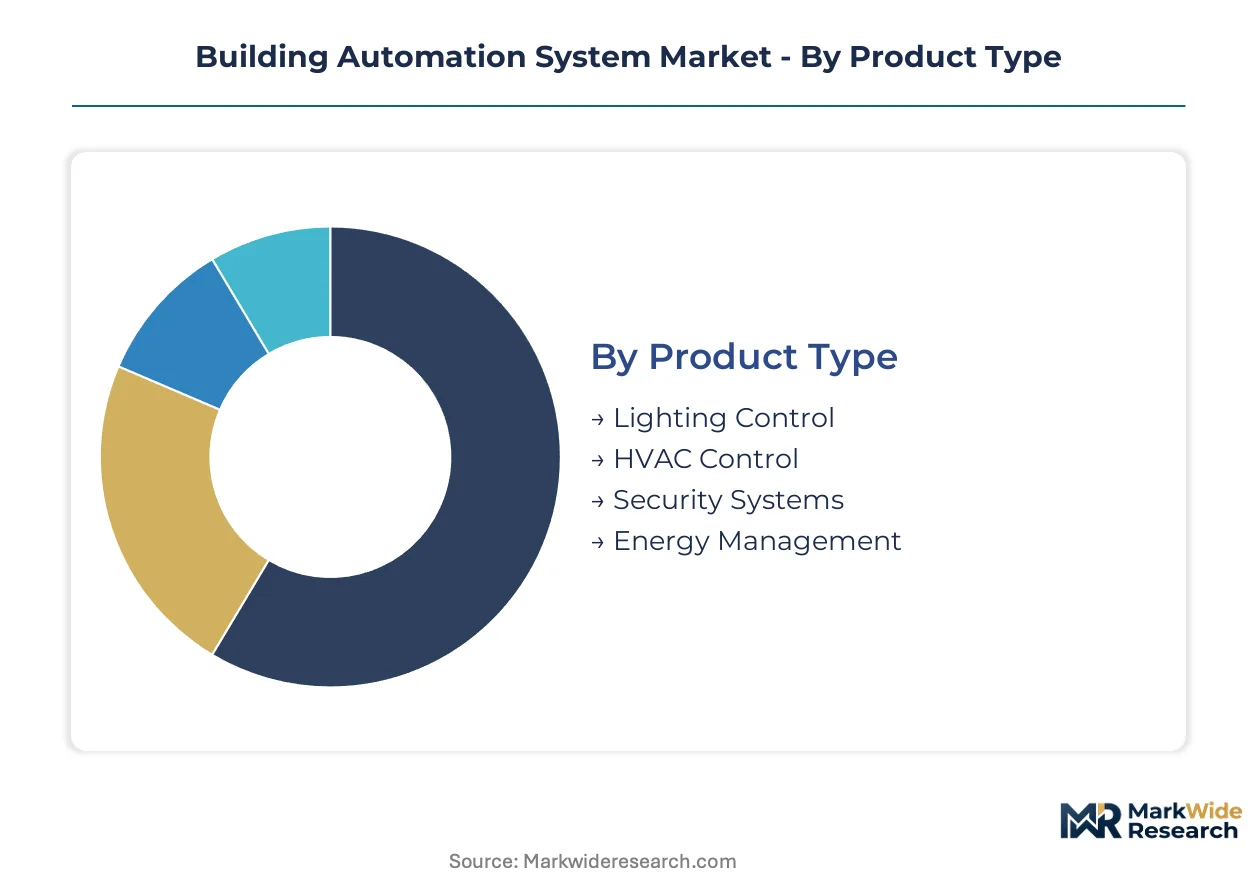
Building automation procurement splits sharply between retrofit installations demanding backward compatibility and new construction specifying native IP architectures. Segmentation reveals where vendor R&D investments concentrate and which integration protocols capture specification authority across major building portfolios.
Product Type:
Standardization dominates lighting and security hardware, while HVAC and energy management require deep customization to building thermal profiles and local regulatory thresholds.
- HVAC Control:Systems regulate thermal environments through variable air volume terminals, heat pump coordination, and refrigerant loop optimization. Demand clusters in Germany and France where F-Gas Regulation mandates hydrofluorocarbon phase-downs, forcing wholesale chiller replacements with lower-global-warming-potential equipment.
- Energy Management:Platforms aggregate meter data, benchmark consumption against design baselines, and automate demand response participation. Owners in California and Texas deploy these most aggressively where utility programs compensate automated load curtailment above prevailing tariffs.
- Lighting Control:Daylight harvesting and occupancy-based dimming reduce electrical loads in commercial interiors.
- Security Systems:Access control and surveillance integration protects building perimeters and sensitive zones.
Most installed capacity flows through HVAC Control. Expansion is steepest in Energy Management.
Technology:
Protocol selection tracks construction vintage: greenfield projects specify IP-native stacks, while brownfield retrofits tolerate gateway-heavy legacy bridging.
- BACnet:ASHRAE-developed standard dominates North American commercial specifications with native IP transport and standardized object models. Public-sector procurement in the United States increasingly mandates BACnet/SC for cybersecurity-hardened wireless deployments in healthcare and government facilities.
- KNX:European standard prevails in residential and light commercial across Germany, Belgium, and Switzerland where CE marking requirements favor pre-certified device ecosystems.
- Modbus:Legacy serial protocol persists in industrial facilities requiring minimal retrofit disruption.
- Zigbee:Low-power mesh networking serves residential and small commercial wireless sensor deployments.
Specification authority concentrates with BACnet in commercial new construction. KNX defends its position most tenaciously in European residential integration.
End User:
Customer scale determines integration depth: portfolio owners demand centralized command platforms while single-asset operators accept point solutions.
- Commercial Buildings:Office towers, retail centers, and hospitality assets drive platform consolidation. Asset managers in the Netherlands and Germany face portfolio write-downs when buildings fall below EU Green Deal Class C energy ratings, redirecting capital toward sensor-rich automation that documents continuous compliance.
- Educational Institutions:K-12 districts and university campuses in the United States aggregate procurement across multiple facilities, sharpening price negotiation leverage and favoring vendors with unified software stacks and 24/7 remote operations centers.
- Industrial Facilities:Manufacturing plants prioritize process-critical environmental control and safety interlocks.
- Residential Homes:Single-family and multi-family dwellings emphasize cost-competitive wireless solutions over structured cabling.
Revenue concentration sits with Commercial Buildings. Educational Institutions are expanding most quickly as district-wide procurement templates proliferate.
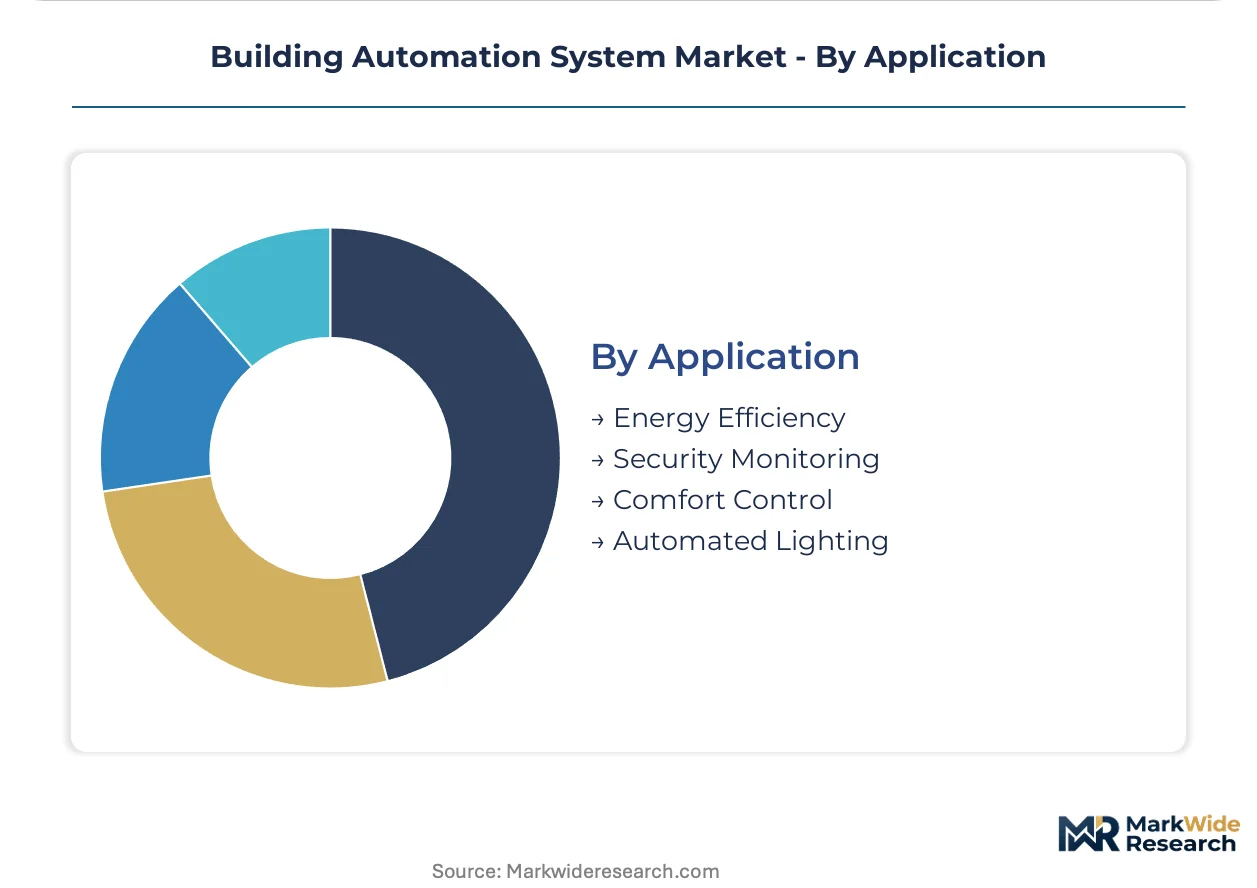
Application:
Use-case priority varies by building type and regulatory pressure, with energy compliance now overriding pure comfort optimization in specification decisions.
- Energy Efficiency:Real-time carbon accounting and automated demand response dominate new procurement. Grid operators in California compensate commercial buildings for sub-50-millisecond load curtailment, creating direct revenue streams from automation infrastructure.
- Security Monitoring:Integrated access control and video analytics protect critical infrastructure and healthcare environments.
- Comfort Control:Thermal and air quality management maintains occupant productivity in office and educational settings.
- Automated Lighting:Occupancy-based switching and daylight harvesting reduce electrical consumption in perimeter zones.
Procurement priority has shifted toward Energy Efficiency. Security Monitoring retains strongest defensive spending in healthcare and government assets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany enforces the strictest building performance disclosure rules in Europe, while the United States channels retrofit capital through federal energy efficiency mandates. China, India, and Japan round out the five-country concentration where regulatory pressure and smart city investment intersect most directly.
United States
Commercial real estate owners in California and Texas deploy automated demand response systems to capture grid operator compensation for sub-50-millisecond load curtailment. ASHRAE Standard 90.1 and EPA ENERGY STAR certification penalize structures exceeding prescribed energy use intensity thresholds. Healthcare facility managers specify wireless BACnet/SC for infection-control zones where wall penetrations are prohibited.
Germany
Asset managers face portfolio write-downs when office assets over 1,000 square meters fall below EU Green Deal Class C energy ratings. The F-Gas Regulation mandates hydrofluorocarbon phase-downs, compelling wholesale chiller replacements in Frankfurt and Munich. KNX-certified device ecosystems dominate residential and light commercial integration across Bavaria and North Rhine-Westphalia.
China
Municipalities bundle building automation into district-scale energy management platforms as smart city investments accelerate in Beijing and Shanghai. MIIT standards and dual carbon goals drive native IP architecture specifications in new commercial construction. Yangtze River Delta manufacturing clusters supply controllers and sensors for domestic retrofit programs.
India
The Energy Conservation Building Code mandates energy audits for commercial structures exceeding 100 kW connected load, creating first-time automation demand in Mumbai and Bangalore. BIS certification requirements favor pre-integrated platform providers over point-solution specialists. Gujarat and Maharashtra industrial corridors prioritize process-critical environmental control in pharmaceutical and electronics manufacturing.
Japan
Tokyo and Osaka commercial towers specify edge-computing architectures that collapse sensing, control, and optimization layers into unified stacks. METI efficiency standards and JIS certification programs accelerate wireless mesh deployment to avoid disruption in dense urban cores. Kansai region facility managers consolidate vendor relationships from seven specialized contractors to two integrated platform providers.
Building Automation System Market Vendor Landscape
Top-tier vendors anchor high-performance commercial installations, while mid-scale specialists compete on retrofit backward compatibility and wireless deployment speed. The market structure reflects concentrated specification authority among portfolio owners demanding unified software stacks and 24/7 remote operations centers. Two strategic archetypes dominate: diversified industrial conglomerates with captive sensor supply chains, and pure-play automation specialists with deep backward integration into energy analytics software. Competitive moves concentrate on M&A to acquire edge-computing capabilities and strategic partnerships with utility demand response aggregators.
Within the diversified conglomerate tier, Johnson Controls International plc and Honeywell International Inc. exemplify vendors leveraging brand strength and channel control across healthcare and educational facilities. Siemens AG occupies a position representing deep software-centric positioning through building energy analytics platforms. These three entities anchor the premium specification tier where procurement committees prioritize performance guarantees over hardware commodity pricing.
| Leading Market Players |
|---|
| Johnson Controls International plc |
| Emerson Electric Co. |
| Siemens AG |
| Carrier Global Corporation |
| Delta Electronics, Inc. |
| Schneider Electric SE |
| ABB Ltd |
| Rockwell Automation, Inc. |
| Honeywell International Inc. |
| Others |
Supply Flow & Price Mechanics
Copper and neodymium price indices cascade through building automation manufacturing, compressing margins on permanent-magnet motor drives while amplifying cost differentials between captive-supply conglomerates and assembly-dependent specialists across procurement tiers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing clusters are reshaping price floors for HVAC controllers and sensor modules. Three-tier pricing structure across premium, standard, and economy levels separates vendors with captive silicon foundry relationships from gateway-dependent integrators. Price differentiation hinges on BACnet/SC cybersecurity certification and volume scale through district-wide educational procurement. Pricing pressure stems from semiconductor supply concentration exposing manufacturers to extended lead times. Single-asset building operators exhibit highest price sensitivity; portfolio owners with centralized command platforms prioritize performance guarantees over hardware commodity pricing.
Supply Chain Analysis
Trans-Pacific freight cost volatility compounds margin compression for European and North American system integrators sourcing from Asian component hubs. Taiwan-based foundries, Chinese sensor manufacturers, and German precision-motor suppliers anchor global controller production. Raw material dependencies center on copper wiring, neodymium permanent magnets, and silicon wafers. Single-source vulnerability concentrates in microcontroller fabrication. Distribution runs through authorized system integrators and direct OEM relationships with large commercial developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Building automation has entered a late-cycle quality phase where EU Green Deal Class C rating mandates and ASHRAE Standard 90.1 enforcement redirect capital toward sensor-rich platforms that document continuous compliance over point-solution commodity hardware.
For Market Incumbents: Extend software-centric positioning through building energy analytics platforms that capture 15-year lifecycle value via predictive maintenance contracts. Deepen backward integration into edge-computing silicon to offset Taiwan foundry concentration risk. Consolidate vendor relationships across K-12 district procurement templates to sharpen price negotiation leverage against point-solution specialists. For New Entrants and Emerging Players: India's Energy Conservation Building Code opens a window for wireless mesh specialists targeting first-time automation demand in Mumbai and Bangalore commercial structures exceeding 100 kW connected load. White-space concentrates in BIS-certified pre-integrated platforms for pharmaceutical and electronics manufacturing corridors in Gujarat and Maharashtra. Go-to-market should anchor in utility demand response aggregator partnerships compensating automated load curtailment. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play automation specialists possessing deep backward integration into energy analytics software rather than diversified industrial conglomerates dependent on hardware shipment volumes. Long-term viability favors vendors with 24/7 remote operations centers and captive sensor supply chains. Watch for harmonization between emerging US federal building performance standards and European carbon disclosure rules as inflection indicator for procurement specification consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Architecture Development | On-premise inference below 50 milliseconds enables California grid operator compensation for demand response. |
| BACnet/SC Cybersecurity Certification | UL 2900-2-3 compliance opens US healthcare and government procurement specifications to wireless deployments. |
| Digital Twin Platform Integration | Physics-based building models fused with live sensor streams capture predictive maintenance contract value. |
| Utility Demand Response Partnership | Texas and Australian aggregator recruitment converts commercial buildings into compensated virtual power plant assets. |
| F-Gas Compliant HVAC Replacement | Lower-global-warming-potential equipment mandates in Germany and France force wholesale chiller upgrade cycles. |
Methodological Framework
Bottom-up commercial building and educational facility modeling reconciled against top-down controller and sensor shipment tracking forms the analytical core of this study. Primary interviews with facility managers, controls engineering directors, procurement leads at portfolio real estate owners, and utility demand response program administrators combined with secondary validation from ASHRAE standards documentation, EPA ENERGY STAR certification databases, EU EPC registry filings, and customs trade data for HVAC controller imports. Triangulation across these sources ensures segmentation integrity across product type, protocol technology, and end-user verticals.
Historical trendline analysis of installed base growth and retrofit penetration rates anchored the projection framework across the analysis window. Segmentation dimensions modeled include HVAC control versus energy management application, BACnet versus KNX versus Modbus protocol specification, and commercial building versus educational institution end-user archetype. CAGRs derived from regression analysis of regulatory enforcement timelines and smart city investment disbursement patterns. Industry-specific forecast inputs incorporate F-Gas Regulation phase-down schedules and India's Energy Conservation Building Code audit mandate expansion trajectories.
Revisions become necessary when semiconductor supply concentration triggers extended lead times, copper and rare earth price volatility exceeds historical bands, or cybersecurity certification timelines delay product launches beyond capital committee thresholds. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Dumbwaiter Lifts Market
Building Automation Systems
Escalator Market
Building Automation Systems
Underfloor Heating Actuator Market
Building Automation Systems
Residential Electric Underfloor Heating Market
Building Automation Systems
Energy Efficient Elevators Market
Building Automation Systems
Asia-Pacific Building Automation System Market
Building Automation Systems
Global Enterprise Building Solutions Market
Building Automation Systems
Flushing Systems Market
Building Automation Systems
Platform Screen Door System Market
Building Automation Systems
Tunnel Automation Market
Building Automation Systems
Commercial Building Automation Systems Market
Building Automation Systems
Vinyl Strip Door and Curtains Market
Building Automation Systems
Europe Building Automation Systems Market
Building Automation Systems
Europe HVAC Controls Market
Building Automation Systems
Global HVAC Controls Market
Building Automation Systems
US Commercial Building Automation Market