
 Electromechanical Actuator Market | 2026-2036
Electromechanical Actuator Market Size, Share, and Industry Trends Forecast 2026-2036
Electromechanical Actuator Market Foresight
Buyer concentration in aerospace and automotive OEM supply chains is recalibrating procurement dynamics across the electromechanical actuator landscape. Parker Hannifin Corporation leverages its motion control portfolio to sustain long-term platform contracts with tier-one suppliers. ABB Ltd anchors factory automation demand through integrated servo-actuator systems for robotics and CNC applications. Moog Inc. specializes in high-reliability flight control actuation, occupying a defensible niche in commercial and defense aerospace programs.
An electromechanical actuator converts electrical energy into precise mechanical motion through motor-driven screw, belt, or direct-drive mechanisms, typically achieving positioning accuracy within micrometers under closed-loop servo control. These devices replace hydraulic and pneumatic systems across manufacturing equipment, surgical robotics, and aircraft flight surfaces where energy efficiency and elimination of fluid leaks are critical. Linear actuators dominate industrial installation bases due to their straightforward integration into existing motion architectures, while integrated actuators represent the fastest-expanding category as machine builders consolidate electronics, motors, and feedback devices into single-source subsystems. Servo technology leads revenue contribution given its prevalence in multi-axis automation, though piezoelectric technology captures premium positioning in medical device and semiconductor applications requiring nanometer-scale resolution.
The EU Machinery Directive and CE marking requirements shape product design cycles by mandating functional safety ratings and electromagnetic compatibility validation for actuator systems deployed in European manufacturing environments. The US FAA airworthiness standards and NHTSA automotive safety regulations impose qualification burdens that favor established suppliers with dedicated certification engineering resources. ISO 13849 safety integrity standards further filter market access for entrants lacking documented failure-mode analysis capabilities. Stakeholders must monitor how evolving battery-electric vehicle architectures and next-generation aircraft electrification programs redirect actuator specification roadmaps away from legacy hydraulic benchmarks.
Market Dynamics
Aerospace OEMs are consolidating actuator procurement under multi-year platform contracts, compressing supplier bases and elevating technical qualification barriers for electromechanical actuator vendors seeking entry into flight control and landing gear programs.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants and hydraulic fluids is accelerating factory conversions from fluid power to electric actuation across German and Italian manufacturing corridors.
- Battery-electric vehicle architectures:Automotive OEMs are eliminating engine-driven hydraulic pumps, creating specification pull for high-force electromechanical alternatives in chassis and steering systems.
- Stuttgart-Munich automation cluster:Concentrated demand from precision machinery and robotics OEMs is sustaining capacity expansion for integrated servo-actuator systems with embedded drive electronics.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings embedded in permanent magnet motors create margin compression for actuator manufacturers lacking long-term supply agreements.
- Supply concentration in precision ball screws:Japanese and German specialty manufacturers control critical feedstock for high-accuracy linear motion, exposing buyers to allocation risk during demand surges.
- Power density limitations:Electromechanical alternatives cannot yet match hydraulic force-to-weight ratios in heavy-lift applications above 50 kN, preserving incumbent technology in construction and mining equipment.
Strategic Opportunities
- India PLI scheme for manufacturing:Production-linked incentives for industrial automation and automotive component localization are attracting actuator assembly investments targeting domestic and export demand.
- Urban air mobility platforms:Electric vertical takeoff aircraft programs require fault-tolerant electromechanical flight controls with redundancy architectures absent from legacy aerospace supply chains.
- ISO 13849 safety integration:Pre-certified actuator subsystems that embed functional safety ratings are capturing premium positioning in European collaborative robot deployments.
Industry Challenges
- Mechatronics engineering scarcity:Cross-functional talent combining motor control, mechanical design, and safety validation is concentrated at established vendors, constraining product development velocity for mid-tier suppliers.
- FAA airworthiness certification timelines:Design assurance level validation for flight-critical actuators extends development cycles to 4-7 years, freezing specification commitments before technology obsolescence risks emerge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electromechanical Actuator Market |
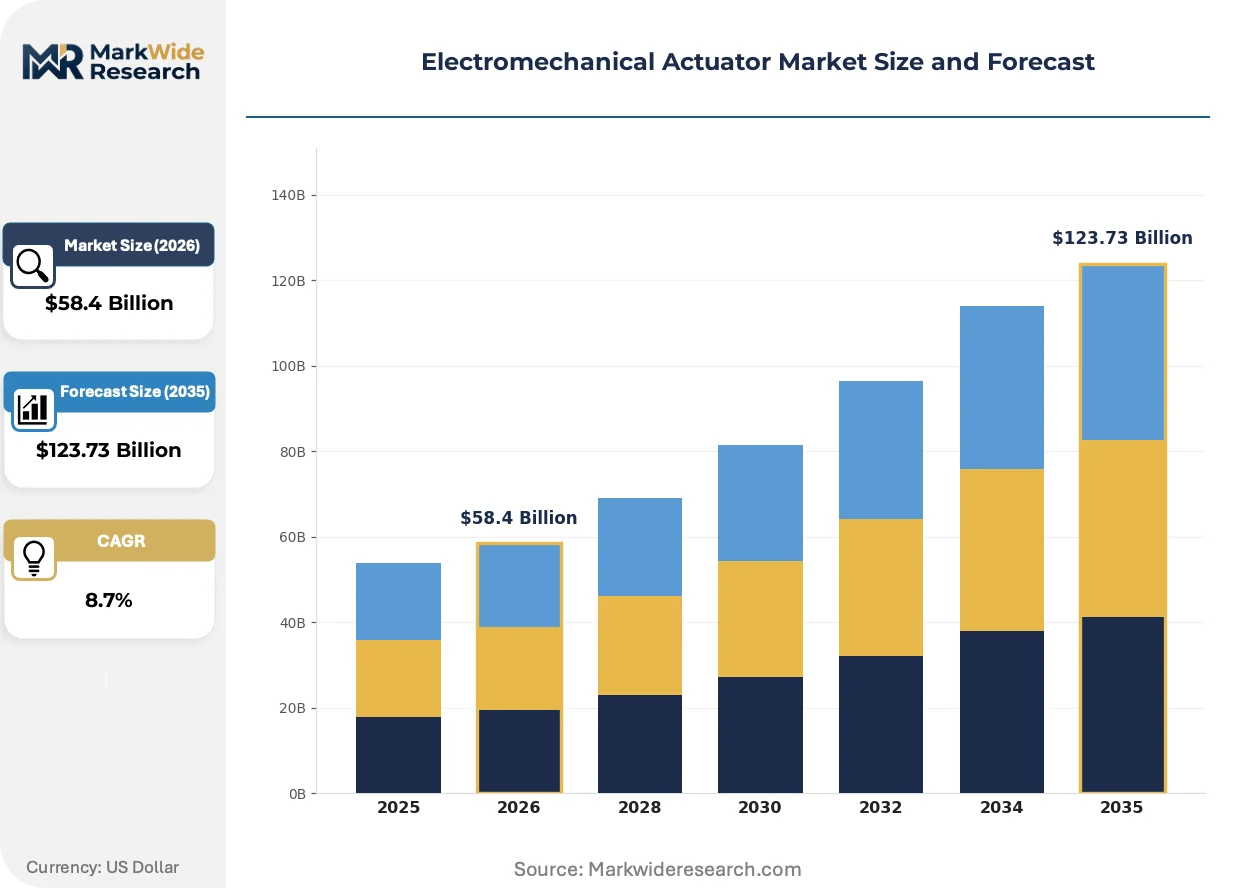
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $123.73 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Rotary Actuators, Gear Motors, Integrated Actuators End User: Aerospace, Automotive, Industrial Automation, Robotics Technology: Servo Technology, Stepper Technology, Piezoelectric Technology, Voice Coil Technology Application: Robotic Systems, Manufacturing Equipment, Medical Devices, Aerospace Systems |
| Companies Covered | Liebherr Group, ABB Ltd, Honeywell International Inc., Parker Hannifin Corporation, Emerson Electric Co., Curtiss-Wright Corporation, AMETEK Inc., Festo AG & Co. KG, Moog Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electromechanical Actuator Market Shifts & Advancements
Electromechanical actuator architectures are converging around integrated electromechanical systems that collapse motor, drive, and feedback components into single-source subsystems, compressing supply chain complexity and installation labor.
Integrated smart actuators with embedded servo drives and industrial Ethernet connectivity are consolidating machine builder procurement from multi-vendor assemblies to single-source motion subsystems. Packaging houses and semiconductor equipment OEMs in Taiwan and South Korea are adopting these consolidated units to reduce panel space and commissioning time. The shift is compressing margins for standalone motor and drive suppliers while elevating system-level vendors with firmware and safety certification capabilities.
REACH substance restrictions and RoHS substance bans are forcing reformulation of bearing greases, cable insulation, and potting compounds used in actuator construction. European machinery OEMs are demanding full material disclosure documentation from suppliers to satisfy downstream compliance obligations. Medical device and food processing equipment manufacturers are responding fastest, specifying actuators with halogen-free cabling and food-grade lubricants to preempt regulatory exposure.
Long-term platform contracting is displacing spot purchasing in aerospace and automotive supply chains, locking actuator specifications 5-10 years ahead of production. Tier-one suppliers are consolidating volume commitments with single-source agreements that bundle development funding, lifetime service, and obsolete component management. German automotive suppliers and US defense primes are most advanced in this transition, using captive engineering resources to co-design actuator architectures with their strategic vendors.
Electromechanical Actuator Market Segmentation
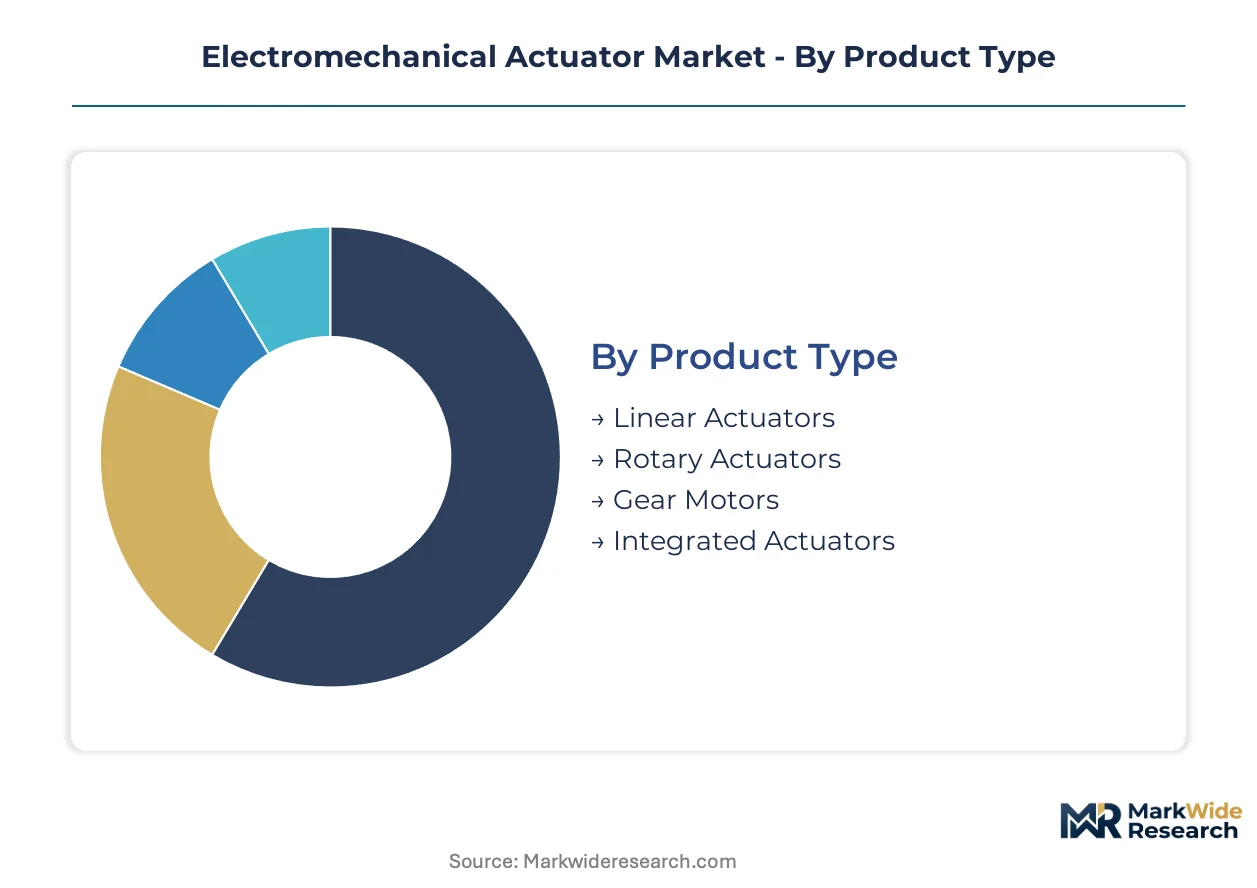
Electromechanical actuator procurement patterns diverge sharply across product architectures and end-use specifications, with supply chain configuration dictating which segment combinations capture premium positioning versus commodity volume.
Product Type:
Supply concentration in precision ball screws and integrated drive electronics favors vendors with captive manufacturing or long-term offtake agreements.
- Linear Actuators:Motor-driven screw or belt mechanisms translate rotational motion into precise linear displacement, typically achieving positioning accuracy within micrometers. Demand concentrates in Germany's Stuttgart-Munich industrial corridor where factory automation OEMs specify integrated units for CNC and packaging machinery. Ball screw supply bottlenecks from Japanese and German specialty manufacturers constrain expansion for mid-tier suppliers lacking qualified second sources.
- Integrated Actuators:Consolidated subsystems embed servo motors, drives, and feedback devices into single-source units, collapsing procurement from multi-vendor assemblies. Taiwan and South Korean semiconductor equipment manufacturers are adopting these units aggressively to reduce panel space and commissioning time. Firmware capabilities and safety certification resources separate winning vendors from component assemblers.
- Rotary Actuators:Direct-drive and geared configurations deliver precise angular positioning for indexing tables and robotic joints.
- Gear Motors:Compact motor-reducer combinations serve lower-precision material handling and conveyor applications where cost dominates specification.
Linear actuators absorb the bulk of installed capacity; integrated actuators are expanding most quickly.
End User:
Customer procurement maturity spans from spot purchasing in industrial automation to decade-long platform contracts in aerospace and automotive.
- Industrial Automation:Factory equipment builders specify actuators for robotics, packaging, and CNC machinery with emphasis on mean time between failure and energy efficiency. The EU Machinery Directive and CE marking requirements filter supplier access through functional safety validation and electromagnetic compliance documentation. REACH substance restrictions force reformulation of bearing greases and cable insulation, elevating vendors with full material disclosure capabilities.
- Aerospace:Flight control and landing gear programs demand fault-tolerant architectures with redundancy and failure-mode analysis documentation. FAA airworthiness standards and design assurance level validation extend development cycles to 4-7 years, freezing specifications before technology obsolescence risks emerge. Long-term platform contracts consolidate volume with strategic vendors bundling development funding and lifetime service.
- Automotive:Battery-electric vehicle architectures eliminate engine-driven hydraulic pumps, pulling specification toward high-force electromechanical alternatives in chassis and steering systems.
- Robotics:Collaborative robot deployments require ISO 13849 safety-integrated actuators with embedded functional safety ratings for human-robot interaction.
Industrial automation commands the largest installed base; aerospace programs show the steepest expansion trajectory as electrification displaces hydraulic flight controls.
Technology:
Performance tier and price point stratification follow motor technology selection, with permanent magnet costs creating margin pressure across architectures.
- Servo Technology:Closed-loop systems with encoder feedback deliver dynamic positioning for multi-axis automation and high-speed packaging. Neodymium and dysprosium price volatility in permanent magnet motors compresses margins for manufacturers lacking long-term rare earth supply agreements. Prevalence in robotics and CNC applications sustains revenue concentration despite material cost headwinds.
- Piezoelectric Technology:Ceramic-driven mechanisms achieve nanometer-scale resolution through inverse piezoelectric effect, serving medical device and semiconductor inspection equipment where sub-micron positioning is mandatory. Premium pricing reflects material and amplification architecture complexity rather than volume scale.
- Stepper Technology:Open-loop position control suits lower-cost applications where absolute accuracy is secondary to repeatability and simplicity.
- Voice Coil Technology:Direct-drive linear motors provide frictionless motion for optical focusing and vibration cancellation in precision instrumentation.
Servo technology dominates revenue contribution; piezoelectric systems gain share fastest in medical and semiconductor end uses.
Application:
Specification intensity varies from force-density optimization in manufacturing to fault tolerance in flight-critical systems.
- Manufacturing Equipment:CNC machinery, packaging lines, and assembly systems specify actuators for throughput and positioning repeatability under continuous duty cycles. German and Italian manufacturing corridors drive demand concentration as EU F-Gas Regulation accelerates hydraulic-to-electric conversions. Energy efficiency and elimination of fluid leaks motivate specification shifts away from legacy fluid power.
- Aerospace Systems:Primary flight controls, landing gear, and thrust vectoring demand force-to-weight optimization with failure-mode containment. Electromechanical alternatives cannot yet match hydraulic ratios above 50 kN, preserving incumbent technology in heavy-lift surfaces while electric architectures penetrate secondary systems. Urban air mobility platforms require redundant electromechanical controls absent from legacy supply chains.
- Robotic Systems:Articulated arms and collaborative robots specify actuators for dynamic response and safety-rated torque limiting.
- Medical Devices:Surgical robotics and diagnostic equipment demand sterilizable actuators with nanometer precision and electromagnetic compatibility for imaging environments.
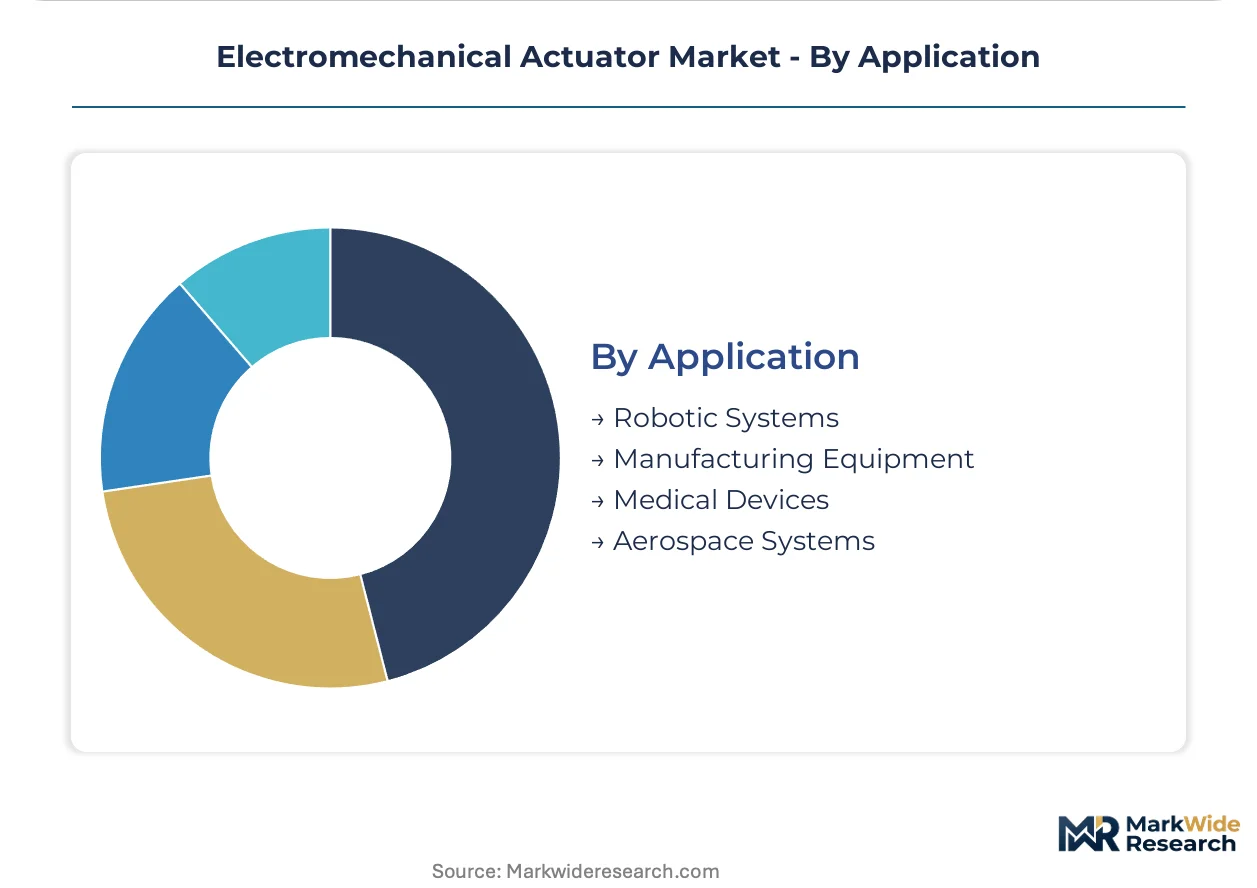
Manufacturing equipment holds the majority of unit shipments; aerospace systems are climbing the fastest as next-generation aircraft electrification programs redirect specification roadmaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany's industrial automation corridor, where Stuttgart and Munich anchor precision machinery and robotics OEM procurement. Aerospace electrification programs in the United States and battery-electric vehicle architectures in China are redirecting specification roadmaps away from legacy hydraulic systems.
Germany
The Stuttgart-Munich automation cluster sustains capacity expansion for integrated servo-actuator systems with embedded drive electronics. EU F-Gas Regulation accelerates factory conversions from fluid power to electric actuation across Baden-Württemberg and Bavaria. REACH substance restrictions force reformulation of bearing greases and cable insulation, elevating vendors with full material disclosure capabilities.
United States
FAA airworthiness standards and NHTSA automotive safety regulations impose qualification burdens that favor established suppliers with dedicated certification engineering resources. Battery-electric vehicle architectures eliminate engine-driven hydraulic pumps, creating specification pull for high-force electromechanical alternatives. Defense primes in the aerospace belt consolidate volume commitments with single-source agreements bundling development funding and lifetime service.
China
Dual carbon goals and machinery modernization programs accelerate hydraulic-to-electric conversions in manufacturing equipment. GB standards and MIIT industrial automation directives filter supplier access through electromagnetic compliance and safety validation requirements. Yangtze River Delta packaging houses and semiconductor equipment OEMs adopt integrated smart actuators to reduce panel space and commissioning time.
Japan
METI industrial efficiency mandates and JIS standards drive precision motion requirements in robotics and CNC applications. Rare earth magnet cost volatility in permanent magnet motors creates margin compression for actuator manufacturers lacking long-term supply agreements. Nagoya-area automotive suppliers specify electromechanical alternatives for chassis and steering systems as hybrid and electric platforms expand.
India
PLI scheme production-linked incentives for industrial automation and automotive component localization attract actuator assembly investments. BIS machinery safety standards and electromagnetic compatibility requirements shape product design cycles for European and domestic OEM supply chains. Gujarat and Maharashtra industrial corridors concentrate demand from precision machinery builders targeting export markets.
Electromechanical Actuator Market Competitive Landscape
German and Swiss producers anchor the premium tier; Japanese specialists hold supply concentration in precision ball screws. The vendor base stratifies across three archetypes: diversified motion control conglomerates with captive electronics capabilities, aerospace-focused specialists with airworthiness certification resources, and integrated actuator assemblers dependent on external motor and screw supply. Dominant competitive moves include backward integration into rare earth magnet sourcing and pre-certification of actuator subsystems to ISO 13849 safety integrity standards.
Within the diversified industrial tier, ABB Ltd and Parker Hannifin Corporation exemplify vendors with integrated servo-actuator portfolios spanning factory automation and process industries. Moog Inc. occupies a defensible position among aerospace specialists, where FAA design assurance level validation and long-term platform contracting create structural barriers to entry. These three anchors demonstrate how firmware capabilities, safety certification resources, and captive manufacturing separate winning vendors from component assemblers in procurement consolidation environments.
| Leading Market Players |
|---|
| Liebherr Group |
| ABB Ltd |
| Honeywell International Inc. |
| Parker Hannifin Corporation |
| Emerson Electric Co. |
| Curtiss-Wright Corporation |
| AMETEK Inc. |
| Festo AG & Co. KG |
| Moog Inc. |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between aerospace-qualified and industrial-grade actuators manifests in both pricing power and supply chain depth. Premium-tier vendors with FAA design assurance validation and ISO 13849 safety ratings command 3-5x unit economics over commodity linear actuators, while their captive rare earth magnet sourcing and precision ball screw manufacturing insulate margins from spot-market volatility.
Pricing Analysis
Volume-mass industrial actuators trade on thin margins while aerospace and medical tiers retain pricing power. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden and safety integrity ratings. Cost compression in the industrial tier is intensifying because Japanese and German ball screw suppliers exert allocation leverage during demand surges. Automotive chassis OEMs show highest price sensitivity due to platform-standardization mandates, whereas surgical robotics manufacturers prioritize nanometer precision over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States maintain hub-and-spoke patterns for spare parts and emergency replacement units. Manufacturing concentration rests on China for rare earth processing, Japan and Germany for precision ball screws, and Taiwan for servo drive electronics. Single-source vulnerability in neodymium and dysprosium supply creates exposure to export restriction shocks. Distribution runs through authorized system integrators for industrial automation, direct OEM contracting for aerospace, and tier-one automotive supplier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rare earth magnet supply bottlenecks and precision ball screw manufacturing constraints prop pricing premiums for vendors with captive or contracted supply. Ball screw allocation scarcity from Japanese and German specialty manufacturers sustains structural pricing power for integrated producers.
For Market Incumbents: Hedge against rare earth cost volatility through backward integration into magnet sourcing or long-term offtake agreements with Chinese processors. Expand ISO 13849 pre-certified actuator subsystems to capture collaborative robot demand in Europe. Lock in aerospace platform contracts before urban air mobility programs mature alternative supplier relationships. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany and Italy opens a window for hydraulic-to-electric conversion services targeting mid-tier machinery OEMs lacking in-house mechatronics capabilities. Target India's PLI scheme corridors in Gujarat and Maharashtra for assembly investments serving domestic precision machinery builders. Pursue semiconductor equipment OEMs in Taiwan and South Korea with integrated smart actuators that collapse commissioning time. For Investors and Strategic Acquirers: Re-rating potential sits with aerospace-focused specialists given FAA certification timelines and design assurance level validation creating structural barriers to entry. Five-to-ten year viability favors vendors bundling firmware capabilities, safety certification resources, and lifetime service contracts. Watch urban air mobility program flight control specification releases as inflection indicators for electromechanical architecture penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Captive neodymium sourcing insulates margins from spot-price volatility in permanent magnet motors. |
| ISO 13849 Safety Certification Pre-qualification | Pre-certified subsystems capture premium positioning in European collaborative robot deployments. |
| Long-term Platform Contracting with Aerospace OEMs | Multi-year agreements bundle development funding and obsolete component management. |
| Integrated Smart Actuator Development | Consolidated motor-drive-feedback units reduce panel space for Taiwan semiconductor equipment OEMs. |
| India PLI Scheme Manufacturing Localization | Production-linked incentives attract assembly investments targeting domestic and export automation demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this electromechanical actuator market analysis. Primary interviews with maintenance directors at German automotive suppliers, OEM procurement teams in Stuttgart and Munich, aftermarket service heads at aerospace distributors, and plant engineers at Taiwanese semiconductor equipment manufacturers combined with secondary validation from FAA airworthiness directives, EU Machinery Directive implementation guidance, and Japan METI industrial efficiency reports. Bottom-up unit shipment modeling and top-down value triangulation cross-validated segment estimates.
Granularity-level modeling dissected the market across product architecture, end-use specification, motor technology, and application intensity. Servo versus piezoelectric versus stepper technology splits, aerospace versus industrial automation versus automotive end-use concentrations, and linear versus integrated versus rotary actuator form factors were projected across the analysis window. CAGRs derived from regression against industrial automation capital expenditure cycles, battery-electric vehicle platform rollout schedules, and aircraft electrification program milestones.
The model assumes a particular technology adoption path; alternative pathways for hydraulic system retention in heavy-lift applications above 50 kN would alter the outlook. Forecasts reflect stated assumptions regarding rare earth supply continuity, REACH substance restriction enforcement, and aerospace certification timeline stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
Construction Risk Assessment Software Market
Construction and Engineering
UK Facade Market
Construction and Engineering
Brazing Torch Market
Construction and Engineering
Thickness Planers Market
Construction and Engineering
China Construction Equipment Market
Construction and Engineering
North and Latin America Weatherization Services Market
Construction and Engineering
Residential Heat Pump Market
Construction and Engineering
Leather Cutting Machine Market
Construction and Engineering
Global DC Torque Tool Market
Construction and Engineering
Civil Engineering Market
Construction and Engineering
Cross Laminated Timber (CLT) Market
Construction and Engineering
Jade Engraving Machines Market
Construction and Engineering
Well Cementing Services Market
Construction and Engineering
Compressed Earth Block Machine Market
Construction and Engineering
US Commercial HVAC Rooftop Units Market
Construction and Engineering
Grabber Pole Market