
 Automated Daylight Harvesting Systems Market | 2026-2036
Automated Daylight Harvesting Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Daylight Harvesting Systems Market Insights
Lighting control engineering talent is collapsing across North America, constraining deployment velocity for complex retrofit projects. Signify leverages its vertical manufacturing footprint to maintain installer training programs and buffer lead times. Acuity Brands competes through deep specification relationships with electrical contractors, while Lutron Electronics specializes in premium dimming algorithms that command higher margins in hospitality venues.
Automated daylight harvesting systems combine photosensors, light controllers, and networked dimmers to modulate artificial illumination based on available natural light, typically maintaining target lux levels within ten percent variance. These systems reduce connected lighting loads by fifteen to fifty percent in perimeter zones, serving commercial operators seeking to cut utility expenditures. Photosensors and smart switches anchor the hardware stack, though integrated building systems installations now outpace standalone setups as new construction mandates whole-building automation. Office complexes and educational institutions represent the deepest application pools, with warehouses emerging as a faster-growing segment due to high-bay retrofit economics.
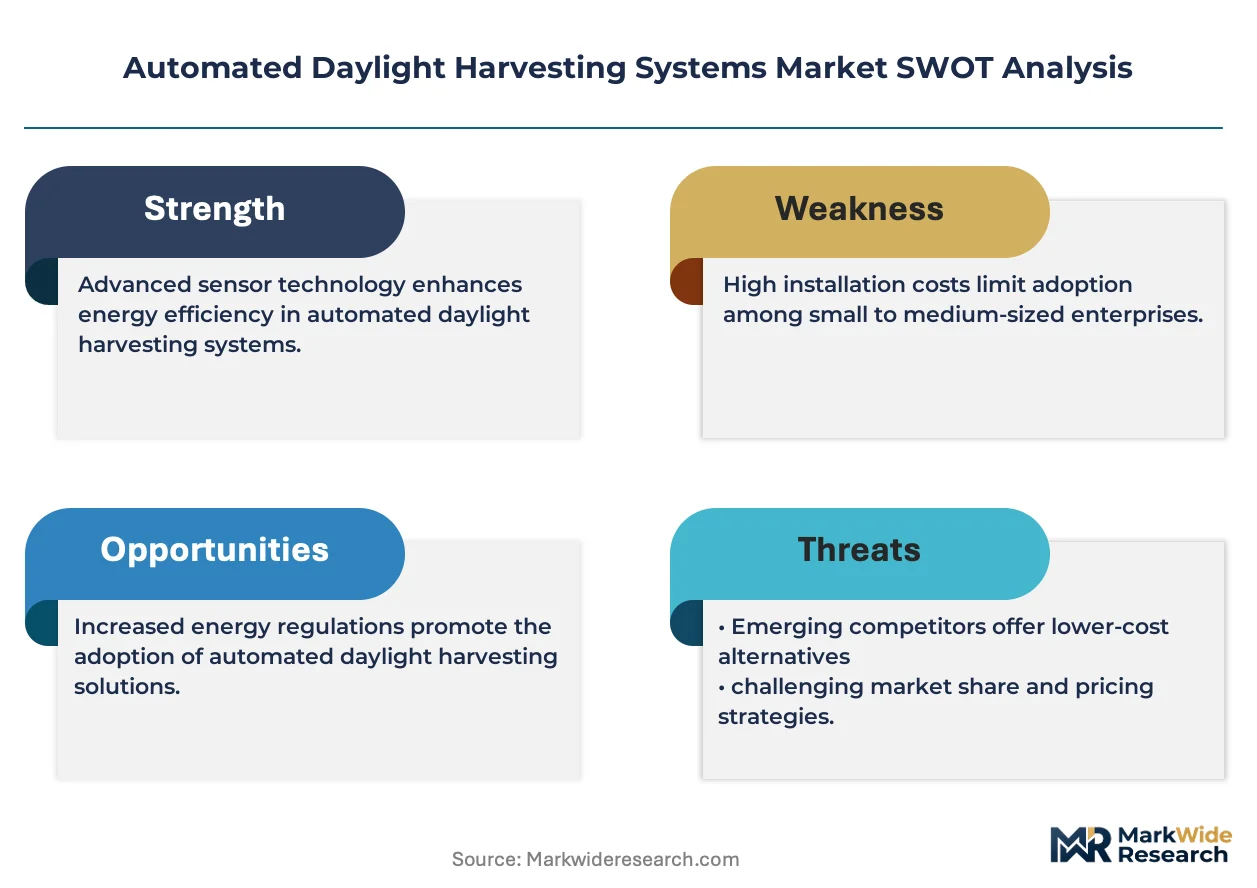
ASHRAE Standard 90.1, the EPA Energy Star certification framework, and California Title 24 collectively shape product specifications and procurement eligibility across the United States. The EU Green Deal and F-Gas Regulation indirectly reinforce demand by tightening overall building energy budgets, pushing facility managers toward daylight-linked HVAC-lighting integration. Stakeholders must monitor whether evolving utility interconnection rules will require bidirectional communication between daylight harvesting networks and grid operators, a shift that would favor suppliers with native software platforms over hardware-only vendors.
Market Dynamics
Building energy code stringency is compressing deployment timelines for automated daylight harvesting systems, forcing facility managers to integrate photosensor networks with HVAC controls rather than treating lighting as a standalone retrofit.
Growth Catalysts
- ASHRAE Standard 90.1 updates:The latest revisions mandate daylight-responsive controls in perimeter zones across commercial construction, creating compliance-driven procurement pipelines for electrical contractors.
- Warehouse retrofit economics:High-bay facilities with expansive skylight arrays generate payback periods under three years, accelerating adoption among logistics operators facing utility cost pressure.
- Photosensor miniaturization:Solid-state sensing elements now integrate directly into LED luminaire housings, eliminating separate mounting hardware and reducing installation labor by half.
Market Restraints
- Silicon photodiode supply concentration:Discrete photosensor production clusters in East Asian foundries, exposing North American system integrators to lead time volatility during capacity constraints.
- Commissioning complexity:Calibrating daylight setpoints across variable facade orientations demands specialized lighting control engineers, a function where talent scarcity adds project risk.
- Fluorescent ballast substitution:Existing T8 and T5 installations with basic occupancy sensors satisfy minimum code requirements in secondary markets, delaying full harvesting system upgrades.
Strategic Opportunities
- Title 24 Part 6 expansion:California's ongoing code cycles will mandate networked lighting controls in smaller buildings, opening mid-market commercial segments previously served by standalone dimmers.
- Daylight-HVAC convergence:Integrated building automation platforms that link photosensor data to chilled beam and VAV systems command premium specification positions in new construction.
- Educational institution retrofits:K-12 districts under deferred maintenance pressure represent an underpenetrated vertical where utility rebate stacking can offset capital constraints.
Industry Challenges
- Controls engineering talent pipeline:The specialized skill set bridging electrical contracting and software commissioning is collapsing across North America, constraining deployment velocity for complex retrofit projects.
- Legacy DALI protocol fragmentation:Inconsistent implementation of DALI-2 certification across dimming driver manufacturers forces integrators to maintain extensive compatibility matrices, adding project engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Daylight Harvesting Systems Market |
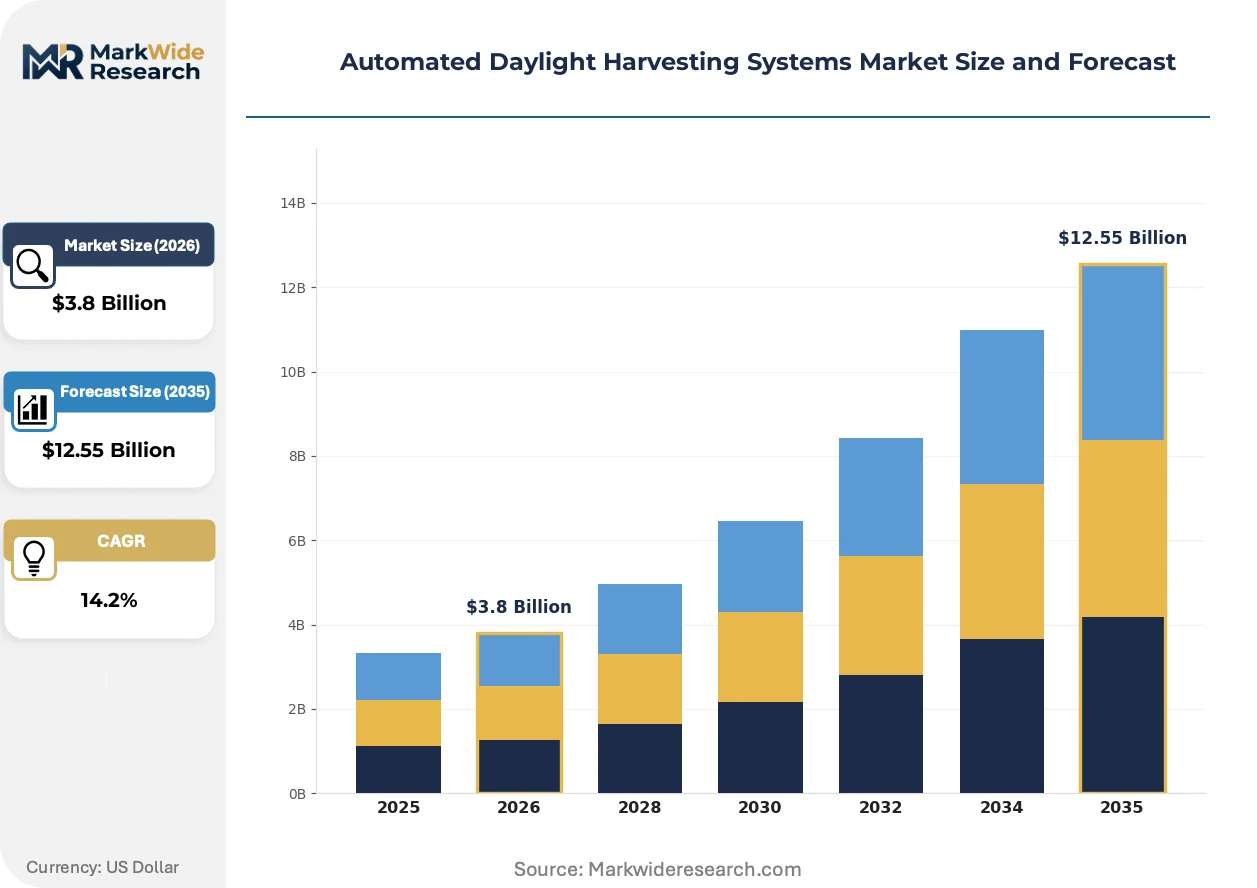
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photosensors, Light Controllers, Dimmers, Controllers, Smart Switches Application: Commercial Buildings, Educational Institutions, Warehouses, Hospitality Venues, Office Complexes Installation Type: New Construction, Retrofit, Integrated Building Systems, Standalone Setup End User: Facility Managers, Building Automation Companies, Energy Consultants, Property Developers |
| Companies Covered | Signify, Acuity Brands, Schneider Electric, Siemens, Honeywell, Johnson Controls, Legrand, Lutron Electronics, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Daylight Harvesting Systems Market Trends and Innovations
Wireless mesh networking is decomposing the traditional wired infrastructure model for daylight harvesting deployments, enabling retrofit installations without conduit runs and disrupting established electrical contractor workflows.
Daylight harvesting control architecture is decomposing into modular software-defined layers. Photosensors now stream raw illuminance data to edge computing nodes running open-source control algorithms, allowing facility managers to swap dimming strategies without hardware replacement. Higher education campuses and corporate headquarters with in-house engineering staff are piloting these disaggregated systems fastest.
EU Green Deal implementation is tightening F-Gas Regulation enforcement and overall building energy budgets, indirectly reinforcing demand for daylight-linked HVAC-lighting integration. Facility managers in Germany and the Netherlands now specify harvesting systems as mandatory components of whole-building automation tenders. Product suppliers with native software platforms gain specification preference over hardware-only vendors.
Electrical distributors are unbundling specification support from hardware procurement, responding to contractor demand for pre-engineered control sequences. Independent lighting design consultants now sell standardized daylight harvesting templates directly to mid-sized commercial developers, bypassing traditional manufacturer representative channels. This channel compression is most visible in Texas and Florida metropolitan construction markets.
Automated Daylight Harvesting Systems Market Segmentation
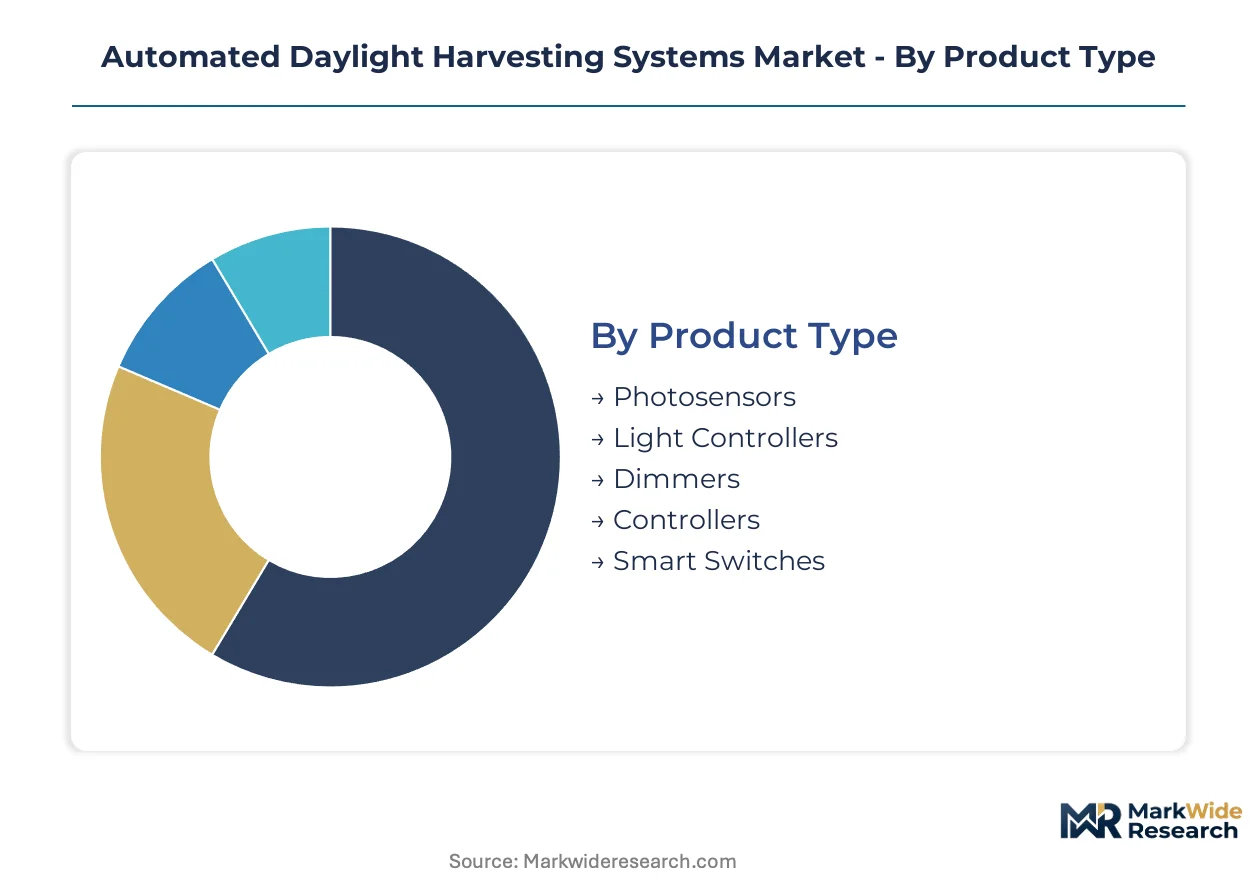
Segmentation in automated daylight harvesting systems reveals how hardware commoditization pressures intersect with installation complexity premiums. Procurement patterns diverge sharply between code-mandated new construction and discretionary retrofit upgrades, reshaping vendor pricing power across each slice.
Product Type:
Photosensors face the most acute substitution threat from integrated LED luminaires with embedded sensing, while discrete dimming controllers defend their specification position through protocol complexity barriers.
- Photosensors:Discrete silicon photodiode units with analog or digital output signals dominate perimeter zone installations. Demand concentrates in United States commercial retrofits where ASHRAE 90.1 compliance mandates independent sensing points, though luminaire-integrated alternatives are eroding standalone volumes in new construction.
- Light Controllers:Programmable logic devices executing closed-loop dimming algorithms based on photosensor feedback. Educational institutions in California represent the deepest application pool, driven by Title 24 Part 6 networked control mandates and available utility rebate stacking.
- Dimmers:Phase-cut or 0-10V output devices modulating LED driver current. Warehouses with high-bay skylight arrays generate concentrated demand for robust industrial-grade units.
- Controllers:Centralized processing units coordinating multi-zone harvesting networks. Hospitality venues in Florida and Texas specify these for integrated scene-setting alongside daylight modulation.
- Smart Switches:Wall-mounted user interfaces with override capabilities and energy monitoring. Building automation companies in Germany favor these for EU Green Deal-compliant facility upgrades.
Photosensors retain volume leadership; smart switches hold the steepest expansion curve.
Application:
Cost tier stratification separates code-minimum installations from premium integrated systems, with hospitality and educational verticals commanding 40-60% hardware premiums over warehouse baseline specifications.
- Commercial Buildings:Perimeter office zones and atrium spaces requiring maintained illuminance within ten percent variance. United States metropolitan construction markets absorb the highest absolute volumes, constrained by tightening utility interconnection rules in California and New York.
- Educational Institutions:K-12 classrooms and university lecture halls with predictable occupancy schedules. Deferred maintenance pressure in United States public school districts creates retrofit opportunity where rebate programs offset capital constraints.
- Warehouses:High-bay logistics facilities with expansive skylight arrays generating sub-three-year payback periods. Demand is climbing fastest among third-party logistics operators facing utility cost pressure.
- Hospitality Venues:Hotels and conference centers prioritizing guest comfort alongside energy reduction. Lutron Electronics' premium dimming algorithms command specification preference in this tier.
- Office Complexes:Corporate headquarters and multi-tenant buildings with whole-building automation mandates. Netherlands and Germany facility managers specify these as mandatory components of EU Green Deal tenders.
Commercial buildings dominate absolute revenue; warehouses are expanding most quickly.
Installation Type:
Customer type fragmentation separates sophisticated building automation integrators from electrical contractors executing commodity retrofit swaps, with capability gaps widening between these procurement channels.
- New Construction:Whole-building automation mandates in California Title 24 and ASHRAE 90.1 jurisdictions. Property developers in Texas and Florida metropolitan markets specify integrated systems as standard.
- Retrofit:Existing building upgrades driven by utility rebate programs and energy cost pressure. Wireless mesh networking is decomposing traditional wired infrastructure models, enabling installations without conduit runs.
- Integrated Building Systems:Daylight harvesting networks linked to HVAC controls via BACnet or Modbus protocols. Germany and Netherlands facility managers now treat these as mandatory in whole-building automation tenders.
- Standalone Setup:Discrete photosensor-dimmer pairs without network connectivity. Secondary United States markets with basic code compliance requirements sustain residual demand.
Integrated building systems command specification preference; retrofit installations are gaining share fastest.
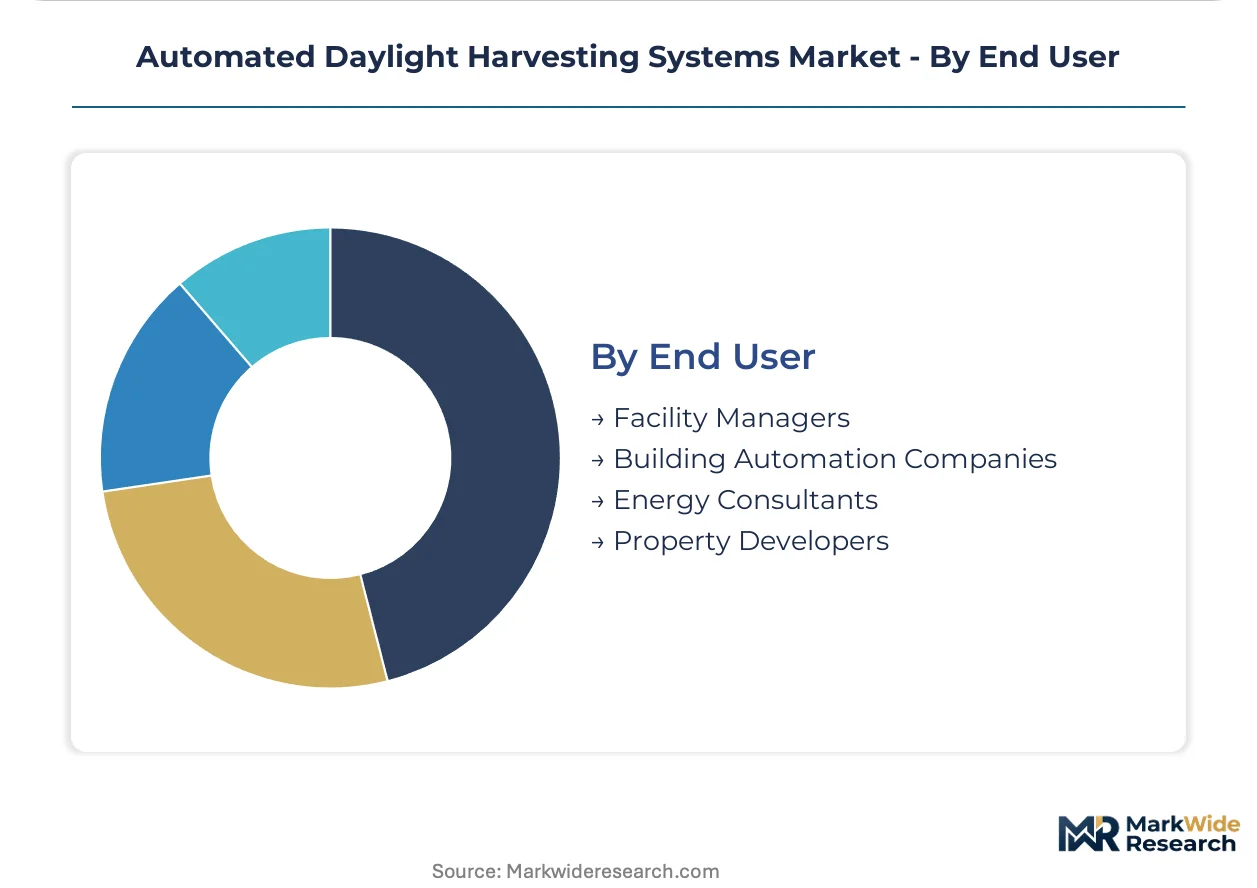
End User:
Supply concentration in controls engineering talent reshapes which end user segments can execute complex deployments, with energy consultants and building automation companies capturing margin from capability-scarce facility managers.
- Facility Managers:In-house building operators seeking utility expenditure reduction. Talent scarcity in lighting control engineering constrains their deployment velocity for complex retrofit projects.
- Building Automation Companies:System integrators specifying multi-protocol platforms with native software stacks. These vendors gain preference where bidirectional grid communication requirements emerge.
- Energy Consultants:Independent advisors stacking utility rebates and optimizing payback calculations. K-12 districts under capital constraints represent their fastest-growing client segment.
- Property Developers:Commercial real estate owners mandating harvesting systems for LEED certification or tenant attraction. California and New York jurisdictions dominate their procurement geography.
Building automation companies capture the highest project values; energy consultants are expanding their client base most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ASHRAE anchors demand concentration in the United States, where utility rebate programs and Title 24 mandates accelerate retrofit installations. Facility managers in Germany and the Netherlands specify daylight harvesting as mandatory components of EU Green Deal tenders. China and Japan round out the geographic footprint with diverging regulatory drivers.
United States
Commercial building portfolios expand adoption as energy codes tighten across metropolitan construction markets. ASHRAE Standard 90.1 and California Title 24 Part 6 create compliance-driven procurement pipelines for electrical contractors. Texas and Florida property developers specify integrated systems as standard in new construction.
Germany
Facility managers treat daylight harvesting as mandatory in whole-building automation tenders under EU Green Deal implementation. The F-Gas Regulation tightens overall building energy budgets, pushing integration with chilled beam and VAV systems. Industrial clusters in Bavaria and North Rhine-Westphalia pilot disaggregated software-defined control architectures.
Netherlands
Corporate headquarters and multi-tenant buildings mandate networked lighting controls for LEED certification and tenant attraction. The EU Green Deal reinforces demand for daylight-linked HVAC-lighting integration. Amsterdam and Rotterdam metropolitan markets absorb concentrated specification activity from building automation integrators.
China
Yangtze River Delta and Pearl River Delta manufacturing bases supply silicon photodiode components to North American system integrators. Dual carbon goals and GB standards tighten commercial building energy efficiency requirements. Shanghai facility managers pilot bidirectional communication between harvesting networks and grid operators.
Japan
METI efficiency standards and JIS certification frameworks shape product specifications in corporate headquarters and educational institutions. Kanto and Kansai regions concentrate demand for premium dimming algorithms in hospitality venues. Tokyo-based building automation companies specify multi-protocol platforms with native software stacks.
Automated Daylight Harvesting Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the automated daylight harvesting systems market. The vendor base separates into three tiers: diversified electrical conglomerates with vertical manufacturing footprints, specialized lighting control engineers with premium algorithm portfolios, and building automation integrators with multi-protocol software platforms. Strategic moves concentrate on installer training program expansion and deep specification relationships with electrical contractors.
Among diversified electrical conglomerates, Signify and Schneider Electric occupy positions spanning hardware manufacturing through software platform development. Legrand and ABB exemplify the building automation integrator archetype with specification preference where networked control mandates emerge. Lutron Electronics anchors the specialized engineering tier with concentration in premium venue applications.
| Leading Market Players |
|---|
| Signify |
| Acuity Brands |
| Schneider Electric |
| Siemens |
| Honeywell |
| Johnson Controls |
| Legrand |
| Lutron Electronics |
| ABB |
| Others |
Pricing and Supply Chain Analysis
Luminaire-integrated photosensors replacing discrete silicon photodiode units simultaneously concentrate component sourcing in East Asian LED manufacturing clusters and compress hardware margins for North American system integrators by eliminating separate mounting hardware and halving installation labor.
Pricing Analysis
Price spreads between United States and European procurement run 15-25 percent for equivalent hardware specifications due to ASHRAE 90.1 compliance premiums and California Title 24 networked control mandates. Project-based transactional pricing dominates, with differentiation driven by certification tier (UL versus CE marking) and after-sales commissioning support. Cost compression in standard-tier hardware intensifies as Chinese LED OEMs bundle sensing capabilities at marginal cost. Facility managers in secondary United States markets exhibit highest price sensitivity, while hospitality venue operators in Florida and Texas accept premium algorithms for guest experience optimization.
Supply Chain Analysis
China and Taiwan anchor silicon photodiode wafer fabrication and LED luminaire final assembly, while Germany and the Netherlands concentrate building automation platform integration. Discrete sensor production draws from Yangtze River Delta component suppliers, with solid-state sensing elements and programmable logic controllers as critical inputs. Single-source vulnerability in East Asian foundry capacity exposes North American integrators to lead time volatility during semiconductor allocation cycles. Distribution runs through electrical distributor networks unbundling specification support from hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined control architectures and recurring firmware subscription layers expand faster than hardware shipments as facility managers seek dimming strategy flexibility without hardware replacement cycles.
For Market Incumbents: Secure installer training program expansion to buffer against collapsing lighting control engineering talent across North America. Deepen specification relationships with electrical contractors in Texas and Florida metropolitan construction markets where integrated system mandates accelerate. Counter wireless mesh retrofit entrants by emphasizing BACnet and Modbus protocol compatibility in whole-building automation tenders. For New Entrants and Emerging Players: Lead with pre-engineered control sequence templates sold direct to mid-sized commercial developers, bypassing traditional manufacturer representative channels. Target K-12 educational institution retrofits in United States public school districts where deferred maintenance pressure and utility rebate stacking offset capital constraints. Emphasize commissioning simplicity as the primary go-to-market wedge against established hardware vendors. For Investors and Strategic Acquirers: The market sits at a code-mandated acceleration phase that favors building automation integrators with native software platforms over hardware-only vendors. Long-term viability over the next decade hinges on bidirectional grid communication capabilities as utility interconnection rules evolve. Acquisition candidates with open-source algorithm portfolios and edge computing node architectures merit priority evaluation. Monitor California Title 24 Part 6 expansion into smaller commercial buildings as the inflection signal for mid-market segment penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Installer Training Program Expansion | Signify's vertical manufacturing footprint buffers lead times while building certified contractor networks in ASHRAE 90.1 jurisdictions. |
| Wireless Mesh Platform Launch | Retrofit installations without conduit runs disrupt established electrical contractor workflows and accelerate warehouse upgrade timelines. |
| Daylight-HVAC Integration Partnership | Legrand and ABB command premium specification positions where EU Green Deal tenders mandate whole-building automation convergence. |
| Open-Source Algorithm Licensing | Disaggregated software-defined layers allow facility managers to swap dimming strategies without hardware replacement cycles. |
| Utility Rebate Stacking Service | Energy consultants capture margin from capability-scarce facility managers in K-12 districts under deferred maintenance pressure. |
Research Methodology
A standing panel of lighting control engineers, electrical contractor specification leads, facility management directors, and building automation integrators provided ongoing calibration across primary fieldwork. Secondary validation drew from ASHRAE standard documentation, California Title 24 Part 6 code cycles, EU Green Deal implementation filings, and utility rebate program databases. Customs records from Yangtze River Delta and Pearl River Delta export zones supplemented hardware shipment analysis. Bottom-up project pipeline tracking and top-down building stock penetration estimates were triangulated against manufacturer production disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation by product type, application vertical, installation category, and end-user archetype, with additional dimensioning by regulatory jurisdiction cluster. CAGRs were derived from installed base turnover rates and new construction mandate timing. Forecast inputs incorporated photosensor miniaturization curves, wireless mesh adoption slopes, and controls engineering talent pipeline constraints.
Forecasts assume regulatory continuity in ASHRAE 90.1 update cycles, California Title 24 Part 6 expansion, and EU Green Deal F-Gas Regulation enforcement; material policy shifts would require re-modeling procurement elasticity assumptions. Supply chain disruptions in East Asian semiconductor foundries or silicon photodiode component allocation represent specific revision triggers. Recalibration cycles align with material shifts in building energy code stringency and utility interconnection rule evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Zero Energy Buildings Market
Building Automation Systems
Global Door Closers Market
Building Automation Systems
Building-To-Grid Technology Market
Building Automation Systems
Global Solar Shading Systems Market
Building Automation Systems
Signage Market
Building Automation Systems
Electrochromic Glass Market
Building Automation Systems
Europe HVAC Controls Market
Building Automation Systems
Underfloor Heating Actuator Market
Building Automation Systems
Building Automation and Control System Market
Building Automation Systems
Elevator Modernization Market
Building Automation Systems
Rotary Sprinkler System Market
Building Automation Systems
Architecture Smart Glass Market
Building Automation Systems
Building Technologies Market
Building Automation Systems
Global Modularization Market
Building Automation Systems
Europe Commercial Refrigeration Market
Building Automation Systems
Infrastructure Monitoring Market