
 Global Modularization Market | 2026-2036
Global Modularization Market Size, Share, and Industry Trends Forecast 2026-2036
Global Modularization Market Foresight
Skilled prefabrication labor availability is bifurcating the competitive landscape into firms with captive training pipelines and those facing project delays. Honeywell International leverages its process automation expertise to anchor modular control system integration. Siemens competes through factory-standardized electrical skids that reduce onsite commissioning hours. ABB differentiates with robotics-integrated module production lines serving energy sector clients.
Modularization denotes the industrial practice of designing, fabricating, and assembling discrete building or process units in controlled factory conditions before transporting them to final installation sites, typically achieving dimensional tolerances within two millimeters and compressing construction schedules by thirty to fifty percent versus stick-built methods. The technique serves primary commercial purposes across commercial construction, infrastructure projects, and temporary facilities where speed, quality control, and labor efficiency command premium value. Modular buildings occupy the largest revenue share given their deployment across healthcare, education, and residential verticals, while container modules represent the fastest-expanding category driven by port-adjacent logistics hubs and data center expansion. Sub-assemblies concentrate margin pools among specialist engineering firms supplying mechanical-electrical-plumbing packages to tier-one integrators.
Factory fabrication standards in Germany fall under KBA and regional building code enforcement, while OSHA and FAA regulations govern module transport and crane-lift operations in the United States, and China's GB standards plus MIIT directives shape steel fabrication and module certification protocols. These regulatory frameworks dictate weld inspection frequencies, transport weight limits, and fire-resistance ratings that directly determine product design and market access eligibility. Stakeholders must monitor evolving carbon accounting rules under the EU Green Deal and China's dual carbon goals, as embodied emissions thresholds will increasingly determine which module suppliers qualify for public infrastructure procurement.
Market Dynamics
Factory fabrication protocols are tightening dimensional tolerances while compressing project delivery windows, forcing integrators to choose between captive production capacity and third-party module sourcing. This structural pressure is bifurcating the competitive landscape based on capital deployment speed and quality certification depth.
Growth Catalysts
- EU Green Deal embodied emissions thresholds:Public infrastructure procurement in Germany and France now favors module suppliers with verified carbon accounting, redirecting contract flows toward prefabrication specialists with factory-controlled material efficiency.
- Healthcare vertical expansion:Hospital systems in Australia and the United States are specifying modular patient towers and surgical suites to minimize onsite disruption in dense urban campuses.
- Cross-laminated timber (CLT) panel systems:This engineered wood product is penetrating mid-rise residential modules in Japan and Canada, offering seismic resilience alongside reduced foundation loads.
Market Restraints
- Specialized welder shortages:AWS-certified structural welders for steel module fabrication concentrate in Poland and South Korea, creating bottleneck risk for projects requiring D1.1 compliance.
- Transport weight limits:FAA crane-lift regulations and state-level oversize permitting in the United States restrict module dimensions, forcing design fragmentation that erodes factory efficiency gains.
- Onsite foundation precision requirements:Two-millimeter module tolerance demands are clashing with legacy concrete pad variability, requiring costly pre-installation surveying and shimming protocols.
Strategic Opportunities
- Data center container modules:Hyperscale operators in Northern Virginia and Frankfurt are specifying liquid-cooled modular units to compress commissioning timelines for AI training clusters.
- India's PLI scheme for construction materials:Domestic module fabrication incentives are drawing steel integrators to Gujarat and Tamil Nadu industrial corridors for port-adjacent export capacity.
- Digital twin integration:Convergence of BIM workflows with factory MES systems is enabling real-time quality tracking that differentiates tier-one integrators in competitive bidding.
Industry Challenges
- Multi-jurisdiction certification timelines:Modules requiring KBA approval for German deployment plus OSHA compliance for US installation face sequential review queues that extend order-to-delivery windows.
- Legacy MEP integration complexity:Factory-built modules meeting GB standards for Chinese fabrication must be re-engineered for compatibility with US National Electrical Code conduit sizing, duplicating design effort.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Modularization Market |
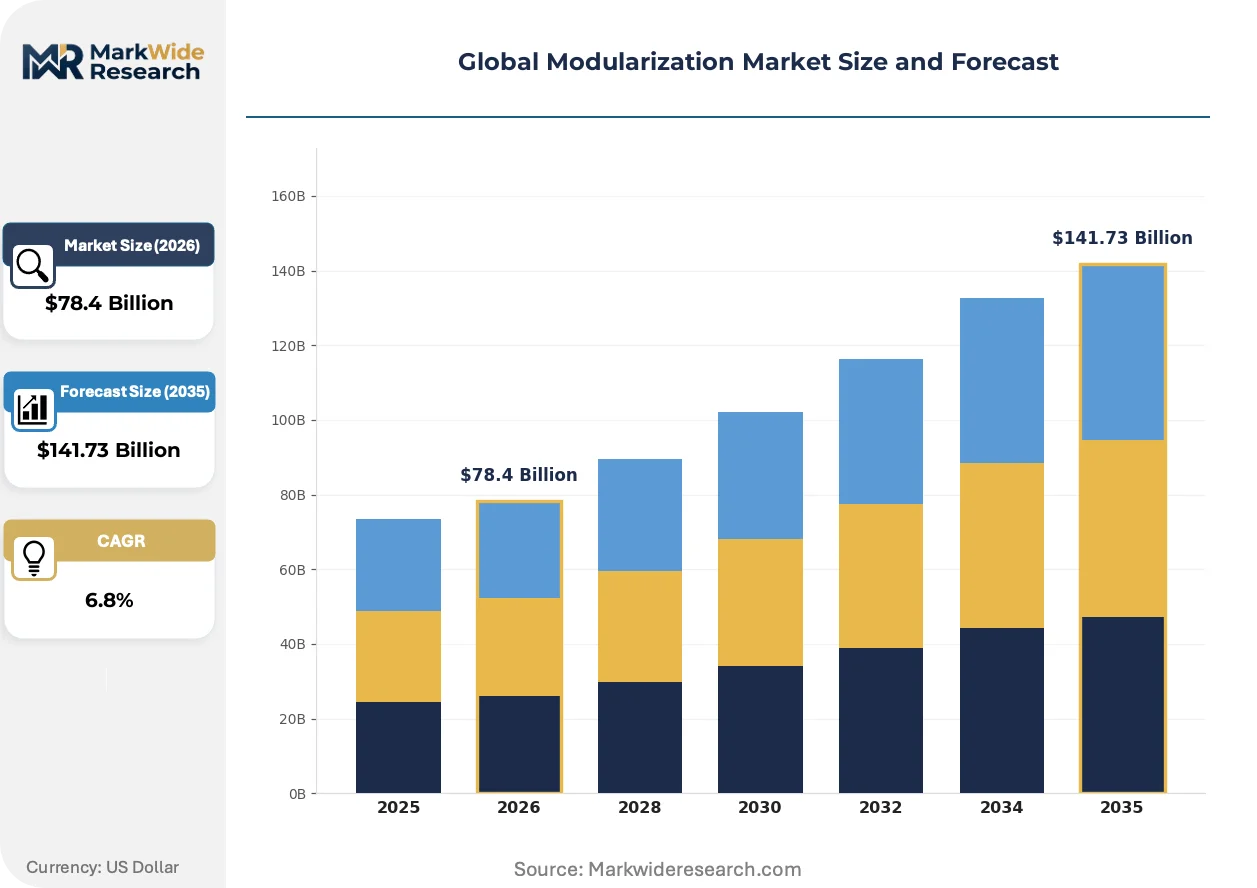
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Buildings, Prefabricated Modules, Sub-Assemblies, Container Modules Application: Commercial Construction, Infrastructure Projects, Temporary Facilities, Disaster Relief End User Sector: Construction Contractors, Government Agencies, Event Organizers, Engineering Firms Deployment Method: Onsite Assembly, Offsite Fabrication, Hybrid Modularization, Mobile Unit Setup |
| Companies Covered | Honeywell International, General Electric, ABB, Eaton, Hitachi, Yaskawa Electric Corporation, Siemens, Rockwell Automation, Festo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Modularization Market Shifts & Advancements
Digital fabrication workflows and carbon-accounting transparency are converging to redefine competitive advantage in module supply. These shifts are compressing traditional procurement cycles while elevating factory certification as a primary selection criterion.
Robotic welding cells equipped with machine vision are displacing manual seam tracking in structural steel module production. European shipyard integrators are adopting these systems at pace to meet EU Green Deal traceability requirements for public hospital contracts. The technology is displacing conventional QA sampling protocols by enabling 100% weld inspection without throughput penalty.
China's MIIT directives on steel fabrication emissions intensity are tightening GB standard compliance for export-bound modules. Factory operators in Jiangsu and Shandong provinces are retrofitting electric arc furnace feedstock systems to maintain market access eligibility. Energy sector module buyers are responding by shifting procurement qualification weight toward embodied carbon disclosure.
Integrated design-build contracts are consolidating module specification authority with single-source integrators rather than fragmented architect-contractor relationships. Healthcare and education verticals in Australia are leading this transition, bundling performance guarantees with accelerated delivery commitments. This compression is most visible in Sydney and Melbourne where labor availability constraints favor turnkey module procurement over stick-built alternatives.
Global Modularization Market Segmentation
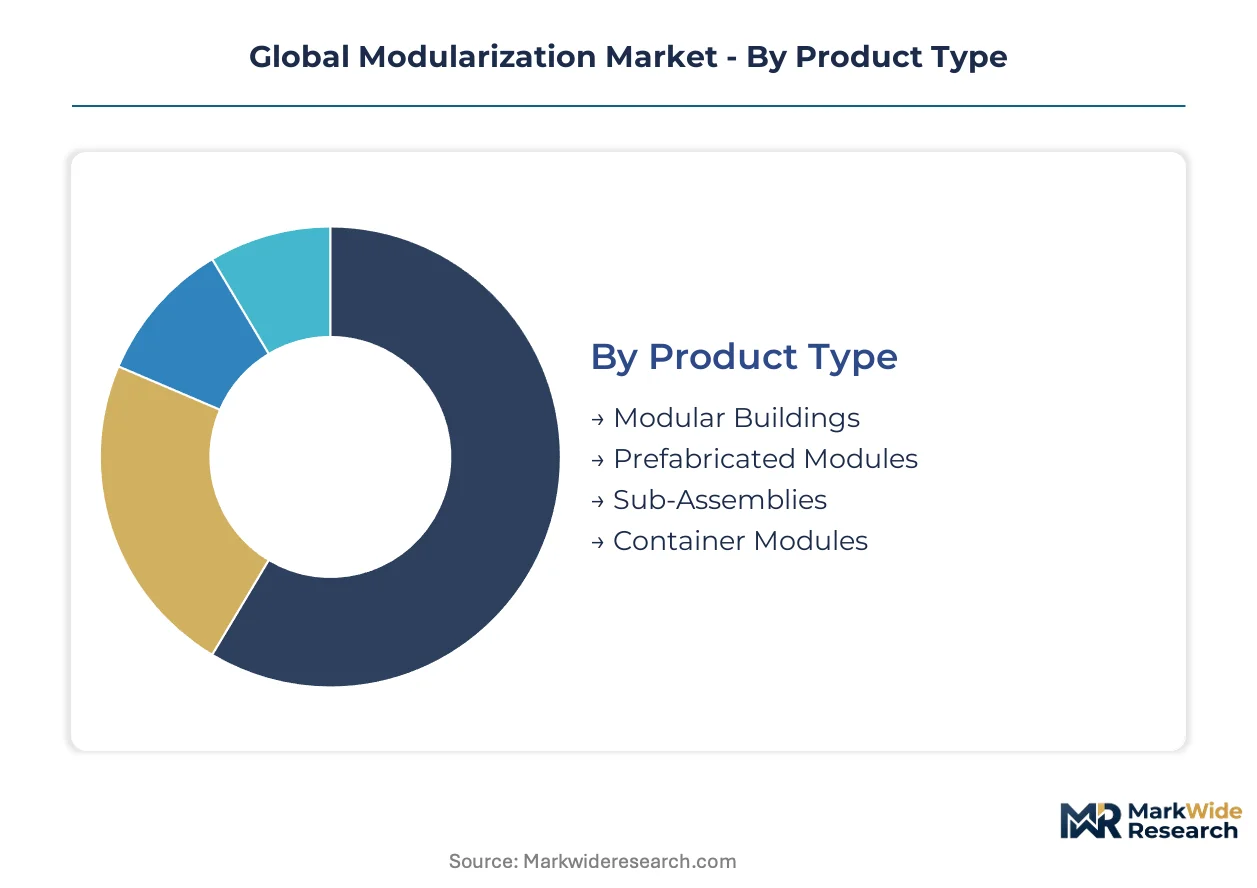
Segmentation in modularization reveals where factory fabrication protocols create defensible margin pools versus commoditized competition. Understanding substitution pressures across product architectures and deployment methods determines capital allocation for integrators and component suppliers.
Product Type:
Container modules face acute substitution pressure from refurbished shipping containers in temporary applications, forcing certified fabricators to differentiate through climate control integration and seismic bracing.
- Modular Buildings:These are complete volumetric units with integrated MEP systems, structural frames, and interior finishes fabricated under factory-controlled conditions. Demand concentrates in United States healthcare verticals where OSHA compliance and infection control protocols favor hospital-grade cleanroom modules over conventional construction. Labor shortages in dense urban campuses accelerate specification.
- Container Modules:Repurposed or purpose-built intermodal containers configured for data centers, workforce housing, or mobile offices. Northern Virginia hyperscale operators specify liquid-cooled variants to compress AI cluster commissioning timelines, while port-adjacent logistics hubs in Hamburg and Singapore drive standardization.
- Prefabricated Modules:Pre-engineered structural and envelope assemblies requiring onsite MEP connection and interior fit-out.
- Sub-Assemblies:Discrete mechanical-electrical-plumbing packages supplied to tier-one integrators.
Modular buildings retain volume leadership; container modules hold the steepest expansion curve.
Application:
Cost tier differentiation separates performance-guaranteed healthcare contracts from price-sensitive disaster relief procurement, with infrastructure projects occupying the contested middle ground.
- Commercial Construction:Permanent facilities including offices, retail, and hospitality delivered through design-build contracts. Sydney and Melbourne healthcare systems bundle performance guarantees with accelerated delivery commitments, consolidating specification authority with single-source integrators rather than fragmented architect-contractor relationships.
- Infrastructure Projects:Transportation hubs, utilities, and public works requiring multi-jurisdiction certification. German KBA approval sequences with OSHA compliance extend order-to-delivery windows for export-bound modules.
- Temporary Facilities:Short-occupancy structures for events, seasonal workforce housing, or interim healthcare capacity.
- Disaster Relief:Rapid-deployment shelters and medical units prioritized for speed over durability specifications.
Commercial construction commands premium pricing; infrastructure projects carry the longest certification cycles.
End User Sector:
Customer type fragmentation concentrates procurement sophistication with engineering firms and government agencies, while event organizers drive spot-market volatility.
- Construction Contractors:General and specialty contractors seeking schedule compression through offsite fabrication. Australian tier-one firms with captive training pipelines capture contracts from competitors facing AWS-certified welder shortages.
- Government Agencies:Public infrastructure buyers with embodied emissions thresholds under EU Green Deal and China's dual carbon goals. Verified carbon accounting redirects contract flows toward prefabrication specialists with factory-controlled material efficiency.
- Engineering Firms:Specialist designers and integrators consolidating module specification authority.
- Event Organizers:Short-cycle buyers prioritizing rapid availability over long-term performance warranties.
Construction contractors drive procurement volume; government agencies are tightening qualification standards fastest.
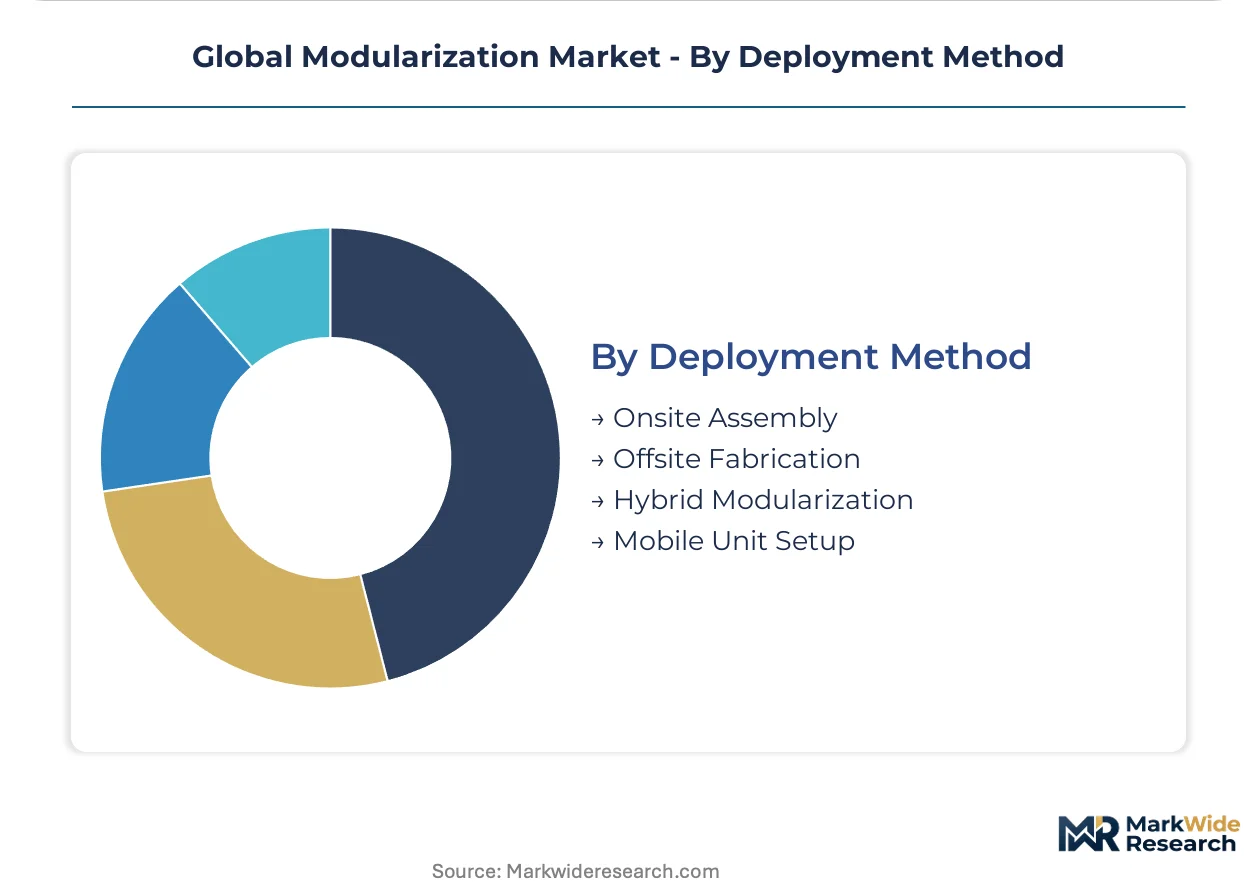
Deployment Method:
Supply concentration in offsite fabrication creates margin pressure on hybrid approaches that fragment quality accountability across factory and site teams.
- Offsite Fabrication:Complete module production in controlled factory environments achieving dimensional tolerances within two millimeters. Jiangsu and Shandong province operators retrofit electric arc furnace feedstock systems to meet China's MIIT emissions intensity directives for export eligibility.
- Hybrid Modularization:Split fabrication with structural elements factory-built and MEP systems site-installed. Legacy conduit sizing mismatches between GB standards and US National Electrical Code force re-engineering duplication.
- Onsite Assembly:Component kit installation requiring extensive field labor.
- Mobile Unit Setup:Transportable systems deployed without permanent foundation anchoring.
Offsite fabrication dominates revenue capture; hybrid modularization is gaining share where transport weight limits force design fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA regulations in the United States govern module transport and crane-lift operations, establishing baseline safety protocols that influence factory design standards across export markets. Labor shortages and urban density pressures in specific national markets are redirecting procurement toward offsite fabrication methods.
United States
Hospital systems specify modular patient towers and surgical suites to minimize onsite disruption in dense urban campuses. FAA crane-lift regulations and state-level oversize permitting restrict module dimensions, forcing design fragmentation. Northern Virginia hyperscale operators drive demand for liquid-cooled container modules serving AI training clusters.
Germany
Public infrastructure procurement favors module suppliers with verified carbon accounting under EU Green Deal embodied emissions thresholds. KBA factory fabrication standards and regional building code enforcement dictate weld inspection frequencies and fire-resistance ratings. Hamburg port-adjacent logistics hubs standardize container module specifications for European distribution.
China
MIIT directives on steel fabrication emissions intensity tighten GB standard compliance for export-bound modules. Factory operators in Jiangsu and Shandong provinces retrofit electric arc furnace feedstock systems to maintain market access eligibility. Dual carbon goals redirect public infrastructure procurement toward suppliers with factory-controlled material efficiency.
Australia
Healthcare and education verticals bundle performance guarantees with accelerated delivery commitments, consolidating specification authority with single-source integrators. Sydney and Melbourne labor availability constraints favor turnkey module procurement over stick-built alternatives. Tier-one firms with captive training pipelines capture contracts from competitors facing certified welder shortages.
Japan
Cross-laminated timber panel systems penetrate mid-rise residential modules, offering seismic resilience alongside reduced foundation loads. METI sustainability frameworks accelerate material efficiency requirements for factory-built construction. Prefabrication specialists with captive supply chains capture contracts in dense urban corridors facing demographic labor pressure.
Global Modularization Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where process automation expertise commands premium positioning. The vendor base spans industrial conglomerates with captive module production, specialized engineering firms supplying MEP packages, and factory-standardized electrical skid manufacturers. Three strategic archetypes dominate: integrators with robotics-integrated production lines, specialists in control system modularization, and scale-driven fabricators with captive training pipelines. Competitive moves concentrate on strategic partnerships for digital twin integration and capacity expansion in port-adjacent industrial corridors.
Among diversified industrial conglomerates, Honeywell International, ABB, and Siemens occupy positions that exemplify distinct competitive vectors. Honeywell International represents the process automation-anchored archetype leveraging control system integration capabilities. ABB sits within the robotics-integrated production tier serving energy sector module requirements. Siemens exemplifies factory-standardized electrical skid manufacturing that reduces onsite commissioning hours. Each company structure reflects geographic origin through suffix patterns—International, AG-equivalent positioning, and the German-rooted naming convention respectively.
| Leading Market Players |
|---|
| Honeywell International |
| General Electric |
| ABB |
| Eaton |
| Hitachi |
| Yaskawa Electric Corporation |
| Siemens |
| Rockwell Automation |
| Festo |
| Others |
Supply & Pricing Matrix
Factory utilization rates above eighty percent in Jiangsu and Shandong provinces compress per-unit fixed costs while elevating price floors for smaller fabricators lacking comparable throughput. This scale asymmetry concentrates procurement power with tier-one integrators and forces mid-tier suppliers toward commodity positioning in container module segments.
Pricing Analysis
Price spreads between German KBA-certified modules and standard-grade Asian exports exceed thirty percent on equivalent volumetric units. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth and carbon disclosure granularity. Cost compression in the economy tier intensifies because refurbished shipping containers flood temporary facility applications. Government agencies exhibit lowest price sensitivity given EU Green Deal procurement mandates, while event organizers drive spot-market volatility.
Supply Chain Analysis
China, South Korea, and Poland anchor structural steel module fabrication through distinct specialization patterns. Jiangsu province draws from electric arc furnace feedstock, while Polish fabricators rest on AWS-certified welder concentrations for D1.1 compliance. Single-source vulnerability concentrates in AWS-certified structural welder availability. Distribution runs through port-adjacent logistics hubs in Hamburg, Singapore, and Northern Virginia for hyperscale data center deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Modularization Market is recovering from cyclical lows in commercial construction investment, with healthcare vertical capital expenditure serving as the primary demand restocking mechanism.
For Market Incumbents: Shield margin pools in healthcare and education verticals by deepening captive training pipelines for AWS-certified welders. Accelerate certification investment for EU Green Deal carbon accounting to preempt qualification exclusion from German and French public infrastructure tenders. Consolidate specification authority through integrated design-build contracts that fragment competitor access in Australian urban corridors. For New Entrants and Emerging Players: Differentiate on digital twin integration capabilities that converge BIM workflows with factory MES systems for real-time quality tracking. Target India's PLI scheme construction materials incentives in Gujarat and Tamil Nadu industrial corridors where domestic fabrication incentives lack established incumbent density. Pursue data center container module specialization serving Northern Virginia and Frankfurt hyperscale operators with liquid-cooled variants. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrators with robotics-integrated production lines and verified carbon accounting infrastructure over pure-play fabricators. Long-term viability across a five-to-ten year window rests on regulatory qualification depth rather than unit cost minimization. Monitor MIIT emissions intensity directive enforcement as the inflection signal for Chinese export eligibility compression.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Welding Cell Deployment | Machine vision-enabled seam tracking displaces manual QA sampling for EU Green Deal traceability compliance. |
| Electric Arc Furnace Retrofit | Jiangsu and Shandong operators reduce emissions intensity to maintain MIIT GB standard export eligibility. |
| Digital Twin Integration | BIM-MES convergence enables real-time quality tracking that differentiates tier-one integrators in competitive bidding. |
| Captive Welder Training Pipeline | Australian tier-one firms capture contracts from competitors facing AWS-certified structural welder shortages. |
| Port-Adjacent Capacity Expansion | Hamburg and Singapore logistics hubs standardize container module specifications for European distribution. |
Research Methodology
Initial hypotheses were tested against primary input from module fabrication plant managers, EPC contractor procurement leads, hospital facility directors, and steel integrator technical directors and refined through secondary validation. Construction industry SEC filings, KBA factory audit records, EU Green Deal procurement databases, and MIIT directive compliance filings anchored quantitative baselines. Bottom-up module shipment tallies and top-down construction expenditure aggregates were triangulated to reconcile volume estimates.
Variance decomposition across product type, application vertical, deployment method, and end-user sector isolates growth contribution by segment. CAGRs were derived from logistic diffusion curves fitted to historical adoption patterns and forward-projected against regulatory enforcement timelines. Forecast inputs incorporated embodied emissions threshold implementation schedules under EU Green Deal and China's dual carbon goals.
Decision-makers should treat outputs as directional under sustained healthcare capital expenditure and carbon accounting enforcement assumptions; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Architecture Smart Glass Market
Building Automation Systems
Rotary Sprinkler System Market
Building Automation Systems
Global Solar Shading Systems Market
Building Automation Systems
US Commercial Building Automation Market
Building Automation Systems
Building Automation and Control System Market
Building Automation Systems
Integrated Building Management Systems Market
Building Automation Systems
United States Building Automation Controls Market
Building Automation Systems
Asia-Pacific Building Automation System Market
Building Automation Systems
Europe Smart Windows Market
Building Automation Systems
Dumbwaiter Lifts Market
Building Automation Systems
Underfloor Heating Actuator Market
Building Automation Systems
China Revolving Doors Market
Building Automation Systems
North America Building Automation System Market
Building Automation Systems
Collapsible Gates Market
Building Automation Systems
Flushing Systems Market
Building Automation Systems
Global HVAC Controls Market