
 United States Building Automation Controls Market | 2026-2036
United States Building Automation Controls Market Size, Share, and Industry Trends Forecast 2026-2036
United States Building Automation Controls Market Analytics
The Inflation Reduction Act's commercial building deduction framework is consolidating investment priorities across U.S. facility portfolios toward electrified, sensor-rich environments. Honeywell International leverages its distributed sensing architecture to capture retrofit flows in aging office stock. Johnson Controls International anchors large campus deployments through performance contracting models. Siemens AG differentiates on digital twin integration for predictive HVAC optimization.
Building automation controls encompass networked hardware and software systems that regulate mechanical, electrical, and environmental functions within structures, typically operating through BACnet or Modbus protocols with response latencies under 100 milliseconds for critical loop control. HVAC Controls command the largest installed base due to thermal load management requirements across commercial portfolios. Cloud-Based Solutions represent the fastest-expanding technology dimension as remote commissioning and AI-driven fault detection displace on-premise server architectures. Energy Management Systems concentrate margin pools through subscription-based analytics layers that monetize utility demand-response participation.
ASHRAE Standard 90.1, the EPA's ENERGY STAR certification pathway, and state-level stretch codes adopted by California's Energy Commission collectively mandate granular metering and automated demand response capability for new construction and major renovations. The Department of Energy's appliance and equipment standards program further tightens baseline efficiency thresholds that automation must enable. Stakeholders must weigh interoperability protocol selection against cybersecurity compliance obligations as federal critical infrastructure designations expand to building systems.
Market Dynamics
The Inflation Reduction Act's efficiency incentives are consolidating capital flows toward retrofit automation in aging commercial portfolios, redirecting facility investment priorities from new construction to sensor-rich electrification of existing building stock.
Growth Catalysts
- Utility Rebate Structures:State-level demand-response programs in California, Texas, and New York metro corridors accelerate payback periods for automated HVAC retrofits.
- Stretch Code Adoption:California's Energy Commission mandates granular metering and automated demand response for major renovations, expanding addressable retrofit volume.
- Cloud-Based Platforms:Remote commissioning and AI-driven fault detection displace on-premise server architectures, reducing deployment friction for mid-market facilities.
Market Restraints
- Semiconductor Supply Concentration:BACnet and Modbus controller chipsets face sourcing volatility from concentrated Asian foundry capacity.
- Legacy Protocol Fragmentation:Interoperability gaps between proprietary vendor ecosystems create integration friction and extend project timelines.
- Cybersecurity Compliance Burden:Expanding federal critical infrastructure designations impose audit and certification costs on building system deployments.
Strategic Opportunities
- Texas Metro Corridors:Rapid commercial construction and lax legacy infrastructure create greenfield automation demand unmatched by retrofit complexity.
- Digital Twin Convergence:Integration of building information modeling with real-time sensor feeds enables predictive HVAC optimization for large campus portfolios.
- Subscription Analytics Layers:Energy Management Systems monetize utility demand-response participation through recurring revenue models.
Industry Challenges
- Control Systems Integration:Facility teams lack expertise bridging IT network security requirements with operational technology commissioning protocols.
- Certification Timeline Compression:ASHRAE Standard 90.1 updates and EPA ENERGY STAR pathway revisions accelerate compliance recertification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Building Automation Controls Market |
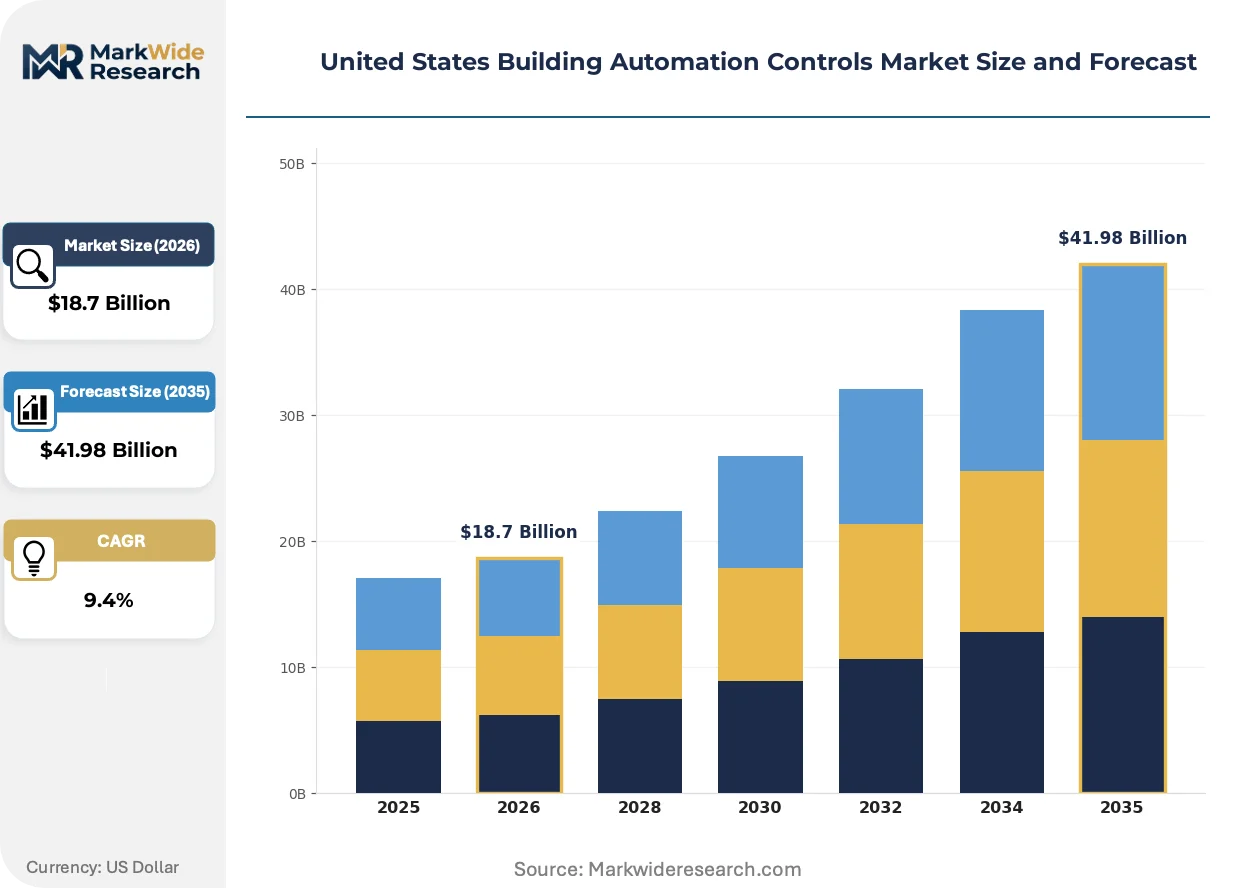
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lighting Controls, HVAC Controls, Security Controls, Energy Management Systems End User: Commercial Buildings, Residential Properties, Industrial Facilities, Educational Institutions Technology: Wired Systems, Wireless Systems, Cloud-Based Solutions, Hybrid Systems Installation Type: New Construction, Retrofit Projects, Integrated Systems, Standalone Solutions |
| Companies Covered | Honeywell International, Johnson Controls International, Siemens AG, Schneider Electric, ABB Ltd, Trane Technologies, Carrier Global Corporation, Lutron Electronics, Hubbell, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Building Automation Controls Market Evolving Landscape
Edge computing architectures are redistributing processing load from centralized servers to distributed sensor nodes, collapsing response latencies for critical loop control while enabling new predictive maintenance service models.
Wireless mesh networking for building automation is decentralizing sensor deployment economics by eliminating structured cabling requirements in retrofit environments. Multi-tenant office portfolios in New York and Chicago are adopting battery-powered environmental sensors at accelerated replacement cycles. The shift is decentralizing incumbent wired system architectures and compressing installation labor costs by roughly half.
The EPA's ENERGY STAR certification pathway now mandates automated demand response capability as a prerequisite for commercial building eligibility. Facility managers must demonstrate sub-100 millisecond load curtailment response to grid signals. Large suburban office campuses in Texas and California are retrofitting legacy HVAC controls fastest to maintain portfolio-wide certification status.
Performance contracting models are displacing capital expenditure procurement for campus-scale automation deployments. Universities and hospital systems in the Northeast are prioritizing energy savings guarantees over equipment ownership. The shift concentrates vendor selection criteria on guaranteed savings verification rather than upfront hardware specifications, favoring contractors with balance sheet capacity to underwrite long-term performance risk.
United States Building Automation Controls Market Segmentation
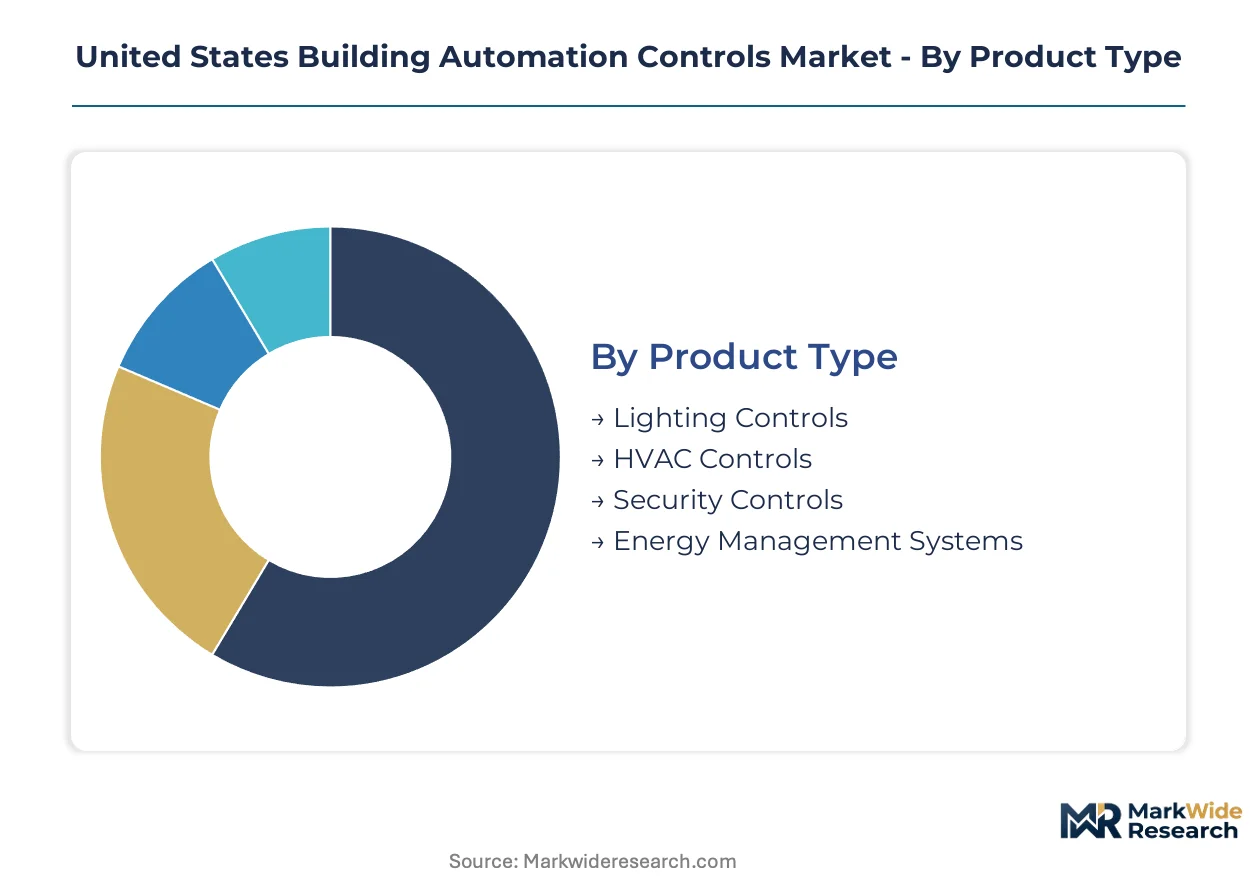
Segmentation in the United States building automation controls market reveals how capital allocation priorities diverge across facility types and technology architectures. Procurement patterns in California, Texas, and New York metro corridors concentrate demand in specific product and installation categories driven by local code stringency and utility incentive structures.
Product Type:
Facility managers select automation products based on thermal load intensity, security exposure, and utility demand-response participation potential.
- HVAC Controls:Networked hardware regulating heating, ventilation, and air conditioning through BACnet or Modbus protocols with sub-100 millisecond response latencies. Demand concentrates in aging office stock across California and Texas where ASHRAE Standard 90.1 compliance deadlines accelerate retrofit timelines.
- Energy Management Systems:Software platforms with subscription-based analytics layers monetizing utility demand-response participation. Large suburban office campuses in Texas prioritize these systems to maintain EPA ENERGY STAR certification status amid automated load curtailment mandates.
- Lighting Controls:Occupancy and daylight harvesting systems reducing electrical load through sensor-driven dimming protocols.
- Security Controls:Access management and surveillance integration platforms protecting commercial portfolios against physical and cyber intrusion.
HVAC Controls lead volumes today; Energy Management Systems are gaining share fastest.
End User:
Building automation adoption intensity tracks square footage under professional facility management and exposure to state-level efficiency mandates.
- Commercial Buildings:Multi-tenant office, retail, and hospitality portfolios with centralized mechanical systems and professional energy management staffing. California's Title 24 and New York's Local Law 97 carbon caps drive the fastest deployment velocity in this segment.
- Educational Institutions:K-12 districts and university campuses with complex HVAC requirements and public procurement transparency obligations. Northeast universities prioritize performance contracting models with guaranteed savings verification over capital expenditure procurement.
- Industrial Facilities:Manufacturing and warehouse environments with process-critical environmental control and high baseline energy consumption.
- Residential Properties:Multi-family housing and luxury single-family developments with smart home integration expectations.
Commercial Buildings anchor installed base; Educational Institutions show steepest expansion trajectory.
Technology:
Technology selection hinges on legacy infrastructure density, IT security posture, and commissioning timeline pressure.
- Cloud-Based Solutions:Architectures displacing on-premise server infrastructure through remote commissioning and AI-driven fault detection capabilities. Mid-market facilities in Texas metro corridors adopt these fastest where greenfield construction avoids legacy protocol fragmentation.
- Wireless Systems:Battery-powered environmental sensors using mesh networking to eliminate structured cabling in retrofit environments. New York and Chicago multi-tenant office portfolios compress installation labor costs by roughly half through accelerated replacement cycles.
- Wired Systems:Traditional BACnet and Modbus deployments with proven reliability for critical loop control in hospital and data center applications.
- Hybrid Systems:Architectures combining wired backbone infrastructure with wireless edge sensor extensions for phased upgrade paths.
Cloud-Based Solutions are climbing the fastest; Wired Systems retain dominance in critical infrastructure.
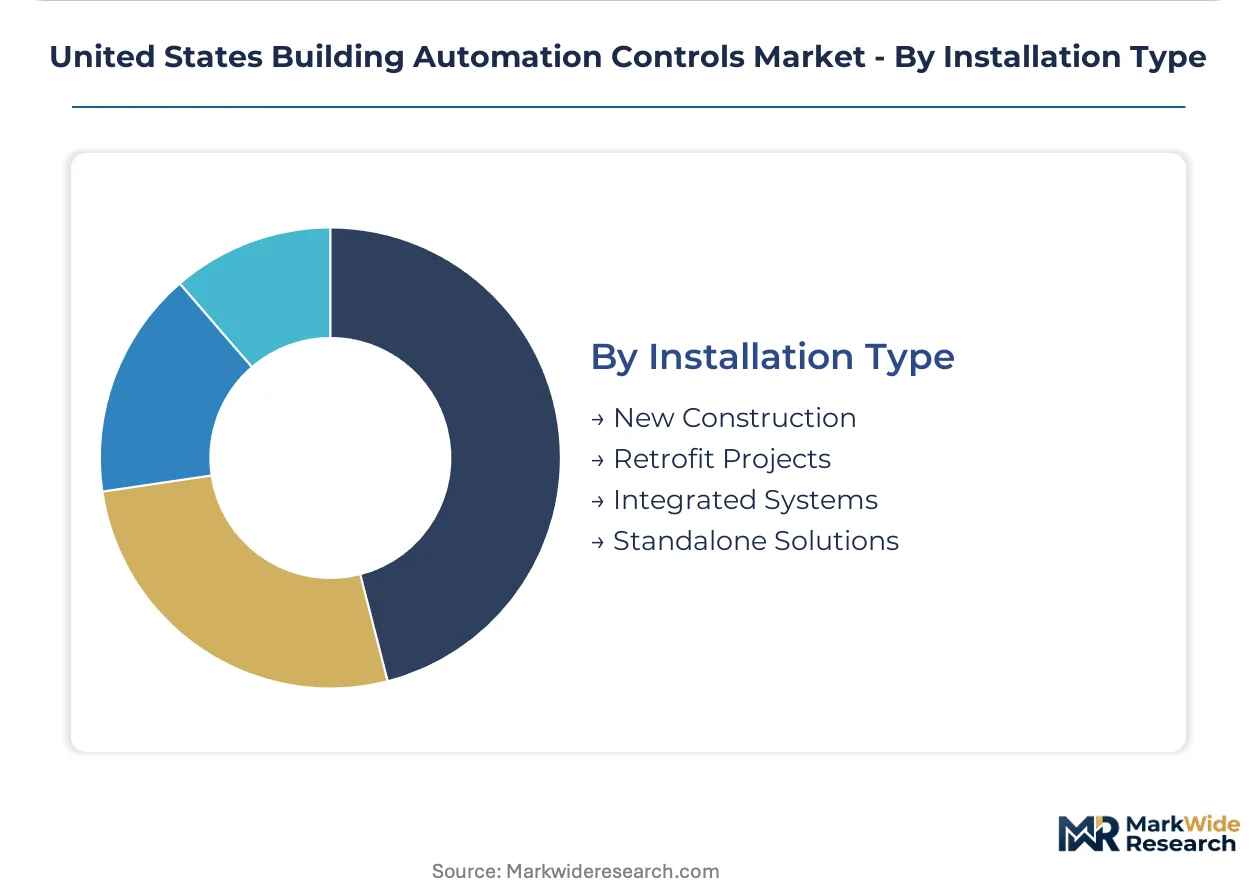
Installation Type:
Installation approach reflects capital availability, existing building age distribution, and performance risk allocation preferences.
- Retrofit Projects:Automation upgrades to aging mechanical systems in commercial stock built before 2010. The Inflation Reduction Act's efficiency incentives redirect facility investment priorities from new construction toward sensor-rich electrification of existing buildings.
- New Construction:Integrated automation specified during design phase with full digital twin compatibility and native cloud connectivity. Texas metro corridors generate unmatched greenfield demand where lax legacy infrastructure eliminates retrofit complexity.
- Integrated Systems:Unified platforms spanning HVAC, lighting, security, and energy management through single vendor ecosystems.
- Standalone Solutions:Point automation addressing single building system without broader platform integration.
Retrofit Projects dominate addressable volume today; New Construction offers margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States building automation controls industry traces its commercial scale to post-war HVAC electrification in the 1950s, when pneumatic control systems first centralized thermal management in commercial high-rises. Federal energy crisis responses in the 1970s accelerated digital control adoption, embedding automation expertise in Northeast and Midwest industrial corridors before West Coast technology clusters drove cloud-native architectures forward.
California
California's Title 24 Building Energy Standards mandate automated demand response and granular metering for all new construction and major renovations above 10,000 square feet. The California Energy Commission updates these stretch codes on three-year cycles, compressing compliance timelines for facility managers. Silicon Valley data center clusters and Los Angeles commercial portfolios drive the nation's densest concentration of cloud-integrated building management deployments.
Texas
Texas metro corridors including Dallas-Fort Worth, Houston, and Austin generate unmatched greenfield automation demand through rapid commercial construction and minimal legacy infrastructure burden. The Public Utility Commission of Texas operates the nation's largest competitive retail electricity market, creating direct price signals that accelerate payback calculations for automated HVAC and energy management investments. Suburban office campuses in Plano and The Woodlands prioritize EPA ENERGY STAR certification maintenance through sub-100 millisecond load curtailment capabilities.
New York Metro
New York City's Local Law 97 imposes carbon emissions caps on buildings exceeding 25,000 square feet, with automated controls qualifying as core compliance infrastructure. The New York State Energy Research and Development Authority channels utility rebate flows toward demand-response-enabled retrofits in aging Manhattan and Brooklyn commercial stock. Multi-tenant office portfolios across Manhattan, Jersey City, and White Plains adopt wireless mesh sensor networks to halve installation labor costs in constrained urban envelopes.
Greater Boston
Massachusetts stretch codes adopted from the International Energy Conservation Code mandate commissioning of automated building systems for projects seeking net-zero certification. The Massachusetts Clean Energy Center administers workforce training programs that address the shortage of technicians capable of bridging IT network security with operational technology protocols. University and hospital campuses in Cambridge, Worcester, and Springfield anchor performance contracting volumes where energy savings guarantees displace capital expenditure procurement.
Pacific Northwest
Washington State's Clean Buildings Performance Standard requires automated energy management systems for commercial buildings above 50,000 square feet beginning in 2026. The Northwest Energy Efficiency Alliance aggregates utility demand-response programs across Oregon and Washington, standardizing rebate structures that accelerate retrofit automation in Seattle and Portland commercial portfolios. Technology sector campuses in Redmond and Hillsboro drive early adoption of edge computing architectures that redistribute processing load to distributed sensor nodes.
United States Building Automation Controls Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the United States building automation controls landscape, with full-stack hardware manufacturers maintaining foundry-like control over sensor fabrication while software-native entrants license control algorithms to third-party integrators. The market structures around three tiers: diversified industrial conglomerates with century-scale building systems heritage, pure-play automation specialists with vertical depth in specific control domains, and cloud-native entrants leveraging AI-driven fault detection to displace on-premise server architectures. Consolidation pressure intensifies through strategic partnerships between hardware incumbents and cybersecurity vendors, alongside portfolio diversification into subscription-based analytics layers that monetize utility demand-response participation.
Within the diversified industrial tier, Honeywell International, Johnson Controls International, and Siemens AG occupy positions that exemplify contrasting strategic postures. Honeywell leverages distributed sensing architecture to capture retrofit flows in aging office stock. Johnson Controls anchors large campus deployments through performance contracting models with guaranteed savings verification. Siemens differentiates on digital twin integration for predictive HVAC optimization in complex mechanical environments.
| Leading Market Players |
|---|
| Honeywell International |
| Johnson Controls International |
| Siemens AG |
| Schneider Electric |
| ABB Ltd |
| Trane Technologies |
| Carrier Global Corporation |
| Lutron Electronics |
| Hubbell |
| Others |
Value Network & Pricing Analysis
Controls integration specialists concentrated in Greater Boston and the Pacific Northwest command wage premiums that widen pricing spreads between premium-tier digital twin deployments and economy-grade wired retrofits. Labor-cost differentials across these engineering clusters directly feed into tiered quotation structures for campus-scale automation projects.
Pricing Analysis
Performance-based contracting with energy savings guarantees anchors the dominant pricing structure for large-scale deployments, separating guaranteed-outcome premium tiers from hardware-only economy offerings. Price differentiation hinges on EPA ENERGY STAR certification tier and the extent of cloud-native analytics bundling. Cost compression in mid-market retrofit segments is intensifying because wireless mesh alternatives are collapsing installation labor requirements. Educational institutions and public-sector buyers exhibit the highest price sensitivity, while data center operators prioritize sub-100 millisecond response specifications over unit cost.
Supply Chain Analysis
Direct-to-facility channels handle hyperscale campus deployments, while systems integrators and electrical contractors manage fragmented mid-market retrofit demand. Controller chipset fabrication concentrates in Taiwan, South Korea, and mainland China, with BACnet and Modbus protocol silicon drawing from concentrated Asian foundry capacity. Supply chain risk centers on single-source vulnerability for specialized environmental sensors and semiconductor components. Distribution runs through authorized integrator networks that bridge IT security compliance with operational technology commissioning protocols.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in building automation controls rests on the shift from capital equipment sales toward recurring subscription analytics layers that monetize utility demand-response participation. Cloud-based remote commissioning capabilities are compressing deployment costs while enabling premium-tier pricing for AI-driven fault detection services.
For Market Incumbents: Deploy cybersecurity certification investments to defend installed-base relationships against cloud-native entrants exploiting IT-OT convergence gaps. Consolidate position through backward integration into sensor fabrication and captive supply of edge computing hardware. Lock in large campus deployments via performance contracting models that underwrite long-term energy savings guarantees, raising balance sheet barriers for challengers.
For New Entrants and Emerging Players: Regional systems integrators in Texas metro corridors represent the most accessible channel partner type for cloud-native automation platforms seeking greenfield penetration. Target mid-market commercial facilities in Dallas-Fort Worth and Austin where lax legacy infrastructure eliminates retrofit complexity and accelerates commissioning timelines. Lead with wireless mesh sensor bundles that halve installation labor costs against incumbent wired architectures.
For Investors and Strategic Acquirers: Industrial conglomerates with building systems heritage are the most active acquirers in this space, seeking software capabilities to complement hardware portfolios. Long-term viability favors targets with demonstrated utility demand-response revenue streams and digital twin integration expertise. Watch for inflection when ASHRAE Standard 90.1 update cycles compress compliance recertification timelines, forcing accelerated replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Analytics Layer Development | Recurring revenue from EPA ENERGY STAR demand-response participation monetizes operational data streams. |
| Wireless Mesh Sensor Platform Launch | Battery-powered environmental sensors compress installation labor costs by eliminating structured cabling requirements. |
| Digital Twin Integration Partnership | Building information modeling convergence with real-time sensor feeds enables predictive HVAC optimization. |
| Cybersecurity Certification Investment | Federal critical infrastructure designations impose audit requirements that favor pre-certified vendor ecosystems. |
| Performance Contracting Expansion | Energy savings guarantees displace capital expenditure procurement in university and hospital campus deployments. |
Research Methodology
Bottom-up facility-type modeling reconciled against top-down vendor shipment tracking forms the analytical core of this study. Primary interviews with facility managers, controls integrators, utility demand-response program administrators, and commissioning agents were cross-validated against secondary sources including FERC filings, EPA ENERGY STAR certification databases, state energy commission stretch code documentation, and ASHRAE standard revision records. Triangulation between procurement pattern analysis and regulatory mandate timelines anchors segmentation-level estimates.
Historical trendline analysis of automation deployment velocity across California Title 24 compliance cycles, Texas greenfield construction permits, and New York Local Law 97 enforcement phases informed projection frameworks. Modeled dimensions span product type, end-use facility category, technology architecture, and installation approach, with CAGRs derived from regression against regulatory deadline clustering and utility incentive program renewals. Edge computing adoption curves and wireless sensor replacement cycles provided industry-specific forecast inputs.
Revisions become necessary when semiconductor supply disruptions, cybersecurity designation expansions, or stretch code acceleration beyond three-year cycles materialize. Forecasts reflect documented assumptions regarding IRA incentive continuity and utility rebate program stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Smart Garage Door Opener and Controller Market
Building Automation Systems
Signage Market
Building Automation Systems
Platform Screen Door System Market
Building Automation Systems
Elevator Modernization Market
Building Automation Systems
Global Nordic Building Automation and Control Market
Building Automation Systems
Europe Building Automation Systems Market
Building Automation Systems
Architecture Smart Glass Market
Building Automation Systems
Residential Electric Underfloor Heating Market
Building Automation Systems
China Revolving Doors Market
Building Automation Systems
Building Automation and Control System Market
Building Automation Systems
Electrochromic Glass Market
Building Automation Systems
Building Information Management System Market
Building Automation Systems
Zero Energy Buildings Market
Building Automation Systems
AEC Market
Building Automation Systems
Computer-Aided Facility Management (CAFM) Market
Building Automation Systems
Europe Smart Windows Market