
 Unconventional Gas Market | 2026-2036
Unconventional Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Unconventional Gas Market Intelligence
The bundling of seismic imaging, horizontal drilling, and hydraulic fracturing services into integrated project packages is realigning procurement patterns for exploration and production companies. ExxonMobil Corporation leverages its vast operational scale to offer these comprehensive service bundles for large-scale shale developments. In contrast, EOG Resources differentiates by specializing in optimizing specific extraction techniques for different geological formations, competing on drilling and completion efficiency rather than bundled service scope.
Unconventional gas refers to natural gas extracted from geological formations with low permeability, such as shale rock, tight sandstones, or coal seams. Its extraction requires advanced stimulation techniques, most commonly hydraulic fracturing, to create artificial pathways for the gas to flow to the wellbore. While shale gas continues to dominate production volumes and investment, tight gas represents a significant and mature portion of the supply mix. The application mix is led by power generation, with chemicals manufacturing also being a major consumer.
Producers operate within a complex and often conflicting regulatory environment. The US Environmental Protection Agency (EPA) enforces strict rules on methane emissions and wastewater disposal from hydraulic fracturing. In parallel, frameworks like the EU Green Deal and China's dual carbon goals create divergent pressures, supporting gas as a bridge fuel away from coal while simultaneously scrutinizing its lifecycle emissions. Future investment decisions depend heavily on navigating this uncertain policy landscape which both supports and restricts unconventional gas development.
Market Dynamics
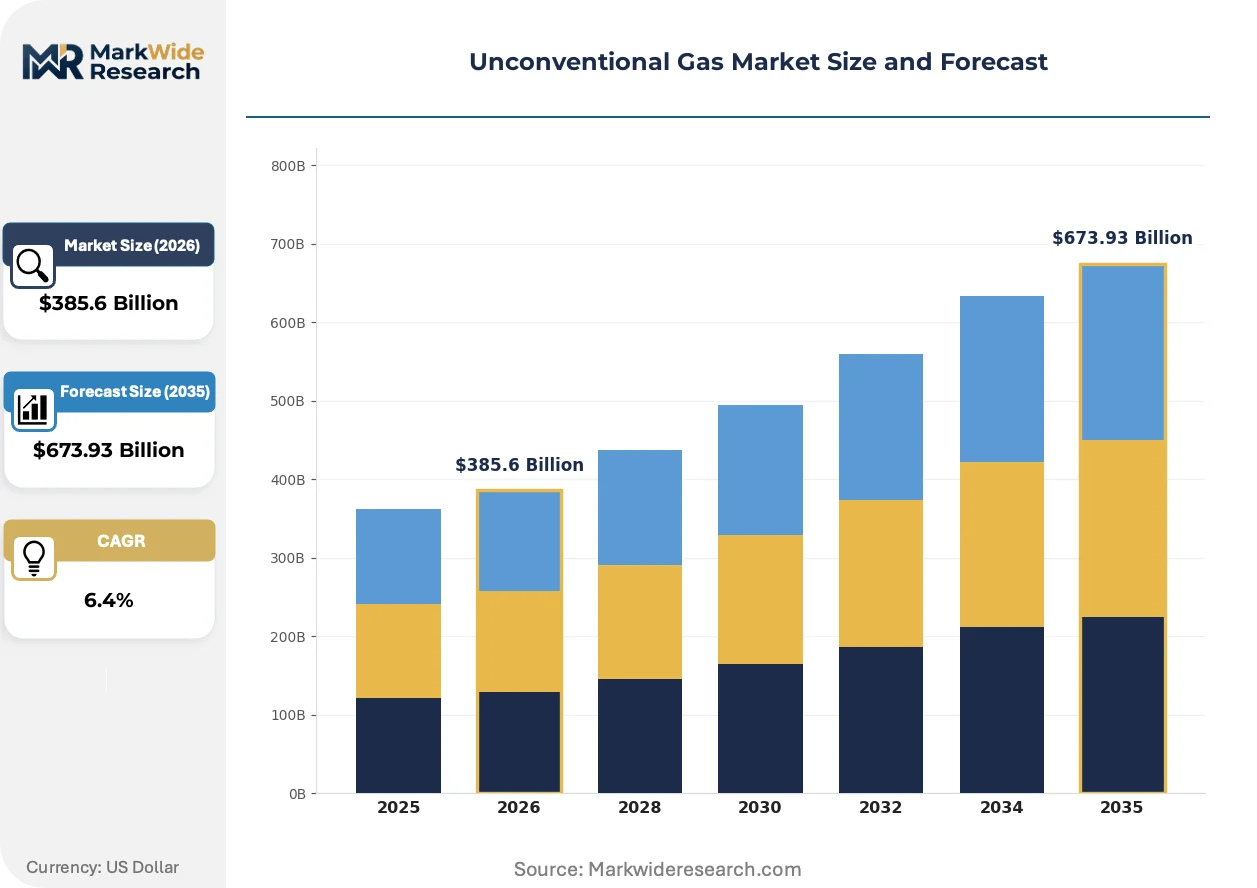
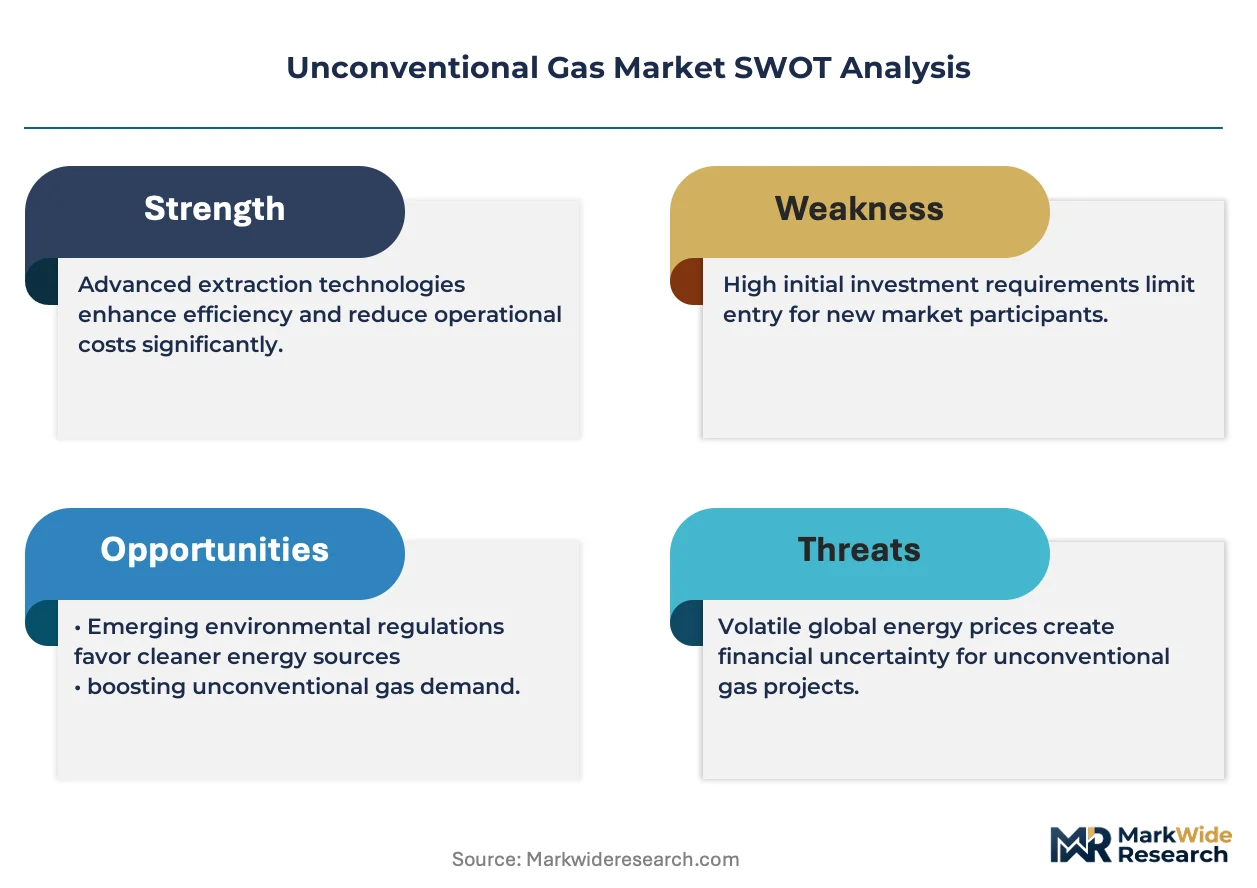
The central dynamic shaping the unconventional gas market is the tension between rapid technological advancements that lower production costs and an increasingly fragmented global regulatory environment. This creates uncertainty for long-term capital investment decisions, balancing efficiency gains against policy-driven market access and emissions compliance risks.
Growth Catalysts
- Technological Maturation:Continuous improvements in horizontal drilling and multi-stage hydraulic fracturing techniques are enhancing recovery rates and reducing the break-even cost per well, making more geological plays economically viable.
- Power Generation Demand:The power sector's shift from coal to lower-emission fuels positions natural gas as a critical transitional energy source, particularly in regions with aggressive carbon reduction targets.
- Supportive Policy Frameworks:Initiatives like the EU Green Deal, while targeting renewables, acknowledge a role for gas as a bridge fuel, supporting infrastructure investment and creating stable demand to displace more carbon-intensive sources.
Market Restraints
- Stringent Environmental Regulations:Rules governing methane emissions and wastewater disposal, such as those enforced by the US Environmental Protection Agency (EPA), increase operational complexity and compliance costs for producers.
- High Capital Intensity:The development of unconventional resources requires substantial upfront investment in drilling, completions, and midstream infrastructure before production can commence, creating high barriers to entry.
- Public and Landowner Opposition:Concerns over water contamination, induced seismicity, and land use associated with hydraulic fracturing can lead to permitting delays, legal challenges, and moratoria on development activities.
Strategic Opportunities
- Digital Transformation:The application of artificial intelligence and machine learning to analyze seismic and production data offers significant opportunities to optimize well placement, completion design, and reservoir management.
- Blue Hydrogen Feedstock:Unconventional gas can serve as a primary feedstock for blue hydrogen production, where associated carbon emissions are captured, creating a new, large-scale industrial demand segment.
- International Expansion:Significant shale gas resources in basins outside of North America, such as the Vaca Muerta in Argentina and various formations in China, remain underdeveloped and represent major growth frontiers.
Industry Challenges
- Water Management Logistics:Securing, transporting, storing, and disposing of the large volumes of water required for hydraulic fracturing presents a significant logistical and cost challenge, especially in arid regions.
- Specialized Talent Scarcity:A shortage of geoscientists, petroleum engineers, and data analysts with specific expertise in unconventional reservoir characterization and development can constrain company growth.
- Midstream Infrastructure Bottlenecks:The pace of drilling can outstrip the development of new pipelines and processing facilities, leading to localized price discounts and stranded gas production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unconventional Gas Market |
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $673.93 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Tight Gas, Shale Gas, Coalbed Methane, Methane Hydrates, Deep Gas Technology: Hydraulic Fracturing, Horizontal Drilling, Enhanced Gas Recovery, Seismic Imaging, Gas Processing Application: Power Generation, Fertilizer Production, Chemicals Manufacturing, Residential Heating, Compressed Natural Gas End User: Energy Utilities, Petrochemical Producers, Residential Consumers, Transportation Sector, Industrial Manufacturers |
| Companies Covered | ExxonMobil Corporation, Chevron Corporation, ConocoPhillips, Royal Dutch Shell plc, BP plc, EOG Resources, Pioneer Natural Resources, PetroChina Company Limited, Schlumberger Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unconventional Gas Market Strategic Shifts & Innovations
The operational playbook for unconventional gas is being rewritten by data analytics and automation, enabling producers to optimize well-level economics. This push for efficiency coexists with a divergent global policy landscape, where gas is simultaneously promoted as a clean-air solution and scrutinized for its lifecycle emissions.
Technology: Digital Twins for Reservoir Management
Advanced digital twin technology creates virtual models of subsurface reservoirs and surface facilities. Exploration and production companies are increasingly adopting these tools for optimizing well planning and forecasting production throughout a field's life. This technology is consolidating vast, disparate data sets from seismic surveys, drilling logs, and sensor outputs into a unified, predictive framework that improves capital allocation.
Regulation: China's Dual Carbon Policy
Regulatory frameworks like China's "dual carbon" goals are creating powerful incentives for fuel switching. The policy aims to peak carbon emissions and achieve neutrality, which directly drives demand for natural gas to displace coal in industrial processes and power generation. This shift most affects domestic producers in regions like the Sichuan Basin, who are ramping up shale gas development to meet national energy and environmental targets.
Demand: Integrated Well Construction Contracts
Service procurement is evolving from discrete, single-service contracts to integrated project management models for well construction. This approach bundles drilling, completion, and stimulation services into a single package, displacing the traditional fragmented purchasing process. The trend is most visible in high-activity US shale plays like the Permian and Marcellus, where operators prioritize drilling efficiency and faster first-production timelines.
Unconventional Gas Market Segmentation
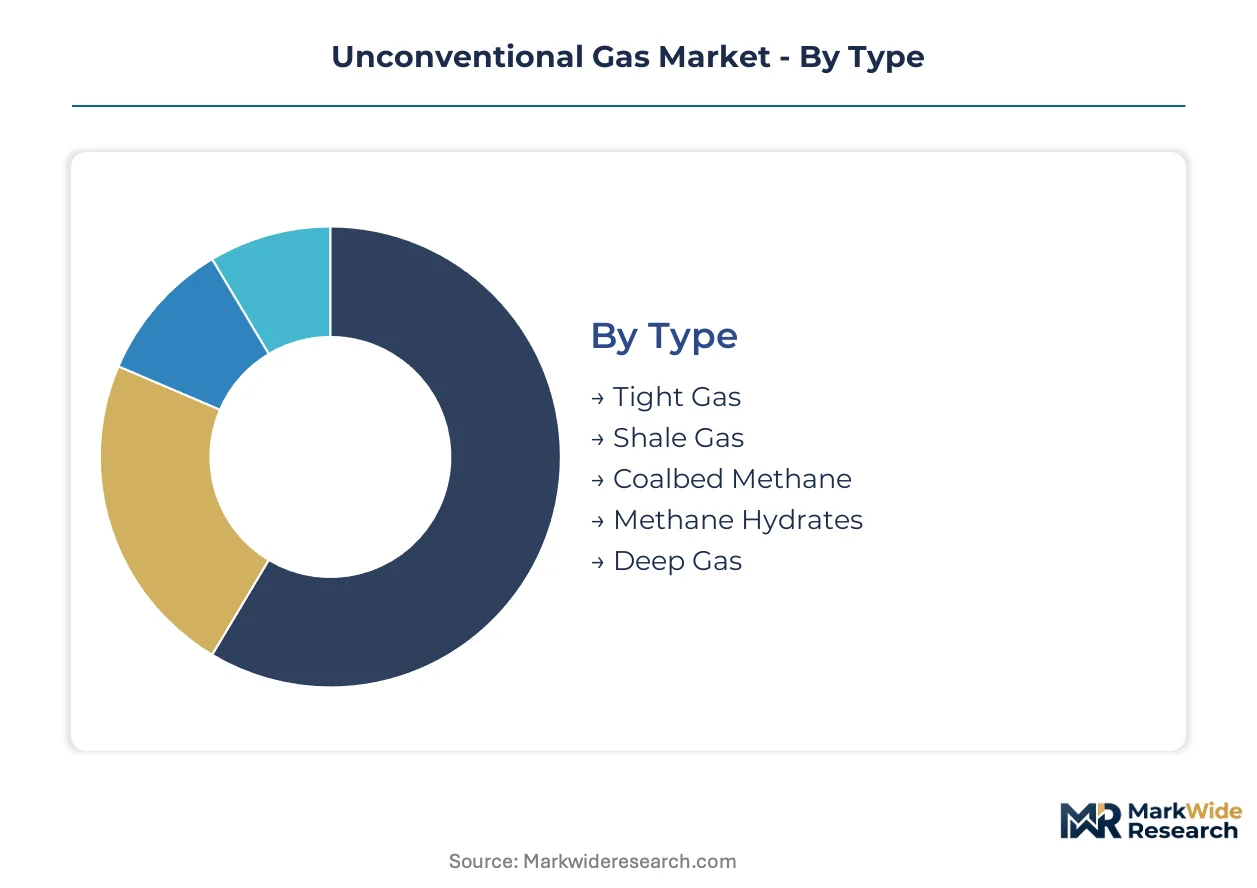
The unconventional gas market exhibits diverse characteristics across its resource types, enabling technologies, and end-use applications. Understanding these distinct segments is crucial for identifying areas of sustained investment and emerging demand patterns. Production methodologies and consumer requirements shape the competitive landscape for producers and service providers.
Type:
Supply concentration within the unconventional gas market is primarily dictated by the geological availability and economic viability of various resource types.
- Shale Gas:Extracted from shale rock formations, this gas requires hydraulic fracturing and horizontal drilling to liberate hydrocarbons. Demand is concentrated in the United States and China, driven by abundant resources and established infrastructure for power generation.
- Tight Gas:This gas is found in low-permeability sandstone and carbonate reservoirs, necessitating advanced stimulation techniques. North America's mature fields contribute significantly to supply, with industrial manufacturing providing consistent demand.
- Coalbed Methane:Methane adsorbed within coal seams is recovered through dewatering, predominantly in Australia and the United States.
- Methane Hydrates:These ice-like crystalline solids contain methane molecules, found in permafrost regions and oceanic sediments, representing a long-term resource.
- Deep Gas:Natural gas located at depths exceeding 15,000 feet, often requiring ultra-deep drilling technologies for access.
Shale gas absorbs the bulk of installed capacity; methane hydrates are expanding most quickly.
Technology:
Operational efficiency defines the adoption patterns for various technologies in unconventional gas extraction.
- Hydraulic Fracturing:This stimulation technique involves injecting high-pressure fluid to create fractures in low-permeability rock, enhancing gas flow. It remains critical for shale and tight gas production, particularly in the Permian Basin.
- Horizontal Drilling:This technique allows wells to be drilled laterally through reservoir rock, maximizing contact with the hydrocarbon-bearing formation. It significantly increases recovery rates in shale plays across North America.
- Enhanced Gas Recovery:Methods like CO2 injection improve recovery from mature unconventional reservoirs, extending field life.
- Seismic Imaging:Advanced subsurface mapping technologies, including 3D and 4D seismic, optimize well placement and reservoir characterization.
- Gas Processing:Facilities separate natural gas liquids and impurities from raw gas, preparing it for pipeline transport and market.
The market prioritizes hydraulic fracturing for immediate production gains, while enhanced gas recovery drives long-term resource optimization.
Application:
Demand drivers for unconventional gas span a broad spectrum of industrial and consumer needs, reflecting its versatility as an energy source and feedstock.
- Power Generation:Natural gas fuels turbines to produce electricity, serving as a critical bridge fuel in the global energy transition. This application dominates consumption in the United States and Europe due to coal displacement efforts.
- Chemicals Manufacturing:Unconventional gas, particularly ethane and propane, serves as a primary feedstock for petrochemicals like plastics and fertilizers. This segment sees significant demand in China and the US Gulf Coast region.
- Fertilizer Production:Natural gas is a key input for ammonia synthesis, essential for producing nitrogen-based agricultural fertilizers.
- Residential Heating:Direct use of natural gas for heating homes and water remains a significant application in colder climates.
- Compressed Natural Gas:CNG serves as a transportation fuel, offering a cleaner alternative to gasoline and diesel in fleet vehicles.
Power generation represents the largest volume consumption; chemicals manufacturing exhibits strong growth potential.
End User:
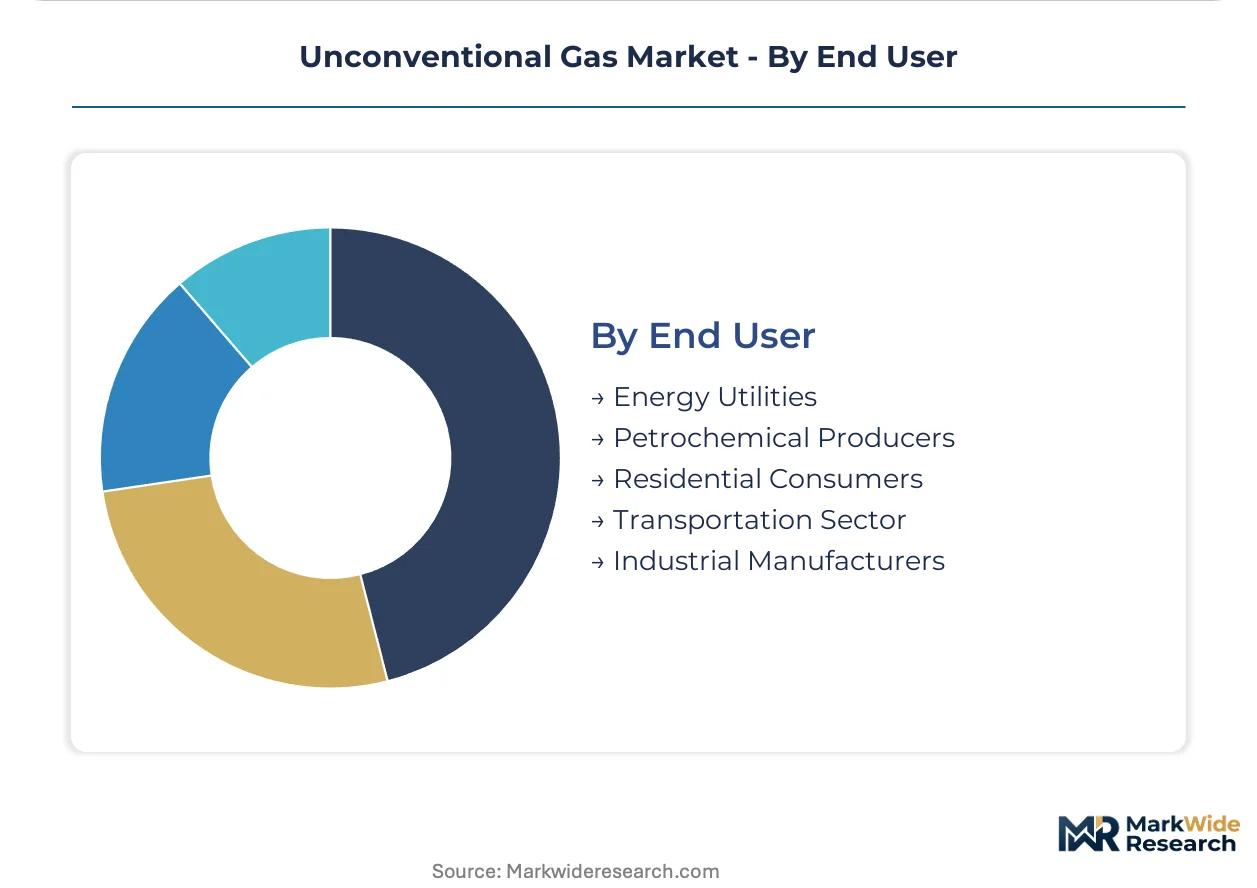
Procurement patterns for unconventional gas vary significantly across different end-user industries, influenced by scale and regulatory requirements.
- Energy Utilities:These entities purchase large volumes of unconventional gas for electricity generation and distribution to commercial and residential customers. They represent the largest customer base in North America and Europe.
- Petrochemical Producers:Industrial companies utilize natural gas as a feedstock for producing a wide range of chemicals and plastics. This sector's demand is concentrated in regions with robust chemical industries, such as the US and China.
- Residential Consumers:Households directly use natural gas for heating, cooking, and water heating, often supplied through local distribution companies.
- Transportation Sector:Fleets and public transport increasingly adopt natural gas as a fuel, driven by emissions reduction goals.
- Industrial Manufacturers:Various industries, including glass, steel, and food processing, use natural gas for process heat and power.
Energy utilities hold the largest market share; the transportation sector is gaining traction rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentrated development within key shale plays, particularly in North America, drives significant unconventional gas production. Areas like the Permian Basin and Marcellus Shale benefit from established infrastructure and continuous technological refinement. China's national energy security goals also prioritize domestic unconventional gas development in specific basins.
United States
Power generation and chemicals manufacturing drive demand for unconventional gas across the United States. The US Environmental Protection Agency (EPA) enforces regulations on methane emissions and wastewater disposal, impacting operational costs. High activity in the Permian Basin and Marcellus Shale continues, with operators optimizing drilling and completion efficiencies.
China
China's dual carbon goals directly incentivize the use of natural gas to displace coal, boosting demand for unconventional gas. The Ministry of Ecology and Environment (MEE) oversees environmental compliance for domestic shale gas projects. Development efforts concentrate in the Sichuan Basin, where producers are expanding shale gas production to meet national energy targets.
Argentina
The Vaca Muerta shale play in Argentina represents a significant frontier for unconventional gas development, attracting international investment. Argentina's national energy policies aim to increase domestic hydrocarbon production and exports. Neuquén Province, home to the Vaca Muerta, sees substantial infrastructure investment to support drilling and pipeline expansion.
Australia
Power generation and industrial applications create consistent demand for coalbed methane and tight gas in Australia. State-level environmental regulations, particularly regarding water management, influence project approvals. Queensland is a major hub for coalbed methane production, with integrated gas-to-liquefied natural gas (LNG) projects operating there.
Canada
Energy utilities and the petrochemical sector represent major consumers of unconventional gas across Canada. Federal and provincial environmental assessments guide large-scale resource development, ensuring responsible extraction. The Western Canada Sedimentary Basin remains the primary production area, with ongoing tight gas and shale gas activity.
Unconventional Gas Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, shaping the unconventional gas market structure. The market exhibits a tiered competitive landscape, with large integrated energy companies alongside independent exploration and production firms. Strategic archetypes include scale-driven operators, technology innovators, and regional specialists. Dominant competitive moves involve capacity expansion through optimized drilling programs and strategic partnerships for infrastructure development.
ExxonMobil Corporation, a global integrated energy company, exemplifies the scale-driven archetype, leveraging its vast operational footprint for large-scale shale developments. EOG Resources represents a focused pure-play specialist, competing on drilling and completion efficiency in specific geological formations. PetroChina Company Limited, a state-owned enterprise, anchors domestic unconventional gas supply within China, driving development in key basins like the Sichuan.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Chevron Corporation |
| ConocoPhillips |
| Royal Dutch Shell plc |
| BP plc |
| EOG Resources |
| Pioneer Natural Resources |
| PetroChina Company Limited |
| Schlumberger Limited |
| Others |
Cost & Logistics Intelligence
Specialized drilling engineers in the Permian Basin influence pricing-tier spreads, reflecting the scarcity of highly skilled labor in key production regions. This workforce concentration creates a cost differential for operators seeking to maximize efficiency in complex unconventional plays.
Pricing Analysis
Project-based pricing for integrated well construction contracts offers a premium for short lead times and guaranteed first-production targets. Price differentiation stems from completion efficiency metrics and the inclusion of advanced digital twin services. Pricing softness runs through the commodity spot market, influenced by oversupply in regions with infrastructure bottlenecks. Energy utilities, requiring stable, long-term supply, exhibit lower price sensitivity compared to industrial manufacturers reacting to short-term market fluctuations.
Supply Chain Analysis
Logistics and freight costs for proppant and water significantly impact the delivered cost of unconventional gas, particularly in remote drilling locations. Geographic supply concentration for unconventional gas centers on the United States, China, and Canada, drawing from domestic resources. Key dependencies include specialized drilling equipment and steel tubulars, often sourced from global markets. Midstream infrastructure bottlenecks represent a primary supply chain risk, creating localized price disparities. Distribution runs through extensive pipeline networks and, increasingly, via LNG export terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The unconventional gas market is firmly in a technology-transition phase, with advanced digital twins replacing traditional, static reservoir modeling. This shift underpins operational optimization and investment decisions across the value chain.
For Market Incumbents: Acquire advanced seismic imaging portfolios to enhance subsurface understanding and reduce exploration risk. Consolidate midstream assets in key shale plays to mitigate infrastructure bottlenecks and secure market access, defending against localized price discounts. Invest in CO2 injection technologies to extend the life of mature unconventional reservoirs, countering the threat of declining production rates.
For New Entrants and Emerging Players: Enter via specialized service offerings focusing on water management solutions for hydraulic fracturing, targeting arid regions like the Permian Basin. Focus on optimizing specific extraction techniques for tight gas formations, a segment with mature demand but room for efficiency gains. A go-to-market angle emphasizing environmental compliance and methane emissions reduction can attract discerning industrial buyers.
For Investors and Strategic Acquirers: Re-rating potential sits with technology-focused independents given their ability to drive down break-even costs through innovation. Target firms specializing in blue hydrogen feedstock production, anticipating a new, large-scale industrial demand segment. A signal to watch is the acceleration of carbon capture and storage infrastructure development, validating the long-term viability of gas as a bridge fuel.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Digital Twin Technology | Optimizes well planning and production forecasting, improving capital allocation for operators. |
| Expand Blue Hydrogen Production Capacity | Creates a new, large-scale industrial demand segment for unconventional gas as feedstock. |
| Acquire Midstream Infrastructure Assets | Secures market access and reduces transportation costs for producers in active shale plays. |
| Develop Advanced Water Recycling Solutions | Addresses critical water management logistics and reduces operational costs in arid regions. |
| Form International Joint Ventures | Unlocks underdeveloped shale gas resources in basins outside North America, diversifying supply. |
Research Approach
Energy Information Administration (EIA) data, International Energy Agency (IEA) reports, and company 10-K filings formed the secondary backbone, complemented by government energy statistics. This data was rigorously triangulated with primary interviews conducted with petroleum engineers, geoscientists, utility procurement managers, and chemical plant managers. The comprehensive approach combined bottom-up market sizing with top-down validation to ensure robust data integrity.
A bottom-up analytical framework informed the market forecast across the analysis window, segmenting by resource type, technology, application, end user, and major regional basins. Compound annual growth rates were derived from historical data and projected trends in drilling rig counts and natural gas prices. Key forecast inputs included anticipated regulatory changes and technological advancements in extraction efficiency.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of rapid geopolitical shifts or unforeseen technological breakthroughs. These forecasts reflect assumptions regarding global energy policies and the pace of environmental regulations. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Geothermal Drill Bits Market
Oil & Gas
Underground Gas Storage (UGS) Market
Oil & Gas
United States Oil and Gas Midstream Market
Oil & Gas
Deepwater and Ultra-Deepwater Exploration and Production Market
Oil & Gas
Gulf of Mexico Oil and Gas Midstream Market
Oil & Gas
Nigeria Oil and Gas Market
Oil & Gas
Rigless Intervention Systems Sales Market
Oil & Gas
Smart Oilfield Market
Oil & Gas
Canada LNG Market
Oil & Gas
Global Drilling Jars Market
Oil & Gas
Middle-East Completion Equipment and Services Market
Oil & Gas
Europe Natural Gas Market
Oil & Gas
Shale Gas Hydraulic Fracturing Market
Oil & Gas
Well Stimulation Vessels Market
Oil & Gas
India Oil and Gas Market
Oil & Gas
Asia-Pacific Liner Hanger System Market