
 Global Drilling Jars Market | 2026-2036
Global Drilling Jars Market Size, Share, and Industry Trends Forecast 2026-2036
Global Drilling Jars Market Analysis
Modular jar system bundling is broadening buyer choice across the Global Drilling Jars Market as operators seek integrated bottom-hole assembly packages rather than standalone components. Schlumberger leverages its integrated drilling services portfolio to anchor large-scale offshore contracts. National Oilwell Varco sustains manufacturing scale across multiple jar product lines. Baker Hughes differentiates through advanced materials engineering for extended-reach applications.
Drilling jars are mechanical downhole tools engineered to deliver controlled axial impact forces of up to several hundred thousand pounds to free stuck pipe, typically constructed from high-strength alloy steel with critical components heat-treated to API 7-1 hardness specifications. Their primary industrial purpose centers on maintaining drilling continuity in high-torque, high-drag environments where differential sticking or wellbore instability interrupts operations. Shock jars and torque jars occupy the largest product type positions due to universal deployment across vertical and directional well profiles. Steel material grades dominate current procurement volumes, though titanium alloys represent the fastest-growing material segment for ultra-deep high-pressure high-temperature wells where weight reduction extends rig load limits.
API standards, the EPA's offshore emissions frameworks, and Norway's Petroleum Safety Authority regulations collectively shape product certification requirements and operational deployment protocols for drilling jar manufacturers seeking market access. The EU F-Gas Regulation and REACH chemical compliance add material sourcing constraints for European offshore suppliers. Stakeholders must monitor evolving well integrity mandates and materials traceability requirements as regulatory scope expands beyond traditional equipment safety into lifecycle environmental accountability.
Market Dynamics
Deepwater offshore drilling programs in the United States Gulf of Mexico and Brazil's pre-salt basins are forcing manufacturers to redesign jar assemblies for higher-reliability performance under extreme pressure-temperature conditions, compressing product development cycles and consolidating procurement toward integrated service providers.
Growth Catalysts
- API 7-1 Material Standards:Revised hardness and heat-treatment specifications are compelling operators to replace legacy jar inventories, generating replacement demand across mature North American fields.
- Titanium Alloy Adoption:Ultra-deep high-pressure high-temperature wells in the Gulf of Mexico and offshore West Africa are driving specification upgrades for weight-reduced jar assemblies that extend rig load limits.
- Modular System Bundling:Integrated bottom-hole assembly procurement is displacing standalone component purchasing, favoring suppliers with full drilling tool portfolios.
Market Restraints
- Alloy Steel Input Volatility:Nickel and chromium price fluctuations directly impact manufacturing margins for conventional jar construction, squeezing producers without long-term raw material hedging.
- Supply Concentration in Forging Capacity:Specialized heat-treatment and forging capabilities cluster in Germany, the United States, and Japan, creating geographic bottlenecks for non-integrated manufacturers.
- Extended-Reach Technical Limits:Torque transmission efficiency degrades beyond 15,000-meter measured depths, constraining jar effectiveness in the deepest offshore exploratory wells.
Strategic Opportunities
- Underpenetrated Brazilian Pre-Salt:Petrobras-led development programs lack sufficient local jar service infrastructure, creating entry points for integrated suppliers with offshore logistics capabilities.
- EU F-Gas Regulatory Tailwind:Emissions accountability mandates for offshore equipment lifecycle are favoring jar manufacturers with certified environmental traceability systems.
- Digital Twin Convergence:Real-time downhole telemetry fused with predictive jar maintenance algorithms is enabling performance-based service contracts that lock in multi-year operator relationships.
Industry Challenges
- Specialized Welding Certification Gap:API-qualified friction welders for high-strength alloy jar components remain scarce, extending production lead times and inflating labor costs.
- Legacy System Integration Friction:New modular jar designs face compatibility constraints with incumbent bottom-hole assembly configurations, complicating field deployment and requiring custom adapter engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Drilling Jars Market |
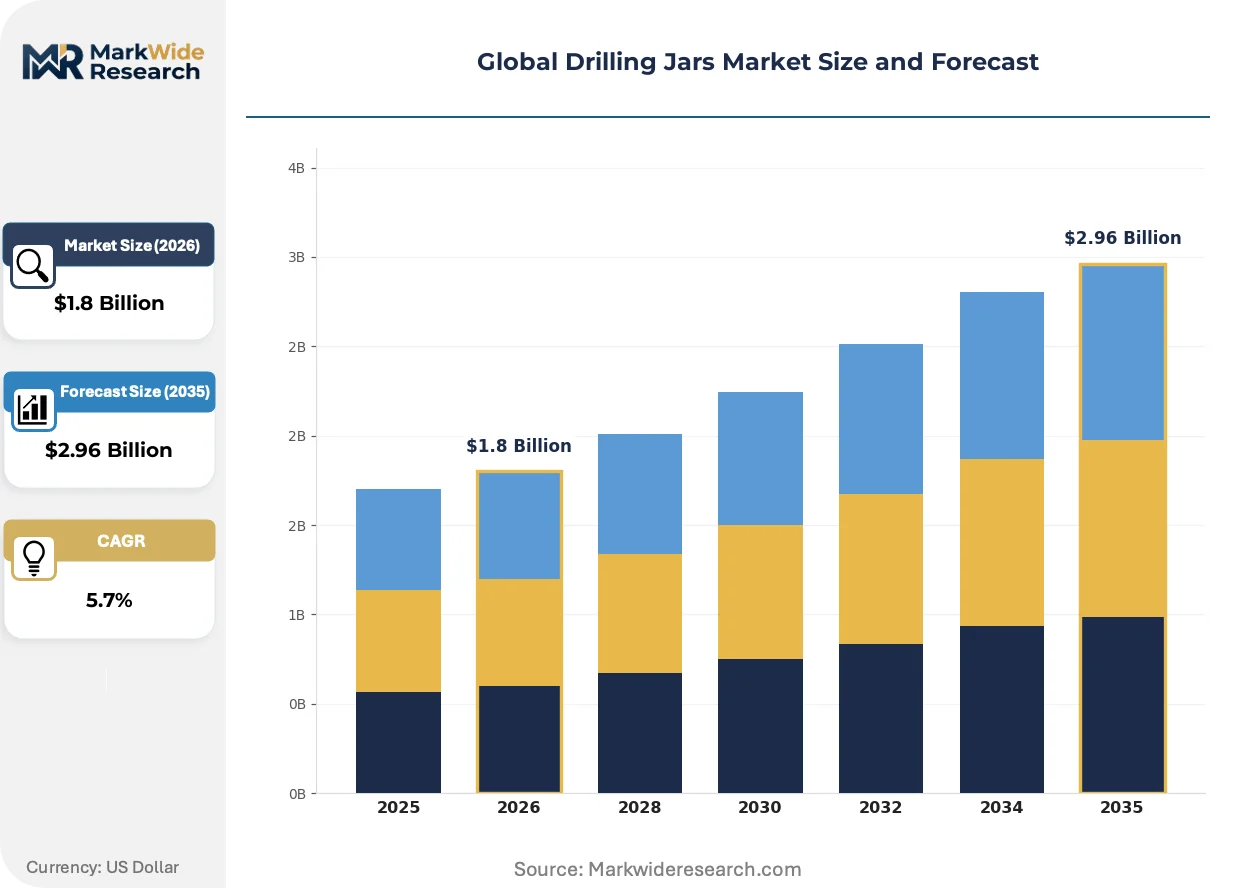
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shock Jars, Torque Jars, Catching Jars, Flotation Jars Material: Steel, Composite, Titanium, Aluminum End User: Oil & Gas, Mining, Geothermal, Water Well Application: Deep Well Drilling, Horizontal Drilling, Controlled Directional Drilling, Coiled Tubing |
| Companies Covered | Schlumberger, National Oilwell Varco, Halliburton Energy Services, Weatherford International, Baker Hughes, Toro Downhole Tools, BICO Drilling Tools, Odfjell Drilling, Cougar Drilling Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Drilling Jars Market Emerging Trajectories
Downhole tool engineering is converging with advanced materials science and digital instrumentation, compressing the gap between mechanical reliability and real-time operational intelligence. Three developments are actively restructuring competitive positioning.
Smart jar systems embedding fiber-optic load sensors and wireless telemetry are rewriting how operators monitor stuck-pipe events. Offshore drillers in Norway and the United States Gulf of Mexico are deploying these instrumented assemblies on half of new deepwater rigs. The technology is compressing response times from hours to minutes, eliminating guesswork in jar firing decisions and reducing non-productive time penalties.
REACH chemical compliance and the EU F-Gas Regulation are tightening material traceability requirements for European offshore suppliers. Manufacturers must now document full alloy provenance and heat-treatment batch records through equipment retirement. Norwegian operators under Petroleum Safety Authority jurisdiction are demanding extended environmental accountability, forcing jar producers to reconfigure supply chain documentation systems or lose North Sea access.
Integrated drilling service contracts are displacing standalone jar procurement across major offshore programs. Operators in Brazil and West Africa now specify jar performance within bundled bottom-hole assembly agreements rather than purchasing components separately. This procurement consolidation favors suppliers with captive manufacturing of jars, shock subs, and agitators, marginalizing pure-play jar specialists without adjacent product lines.
Global Drilling Jars Market Segmentation
Drilling jar procurement patterns diverge sharply across operating environments, with certification requirements and material specifications driving vendor selection. Understanding these segment boundaries clarifies where integrated suppliers capture premium pricing versus where commodity competition dominates.
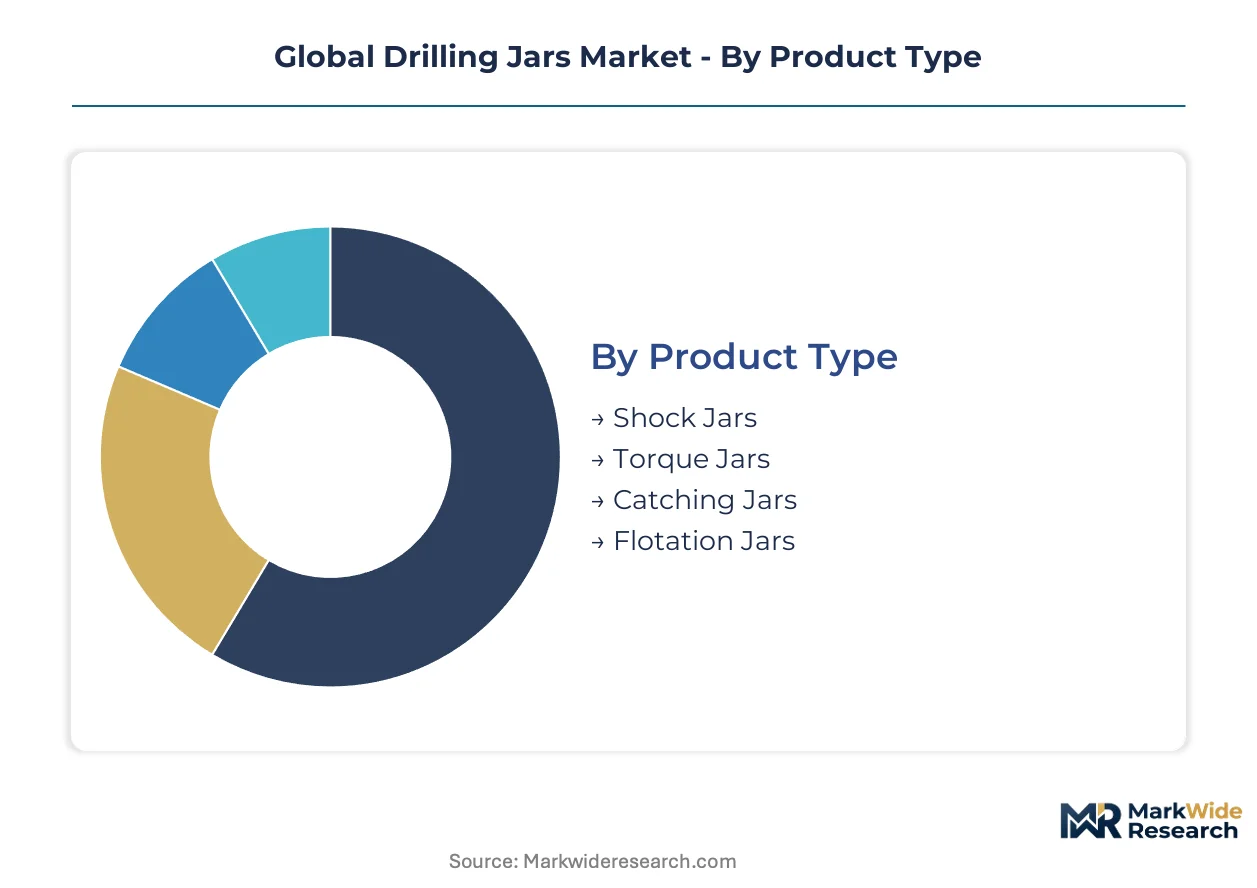
Product Type:
API 7-1 hardness specifications apply universally across all jar types, though torque jars face additional torsional fatigue testing under revised standards. Shock jars and torque jars carry identical material traceability burdens; catching jars and flotation jars operate under lighter documentation loads in non-critical applications.
- Shock Jars:Deliver controlled axial impact forces through spring-loaded or hydraulic mechanisms to free stuck pipe in vertical and directional wells. Demand concentrates in United States Permian Basin extended-reach programs where differential sticking risks escalate at depths beyond 4,500 meters. API 7-1 heat-treatment compliance now mandates replacement of legacy inventories across mature North American fields.
- Torque Jars:Transmit rotational impact energy to overcome torsional sticking in high-drag horizontal sections. Offshore Brazil pre-salt development programs specify these assemblies for salt zone penetration where conventional jar firing proves ineffective. Petrobras procurement contracts bundle torque jars within integrated bottom-hole assembly packages.
- Catching Jars:Specialized fishing tools for retrieving broken drillstring components.
- Flotation Jars:Buoyancy-assisted variants for shallow water well deployment.
Shock Jars sits at the top of the volume ranking, with Torque Jars climbing the fastest.
Material:
Raw material cost tiers separate procurement strategies, with nickel-chromium alloy fluctuations squeezing margins on conventional steel while titanium commands premium positioning for ultra-deep applications.
- Steel:High-strength alloy grades dominate current procurement volumes across standard well profiles. Heat-treatment to API 7-1 hardness specifications occurs at specialized forging facilities in Germany, the United States, and Japan. Nickel price volatility directly impacts manufacturing margins for producers without long-term hedging arrangements.
- Titanium:Weight-reduced assemblies extend rig load limits in Gulf of Mexico and West Africa ultra-deep high-pressure high-temperature wells. REACH chemical compliance and full alloy provenance documentation now mandatory for European offshore access. Fastest-expanding material segment as operators push measured depths beyond 15,000 meters.
- Composite:Emerging non-metallic alternatives for corrosive environments.
- Aluminum:Lightweight options restricted to shallow, low-temperature applications.
Steel maintains absolute volume leadership, while Titanium gains share fastest in offshore procurement.
End User:
Customer sophistication levels dictate service intensity, with oil and gas majors demanding predictive maintenance integration while mining and water well operators prioritize upfront cost minimization.
- Oil & Gas:Integrated drilling service contracts now specify jar performance within bundled bottom-hole assembly agreements rather than component-level purchasing. United States Gulf of Mexico and Brazil pre-salt corridors concentrate demand for instrumented smart jar systems with fiber-optic load sensors. Real-time telemetry adoption compresses response times from hours to minutes during stuck-pipe events.
- Mining:Exploration drilling programs in Australian and Canadian mineral belts deploy shock jars for core recovery operations. Procurement emphasizes durability over precision instrumentation, with replacement cycles driven by abrasive wear rather than fatigue limits.
- Geothermal:High-temperature corrosion challenges favor specialized material specifications.
- Water Well:Cost-sensitive shallow drilling with minimal technical differentiation.
Oil & Gas commands the volume peak, with Geothermal showing steepest expansion trajectory as renewable baseload investment accelerates.
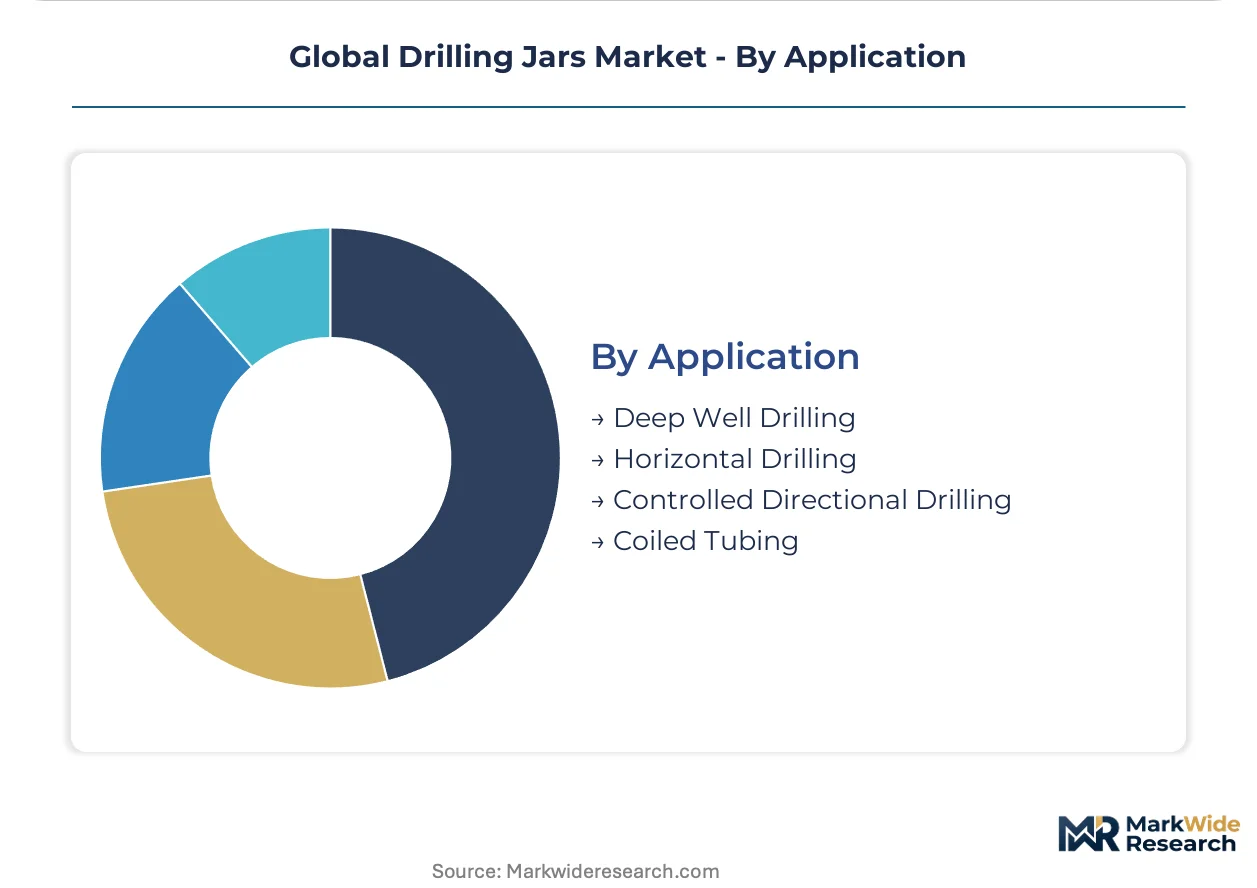
Application:
Well architecture complexity determines jar specification intensity, with deep and horizontal configurations requiring multi-axis load management absent in vertical coiled tubing deployment.
- Deep Well Drilling:Extreme pressure-temperature conditions in United States Gulf of Mexico lower tertiary formations force redesign of seal packages and lubrication systems. Manufacturers consolidate procurement toward integrated service providers capable of full-system accountability. Torque transmission efficiency degrades beyond 15,000-meter measured depths, constraining jar effectiveness in exploratory wildcats.
- Horizontal Drilling:Extended-reach laterals in Permian Basin and DJ Basin require jar assemblies with enhanced fatigue resistance for high-cycle bending loads. Modular system bundling favors suppliers with captive manufacturing of jars, shock subs, and agitators.
- Controlled Directional Drilling:Steerable assemblies with integrated measurement-while-drilling compatibility.
- Coiled Tubing:Slim-hole jar variants for through-tubing interventions and workovers.
Deep Well Drilling anchors procurement volume, with Horizontal Drilling expanding most quickly as unconventional development intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Drilling jar manufacturing originated in the United States Gulf Coast forging corridors during the 1950s offshore boom, with German and Japanese metallurgical centers subsequently developing specialized heat-treatment capabilities for high-strength alloy components.
United States
Permian Basin extended-reach programs and Gulf of Mexico deepwater corridors drive specification upgrades for instrumented jar systems. EPA offshore emissions frameworks mandate lifecycle environmental accountability for equipment deployed in federal waters. Houston anchors integrated service provider headquarters, while Oklahoma City clusters house specialized downhole tool engineering operations.
Brazil
Pre-salt basin development programs generate demand for torque jars capable of penetrating thick salt zones. ANVISA-equivalent offshore equipment certification requirements align with Petroleum Safety Authority standards for well integrity documentation. Macaé serves as the primary logistics hub for offshore jar service infrastructure, with local content regulations pressuring foreign suppliers toward partnership structures.
Norway
North Sea electrification and subsea compression projects require jar assemblies rated for extended pressure-temperature envelopes. Petroleum Safety Authority regulations enforce full materials traceability from alloy provenance through equipment retirement. Stavanger concentrates engineering expertise for smart jar systems with fiber-optic load sensors, while Bergen hosts specialized subsea tooling integration facilities.
China
Domestic shale development in Sichuan and Tarim basins expands procurement of API 7-1 compliant jar inventories. MIIT industrial standards and GB certification requirements shape local manufacturing quality thresholds. Shanghai and Tianjin harbor districts cluster forging and heat-treatment capacity for regional supply, with CNOOC deepwater programs driving specification convergence toward international norms.
United Arab Emirates
Adnoc offshore expansion and sour gas development programs specify corrosion-resistant jar materials for high-H2S environments. MOHAP-equivalent equipment safety frameworks govern offshore tool certification in federal waters. Abu Dhabi Industrial City hosts assembly operations for Middle East and East African export markets, with Jebel Ali logistics corridors enabling rapid deployment to West African deepwater fields.
Global Drilling Jars Market Vendor Landscape
Premium-margin players sit above commodity-margin players across the integration depth spectrum, with full-service drilling contractors capturing bundled procurement contracts while specialized manufacturers compete on component pricing. The vendor base stratifies into three tiers: integrated oilfield service conglomerates with captive jar manufacturing, independent tool specialists with focused product lines, and regional fabricators serving replacement part demand. Consolidation pressure intensifies as operators consolidate procurement toward single-source accountability. Two dominant competitive moves reshape positioning: backward integration into specialized forging capacity, and technology licensing agreements for smart jar telemetry systems.
Among Houston-based integrated service providers, Schlumberger, Baker Hughes, and Halliburton Energy Services exemplify the full-service archetype, anchoring large-scale offshore contracts through bundled bottom-hole assembly offerings. These entities represent the premium tier where drilling jar performance is embedded within integrated service agreements rather than sold as discrete components, capturing multi-year operator relationships through performance-based contracting structures.
| Leading Market Players |
|---|
| Schlumberger |
| National Oilwell Varco |
| Halliburton Energy Services |
| Weatherford International |
| Baker Hughes |
| Toro Downhole Tools |
| BICO Drilling Tools |
| Odfjell Drilling |
| Cougar Drilling Solutions |
| Others |
Supply Flow & Price Mechanics
Nickel and chromium futures volatility on the London Metal Exchange cascades directly through forging economics into three distinct procurement tiers for jar assemblies, with integrated service providers absorbing cost swings through captive capacity while independent manufacturers pass alloy spikes through to spot buyers.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement for oil and gas majors, with price differentiation resting on API 7-1 certification grade and volume scale commitments. Premium-mid-economy pricing differentiation separates instrumented smart jar systems from standard mechanical assemblies and replacement part sourcing. Margins are tightening due to nickel price volatility eroding unhedged manufacturers. Mining exploration operators exhibit highest price sensitivity, while Gulf of Mexico deepwater drillers prioritize reliability over unit cost.
Supply Chain Analysis
High-strength alloy steel supply rests on specialized forging capacity clustered in Germany, the United States, and Japan, with heat-treatment batch documentation now mandatory for North Sea and Gulf of Mexico access. Critical inputs include nickel-chromium alloy bar stock, API-qualified friction welding services, and fiber-optic sensor telemetry modules. Single-source vulnerability concentrates in Japanese heat-treatment facilities certified to extreme pressure-temperature specifications. Distribution runs through integrated service provider logistics hubs in Houston, Stavanger, and Macaé.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazilian pre-salt development offers geographic-arbitrage upside against mature North American fields, with local content regulations creating cost premiums that reward established offshore logistics infrastructure over pure manufacturing scale.
For Market Incumbents: Anticipate titanium alloy specification upgrades displacing conventional steel in ultra-deep Gulf of Mexico and West Africa programs, eroding margin contribution from legacy product lines. Defensive consolidation into Brazilian forging partnerships satisfies ANVISA-equivalent certification requirements while blocking new entrant access. Priority levers include captive heat-treatment capacity in Germany and Japan, plus smart jar telemetry R&D lock-in with Norwegian Petroleum Safety Authority jurisdictions. For New Entrants and Emerging Players: Direct-to-operator digital procurement platforms bypass integrated service provider gatekeeping in underpenetrated Brazilian and West African offshore markets. White-space targets include torque jar service infrastructure for Petrobras pre-salt salt-zone penetration and REACH-compliant titanium documentation systems for European offshore suppliers. Geothermal drilling programs in Nevada and Turkey offer fastest penetration path with lower certification barriers than oil and gas. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap forging specialists holding API 7-1 friction welding certification and established heat-treatment batch documentation systems. Long-term viability over a decade-long horizon favors suppliers with environmental traceability platforms aligned to EU F-Gas and EPA offshore emissions accountability. Signal to watch is Petrobras procurement contract consolidation toward single-source integrated providers versus component-level purchasing revival.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forging Capacity | Captive heat-treatment facilities in Germany and Japan insulate margins from nickel volatility and API certification delays. |
| Smart Jar Telemetry Licensing | Fiber-optic load sensor partnerships with Norwegian drilling contractors lock in multi-year performance-based service contracts. |
| Brazilian Logistics Hub Establishment | Macaé-based service infrastructure satisfies ANVISA-equivalent local content requirements for Petrobras pre-salt programs. |
| Titanium Alloy Provenance Documentation | Full batch traceability systems ensure REACH and EU F-Gas compliance for continued North Sea market access. |
| Geothermal Segment Entry | High-temperature corrosion-resistant specifications open Nevada and Turkey markets with lower regulatory barriers than offshore oil. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drilling operations managers, procurement leads at national oil companies, downhole tool engineering directors, and aftermarket service heads with secondary validation through API specification filings, EPA offshore emissions framework updates, SEC 10-K disclosures from integrated service providers, and customs trade data on alloy steel imports. Bottom-up jar shipment tallies by product type and material grade were cross-checked against top-down drilling activity indices across the analysis window.
Segment-weighting approaches modeled product type, material specification, end-user industry, and application depth configuration as independent demand drivers throughout the projection horizon. CAGRs were derived from elasticity-adjusted drilling activity forecasts and replacement cycle assumptions tied to API 7-1 revision implementation. Industry-specific inputs included rig count trajectories in the Permian Basin and Gulf of Mexico, plus Petrobras pre-salt development cadence.
The model assumes a particular technology adoption path for smart jar telemetry integration; alternative pathways for fiber-optic sensor deployment or wireless telemetry standards would alter the outlook for instrumented assembly penetration. Forecasts reflect assumptions about regulatory enforcement consistency for materials traceability and alloy price volatility containment. A small set of triggers—Petrobras procurement consolidation decisions, EPA offshore emissions framework expansion, and titanium alloy supply diversification—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
North Sea Oil and Gas Upstream Market
Oil & Gas
Middle East and Africa Early Production Facility Market
Oil & Gas
Rigless Intervention Systems Sales Market
Oil & Gas
Subsea Well Access and BOP System Market
Oil & Gas
Oil and Gas Automation and Instrumentation Market
Oil & Gas
North America Oil Country Tubular Goods Market
Oil & Gas
Oil Field Drill Bits Market
Oil & Gas
Oil and Gas Midstream Market
Oil & Gas
Qatar Oilfield Service Market
Oil & Gas
United States Liner Hanger System Market
Oil & Gas
Asia-Pacific Liner Hanger System Market
Oil & Gas
Intelligent Completion Sales Market
Oil & Gas
Europe Hydraulic Fracturing Market
Oil & Gas
Deepwater Hydrocarbons Exploration Market
Oil & Gas
Coal Bed Methane Market
Oil & Gas
Crown Block Market