
 Tight Gas Market | 2026-2036
Tight Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Tight Gas Market Intelligence
The reservoir engineering talent pool is rotating towards data analytics and real-time geosteering capabilities. This shift benefits specialists like EOG Resources Inc., which leverages advanced subsurface modeling for well placement. Major integrated firms such as ExxonMobil Corporation sustain their market position through large-scale project execution and capital discipline. ConocoPhillips competes by optimizing its portfolio of unconventional assets in North America.
Tight gas refers to natural gas trapped in low-permeability rock formations like sandstone or carbonates, with a permeability typically below 0.1 millidarcies. Its extraction requires stimulation techniques to create flow paths to the wellbore, serving primarily as an energy source. Within the technology segment, hydraulic fracturing remains the dominant extraction method, complemented by horizontal drilling. The power generation application represents the largest consumption segment, followed by its use as a chemical feedstock in petrochemical plants.
Regulatory frameworks from the US Environmental Protection Agency (EPA) and China's Ministry of Ecology and Environment (MEE) increasingly focus on methane emission monitoring and reduction. Concurrently, policies like the EU Green Deal influence investment criteria for gas projects by prioritizing lower-carbon energy sources. Producers must therefore navigate the divergent pressures of ensuring national energy security while aligning with decarbonization mandates.
Market Dynamics
The central dynamic shaping the tight gas market is the conflict between escalating national energy security needs and stringent decarbonization mandates. This tension forces producers to innovate with advanced extraction technologies while simultaneously complying with tightening environmental regulations on emissions.
Growth Catalysts
- Advanced Extraction Technologies:Continuous improvements in multi-stage hydraulic fracturing and extended-reach horizontal drilling are unlocking vast, previously uneconomical tight gas reserves, thereby increasing the technically recoverable resource base and lowering breakeven costs for producers.
- Power Generation Demand:The global power sector's ongoing shift from coal to natural gas provides a significant demand pull, as tight gas offers a lower-emission fuel source for baseload and dispatchable electricity generation.
- Energy Security Policies:Government policies in countries like China and the United States that prioritize domestic energy production support the development of unconventional gas resources, including tight gas, to reduce reliance on imported energy.
Market Restraints
- High Capital Intensity:The extraction of tight gas requires substantial upfront capital investment in drilling, hydraulic fracturing, and associated surface infrastructure, creating high barriers to entry and exposing producers to commodity price volatility.
- Renewable Energy Competition:The falling cost of renewable energy sources, such as solar and wind, coupled with battery storage, presents a long-term substitution threat, particularly in the power generation segment.
- Regulatory Scrutiny:Strict environmental rules, including the US EPA's methane regulations and local water management policies, impose significant compliance costs and operational constraints on drilling and completion activities.
Strategic Opportunities
- Petrochemical Feedstock:An expanding opportunity exists in using tight gas as a primary feedstock for producing blue hydrogen and ammonia, positioning it as a transition fuel within the emerging low-carbon industrial economy.
- Digital Transformation:Integrating artificial intelligence and machine learning into subsurface modeling allows for more precise well placement and real-time optimization of fracturing operations, significantly improving ultimate recovery rates.
- Geographic Expansion:Developing untapped tight gas formations in basins outside North America, such as the Vaca Muerta in Argentina or the Sichuan Basin in China, offers significant growth potential to meet regional energy demand.
Industry Challenges
- Specialized Talent Scarcity:A critical shortage of reservoir engineers and geoscientists skilled in both advanced data analytics and subsurface geology hinders the optimal application of new digital technologies in field development.
- Midstream Infrastructure Bottlenecks:Rapid production growth in key basins can outpace the development of necessary pipeline and processing capacity, leading to localized price discounts and constrained offtake.
- Public Opposition:Managing public concern and investor pressure related to the environmental impacts of hydraulic fracturing, such as water usage and induced seismicity, remains a persistent operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tight Gas Market |
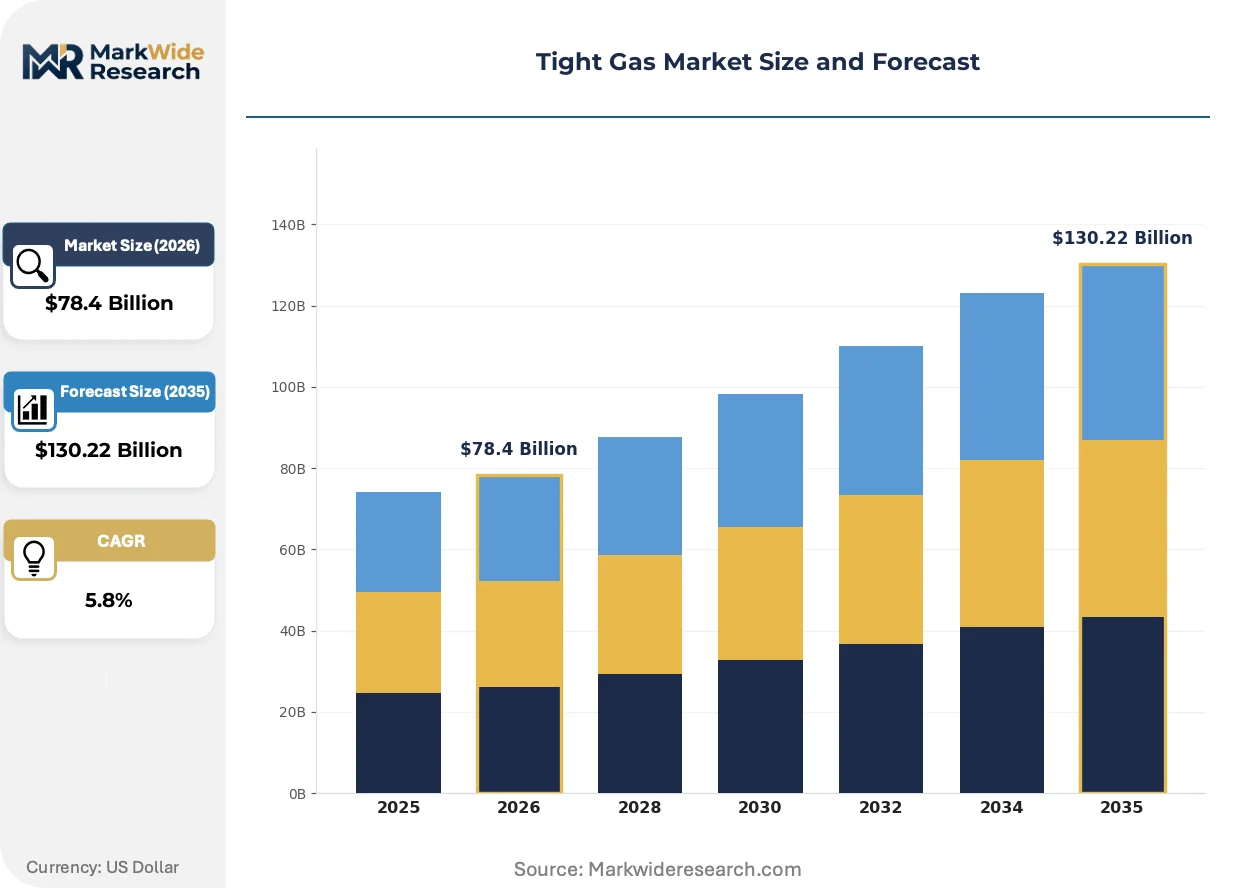
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $130.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Coalbed Methane, Shale Gas, Basin-Centered Gas, Deep Gas Technology: Hydraulic Fracturing, Horizontal Drilling, Microseismic Monitoring, Enhanced Recovery Application: Power Generation, Chemical Feedstock, Industrial Fuel, Residential Heating End User: Energy Utilities, Petrochemical Plants, Manufacturing Facilities, Domestic Consumers |
| Companies Covered | ExxonMobil Corporation, Chevron Corporation, ConocoPhillips, BP plc, TotalEnergies SE, PetroChina Company Limited, China Petroleum & Chemical Corporation, EOG Resources Inc., Equinor ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tight Gas Market Strategic Shifts & Innovations
Technological advancements and tightening environmental oversight are concurrently reshaping extraction methodologies and operational priorities in the tight gas sector. These forces push producers toward greater efficiency, improved resource recovery, and enhanced environmental accountability across their operations.
Re-fracturing techniques are designed to restimulate production from existing, underperforming wells. Operators in mature North American basins are increasingly adopting these methods to maximize the value of their current asset portfolio. This focus on well revitalization is displacing the traditional model of exclusively drilling new wells, thereby extending the productive life of existing infrastructure.
Regulations from bodies like the US Environmental Protection Agency (EPA) are imposing stricter controls on methane emissions from oil and gas facilities. This policy compels operators to implement enhanced leak detection and repair (LDAR) programs and invest in lower-emitting pneumatic devices. The upstream production segment is most affected, driving investment in advanced monitoring technologies like aerial surveillance and continuous emissions sensors.
A clear shift is occurring from purely spot-market sales toward long-term supply agreements that incorporate environmental performance metrics, such as certified low-methane gas. This development disrupts traditional commodity trading by creating a distinct market for differentiated, verifiably cleaner natural gas. The trend is most prominent in Europe, where utilities face pressure from frameworks like the EU Green Deal to decarbonize their energy procurement.
Tight Gas Market Segmentation
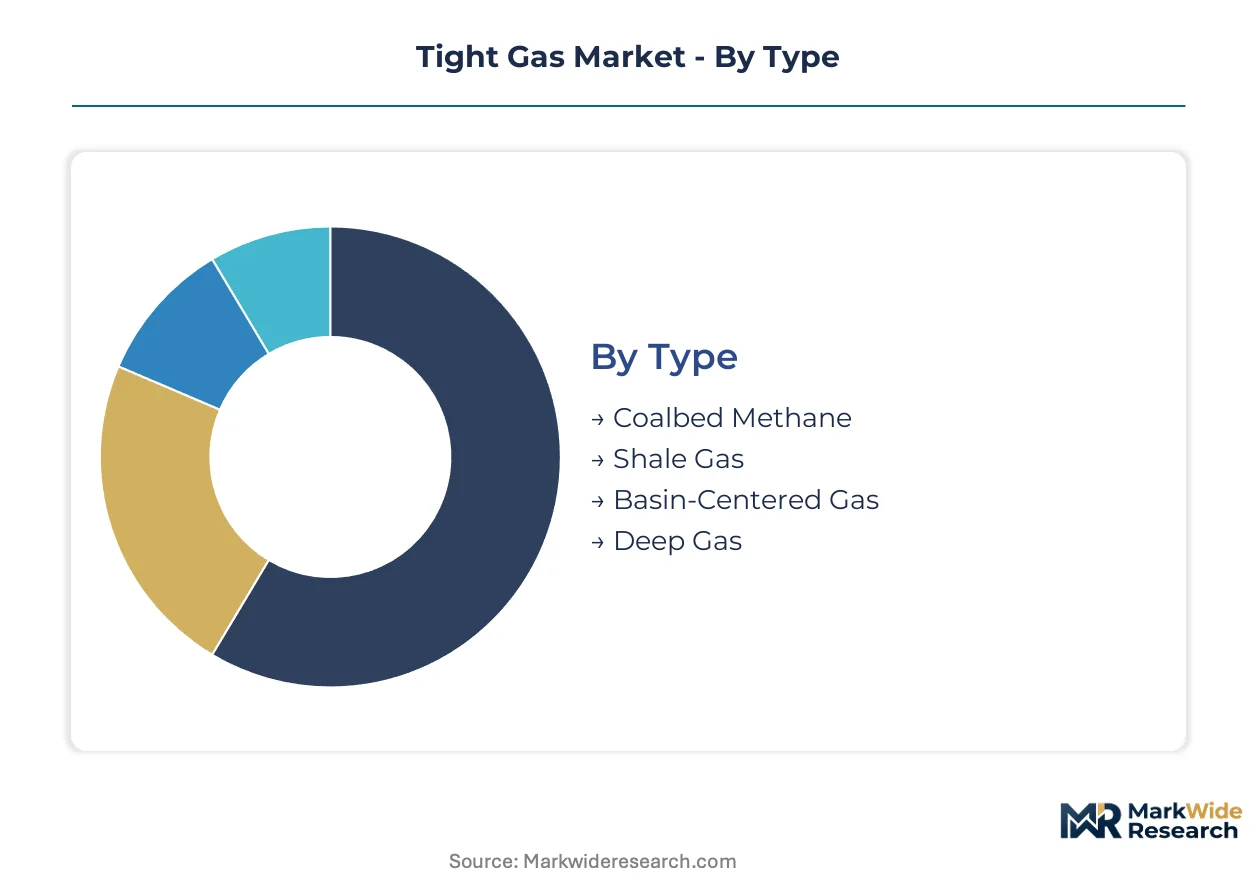
The tight gas market is segmented to reflect the diverse geological characteristics of unconventional reservoirs, the specialized technologies required for their extraction, and the varied end-use applications for this critical energy source. Understanding these distinctions helps producers tailor development strategies and manage complex regulatory landscapes.
Type:
Regulatory frameworks often differentiate tight gas resources based on their geological characteristics and extraction complexities.
- Shale Gas:This natural gas is trapped within low-permeability shale formations, often requiring extensive hydraulic fracturing and horizontal drilling for economic recovery. Demand from the power generation sector in the United States and China drives significant production volumes.
- Coalbed Methane:Methane adsorbed within coal seams constitutes this gas type, typically extracted through dewatering to reduce pressure. Environmental regulations from the US EPA and China's MEE increasingly focus on reducing associated methane emissions.
- Basin-Centered Gas:These continuous accumulations of gas exist in abnormally pressured, low-permeability reservoirs, often without a conventional water drive. Production requires specialized completion techniques to maintain flow rates.
- Deep Gas:This gas is found at significant depths, often under high pressure and temperature conditions, necessitating advanced drilling and completion technologies.
Established volume favors Shale Gas; emerging adoption favors Deep Gas.
Technology:
Extraction technologies for tight gas are primarily differentiated by their functional role in reservoir stimulation and production optimization.
- Hydraulic Fracturing:This technique involves injecting high-pressure fluid to create fractures in tight rock formations, enhancing permeability and gas flow to the wellbore. Continuous improvements in multi-stage fracturing unlock vast, previously uneconomical reserves across North America.
- Horizontal Drilling:This method allows wells to be drilled laterally through hydrocarbon-bearing formations, maximizing reservoir contact and improving recovery rates. Operators leverage extended-reach horizontal wells to optimize field development in basins like the Permian.
- Microseismic Monitoring:This technology detects and maps the micro-earthquakes generated during hydraulic fracturing, providing real-time insights into fracture geometry and growth. It allows for more precise stimulation designs.
- Enhanced Recovery:These techniques aim to boost production from existing wells, including re-fracturing or injecting fluids to displace residual gas.
Efficiency gains concentrate in Hydraulic Fracturing; future innovation targets Enhanced Recovery.
Application:
Tight gas applications are segmented by their scale of consumption and their strategic importance across various industrial and consumer sectors.
- Power Generation:Tight gas serves as a critical fuel for gas-fired power plants, providing baseload and dispatchable electricity generation. The global power sector's shift from coal to natural gas drives sustained demand, particularly in Europe.
- Chemical Feedstock:Natural gas is a primary raw material for producing petrochemicals, including ammonia and methanol, and serves as a key input for blue hydrogen production. This application offers a strategic growth opportunity within the emerging low-carbon industrial economy.
- Industrial Fuel:Manufacturing facilities use tight gas as a direct energy source for process heat, boilers, and industrial furnaces.
- Residential Heating:Domestic consumers utilize natural gas for space heating, water heating, and cooking in homes.
The largest demand segment remains Power Generation; diversification opportunities emerge in Chemical Feedstock.
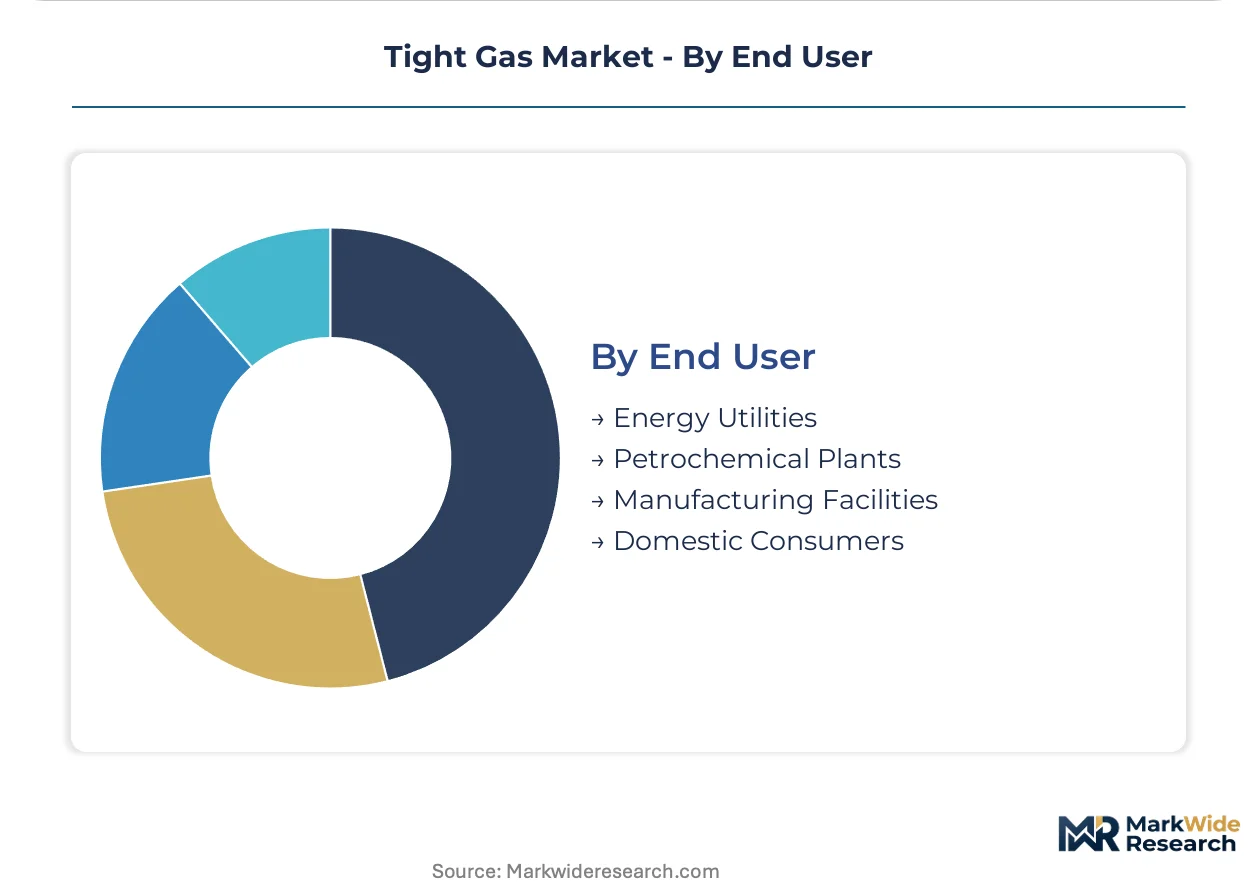
End User:
End-user segments for tight gas reflect the direct and indirect consumption patterns across the energy value chain.
- Energy Utilities:These entities purchase tight gas to fuel their power generation assets, ensuring grid stability and meeting electricity demand. Utilities face increasing pressure from frameworks like the EU Green Deal to procure lower-emission fuels.
- Petrochemical Plants:Chemical manufacturers consume tight gas as a vital feedstock for various industrial processes and product synthesis. These plants drive the demand for gas as a transition fuel for decarbonization.
- Manufacturing Facilities:Industrial plants across diverse sectors consume tight gas directly for their operational energy requirements.
- Domestic Consumers:Households represent the residential end-users, relying on tight gas for heating and other domestic energy needs.
Bulk consumption is dominated by Energy Utilities; distributed consumption is served by Domestic Consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Environmental Protection Agency (EPA) sets a precedent for methane emission monitoring, influencing tight gas operations globally. National energy security concerns drive increased production in several key regions. Producers navigate complex regulatory environments while addressing growing energy demand.
United States
Demand for power generation continues to expand across the United States, utilizing tight gas as a cleaner burning fuel. The US EPA's methane regulations impose significant compliance costs on operators, encouraging investment in emission reduction technologies. Extraction activity is concentrating heavily in the Permian Basin, where advanced technologies optimize well placement and recovery.
China
China's Ministry of Ecology and Environment (MEE) focuses on reducing methane emissions from gas operations, impacting domestic producers. Domestic energy security policies support unconventional gas development to reduce reliance on imported energy sources. The Sichuan Basin is a key area for tight gas development, meeting regional industrial fuel needs and supporting economic growth.
Argentina
Demand for energy in Argentina supports the exploration of unconventional resources to meet industrial and residential requirements. Government policies promote investment in domestic hydrocarbon production to bolster the national economy and energy independence. The Vaca Muerta formation in Patagonia offers substantial growth potential for tight gas extraction and development.
Germany
European demand for natural gas as a transition fuel drives import needs, despite the EU Green Deal prioritizing lower-carbon sources. Germany's energy policies are shifting towards natural gas to phase out coal and nuclear power generation. Industrial facilities across the Ruhr Area utilize gas for process heat and manufacturing, sustaining import demand.
Canada
Natural gas demand from the power generation sector remains consistent in Canada, especially for baseload electricity generation. Environmental regulations from federal and provincial agencies influence drilling and completion activities, requiring rigorous operational standards. The Montney Formation in British Columbia and Alberta represents a major tight gas production hub, serving North American markets.
Tight Gas Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the tight gas market, defining its competitive structure. These large firms leverage extensive capital for large-scale project execution and maintain market position through diversified energy portfolios. Specialized E&P companies focus on optimizing unconventional assets with advanced subsurface modeling and real-time geosteering. Dominant competitive moves include disciplined capital allocation for new projects and strategic portfolio optimization across geographies.
Within the integrated energy firm archetype, ExxonMobil Corporation exemplifies a strategy of large-scale project execution and disciplined capital allocation across its global operations. ConocoPhillips occupies a distinct position as a North American unconventional asset optimizer, strategically focusing its portfolio on high-value tight gas resources. EOG Resources Inc. represents a specialist approach, leveraging advanced subsurface modeling capabilities for precise well placement and real-time optimization of fracturing operations, thereby enhancing recovery rates from complex reservoirs.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Chevron Corporation |
| ConocoPhillips |
| BP plc |
| TotalEnergies SE |
| PetroChina Company Limited |
| China Petroleum & Chemical Corporation |
| EOG Resources Inc. |
| Equinor ASA |
Cost & Logistics Intelligence
The shift from coal to natural gas for power generation reshapes energy supply chains and influences pricing dynamics. This transition impacts regional gas pricing and infrastructure investment.
Pricing Analysis
Geographic price spreads for tight gas reflect regional supply-demand imbalances and infrastructure bottlenecks. The dominant pricing model is commodity spot pricing, supplemented by long-term contract-based offtake agreements. Price differentiation stems from certified low-methane content and delivery location. Pricing pressure stems from competition with renewable energy sources. Energy utilities are the least price-sensitive segment, while industrial fuel users show higher sensitivity.
Supply Chain Analysis
Strategic stockpiles of tight gas are preferred over just-in-time inventory for energy security, particularly in Europe. Supply concentration draws from North America, especially the United States and Canada, and emerging regions like Argentina. Raw material dependencies include specialized proppants and water for hydraulic fracturing. Logistics chokepoints, particularly midstream infrastructure bottlenecks, represent a structural supply chain risk. Distribution runs through extensive pipeline networks to end-user facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tight gas market presents a significant service-attach opportunity, with advanced monitoring technologies for emissions reduction expanding faster than new drilling hardware. This growth in environmental services offers recurring revenue streams.
For Market Incumbents: Secure access to specialized talent in data analytics and geosteering to counter skill scarcity. Invest in advanced subsurface modeling R&D to optimize well placement and recovery rates, mitigating commodity price volatility. Pursue vertical integration into midstream infrastructure to alleviate bottlenecks. This strategy defends against margin pressure from infrastructure constraints.
For New Entrants and Emerging Players: Lead with innovative re-fracturing techniques to revitalize existing wells in mature basins, targeting underperforming assets. The most penetrable segment for new players involves specialized service provision for enhanced recovery. Focus on digital transformation solutions for real-time optimization. A go-to-market angle can be offering superior environmental performance metrics.
For Investors and Strategic Acquirers: The market sits at a maturation phase that favors specialized E&P companies with strong technological differentiation. Long-term viability rests on balancing energy security with decarbonization mandates over the next decade. Acquisition targets should prioritize firms with proven expertise in methane emission reduction technologies. The signal to watch is sustained investment in blue hydrogen production facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout in Permian Basin | Increases domestic energy supply for power generation demand in the United States. |
| Green Certification Program | Attracts European energy utilities seeking lower-carbon natural gas for procurement. |
| Technology Licensing for Re-fracturing | Extends productive life of existing tight gas wells in North American basins. |
| Vertical Integration into Methane Monitoring | Reduces operational costs and ensures regulatory compliance with US EPA standards. |
| Strategic Partnership for Blue Hydrogen | Positions tight gas as a transition fuel in the emerging industrial economy. |
Research Approach
Initial hypotheses were tested against primary input from reservoir engineers, environmental compliance officers, utility procurement managers, and petrochemical plant operators, then refined through iterative analysis. This involved combining insights from in-depth interviews with secondary validation from EIA data, IEA reports, and corporate sustainability disclosures. A bottom-up and top-down triangulation approach ensured robust data integrity.
Variance decomposition identified key drivers across the analysis window, categorizing tight gas by type, technology, application, and end-user, alongside regional production hubs. Compound annual growth rates were derived through a weighted average of segment-specific growth trajectories. Forecast inputs included projected power generation capacity additions and petrochemical feedstock demand.
Forecasts assume regulatory continuity in US EPA and EU Green Deal regimes; material policy shifts would require re-modeling. Geopolitical events or significant technological breakthroughs represent key risk factors. Revision becomes warranted when global energy demand patterns shift unexpectedly.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Accumulators Market
Oil & Gas
Africa Oil Refining Market
Oil & Gas
Europe Oilfield Services Market
Oil & Gas
United States Oil and Gas Midstream Market
Oil & Gas
Smart Well Market
Oil & Gas
Latin America Oilfield Chemicals Market
Oil & Gas
Oil Storage Terminal Market
Oil & Gas
Europe Intelligent Pigging Market
Oil & Gas
Russia Drill Pipe Market
Oil & Gas
South and Central America Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Oil and Gas Cloud Applications Market
Oil & Gas
Italy Oil and Gas Downstream Market
Oil & Gas
Rig and Oilfield Mats Market
Oil & Gas
Europe Seismic Survey Market
Oil & Gas
Middle-East Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Oil and Gas Engineering Services Market