
 Deepwater and Ultra-Deepwater Exploration and Production Market | 2026-2036
Deepwater and Ultra-Deepwater Exploration and Production Market Size, Share, and Industry Trends Forecast 2026-2036
Deepwater and Ultra-Deepwater Exploration and Production Market Outlook
The global deepwater engineer labor pool is collapsing as demographic retirements outpace university pipeline replenishment. Shell PLC sustains its competitive edge through proprietary subsea architecture and integrated project delivery capabilities. Petroleo Brasileiro SA anchors Latin American deepwater activity through its dominant position in Brazil's pre-salt province. Equinor ASA differentiates via floating offshore wind-to-oil hybrid competencies and harsh-environment North Sea expertise.
Deepwater and ultra-deepwater exploration and production denotes hydrocarbon extraction from seabed depths exceeding 400 meters, employing dynamic positioning drillships and subsea trees rated for pressures above 15,000 psi and temperatures surpassing 350°F. Floating Production Storage and Offloading vessels command the largest capital allocation within technology segmentation due to their elimination of pipeline infrastructure requirements. Within service type segmentation, production-phase contracts generate superior margin pools relative to commoditized drilling services. Enhanced Oil Recovery applications are expanding fastest within the application dimension as operators target recovery factors above forty percent in mature deepwater basins.
The US Bureau of Safety and Environmental Enforcement mandates blowout preventer testing protocols that shape subsea hardware procurement specifications. Brazil's national petroleum regulator imposes local content requirements that redirect supply chain sourcing toward domestic fabrication yards. The EU F-Gas Regulation constrains synthetic drilling fluid formulations in European offshore operations. Stakeholders must monitor regulatory divergence between prescriptive safety regimes and risk-based performance standards when allocating capital across jurisdictional portfolios.
Market Dynamics
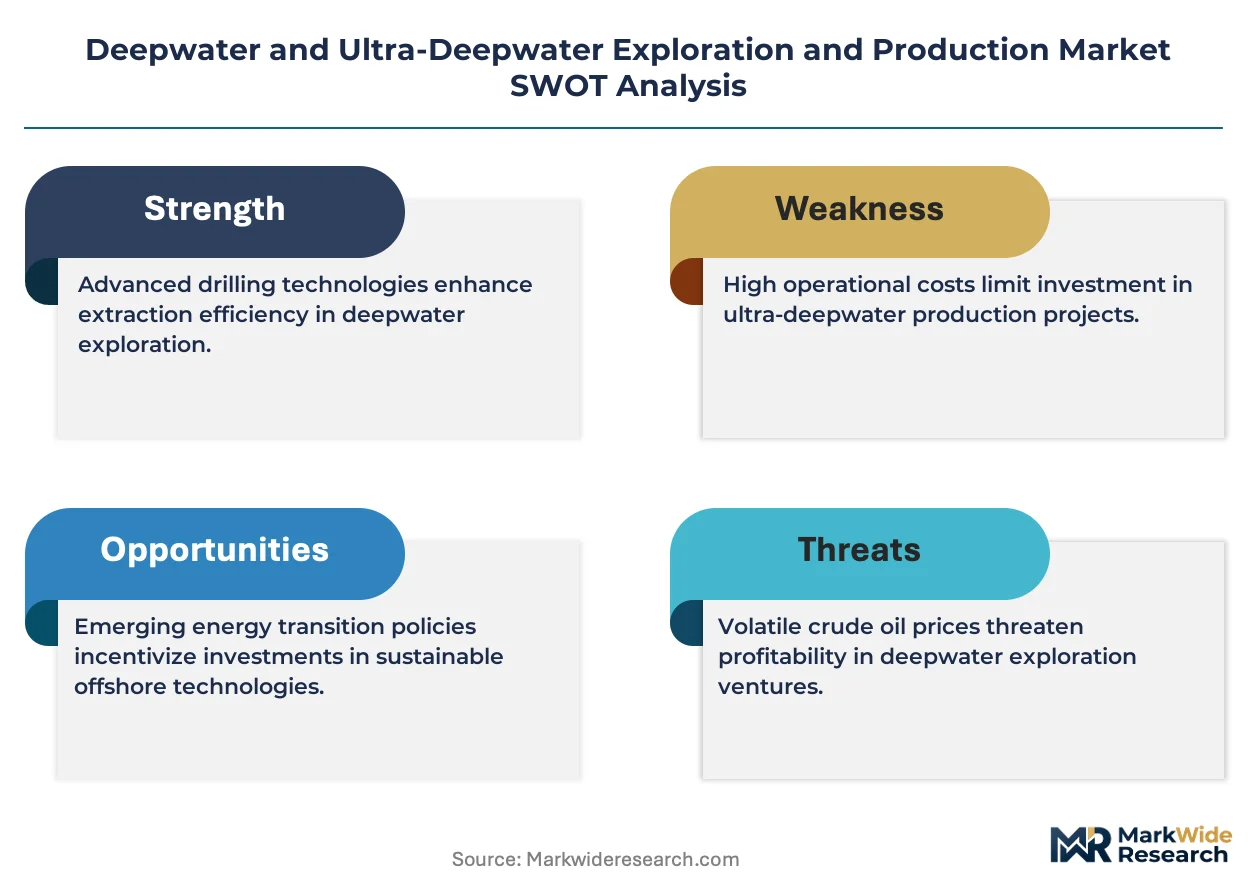
Subsea tieback architecture is collapsing field development economics across marginal deepwater reservoirs, compressing breakeven thresholds below fifty dollars per barrel and unlocking stranded assets previously classified as non-commercial.
Growth Catalysts
- Pre-salt basin development:Brazil's prolific pre-salt formations anchor Latin American capital allocation, with national oil companies committing to multi-decade floating production programs.
- F-Gas Regulation phase-down:The EU's synthetic fluid constraints are accelerating adoption of bio-based drilling mud formulations in European offshore operations.
- Enhanced Oil Recovery deployment:Thermal and chemical EOR applications target recovery factors exceeding forty percent in mature Gulf of Mexico lower tertiary formations.
Market Restraints
- Specialized vessel scarcity:Dynamic positioning drillship availability concentrates among Asian shipyards, creating yard-slot bottlenecks and eighteen-month delivery backlogs.
- High-pressure hardware qualification:Subsea trees rated for fifteen-thousand psi and three-hundred-fifty-degree Fahrenheit service face extended factory acceptance testing cycles.
- Demographic engineering deficit:The global deepwater technical labor pool contracts as retirement rates outpace petroleum engineering university matriculation.
Strategic Opportunities
- West African frontier basins:Underexplored deepwater blocks offshore Angola and Nigeria offer untapped resource potential for operators with subsea installation capabilities.
- Floating offshore wind convergence:Hybrid floating platforms combining oil production with offshore wind generation create dual-revenue infrastructure models.
- Local content mandates:Brazil's ANP domestic sourcing requirements redirect supply chain investment toward domestic fabrication yards and service providers.
Industry Challenges
- Subsea architecture integration:Brownfield tieback projects demand complex interface engineering with legacy platform infrastructure and obsolete control systems.
- Blowout preventer certification:US Bureau of Safety and Environmental Enforcement testing protocols impose rigorous maintenance documentation and recertification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deepwater and Ultra-Deepwater Exploration and Production Market |
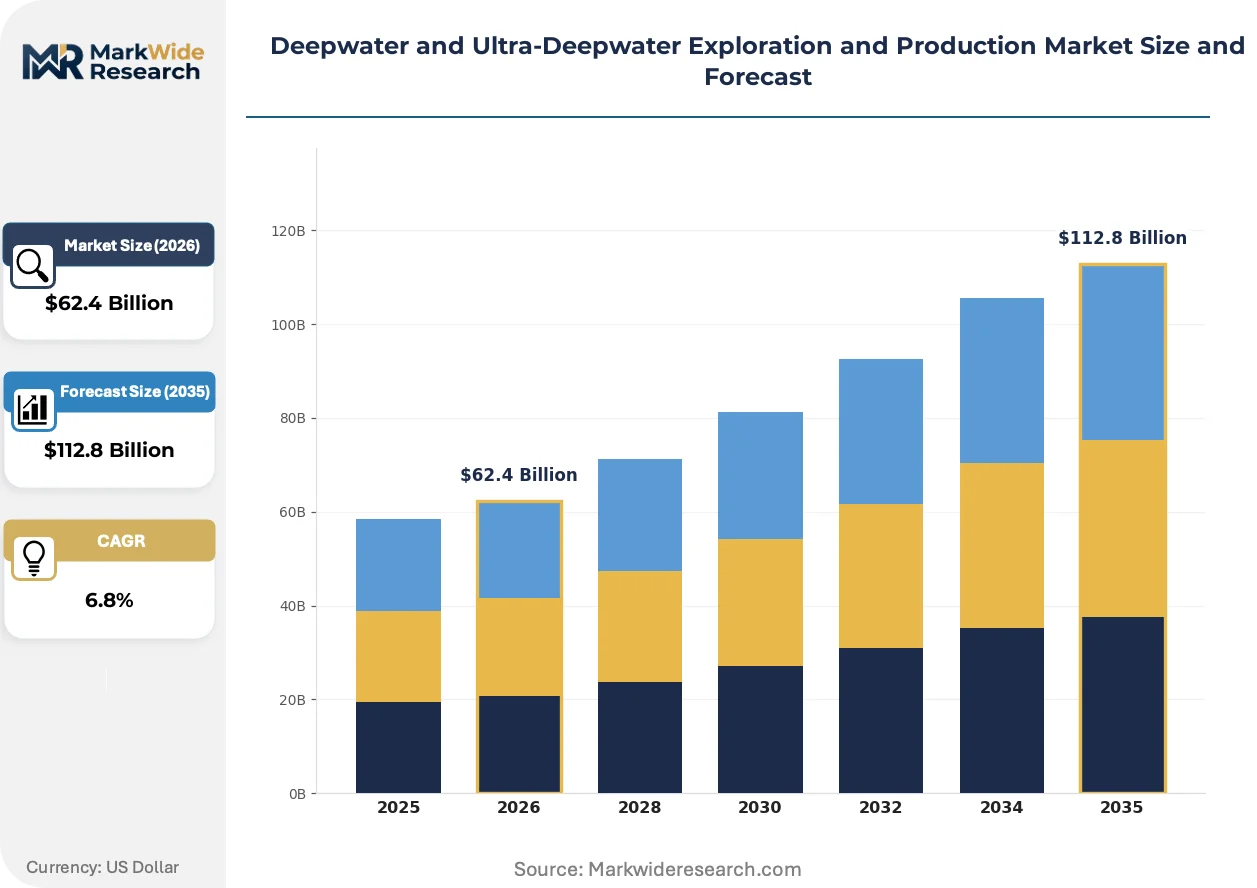
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $112.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Subsea Production Systems, Floating Production Storage and Offloading, Drill Ships, Semi-Submersibles Service Type: Exploration, Drilling, Production, Decommissioning Application: Oil Extraction, Gas Extraction, Enhanced Oil Recovery, Site Surveying End User: Oil and Gas Companies, Independent Operators, Service Providers, Government Agencies |
| Companies Covered | BP PLC, Petroleo Brasileiro SA, Shell PLC, Eni S.p.A., Equinor ASA, Chevron Corporation, TotalEnergies SE, China National Offshore Oil Corporation, Exxon Mobil Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deepwater and Ultra-Deepwater Exploration and Production Market Strategic Shifts
Digital twin technology and autonomous subsea robotics are restructuring how operators monitor reservoir performance and execute intervention campaigns without surface vessel support.
All-electric subsea production systems are bifurcating field architecture design. Equinor and Shell deploy all-electric trees and manifolds in North Sea and Gulf of Mexico developments. This technology eliminates hydraulic umbilical requirements, reducing installation cost and complexity while enabling longer step-out distances from host facilities.
The EU F-Gas Regulation constrains synthetic drilling fluid formulations in European offshore operations. Operators substitute bio-based alternatives or closed-loop mud systems to maintain compliance. North Sea drilling contractors face reformulation costs and supply chain requalification for fluid additives.
Integrated project delivery contracts compress supplier tiers and transfer risk to engineering-procurement-construction firms. National oil companies in Brazil and West Africa favor single-point accountability models over traditional fragmented contracting. This procurement evolution demands EPC vendors absorb subsea hardware, installation, and commissioning scope within fixed-price structures.
Deepwater and Ultra-Deepwater Exploration and Production Market Segmentation
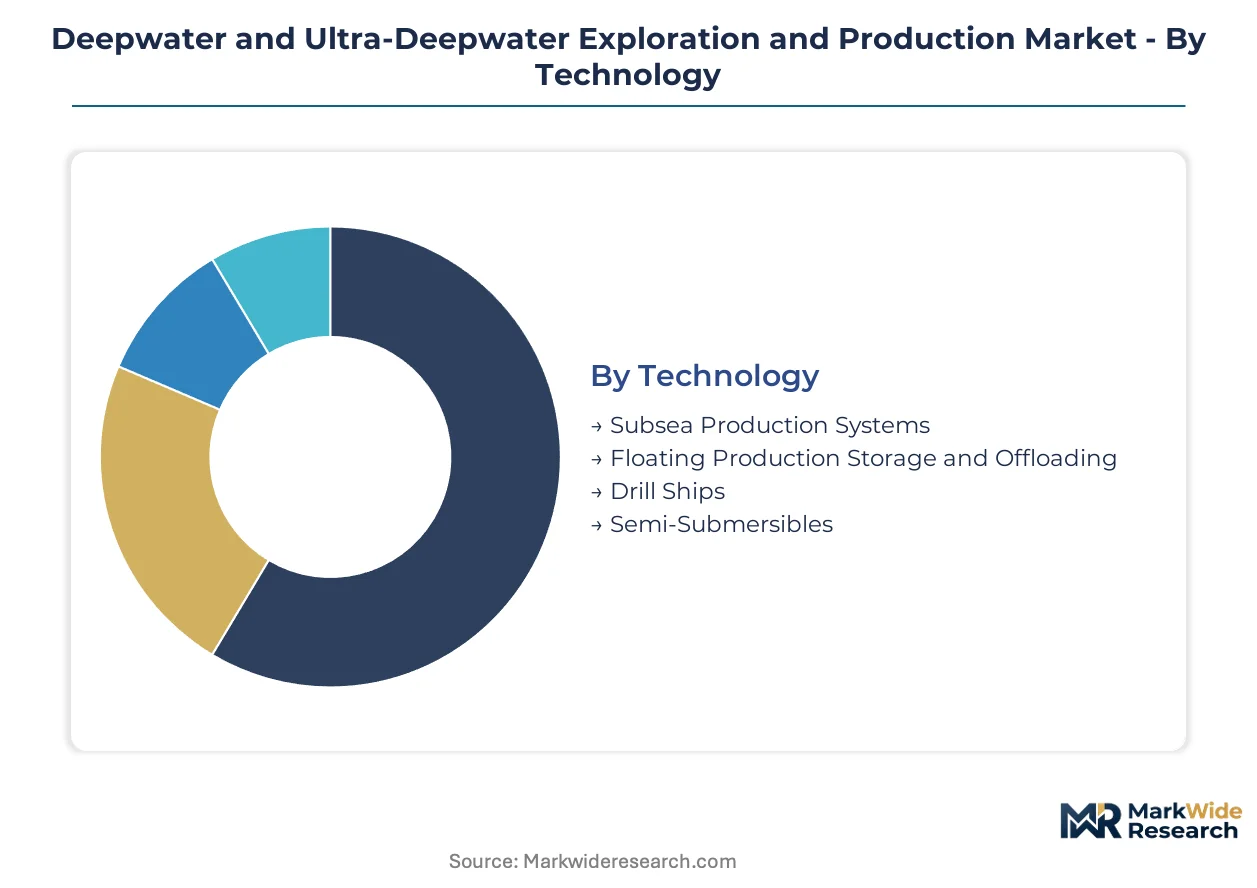
Deepwater and ultra-deepwater exploration and production markets fragment across four distinct dimensions that shape capital allocation, regulatory exposure, and margin structure. Technology segmentation determines hardware procurement specifications. Service type segmentation governs contract duration and revenue recognition patterns. Application and end-user dimensions direct geographic deployment and risk-bearing arrangements.
Technology:
Regulatory differentiation between prescriptive safety regimes and risk-based performance standards shapes hardware qualification timelines and certification costs across each technology class.
- Floating Production Storage and Offloading:These vessels eliminate pipeline infrastructure requirements through integrated hydrocarbon processing, storage, and offloading capabilities. Brazil's national oil company anchors regional demand through multi-decade floating production commitments in pre-salt basins. The US Bureau of Safety and Environmental Enforcement mandates blowout preventer testing protocols that extend commissioning timelines.
- Subsea Production Systems:All-electric trees and manifolds rated for fifteen-thousand psi and three-hundred-fifty-degree Fahrenheit service enable longer step-out distances from host facilities. Equinor and Shell deploy these systems in North Sea and Gulf of Mexico developments where hydraulic umbilical elimination reduces installation complexity.
- Drill Ships:Dynamic positioning drillship availability concentrates among Asian shipyards, creating eighteen-month delivery backlogs for newbuild capacity.
- Semi-Submersibles:Harsh-environment hull designs support North Sea and West African operations where station-keeping reliability dominates contractor selection.
Established volume favors Floating Production Storage and Offloading; emerging adoption favors Subsea Production Systems.
Service Type:
Contract duration and margin structure diverge sharply between front-loaded exploration services and long-tail production-phase engagements.
- Production:Long-term field operation contracts generate superior margin pools through integrated service provision spanning subsea intervention, facility maintenance, and reservoir management. Brazil's local content mandates redirect procurement toward domestic fabrication yards and service providers.
- Drilling:Commoditized day-rate competition compresses returns despite high capital intensity, with specialized vessel scarcity creating pricing leverage for available rig capacity.
- Exploration:Seismic acquisition and wildcat drilling programs carry binary outcome risk with concentrated revenue recognition in appraisal phases.
- Decommissioning:Mature basin liability management drives demand for plug-and-abandonment and platform removal services in the Gulf of Mexico and North Sea.
Production commands the steepest expansion trajectory as operators prioritize recovery optimization over frontier exploration.
Application:
Recovery factor targets and reservoir maturity determine technology selection and service intensity across application categories.
- Enhanced Oil Recovery:Thermal and chemical EOR applications target recovery factors exceeding forty percent in mature Gulf of Mexico lower tertiary formations. Subsea tieback architecture collapses development economics for marginal reservoirs.
- Oil Extraction:Pre-salt carbonate reservoirs in Brazil's Santos Basin anchor Latin American capital allocation through high-flow-rate wells.
- Gas Extraction:Deepwater gas developments face commercial constraints from liquefaction infrastructure access and regional demand patterns.
- Site Surveying:Autonomous subsea robotics and digital twin technology restructure how operators execute seabed characterization without surface vessel support.
Oil Extraction retains dominant revenue share; Enhanced Oil Recovery gains share fastest as basin maturity advances.
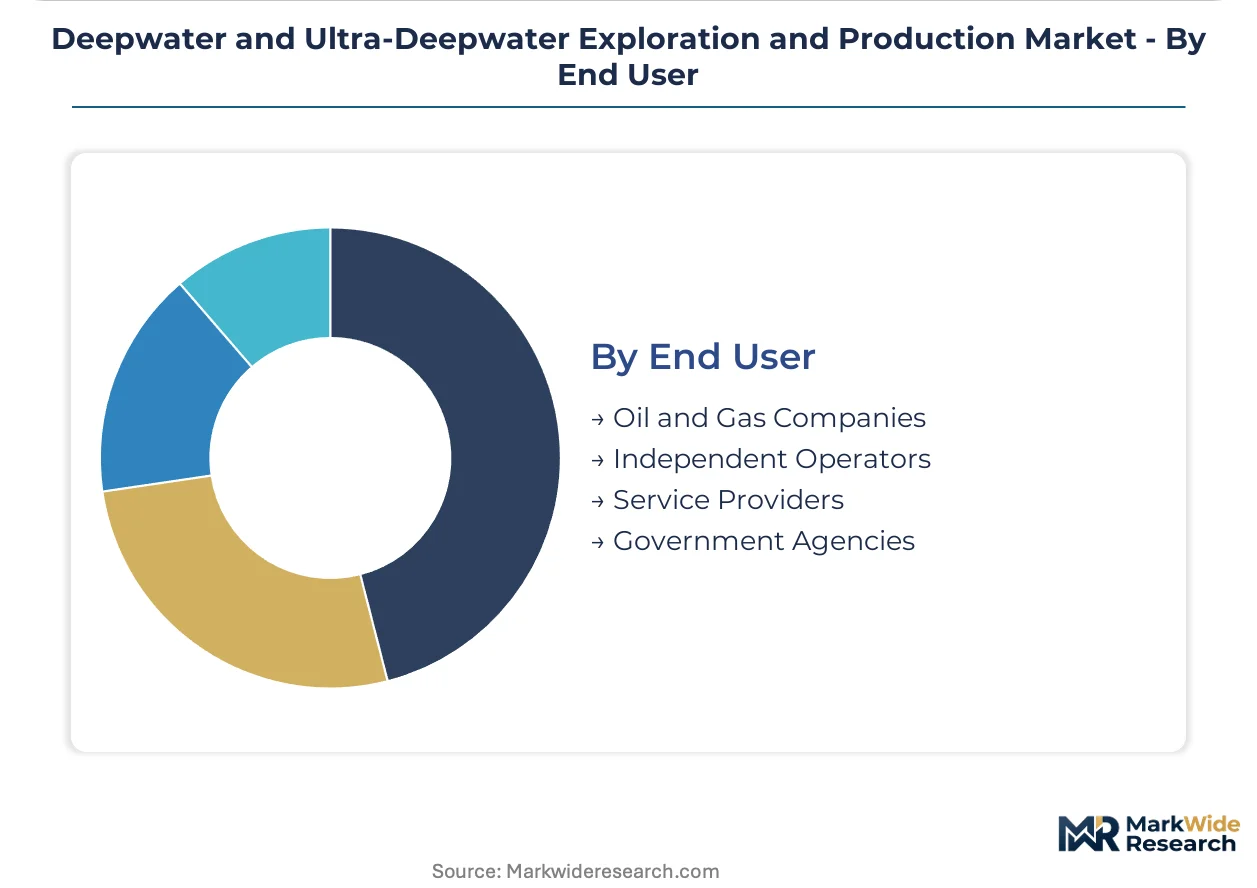
End User:
Risk-bearing capacity and capital access determine procurement strategy and contract structure preferences across end-user categories.
- Oil and Gas Companies:Integrated majors deploy proprietary subsea architecture and integrated project delivery capabilities to compress development schedules. Shell sustains competitive edge through captive technology and EPC absorption of installation risk.
- Independent Operators:Portfolio players target stranded assets unlocked by subsea tieback economics below fifty dollars per barrel breakeven thresholds.
- Service Providers:Engineering-procurement-construction firms face margin compression from fixed-price risk transfer in single-point accountability contracts favored by national oil companies.
- Government Agencies:Regulatory bodies impose local content requirements and safety protocols that redirect supply chain sourcing and shape hardware specifications.
Oil and Gas Companies dominate capital deployment; Independent Operators expand fastest as tieback technology unlocks marginal field commercialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deepwater operators deploy capital differently across basins. Brazil prioritizes pre-salt carbonate development through national oil company programs. The United States concentrates on lower tertiary formations with tieback economics. West Africa pursues frontier exploration in underexplored blocks.
Brazil
Petroleo Brasileiro SA anchors Latin American floating production commitments through multi-decade pre-salt programs in the Santos Basin. The Agência Nacional do Petróleo imposes local content requirements redirecting supply chain sourcing toward domestic fabrication yards. Rio de Janeiro's offshore engineering cluster hosts subsea hardware qualification and vessel commissioning operations.
United States
Gulf of Mexico operators target recovery factors exceeding forty percent in mature lower tertiary formations through enhanced oil recovery deployment. The Bureau of Safety and Environmental Enforcement mandates blowout preventer testing protocols shaping subsea hardware procurement specifications. Houston's energy corridor concentrates engineering-procurement-construction firm headquarters and subsea technology development centers.
Angola
Underexplored deepwater blocks offshore Cabinda and the Kwanza Basin attract operators with subsea installation capabilities seeking frontier resource access. The national petroleum regulator enforces production sharing contract terms governing cost recovery and local participation requirements. Luanda's port infrastructure supports floating production storage and offloading vessel integration and offshore logistics coordination.
Norway
Equinor ASA deploys floating offshore wind-to-oil hybrid platforms combining hydrocarbon production with renewable generation in North Sea harsh environments. The Petroleum Safety Authority applies risk-based performance standards distinct from prescriptive safety regimes elsewhere. Stavanger's subsea technology cluster advances all-electric tree and manifold development for high-pressure high-temperature service.
United Kingdom
North Sea decommissioning obligations drive demand for plug-and-abandonment and platform removal services as mature basin liability management intensifies. The Health and Safety Executive regulates well integrity and subsea installation safety through goal-setting frameworks. Aberdeen's subsea engineering hub supports brownfield tieback projects demanding complex interface engineering with legacy infrastructure.
Deepwater and Ultra-Deepwater Exploration and Production Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in deepwater exploration and production. Integrated majors deploy proprietary subsea architecture and captive project delivery capabilities to compress development schedules. Engineering-procurement-construction firms and drilling contractors occupy the specialist tier, absorbing installation risk under fixed-price structures. Strategic moves concentrate on integrated project delivery contracting and subsea technology licensing arrangements.
Within the integrated major tier, Shell PLC and BP PLC exemplify operators with captive subsea capabilities and multi-basin deployment records. Petroleo Brasileiro SA occupies a distinctive position as a national oil company with dominant pre-salt access and floating production program scale. Equinor ASA represents the hybrid competency archetype, bridging offshore oil and floating wind development in harsh North Sea conditions.
| Leading Market Players |
|---|
| BP PLC |
| Petroleo Brasileiro SA |
| Shell PLC |
| Eni S.p.A. |
| Equinor ASA |
| Chevron Corporation |
| TotalEnergies SE |
| China National Offshore Oil Corporation |
| Exxon Mobil Corporation |
| Others |
Value Chain & Pricing Dynamics
Asian shipyard capacity utilization above ninety percent creates pricing leverage for dynamic positioning drillship newbuilds while compressing margins for European subsea hardware fabricators competing on local content compliance. Scale concentration in South Korean and Singaporean yards establishes price floors that independent operators cannot undercut without sacrificing high-pressure qualification standards.
Pricing Analysis
Long-term offtake contracts dominate capital-intensive floating production storage and offloading procurement, insulating Brazilian national oil companies from spot-market volatility while exposing independent operators to day-rate fluctuations in commoditized drilling services. Price differentiation rests on pressure rating certification tiers—fifteen-thousand psi subsea trees command substantial premiums over ten-thousand psi equivalents—and on vertical integration depth among engineering-procurement-construction firms. Cost compression in drilling services is intensifying because dynamic positioning vessel scarcity concentrates pricing power with Asian yard incumbents. National oil companies exhibit lowest price sensitivity due to sovereign capital access; independent portfolio operators face acute sensitivity at sub-fifty-dollar breakeven thresholds.
Supply Chain Analysis
Strait of Malacca transit underwrites just-in-time delivery schedules for high-grade steel forgings sourced from South Korea, Japan, and Germany that feed subsea tree manufacturing. Raw material dependencies center on nickel-based alloys for high-temperature service, synthetic drilling fluid base stocks subject to EU F-Gas Regulation constraints, and specialized dynamic positioning system electronics. Single-source vulnerability concentrates in Asian shipyard slots for drillship newbuilds, where eighteen-month backlogs create irreplaceable capacity bottlenecks. Distribution runs through integrated project delivery contracts that compress supplier tiers and transfer installation risk to engineering-procurement-construction firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The contracting global deepwater engineer labor pool—where demographic retirements outpace petroleum engineering matriculation—creates durable scarcity premiums for operators with captive technical capabilities and integrated project delivery competencies.
For Market Incumbents: Secure proprietary subsea architecture licensing revenue streams and captive fabrication yard partnerships to defend against emerging all-electric system specialists. Anchor workforce development pipelines through university endowments and accelerated certification programs that narrow the demographic engineering deficit. Vertical integration into high-pressure hardware qualification laboratories insulates margin pools from extended factory acceptance testing cycles. For New Entrants and Emerging Players: ANP local content fast-track certification unlocks procurement access to Petrobras pre-salt floating production programs where incumbent service provider concentration remains incomplete. Target West African frontier basins offshore Angola and Nigeria where subsea installation capability scarcity exceeds competitive supply. Deploy digital twin technology partnerships as differentiated go-to-market positioning against legacy intervention contractors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors engineering-procurement-construction firms with fixed-price risk absorption capabilities and all-electric subsea system development pipelines. Long-term viability hinges on exposure to pre-salt basin development duration and lower tertiary enhanced oil recovery deployment intensity. Monitor blowout preventer recertification timeline extensions as inflection indicator for regulatory compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| All-Electric Subsea System Deployment | Equinor and Shell deployments in North Sea and Gulf of Mexico eliminate hydraulic umbilical infrastructure. |
| Integrated Project Delivery Contracting | Single-point accountability models transfer installation risk to engineering-procurement-construction vendors. |
| Local Content Compliance Investment | ANP domestic sourcing requirements redirect supply chain toward Brazilian fabrication yards. |
| Digital Twin Technology Integration | Autonomous subsea robotics enable reservoir monitoring without surface vessel support. |
| Enhanced Oil Recovery Capability Buildout | Thermal and chemical applications target recovery factors exceeding forty percent in mature basins. |
Study Parameters
Cross-validation between primary fieldwork with subsea project engineers and secondary analysis of regulatory filings anchors the qualitative findings on technology adoption timelines and local content compliance costs. The research program combined structured interviews with floating production vessel procurement officers, petroleum reservoir engineers, subsea hardware qualification specialists, and drilling contract negotiators alongside validation through ANP regulatory databases, Bureau of Safety and Environmental Enforcement incident reports, and engineering-procurement-construction firm SEC disclosures. Bottom-up field development project aggregation and top-down basin-level resource assessment triangulate volume estimates.
Sensitivity analysis around Brent price assumptions, vessel delivery schedules, and regulatory local content percentage thresholds shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include technology class, service type contract duration, application recovery factor target, and end-user risk-bearing capacity. CAGRs derive from project sanctioning velocity and installed base replacement cycles. Forecast inputs incorporate subsea tieback breakeven threshold trajectories and floating offshore wind convergence adoption rates.
Decision-makers should treat outputs as directional under base assumptions of sustained pre-salt capital commitment and stable high-pressure hardware qualification timelines; material deviation in Brazilian fiscal regime terms or Asian shipyard capacity expansion would warrant model refresh. Practitioners should keep alternative scenarios live as EU F-Gas Regulation phase-down schedules and demographic engineering deficit severity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
United States Oil and Gas Separation Market
Oil & Gas
Sudan Oil and Gas Market
Oil & Gas
South America Oil and Gas Hoses and Coupling Market
Oil & Gas
Mining and Oil & Gas Fasteners Market
Oil & Gas
Downhole Equipment Market
Oil & Gas
Flexible Pipes for Oil and Gas Market
Oil & Gas
Middle East Wireline Logging Services Market
Oil & Gas
Subsea Well Access System Market
Oil & Gas
Oil and Gas Logistics Market
Oil & Gas
Spacer Fluid Market
Oil & Gas
Australia Oil and Gas Upstream Market
Oil & Gas
Middle-East and Africa Liner Hanger System Market
Oil & Gas
Oilfield Air Drilling Market
Oil & Gas
Africa Oil Refining Market
Oil & Gas
Africa Drilling and Completion Fluids Market
Oil & Gas
Intelligent Pigging Services Market