
 North Africa Refined Petroleum Products Market | 2026-2036
North Africa Refined Petroleum Products Market Size, Share, and Industry Trends Forecast 2026-2036
North Africa Refined Petroleum Products Market Analytics
A widening capital-intensity divergence between integrated upstream operators and downstream marketers is reorganizing competitive tiers across North Africa. Sonatrach SPA leverages its captive crude supply and refinery network to dominate Algeria's domestic product distribution. TotalEnergies SE competes through its coastal storage terminals and retail footprint spanning Morocco and Tunisia. Egyptian General Petroleum Corporation anchors government-backed supply contracts with power generators and state transport fleets.
Refined petroleum products are hydrocarbon derivatives produced through atmospheric and vacuum distillation, catalytic cracking, and hydrotreating of crude oil, yielding fuels with specified sulfur content, octane ratings, and cetane indices for combustion engines and industrial heat systems. Diesel commands the largest volume share across North Africa's product slate, driven by freight transport and backup power generation in grid-stressed areas. Jet fuel represents the fastest-expanding category, reflecting capacity additions at Cairo International Airport and Casablanca Mohammed V International Airport. The transportation application absorbs the majority of regional output, while industrial buyers in Egypt's cement and fertilizer sectors sustain premium-priced low-sulfur diesel offtake.
Algeria's national hydrocarbon regulator enforces domestic supply obligations on refiners, while Egypt's petroleum ministry coordinates import licensing and pricing through the Egyptian General Petroleum Corporation. Morocco's energy transition agency applies blending mandates that incrementally raise biofuel content in gasoline and diesel pools. Stakeholders must track subsidy phase-out schedules, refinery modernization timelines, and cross-border pipeline negotiations that will determine product arbitrage flows between Maghreb and Nile Basin markets.
Market Dynamics
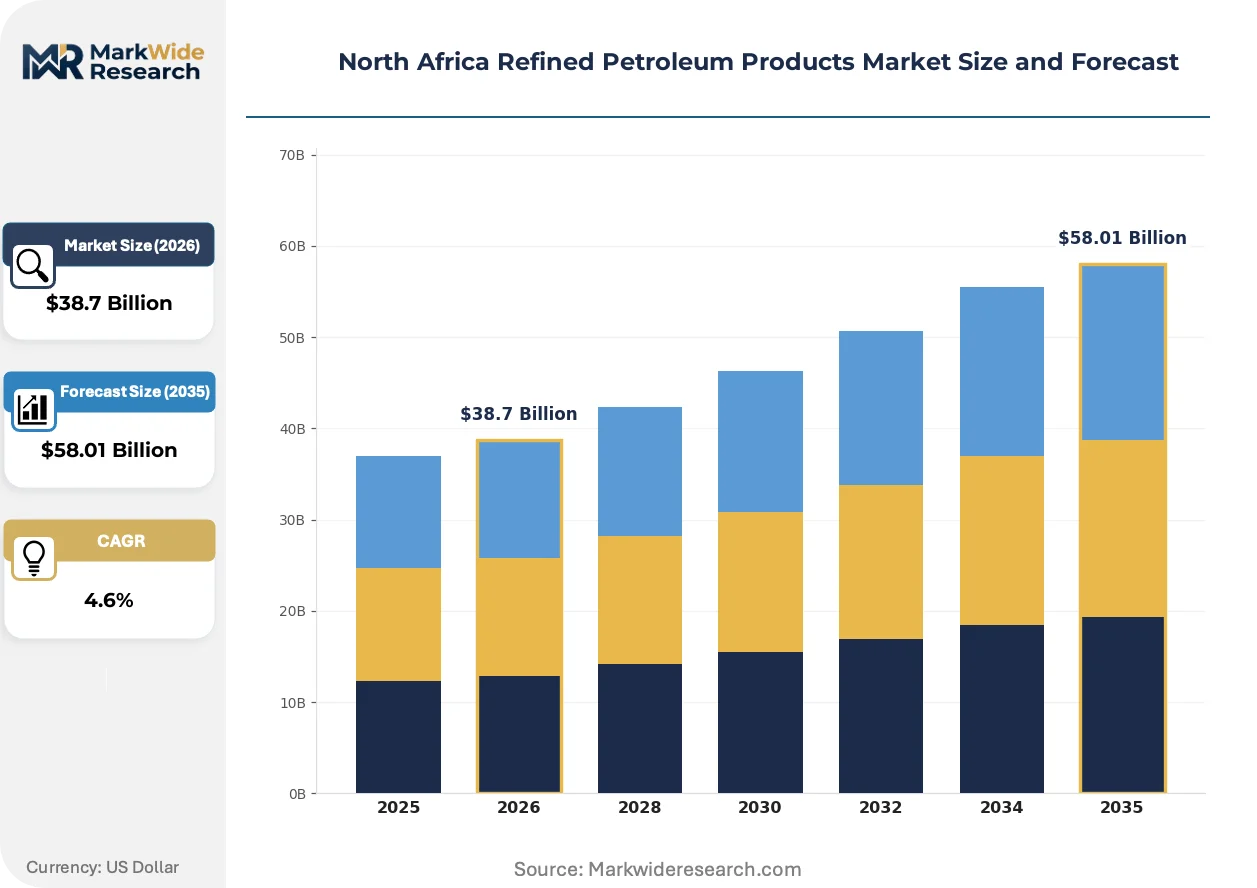
Algeria's domestic supply obligations and Egypt's fuel subsidy reforms are restructuring refined product flows across North Africa, concentrating purchasing power among state-backed industrial buyers while marginalizing smaller distributors dependent on arbitrage margins.
Growth Catalysts
- Jet fuel infrastructure:Capacity additions at Cairo International Airport and Casablanca Mohammed V International Airport are expanding aviation fuel offtake. These hub expansions anchor demand growth for kerosene-grade products.
- Morocco's blending mandates:The country's energy transition agency enforces rising biofuel content requirements in gasoline and diesel pools. Refiners must reconfigure hydrotreating units to accommodate renewable feedstock integration.
- Egypt's petrochemical corridor:Cement and fertilizer producers in the Nile Delta sustain premium-priced low-sulfur diesel procurement. Industrial heat applications command consistent volume despite transport sector volatility.
Market Restraints
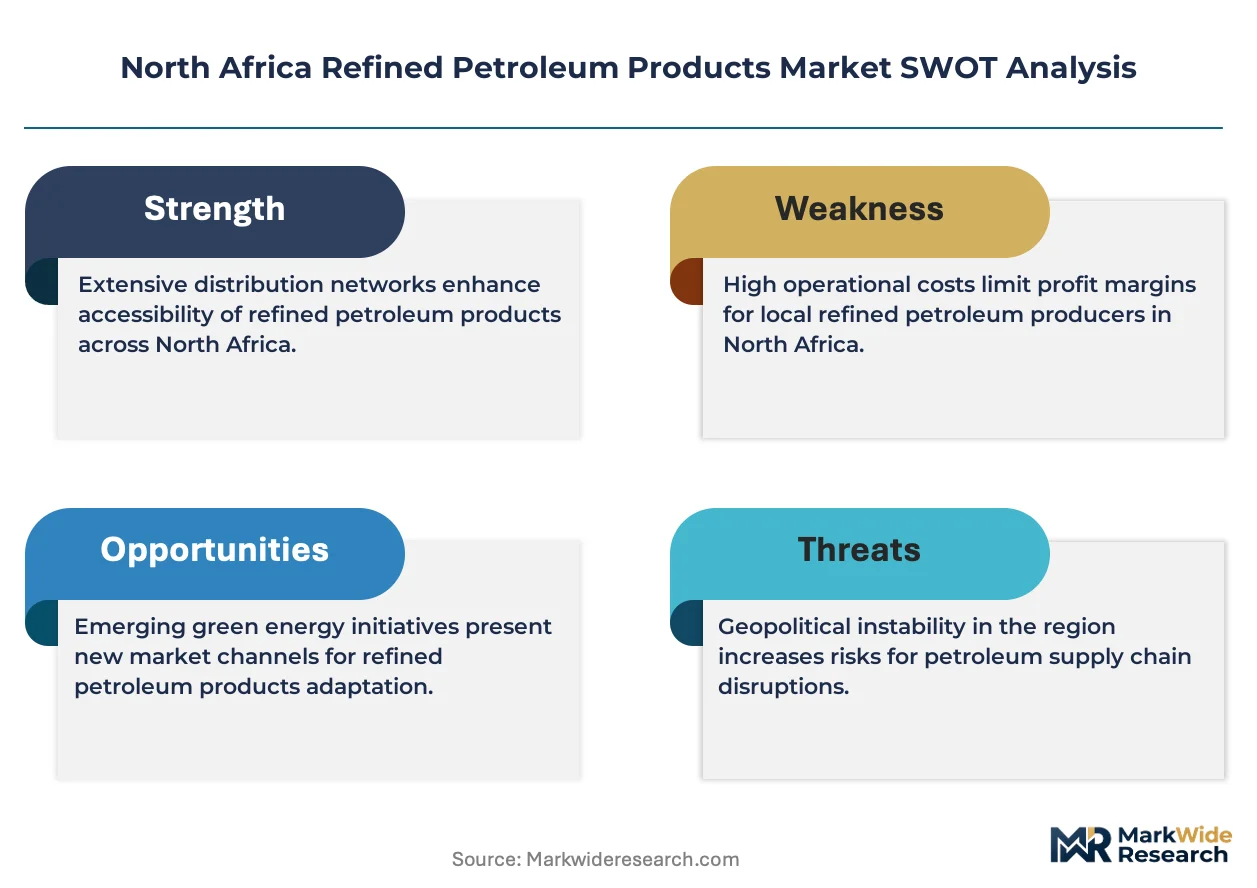
- Crude supply concentration:Sonatrach SPA's captive crude production limits third-party refiner feedstock access in Algeria. Independent marketers remain dependent on Sonatrach's product release schedules and pricing.
- Subsidy phase-out friction:Egypt's petroleum ministry coordinates gradual fuel price liberalization through Egyptian General Petroleum Corporation. Social stability concerns compress reform timelines and create policy unpredictability.
- Grid reliability gaps:Backup diesel generator dependence in grid-stressed areas inflates operating costs for industrial buyers. Fuel quality requirements for emergency power systems add procurement complexity.
Strategic Opportunities
- Tunisia's underdeveloped retail network:Coastal storage terminal expansion offers entry points for marketers seeking Maghreb distribution presence. Infrastructure gaps in interior regions present white-space capture potential.
- Cross-border pipeline negotiations:Product arbitrage flows between Maghreb and Nile Basin markets hinge on transit agreements. Early positioning in corridor development secures offtake commitments.
- Low-sulfur marine fuel transition:International Maritime Organization bunker specifications are redirecting regional bunker supply chains. Refiners with hydrotreating capability can capture port fueling demand at Mediterranean hubs.
Industry Challenges
- Refinery modernization timelines:Atmospheric and vacuum distillation unit upgrades require extended shutdown windows. Egyptian General Petroleum Corporation coordinates import licensing to cover supply gaps during maintenance cycles.
- Product quality certification:Sulfur content, octane rating, and cetane index testing protocols vary across national regulators. Multi-jurisdiction compliance adds laboratory capacity requirements and documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North Africa Refined Petroleum Products Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Jet Fuel, Kerosene Application: Transportation, Industrial, Residential Heating, Power Generation Distribution Channel: Direct Sales, Retail Outlets, Wholesale Distributors, Online Sales End User: Automotive, Aviation, Manufacturing, Energy Sector |
| Companies Covered | Sonatrach SPA, Qalaa Holdings SAE, TotalEnergies SE, Shell plc, Abu Dhabi National Energy Company PJSC, Egyptian General Petroleum Corporation, ExxonMobil Corporation, Eni S.p.A., BP plc, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North Africa Refined Petroleum Products Market Evolving Landscape
Digital fuel monitoring systems and hydrotreater optimization software are compressing operational response times across North African refineries. These capabilities separate integrated operators from distribution-dependent competitors.
Advanced process control systems incorporating real-time sulfur analyzers are bifurcating refinery performance tiers. Sonatrach SPA's Arzew and Skikda complexes deploy these platforms to minimize off-spec product volumes. Operators without comparable instrumentation face wider quality variance and penalty exposure.
Morocco's energy transition agency applies progressive biofuel blending mandates that incrementally raise renewable content thresholds. Refiners must reconfigure catalytic cracking units to process hydrotreated vegetable oil alongside fossil feedstocks. Diesel pool composition shifts most dramatically, with transport fleets adapting to B7 and B10 specifications.
Industrial buyers in Egypt's cement sector are consolidating procurement through Egyptian General Petroleum Corporation-negotiated term contracts. Spot market participation is narrowing to distressed supply situations and emergency volume needs. This concentration compresses marketer margins while securing volume predictability for integrated upstream-downstream operators.
North Africa Refined Petroleum Products Market Segmentation
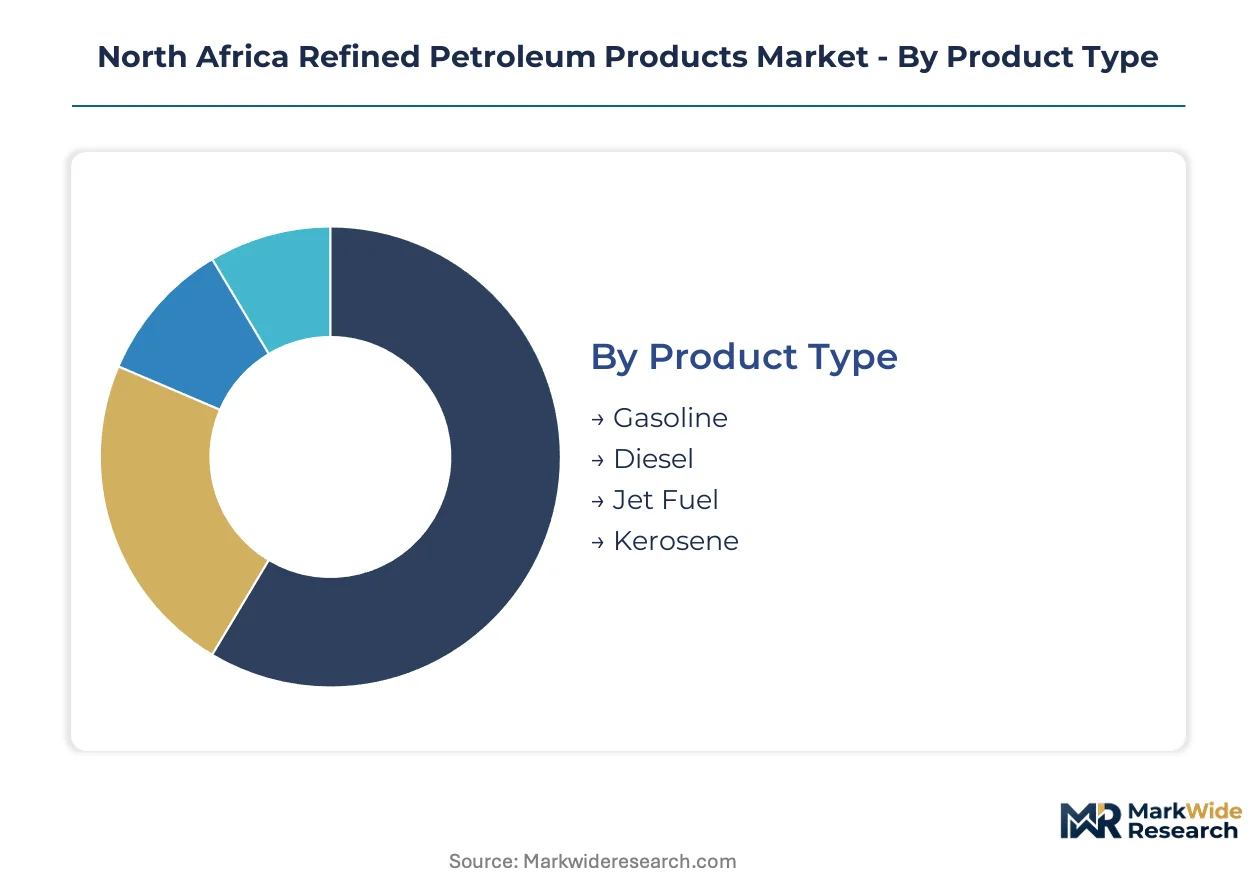
Refined petroleum product flows across North Africa fragment along sulfur specifications, end-use combustion requirements, and state-controlled distribution hierarchies. Segment boundaries determine margin capture for integrated refiners versus independent marketers.
Product Type:
Middle distillates command premium pricing over light ends due to transport sector dependency and hydrotreating intensity requirements.
- Diesel:A middle distillate with specified cetane index and sulfur content below 10 ppm for low-sulfur grades. Egypt's cement producers in the Nile Delta and Morocco's freight corridors sustain premium-priced offtake for backup power and heavy-duty transport. Diesel holds installed capacity.
- Jet Fuel:Kerosene-grade product meeting aviation turbine fuel specifications for flash point and freezing point. Capacity additions at Cairo International Airport and Casablanca Mohammed V International Airport anchor demand expansion. Jet fuel is rotating up the share rankings.
- Gasoline:Light distillate blended to octane ratings of 95 RON for premium grades and 90 RON for regular pools. Morocco's biofuel blending mandates progressively raise ethanol content in gasoline specifications.
- Kerosene:Illuminating and heating-grade middle distillate with lower volatility than jet fuel. Residential heating demand concentrates in Algeria's interior regions during winter months.
Diesel anchors volume throughput at Algerian refineries. Jet fuel climbs fastest on aviation infrastructure expansion.
Application:
Transport sector procurement absorbs the majority of regional refinery output, though industrial term contracts offer margin stability.
- Transportation:Road, rail, and marine combustion applications across Egypt's Nile Delta corridors and Morocco's Atlantic coastal routes. Freight operators favor diesel for torque requirements and fuel economy.
- Industrial:Heat and process energy for cement kilns, fertilizer ammonia plants, and steel re-rolling mills. Egyptian General Petroleum Corporation negotiates bulk supply agreements with state-affiliated manufacturers.
- Power Generation:Backup diesel generator sets in grid-stressed areas of Tunisia and rural Egypt. Emergency power systems require low-sulfur fuel to minimize particulate emissions.
- Residential Heating:Kerosene and diesel combustion for space heating in Algeria's highland regions. Seasonal demand peaks compress storage capacity during winter procurement cycles.
Transportation maintains throughput dominance. Industrial procurement offers pricing predictability through term contracts.
Distribution Channel:
State-controlled wholesale networks capture volume, while retail margin pools fragment across branded and independent station networks.
- Wholesale Distributors:Bulk product transfers from refinery gates to industrial buyers and retail network depots. Sonatrach SPA controls Algerian wholesale flows through captive terminal infrastructure.
- Retail Outlets:Branded service stations and independent fuel retailers across Morocco's coastal highways and Egypt's urban centers. TotalEnergies SE maintains network presence in Maghreb markets.
- Direct Sales:Refinery-to-buyer contracts for power generators and state transport fleets. Egyptian General Petroleum Corporation coordinates direct supply to government entities.
- Online Sales:Digital procurement platforms for commercial fleet card management and industrial buyer tendering. Adoption remains limited by payment system infrastructure gaps.
Wholesale distributors retain volume concentration. Retail outlets fragment across competitive branded networks.
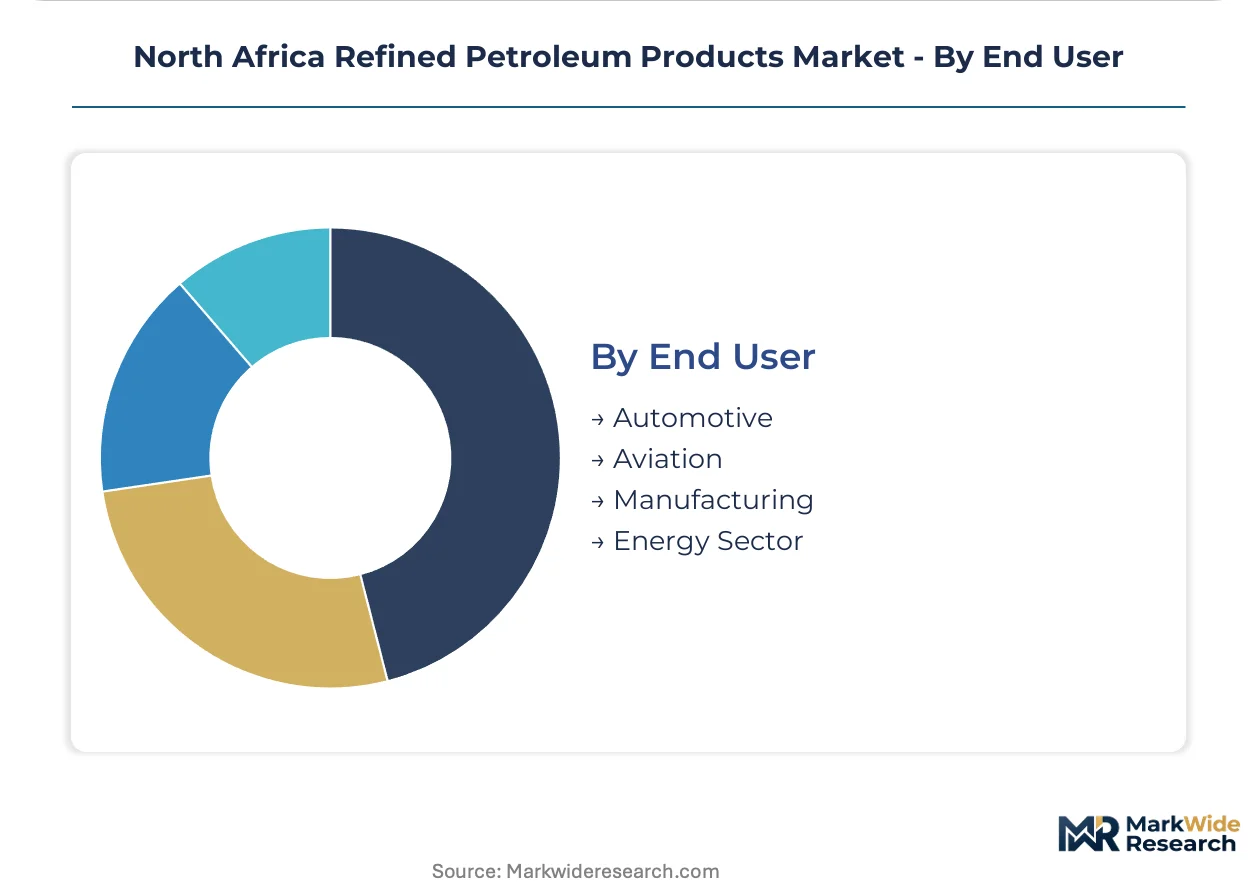
End User:
Aviation and automotive sectors drive specification intensity, while manufacturing procurement emphasizes volume scale over quality tiering.
- Aviation:International and domestic carriers operating from Cairo, Casablanca, and Tunis hubs. Jet fuel offtake expands with passenger traffic recovery and route network additions.
- Automotive:Private vehicle owners and commercial fleet operators across Morocco's urban centers and Egypt's Delta cities. Gasoline demand tracks vehicle registration growth and fuel subsidy adjustments.
- Manufacturing:Cement, fertilizer, and steel producers requiring consistent diesel supply for process heat and captive power. Egyptian General Petroleum Corporation term contracts cover majority procurement.
- Energy Sector:Grid operators and independent power producers utilizing diesel for peaking capacity and grid stabilization. Backup generator specifications mandate low-sulfur product to comply with emissions protocols.
Aviation commands specification premiums. Manufacturing consolidates procurement through state-negotiated supply agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across North African markets. Egypt's industrial buyers absorb price shocks through Egyptian General Petroleum Corporation-negotiated term contracts. Morocco's transport operators face immediate pass-through from subsidy adjustments. Algeria's state-backed distribution networks buffer consumer exposure.
Egypt
Cement and fertilizer producers in the Nile Delta sustain premium-priced low-sulfur diesel procurement through Egyptian General Petroleum Corporation bulk agreements. The petroleum ministry coordinates gradual fuel price liberalization, compressing reform timelines due to social stability concerns. Cairo's petrochemical corridor anchors industrial heat demand.
Algeria
Sonatrach SPA's captive crude production limits third-party refiner feedstock access across domestic markets. The national hydrocarbon regulator enforces domestic supply obligations on refiners, redirecting product flows toward state-controlled distribution. Arzew and Skikda refining complexes deploy advanced process control systems.
Morocco
Freight corridors along Atlantic coastal routes drive diesel consumption for heavy-duty transport applications. The energy transition agency applies progressive biofuel blending mandates, raising renewable content thresholds in gasoline and diesel pools. Casablanca Mohammed V International Airport capacity additions expand aviation fuel offtake.
Tunisia
Backup diesel generator dependence in grid-stressed areas inflates operating costs for industrial buyers. Coastal storage terminal expansion offers entry points for marketers seeking Maghreb distribution presence. Interior regions present white-space capture potential for retail network development.
North Africa Refined Petroleum Products Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in North Africa's refined petroleum products market. Sonatrach SPA and Egyptian General Petroleum Corporation control captive crude supplies and refinery networks, dominating domestic wholesale flows. Independent marketers compete through coastal storage terminals and retail footprint expansion. Strategic differentiation concentrates on refinery modernization timelines and cross-border pipeline positioning.
Within the integrated national champion tier, Sonatrach SPA exemplifies upstream-downstream consolidation through its Algerian refinery network and distribution infrastructure. Egyptian General Petroleum Corporation anchors government-backed supply contracts with state-affiliated power generators and transport fleets. Among international marketers, TotalEnergies SE occupies a position spanning Maghreb retail networks and coastal storage terminals.
| Leading Market Players |
|---|
| Sonatrach SPA |
| Qalaa Holdings SAE |
| TotalEnergies SE |
| Shell plc |
| Abu Dhabi National Energy Company PJSC |
| Egyptian General Petroleum Corporation |
| ExxonMobil Corporation |
| Eni S.p.A. |
| BP plc |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Egyptian General Petroleum Corporation and Nile Delta cement producers lock in diesel supply access while capping price volatility for industrial heat applications. These arrangements concentrate purchasing power among state-backed buyers and marginalize spot market participation.
Pricing Analysis
After-sales service revenue from hydrotreater maintenance contracts and sulfur analyzer calibration services drives lifetime value for refinery equipment suppliers. Three-tier pricing structure across premium low-sulfur diesel, standard automotive fuels, and economy-grade heating kerosene separates quality grades. Cost compression in the standard tier is intensifying because Morocco's biofuel blending mandates force feedstock reconfiguration. State transport fleets show lowest price sensitivity due to subsidy pass-through mechanisms, while independent retailers face acute margin pressure.
Supply Chain Analysis
Strategic stockpiling preferences dominate Algerian refinery operations due to Sonatrach SPA's domestic supply obligations and seasonal demand swings. Feedstock draws from Algeria's captive crude fields, Egypt's import-dependent coastal terminals, and Morocco's Atlantic storage hubs. Sulfur content testing reagents and hydrotreating catalysts rest on specialized chemical supply chains. Single-source vulnerability concentrates in Sonatrach's refinery gate control. Distribution runs through state-controlled wholesale depots to retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North Africa refined petroleum products market sits in a cyclical recovery phase as aviation capacity additions at Cairo and Casablanca airports rebuild jet fuel offtake from pandemic lows.
For Market Incumbents: Consolidate wholesale terminal control through Egyptian General Petroleum Corporation-negotiated direct sales contracts with state power generators. Expand hydrotreating capacity to capture low-sulfur marine fuel demand at Mediterranean bunkering hubs. The threat of subsidy phase-out friction compresses margin predictability. Vertical integration into catalytic cracking unit upgrades offers the strongest defensive lever.
For New Entrants and Emerging Players: Lead with coastal storage terminal expansion in Tunisia's underdeveloped interior regions where retail network gaps persist. Target white-space capture in Maghreb distribution corridors ahead of cross-border pipeline negotiations. Digital fuel monitoring systems provide the clearest differentiation angle against established wholesale distributors.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated upstream-downstream operators with captive crude access and refinery modernization timelines already committed. Long-term viability over a multi-year horizon hinges on positioning before biofuel mandate thresholds tighten. Watch Morocco's energy transition agency blending schedule acceleration as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Refinery Hydrotreater Upgrade | Enables Sonatrach SPA to meet International Maritime Organization low-sulfur bunker specifications at Arzew and Skikda. |
| Coastal Storage Terminal Expansion | TotalEnergies SE secures Maghreb distribution presence ahead of product arbitrage corridor development. |
| Biofuel Blending Capacity Addition | Morocco's energy transition agency mandates force catalytic cracking unit reconfiguration for hydrotreated vegetable oil processing. |
| Direct Supply Contract Negotiation | Egyptian General Petroleum Corporation locks in term volumes with Nile Delta cement and fertilizer producers. |
| Cross-Border Pipeline Positioning | Early transit agreement participation secures offtake commitments between Maghreb and Nile Basin markets. |
Research Methodology
A standing panel of refinery operations directors, fuel procurement managers at cement and fertilizer producers, coastal terminal logistics coordinators, and national hydrocarbon regulator officials provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against customs trade data, national petroleum ministry import licensing records, refinery maintenance schedule disclosures, and International Maritime Organization bunker specification filings. Bottom-up volume modeling triangulated against top-down macroeconomic demand projections.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. The analytical framework modeled segmentation dimensions spanning sulfur specification tiers, end-use combustion requirements, distribution channel hierarchies, and national regulatory clusters. CAGRs were derived from trend extrapolation anchored in infrastructure capacity additions and policy implementation timelines. Forecast inputs incorporated aviation passenger traffic recovery trajectories and biofuel blending mandate phase-in schedules.
Underlying assumptions cover subsidy reform continuity, refinery modernization completion, and cross-border pipeline negotiation progress, with deviation risk concentrated in social stability constraints on Egyptian price liberalization. Forecasts reflect these documented conditions. Revision becomes warranted when Morocco's renewable content thresholds accelerate beyond current schedules or Algerian domestic supply obligations shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
East Africa Refined Petroleum Products Market
Petroleum Products
Gasoline-Naphtha-Crude-MTBE Market
Petroleum Products
Very Low Sulphur Fuel Oil (VLSFO) Market
Petroleum Products
Spindle Oil Market
Petroleum Products
Africa Refined Petroleum Products Market
Petroleum Products
Pyrolysis Gasoline Market
Petroleum Products
Nigeria Petrol Station Market
Petroleum Products
Oil Refinery Market
Petroleum Products
Liquefied Petroleum Gas Market
Petroleum Products
Marine Minerals Market
Petroleum Products
Oil Shale Market
Petroleum Products
Global Petroleum Pitch Market
Petroleum Products
North America Natural Gas Liquids Market
Petroleum Products
Automotive Oil Strainer Market
Petroleum Products
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market
Petroleum Products
Pyrolysis Oil Market