
 Canada LNG Market | 2026-2036
Canada LNG Market Size, Share, and Industry Trends Forecast 2026-2036
Canada LNG Market Outlook
Ultra-low carbon intensity LNG certification is rotating toward the center of Canadian export contracts. Shell leverages its integrated upstream-to-liquefaction footprint to secure premium offtake agreements. PETRONAS anchors the LNG Canada venture with disciplined capital allocation across the Kitimat terminal complex. ExxonMobil Corporation differentiates through proprietary dual-mixed refrigerant technology that trims liquefaction energy consumption.
Liquefied natural gas is natural gas cooled to approximately minus 162 degrees Celsius, reducing volume by a factor of six hundred for efficient marine transport. The process strips heavier hydrocarbons and removes water, carbon dioxide, and sulfur compounds to prevent freezing and corrosion in cryogenic systems. Within the technology segment, liquefaction capacity captures the dominant share of capital deployment, while regasification infrastructure at receiving terminals commands stable operational revenue streams. The application dimension shows industrial use leading current offtake volumes, though transportation fuel switching toward LNG-powered marine and heavy trucking fleets posts the fastest trajectory. Service type revenue pools concentrate in terminal operations, where long-term tolling agreements generate predictable cash flows.
Health Canada and Environment and Climate Change Canada enforce methane emission caps under the Pan-Canadian Framework, while the Canadian Energy Regulator governs export licensing and facility approvals. British Columbia's CleanBC plan layers provincial carbon intensity benchmarks atop federal requirements, compelling producers to adopt electrified compression and carbon capture retrofits. The Canadian Standards Association certifies cryogenic equipment and pipeline materials for arctic and coastal operating conditions. Stakeholders must weigh feedstock cost advantages against lengthening regulatory approval timelines for greenfield terminal expansions.
Market Dynamics
Federal methane emission caps under the Pan-Canadian Framework are compressing extraction economics while electrified compression retrofits absorb capital that would otherwise flow to liquefaction expansion. This regulatory tightening is bifurcating producer strategies between carbon capture investment and terminal project delays.
Growth Catalysts
- CleanBC Carbon Intensity Benchmarks:British Columbia's layered provincial standards compel producers to adopt electrified compression, creating technology upgrade cycles that favor integrated upstream-to-terminal operators with captive hydroelectric access.
- Asian Power Utility Diversification:Japanese and South Korean buyers are rotating contract volumes away from pipeline-dependent suppliers toward marine-delivered Canadian cargoes with certified low-carbon intensity.
- Kitimat-Prince Rupert Infrastructure Clustering:Coastal British Columbia liquefaction corridors concentrate engineering talent, modular fabrication yards, and deepwater marine terminals within tight geographic proximity.
Market Restraints
- Canadian Energy Regulator Licensing Timelines:Export facility approvals now stretch across multiple federal review cycles, delaying final investment decisions for greenfield terminal expansions at Kitimat.
- Steel and Cryogenic Equipment Cost Volatility:Nickel-alloy heat exchangers and arctic-grade pipeline materials face price swings tied to mining supply constraints and energy-intensive smelting.
- Electrification Infrastructure Gaps:Remote coastal sites lack transmission capacity to support full electrification of compression trains, forcing continued reliance on gas-turbine drivers.
Strategic Opportunities
- Carbon Capture Retrofit Incentives:Federal investment tax credits for CCUS equipment create economic justification for post-combustion capture at existing gas processing facilities serving liquefaction plants.
- LNG Marine Bunkering:Vancouver and Prince Rupert port authorities are developing liquefaction-to-bunker supply chains to capture fuel-switching demand from container and cruise vessels.
- Indigenous Equity Partnerships:Structured benefit agreements with First Nations along pipeline routes and terminal sites unlock access to traditional territory while distributing project returns.
Industry Challenges
- Cryogenic Welding Certification Backlogs:Canadian Standards Association qualification timelines for 9% nickel steel welders lag project staffing needs, compressing construction schedules.
- Modular Fabrication Yard Capacity:Limited domestic heavy-lift assembly sites force dependence on Asian module suppliers, exposing schedules to marine transport bottlenecks through the Panama Canal.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada LNG Market |
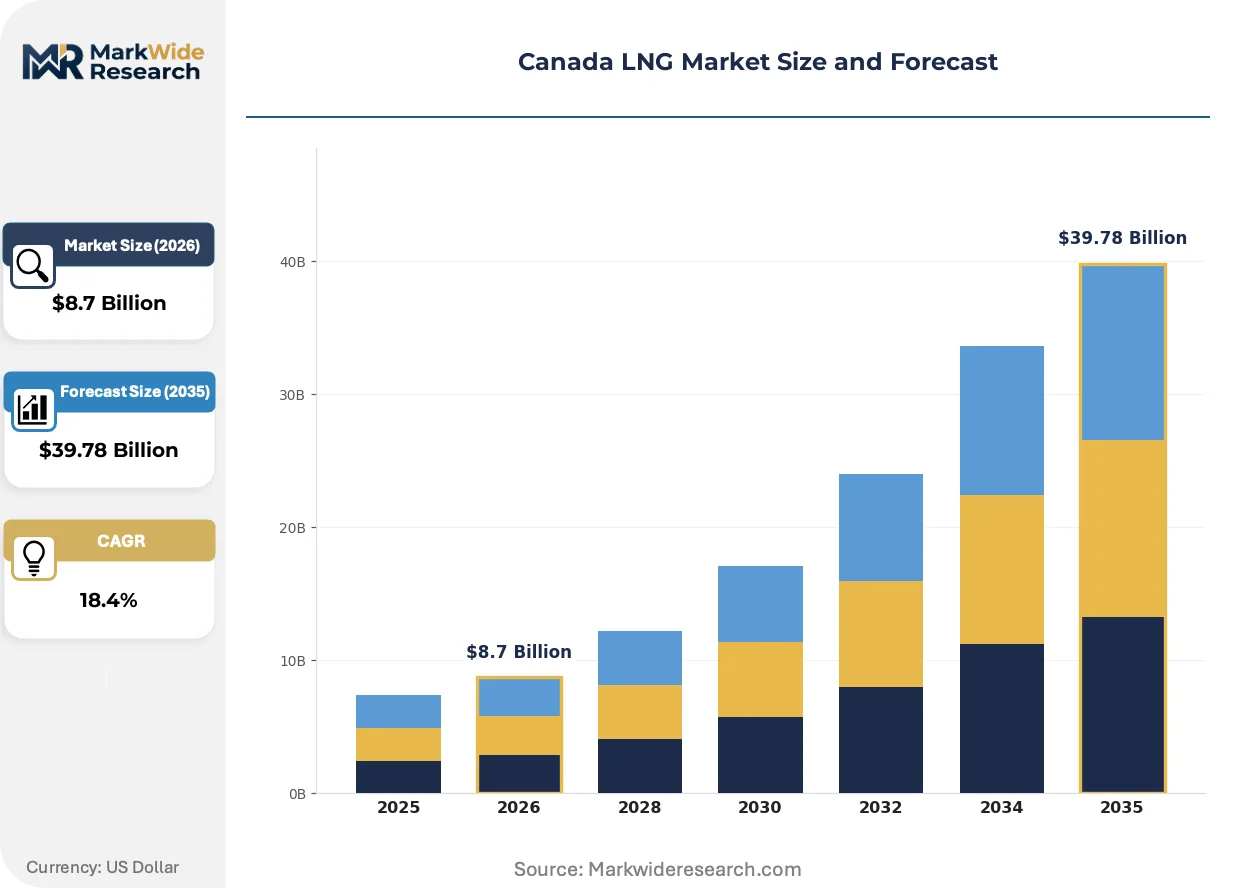
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Power Generation, Transportation, Industrial Use, Residential Heating Technology: Liquefaction, Regasification, Compression, Storage Service Type: Terminal Operations, Transportation Services, Consulting, Maintenance End User: Utilities, Manufacturers, Exporters, Government Agencies |
| Companies Covered | Shell, PETRONAS, PetroChina, Mitsubishi Corporation, Korea Gas Corporation (KOGAS), Chevron Corporation, ExxonMobil Corporation, TotalEnergies SE, TechnipFMC PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada LNG Market Strategic Shifts
Dual-mixed refrigerant liquefaction cycles and electrified compression trains are compressing facility carbon intensity while expanding the addressable buyer pool to climate-constrained Asian utilities. These technology shifts are redrawing competitive positioning around certification rather than volume.
Dual-mixed refrigerant technology is bifurcating the liquefaction technology landscape. This process uses two separate refrigerant circuits to optimize thermodynamic efficiency across variable ambient temperatures. Japanese and South Korean power utilities are prioritizing offtake from terminals deploying this configuration in their procurement specifications. The technology is bifurcating contract premiums between certified low-carbon cargoes and conventional supply.
Health Canada and Environment and Climate Change Canada are tightening methane venting limits under the Pan-Canadian Framework with measurement, reporting, and verification requirements taking effect across upstream facilities. Producers must deploy continuous emissions monitoring systems at compressor stations and well pads, absorbing capital that competes with liquefaction expansion budgets. British Columbia operators face the strictest compliance costs as provincial benchmarks layer atop federal floors.
Asian utility buyers are consolidating procurement through carbon-intensity-weighted tender processes rather than conventional heat-value pricing. Long-term offtake agreements now specify maximum lifecycle emissions thresholds that disqualify conventional liquefaction configurations. Japanese trading houses are leading this contractual evolution, with contract structures spreading to South Korean and Taiwanese power utilities.
Canada LNG Market Segmentation
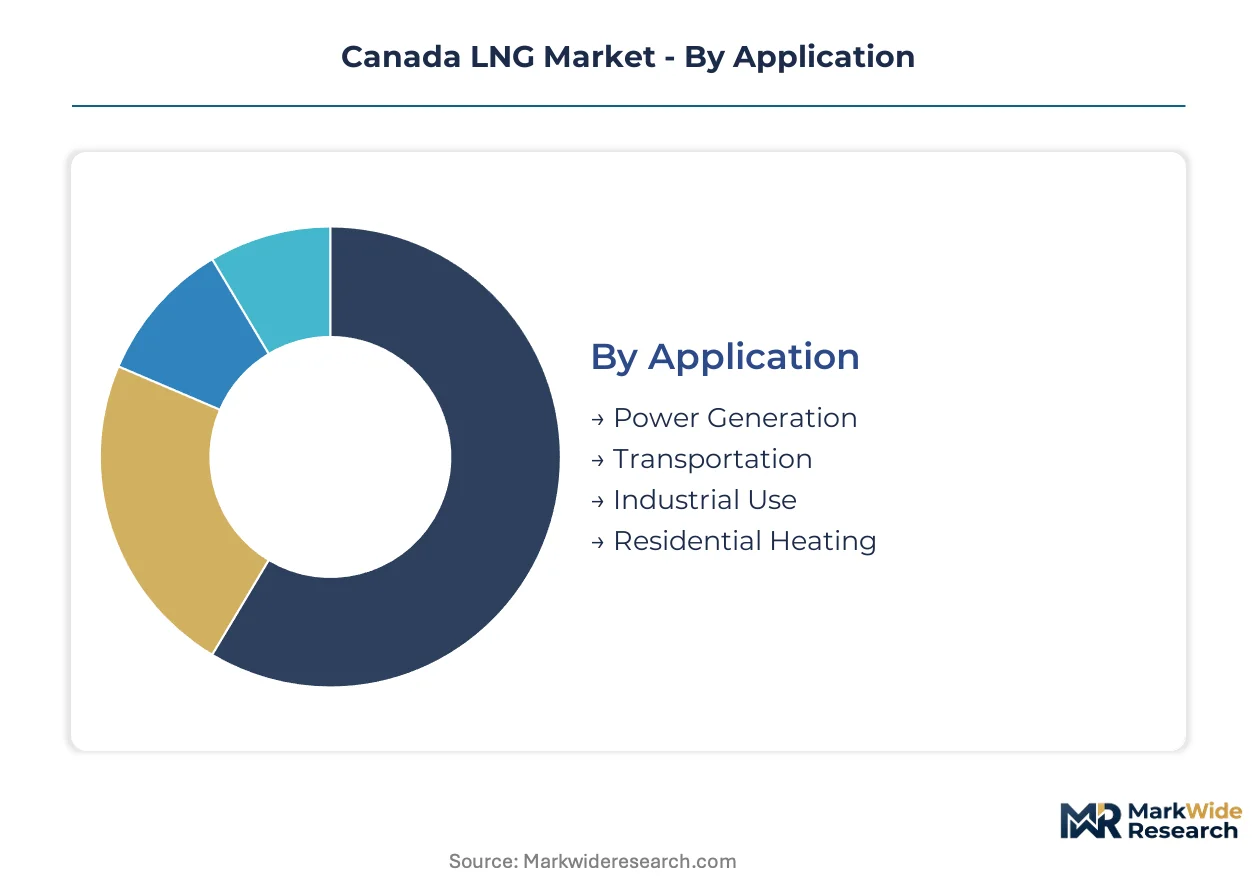
Segmentation in the Canadian LNG market reveals how capital flows bifurcate between domestic consumption corridors and export-oriented liquefaction infrastructure. Understanding these divisions clarifies where regulatory pressure concentrates and which customer categories command pricing premiums.
Application:
Export-led segments dominate revenue concentration while domestic applications absorb regulatory compliance costs from British Columbia's layered carbon intensity benchmarks.
- Power Generation:Cryogenic LNG cargoes serve baseload electricity plants across Japanese and South Korean utility portfolios. Asian power utilities rotate procurement toward certified low-carbon marine deliveries as pipeline diversification accelerates.
- Transportation:Marine bunkering and heavy trucking fuel switching post the steepest demand trajectory. Vancouver and Prince Rupert port authorities are building liquefaction-to-bunker supply chains to capture container and cruise vessel conversions.
- Industrial Use:Petrochemical feedstock and process heat applications anchor current offtake volumes at receiving terminals.
- Residential Heating:Remote coastal communities and northern settlements rely on small-scale LNG delivery where pipeline extension proves uneconomical.
Industrial use commands the established base. The steepest expansion runs through transportation.
Technology:
Capital deployment stratifies sharply between front-end liquefaction capacity and back-end operational infrastructure, with electrification retrofits absorbing funds that would otherwise expand nameplate capacity.
- Liquefaction:Dual-mixed refrigerant cycles optimize thermodynamic efficiency across variable ambient temperatures at Kitimat and Prince Rupert terminals. Shell and ExxonMobil deploy proprietary configurations that trim energy consumption and qualify for carbon-intensity-weighted contract premiums.
- Regasification:Receiving terminal infrastructure generates stable operational revenue through long-term tolling agreements with Asian utility buyers.
- Compression:Electrified compression trains are replacing gas-turbine drivers at upstream facilities to meet Pan-Canadian Framework methane caps.
- Storage:Cryogenic tankage and insulated containment systems buffer supply fluctuations across seasonal demand cycles.
Liquefaction absorbs the dominant capital share. Regasification offers the most predictable cash flow profile.
Service Type:
Revenue predictability varies inversely with operational complexity, with terminal operations locking in decade-long contracts while consulting faces procurement compression.
- Terminal Operations:Long-term tolling agreements at LNG Canada and prospective Kitimat expansions generate contracted cash flows insulated from spot price volatility.
- Transportation Services:Specialized cryogenic marine logistics and rail delivery networks connect interior gas processing to coastal liquefaction corridors.
- Consulting:Regulatory navigation and Indigenous partnership structuring support project development timelines.
- Maintenance:Cryogenic equipment servicing and continuous emissions monitoring system upkeep absorb recurring operational expenditure.
Terminal operations anchor revenue stability. Transportation services are gaining share fastest as marine bunkering corridors mature.
End User:
Procurement authority concentrates with export-facing entities while government agencies increasingly shape project viability through licensing and carbon pricing enforcement.
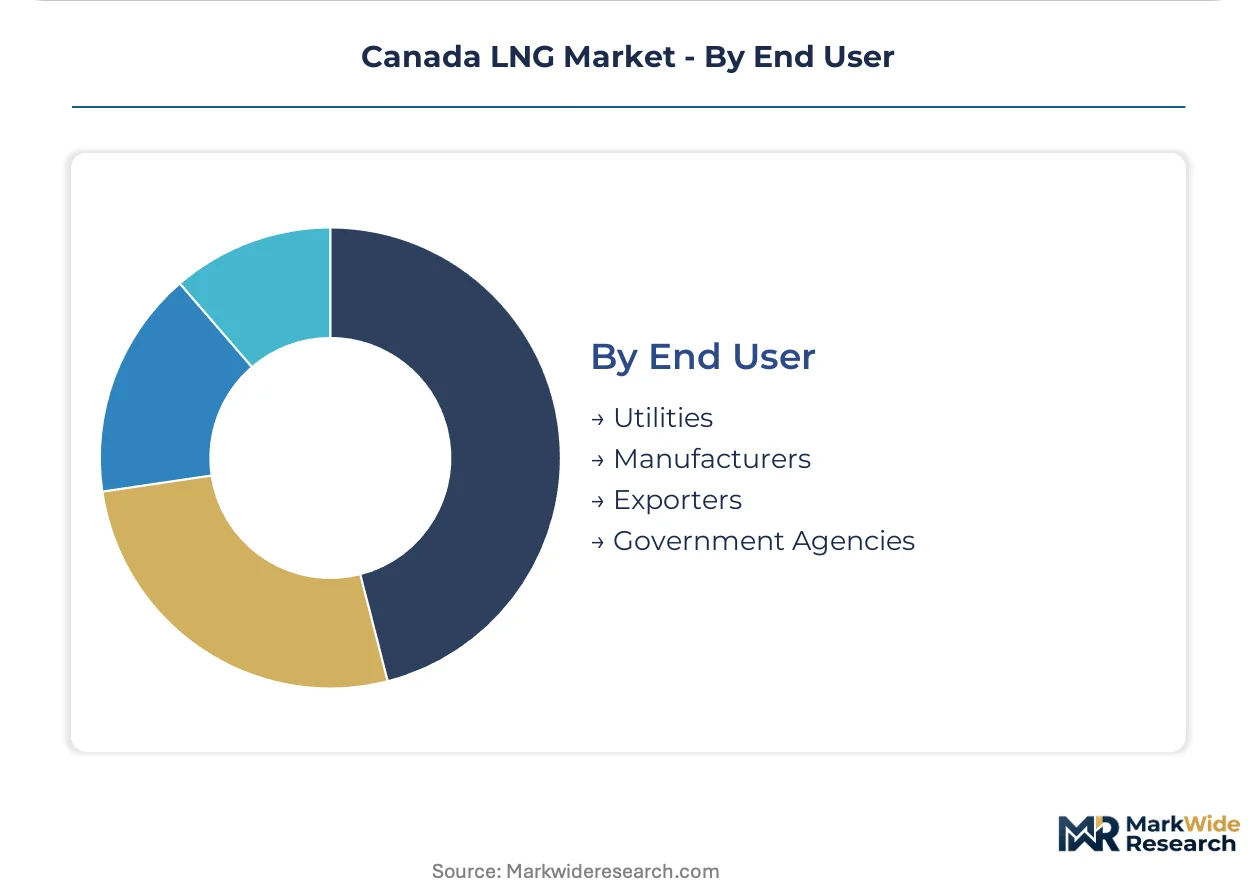
- Utilities:Japanese and South Korean power companies specify maximum lifecycle emissions thresholds in long-term offtake agreements, disqualifying conventional liquefaction configurations.
- Manufacturers:Petrochemical and fertilizer producers source LNG for process heat and hydrogen feedstock in Alberta and British Columbia industrial corridors.
- Exporters:Integrated upstream-to-terminal operators capture premium pricing through ultra-low carbon intensity certification.
- Government Agencies:Canadian Energy Regulator export licensing and Environment and Climate Change Canada methane enforcement determine project timelines and compliance burdens.
Utilities dominate contract volume. Government agencies are expanding their influence fastest through regulatory layering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kitimat and Prince Rupert anchor liquefaction capacity along British Columbia's Pacific coastline, while upstream feedstock extraction clusters in Alberta's Montney and Duvernay formations. Provincial carbon intensity benchmarks and federal methane caps are redrawing competitive positioning across these corridors.
British Columbia
Asian utility offtake contracts specify maximum lifecycle emissions thresholds that favor terminals with electrified compression and hydroelectric power access. The province's CleanBC plan layers carbon intensity benchmarks atop federal Pan-Canadian Framework requirements, compelling retrofits at gas processing facilities. Kitimat hosts the LNG Canada venture with Shell and PETRONAS equity stakes, while Prince Rupert offers deepwater marine access for Panamax carriers.
Alberta
Montney formation producers supply feedstock to coastal liquefaction through the Coastal GasLink pipeline corridor, with carbon capture retrofits absorbing capital that would otherwise expand upstream capacity. Environment and Climate Change Canada methane venting limits force continuous emissions monitoring deployment at compressor stations. Calgary anchors corporate headquarters for integrated operators managing upstream-to-terminal coordination.
Ontario
Provincial demand for LNG marine bunkering is emerging through Great Lakes-St. Lawrence Seaway corridor development, though no liquefaction capacity exists domestically. The Canadian Energy Regulator governs interprovincial pipeline approvals connecting western feedstock to eastern markets. Toronto concentrates financial services structuring project finance for western terminal expansions.
Quebec
Gaz Métro (Énergir) operates small-scale LNG distribution for remote industrial and residential heating applications where pipeline extension proves uneconomical. The province's hydroelectric surplus creates competitive tension with gas-fired alternatives in power generation. Montreal serves as the eastern logistics hub for marine-delivered cargoes transshipped from Atlantic terminals.
Atlantic Canada
Repsol's Saint John LNG regasification terminal in New Brunswick offers the sole large-scale import capacity on Canada's eastern seaboard, with expansion studies evaluating liquefaction addition. Newfoundland and Labrador offshore gas production supplies regional demand through the Come By Chance refinery corridor. Halifax port authority explores LNG marine bunkering infrastructure for container vessel conversions.
Canada LNG Market Competitive Environment
Concentration sits with integrated upstream-to-terminal operators holding captive hydroelectric access and long-term Asian utility offtake contracts. The market structure bifurcates between global supermajors with proprietary liquefaction technology and state-backed Asian buyers securing supply diversification. Two strategic archetypes dominate: technology licensors optimizing thermodynamic efficiency and portfolio aggregators assembling equity stakes across terminal ventures. Competitive moves center on carbon intensity certification premiums and Indigenous partnership structures unlocking pipeline route access.
Within the integrated supermajor tier, Shell and ExxonMobil Corporation exemplify technology-led positioning through proprietary dual-mixed refrigerant configurations and upstream-to-liquefaction footprint control. PETRONAS anchors the state-backed buyer archetype through disciplined capital allocation across the Kitimat terminal complex. These three entities represent distinct competitive vectors: technology differentiation, captive resource access, and offtake security through equity participation.
| Leading Market Players |
|---|
| Shell |
| PETRONAS |
| PetroChina |
| Mitsubishi Corporation |
| Korea Gas Corporation (KOGAS) |
| Chevron Corporation |
| ExxonMobil Corporation |
| TotalEnergies SE |
| TechnipFMC PLC |
| Others |
Value Chain & Pricing Dynamics
British Columbia's CleanBC carbon intensity benchmarks gate both terminal qualification and contract price premiums simultaneously. Producers without electrified compression access face exclusion from Asian utility procurement tiers while certified low-carbon cargoes command measurable contract uplifts.
Pricing Analysis
The Pan-Canadian Framework methane caps dictate the pricing tier structure across Canadian LNG export contracts. Long-term offtake agreements with Japanese and South Korean utilities separate ultra-low carbon certified cargoes from conventional supply through carbon-intensity-weighted tender processes. Price differentiation hinges on lifecycle emissions certification and captive hydroelectric power access at liquefaction terminals. Cost compression in standard-tier supply is intensifying because electrification retrofits absorb capital that would otherwise expand nameplate capacity. Asian power utilities demonstrate lowest price sensitivity, prioritizing emissions thresholds over unit cost, while industrial offtakers in Alberta and British Columbia remain most cost-conscious.
Supply Chain Analysis
Panama Canal transit bottlenecks expose Canadian LNG projects to module delivery delays from Asian fabrication yards. The supply chain draws from South Korea for nickel-alloy heat exchangers, Japan for cryogenic control systems, and China for modular structural components. Raw material dependencies center on 9% nickel steel plate, aluminum heat exchanger tubing, and arctic-grade pipeline coatings. Single-source vulnerability concentrates in qualified cryogenic welder certification through the Canadian Standards Association. Distribution runs through deepwater marine terminals at Kitimat and Prince Rupert, with Coastal GasLink pipeline feedstock from Alberta's Montney formation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat story where Canadian Energy Regulator licensing entrenchment creates decade-long barriers to terminal replication. Switching costs for Asian utilities are rising as carbon-intensity-weighted procurement locks in qualified supplier relationships.
For Market Incumbents: Secure Indigenous equity partnership structures along pipeline routes to defend route access against emerging terminal proposals. Extend backward integration into Montney feedstock production to capture margin compression from methane compliance costs. Electrified compression retrofits at upstream facilities represent the critical defensive lever against carbon intensity disqualification.
For New Entrants and Emerging Players: Lead with LNG marine bunkering infrastructure at Vancouver and Prince Rupert as the most penetrable white-space segment. Target container vessel fuel-switching demand through port authority partnerships rather than competing directly for Asian utility offtake. Carbon capture as a service at existing gas processing facilities offers a capital-light entry angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap Montney producers facing methane compliance capital demands but lacking liquefaction tolling agreements. Long-term viability in this market rests on regulatory licensing depth and hydroelectric power access rather than pure resource scale. The signal to watch is Canadian Energy Regulator export license issuance velocity as inflection indicator for greenfield terminal economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Compression Retrofit | CleanBC benchmarks compel gas-turbine replacement to maintain Asian utility contract eligibility. |
| Indigenous Equity Partnership | Structured benefit agreements with First Nations unlock Coastal GasLink corridor expansion access. |
| Carbon Capture Retrofit | Federal CCUS tax credits justify post-combustion capture at Montney gas processing facilities. |
| Marine Bunkering Infrastructure | Vancouver port authority liquefaction-to-bunker chains capture container vessel fuel-switching demand. |
| Dual-Mixed Refrigerant Licensing | Proprietary thermodynamic configurations from Shell and ExxonMobil qualify for carbon-intensity contract premiums. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility procurement officers at Japanese and South Korean power companies, terminal operations directors at Kitimat and Prince Rupert facilities, Montney formation gas processing executives, and Canadian Energy Regulator licensing specialists. Secondary validation drew from Environment and Climate Change Canada methane enforcement disclosures, British Columbia Ministry of Energy regulatory filings, LNG Canada project development updates, and Asian utility tender documentation. Bottom-up capacity buildout modeling and top-down Asian demand aggregation were triangulated against contracted offtake volumes.
Across the projection horizon, the analytical framework modeled segmentation across liquefaction technology configuration, carbon intensity certification tier, service type revenue stream, and provincial regulatory jurisdiction. CAGRs were derived through capacity utilization curves and Asian import demand elasticity analysis. Forecast inputs incorporated electrification infrastructure buildout timelines and cryogenic equipment procurement lead times.
Forecasts assume regulatory continuity in the Pan-Canadian Framework and CleanBC regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as Canadian Energy Regulator licensing velocity and Asian utility carbon intensity thresholds evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Rigless Intervention Systems Sales Market
Oil & Gas
Well Intervention Service Market
Oil & Gas
Oil and Gas Data Management Market
Oil & Gas
Pipeline Integrity Market
Oil & Gas
Offshore Drilling Fluid Market
Oil & Gas
US Oil and Gas Infrastructure Market
Oil & Gas
Indonesia Oil and Gas Market
Oil & Gas
Middle-East Oilfield Services Market
Oil & Gas
Mineral Oil and Mineral Spirit Market
Oil & Gas
Oilfield Roller Chain Market
Oil & Gas
Canada Oil and Gas Market
Oil & Gas
Asia-Pacific LNG Bunkering Market
Oil & Gas
Small Scale LNG Terminal Market
Oil & Gas
United States Oil and Gas Upstream Market
Oil & Gas
Digital Oilfield Services Market
Oil & Gas
United States Natural Gas Market