
 Shale Gas Hydraulic Fracturing Market | 2026-2036
Shale Gas Hydraulic Fracturing Market Size, Share, and Industry Trends Forecast 2026-2036
Shale Gas Hydraulic Fracturing Market Analysis
The EPA's revised methane emissions standards is restructuring capital deployment across unconventional gas fields. Halliburton leverages its integrated well services portfolio to sustain pad drilling economics. Baker Hughes anchors its position through digital fracturing systems that optimize stage-by-stage proppant placement. Patterson-UTI Energy competes via its super-spec rig fleet purpose-built for multi-well pad development.
Shale gas hydraulic fracturing involves the high-pressure injection of water, proppant, and chemical additives into low-permeability shale formations to create conductive fracture networks, typically operating at surface pressures exceeding 10,000 psi and pump rates above 100 barrels per minute to liberate trapped hydrocarbons. The process enables commercial production from reservoirs that would otherwise yield negligible flow rates. Multi-stage fracturing dominates completion design as operators push lateral lengths beyond 15,000 feet to maximize per-well recovery. Natural gas producers represent the fastest-growing end user category as LNG export commitments pull supply from Appalachian and Haynesville shales. Fracturing fluids command disproportionate margin attention given their chemical complexity and growing regulatory scrutiny of additive disclosure.
The EPA enforces methane performance standards under the Clean Air Act while OSHA governs silica exposure limits during proppant handling, with both agencies intensifying inspection frequency in active basins. State regulators in Texas and New Mexico layer additional setback requirements and groundwater monitoring obligations atop federal baselines. Stakeholders must track how the SEC's climate disclosure rules alter capital access for operators with elevated emissions profiles.
Market Dynamics
Pad drilling economics and multi-well development patterns are compressing breakeven thresholds across the Permian and Haynesville basins, forcing service providers to reconfigure fleet deployment around 24-hour continuous operations.
Growth Catalysts
- Power generation fuel switching:Baseload coal retirements accelerate natural gas procurement from Appalachian and Haynesville shales. Combined-cycle plants now anchor offtake contracts for dry gas production.
- EPA methane performance standards:The Clean Air Act enforcement tightens wellhead monitoring requirements, creating demand for continuous emissions detection systems and leak repair services.
- Proppant logistics optimization:Unit train delivery systems and transload terminals reduce last-mile trucking costs for sand-intensive completion designs in West Texas.
Market Restraints
- Silica exposure compliance costs:OSHA's respirable crystalline silica limits mandate dust suppression systems at sand transfer points, elevating capital requirements for proppant handling infrastructure.
- Water sourcing constraints:Freshwater availability limitations in drought-prone Texas counties force operators toward recycled produced water treatment, increasing completion complexity.
- Pipeline takeaway bottlenecks:Midland-to-Gulf Coast capacity constraints periodically strand Permian production, depressing regional gas prices and fracturing demand volatility.
Strategic Opportunities
- Argentina Vaca Muerta development:The Neuquén Basin offers untapped shale potential with favorable geology but requires imported fracturing horsepower and specialized pressure pumping equipment.
- Electric fracturing fleet conversion:Dual-fuel and grid-tied pump systems reduce fuel costs and emissions intensity, aligning with ESG-linked capital access requirements from institutional investors.
- Direct LNG offtake contracting:Integrated producers are bypassing traditional pipeline marketing to secure long-term export commitments at Gulf Coast liquefaction terminals.
Industry Challenges
- Specialized pressure pumping labor scarcity:Experienced pump operators and maintenance technicians command premium wages as fleet utilization rates climb, constraining operational scalability.
- Multi-basin equipment redeployment friction:Moving high-spec fracturing spreads between the Permian, Eagle Ford, and DJ Basin involves regulatory permitting delays and rig-up downtime.
- Real-time data integration complexity:Merging surface pumping parameters with downhole diagnostics from distributed fiber optic systems requires cross-functional engineering coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shale Gas Hydraulic Fracturing Market |
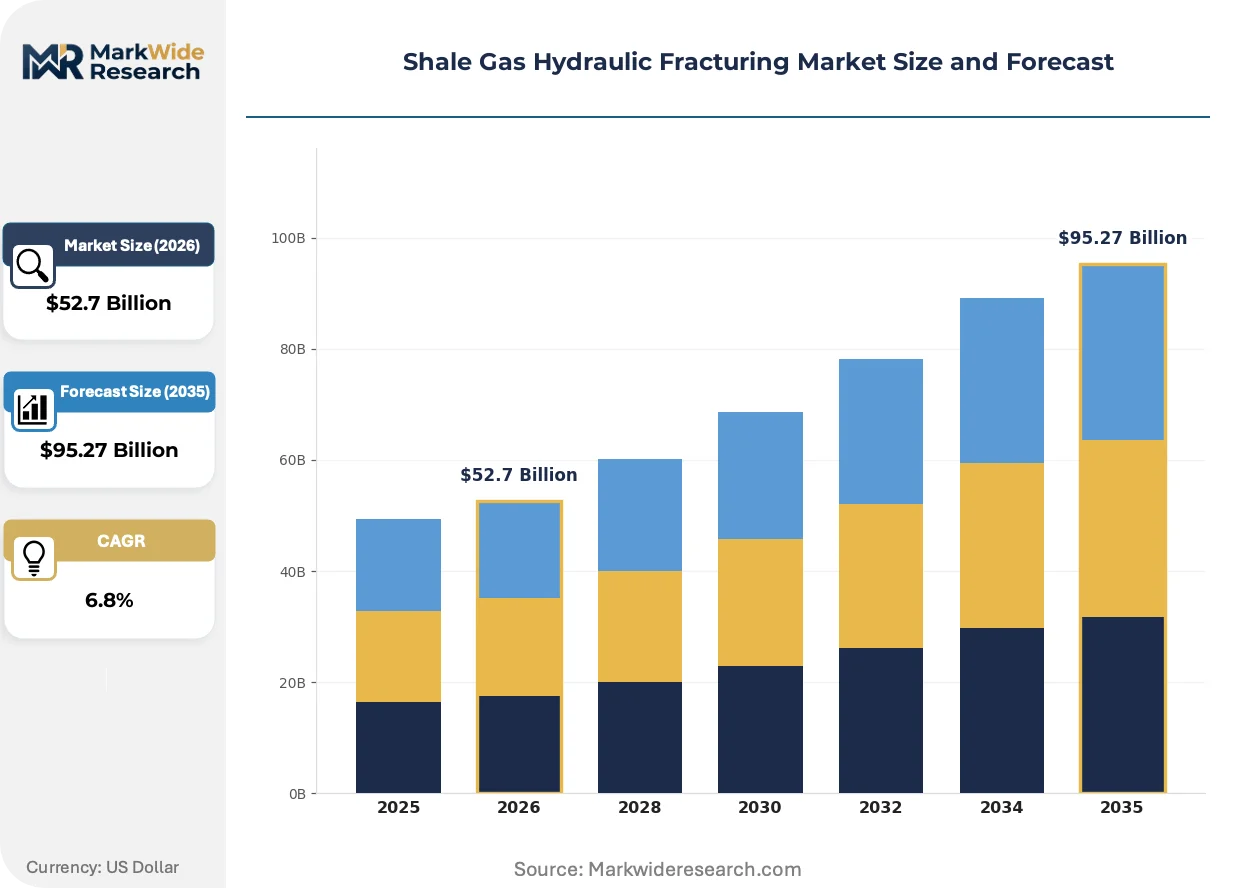
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Conventional Fracturing, Horizontal Drilling, Multi-stage Fracturing, Acid Fracturing End User: Oil Companies, Natural Gas Producers, Service Providers, Government Agencies Application: Production Enhancement, Reservoir Stimulation, Well Completion, Field Development Equipment Type: Hydraulic Pumps, Pressure Control Equipment, Fracturing Fluids, Flowback Equipment |
| Companies Covered | Halliburton, Schlumberger, Baker Hughes, Liberty Oilfield Services, NexTier Oilfield Solutions, Calfrac Well Services, Patterson-UTI Energy, ProFrac Holding Corp., Trican Well Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shale Gas Hydraulic Fracturing Market Emerging Trajectories
Digital orchestration of fracturing operations is compressing stage timing and reducing non-productive time across multi-well pads. Automation and predictive analytics now determine competitive differentiation.
Electric fracturing fleets powered by natural gas turbine generators or grid interconnects are consolidating market share in emissions-sensitive basins. E&P operators with net-zero commitments specify electric or dual-fuel equipment in service tenders. This technology is consolidating supplier margins around fuel efficiency metrics rather than pure pumping horsepower.
The EPA's supplemental methane proposal under the Clean Air Act mandates optical gas imaging surveys at compressor stations and well sites. Equipment suppliers must certify leak detection hardware to performance standards that exceed current commercial specifications. Producers in the Permian Basin are pre-positioning continuous monitoring systems ahead of compliance deadlines.
Integrated service contracts that bundle proppant, chemicals, and pumping operations are displacing discrete procurement of individual completion components. E&P procurement teams consolidate vendor relationships to reduce administrative overhead and secure volume discounts. This pattern concentrates purchasing power among super-majors and large independents operating in the Permian and Haynesville shales.
Shale Gas Hydraulic Fracturing Market Segmentation
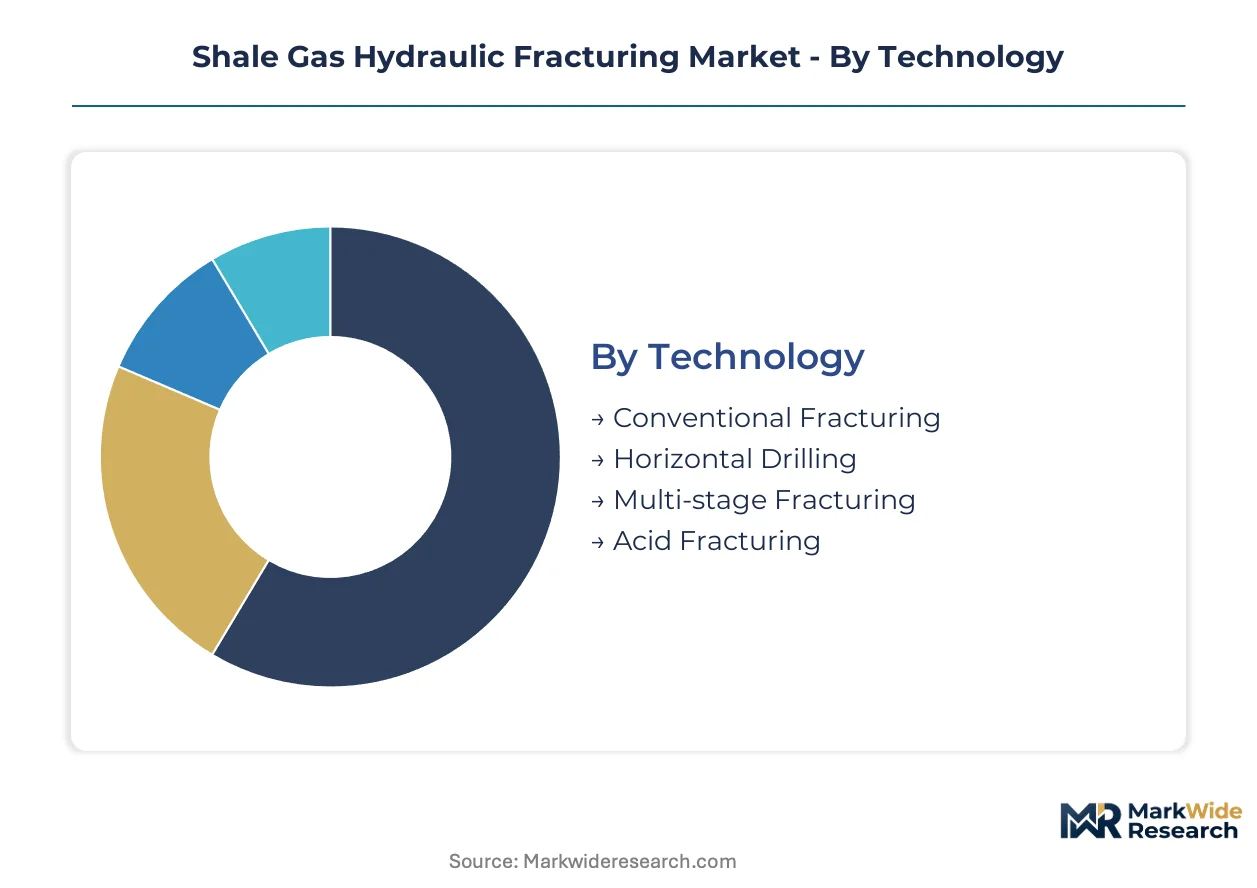
Segmentation in shale gas hydraulic fracturing reveals how capital flows between discrete service offerings and integrated packages. Technology choices determine pump fleet specifications, while end-user procurement patterns dictate contract structures and margin capture.
Technology:
Integration depth varies sharply—some technologies operate as standalone service lines while others embed within broader completion systems.
- Multi-stage Fracturing:Sequential isolation and treatment of multiple zones along extended laterals, typically exceeding 15,000 feet in Permian and Haynesville applications. Demand concentrates among large independents and super-majors pushing per-well recovery metrics; EPA methane monitoring requirements are accelerating adoption of precision stage timing to minimize venting events.
- Horizontal Drilling:Directional borehole construction that creates the wellbore architecture enabling lateral fracturing treatments. Operators in the Delaware Basin sub-region of the Permian deploy this as the foundational step before fracturing operations, with rig dayrates and drilling efficiency directly determining pad economics.
- Conventional Fracturing:Single-stage treatments in vertical or mildly deviated wellbores, now largely confined to legacy asset rejuvenation and marginal field development.
- Acid Fracturing:Reactive fluid systems that etch conductive channels in carbonate-rich formations, deployed selectively in Appalachian Basin plays with mixed lithology.
Volume placements concentrate in Multi-stage Fracturing; the faster expansion belongs to Horizontal Drilling as lateral lengths extend.
End User:
Cost tier stratification separates integrated operators with captive service arms from independents relying entirely on third-party procurement.
- Natural Gas Producers:Dry gas-focused operators in Appalachia and Haynesville securing offtake for combined-cycle power plants and LNG export commitments. Procurement emphasizes fuel switching alignment and emissions intensity metrics under institutional ESG mandates.
- Oil Companies:Liquids-weighted producers in the Permian Midland and Delaware sub-basins where associated gas production requires fracturing services for oil-targeted completions. Water sourcing constraints in drought-prone Texas counties are elevating completion complexity and capital requirements.
- Service Providers:Oilfield services firms subcontracting specialized pressure pumping capacity to operators lacking owned fleets.
- Government Agencies:State-owned enterprises in Argentina's Neuquén Basin and other international shale frontiers importing fracturing horsepower and technical expertise.
Contract value concentrates among Natural Gas Producers; the steepest expansion trajectory is climbing among Oil Companies as Permian development intensifies.
Application:
Customer type differentiation separates greenfield development from brownfield optimization, with distinct service intensity and technology requirements.
- Production Enhancement:Refracturing and restimulation of existing wells to recover bypassed reserves, increasingly deployed in mature Eagle Ford and Bakken assets where new drilling inventory depletes.
- Well Completion:Initial fracturing treatments following drilling, representing the core revenue pool for pressure pumping fleets and consuming the majority of proppant and fluid volumes.
- Reservoir Stimulation:Diagnostic fracture injection tests and step-rate analyses informing subsequent completion design.
- Field Development:Integrated multi-well pad programs spanning drilling, completion, and facilities installation.
Revenue concentration sits with Well Completion; gaining share fastest is Production Enhancement as inventory quality declines in mature basins.
Equipment Type:
Supply concentration shapes margin structures—certain equipment categories consolidate among specialized manufacturers while others fragment across regional fabricators.
- Fracturing Fluids:Complex aqueous systems combining water, gelling agents, crosslinkers, and breakers, with chemical composition increasingly scrutinized under state disclosure mandates and OSHA silica exposure rules. Permian operators are expanding recycled produced water treatment to reduce freshwater dependency.
- Hydraulic Pumps:High-pressure positive displacement units operating above 10,000 psi surface pressure, with electric and dual-fuel variants capturing share in emissions-sensitive basins.
- Pressure Control Equipment:Wellhead isolation tools and manifold systems managing fracture propagation.
- Flowback Equipment:Separation and handling systems for initial production fluids and proppant returns.
Capital deployment concentrates in Fracturing Fluids; expanding most quickly is Hydraulic Pumps as fleet electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration in the United States dominates service procurement volumes, with the Permian Basin spanning Texas and New Mexico accounting for the majority of fracturing fleet deployments. International expansion concentrates in Argentina's Neuquén Basin and select Middle Eastern tight gas formations.
United States
The Permian Basin's Delaware and Midland sub-basins drive fracturing demand through multi-well pad development and extended lateral designs exceeding 15,000 feet. The EPA's supplemental methane proposal under the Clean Air Act mandates optical gas imaging surveys and continuous emissions monitoring systems ahead of compliance deadlines. West Texas proppant logistics hubs in Odessa and Midland reduce last-mile trucking costs through unit train delivery systems.
Argentina
The Vaca Muerta formation in the Neuquén Basin attracts imported fracturing horsepower and specialized pressure pumping equipment for unconventional development. The national energy regulator enforces local content requirements and environmental impact assessments for shale operations. YPF-operated clusters in Loma Campana and La Amarga Chica anchor initial production scaling efforts.
Canada
The Montney and Duvernay shales in Alberta and British Columbia sustain fracturing demand for liquids-rich gas production targeting Pacific LNG export markets. The Alberta Energy Regulator mandates baseline groundwater monitoring and hydraulic fracturing fluid disclosure through the FracFocus registry. Grande Prairie and Fort St. John serve as primary service company staging areas for northern basin operations.
China
Sichuan Basin tight gas and shale formations in the Fuling and Weirong blocks drive domestic fracturing equipment procurement. The Ministry of Ecology and Environment enforces emissions standards and water pollution controls for unconventional gas development. Chongqing municipality anchors operational coordination for national oil company-led development programs.
Saudi Arabia
The Jafurah Basin tight gas development program requires imported fracturing technology and specialized completion services for non-associated gas production. The Ministry of Energy oversees gas sector liberalization and unconventional resource development licensing. Dhahran-based Saudi Aramco technical centers coordinate service provider qualification and technology transfer requirements.
Shale Gas Hydraulic Fracturing Market Vendor Landscape
United States producers anchor one tier of integrated service provision; Canadian and Argentine specialists hold regional positions through localized fleet deployment and joint venture structures. Market structure consolidates around three to five dominant pressure pumping providers with owned equipment fleets, while mid-tier competitors concentrate in single-basin operations or specialized proppant logistics. Strategic archetypes separate integrated well service conglomerates, pure-play pressure pumping specialists, and diversified oilfield service platforms. Competitive dynamics center on electric fleet conversion investments and multi-year integrated service contract awards from super-majors and large independents.
Among Houston-based service conglomerates, Halliburton, Schlumberger, and Baker Hughes exemplify integrated archetypes spanning drilling, completion, and production services. These entities occupy positions defined by technology portfolios and geographic footprint breadth rather than pure pumping horsepower scale. Halliburton represents the integrated well services model; Schlumberger anchors digital and reservoir characterization capabilities; Baker Hughes exemplifies equipment manufacturing and turbomachinery integration. Their competitive positioning depends on bundling fracturing within broader completion packages and securing long-term integrated contracts with Permian and Haynesville operators.
| Leading Market Players |
|---|
| Halliburton |
| Schlumberger |
| Baker Hughes |
| Liberty Oilfield Services |
| NexTier Oilfield Solutions |
| Calfrac Well Services |
| Patterson-UTI Energy |
| ProFrac Holding Corp. |
| Trican Well Services |
| Others |
Supply Flow & Price Mechanics
Electric fleet certification splits service providers into emissions-compliant premium tiers and conventional diesel-dependent commodity players, with this bifurcation driving divergent capital deployment patterns across proppant logistics and pressure pumping procurement. The EPA's methane performance standards amplify this divergence as operators with ESG-linked financing specify certified low-emissions equipment, compressing margins for uncertified fleet operators while rewarding early electrification investments.
Pricing Analysis
Volume placements concentrate among integrated contract structures bundling pumping, proppant, and chemicals, while margin capture concentrates with specialized electric fleet operators serving emissions-sensitive basins. Price differentiation rests on fuel efficiency certification and real-time diagnostics integration, with Permian Basin operators commanding premium rates for continuous monitoring compliance. Cost compression in conventional diesel fleets is intensifying as equipment oversupply meets stagnant demand from cash-constrained independents. Natural gas producers with LNG export commitments demonstrate lowest price sensitivity; small Permian independents facing water sourcing constraints exhibit highest sensitivity.
Supply Chain Analysis
EPA emissions certification and API equipment standards gate supplier access to super-major procurement programs, with uncertified fabricators relegated to regional spot markets. Proppant supply concentrates in Wisconsin and Texas sand mines; pressure pumping equipment fabrication centers on Texas and Oklahoma manufacturing hubs. Raw material dependencies include high-grade silica sand, specialized alloy steel for pump components, and rare earth elements for electric drive systems. Single-source vulnerability runs through Chinese rare earth processing for permanent magnet motors. Distribution runs through Midland-Odessa staging yards for Permian deployment and Appalachian transload terminals for Marcellus-Utica operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
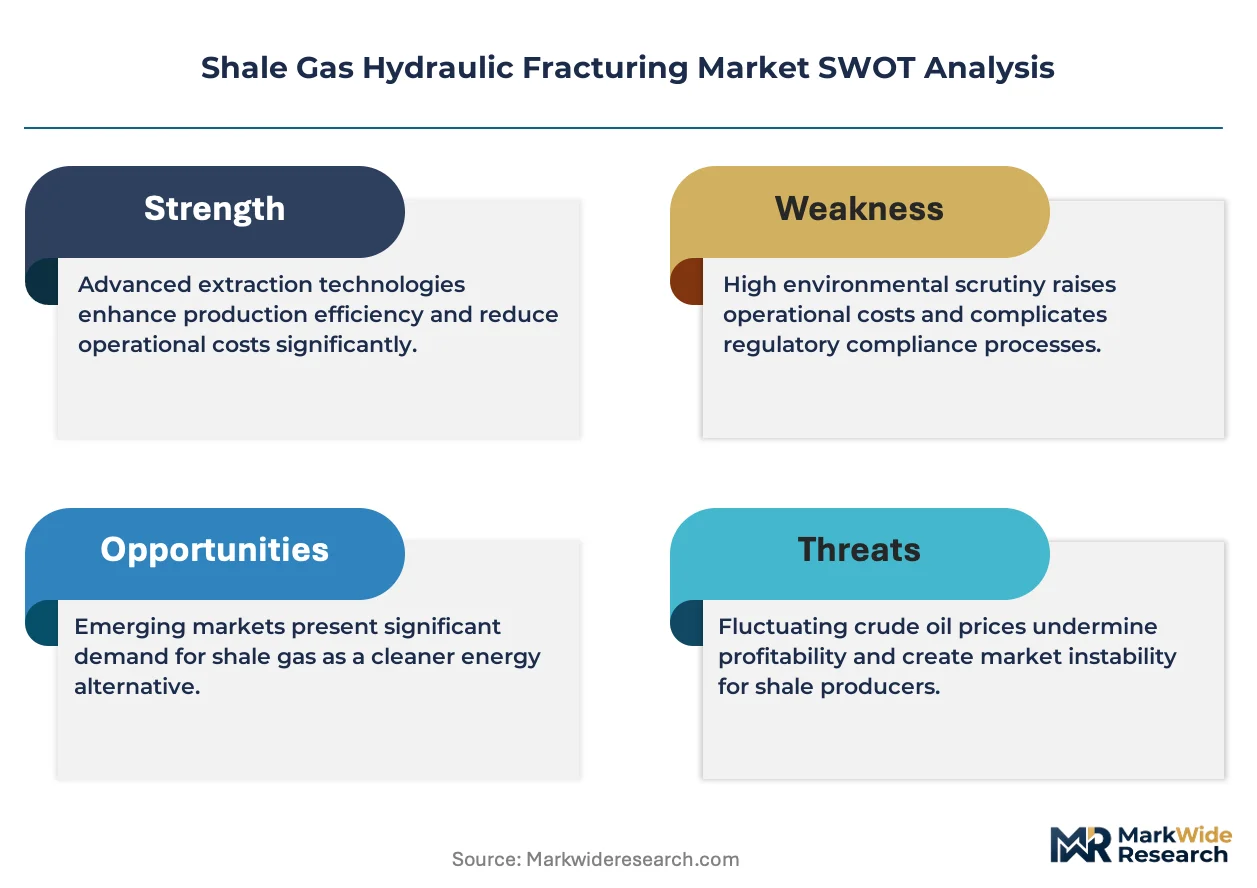
Vertical integration into captive proppant supply and recycled water treatment infrastructure is accelerating as operators seek to control input costs and secure regulatory compliance. This race for upstream control separates consolidators building end-to-end completion platforms from pure-play service providers facing margin compression.
For Market Incumbents: Anchor market position through dual-fuel and electric fleet conversion ahead of EPA compliance deadlines, while securing long-term integrated service contracts with Haynesville and Permian operators possessing LNG export commitments. Threat from emerging electric fleet specialists with ESG-aligned capital access demands preemptive certification investment. Backward integration into regional sand mining and produced water recycling infrastructure secures cost advantages as freshwater constraints tighten in drought-prone Texas counties.
For New Entrants and Emerging Players: Begin with Argentina's Vaca Muerta formation, where imported fracturing horsepower shortages and YPF-operated cluster development create procurement gaps for specialized pressure pumping capacity. The Neuquén Basin offers most penetrable geography given favorable geology and underdeveloped local service infrastructure. Go-to-market angle should emphasize technology transfer partnerships with national oil companies seeking to reduce import dependency.
For Investors and Strategic Acquirers: Re-rating potential sits with electric fleet operators possessing EPA pre-certified equipment given methane regulation enforcement acceleration. Long-term viability across the analysis window favors consolidators with integrated water management and proppant logistics capabilities. Acquisition target archetype: regional pressure pumping specialists with established Permian or Haynesville customer relationships and upgradeable fleet specifications. Signal to watch: SEC climate disclosure implementation altering capital access for operators with elevated emissions intensity profiles.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Conversion | EPA methane standards and ESG capital requirements reward early electrification investments in Permian operations. |
| Backward Integration into Proppant Supply | Wisconsin and Texas sand mine acquisitions secure input cost control against volatile last-mile trucking expenses. |
| Produced Water Recycling Infrastructure | Texas drought conditions and regulatory pressure elevate recycled water treatment to competitive necessity. |
| Integrated Service Contract Consolidation | Halliburton and Baker Hughes bundle pumping, chemicals, and diagnostics to reduce customer procurement overhead. |
| Argentina Market Entry Partnership | YPF-operated Vaca Muerta clusters require imported horsepower and specialized pressure pumping expertise. |
Methodological Framework
Document review covered EIA production databases, EPA regulatory filings, FERC infrastructure reports, and SEC climate disclosure submissions, complemented by interviews with pressure pumping fleet managers, E&P completion engineers, proppant logistics coordinators, and environmental compliance officers at Permian and Haynesville operators. Secondary validation drew from state regulator enforcement data, water use reporting from Texas and New Mexico agencies, and equipment utilization metrics from pressure pumping associations. Bottom-up segmentation modeling triangulated against top-down basin-level activity forecasts.
Segment-level outputs across technology, end user, application, and equipment type dimensions were reconciled with basin-specific drilling and completion activity trajectories over the projection horizon. CAGRs were derived from equipment deployment rates, lateral length extension trends, and stage count intensification patterns. Industry-specific forecast inputs included EPA compliance timeline assumptions, electric fleet conversion adoption curves, and LNG export capacity expansion schedules.
Underlying measurement precision varies by segment; well completion and multi-stage fracturing carry tighter precision than production enhancement given established activity reporting, while Argentina development timing carries higher uncertainty. Forecasts reflect assumptions regarding regulatory enforcement intensity, capital market ESG integration speed, and proppant logistics cost trajectories. A model refresh is warranted upon material change in EPA methane rule implementation schedules or LNG export license approvals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oilwell Spacer Fluids Market
Oil & Gas
United States Artificial Lift Systems Market
Oil & Gas
South America LNG Bunkering Market
Oil & Gas
North America Wireline Services Market
Oil & Gas
Middle East and Africa Early Production Facility Market
Oil & Gas
Enhanced Gas Recovery (EGR) Market
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
Oilfield Drilling Elevator Market
Oil & Gas
Offshore Drilling Fluid Market
Oil & Gas
North America Directional Drilling Services Market
Oil & Gas
Mexico Wireline Services Market
Oil & Gas
Ecuador Oil and Gas Midstream Market
Oil & Gas
Flare Gas Recovery System Market
Oil & Gas
India AI in Oil and Gas Market
Oil & Gas
Europe Natural Gas Market
Oil & Gas
Africa Oil Country Tubular Goods (OCTG) Market