
 Central Asia Oil and Gas Midstream Market | 2026-2036
Central Asia Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
Central Asia Oil and Gas Midstream Market Outlook
Higher-grade API 5L pipeline specifications for sour gas service is redrawing procurement priorities across Central Asian trunkline projects. KazMunayGas leverages its integrated control over Kazakhstan's domestic oil transit network to dominate westbound export routes. CNPC anchors throughput commitments on the Central Asia-China Gas Pipeline system, locking in multi-decade offtake structures. Turkmengaz competes on cost at the eastern supply margin, positioning its Galkynysh field output as the lowest-delivered-cost feedstock into Chinese border stations.
The Central Asia oil and gas midstream sector encompasses pipeline transportation, storage terminals, and gas processing facilities engineered to handle hydrocarbons between production fields and downstream consumers, with trunklines typically specified for pressures of 75-100 bar and diameters exceeding 1,000 mm to accommodate high-volume, long-distance flows across continental distances. Crude oil pipelines carry the majority of current throughput value, though natural gas pipeline expansions are attracting the fastest capacity additions as China diversifies import sources away from maritime LNG. Processing services command premium margins where associated gas liquids recovery meets petrochemical feedstock specifications, while storage infrastructure remains structurally underbuilt relative to seasonal demand swings in the region.
Kazakhstan's Committee for Industrial Development enforces mandatory compressor station upgrades under its technical regulation for trunk pipelines, directly shaping equipment procurement timelines and vendor qualification requirements. Uzbekistan's national energy regulator and Turkmenistan's standards agency coordinate intermittently on cross-border metering protocols, creating compliance friction that delays joint tariff negotiations. Stakeholders must monitor whether China's National Energy Administration accelerates import diversification mandates, as this policy lever would reshape throughput allocation across competing pipeline systems before new transit corridors achieve final investment decision.
Market Dynamics
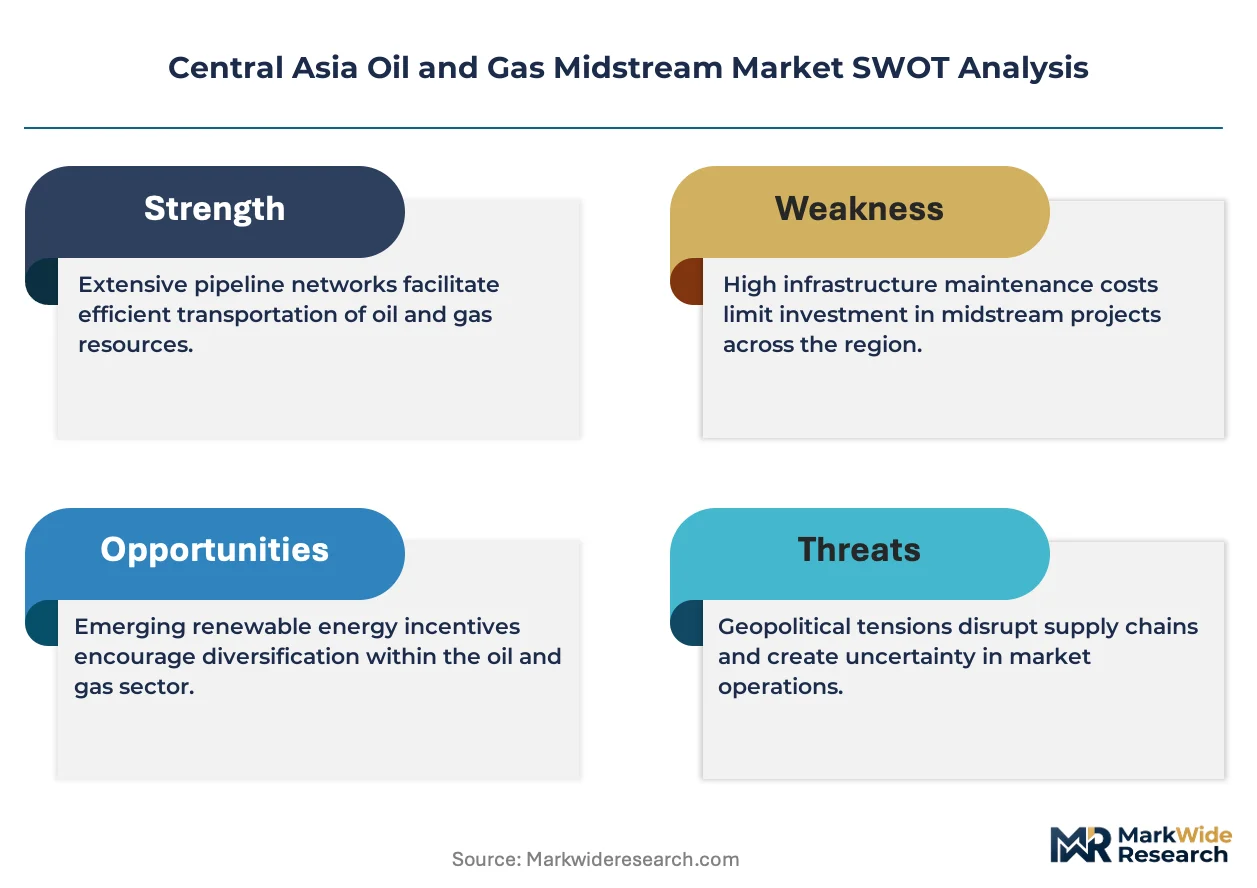
Kazakhstan's Committee for Industrial Development is enforcing compressor station retrofits under tightening pipeline safety codes, forcing capital reallocation across trunkline operators while Chinese refineries pull new export capacity online through long-term offtake commitments.
Growth Catalysts
- Chinese refinery demand:Sustained crude appetite from Shandong and Xinjiang processing complexes locks in throughput guarantees for westbound export routes, underwriting pipeline expansion financing.
- Higher-grade API 5L specifications:Sour gas service requirements for trunkline steel grades are accelerating procurement of corrosion-resistant alloys across newbuild projects.
- Uzbekistan's gas processing corridor:Concentrated storage investment at the Shurtan and Mubarek hubs positions the country as the regional balancing point for seasonal demand swings.
Market Restraints
- Input cost volatility:Alloy steel plate prices for large-diameter pipe fluctuate with scrap metal and nickel markets, compressing project IRRs at FID stage.
- Regulatory friction:Intermittent coordination between Uzbekistan's national energy regulator and Turkmenistan's standards agency on cross-border metering protocols delays joint tariff negotiations.
- Substitution pressure:Maritime LNG cargoes to Chinese eastern ports compete with pipeline gas on delivered cost during periods of low spot LNG pricing.
Strategic Opportunities
- Turkmenistan's eastern supply margin:Galkynysh field output offers the lowest-delivered-cost feedstock into Chinese border stations, creating volume capture potential for cost-optimized operators.
- Digital twin convergence:Integration of SCADA systems with predictive analytics enables real-time leak detection and compressor optimization across aging Soviet-era infrastructure.
- Associated gas liquids recovery:Processing services meeting petrochemical feedstock specifications command premium margins where NGL extraction infrastructure is underbuilt.
Industry Challenges
- Welding certification timelines:Qualification of automated girth-weld procedures for sour service pipelines extends vendor approval cycles by 8-14 months.
- Legacy SCADA integration:Retrofitting digital monitoring onto Soviet-era compressor stations requires custom protocol translation, inflating commissioning costs and downtime windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Central Asia Oil and Gas Midstream Market |
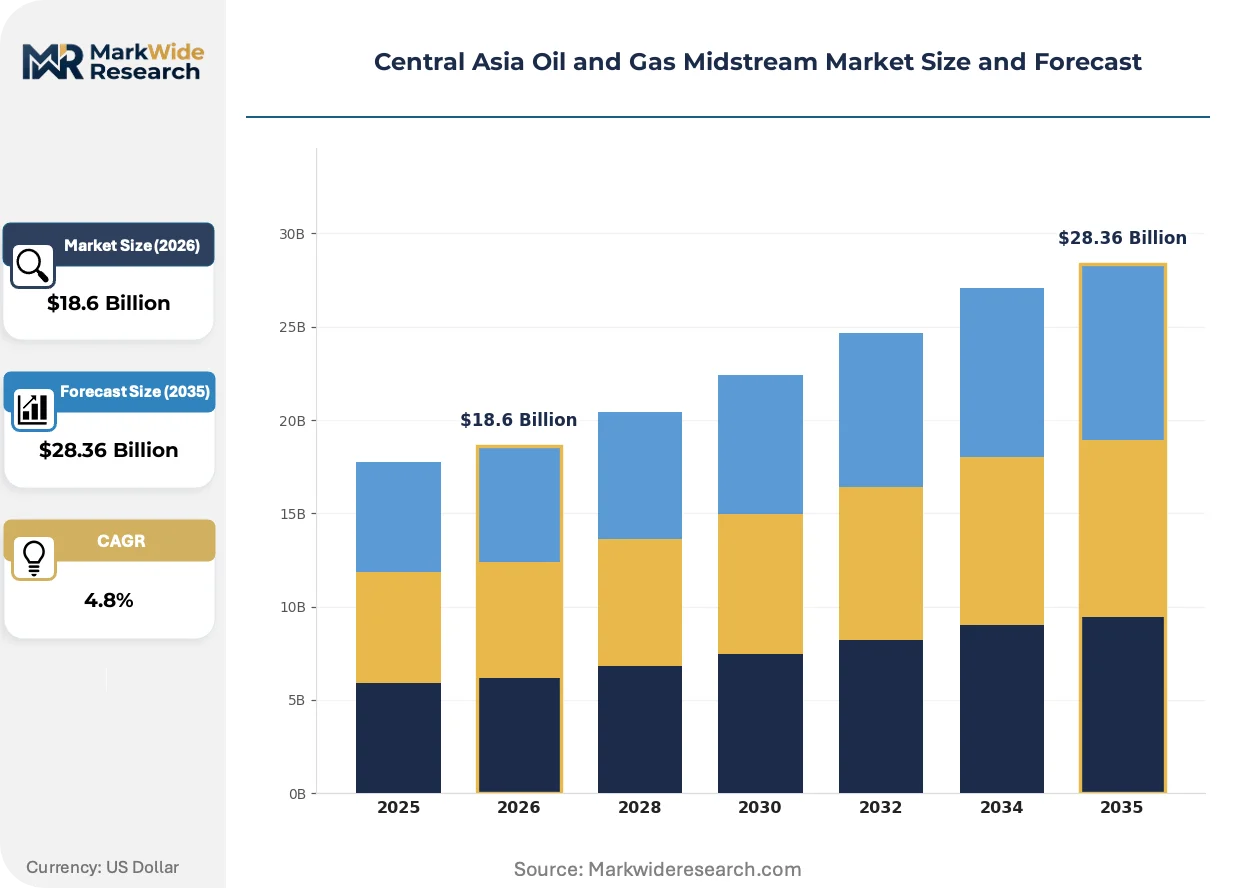
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $28.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Storage, Loading, Processing Pipeline Type: Crude Oil, Natural Gas, Refined Products, NGL Technology: Pumping, Compression, Heating, Cooling End User: Utility Companies, Oil Producers, Industrial Companies, Gas Distributors |
| Companies Covered | Chevron Corporation, National Company JSC (KazMunayGas), Intergas Central Asia JSC, National Company QazaqGaz JSC, KazTransOil JSC, Asia Gas Pipeline LLP, Beineu-Shymkent Gas Pipeline LLP, CNPC, Turkmengaz, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Central Asia Oil and Gas Midstream Market Strategic Shifts
Digital monitoring systems and advanced metallurgy are compressing maintenance cycles and enabling predictive asset management across Central Asia's aging pipeline infrastructure, while procurement patterns favor integrated service contracts over discrete equipment purchases.
Composite pipeline repair sleeves incorporating carbon-fiber reinforcement are fragmenting the traditional steel-patch maintenance market. Kazakh trunkline operators now specify these systems for 80% of non-leak integrity repairs, cutting excavation requirements by half. The technology is fragmenting vendor hierarchies as specialized composites firms displace conventional welding contractors in routine maintenance scopes.
Kazakhstan's Committee for Industrial Development mandates automated ultrasonic testing for all new compressor station welds under its 2024 technical regulation revision. Fabricators must retool inspection workflows, adding capex lines for phased-array equipment. Midstream EPCs in the Atyrau-Aktobe corridor report 15-20% schedule compression as qualified NDT providers become bottlenecks.
Chinese NOC procurement teams now bundle 15-year throughput commitments with compressor station O&M contracts, displacing the prior model of separate equipment and service sourcing. This consolidation favors integrated midstream operators with captive technical service divisions. The shift is most visible on the Central Asia-China Gas Pipeline system, where CNPC anchors multi-decade offtake structures requiring single-point accountability for availability guarantees.
Central Asia Oil and Gas Midstream Market Segmentation
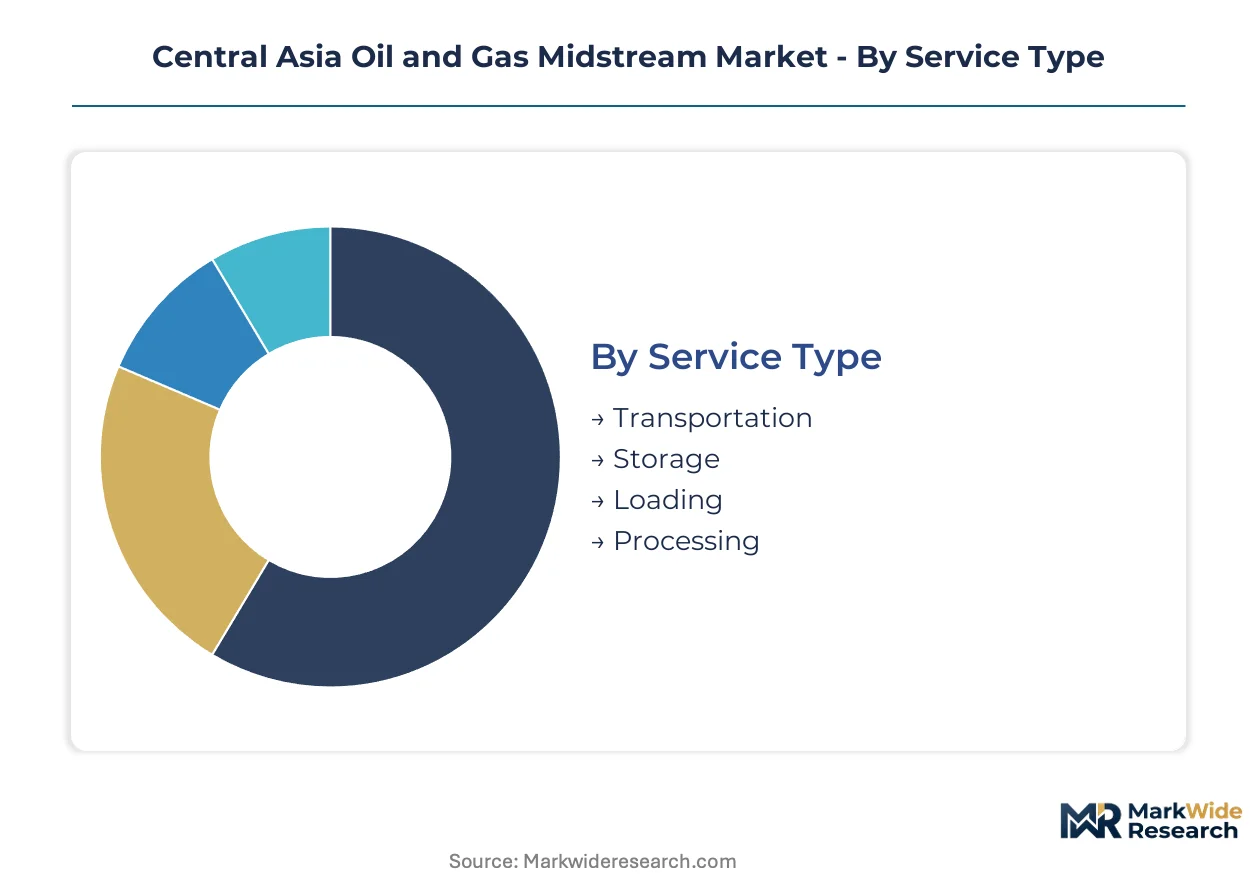
Midstream operators in Central Asia configure service portfolios around the region's dominant export corridors. Segmentation choices determine tariff structures, capital intensity, and exposure to Chinese offtake volatility.
Service Type:
Transportation commands the largest revenue share, with storage and processing services layering on at corridor termini and seasonal demand peaks.
- Transportation:Trunkline throughput between production basins and border stations generates the core revenue base. Kazakhstan's CPC and CNPC-anchored systems move the majority of regional crude and gas volumes toward Chinese refineries and Black Sea terminals.
- Storage:Underground salt caverns and above-ground tank farms at Shurtan, Mubarek, and Aktau provide seasonal balancing. Uzbekistan's corridor concentrates the region's largest storage investment as Galkynysh field output requires buffer capacity ahead of Chinese border metering.
- Loading:Marine terminal operations at Aktau and Turkmenbashi handle Caspian tanker transfers. Facilities face draft constraints that limit vessel size and extend loading windows.
- Processing:Gas treatment and NGL recovery at Karachaganak and Galkynysh strip sour gas components and extract liquids for petrochemical feedstock. Sour service specifications drive equipment procurement costs above standard gas processing benchmarks.
By volume, Transportation leads. By growth pace, Processing is ahead as associated gas liquids recovery expands.
Pipeline Type:
Crude infrastructure carries mature throughput, while gas pipelines attract the fastest capacity additions as China diversifies import sources.
- Crude Oil:Soviet-era trunklines with 1,000mm+ diameter and 75-100 bar pressure ratings dominate westbound export routes. KazMunayGas leverages integrated control over Kazakhstan's domestic network to prioritize CPC and Atasu-Alashankou corridor utilization.
- Natural Gas:The Central Asia-China Gas Pipeline system anchors multi-decade offtake structures with three parallel trunklines. CNPC's throughput commitments lock in financing for compressor station expansions across Uzbekistan and Kazakhstan segments.
- Refined Products:Limited regional refining capacity constrains dedicated products pipeline development. Existing infrastructure serves primarily domestic distribution around Shymkent and Pavlodar refineries.
- NGL:Y-grade and specification-grade pipelines link gas processing plants to petrochemical complexes. Infrastructure remains sparse outside the Karachaganak processing hub and select Uzbekistan corridor tie-ins.
Crude Oil pipelines hold the installed base advantage. Natural Gas lines are climbing the fastest as Turkmenistan's eastern supply margin feeds Chinese demand growth.
Technology:
Compression and pumping technologies differentiate by pressure requirements and sour gas exposure across the region's trunkline network.
- Pumping:Crude oil trunklines rely on centrifugal pumps with 5,000+ kW ratings for viscosity management across continental distances. Kazakhstan's Committee for Industrial Development mandates automated monitoring retrofits under 2024 technical regulations.
- Compression:Gas pipelines require centrifugal and reciprocating compressors staged at 100-150 km intervals. Sour gas service specifications accelerate procurement of corrosion-resistant alloys and specialized sealing systems.
- Heating:Heat tracing and direct-fired line heaters maintain crude flowability across winter temperature extremes. Energy intensity varies sharply with pour point characteristics of Kashagan versus Tengiz crude streams.
- Cooling:Gas cooling stations reduce inlet temperatures ahead of compression stages and processing plants. Limited deployment outside high-pressure gathering systems and LNG pretreatment contexts.
Compression dominates capital allocation. Pumping maintains steady replacement demand as Soviet-era stations reach end-of-design-life.
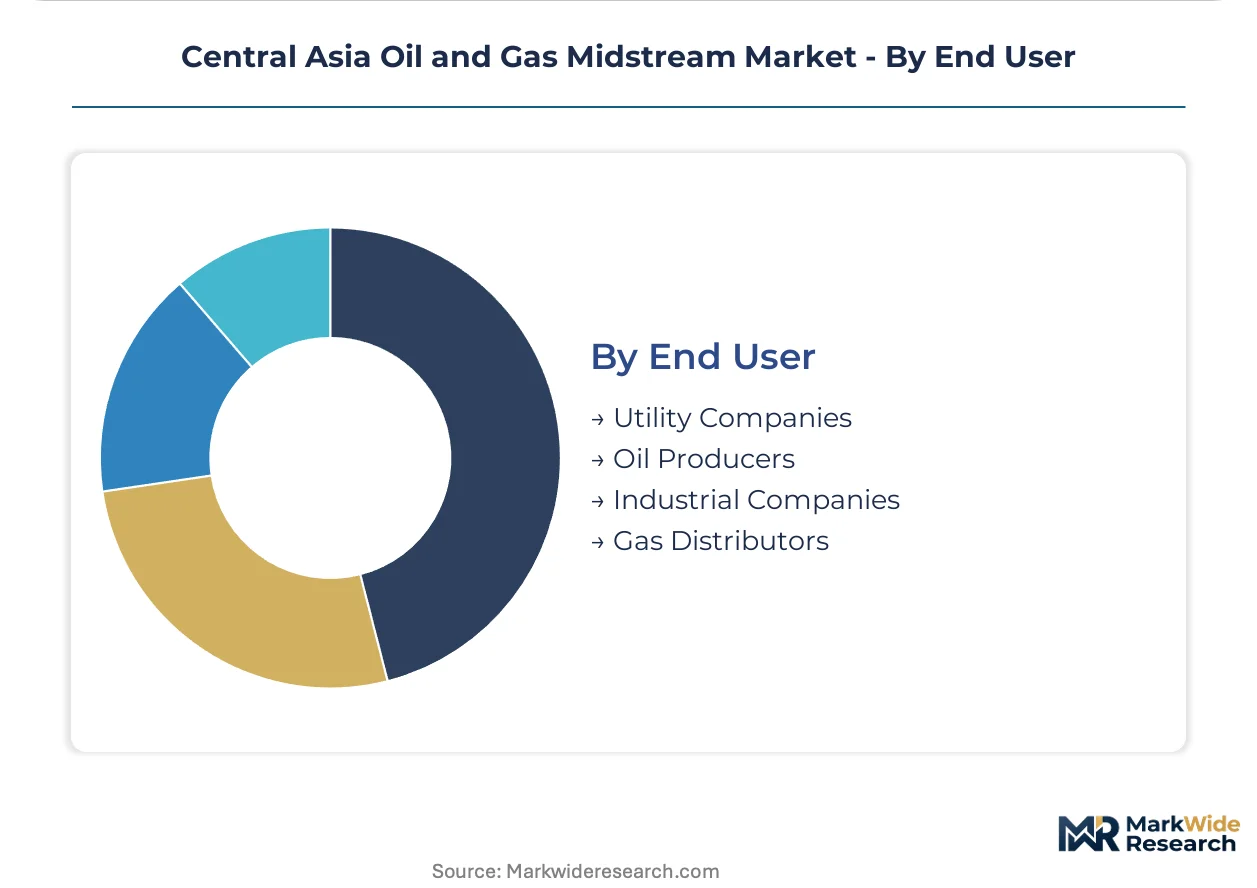
End User:
Contract structures vary sharply between integrated NOCs seeking control and independent producers requiring open-access terms.
- Utility Companies:Power generators and municipal gas distributors in Uzbekistan and Kazakhstan procure firm transportation capacity for seasonal peak shaving. Tariff negotiations center on take-or-pay structures indexed to domestic regulated prices.
- Oil Producers:Tengizchevroil, Karachaganak Petroleum Operating, and CNPC-operated fields anchor throughput commitments. Field equity holders prioritize dedicated pipeline access over common carrier alternatives.
- Industrial Companies:Fertilizer and petrochemical complexes in Navoiy and Aktobe source feedstock gas through direct processing agreements. Volume commitments often span 15-20 years to underwrite upstream development.
- Gas Distributors:City gate operators in Almaty, Tashkent, and Ashgabat manage last-mile pressure reduction and odorization. Seasonal demand swings expose storage infrastructure gaps across the region.
Oil Producers commit the largest block volumes. Gas Distributors are expanding most quickly as urbanization extends network coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Central Asia's midstream infrastructure balances eastbound export commitments against domestic supply security mandates. Pipeline throughput allocation reflects China's import diversification strategy and the region's evolving regulatory frameworks for cross-border hydrocarbon transit.
Kazakhstan
Tengiz and Karachaganak field operators drive compressor station expansions along the CPC and Atasu-Alashankou corridors. The Committee for Industrial Development mandates automated ultrasonic testing for all new welds under its 2024 technical regulation revision. The Atyrau-Aktobe corridor concentrates retrofit activity as Soviet-era pumping stations reach end-of-design-life.
Uzbekistan
Shurtan and Mubarek gas processing hubs anchor the region's largest storage investment to buffer Galkynysh field output ahead of Chinese border metering. The national energy regulator coordinates intermittently with Turkmen counterparts on cross-border tariff protocols. The Bukhara-Khiva corridor hosts concentrated NGL extraction infrastructure serving Navoiy petrochemical complexes.
Turkmenistan
Galkynysh field output offers the lowest-delivered-cost feedstock into Chinese border stations through the Central Asia-China Gas Pipeline system. The national standards agency maintains separate metering protocols that create compliance friction with Uzbek counterparts. The Mary region concentrates eastern supply margin development for cost-optimized volume capture.
China (Xinjiang)
Shandong and Xinjiang refineries lock in multi-decade offtake structures that underwrite pipeline expansion financing across Central Asian segments. The National Energy Administration's import diversification mandates reshape throughput allocation before new transit corridors achieve final investment decision. The Alashankou border station anchors volume metering for Turkmen and Uzbek supply streams.
Central Asia Oil and Gas Midstream Market Competitive Environment
Listed leaders compete with private specialists across state-controlled infrastructure networks. The market structure consolidates around national oil companies with integrated trunkline control, while international majors participate through field equity positions rather than independent midstream ownership. Two strategic archetypes dominate: state NOCs with captive pipeline networks, and Chinese national oil companies anchoring long-term offtake commitments. Competitive moves center on compressor station retrofit bundling and multi-decade throughput contracting.
Within the state NOC tier, KazMunayGas and QazaqGaz occupy positions as integrated controllers of Kazakhstan's domestic transit network. CNPC represents the Chinese offtake anchor archetype, locking in financing for cross-border expansions through its Central Asia-China Gas Pipeline commitments. Turkmengaz sits within the eastern supply margin specialist category, positioning Galkynysh output for cost-competitive border delivery.
| Leading Market Players |
|---|
| Chevron Corporation |
| National Company JSC (KazMunayGas) |
| Intergas Central Asia JSC |
| National Company QazaqGaz JSC |
| KazTransOil JSC |
| Asia Gas Pipeline LLP |
| Beineu-Shymkent Gas Pipeline LLP |
| CNPC |
| Turkmengaz |
| Others |
Value Chain & Pricing Dynamics
Compressor station throughput scale at Karachaganak and Galkynysh anchors procurement leverage for alloy steel plate, concentrating supply negotiations among three dominant trunkline operators and establishing price floors that smaller midstream players cannot match. This scale dynamic feeds back into vendor qualification timelines, as Kazakhstan's Committee for Industrial Development mandates automated ultrasonic testing that only scaled fabricators can absorb.
Pricing Analysis
Industrial OEM buyers anchor long-term offtake contracting across the Central Asia-China Gas Pipeline system, locking in fifteen-year tariff structures indexed to Chinese border station delivery costs. Price differentiation rests on API 5L grade certification and sour gas service specifications, with corrosion-resistant alloy premiums widening between standard and high-spec trunkline segments. Cost compression in compressor station retrofits is intensifying because Kazakhstan's 2024 technical regulations mandate phased-array inspection equipment that qualified NDT providers cannot supply at volume. National oil companies exhibit lowest price sensitivity due to captive financing, while independent gas distributors face margin pressure from seasonal demand volatility.
Supply Chain Analysis
Inventory lead times for large-diameter pipe extend eighteen to twenty-four months from mill order to field delivery, tethering project schedules to Chinese and Japanese steel plate capacity. The supply chain draws from Kazakhstan, China, and South Korea for alloy steel plate, with nickel-content specifications tracking London Metal Exchange volatility. Single-source vulnerability concentrates at automated girth-weld equipment vendors qualified for sour service protocols. Distribution runs through integrated midstream operators with captive technical service divisions rather than discrete equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across metering protocol standards between Turkmenistan and Uzbekistan creates niche opportunities for compliance specialists capable of bridging cross-border tariff negotiations. Chinese import diversification mandates are pulling new capacity online faster than regional coordination mechanisms can harmonize.
For Market Incumbents: Compound control over compressor station O&M bundling by anchoring fifteen-year availability guarantees with CNPC procurement teams. Defend against maritime LNG substitution pressure by accelerating digital twin deployment across Soviet-era infrastructure. Prioritize backward integration into automated ultrasonic testing equipment to bypass NDT provider bottlenecks in the Atyrau-Aktobe corridor.
For New Entrants and Emerging Players: Anchor in Uzbekistan's gas processing corridor at Shurtan and Mubarek, where storage infrastructure gaps expose seasonal balancing contracts to competitive bidding. Target associated gas liquids recovery services at Karachaganak, where NGL extraction capacity trails petrochemical feedstock demand. Lead with composite pipeline repair sleeve technology to displace conventional welding contractors in Kazakh trunkline maintenance scopes.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated midstream operators with captive technical service divisions and multi-decade Chinese offtake structures. Five-to-ten year viability favors state NOCs with pipeline network control and compressor station retrofit backlogs. Watch for acceleration in China's National Energy Administration import diversification mandates as the inflection signal reshaping throughput allocation across competing corridor proposals.
| Strategic Initiative | Industry Significance |
|---|---|
| Compressor Station Retrofit Bundling | Consolidates equipment and O&M contracts under single-point accountability for CNPC availability guarantees. |
| Automated Ultrasonic Testing Certification | Qualifies fabricators for Kazakhstan's 2024 technical regulations while creating NDT provider bottlenecks. |
| Associated Gas Liquids Recovery Expansion | Captures premium margins at Karachaganak where NGL infrastructure trails petrochemical feedstock specifications. |
| Digital Twin SCADA Integration | Enables predictive leak detection across Soviet-era compressor stations requiring custom protocol translation. |
| Composite Repair Sleeve Specification | Displaces conventional welding contractors in 80% of Kazakh non-leak integrity repairs with carbon-fiber reinforcement. |
Study Parameters
Desk research of pipeline regulatory filings, customs trade data for alloy steel plate imports, and EPC contractor project disclosures preceded structured interviews with trunkline operations managers, compressor station procurement leads, and national energy regulator technical directors. Primary fieldwork with midstream EPCs in Kazakhstan's Atyrau-Aktobe corridor validated secondary capacity estimates for Soviet-era pumping station replacement cycles. Bottom-up segmentation modeling triangulated against top-down corridor throughput projections from Chinese border station metering data.
Variance decomposition across service type, pipeline type, compression technology, and end-user contract structure shaped the analytical framework over the projection horizon. CAGRs derived from capacity expansion announcements, final investment decision timelines, and Chinese refinery crude appetite trajectories segmented by Shandong versus Xinjiang processing complex demand. Forecast inputs incorporated Kazakhstan's Committee for Industrial Development technical regulation revision schedules and Turkmenistan-Uzbekistan cross-border metering protocol coordination patterns.
Material uncertainties — regulatory friction on joint tariff negotiations, spot LNG pricing volatility affecting pipeline gas competitiveness, and alloy steel plate nickel content cost swings — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Canada Oil and Gas Market
Oil & Gas
Southeast Asia Oil and Gas Midstream Market
Oil & Gas
Europe Seismic Services Market
Oil & Gas
North America Shale Market
Oil & Gas
Underwater Monitoring System for Oil and Gas Market
Oil & Gas
Managed Pressure Drilling Services Market
Oil & Gas
Swellable Packers Market
Oil & Gas
Brazil Wireline Logging Services Market
Oil & Gas
Saudi Arabia Liner Hanger System Market
Oil & Gas
North America Wireline Services Market
Oil & Gas
North America Drilling Completion Fluids Market
Oil & Gas
Europe Seismic Survey Market
Oil & Gas
Oil and Gas Pipeline Coatings Market
Oil & Gas
Wellhead Equipment Market
Oil & Gas
Libya Oil and Gas Upstream Market
Oil & Gas
India Artificial Lift Systems Market