
 US Commercial Boiler Market | 2026-2036
US Commercial Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
US Commercial Boiler Market Analysis
Equipment leasing and energy-as-a-service contracting is reconfiguring capital deployment for mid-sized building operators that previously deferred boiler replacements. Cleaver-Brooks leverages its nationwide service footprint to capture recurring revenue from leased high-efficiency units. Miura America Co., Ltd. differentiates through modular once-through steam technology that reduces installed footprint in urban mechanical rooms. Fulton Boiler Company anchors its position with compact vertical tubeless designs suited for hospitals and universities with constrained plant space.
US commercial boilers are pressurized vessels generating steam or hot water for space heating, process loads, and domestic hot water, typically operating at pressures from 15 to 150 psi with combustion efficiencies now pushed above 85% by condensing architectures. Fire-tube designs dominate the replacement market due to lower installed cost and familiar maintenance protocols, while condensing segments capture margin pools where utility incentives and EPA compliance deadlines coincide. Water-tube configurations lead in high-capacity manufacturing and district heating applications where rapid steam demand fluctuation requires faster response curves than shell-and-tube geometries permit.
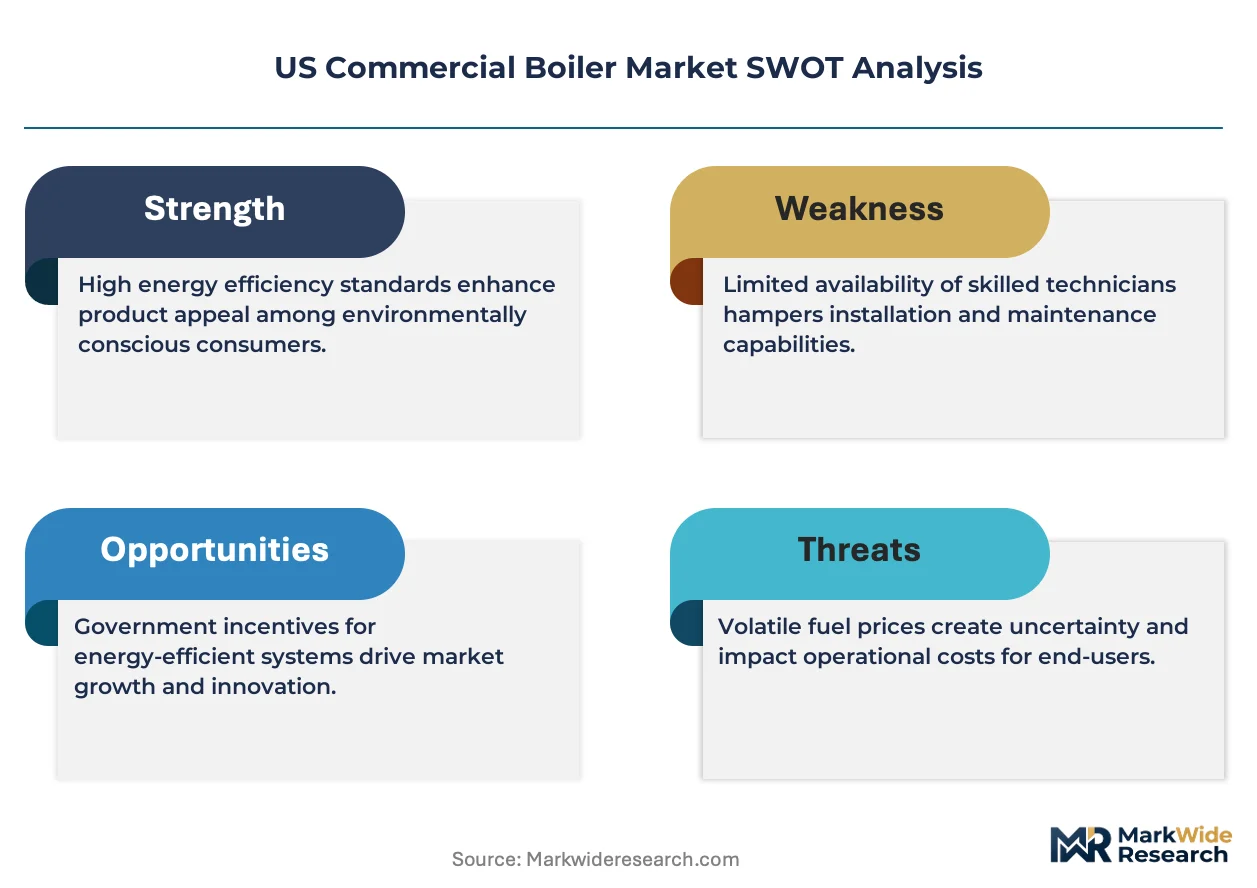
EPA New Source Performance Standards, DOE minimum efficiency regulations under the Energy Policy and Conservation Act, and OSHA boiler safety inspection protocols collectively shape product design cycles and qualification costs for domestic manufacturers. Compliance with these frameworks now requires integrated emissions monitoring and automated burner management systems that add bill-of-materials complexity but create specification stickiness once installed. Stakeholders must monitor state-level building performance standards in California and New York that extend federal baselines and determine which efficiency tiers qualify for public financing.
Market Dynamics
EPA New Source Performance Standards and DOE efficiency mandates are compressing replacement cycles while forcing capital-intensive burner management retrofits across aging Midwest and Northeast building stock.
Growth Catalysts
- Healthcare Facility Modernization:Hospital and long-term care construction across Texas and Florida is expanding the installed base of high-capacity steam systems. Aging boiler rooms in 1970s-era medical centers require complete plant replacement rather than component repair.
- IRA Commercial Building Incentives:Federal tax credits for high-efficiency HVAC upgrades are accelerating condensing boiler specification in mid-sized office and retail properties. Utility rebate stacking with federal incentives reduces payback periods below five years in California and New York markets.
- Condensing Architecture Maturation:Stainless steel heat exchanger fabrication advances are extending condensing boiler lifespans to match fire-tube durability. This technology convergence erodes the traditional reliability objection that slowed adoption in conservative maintenance departments.
Market Restraints
- Steel and Copper Price Volatility:Input material cost swings compress manufacturer margins and delay project quoting. Fire-tube pressure vessel fabrication requires thick-gauge carbon steel plate subject to tariff and energy-price pass-through.
- Skilled Technician Scarcity:Licensed boiler operators and combustion specialists concentrate in legacy industrial regions. Southeast and Southwest building booms outpace local apprenticeship pipeline output.
- Heat Pump Substitution in Light Commercial:Electrification mandates in California and Washington are diverting sub-300 MBH heating loads to electric heat pump systems. This segment erosion constrains volume growth in the smallest commercial boiler classes.
Strategic Opportunities
- District Heating Revival:University and medical campus central plant expansions in the Midwest are creating bundled steam and hot water demand. Modular water-tube configurations capture these high-capacity, high-reliability specifications.
- Energy-as-a-Service Contracting:Capital-constrained school districts and municipal buildings are adopting performance-based boiler provision. Equipment leasing shifts balance sheet treatment and locks in long-term service revenue streams.
- Stack Heat Recovery Integration:Combined heat and power compatibility requirements in New York and Massachusetts are creating specification pull for waste-heat recovery economizers. This technology bundling differentiates premium system offerings.
Industry Challenges
- OSHA Inspection Compliance Burden:Automated burner management system certification requires specialized controls engineering capacity that smaller mechanical contractors lack. Third-party inspection backlogs delay project commissioning.
- Legacy Control System Integration:1980s-era building automation protocols resist seamless integration with modern modulating burner controls. Retrofit projects require costly gateway hardware and custom programming.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Commercial Boiler Market |
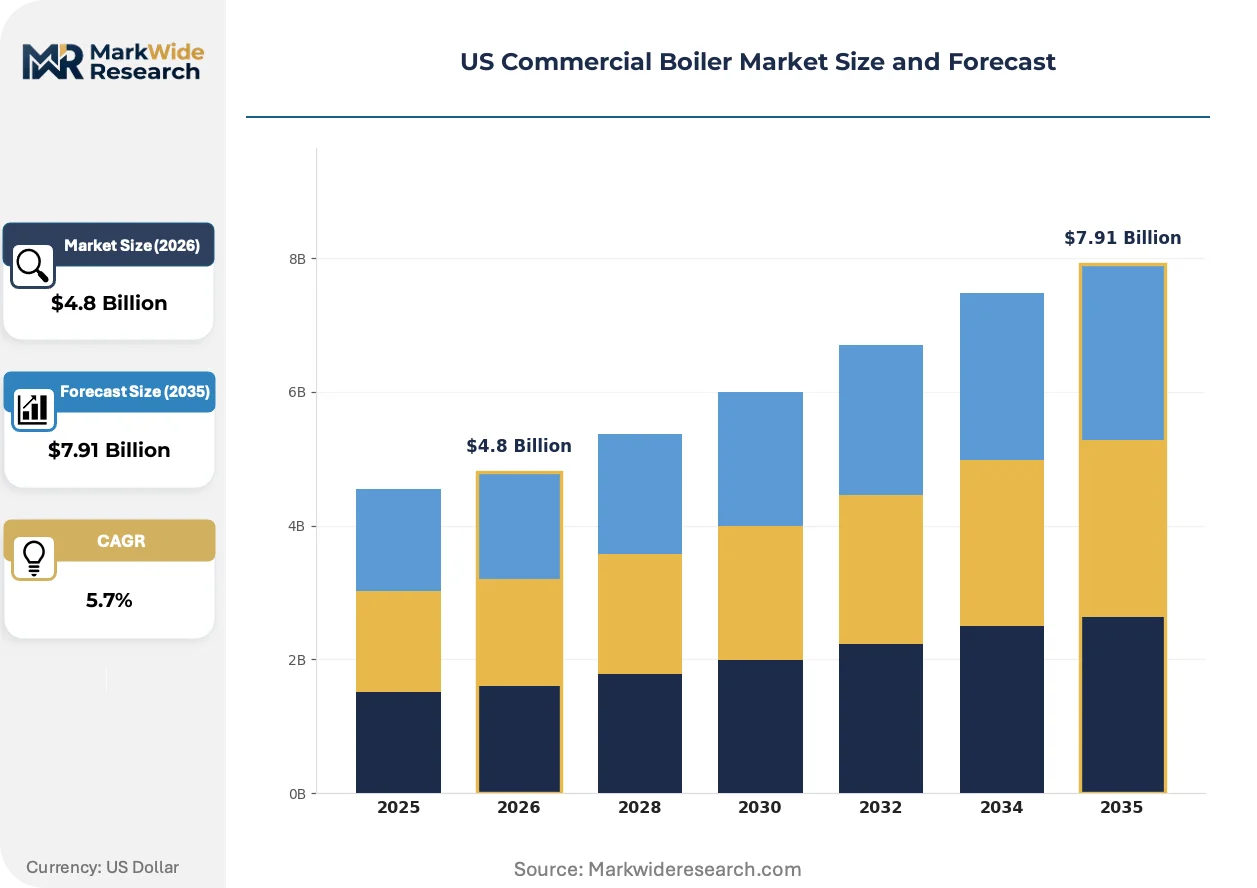
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire-Tube, Water-Tube, Condensing, Electric Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity End User: Manufacturing, Hospitality, Educational Institutions, Healthcare Facilities Installation Type: Indoor, Outdoor, Modular, Retrofitted |
| Companies Covered | Cleaver-Brooks, A.O. Smith Corporation, Fulton Boiler Company, Babcock & Wilcox Enterprises, Burnham Commercial Boilers, Miura America Co., Ltd., Parker Boiler Company, Hurst Boiler & Welding Co., Inc., Superior Boiler Works, Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Commercial Boiler Market Emerging Trajectories
Condensing technology penetration and digitized combustion control are reconfiguring product architectures while compressing the traditional divide between high-efficiency and standard-efficiency specification tiers.
Modulating burner control systems are migrating from pneumatic linkage mechanisms to direct digital servo positioning. Large hospital and university facilities in the Northeast are specifying these systems for sub-5% excess air operation. This precision is migrating from premium condensing units into mid-range fire-tube replacement specifications, compressing the efficiency gap that once justified tiered pricing.
EPA emissions monitoring mandates are forcing continuous NOx and CO measurement integration into burner management systems. Industrial consequence includes elevated bill-of-materials costs and firmware validation cycles that extend product development timelines. High-turnover urban districts in California and Texas are responding fastest, with air quality management districts requiring real-time emissions data submission.
Building operators are unbundling equipment procurement from long-term service agreements. Multi-site retail and hospitality chains in the Southeast are consolidating vendor relationships under national maintenance contracts that specify response-time SLAs. This consolidation favors manufacturers with dense service technician networks over pure equipment suppliers.
US Commercial Boiler Market Segmentation
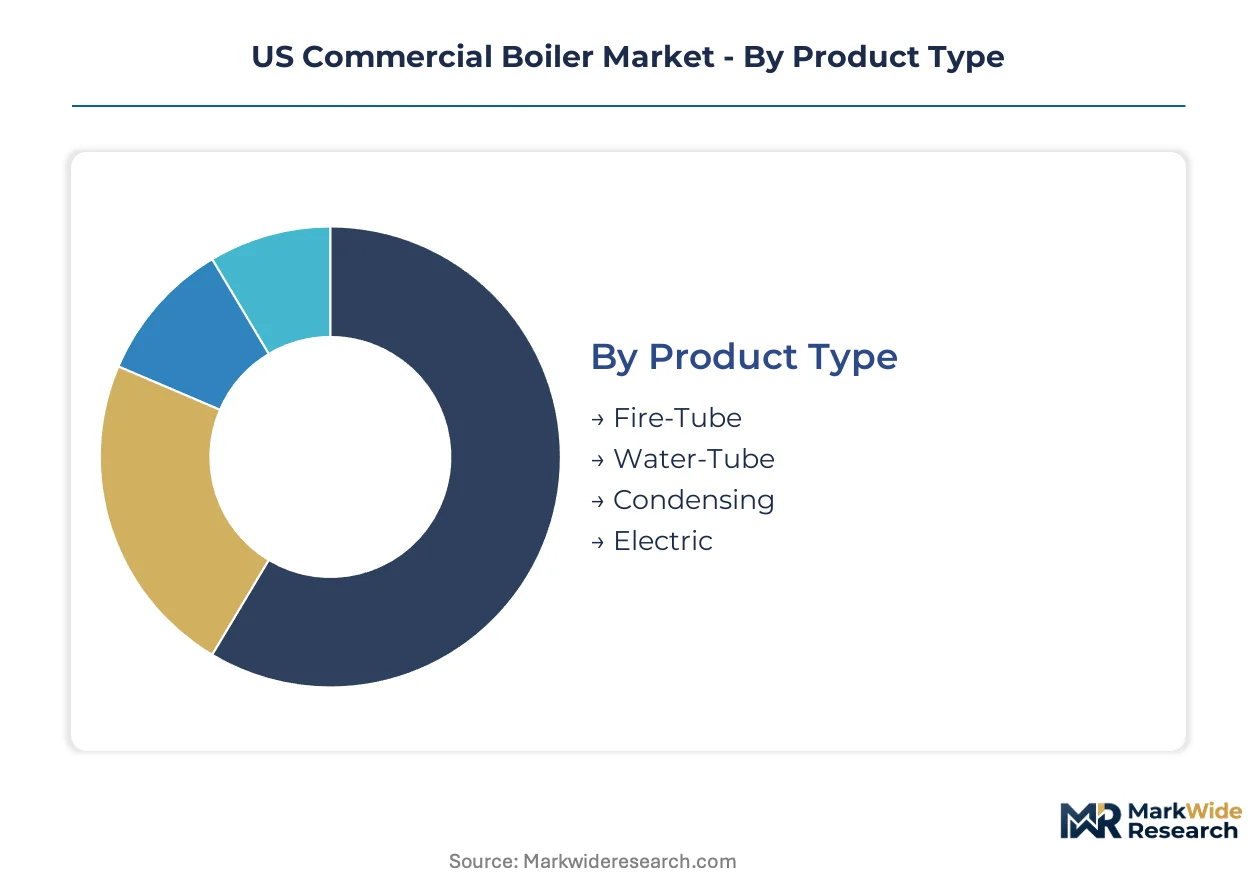
US commercial boiler procurement patterns diverge sharply across product architectures, capacity tiers, and installation contexts. Segment boundaries determine specification requirements, maintenance protocols, and capital deployment timelines for building operators and mechanical contractors.
Product Type:
Fire-tube designs turn over every 15-20 years in legacy buildings, while condensing architectures refresh on compressed 10-12 year cycles driven by efficiency mandates.
- Fire-Tube:Shell-and-tube pressure vessels route combustion gases through submerged tubes, delivering saturated steam at 15-150 psi. Replacement demand concentrates in Midwest manufacturing facilities and 1970s-era hospitals where maintenance departments favor familiar cast-iron maintenance protocols.
- Condensing:Stainless steel heat exchangers recover latent heat from flue gases, pushing combustion efficiencies above 90%. California and New York utility rebate programs accelerate specification in mid-sized office properties where payback periods now compress below five years.
- Water-Tube:Circulating water through heated tubes enables rapid steam response for fluctuating process loads.
- Electric:Resistance and electrode configurations eliminate on-site combustion, serving urban mechanical rooms with strict emissions limits.
Fire-tube anchors the volume base while condensing gains share at the steepest rate.
Capacity:
Cost tier stratification separates commodity replacement units from engineered central plant systems with multi-decade service horizons.
- Medium Capacity:300-2,500 MBH output ranges serve multi-building school campuses and regional hospital wings. Texas and Florida healthcare construction booms are expanding this tier fastest, with packaged fire-tube and condensing configurations competing on installed footprint and utility incentive stacking.
- High Capacity:2,500-10,000 MBH systems anchor university central plants and medical campus steam distribution networks. Midwest district heating revivals specify modular water-tube geometries for load-following flexibility.
- Low Capacity:Sub-300 MBH units face electrification pressure from heat pump substitution in California and Washington light-commercial mandates.
- Ultra High Capacity:Above 10,000 MBH configurations serve industrial process loads and municipal district heating with custom engineering cycles.
Medium capacity captures the broadest replacement flow while high capacity expands most quickly through bundled infrastructure projects.
End User:
Application-specific duty cycles and reliability requirements reshape product specification across vertical markets.
- Healthcare Facilities:Steam sterilization and humidification loads demand 99.9% uptime with redundant boiler configurations. Aging 1970s-era medical centers in the Midwest and Southeast require complete plant replacement rather than component repair, driving high-capacity specifications.
- Educational Institutions:Seasonal heating loads and capital constraints favor energy-as-a-service contracting. School districts in Texas and California are consolidating vendor relationships under performance-based provisions with response-time SLAs.
- Manufacturing:Process steam requirements vary with production scheduling and product mix.
- Hospitality:Domestic hot water and space heating loads prioritize rapid recovery and compact footprint in constrained mechanical rooms.
Healthcare anchors the volume base while educational institutions gain share at the steepest rate through alternative financing structures.
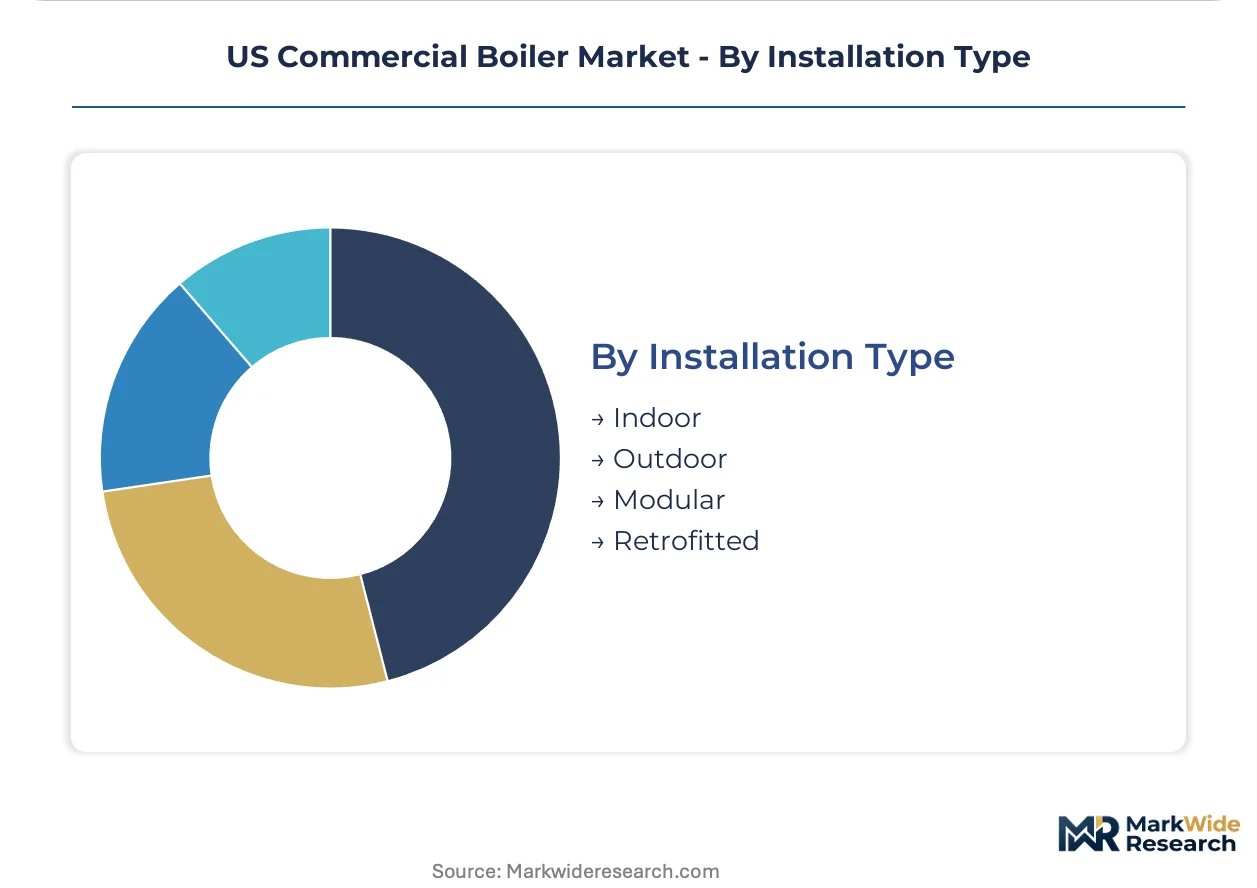
Installation Type:
Customer type and project context determine whether procurement favors standard packaged units or engineered retrofit solutions.
- Retrofitted:Legacy boiler room constraints in 1960s-1980s buildings force creative piping and footprint solutions. Northeast urban universities and municipal buildings face integration challenges with 1980s-era building automation protocols, requiring gateway hardware and custom programming.
- Modular:Factory-assembled skid packages reduce field labor and commissioning time for capacity expansions. Miura America and Cleaver-Brooks compete on vertical integration of controls and combustion systems.
- Indoor:Standard mechanical room installations dominate replacement flows with conventional ventilation and fuel delivery.
- Outdoor:Weatherized enclosures serve remote campus buildings and temporary construction heating with minimal structural investment.
Indoor installation anchors the volume base while modular gains share at the steepest rate through labor cost reduction and faster commissioning cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US commercial boiler demand flows through distinct regional channels shaped by local building stock age, utility incentive structures, and state-level emissions mandates. Import intensity remains low as domestic fabrication serves most replacement cycles, though specialized components draw from global steel and controls supply chains.
Texas
Hospital construction booms across Dallas-Fort Worth and Houston expand high-capacity steam specifications. ERCOT grid reliability concerns reinforce on-site thermal generation preferences over full electrification. Austin's municipal building performance standards accelerate condensing boiler retrofits in aging university plant facilities.
California
Title 24 building efficiency mandates and South Coast Air Quality Management District rules compress replacement cycles below national averages. Los Angeles and San Francisco utility rebate stacking reduces high-efficiency system payback periods. Sacramento school districts adopt energy-as-a-service contracting to bypass capital budget constraints.
New York
Local Law 97 carbon intensity caps drive steam system decarbonization across Manhattan commercial core. Con Edison district steam network expansions in Brooklyn and Queens create bundled demand for modular water-tube configurations. Buffalo and Rochester manufacturing facilities face compressed timelines for burner management retrofits.
Midwest
Aging 1970s hospital and university central plants across Ohio, Michigan, and Illinois require complete boiler room replacement rather than component repair. Chicago and Cleveland district heating revivals specify rapid-response water-tube geometries for load-following flexibility. EPA regional enforcement priorities accelerate NOx compliance investments.
Southeast
Florida long-term care facility construction and Georgia hospital expansions expand medium-capacity fire-tube demand. Atlanta and Charlotte building booms outpace licensed boiler operator apprenticeship pipeline output. Virginia and North Carolina manufacturing reshoring revives process steam specifications in legacy textile corridors.
US Commercial Boiler Market Vendor Landscape
On the supply side, the industry is structured around three distinct capability tiers anchored by full-system integrators, specialized steam technology developers, and regional fabrication houses. National service network coverage separates premium-positioned providers from commodity replacement suppliers. Dominant competitive moves include energy-as-a-service contracting structures that convert capital equipment sales into recurring revenue streams, and modular product architectures that reduce field installation labor dependence.
Among the full-system integrators, Cleaver-Brooks anchors the tier with nationwide technician density suited for performance-based maintenance contracts. Miura America Co., Ltd. occupies a position within the rapid-steam-response specialization, while Fulton Boiler Company exemplifies the compact-footprint archetype targeting constrained urban mechanical rooms. These three represent divergent strategic bets on how building operators will procure thermal infrastructure over the coming decade.
| Leading Market Players |
|---|
| Cleaver-Brooks |
| A.O. Smith Corporation |
| Fulton Boiler Company |
| Babcock & Wilcox Enterprises |
| Burnham Commercial Boilers |
| Miura America Co., Ltd. |
| Parker Boiler Company |
| Hurst Boiler & Welding Co., Inc. |
| Superior Boiler Works, Inc |
| Others |
Supply Flow & Price Mechanics
Steel and copper tariff exposure compresses manufacturer margins unevenly across product tiers, widening the spread between commodity fire-tube replacements and premium condensing systems while forcing procurement teams toward domestic pressure-vessel fabricators with captive metallurgy supply.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with stainless steel heat exchanger certification grade and nationwide service network density as the primary differentiation drivers. Cost compression in the standard tier is intensifying because thick-gauge carbon steel plate faces tariff pass-through volatility. Hospital procurement committees demonstrate the lowest price sensitivity due to uptime SLA requirements, while school districts under capital constraints exhibit the highest.
Supply Chain Analysis
Domestic pressure-vessel fabricators in Ohio, Michigan, and Texas hold the majority of contract-manufacturing capacity for fire-tube and water-tube assemblies. Raw material feeds draw from Canadian and Mexican steel mills for carbon plate, with specialty stainless alloys sourcing from South Korean and Japanese foundries. Single-source vulnerability concentrates in automated burner management system controls, which hinge on semiconductor components from Taiwan. Distribution runs through manufacturer-direct sales for large hospital and university projects, with regional mechanical contractors serving replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Energy-as-a-service contracting layers now expand faster than hardware shipments, converting capital equipment sales into recurring maintenance revenue streams that improve lifetime customer value capture.
For Market Incumbents: Build dense service technician networks as the defensive moat against modular steam specialists. Consolidate regional mechanical contractor relationships to lock out emerging leasing competitors. Add captive stainless steel heat exchanger fabrication capacity to insulate margin from alloy price volatility. Defend against heat pump substitution by bundling stack heat recovery economizers in mid-range specifications. For New Entrants and Emerging Players: Southeast hospital construction corridors outside Atlanta and Charlotte present the most penetrable geographic underpenetration, where licensed boiler operator scarcity delays incumbent response times. Target Florida long-term care facility expansions with modular skid packages that reduce field commissioning dependence. Enter through performance-based maintenance contracts rather than equipment-only sales to bypass capital budget gatekeepers. For Investors and Strategic Acquirers: The market sits at a replacement-cycle acceleration phase that favors vertically integrated service networks over pure equipment suppliers. Long-term viability rests on manufacturers capturing recurring revenue from combustion controls and emissions monitoring firmware updates. Acquisition target archetypes include regional fabrication houses with EPA certification infrastructure and established utility rebate program relationships. Monitor state-level building performance standard adoption velocity as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Energy-as-a-Service Contracting | Shifts balance sheet treatment for school districts while locking in 10-15 year service revenue streams. |
| Backward Integration into Stainless Heat Exchangers | Reduces alloy cost pass-through exposure and accelerates condensing product development cycles. |
| Modular Skid Package Standardization | Cuts field labor dependence and commissioning time for Texas and Florida healthcare construction booms. |
| Emissions Monitoring Firmware Development | Creates specification stickiness through EPA-mandated continuous NOx and CO measurement integration. |
| Regional Service Network Expansion | Captures maintenance contract consolidation from multi-site retail and hospitality chains in the Southeast. |
Methodological Framework
A spread of perspectives from plant engineers at Midwest hospitals, procurement directors at Texas school districts, combustion controls specialists, and regional mechanical contractors converged on the working assumptions. Secondary validation drew from EPA enforcement databases, DOE efficiency standard filings, utility rebate program disclosures, and AHR Expo product registration records. Bottom-up unit shipment estimates triangulated against top-down construction spending allocations across healthcare and educational verticals.
Demand-supply balance modeling tracked replacement cycle compression from regulatory mandates against manufacturing capacity constraints in domestic pressure-vessel fabrication. Segmentation dimensions included product architecture, capacity tier, end-use vertical, and installation context. CAGRs were derived from installed base turnover rates and incentive program sunset timelines. Industry-specific forecast inputs incorporated South Coast Air Quality Management District rulemaking velocity and IRA commercial building tax credit utilization rates.
Practitioners should monitor steel tariff adjustments, EPA regional enforcement priority shifts, and state-level electrification mandate expansion for early signals of forecast revision. Quarterly review of utility rebate program funding exhaustion rates and licensed boiler operator apprenticeship graduation volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Watertube Boilers Market
Boilers
Steam Boiler for Thermal Power Plant and Oil Refinery Market
Boilers
Residential Boiler Market
Boilers
Oil-Fired Boiler Market
Boilers
Marine Boiler Burner Market
Boilers
Fuel Operated Heaters Market
Boilers
Middle East and Africa Power Plant Boiler Market
Boilers
Power Boiler Market
Boilers
Industrial and Residential Heating Market
Boilers
Space Heating Boilers Market
Boilers
Europe Residential Boiler Market
Boilers
Waste Heat Boiler Market
Boilers
US Boiler Market
Boilers
Germany Combined Heat and Power Market
Boilers
Utility Boiler Market
Boilers
Coal-Saving Combustion-Supporting Agent Market