
 Underground Gas Storage (UGS) Market | 2026-2036
Underground Gas Storage (UGS) Market Size, Share, and Industry Trends Forecast 2026-2036
Underground Gas Storage (UGS) Market Insights
A shortage of qualified reservoir engineers and subsurface geoscientists is unwinding project timelines across the UGS sector, forcing operators to stretch existing technical teams across multiple site expansions. Gazprom sustains the largest working gas volume globally through its West Siberian depleted field complexes. Enbridge Inc. leverages its North American pipeline network to integrate storage assets with interstate transmission corridors. Snam S.p.A. specializes in salt cavern conversions along Italy's Po Valley, where geological conditions favor high-deliverability facilities.
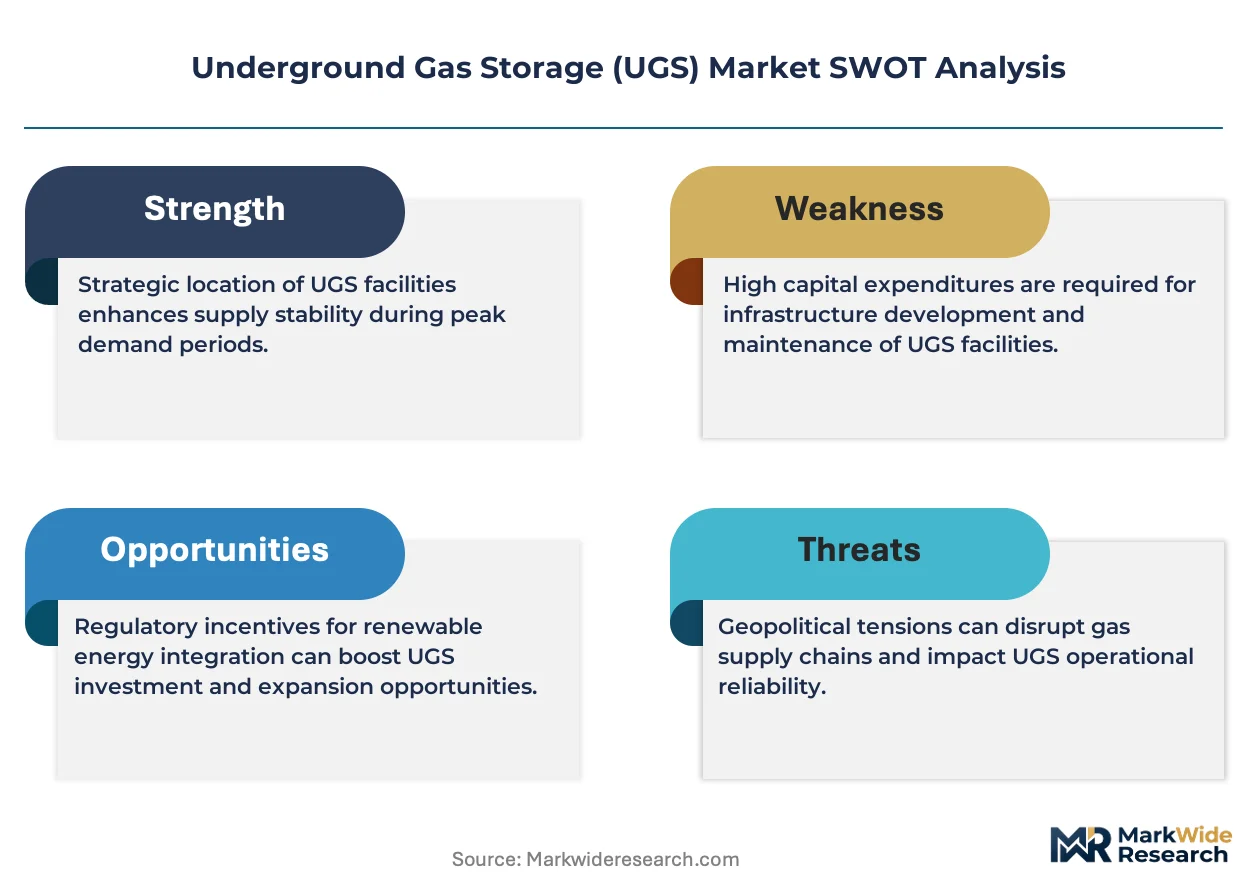
Underground gas storage encompasses the injection of natural gas into subsurface geological formations—depleted hydrocarbon reservoirs, aquifer structures, or solution-mined salt caverns—for subsequent withdrawal during periods of peak demand or supply disruption, with typical working gas capacities ranging from several hundred million to tens of billions of cubic meters per facility. The primary commercial purpose is temporal arbitrage and supply security, enabling pipeline shippers and utilities to balance seasonal demand swings without constructing excessive transmission infrastructure. Depleted reservoirs dominate installed capacity globally due to proven trap integrity and existing well infrastructure, though salt caverns command premium valuation for peak-shaving applications because of their rapid injection and withdrawal cycling rates. Seasonal storage operations generate the steadiest revenue streams through long-term capacity contracts, while peak shaving segments attract higher tariff volatility but superior margins during extreme weather events.
The EPA's Underground Injection Control program and Class VI well standards shape facility permitting timelines and capital requirements for new UGS development in the United States. In Europe, the EU Green Deal methane emissions framework and national storage obligation mandates under the Gas Directive compel utilities to maintain minimum inventory levels, directly stimulating capacity bookings. Operators and regulators must weigh the trade-off between accelerating salt cavern construction for fast-cycle flexibility and extending depleted field life through enhanced monitoring against prolonged development horizons and geological uncertainty.
Market Dynamics
The EU Green Deal methane emissions framework is compressing facility upgrade timelines while simultaneously mandating minimum inventory obligations, forcing operators to balance integrity investments against accelerated capacity expansion schedules.
Growth Catalysts
- Storage obligation mandates:The EU Gas Directive compels utilities to maintain minimum inventory levels, directly stimulating long-term capacity bookings across Germany and Italy.
- Salt cavern conversions:Solution-mined caverns near the Dutch border offer rapid cycling rates that seasonal arbitrage operators prize for peak-shaving flexibility.
- Pipeline supply buffers:European utilities are expanding contracting coverage as insurance against Nord Stream corridor interruptions and transit route volatility.
Market Restraints
- Specialized labor scarcity:Reservoir engineers and subsurface geoscientists command premium compensation, stretching project timelines across multiple concurrent site expansions.
- Steel and cement input volatility:Well casing materials and injection tubing face energy-intensive production costs that fluctuate with carbon pricing mechanisms.
- EPA Class VI permitting:Underground Injection Control standards in the United States extend development horizons through multi-year approval cycles for new facilities.
Strategic Opportunities
- Po Valley geological advantages:Italy's favorable salt dome formations support high-deliverability cavern construction with lower leaching cycle times than comparable European sites.
- Hydrogen storage retrofitting:Existing salt cavern infrastructure accommodates hydrogen blending trials, positioning operators for power-to-gas integration.
- Carbon capture co-location:Depleted reservoir complexes adjacent to industrial clusters enable combined gas storage and sequestration revenue stacking.
Industry Challenges
- Subsurface characterization uncertainty:Aquifer structure suitability assessments require extended pressure testing that delays final investment decisions.
- Legacy well integrity:Abandoned production boreholes in converted depleted fields demand extensive remediation before injection permits issue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underground Gas Storage (UGS) Market |
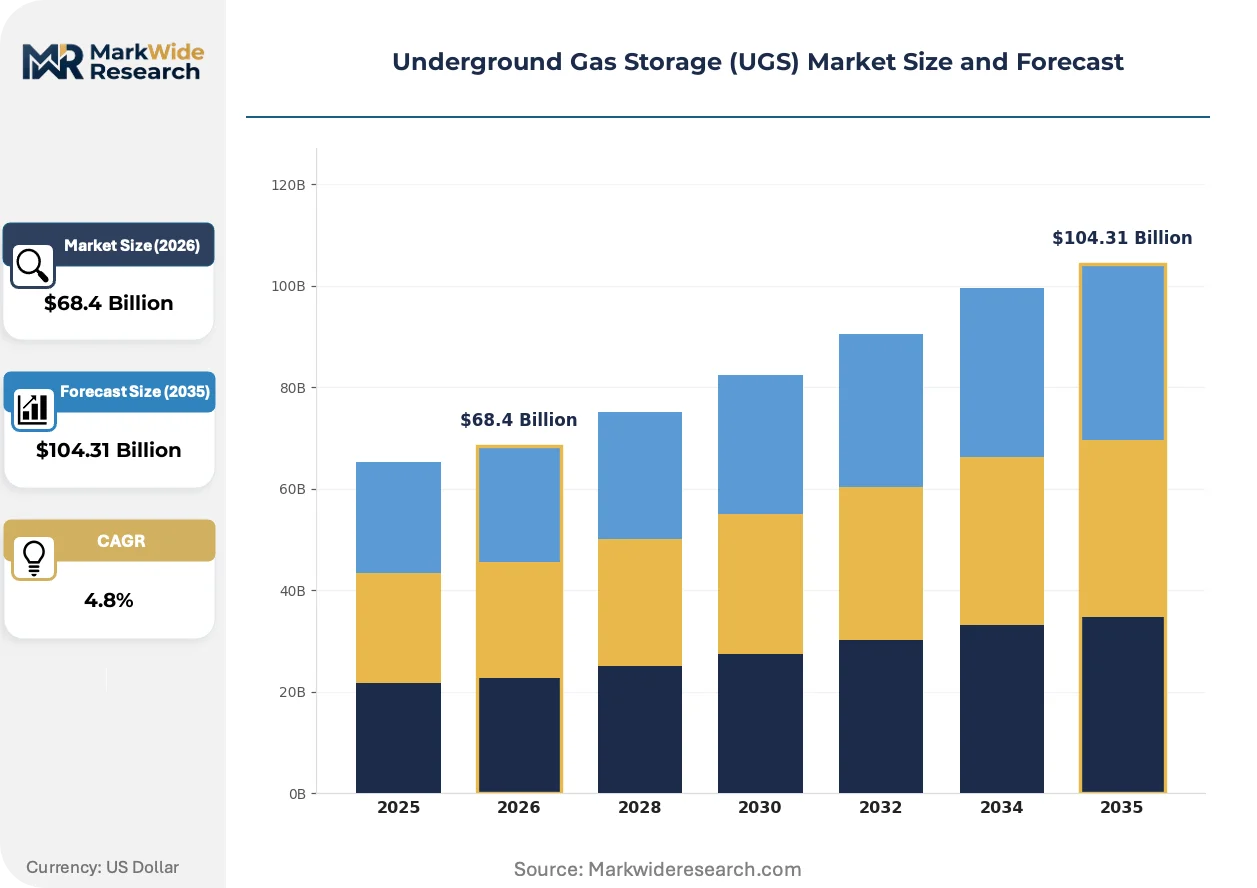
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $104.31 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: Depleted Reservoirs, Aquifers, Salt Caverns, Others Operation Mode: Modified Cycle, Seasonal Storage, Base Load, Peak Shaving End User: Utilities, Industrial Users, Power Generators, Commercial Customers Technology: Compressed Gas Technology, Pumped Storage Technology, Gas-to-Liquid Technology, Injection and Withdrawal Systems |
| Companies Covered | Gazprom, Enbridge Inc., Snam S.p.A., ENGIE SA, Uniper SE, Eni S.p.A., PetroChina Company Limited, ExxonMobil Corporation, TC Energy Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underground Gas Storage (UGS) Market Trends and Innovations
Distributed fiber-optic sensing is reshaping how operators monitor cavern and reservoir behavior, replacing periodic manual surveys with continuous subsurface visibility that compresses incident response windows.
Real-time distributed temperature and strain monitoring along wellbores is supplanting conventional downhole gauge arrays. Mid-cap storage operators in Germany and the Netherlands are deploying this technology aggressively. The shift is enabling predictive maintenance contracts that transfer operational risk from facility owners to instrumentation vendors.
The EU F-Gas Regulation is tightening leak detection and repair protocols for above-ground compression equipment. Operators must retrofit infrared cameras and automated vent monitors across existing facilities. Salt cavern complexes in northern Germany face the steepest compliance costs due to higher cycling frequency and valve density.
Capacity reservation contracts are fragmenting from decade-long firm commitments toward seasonal auction mechanisms. Pipeline shippers now layer short-term bookings with interruptible options. This pattern is most pronounced in the Netherlands, where TTF hub liquidity supports rapid position adjustments without physical nomination penalties.
Underground Gas Storage (UGS) Market Segmentation
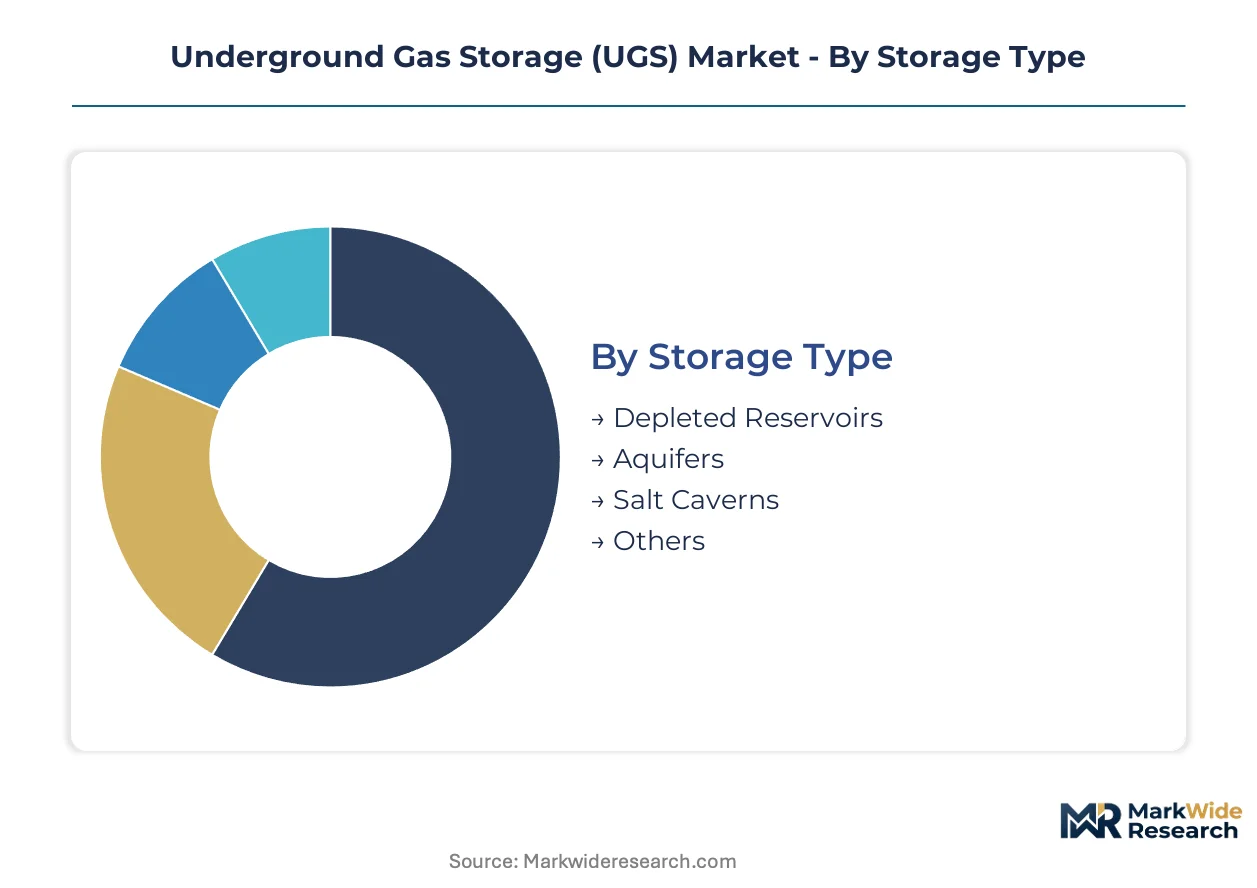
Underground gas storage segmentation reflects how geological constraints, cycling requirements, and end-use obligations shape facility economics. Operators select storage types and technologies based on specific regulatory mandates and demand patterns rather than uniform deployment.
Storage Type:
EPA Class VI standards and EU methane frameworks apply divergent integrity testing protocols across formation categories, altering development timelines and capital recovery profiles.
- Depleted Reservoirs:Converted oil and gas fields leverage proven trap integrity and existing well infrastructure to minimize upfront capital. Demand concentrates in Germany and the Netherlands where North Sea legacy fields offer multi-billion cubic meter working capacities under national storage obligation mandates.
- Salt Caverns:Solution-mined cavities in salt dome formations enable rapid injection-withdrawal cycling for peak-shaving applications. Italy's Po Valley attracts development due to favorable geology that shortens leaching cycles compared to comparable European sites.
- Aquifers:Porous water-bearing formations require extensive pressure testing and caprock verification before injection permits issue. These structures serve regional buffer roles where depleted fields are unavailable.
- Others:Hard rock caverns and lined rock storage occupy niche applications in geologically constrained markets including parts of Japan and South Korea.
Established volume favors depleted reservoirs; emerging adoption favors salt caverns.
Operation Mode:
Contract structures and tariff mechanisms vary sharply across cycling frequencies, with seasonal bookings commanding stable revenue streams and peak services capturing weather-driven volatility.
- Seasonal Storage:Facilities inject gas during summer months for winter withdrawal, matching heating demand curves. Utilities in Germany and Italy anchor capacity bookings under EU Gas Directive minimum inventory obligations.
- Peak Shaving:Rapid-cycle operations address extreme weather events and supply interruptions. Salt cavern operators near the Dutch border capture premium tariffs during pipeline disruption episodes.
- Base Load:Continuous low-rate injection and withdrawal supports steady pipeline flow management. Industrial clusters in Belgium and France utilize these services for process stability.
- Modified Cycle:Customized scheduling accommodates hybrid demand profiles from power generators with intermittent renewable integration needs.
Revenue stability concentrates in seasonal contracts; margin expansion clusters in peak shaving.
End User:
Customer categories face distinct procurement constraints, with utilities bound by public service obligations and industrial users optimizing against spot price exposure.
- Utilities:Distribution network operators hold mandatory reserves under national implementing measures of the EU Gas Directive. German municipal utilities drive capacity contracting expansion as insurance against transit route volatility.
- Industrial Users:Chemical and fertilizer manufacturers require feedstock security with flexible nomination rights. BASF and comparable operators in Ludwigshafen cluster anchor regional storage demand.
- Power Generators:Combined-cycle gas turbine operators balance renewable intermittency with stored gas dispatch. Grid operators in the Netherlands prioritize fast-cycle salt cavern access.
- Commercial Customers:Large commercial and district heating systems purchase interruptible capacity at discounted rates, accepting curtailment risk during supply stress events.
Contract duration extends longest for utilities; tariff flexibility matters most to commercial offtakers.
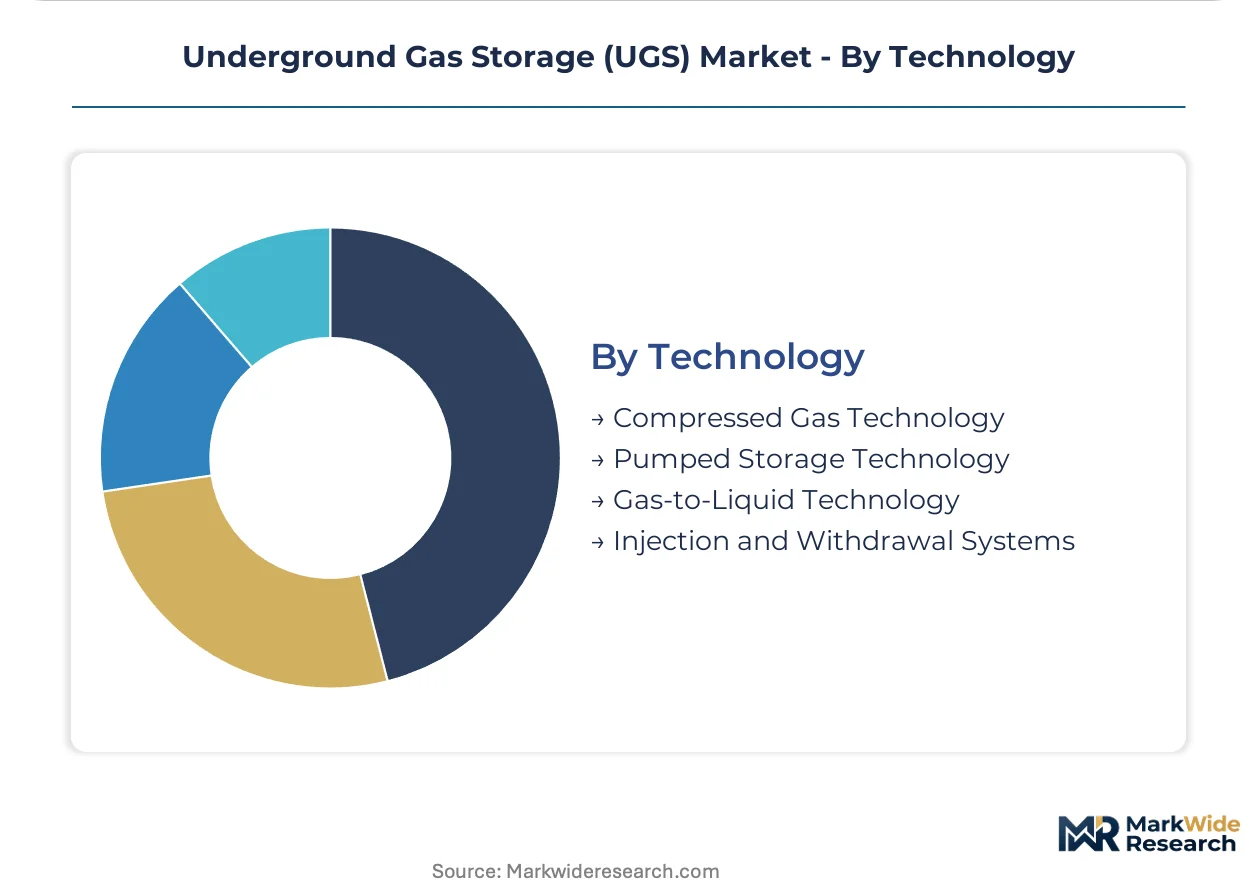
Technology:
Equipment selection determines cycling efficiency, methane containment performance, and compliance with evolving EPA and EU F-Gas regulatory thresholds.
- Injection and Withdrawal Systems:High-rate wellhead assemblies and compression trains govern facility deliverability. Northern German operators retrofit infrared monitoring to satisfy EU F-Gas leak detection mandates.
- Compressed Gas Technology:Above-ground storage in pressure vessels serves satellite buffering and vehicle fueling applications. These systems avoid subsurface permitting complexity but scale poorly beyond niche deployments.
- Pumped Storage Technology:Mechanical gas compression using liquid piston systems achieves higher round-trip efficiency in specific geological settings. Dutch pilot projects test integration with offshore wind curtailment.
- Gas-to-Liquid Technology:Conversion to synthetic fuels or chemicals enables alternative storage chemistry. Power-to-gas trials in Denmark and Germany explore hydrogen blending compatibility with existing salt cavern infrastructure.
Deployment maturity concentrates in injection-withdrawal systems; technology transition favors gas-to-liquid integration pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation anchors European storage development, compressing facility upgrade timelines across member states while national storage obligations under the Gas Directive stimulate capacity expansion. Operators in Germany, Italy, and the Netherlands dominate working gas volume, with depleted North Sea fields and salt dome formations anchoring regional infrastructure.
Germany
Depleted North Sea gas fields and salt caverns near the Dutch border concentrate national working capacity. The country's national energy regulator enforces minimum inventory obligations under EU Gas Directive implementing measures. Rehden and Jemgum salt cavern complexes anchor northern capacity, while Bavarian operators expand seasonal storage contracting for municipal utilities.
Italy
Salt dome formations across the Po Valley enable rapid-cycle peak shaving facilities with shorter leaching cycles than comparable European sites. The EU Green Deal methane emissions framework compels compressor station retrofits with infrared monitoring systems. Lombardy and Emilia-Romagna clusters host high-deliverability cavern conversions serving power generators balancing renewable intermittency.
United States
Depleted reservoir complexes along the Gulf Coast and in the Southwest anchor seasonal storage capacity for interstate pipeline networks. EPA Class VI well standards under the Underground Injection Control program extend permitting timelines for new aquifer storage developments. Texas and Louisiana salt dome facilities capture premium peak-shaving tariffs during extreme weather events.
Netherlands
TTF hub liquidity supports rapid position adjustments without physical nomination penalties, fragmenting capacity contracts toward seasonal auction mechanisms. National implementing measures of the EU Gas Directive mandate strategic reserves for distribution network operators. Groningen region depleted fields transition toward seasonal buffer roles as production winds down.
China
Depleted oil and gas fields in Sichuan and Xinjiang anchor working gas expansion for pipeline supply security. The country's national energy administration prioritizes storage obligation frameworks under dual carbon goals. PetroChina operates multi-billion cubic meter facilities serving industrial clusters in the Yangtze River Delta and Pearl River Delta.
Underground Gas Storage (UGS) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with national champions controlling depleted field complexes and mid-cap operators dominating salt cavern conversions. Pipeline-integrated storage assets command superior interconnectivity premiums over standalone facilities. Two strategic archetypes define competitive positioning: vertically integrated energy majors leveraging upstream-downstream synergies, and specialized storage operators monetizing geological advantages through rapid-cycle services. Dominant competitive moves include capacity expansion through salt cavern leaching programs and strategic partnerships linking storage assets to hydrogen blending trials.
Among Russian and North American integrated players, Gazprom and Enbridge Inc. exemplify the scale-driven archetype through control of West Siberian depleted field complexes and pipeline-integrated storage corridors respectively. Snam S.p.A. occupies a specialist position within the salt cavern conversion tier, leveraging Po Valley geological conditions for high-deliverability facilities. These three companies represent contrasting geographic and geological strategies: Siberian reservoir dominance, North American transmission corridor integration, and Mediterranean salt dome specialization.
| Leading Market Players |
|---|
| Gazprom |
| Enbridge Inc. |
| Snam S.p.A. |
| ENGIE SA |
| Uniper SE |
| Eni S.p.A. |
| PetroChina Company Limited |
| ExxonMobil Corporation |
| TC Energy Corporation |
| Others |
Pricing and Supply Chain Analysis
Distributed fiber-optic sensing replacing conventional downhole gauge arrays simultaneously shifts instrumentation sourcing toward Dutch and German sensor manufacturers while compressing pricing premiums for legacy monitoring equipment. This substitution dynamic concentrates procurement leverage with operators running multi-site cavern networks, forcing incumbent gauge suppliers into defensive service-contract bundling.
Pricing Analysis
Long-term capacity reservation contracts anchor facility revenue, though seasonal auction mechanisms fragment pricing structures toward interruptible options with weather-driven volatility. Tariff differentiation rests on cycling frequency and deliverability rates, with peak-shaving salt cavern operators capturing premium spreads during pipeline disruption episodes. Cost compression in seasonal storage tiers intensifies because utilities face mandatory inventory obligations under EU Gas Directive implementing measures. Industrial users exhibit highest price sensitivity, while utilities bound by public service obligations accept firmer long-term commitments.
Supply Chain Analysis
Port congestion along Rotterdam-Antwerp corridors and container availability constraints on Asia-Europe trade lanes inflate lead times for wellhead assemblies and compression train components. Steel casing and cement sourcing concentrates in Germany, China, and South Korea, with specialized alloy tubing drawing from Japanese and Austrian mills. Single-source vulnerability sits with EU F-Gas compliant infrared monitoring systems, where qualified vendors remain limited. Distribution runs through EPC contractors integrating storage facility construction with pipeline interconnectivity projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Underground Gas Storage market functions as a defensive moat anchored in regulatory entrenchment, where EU Gas Directive storage obligations and EPA Class VI permitting timelines create structural barriers to capacity replication.
For Market Incumbents: Secure long-term reservoir engineering talent through captive training partnerships with technical universities in Delft and Clausthal-Zellerfeld, insulating project timelines against specialized labor scarcity. Deepen backward integration into salt cavern leaching services to capture margin pools currently held by third-party solution mining contractors, defending against mid-cap operators scaling through geological specialization.
For New Entrants and Emerging Players: Anchor in hydrogen storage retrofitting opportunities at existing salt cavern complexes, where power-to-gas integration trials create white-space demand from grid operators balancing renewable intermittency. Target capacity reservation contracting for industrial clusters in Belgium and France, segments where utility procurement constraints create procurement flexibility for non-traditional storage providers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-cap salt cavern specialists holding Po Valley geological positions. Long-term viability frames around hydrogen blending infrastructure compatibility and carbon capture co-location revenue stacking. Watch EU methane emissions enforcement intensity as the inflection indicator for integrity capital deployment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Salt Cavern Capacity Expansion | Solution-mined caverns near the Dutch border capture premium peak-shaving tariffs during supply interruptions. |
| Hydrogen Storage Retrofitting | Existing salt cavern infrastructure accommodates blending trials positioning operators for power-to-gas integration. |
| Carbon Capture Co-location | Depleted reservoir complexes adjacent to industrial clusters enable combined gas storage and sequestration revenue stacking. |
| Fiber-Optic Monitoring Deployment | Distributed sensing systems compress incident response windows while transferring operational risk to instrumentation vendors. |
| Long-term Utility Contracting | German municipal utilities anchor capacity bookings under EU Gas Directive minimum inventory obligations. |
Research Methodology
A spread of perspectives from utility planning officers, salt cavern facility operators, EPC contractors, and pipeline transmission engineers converged on the working assumptions driving capacity expansion timelines. Primary fieldwork combined structured interviews with secondary validation against FERC filings, EIA storage data, EU Gas Directive implementing measures, and project development databases tracking salt cavern leaching programs. Bottom-up facility-level capacity builds triangulated against top-down regional demand projections from heating degree-day modeling and industrial consumption patterns.
Segmentation dimensions modeled span storage type, operation mode, end-user category, and technology across the projection horizon. CAGRs derived from facility-level capital deployment schedules and contract tariff evolution, with working gas capacity builds cross-referenced against national storage obligation mandates and methane emissions compliance timelines. Forecast inputs incorporated EPA Class VI permitting velocity, EU F-Gas retrofit requirements, and fiber-optic sensing adoption curves.
Material uncertainties — regulatory enforcement intensity, steel and cement input volatility, subsurface characterization delays — sit outside the modeled envelope. Forecasts reflect documented assumptions around EU Green Deal implementation pacing and salt dome leaching cycle durations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Subsea Flowlines Market
Oil & Gas
India AI in Oil and Gas Market
Oil & Gas
Tricone Bits Market
Oil & Gas
Qatar Oilfield Chemicals Market
Oil & Gas
Kuwait Oil and Gas Market
Oil & Gas
Polycrystalline Diamond Compact (PDC) Drill Bit Market
Oil & Gas
Oil and Gas Automation and Instrumentation Market
Oil & Gas
Connected Oil and Gas Market
Oil & Gas
Global Oil Line Corrosion Inhibitors Market
Oil & Gas
Nigeria Oil and Gas Market
Oil & Gas
Injection Well Market
Oil & Gas
Fracking Fluid Market
Oil & Gas
Frac Stack Market
Oil & Gas
Wellhead Equipment Market
Oil & Gas
Asia Pacific Upstream Oil and Gas Services Market
Oil & Gas
Pipeline Pigging Services Market