
 Well Stimulation Vessels Market | 2026-2036
Well Stimulation Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
Well Stimulation Vessels Market Outlook
Gulf Coast shipyards is broadening construction capacity for specialized marine stimulation equipment. Halliburton leverages integrated service portfolios to anchor offshore fracturing demand in the US territorial waters. Schlumberger sustains technology leadership through advanced monitoring systems embedded across vessel classes. Baker Hughes Company competes on modular deployment architectures that reduce mobilization timelines for independent operators.
Well stimulation vessels are purpose-built marine craft equipped with high-pressure pumping arrays, coiled tubing injectors, and cementing skids rated for subsea well intervention. These vessels perform hydraulic fracturing, acidizing, and cementing operations in offshore environments where land-based equipment cannot access subsea completions. Hydraulic fracturing vessels command the largest equipment allocation due to sustained deepwater shale development in the US Gulf and Brazil's pre-salt fields. Coiled tubing vessels represent the fastest-expanding category as operators seek live-well intervention without riser disconnection. Electric-driven technology segments attract capital allocation where shore-power integration and battery-hybrid architectures cut fuel consumption during standby operations.
The US Coast Guard enforces structural fire-safety and stability standards under 46 CFR Subchapter I for all vessels engaged in outer continental shelf activities. EPA Tier 4 marine engine regulations and IMO MARPOL Annex VI sulfur caps compel fleet operators to retire older diesel-powered units or retrofit exhaust after-treatment systems. Stakeholders must weigh capital commitment timelines against regulatory phase-in schedules as compliance windows tighten for high-horsepower marine pumping equipment.
Market Dynamics
EPA Tier 4 marine engine mandates and IMO MARPOL Annex VI sulfur caps are forcing fleet operators to retire legacy diesel-powered stimulation vessels or absorb costly exhaust after-treatment retrofits, compressing capital deployment timelines across the Gulf Coast and Brazil's pre-salt basins.
Growth Catalysts
- Deepwater shale development:US Gulf operators are expanding fracturing fleet deployments to access deeper offshore reservoirs where land-based equipment cannot reach subsea completions.
- EPA emissions compliance:Tighter standards for marine diesel engines are accelerating hybrid propulsion retrofits that reduce fuel consumption during standby operations.
- Live-well intervention demand:Coiled tubing technology is displacing conventional riser-disconnection methods as operators prioritize continuous production during well workovers.
Market Restraints
- High-horsepower engine scarcity:EPA Tier 4 certified marine engines face extended lead times from limited US and European suppliers, stretching vessel construction schedules.
- Specialized steel alloy costs:High-pressure pumping manifold fabrication depends on nickel-chromium-molybdenum alloys subject to volatile commodity pricing from concentrated mining jurisdictions.
- Subsea wellhead compatibility limits:Legacy wellhead designs in mature Gulf of Mexico fields constrain stimulation vessel equipment standardization, fragmenting fleet configuration requirements.
Strategic Opportunities
- Brazil pre-salt expansion:Petrobras-led development of ultra-deepwater carbonate reservoirs is creating dedicated demand for high-specification fracturing vessels with extended operational envelopes.
- Shore-power integration:Battery-hybrid architectures compatible with US coastal grid infrastructure offer emission reduction pathways that qualify for IRA clean energy tax credits.
- Modular equipment architectures:Skid-mounted pumping and cementing systems enable rapid reconfiguration between hydraulic fracturing and acidizing service lines, improving vessel utilization rates.
Industry Challenges
- Marine engineer certification gaps:US Coast Guard licensing requirements for high-pressure pumping system operators exceed standard merchant marine training pathways, constraining qualified crew availability.
- 46 CFR Subchapter I compliance timelines:Structural fire-safety and stability recertification for converted offshore supply vessels creates deployment delays during peak seasonal demand windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Well Stimulation Vessels Market |
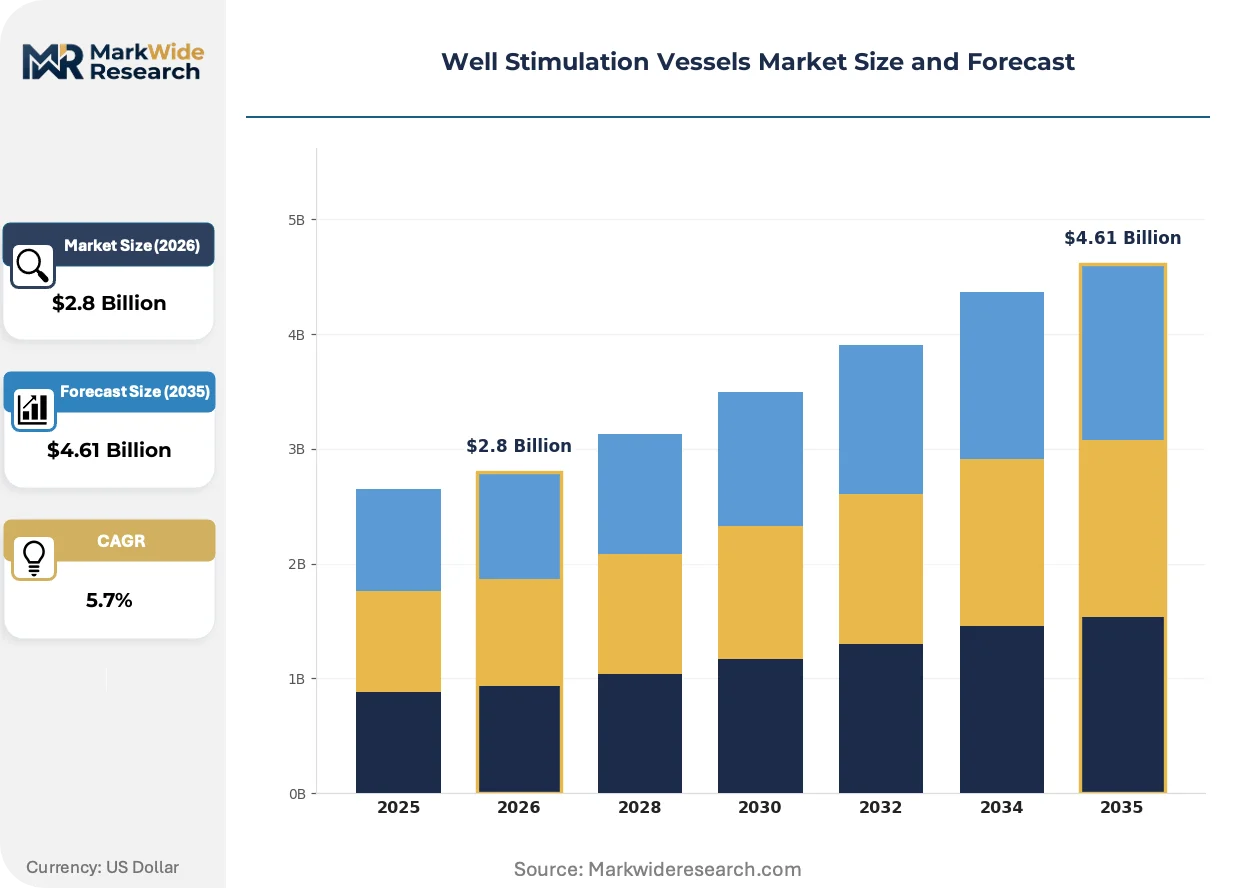
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Coiled Tubing Vessels, Hydraulic Fracturing Vessels, Cementing Vessels, Nitrogen Vessels Technology: Electric-Driven, Diesel-Powered, Hybrid Systems, Advanced Monitoring End User: Oil Producers, Natural Gas Companies, Service Providers, Independent Operators Deployment Type: Onshore Operations, Offshore Operations, Modular Units, Stacked Configurations |
| Companies Covered | Halliburton, Schlumberger, Baker Hughes Company, Oceaneering International, Inc., Damen Shipyards Group, Island Offshore, Transocean Ltd., TechnipFMC plc, Forum Energy Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Well Stimulation Vessels Market Strategic Shifts
Electrification of marine propulsion and pumping systems is compressing the performance gap between conventional diesel architectures and hybrid alternatives. Vessel operators now face technology selection decisions that lock in operational economics for fifteen-to-twenty-year asset lifecycles.
High-capacity lithium-ion battery packs integrated with shore-power connection systems are rewriting vessel fuel consumption profiles during standby and transit operations. Independent operators in the US Gulf are adopting these configurations faster than integrated majors, seeking operating cost advantages against larger fleet competitors. The technology is compressing the total cost of ownership differential that previously favored conventional diesel-only vessels.
EPA Tier 4 Final standards for Category 3 marine engines are compelling exhaust after-treatment retrofits or newbuild specifications across the existing stimulation fleet. Operators must weigh capital commitment timelines against regulatory phase-in schedules as compliance windows tighten for high-horsepower pumping equipment. US-flagged vessels face the most accelerated compliance deadlines, pushing retirement decisions for pre-2015 diesel units.
Day-rate contracting structures are fragmenting as independent exploration companies demand performance-linked pricing tied to barrels stimulated rather than time-charter terms. This shift is displacing traditional flat-rate vessel deployment models in the US Gulf spot market. Shale-focused independents with variable drilling programs are driving the transition, prioritizing cost predictability over guaranteed equipment availability.
Well Stimulation Vessels Market Segmentation
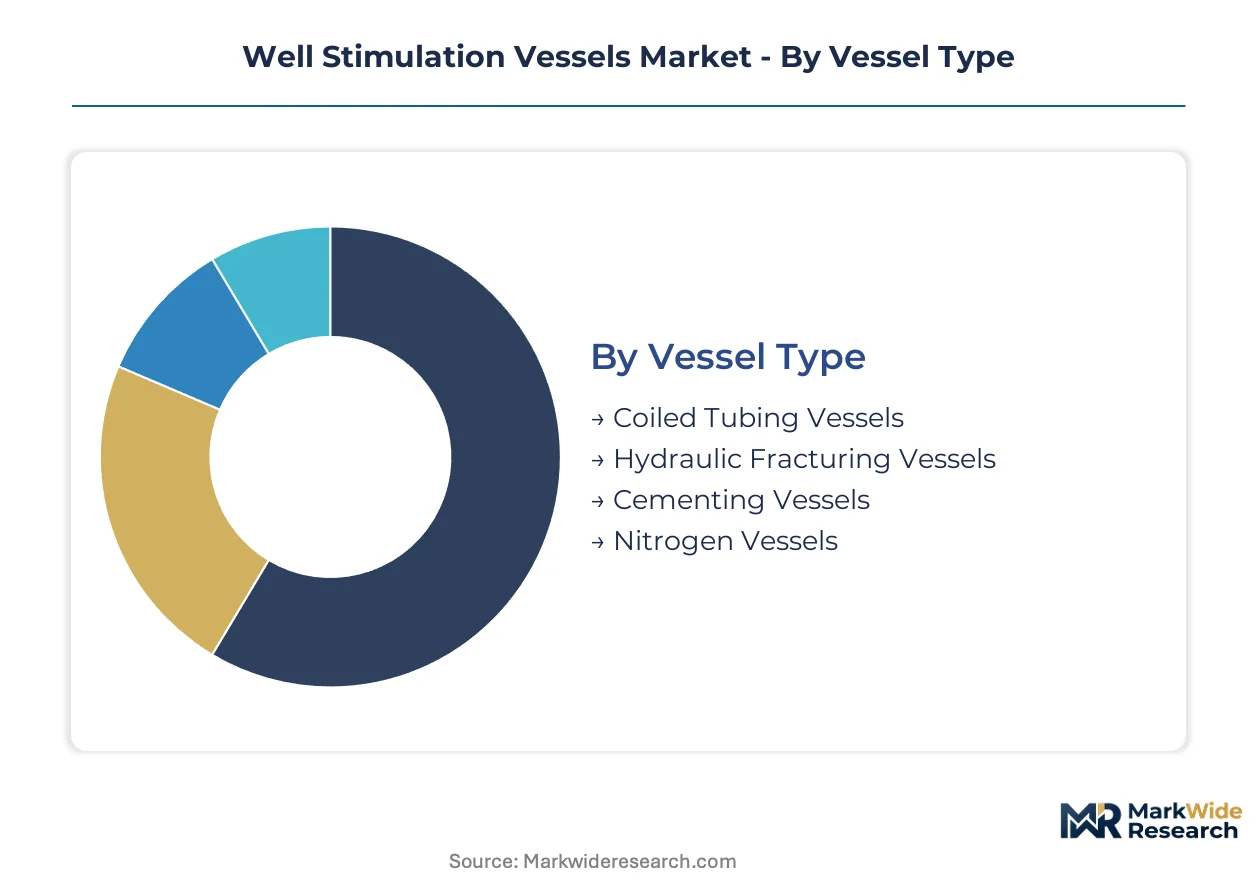
Vessel configuration and propulsion architecture determine capital intensity, regulatory compliance pathways, and operational flexibility across stimulation fleet deployments. Technology selection locks in fifteen-to-twenty-year asset economics, while end-user structure shapes contracting terms and utilization patterns.
Vessel Type:
Pressure rating and pumping capacity specifications differentiate fleet investment profiles and service line compatibility.
- Hydraulic Fracturing Vessels:These craft deploy high-horsepower pumping arrays rated for deepwater shale completion operations. Demand concentrates in US Gulf Coast waters where operators access subsea reservoirs beyond land-based equipment reach, with fleet deployment timelines accelerating under deepwater development schedules.
- Coiled Tubing Vessels:Live-well intervention capability eliminates production shutdowns during workover operations. Independent operators in Texas and Louisiana coastal waters prioritize these units for continuous production economics, displacing conventional riser-disconnection methods.
- Cementing Vessels:Purpose-built skids handle subsea casing and zonal isolation in high-pressure formations.
- Nitrogen Vessels:Specialized cryogenic systems support underbalanced drilling and gas lift operations.
Hydraulic fracturing vessels lead on scale; coiled tubing vessels lead on momentum.
Technology:
Propulsion architecture and power distribution systems determine fuel consumption profiles and emissions compliance trajectories.
- Hybrid Systems:Battery-electric architectures integrated with shore-power connections cut standby fuel burn. US coastal operators qualify for IRA clean energy tax credits where grid infrastructure supports vessel electrification, compressing total cost of ownership differentials against conventional diesel.
- Electric-Driven:Shore-power compatibility enables zero-emission port operations and reduced transit fuel consumption.
- Diesel-Powered:Legacy fleet faces EPA Tier 4 retrofit mandates or accelerated retirement decisions.
- Advanced Monitoring:Embedded sensor networks optimize pumping parameters and predictive maintenance scheduling.
Diesel-powered units retain installed base dominance; hybrid systems climb the fastest on newbuild specifications.
End User:
Customer scale and integration depth shape equipment procurement patterns and contracting structures.
- Oil Producers:Integrated majors deploy owned or long-term chartered fleets for dedicated field development programs.
- Natural Gas Companies:Dry gas operators prioritize nitrogen and coiled tubing services for well maintenance.
- Service Providers:Halliburton, Schlumberger, and Baker Hughes anchor offshore fracturing demand through integrated service portfolios.
- Independent Operators:Shale-focused drillers drive spot-market day-rate fragmentation, demanding performance-linked pricing tied to barrels stimulated rather than time-charter terms.
Service providers lead on scale; independent operators lead on contracting innovation velocity.
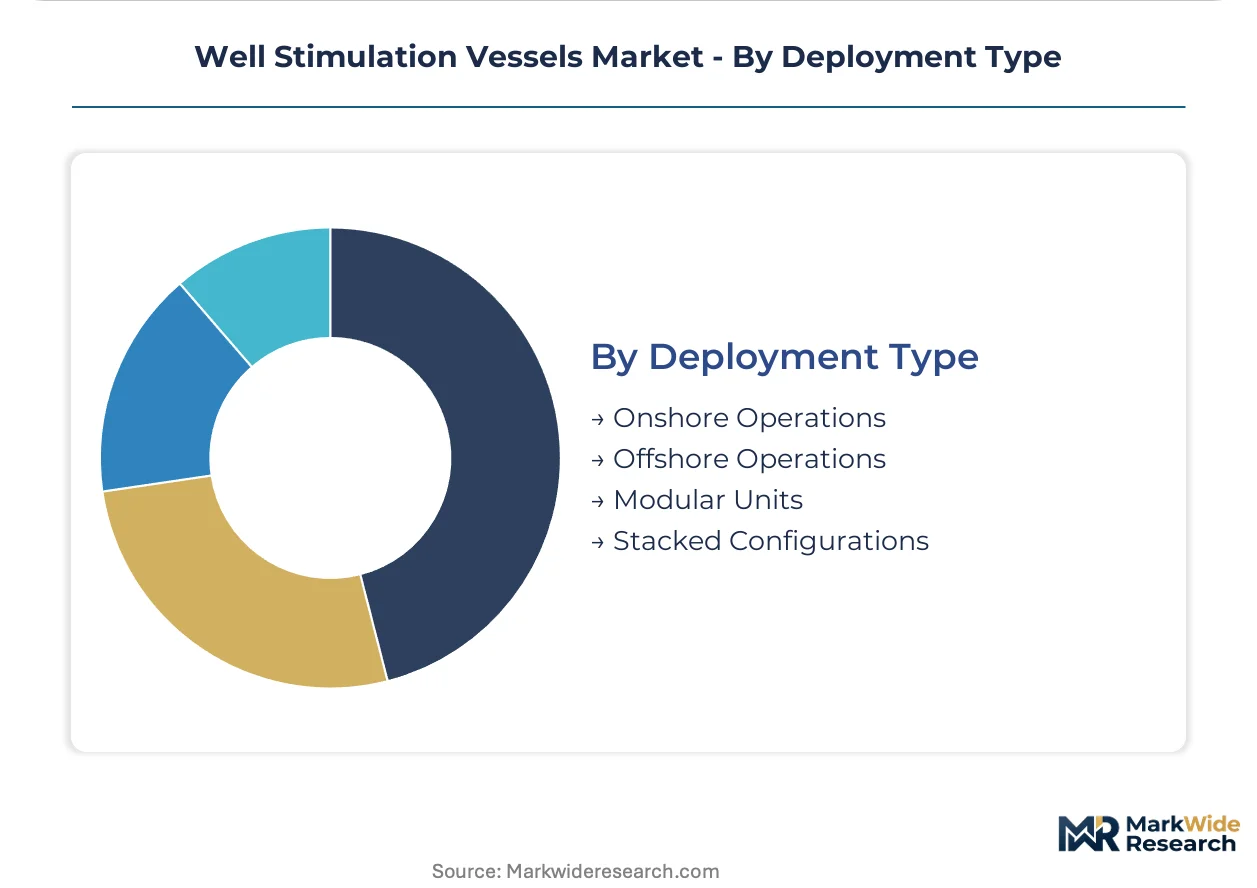
Deployment Type:
Operational geography and mobility requirements dictate vessel specification and crew certification standards.
- Offshore Operations:US Coast Guard 46 CFR Subchapter I compliance mandates structural fire-safety and stability certification for outer continental shelf activities. Deepwater Gulf of Mexico fields require extended operational envelopes and subsea wellhead compatibility.
- Onshore Operations:Coastal bay and estuary deployments serve near-shore completions with reduced draft requirements.
- Modular Units:Skid-mounted pumping systems enable rapid reconfiguration between hydraulic fracturing and acidizing service lines.
- Stacked Configurations:Idle fleet management during demand troughs preserves asset value through lay-up protocols.
Offshore operations lead on revenue concentration; modular units lead on utilization flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping fleet deployment patterns as operators migrate capital toward jurisdictions with extended compliance timelines. The cost-of-compliance gap between EPA Tier 4 mandates and emerging market standards is accelerating newbuild orders in South American and Middle Eastern yards.
United States
Deepwater shale development in the Gulf of Mexico and stranded asset recovery in mature fields drive vessel demand. EPA Tier 4 Final standards for Category 3 marine engines compress retirement schedules for pre-2015 diesel fleets. Houston-Galveston shipyards concentrate construction capacity for high-horsepower pumping arrays serving subsea completions.
Brazil
Petrobras-led pre-salt carbonate development creates dedicated demand for extended operational envelope vessels. ANP regulatory frameworks for ultra-deepwater equipment certification lag EPA timelines, attracting capital seeking compliance flexibility. Rio de Janeiro shipyards anchor fabrication clusters for fracturing vessels targeting Santos Basin fields.
Norway
North Sea well intervention and decommissioning activity sustains coiled tubing vessel utilization. Norwegian Maritime Authority emission controls for the North Sea SECA zone accelerate hybrid propulsion adoption. Stavanger and Bergen harbor specialized marine equipment suppliers serving North Atlantic offshore operations.
Saudi Arabia
Aramco offshore field development in the Arabian Gulf generates demand for high-pressure pumping capacity. Saudi Maritime Authority vessel registration standards offer transitional pathways for Tier 3 engine configurations. Dammam shipyards expand drydock capacity for stimulation vessel maintenance and equipment upgrades.
United Kingdom
North Sea asset integrity programs and P&A campaigns sustain niche demand for intervention vessels. Maritime and Coastguard Agency safety case requirements for high-pressure systems constrain fleet expansion timelines. Aberdeen maintains engineering services clusters supporting North Sea stimulation operations.
Well Stimulation Vessels Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue modular equipment architectures and shore-power integration. The vendor base concentrates around integrated service providers with captive vessel fleets and independent shipyards serving spot-market operators. Three archetypes dominate: technology-integrated majors, regional fabrication specialists, and equipment-leasing intermediaries. Capacity expansion and strategic partnerships represent the primary competitive vectors as operators seek to lock in yard slots ahead of regulatory deadlines.
Within the integrated service tier, Halliburton, Schlumberger, and Baker Hughes Company exemplify technology-anchored positioning. These entities represent the convergence of pumping equipment manufacturing, vessel chartering, and subsea service execution. Their market presence reflects bundled procurement preferences among major oil producers seeking single-accountability contracting structures for complex offshore completions.
| Leading Market Players |
|---|
| Halliburton |
| Schlumberger |
| Baker Hughes Company |
| Oceaneering International, Inc. |
| Damen Shipyards Group |
| Island Offshore |
| Transocean Ltd. |
| TechnipFMC plc |
| Forum Energy Technologies |
| Others |
Value Chain & Pricing Dynamics
EPA Tier 4 retrofit mandates for pre-2015 diesel fleets are compressing procurement timelines for US Gulf operators, forcing shipyards to accelerate nickel-chromium-molybdenum alloy sourcing and accept premium pricing for compliant high-horsepower marine engines. This demand shock propagates through concentrated European and US engine suppliers, amplifying cost pass-through to vessel charter rates.
Pricing Analysis
Direct-to-operator contracting eliminates distributor margins in integrated service provider fleets, while independent operators absorb 15-20% markup through equipment-leasing intermediaries. Three-tier pricing structure across premium hybrid-electric specifications, EPA-compliant Tier 4 diesel retrofits, and legacy pre-regulation units reflects certification-grade differentiation. Cost compression in legacy diesel tiers intensifies as compliance deadlines approach, with shale-focused independents exhibiting highest price sensitivity and integrated majors least willing to trade specification for rate discounts.
Supply Chain Analysis
Marine engineer certification gaps in Houston-Galveston and Rio de Janeiro shipyard clusters constrain skilled workforce availability, extending vessel construction schedules despite yard capacity expansion. High-pressure pumping manifold fabrication draws from concentrated nickel-chromium-molybdenum alloy suppliers in Germany and Japan, while battery-hybrid propulsion systems rest on South Korean lithium-ion cell production. Single-source vulnerability in EPA Tier 4 engine supply from Caterpillar and Wärtsilä manufacturing footprints creates procurement bottlenecks. Distribution runs through integrated service provider captive fleets and spot-market charter brokers serving independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Well Stimulation Vessels Market compounds steadily as deepwater shale development in the US Gulf and Brazil's pre-salt basins sustains replacement demand for aging diesel fleets. Regulatory compliance windows create predictable equipment refresh cycles that anchor long-term revenue visibility.
For Market Incumbents: Acquire stranded hybrid-electric vessel assets from distressed independent operators facing EPA Tier 4 liquidity constraints. Consolidate Rio de Janeiro and Houston-Galveston shipyard slots through forward capacity reservations, locking in construction timelines before nickel-chromium-molybdenum alloy price volatility escalates. Backward integration into shore-power infrastructure development captures IRA clean energy tax credit arbitrage that spot-market competitors cannot replicate. For New Entrants and Emerging Players: The mid-tier specification gap between premium hybrid-electric newbuilds and legacy diesel retrofits offers white-space entry for modular skid-mounted pumping systems compatible with converted offshore supply vessels. Target Louisiana and Texas coastal waters where shale-focused independents prioritize rapid mobilization over integrated service bundles. Pursue equipment-leasing intermediary positioning rather than vessel ownership to minimize capital intensity while capturing performance-linked contracting upside. For Investors and Strategic Acquirers: Asymmetric upside sits with regional fabrication specialists holding ANP-certified construction capacity in Brazil, where regulatory timelines lag EPA mandates and pre-salt field development accelerates. Five-to-ten year viability hinges on fleet electrification technology transfer partnerships with South Korean battery suppliers. Monitor Petrobras capital expenditure announcements as inflection indicator for Santos Basin demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion Retrofit Program | EPA Tier 4 compliance locks in fifteen-year operational economics for US-flagged vessels. |
| Shore-Power Infrastructure Partnership | IRA clean energy tax credits compress total cost of ownership for coastal grid-connected fleets. |
| Modular Equipment Architecture Development | Skid-mounted pumping systems enable rapid reconfiguration between fracturing and acidizing service lines. |
| ANP Certification Pathway Investment | Brazil regulatory lag attracts capital seeking extended compliance flexibility for pre-salt deployments. |
| Marine Engineer Training Consortium | US Coast Guard licensing requirements exceed standard merchant marine pathways, constraining qualified crew availability. |
Study Parameters
Bottom-up vessel deployment modeling reconciled against top-down shipyard capacity tracking forms the analytical core. Primary interviews with offshore project engineers, fleet procurement managers, marine regulatory compliance officers, and shipyard operations directors combine with secondary validation from US Coast Guard 46 CFR filings, EPA Tier 4 certification databases, ANP vessel registration records, and Petrobras capital expenditure disclosures. Triangulation across stakeholder perspectives and documentary sources ensures demand-side and supply-side estimates converge.
Historical fleet deployment trendlines anchor projection parameters across the analysis window. Segmentation dimensions include vessel type, propulsion architecture, end-user integration depth, and operational geography. CAGRs derive from equipment replacement cycle analysis, regulatory phase-in schedules, and field development timeline aggregation. Forecast inputs incorporate nickel-chromium-molybdenum alloy price trajectories and shore-power grid infrastructure buildout assumptions.
Caveats apply where EPA enforcement intensity, Petrobras pre-salt investment pacing, or battery-hybrid technology cost curves could materially shift the outlook. Forecasts reflect modeling assumptions that remain valid absent structural deviation in these triggers. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Mexico Oil and Gas Market
Oil & Gas
Africa Oilfield Services Market
Oil & Gas
Workover Rigs Market
Oil & Gas
Libya Oil and Gas Upstream Market
Oil & Gas
Well Test Market
Oil & Gas
Rotary Steerable System Market
Oil & Gas
Italy Oil and Gas Downstream Market
Oil & Gas
Frac Tree Market
Oil & Gas
Planned LNG Market
Oil & Gas
Microbial Enhanced Oil Recovery Market
Oil & Gas
Brazil Wireline Logging Services Market
Oil & Gas
Coal Seam Gas Market
Oil & Gas
United States Oil and Gas Market
Oil & Gas
Digital Oilfield Solutions Market
Oil & Gas
Asia-Pacific Oilfield Auxiliary Rental Equipment Market
Oil & Gas
India Artificial Lift Systems Market